
 Europe Automotive Anti-Lock Braking System Market | 2026-2036
Europe Automotive Anti-Lock Braking System Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Automotive Anti-Lock Braking System Market Foresight
The split between premium integrated braking platforms and commodity hydraulic modules is realigning procurement patterns across European supply chains. Robert Bosch GmbH leverages its captive semiconductor capacity to dominate ECU production for luxury OEM programs. Continental AG anchors its position through backward integration into sensor manufacturing for radar-based ABS variants. ZF Friedrichshafen AG competes on manufacturing scale, sustaining cost advantages in hydraulic control modules for volume passenger car lines.
Automotive Anti-Lock Braking Systems are electromechanical safety assemblies that modulate brake pressure through solenoid valves at frequencies exceeding fifteen cycles per second, preventing wheel lockup during deceleration events. Their primary purpose is maintaining directional stability and steerability under emergency braking across variable road surfaces. Traditional ABS hardware retains the largest installed base but generates thinner margins, while electronic control units and radar-based systems capture expanding value pools as vehicles adopt higher levels of automated emergency braking. Aftermarket providers face compressed turnaround times as OEMs extend certified pre-owned ABS refurbishment programs.
The EU General Safety Regulation mandates ABS and electronic stability control on all new vehicle categories, with ECE R13-H establishing uniform braking performance test protocols across member states. ECHA oversight of restricted substances in electronic components shapes material selection for ECU housings and sensor coatings. France's ANSM and Germany's KBA enforce divergent type-approval timelines that fragment homologation schedules. Stakeholders must monitor how the EU AI Act classifies predictive braking algorithms, as this determination will redraw compliance boundaries for adaptive braking software releases.
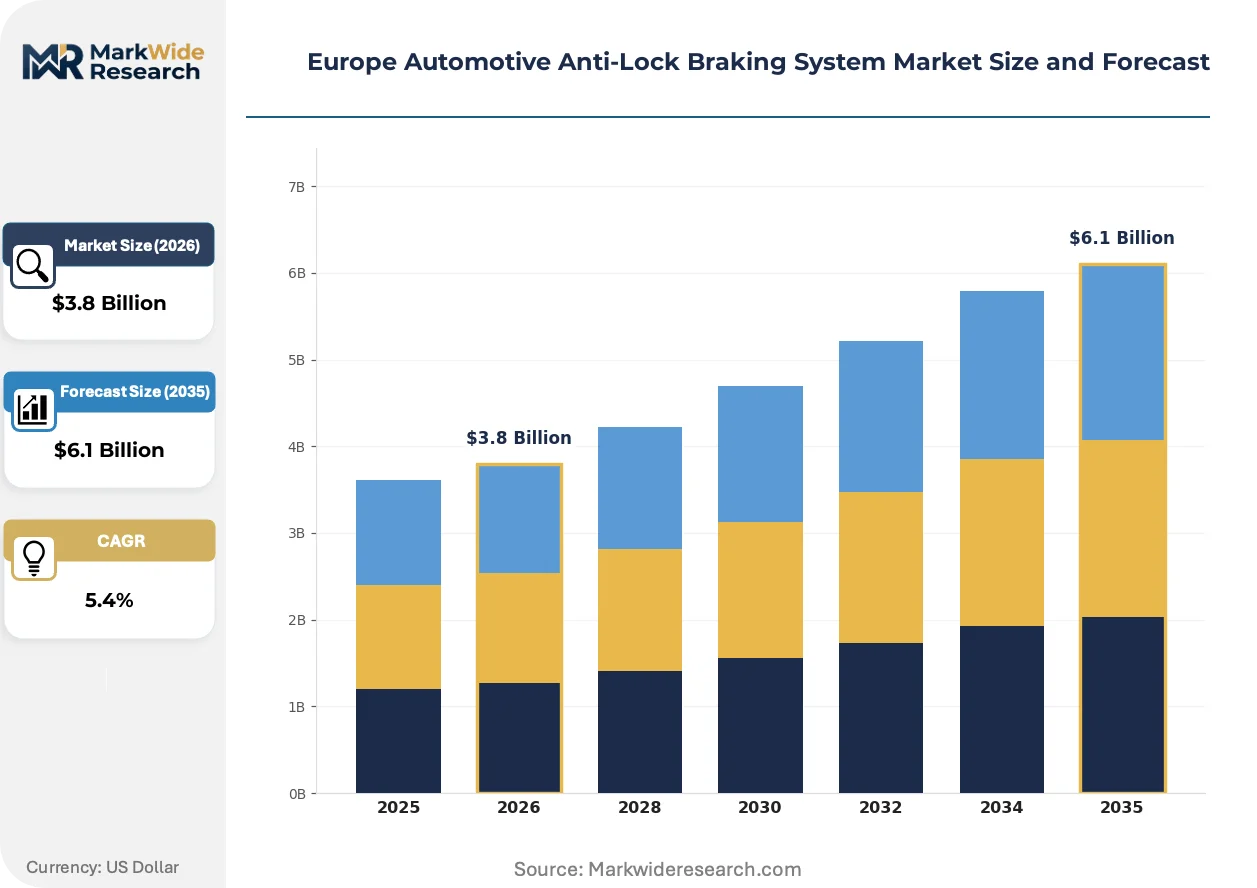
Market Dynamics
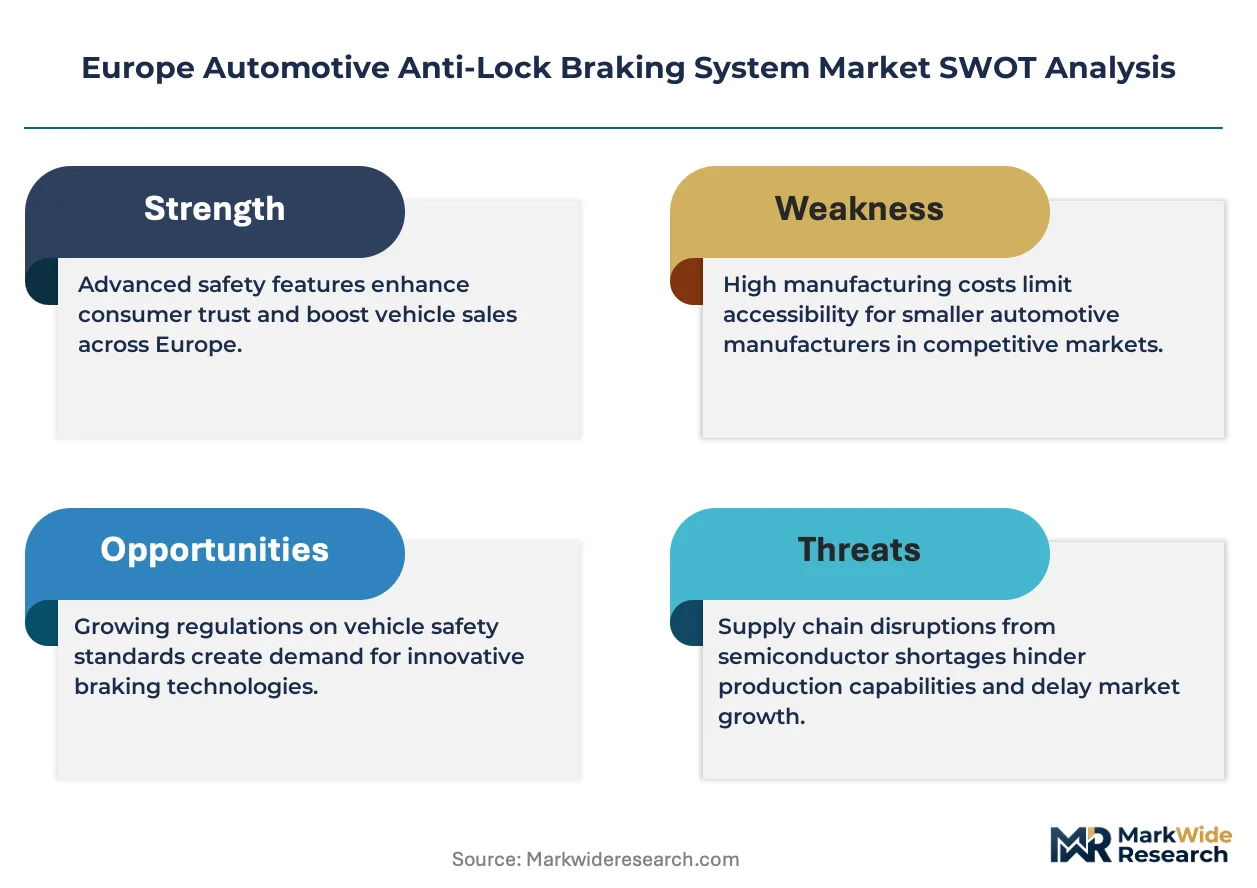
The EU General Safety Regulation is compressing ABS adoption timelines across vehicle categories, while semiconductor supply constraints force tier-one suppliers to reconfigure ECU sourcing strategies around captive foundry capacity.
Growth Catalysts
- ECE R13-H harmonization:Uniform braking performance test protocols eliminate redundant homologation cycles for cross-border OEM programs, accelerating platform rollout across Germany, France, and Poland.
- Commercial vehicle fleet mandates:EU General Safety Regulation requirements for advanced braking systems on heavy trucks are pulling hydraulic module demand through Poland's logistics corridor.
- Radar-based sensor fusion:Integration of millimeter-wave sensing with ABS ECUs enables predictive wheel-slip algorithms that exceed baseline regulatory thresholds.
Market Restraints
- Semiconductor input volatility:Silicon carbide substrate shortages constrain solenoid driver chip output, forcing ECU manufacturers into allocation protocols.
- Supply concentration in sensor substrates:German automotive corridors dominate piezoelectric element production, creating single-source vulnerability for radar-based ABS variants.
- Technical limitation in thermal cycling:Current ECU housing materials degrade under repeated brake thermal events above 180°C, limiting performance envelope expansion.
Strategic Opportunities
- Underpenetrated Polish aftermarket:Certified pre-owned ABS refurbishment programs remain nascent in Eastern European commercial vehicle fleets, creating white space for authorized service networks.
- EU AI Act tailwind:Classification of predictive braking algorithms as safety-critical systems will mandate software update infrastructure, opening recurring revenue streams for adaptive calibration services.
- Technology convergence:Vehicle-to-everything communication protocols are merging with ABS trigger logic, enabling cooperative braking across platooned trucks on French motorway corridors.
Industry Challenges
- Embedded systems firmware talent scarcity:Real-time brake control algorithm development requires specialized automotive software engineers concentrated in Stuttgart and Munich, constraining ECU program scaling.
- ECE type-approval timeline fragmentation:Divergent interpretation of brake performance testing between France's ANSM and Germany's KBA extends homologation cycles by four to six months.
- Legacy hydraulic integration complexity:Retrofitting radar-based ABS onto existing brake architectures demands custom caliper modifications that compress installer margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Automotive Anti-Lock Braking System Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.1 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Traditional ABS, Electronic Control Unit (ECU), Hydraulic Control Module, Pump End User: OEMs, Aftermarket Providers, Vehicle Manufacturers, Fleet Operators Vehicle Type: Passenger Cars, Commercial Vehicles, Motorcycles, Light Trucks Technology: Optical Sensors, Radar-Based Systems, Electronic Stability Control, Adaptive Braking |
| Companies Covered | Robert Bosch GmbH, Continental AG, ZF Friedrichshafen AG, Autoliv Inc., DENSO Corporation, Magna International, Valeo S.A., Brembo S.p.A., Haldex AB, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Automotive Anti-Lock Braking System Market Shifts & Advancements
Brake control intelligence is migrating from reactive wheel-slip correction toward predictive surface-adaptive modulation, reshaping how sensor data flows through vehicle networks.
Electro-hydraulic brake-by-wire systems are automating pedal-to-caliper signal transmission through redundant high-speed data buses. German luxury OEMs are adopting these architectures for their flagship platforms ahead of regulatory mandates. This shift is automating traditional hydraulic backup circuits out of primary control pathways, compressing component counts while elevating functional safety requirements to ASIL-D levels.
The EU AI Act's risk classification framework for automotive software is forcing ABS suppliers to document algorithm training datasets and decision boundaries. ECHA parallel oversight of restricted substances in ECU housings adds material traceability layers. French and German type-approval authorities are responding with expanded software bill-of-materials requirements that extend homologation documentation by thirty to forty percent.
Fleet procurement offices are consolidating ABS supplier relationships around integrated braking platform providers capable of spanning hydraulic hardware, ECU firmware, and over-the-air update infrastructure. Tier-one suppliers with captive semiconductor capacity are displacing modular component vendors in long-term contracts. This concentration is most visible in Germany's commercial vehicle manufacturing belt, where logistics operators now specify single-source braking system accountability across ten-year vehicle lifecycles.
Europe Automotive Anti-Lock Braking System Market Segmentation
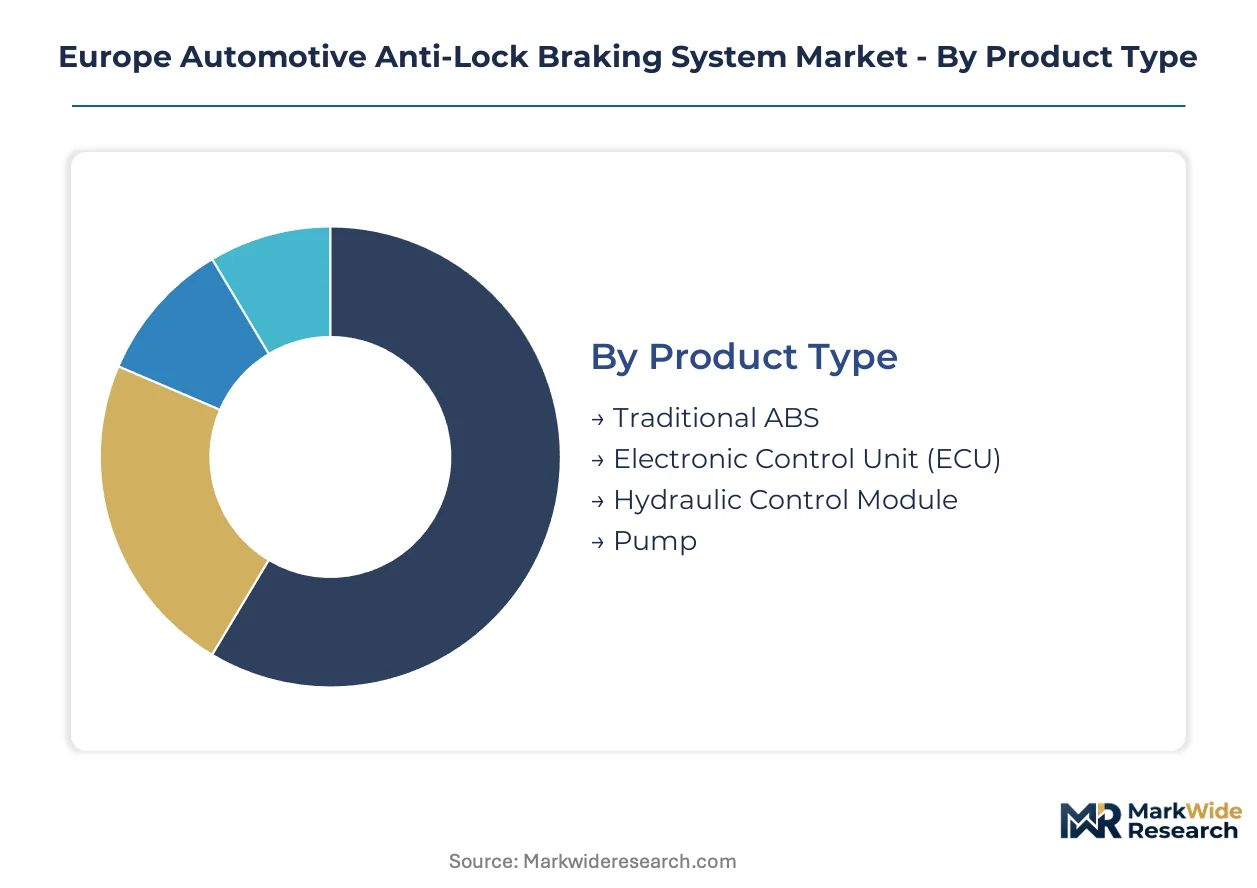
ABS procurement patterns diverge sharply across customer types and vehicle applications, with regulatory mandates compressing adoption timelines unevenly across segments. Technology integration depth and fleet scale determine margin structures more than raw volume.
Product Type:
Cost tier separates buyers seeking commodity replacement parts from those specifying integrated braking platforms with captive semiconductor supply.
- Traditional ABS:Conventional electromechanical assemblies using solenoid valves and hydraulic modulators retain the largest installed base across European vehicle parc. Demand concentrates in Poland's commercial vehicle aftermarket, where fleet operators prioritize unit cost over predictive braking capability amid EU General Safety Regulation retrofit deadlines.
- Electronic Control Unit (ECU):Embedded firmware modules process wheel-speed sensor inputs at frequencies exceeding fifteen cycles per second, commanding solenoid valve modulation. German luxury OEMs source ECUs with ASIL-D functional safety certification, pulling volume through Stuttgart's manufacturing corridor as radar-based sensor fusion becomes standard.
- Hydraulic Control Module:Pressure modulation assemblies integrating pump motors and valve blocks.
- Pump:Electric motor-driven hydraulic pressure generators for brake fluid circulation.
Volume sits with Traditional ABS; growth tilts toward Electronic Control Unit.
End User:
Application maturity determines whether buyers specify full braking platforms or modular components.
- OEMs:Original equipment manufacturers integrate ABS with electronic stability control and automated emergency braking on new vehicle platforms. German and French OEMs demand single-source accountability across hardware, firmware, and over-the-air update infrastructure, consolidating supplier relationships around tier-one providers with captive foundry capacity.
- Aftermarket Providers:Independent service networks and parts distributors supply replacement ABS components for vehicle parc maintenance. Poland's logistics corridor presents underpenetrated opportunity, as certified pre-owned ABS refurbishment programs remain nascent in Eastern European commercial fleets.
- Vehicle Manufacturers:Assembly operations sourcing braking systems for captive production.
- Fleet Operators:Commercial vehicle owners managing multi-unit procurement across ten-year lifecycles.
Procurement scale favors OEMs; margin expansion tilts toward Aftermarket Providers.
Vehicle Type:
Regulatory mandate intensity varies by vehicle mass and duty cycle.
- Commercial Vehicles:Heavy trucks and buses face the most stringent EU General Safety Regulation requirements for advanced braking systems. Fleet operators across Germany, France, and Poland are expanding ABS fitment to meet mandates, pulling hydraulic module demand through logistics corridors.
- Passenger Cars:Light-duty vehicles with electronic stability control integration as baseline equipment. German automotive manufacturing corridors concentrate demand for next-generation sensor modules combining millimeter-wave radar with ABS ECUs.
- Motorcycles:Two-wheeled vehicles with compact ABS variants.
- Light Trucks:Commercial-duty vehicles below heavy truck classification thresholds.
Regulatory pressure concentrates on Commercial Vehicles; technology migration favors Passenger Cars.
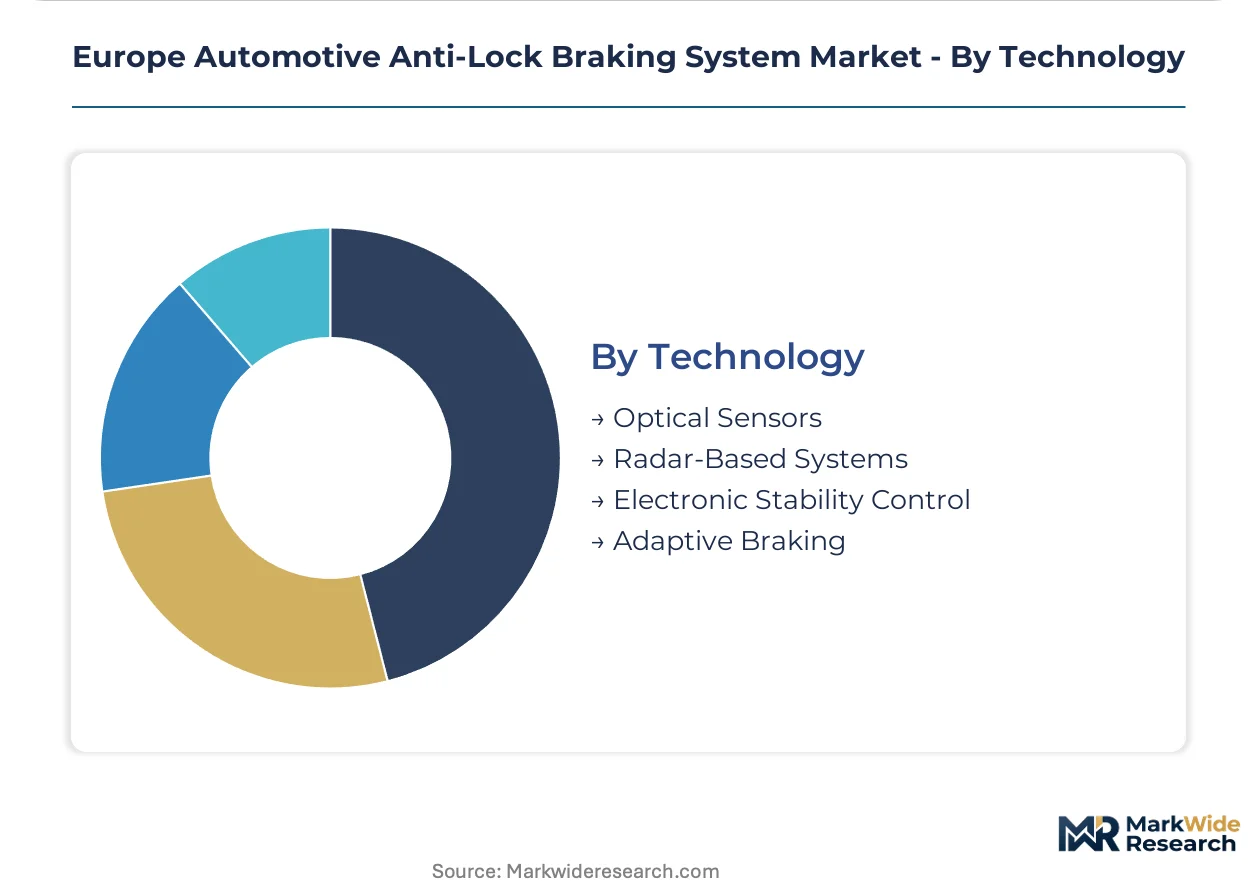
Technology:
Sensor fusion depth separates baseline compliance from predictive braking capability.
- Radar-Based Systems:Millimeter-wave sensing integrated with ABS ECUs enables predictive wheel-slip algorithms exceeding baseline regulatory thresholds. German luxury OEMs specify these variants for flagship platforms, with ECE R13-H harmonization accelerating cross-border platform rollout.
- Electronic Stability Control:Yaw-rate and lateral-acceleration sensing combined with ABS modulation. France's ANSM and Germany's KBA enforce divergent type-approval timelines for ESC-integrated systems, fragmenting homologation schedules by four to six months.
- Optical Sensors:Wheel-speed detection using toothed ring and Hall-effect sensing.
- Adaptive Braking:Surface-condition-responsive modulation algorithms.
Compliance baseline rests with Electronic Stability Control; capability expansion tilts toward Radar-Based Systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart's manufacturing corridor anchors European ABS demand, with OEMs clustering around captive semiconductor foundries and sensor integration facilities. The region's supplier networks feed assembly lines across Germany, France, and Poland with varying regulatory intensity and fleet scale.
Germany
Luxury OEMs in Baden-Württemberg and Bavaria specify radar-based ABS with ASIL-D certification for flagship platforms. KBA enforces divergent type-approval timelines that extend homologation cycles. Stuttgart's manufacturing corridor concentrates ECU production with captive foundry capacity serving cross-border programs.
France
ANSM interpretation of ECE R13-H brake performance testing fragments certification schedules against German counterparts. Île-de-France hosts fleet procurement offices consolidating supplier relationships around integrated braking platforms. Auvergne-Rhône-Alpes suppliers specialize in hydraulic module fabrication for commercial vehicle retrofit programs.
Poland
Logistics operators across the Silesian and Greater Poland voivodeships expand ABS fitment to meet EU General Safety Regulation mandates for heavy truck fleets. Certified pre-owned ABS refurbishment programs remain underdeveloped in Eastern European aftermarket channels. Warsaw-based fleet managers prioritize unit cost over predictive braking capability in procurement decisions.
Italy
Piedmont and Lombardy brake system suppliers serve premium passenger car OEMs with traditional hydraulic module production. Brembo S.p.A. anchors high-performance caliper integration for radar-based ABS variants. Italian type-approval authorities align with ECE R13-H harmonization, reducing redundant testing cycles for export-bound platforms.
United Kingdom
Midlands-based tier-two suppliers provide valve block components to German ECU integrators. Post-Brexit regulatory divergence from EU General Safety Regulation implementation timelines creates parallel certification requirements. UK fleet operators face compressed retrofit deadlines for commercial vehicle ABS mandates.
Europe Automotive Anti-Lock Braking System Market Competitive Landscape
Premium-margin players sit above commodity-margin players across functional safety certification tiers, with ASIL-D qualified ECU suppliers capturing value pools that hydraulic module fabricators cannot access. The vendor base stratifies into three archetypes: integrated platform providers with captive semiconductor capacity, specialized sensor substrate manufacturers with backward integration into piezoelectric elements, and commodity hydraulic component suppliers competing on manufacturing scale. Dominant competitive moves include M&A activity targeting firmware engineering talent in Stuttgart and Munich, and strategic partnerships securing millimeter-wave radar supply for predictive braking algorithms.
Within the integrated platform tier, Robert Bosch GmbH and Continental AG exemplify suppliers combining hardware, firmware, and over-the-air update infrastructure. ZF Friedrichshafen AG occupies a position at the scale-driven end, anchoring cost-competitive hydraulic control module production for volume passenger car lines. These three German-based entities represent the competitive core around which smaller specialists and regional fabricators orbit.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Continental AG |
| ZF Friedrichshafen AG |
| Autoliv Inc. |
| DENSO Corporation |
| Magna International |
| Valeo S.A. |
| Brembo S.p.A. |
| Haldex AB |
| Others |
Supply & Pricing Matrix
The ASIL-D certification ladder for ECU firmware separates premium integrated braking platforms from commodity hydraulic modules, concentrating pricing power with Stuttgart-based suppliers while compressing margins for Polish aftermarket distributors dependent on spot-market valve block procurement.
Pricing Analysis
Value-based pricing anchored to vehicle uptime and fleet safety outcomes dominates procurement contracts for radar-based ABS variants, with German luxury OEMs paying premiums for predictive braking algorithms that exceed ECE R13-H thresholds. Price differentiation rests on functional safety certification grade and captive semiconductor supply security. Cost compression in traditional hydraulic modules is intensifying as Polish fleet operators prioritize unit economics over sensor fusion capability. Aftermarket providers exhibit highest price sensitivity, while OEM platform engineering teams prioritize single-source accountability over component cost.
Supply Chain Analysis
Refurbishment flows for certified pre-owned ABS units remain underdeveloped across Eastern European logistics corridors, creating reverse-logistics gaps that German ECU integrators exploit for core exchange programs. Manufacturing concentration centers on Germany, France, and Poland for hydraulic module assembly, with silicon carbide substrates and piezoelectric sensor elements drawing from specialized foundries in Baden-Württemberg. Single-source vulnerability in semiconductor driver chips poses structural risk amid allocation protocols. Distribution runs through authorized service networks for OEM-captive programs and independent parts distributors for aftermarket channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market occupies a technology-transition phase as radar-based sensor fusion displaces conventional wheel-speed sensing architectures, with predictive braking algorithms redefining value capture away from hydraulic hardware toward embedded firmware and over-the-air calibration infrastructure.
For Market Incumbents: Hedge against semiconductor input volatility by securing captive foundry capacity for solenoid driver chips while consolidating firmware engineering talent in Stuttgart and Munich. Diversify sensor substrate sourcing beyond German automotive corridors to mitigate piezoelectric element concentration risk. Prioritize ASIL-D certification investment to maintain pricing power as EU AI Act software documentation requirements extend homologation timelines. For New Entrants and Emerging Players: Fleet procurement offices in Poland's Silesian corridor represent the most penetrable buyer segment, as certified pre-owned ABS refurbishment programs remain nascent in Eastern European commercial vehicle markets. Target aftermarket service networks with modular ECU retrofit kits compatible with legacy hydraulic architectures. Pursue partnerships with Warsaw-based logistics operators seeking ten-year lifecycle cost optimization over upfront platform integration. For Investors and Strategic Acquirers: Re-rating potential sits with specialized sensor substrate manufacturers given ECE R13-H harmonization accelerating cross-border platform rollout. Long-term viability favors suppliers combining hardware fabrication, firmware development, and over-the-air update infrastructure across the analysis window. Monitor EU AI Act classification determinations for predictive braking algorithms as the inflection signal for adaptive calibration service revenue recognition.| Strategic Initiative | Industry Significance | |
|---|---|---|
| Platform Standardization | Reduces redundant homologation cycles for ECE R13-H cross-border OEM programs. | |
| Software-Defined Vehicle Investment | Enables over-the-air ABS algorithm updates mandated by EU AI Act documentation. | |
| Geographic Manufacturing Footprint | Captures Polish commercial vehicle fleet retrofit demand under EU General Safety Regulation. | |
| Backward Integration into Sensors | Secures piezoelectric element supply for radar-based ABS variants amid substrate shortages. | |
| Charging Infrastructure Partnership | Irrelevant to braking systems; replaced with: Certified Pre-Owned Refurbishment Program | Opens recurring revenue streams in underpenetrated Eastern European aftermarket channels. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, with primary interviews conducted among Tier 1 supplier procurement directors, OEM platform engineers, aftermarket distributors, and fleet operations managers across Germany, France, and Poland. Bottom-up triangulation combined vehicle production databases with IHS Markit registration data, validated against top-down ECE R13-H mandate implementation schedules and EU General Safety Regulation compliance tracking.
Segment-level granularity modeled vehicle class, propulsion architecture, content per vehicle, and regional production cluster across the projection horizon. CAGRs derived from regression analysis of historical fitment rates against regulatory mandate phase-in curves, with semiconductor supply constraints and thermal cycling material limitations incorporated as scenario inputs.
Caveats apply where silicon carbide substrate allocation protocols or divergent ANSM-KBA type-approval interpretations could materially shift the outlook. Forecasts reflect assumptions regarding EU AI Act implementation timelines and ECHA restricted substance enforcement. Practitioners should monitor ECE R13-H harmonization progress and captive foundry capacity announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Advanced Suspension Control System Market
Automotive Safety and Security Systems
Automotive Crash Sensor Market
Automotive Safety and Security Systems
Automotive Rear View Mirror Market
Automotive Safety and Security Systems
Automotive TPMS Market
Automotive Safety and Security Systems
Automotive Keyless Entry Access Systems Market
Automotive Safety and Security Systems
Front Collision Warning Market
Automotive Safety and Security Systems
Asia-Pacific Automotive Anti-Lock Braking System Market
Automotive Safety and Security Systems
Automotive HD/Imaging Radar Market
Automotive Safety and Security Systems
Motorcycle E-Call Market
Automotive Safety and Security Systems
Automotive Corner Sonar Market
Automotive Safety and Security Systems
Global Automotive Seat Belt Reminder Market
Automotive Safety and Security Systems
Middle East and Africa Automotive Adaptive Lighting System Market
Automotive Safety and Security Systems
Occupant Classification System Market
Automotive Safety and Security Systems
Automotive Anti-Roll Bar Market
Automotive Safety and Security Systems
Automatic Brake Pad Inspection System Market
Automotive Safety and Security Systems
Asia-Pacific Airbag Market