
 Leisure Boat Market | 2026-2036
Leisure Boat Market Size, Share, and Industry Trends Forecast 2026-2036
Leisure Boat Market Analysis
Skilled marine fiberglass laminator availability is collapsing across European and North American shipyards, compressing production schedules for custom hull orders. Brunswick Corporation leverages captive supply chains across its Mercury Marine propulsion division to buffer resin and engine shortages. Groupe Beneteau anchors its competitive stance through automated infusion molding investments that reduce manual layup labor by half. Ferretti Group dominates the superyacht segment with Italian design-house integration that sustains premium pricing power.
A leisure boat denotes a privately operated watercraft engineered for recreational navigation, typically constructed through resin-transfer molding of fiberglass-reinforced polymer laminates with gelcoat surface finishes, and designed to displace between 1,500 kg for personal watercraft and 500+ tonnes for megayachts. Motorboats lead volume shipments due to lower operator skill barriers and broader marina infrastructure compatibility, while personal watercraft registers the fastest growth trajectory among product types as rental services expand fleet accessibility. Yachts command the deepest margin pools, particularly in the 24-40 meter range where composite hull construction and bespoke interior fit-out justify substantial price premiums over standardized production models.
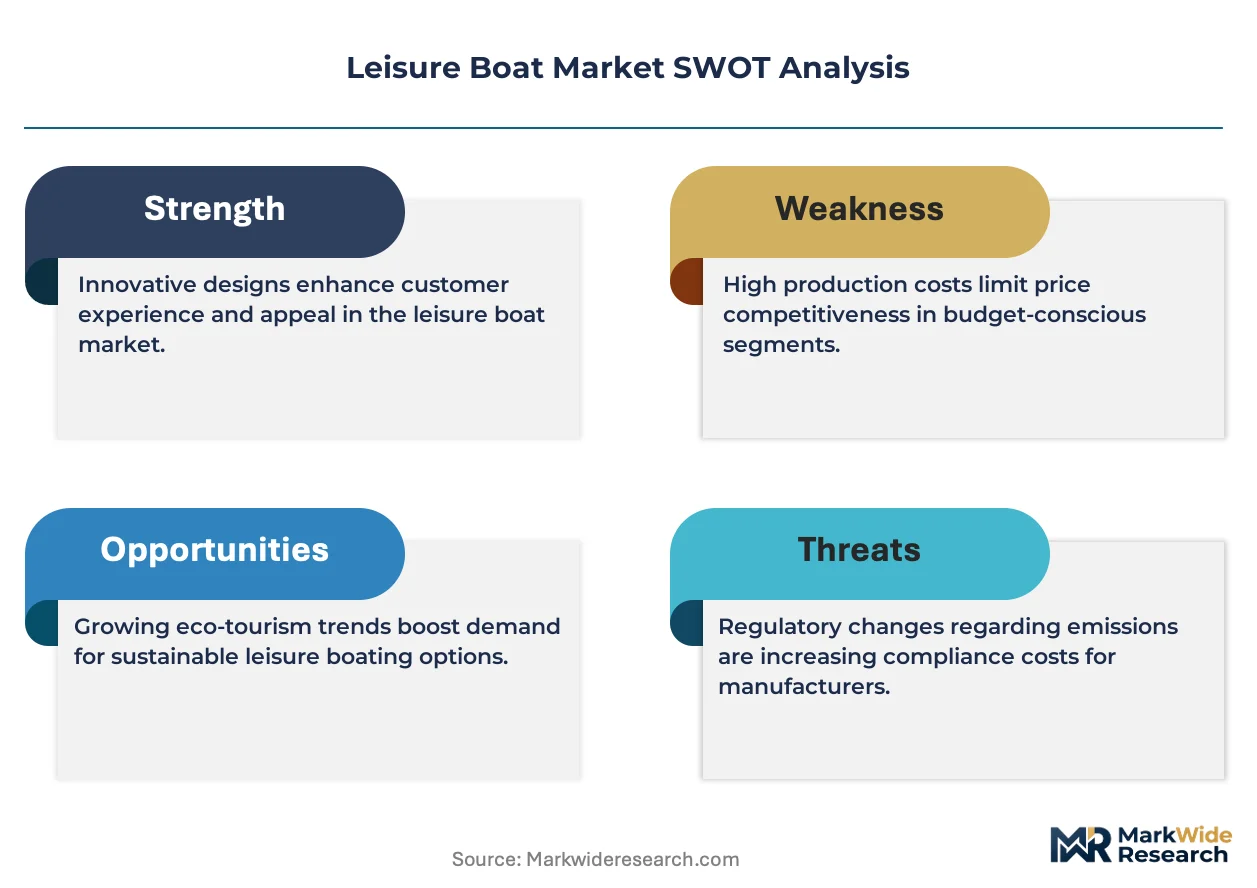
EPA marine engine emission standards under the Clean Air Act and the EU Green Deal's F-Gas Regulation are compelling powertrain electrification and alternative fuel adoption across OEM lineups. ISO 12217 stability and buoyancy standards govern hull certification for market access, while CE marking requirements enforce recreational craft safety compliance throughout European Economic Area waters. Stakeholders must monitor battery energy density improvements and shore charging infrastructure buildouts to assess when electric propulsion crosses total-cost thresholds against conventional diesel outboards.
Market Dynamics
Marine electrification mandates from EPA and EU Green Deal are forcing simultaneous redesign of hull laminates and propulsion architectures, compressing development cycles while resin-transfer molding capacity remains fixed.
Growth Catalysts
- EU Green Deal F-Gas Regulation:Decarbonization timelines accelerate electric outboard adoption across Mediterranean charter fleets, expanding replacement demand for compatible hull designs.
- Resin-transfer molding automation:Automated infusion systems reduce manual layup labor requirements, enabling production scale-up at shipyards facing laminator shortages.
- Queensland marina infrastructure:Gold Coast cluster expansion creates concentrated demand for trailerable cruisers and personal watercraft rental fleets.
Market Restraints
- Epoxy resin supply concentration:Petrochemical feedstock volatility and limited Asian supplier diversification create input cost instability for fiberglass hull production.
- Skilled laminator scarcity:European and North American shipyards face collapsing availability of qualified marine fiberglass technicians, extending custom order lead times.
- Battery energy density limitations:Lithium-ion pack weight-to-range ratios constrain electric propulsion viability for displacement hulls above 12-meter lengths.
Strategic Opportunities
- Shore charging infrastructure gaps:Marina operators in coastal Florida and the French Riviera seek integrated charging solutions, creating vendor partnership potential for OEMs.
- ISO 12217 certification premium:Stability standard compliance enables pricing differentiation for hull builders serving charter insurance markets.
- Personal watercraft rental channel:Fleet-as-a-service models bypass individual ownership barriers, opening volume demand from tourism operators.
Industry Challenges
- CE marking compliance timelines:Recreational craft safety certification delays create market access friction for new hull designs entering European Economic Area waters.
- Legacy diesel outboard integration:Hybrid propulsion architectures require reconciling electric drivetrains with existing transom mounting standards and service networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Leisure Boat Market |
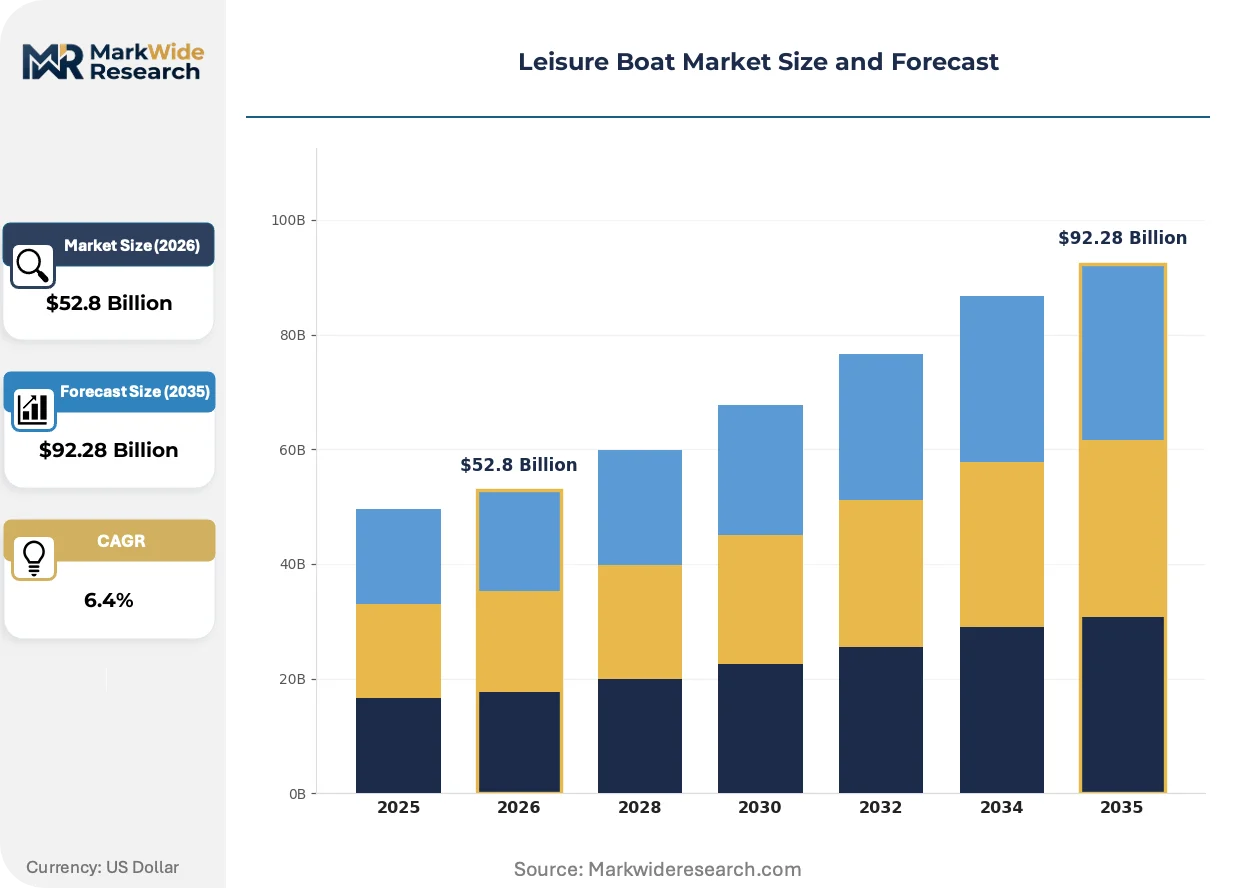
| Market Size in 2026 | $52.8 Billion |
| Market Size in 2035 | $92.28 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sailboats, Motorboats, Yachts, Personal Watercraft End User: Private Owners, Rental Services, Tour Operators, Commercial Users Material: Fiberglass, Aluminum, Wood, Composites Capacity: Small (1-4 persons), Medium (5-10 persons), Large (11-20 persons), Extra Large (21+ persons) |
| Companies Covered | Brunswick Corporation, Groupe Beneteau, Yamaha Motor Co., Ltd., Azimut Benetti Group, Ferretti Group, Bombardier Recreational Products, Sunseeker International Limited, Bavaria Yachtbau GmbH, Polaris Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Leisure Boat Market Emerging Trajectories
Propulsion electrification and automated composite manufacturing are restructuring competitive advantage around energy density and labor substitution rather than traditional engine displacement metrics.
Structural battery enclosures integrated into hull laminates are supplanting conventional lead-acid placement in deck compartments. Day-cruiser and weekender segments in the French Riviera adopt these systems fastest. This integration is supplanting separate battery box suppliers and compressing value chain margins for electrical subsystem vendors.
EPA marine engine emission standards under the Clean Air Act tighten hydrocarbon and NOx limits for outboard and sterndrive powertrains. OEMs accelerate dedicated electric platform development rather than adapting legacy combustion architectures. The 24-40 meter yacht segment responds slowest due to range requirements and shore power availability constraints in Mediterranean marinas.
Fractional ownership platforms and subscription-based fleet access are fragmenting traditional dealer-retail channels. Younger demographics in coastal Florida and Queensland bypass individual purchase in favor of hourly rental applications. This behavioral shift concentrates demand planning power with marina operators and tourism consolidators rather than dispersed private buyers.
Leisure Boat Market Segmentation
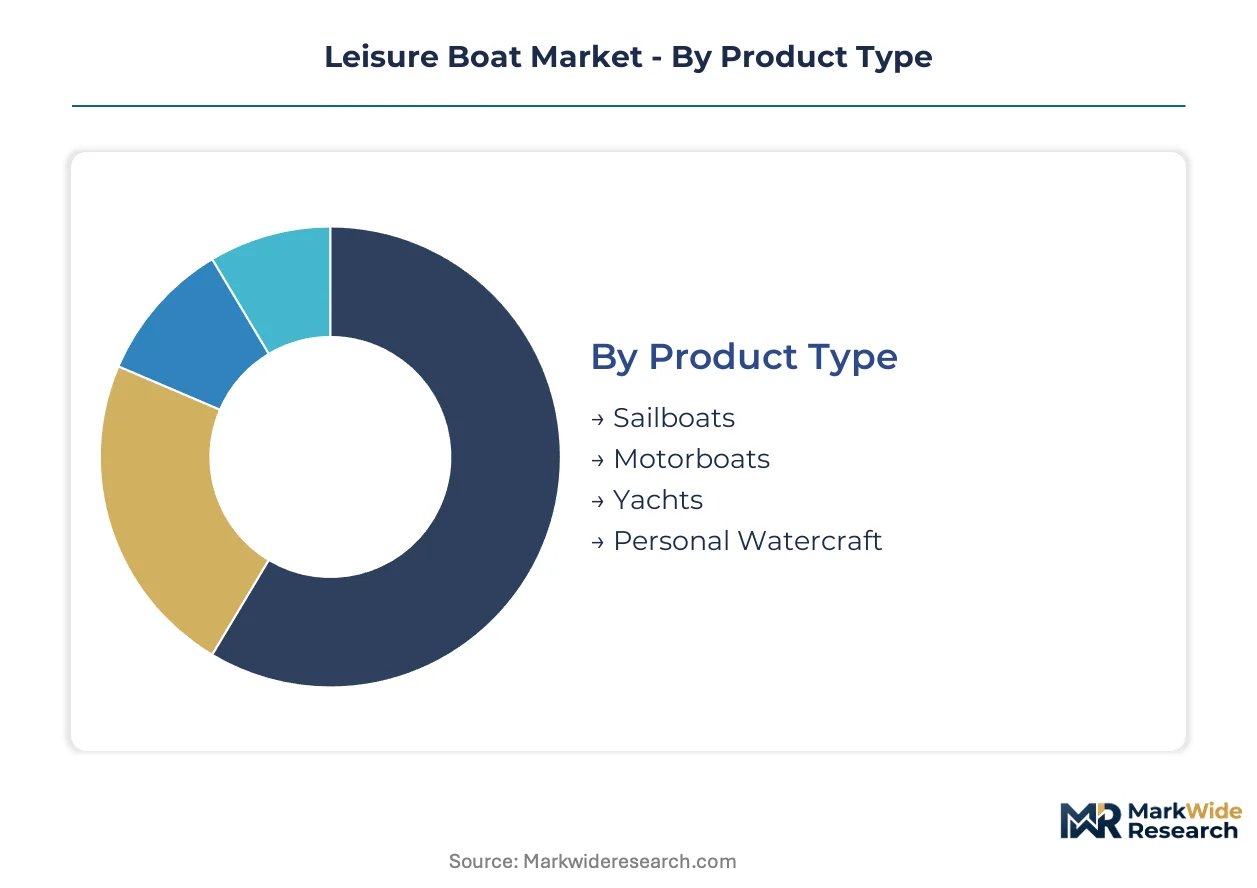
Leisure boat segmentation reveals how regulatory pressure and operational economics split demand across fundamentally different use cases. Hull material certification requirements and propulsion compatibility constraints create rigid boundaries between segments that manufacturers cannot easily bridge.
Product Type:
EPA marine engine standards and EU Green Deal mandates differentiate these categories through emission compliance pathways and electrification feasibility.
- Motorboats:Fiberglass-reinforced polymer hulls with sterndrive or outboard propulsion dominate production volumes due to lower operator certification requirements and universal marina infrastructure compatibility. Coastal Florida and Queensland Gold Coast clusters concentrate demand for trailerable cruisers in the 6-12 meter range as rental fleets expand.
- Personal Watercraft:Rotomolded polyethylene or composite hulls under 4 meters displace 1,500-2,500 kg and require minimal storage infrastructure. French Riviera tourism operators are replacing individual ownership with hourly rental models, compressing dealer-retail channels.
- Sailboats:Displacement hulls with auxiliary diesel or electric propulsion serve cruising enthusiasts seeking extended range without fuel dependency.
- Yachts:Custom composite construction in the 24-40 meter range commands premium pricing through bespoke interior fit-out and Italian design-house integration.
Motorboats handle the majority of throughput; personal watercraft is expanding most quickly on share.
End User:
Procurement authority concentration varies sharply, with rental services and tour operators consolidating volume while private ownership fragments.
- Rental Services:Fleet-as-a-service operators in Mediterranean charter corridors and Queensland marina clusters order standardized hull designs in bulk, bypassing traditional dealer networks. These buyers prioritize maintenance accessibility and insurance compliance over performance specifications.
- Private Owners:Dispersed individual purchasers in coastal Florida and the French Riviera drive demand for premium finishes and customization options, though fractional ownership platforms are fragmenting this segment.
- Tour Operators:Commercial marine tourism providers across Mediterranean corridors require ISO 12217 stability certification for insurance market access.
- Commercial Users:Workboat conversions and fishing charter operations favor aluminum hull durability over fiberglass weight advantages.
Rental services handle the majority of throughput; tour operators are gaining share fastest as Mediterranean fleet orders accelerate.
Material:
Cost tier and labor intensity separate these categories, with automated manufacturing disrupting traditional manual layup economics.
- Fiberglass:Resin-transfer molded FRP laminates with gelcoat finishes constitute the dominant hull construction method for motorboats and yachts under 40 meters. Groupe Beneteau's automated infusion systems reduce manual labor by half, addressing collapsing laminator availability across European shipyards.
- Aluminum:Welded plate hulls serve commercial fishing and patrol applications where impact resistance outweighs weight penalties.
- Wood:Traditional cold-molded or plank-on-frame construction persists in custom sailing yacht and classic restoration niches.
- Composites:Carbon fiber and advanced aramid reinforcements penetrate superyacht segments above 40 meters where strength-to-weight ratios justify material costs.
Fiberglass handles the majority of throughput; composites are climbing the fastest as structural battery integration demands advanced laminate properties.
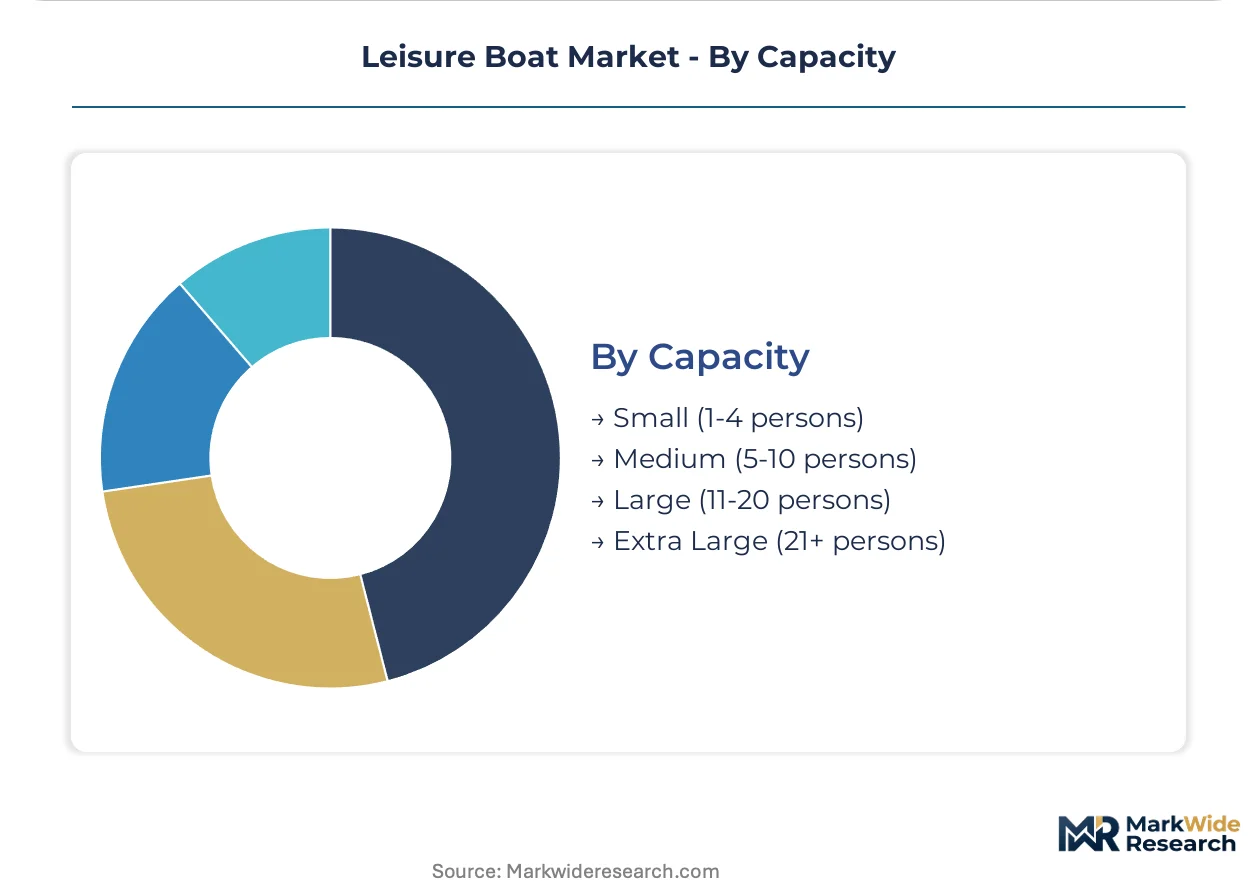
Capacity:
Marina berth economics and crew certification requirements create discrete demand clusters that hull builders must target precisely.
- Small (1-4 persons):Personal watercraft and day-cruisers under 6 meters dominate trailerable segments and hourly rental applications. Battery energy density constraints bite hardest here, limiting electric range for displacement hulls.
- Medium (5-10 persons):Weekender and coastal cruiser configurations in the 8-12 meter range balance accommodation space with marina berth affordability across French Riviera and Florida clusters.
- Large (11-20 persons):Extended cruising yachts require professional crew certification and specialized mooring infrastructure.
- Extra Large (21+ persons):Megayacht and superyacht segments above 24 meters concentrate in Italian and Dutch shipyards with captive design-house relationships.
Small capacity handles the majority of throughput; medium capacity shows the steepest expansion trajectory as rental services standardize fleet specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA marine engine standards anchor United States regulatory pressure, while EU Green Deal mandates reshape European fleet procurement. Coastal marina clusters concentrate replacement demand across three continents.
United States
Coastal Florida marina operators expand rental fleet orders for trailerable cruisers. EPA Clean Air Act emission standards tighten hydrocarbon limits on outboard powertrains. Miami-Dade and Fort Lauderdale clusters drive personal watercraft hourly rental growth among younger demographics bypassing ownership.
France
French Riviera tourism operators replace individual ownership with subscription fleet models. EU Green Deal F-Gas Regulation accelerates electric outboard adoption across Mediterranean charter corridors. Cannes and Nice marina infrastructure expansion concentrates demand for weekender vessels with integrated shore charging compatibility.
Italy
Italian design-house integration sustains premium pricing in the 24-40 meter yacht segment. CE marking requirements enforce recreational craft safety compliance throughout European Economic Area waters. Ferretti Group's captive supply chains dominate superyacht construction in Ligurian and Tuscan shipyard clusters.
Australia
Queensland Gold Coast marina expansion creates concentrated demand for personal watercraft rental fleets. ISO 12217 stability certification requirements govern insurance market access for commercial marine tourism operators. Brisbane-to-Gold Coast corridor operators standardize fleet specifications around medium-capacity trailerable designs.
Germany
Bavaria Yachtbau GmbH anchors production of standardized cruiser hulls for European rental channels. REACH chemical regulations constrain epoxy resin formulation options for fiberglass laminate suppliers. North Rhine-Westphalia and Bavarian industrial zones concentrate automated resin-transfer molding equipment manufacturing.
Leisure Boat Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with captive supply chains and automated manufacturing creating separation. Brunswick Corporation and Groupe Beneteau exemplify vertical integration archetypes, controlling propulsion and infusion molding respectively. Design-house integration and fleet-as-a-service platform development represent the dominant competitive moves reshaping channel relationships.
Among the integrated tier, Brunswick Corporation, Groupe Beneteau, and Ferretti Group occupy distinct positioning vectors. Brunswick exemplifies captive supply chain control across propulsion and hull production. Groupe Beneteau represents automated manufacturing scale addressing laminator scarcity. Ferretti Group anchors Italian design-house premium positioning in superyacht construction. These three entities illustrate how supply chain depth, labor substitution technology, and aesthetic differentiation create defendable market positions.
| Leading Market Players |
|---|
| Brunswick Corporation |
| Groupe Beneteau |
| Yamaha Motor Co., Ltd. |
| Azimut Benetti Group |
| Ferretti Group |
| Bombardier Recreational Products |
| Sunseeker International Limited |
| Bavaria Yachtbau GmbH |
| Polaris Industries |
| Others |
Supply Flow & Price Mechanics
CE marking requirements under the EU Recreational Craft Directive gate both supplier qualification and price tiering simultaneously, as hull builders serving European Economic Area waters must absorb certification costs that standard-tier competitors cannot shoulder. This regulatory threshold concentrates pricing power among certified manufacturers while compressing margins for uncertified entrants.
Pricing Analysis
Coastal Florida marina operators pay 15-25% premiums for ISO 12217-certified hulls versus uncertified equivalents from Asian suppliers. Three-tier pricing structure across premium, standard, and economy levels separates Italian design-house yachts from automated-infusion cruisers and basic rotomolded personal watercraft. Cost compression in the standard tier is intensifying because epoxy resin feedstock volatility erodes fixed-price contract viability. Rental services exhibit highest price sensitivity, while superyacht buyers show minimal elasticity to hull cost escalation.
Supply Chain Analysis
Epoxy resin formulation expertise concentrates in Germany, South Korea, and China, creating single-source vulnerability for European hull laminators facing REACH chemical constraints. Petrochemical feedstocks, gelcoat additives, and marine-grade fiberglass roving draw from Asian suppliers subject to tariff exposure under evolving trade regimes. Distribution runs through captive dealer networks for private buyers and direct fleet procurement for marina operators consolidating rental demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement authority is concentrating among fleet-as-a-service operators and Mediterranean tourism consolidators, fragmenting traditional dealer-retail channels and shifting negotiating leverage toward volume buyers.
For Market Incumbents: Consolidate laminator talent pools through apprenticeship partnerships with North Rhine-Westphalia technical institutes before European shipyard labor scarcity deepens. Lock resin supply contracts with German petrochemical suppliers to buffer Asian feedstock volatility. Defend against automated-infusion competitors by embedding shore charging compatibility into hull designs for French Riviera marina electrification timelines. For New Entrants and Emerging Players: Hourly rental platform software gaps in Queensland Gold Coast clusters offer white-space entry beneath incumbent OEM fleet management systems. Target trailerable cruiser segments where Brunswick Corporation's captive supply chains lack rental-channel specialization. Pursue marina operator partnerships rather than dealer network buy-in to bypass established distribution barriers. For Investors and Strategic Acquirers: EU Green Deal F-Gas Regulation reshapes the acquisition landscape toward electric-compatible hull designers and shore infrastructure integrators. Long-term viability hinges on exposure to Mediterranean charter fleet electrification rather than legacy diesel outboard dependency. Monitor battery energy density improvement trajectories as the inflection signal for when electric propulsion crosses total-cost thresholds against conventional powertrains.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Infusion Molding Scale-Up | Groupe Beneteau's labor substitution halves manual layup requirements while compressing custom order lead times. |
| Structural Battery Hull Integration | French Riviera day-cruiser adoption displaces separate battery box suppliers and compresses electrical subsystem margins. |
| Shore Charging Infrastructure Partnership | Marina operators in coastal Florida seek integrated solutions, creating vendor lock-in potential for compatible hull OEMs. |
| ISO 12217 Certification Investment | Stability compliance enables insurance market access for Mediterranean charter operators consolidating fleet procurement. |
| Fractional Ownership Platform Development | Younger demographics in Queensland bypass individual purchase, concentrating demand planning with tourism consolidators. |
Methodological Framework
Desk research of customs trade databases, SEC 10-K filings, and EU regulatory submissions preceded structured interviews with shipyard operations directors, marina fleet procurement managers, marine insurance underwriters, and epoxy resin procurement leads. Primary fieldwork across Mediterranean charter corridors and Queensland marina clusters validated secondary estimates of fleet replacement cycles. Bottom-up hull production tallies triangulated against top-down tourism expenditure models.
Variance decomposition across propulsion architecture, hull material certification, and regional marina infrastructure density shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include product type, capacity tier, end-user procurement authority, and geographic regulatory cluster. CAGRs derived from regression against historical fleet replacement patterns and tourism operator capex intentions, with battery energy density improvement curves and resin price volatility indices as industry-specific forecast inputs.
Forecasts assume regulatory continuity in EPA marine engine standards and EU Green Deal implementation timelines; material policy shifts would require re-modeling of electrification adoption curves and hull redesign cost amortization. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recreational Vehicles
Global Recreational Off-Highway Vehicles Market
Recreational Vehicles
North America Motorhome Market
Recreational Vehicles
Recreational Boating Market
Recreational Vehicles
Europe Luxury Yacht Market
Recreational Vehicles
Automotive Trailer Market
Recreational Vehicles
North America Recreational Vehicle Market
Recreational Vehicles
Recreational Vehicle Parks and Campgrounds Market
Recreational Vehicles
Europe Recreational Vehicle Market
Recreational Vehicles
Camping Trailer Market
Recreational Vehicles
Kick Scooter Market
Recreational Vehicles
Global Houseboats Market
Recreational Vehicles
United States RV Rental Market
Recreational Vehicles
Hovercraft Market
Recreational Vehicles
Segway Market
Recreational Vehicles
Global Recreational Vehicle (RV) Market
Recreational Vehicles
Self Balancing Scooter Market