
 Automotive Electric Power Steering ECU Market | 2026-2036
Automotive Electric Power Steering ECU Market Size, Share, and Industry Trends Forecast 2026-2036
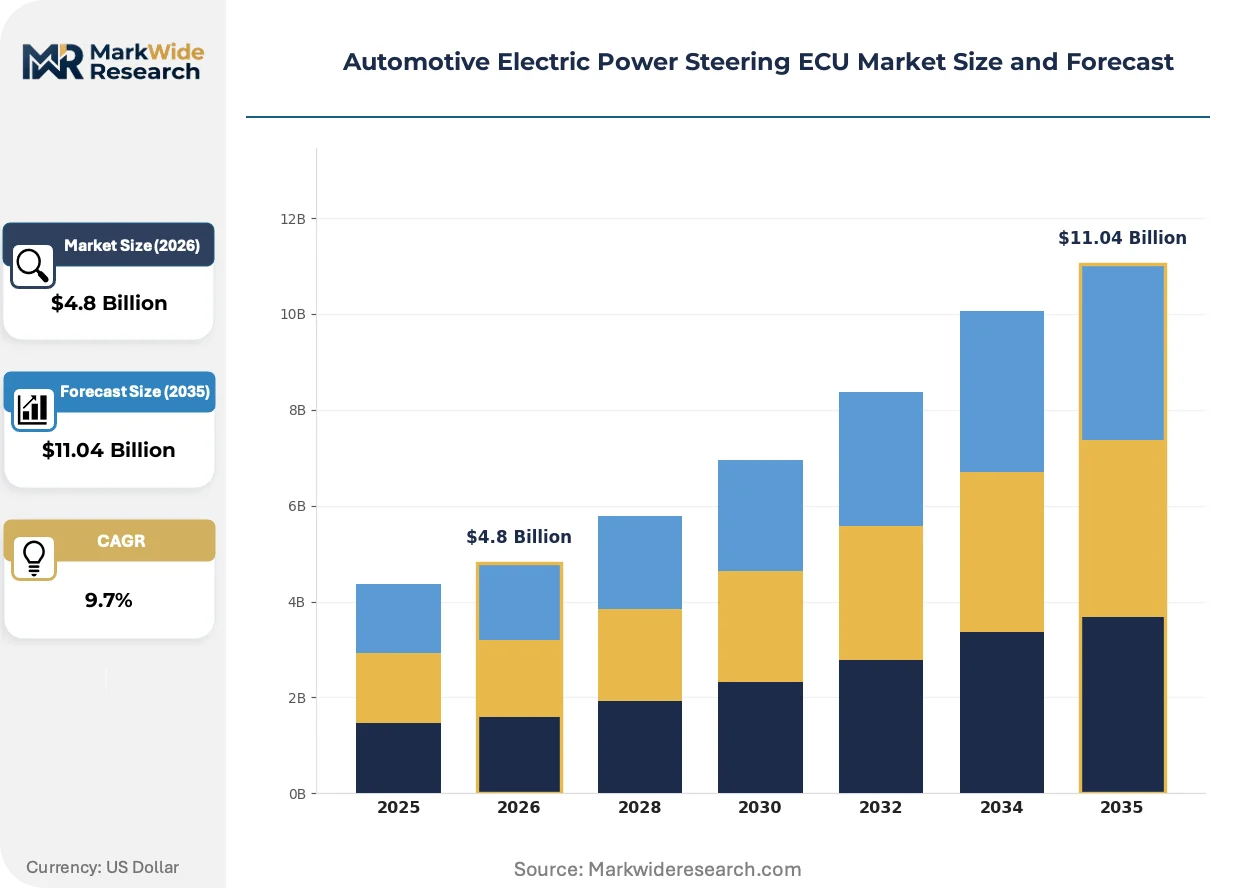
Automotive Electric Power Steering ECU Market Outlook
Electric vehicle platforms are redrawing purchasing patterns among buyer archetypes, with OEMs overtaking Tier-1 suppliers as the dominant ECU procurement channel. Robert Bosch GmbH leverages its integrated sensor-to-actuator portfolio to anchor supply relationships with German and Chinese automakers. Denso Corporation sustains manufacturing scale advantages through captive semiconductor sourcing and proximity to Toyota's global assembly network. JTEKT Corporation specializes in column-assisted architectures, occupying a defensible position in compact vehicle segments where packaging constraints dominate design decisions.
An automotive electric power steering ECU is an embedded electronic control unit that modulates torque assistance through pulse-width modulation signals to brushless DC motors, typically operating at 12V or 48V depending on vehicle electrical architecture, with functional safety ratings up to ASIL-D under ISO 26262. Its primary commercial purpose is to reduce driver steering effort while enabling lane-keeping and automated parking interventions through real-time CAN bus integration. Rack-assisted configurations lead volume shipments due to their compatibility with heavier vehicle platforms, while digital control technology is displacing analog systems as automakers mandate over-the-air update capability. Factory-fitted installation dominates revenue pools, though retro-fitted channels are gaining traction in commercial fleet electrification programs where older chassis require steering system modernization.
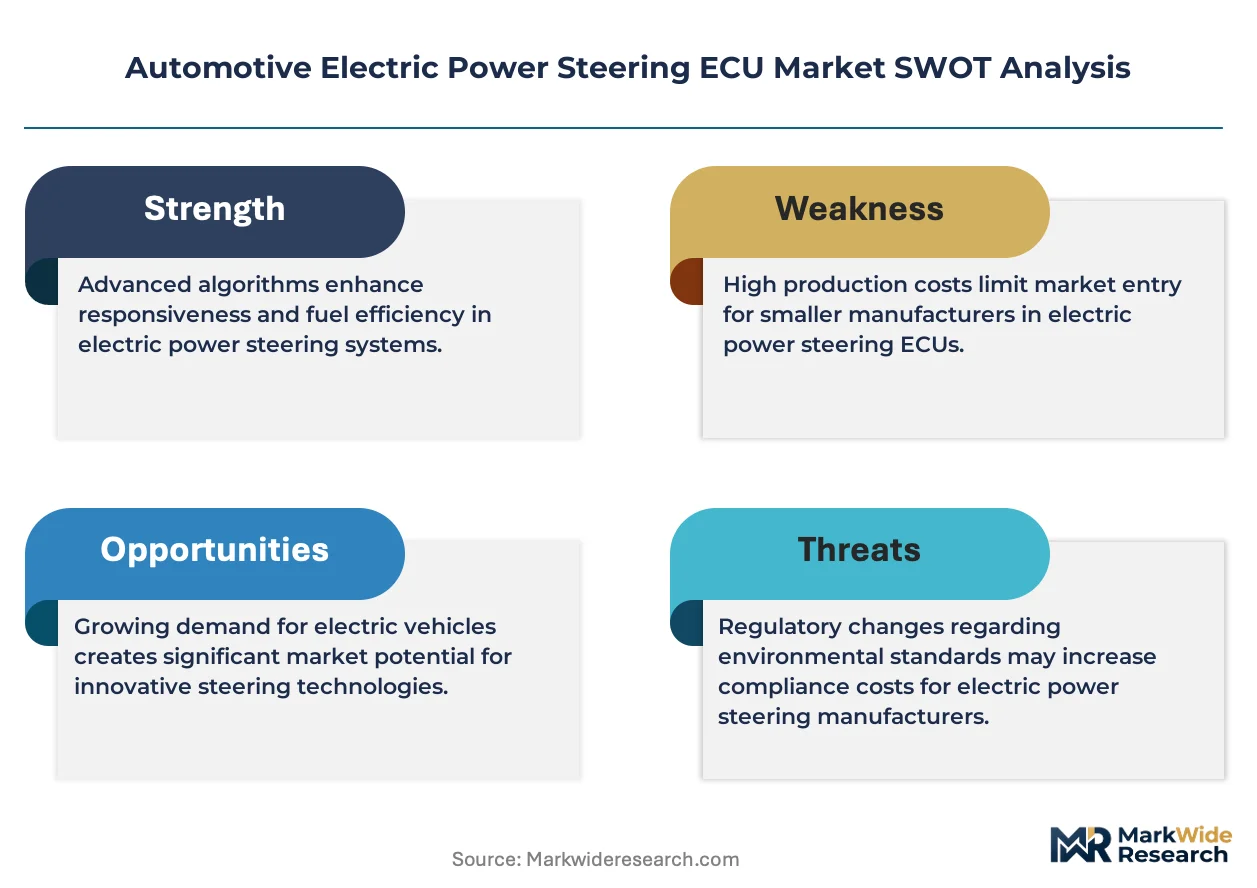
The US NHTSA Federal Motor Vehicle Safety Standards and EPA fuel economy regulations jointly compel ECU designs that optimize energy recovery during steering maneuvers, while China's GB standards and MIIT new-energy vehicle mandates enforce domestic sourcing ratios for steering electronics. Japan's METI roadmap for autonomous driving and JIS functional safety certifications create additional compliance layers for suppliers serving Japanese OEMs. Stakeholders must monitor divergence between regional cybersecurity standards for connected steering systems and the capital allocation trade-offs required to maintain parallel certification pathways across major automotive markets.
Market Dynamics
OEMs are consolidating ECU procurement authority away from Tier-1 suppliers as steer-by-wire architectures demand tighter integration between steering electronics and autonomous driving compute stacks. This vertical reorganization is compressing supplier margins while elevating firmware control as the primary competitive battleground.
Growth Catalysts
- China's MIIT dual carbon mandates:Domestic automakers must source energy-efficient steering electronics to comply with carbon intensity targets, creating guaranteed demand for 48V rack-assisted ECUs in new-energy vehicle platforms.
- Sensor fusion convergence:Integration of torque sensors with lidar and camera data streams enables predictive steering interventions, accelerating replacement cycles for analog-control legacy units.
- East Asian manufacturing corridors:Concentrated assembly capacity across Japan, South Korea, and coastal China reduces logistics costs and accelerates OEM prototype-to-production timelines.
Market Restraints
- Semiconductor supply concentration:Captive silicon sourcing by integrated Tier-1s limits independent ECU vendors' access to automotive-grade microcontrollers, constraining production scalability.
- 48V electrical architecture transition costs:Heavy vehicle platforms require dual-voltage ECU designs that increase bill-of-materials complexity and certification overhead.
- Functional safety certification timelines:ISO 26262 ASIL-D validation cycles extend 18-24 months, freezing design iterations and delaying revenue recognition for new entrants.
Strategic Opportunities
- Commercial fleet retro-fit channels:Electrification programs for aging delivery and municipal vehicle chassis create aftermarket demand for modernized steering ECUs with CAN bus connectivity.
- Software-defined vehicle architectures:Over-the-air update capability requirements position firmware-agnostic ECU platforms to capture share from hardware-locked legacy suppliers.
- Japan's METI autonomous driving roadmap:Tier-2/3 supplier qualification pathways under national safety frameworks open procurement access for specialized column-assisted ECU vendors.
Industry Challenges
- Embedded systems firmware talent scarcity:Shortage of engineers with ISO 26262 functional safety expertise extends development timelines and inflates compensation costs.
- Legacy vehicle integration complexity:Retro-fitting modern ECUs into analog-era steering columns requires mechanical adapter engineering that erodes margin on low-volume fleet orders.
- Parallel cybersecurity certification:Divergent regional standards for connected steering systems force redundant engineering tracks, fragmenting R&D allocation across NHTSA, EU AI Act, and domestic Chinese frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Electric Power Steering ECU Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Column-Assisted, Rack-Assisted, Electro-Hydraulic, Electro-Mechanical End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers Technology: Digital Control, Analog Control, Hybrid Systems, Wireless Systems Installation: Factory-Fitted, Retro-Fitted, Integrated, Direct Replacement |
| Companies Covered | JTEKT Corporation, Robert Bosch GmbH, NSK Ltd., Nexteer Automotive, ZF Friedrichshafen AG, Mitsubishi Electric Corporation, Denso Corporation, Hyundai Mobis, Hitachi Astemo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Electric Power Steering ECU Market Strategic Shifts
Digital control architectures are displacing analog systems as automakers mandate firmware updateability throughout vehicle lifecycles. Three interconnected developments are restructuring supplier competitive positions.
Brushless DC motor control algorithms are bifurcating between 12V and 48V electrical architectures, with each voltage class demanding distinct pulse-width modulation strategies and thermal management protocols. Compact vehicle OEMs favor 12V column-assisted designs for packaging efficiency, while heavy platform manufacturers specify 48V rack-assisted units for torque density. This voltage split is forcing ECU vendors to maintain parallel hardware SKUs and qualification pathways, compressing economies of scale.
China's GB standards for new-energy vehicle safety are mandating domestic sourcing ratios for steering electronics, compelling foreign suppliers to establish localized firmware development centers. The MIIT enforcement mechanism ties vehicle homologation approval to verified supply chain documentation, altering procurement patterns for German and Japanese automakers operating joint ventures. Tier-1 suppliers are responding by transferring ECU assembly to wholly-owned facilities in Jiangsu and Guangdong provinces.
Fleet operators are unbundling steering system service contracts from traditional vehicle maintenance agreements, creating direct procurement relationships with ECU vendors for predictive health monitoring. Logistics companies operating heavy-duty electric trucks in California and Texas are piloting usage-based firmware licensing that ties steering assistance calibration to actual duty cycles. This consumption-pattern shift bypasses established Tier-1 distribution channels and exposes ECU pricing to direct negotiation with asset managers rather than OEM purchasing departments.
Automotive Electric Power Steering ECU Market Segmentation
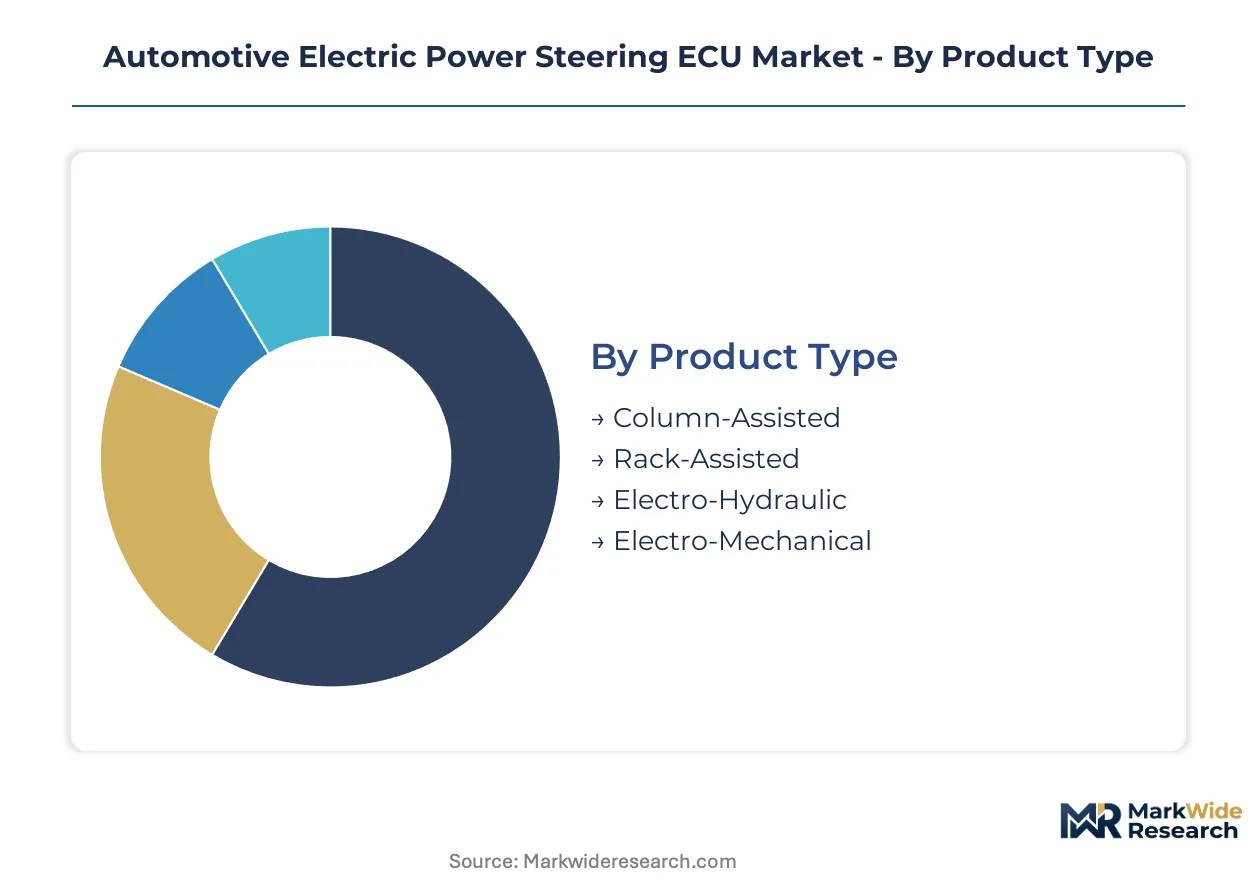
ECU procurement patterns diverge sharply across product architectures and customer channels, with voltage class and integration depth determining margin capture. Segment boundaries are blurring as steer-by-wire platforms force hardware-software bundling decisions.
Product Type:
Margin pools concentrate in rack-assisted architectures serving heavy vehicle platforms, while column-assisted variants defend volume through compact vehicle penetration.
- Column-Assisted:Torque motors mount directly to the steering column, delivering 12V pulse-width modulation control for subcompact and compact vehicle segments. Japanese OEMs in Toyota's supply network favor this architecture for packaging efficiency in kei cars and city vehicles where engine bay space is constrained.
- Rack-Assisted:Brushless DC motors integrate with the steering rack itself, enabling 48V operation and higher torque density for SUVs, trucks, and commercial platforms. Chinese new-energy vehicle manufacturers under MIIT dual carbon mandates are specifying these units for battery-electric heavy platforms where steering loads exceed column-assisted capacity.
- Electro-Hydraulic:Hybrid architectures combining electric motor control with hydraulic power assistance, retaining relevance in legacy commercial vehicle retro-fit programs.
- Electro-Mechanical:Fully electric actuation without hydraulic backup, gaining traction in autonomous driving prototypes requiring deterministic response times.
Rack-Assisted holds installed capacity. Column-Assisted is rotating up the share rankings.
End User:
Procurement authority is migrating upstream as vehicle assemblers internalize ECU specification control.
- OEMs:Direct procurement of steer-by-wire ready ECUs for next-generation autonomous platforms, bypassing traditional Tier-1 distribution. German and Chinese automakers are establishing captive firmware development centers to control steering system roadmaps.
- Aftermarket Providers:Fleet electrification programs for municipal and delivery vehicles create demand for CAN bus-enabled retro-fit units with predictive health monitoring.
- Tier-1 Suppliers:Losing share in steering electronics as OEMs consolidate procurement, though retaining assembly relationships through joint venture structures in Jiangsu and Guangdong provinces.
- Vehicle Assemblers:Contract manufacturers and joint venture partners specifying ECU variants for localized production under China's domestic sourcing ratio requirements.
OEMs hold installed capacity. Aftermarket Providers are rotating up the share rankings.
Technology:
Digital architectures command premium pricing through over-the-air update capability, while analog systems face replacement cycles.
- Digital Control:Microcontroller-based pulse-width modulation with firmware updateability, ASIL-D functional safety certification, and real-time sensor fusion integration. Automakers in Japan's METI autonomous driving roadmap mandate digital architectures for lane-keeping and automated parking interventions.
- Analog Control:Discrete component-based motor drive circuits, still shipping in cost-optimized emerging market vehicles but facing obsolescence as cybersecurity standards tighten.
- Hybrid Systems:Mixed-signal architectures bridging legacy analog actuation with digital supervisory control, serving transition vehicle platforms.
- Wireless Systems:Experimental steer-by-wire prototypes eliminating mechanical steering columns entirely, piloted in California and Texas autonomous trucking corridors.
Digital Control holds installed capacity. Wireless Systems are rotating up the share rankings.
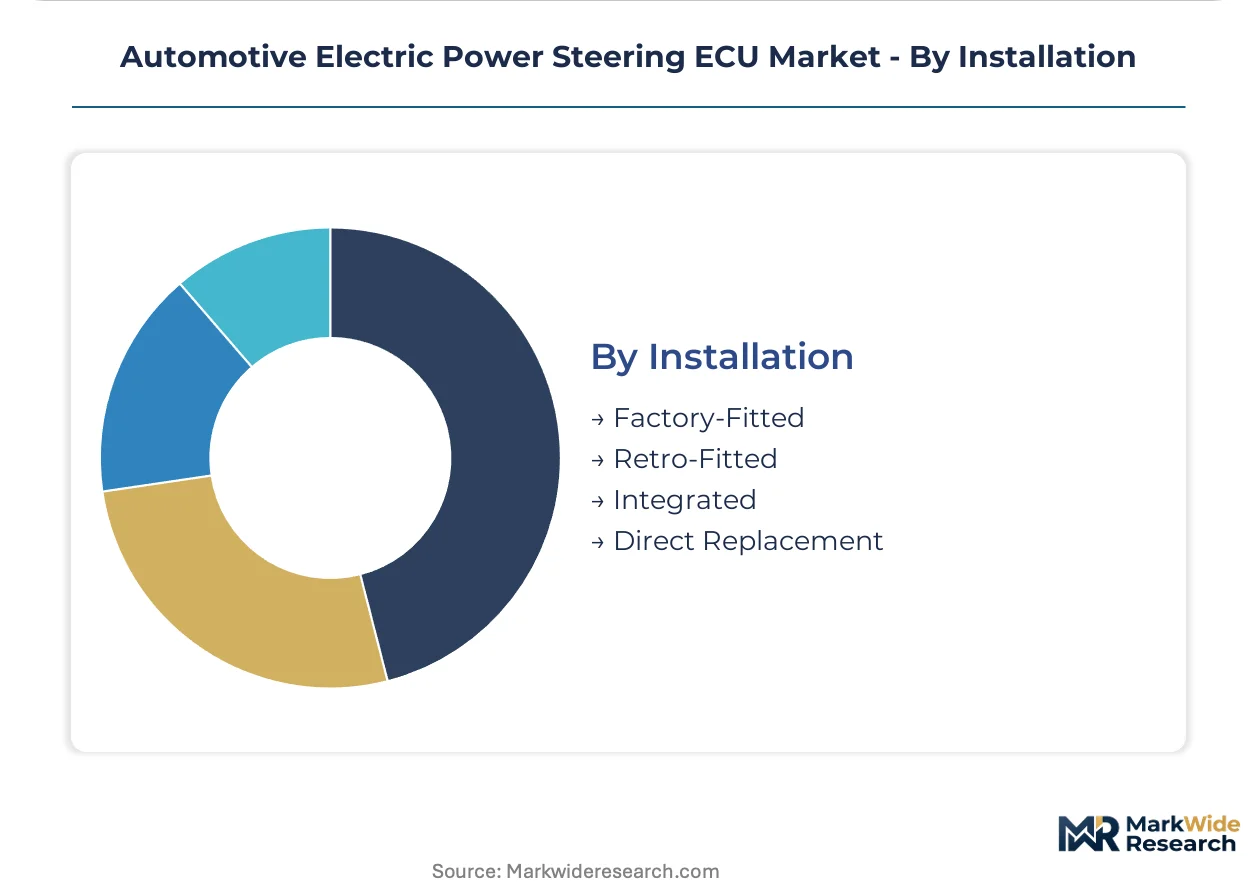
Installation:
Factory integration captures value through warranty bundling, though retro-fit channels open direct fleet relationships.
- Factory-Fitted:ECU calibration matched to vehicle platform at assembly, with firmware locked to specific steering rack and sensor combinations. Dominates revenue pools through OEM warranty coverage and homologation traceability.
- Retro-Fitted:Aftermarket installation in aging chassis undergoing electrification conversion, requiring mechanical adapter engineering and CAN bus gateway integration for legacy vehicle networks.
- Integrated:ECUs bundled with complete steering system modules from Tier-1 suppliers, reducing OEM assembly complexity.
- Direct Replacement:Service-part ECUs for warranty repairs and collision replacement, sourced through dealer networks.
Factory-Fitted holds installed capacity. Retro-Fitted is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
OEM procurement authority concentrates in East Asian manufacturing corridors, with German automakers and Chinese joint ventures driving parallel demand centers for steer-by-wire ready ECUs.
China
Domestic automakers under MIIT dual carbon mandates are specifying 48V rack-assisted ECUs for battery-electric heavy platforms. GB standards for new-energy vehicle safety enforce domestic sourcing ratios for steering electronics, compelling foreign suppliers to transfer assembly to wholly-owned facilities in Jiangsu and Guangdong provinces. Shanghai and Shenzhen automotive clusters host captive firmware development centers serving German and Japanese joint ventures.
Japan
Toyota's supply network favors column-assisted architectures for packaging efficiency in kei cars and city vehicles. METI's autonomous driving roadmap mandates digital control architectures with ASIL-D certification for lane-keeping interventions. Kanto and Chubu manufacturing regions sustain proximity advantages between Denso Corporation and Toyota's global assembly network.
Germany
German automakers are establishing captive firmware development centers to control steering system roadmaps for next-generation autonomous platforms. KBA vehicle type approval requirements intersect with EU AI Act cybersecurity standards for connected steering systems. Bavaria and Baden-Württemberg anchor supplier relationships with Robert Bosch GmbH through integrated sensor-to-actuator portfolios.
United States
NHTSA Federal Motor Vehicle Safety Standards and EPA fuel economy regulations compel ECU designs that optimize energy recovery during steering maneuvers. California and Texas logistics companies pilot usage-based firmware licensing for heavy-duty electric truck fleets. Michigan and Ohio manufacturing bases retain legacy assembly relationships despite OEM consolidation of procurement authority.
South Korea
Hyundai Mobis anchors domestic ECU supply for Hyundai-Kia platforms targeting export markets with 48V electrical architectures. MFDS automotive safety certifications align with ISO 26262 functional safety requirements for steer-by-wire prototypes. Gyeonggi-do and Busan-Ulsan industrial corridors concentrate assembly capacity serving battery-electric SUV and commercial vehicle programs.
Automotive Electric Power Steering ECU Market Competitive Environment
Player mix skews toward integrated Tier-1 suppliers with captive semiconductor sourcing and sensor-to-actuator portfolios. Market structure concentrates procurement relationships around three to four dominant system integrators, with mid-scale specialists defending positions in column-assisted segments. Strategic archetypes include integrated electronics conglomerates, steering-system pure-plays, and captive automotive suppliers. Competitive moves center on firmware control consolidation and geographic relocation of assembly capacity to satisfy domestic sourcing mandates.
Within the integrated Tier-1 tier, Robert Bosch GmbH and Denso Corporation exemplify archetypes combining semiconductor access with proximity to major OEM assembly networks. JTEKT Corporation occupies a position among steering-system specialists with defensible column-assisted expertise. Hyundai Mobis represents the captive supplier model, anchoring domestic Korean demand while expanding export relationships. These three patterns illustrate how supplier positioning stratifies across voltage classes, functional safety certification depth, and geographic proximity to East Asian manufacturing corridors.
| Leading Market Players |
|---|
| JTEKT Corporation |
| Robert Bosch GmbH |
| NSK Ltd. |
| Nexteer Automotive |
| ZF Friedrichshafen AG |
| Mitsubishi Electric Corporation |
| Denso Corporation |
| Hyundai Mobis |
| Hitachi Astemo |
| Others |
Value Chain & Pricing Dynamics
Captive semiconductor fabrication at Denso Corporation and Robert Bosch GmbH generates 40-60% unit cost advantages over fabless competitors, compressing price floors for rack-assisted ECUs while elevating margin capture for integrated Tier-1s serving Chinese new-energy vehicle platforms under MIIT dual carbon mandates.
Pricing Analysis
Cost-plus contracts with raw material indexation to copper and rare-earth magnet prices dominate procurement between Japanese OEMs and their captive suppliers. Pricing stratifies across premium, standard, and economy tiers based on ASIL-D certification depth and 48V versus 12V voltage class. Cost compression in economy-tier column-assisted units is intensifying because Chinese domestic suppliers are absorbing margin to secure MIIT homologation slots. Fleet operators retrofitting commercial chassis exhibit highest price sensitivity, while German automakers establishing captive firmware centers show lowest sensitivity due to roadmap control priorities.
Supply Chain Analysis
Automotive-grade microcontroller inventory cycles extending 26-32 weeks force OEMs to hold 90-day safety stock for steer-by-wire ECUs, inflating working capital requirements. Manufacturing concentrates in Japan, South Korea, and coastal China, with Jiangsu and Guangdong provinces hosting transferred assembly lines to satisfy GB standards domestic sourcing ratios. Supply chains rest on silicon carbide power modules, rare-earth permanent magnets, and high-temperature PCB substrates. Single-source vulnerability around TSMC-fabricated automotive MCUs creates concentration risk. Distribution runs through Tier-1 system integrators with direct OEM relationships, bypassing traditional electronics distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive electric power steering ECU market is exiting a semiconductor-constrained trough, with cyclical recovery justified by MIIT dual carbon procurement mandates guaranteeing demand visibility through the forecast horizon.
For Market Incumbents: Compound firmware control advantages by acquiring ISO 26262 functional safety engineering teams in Romania and Poland, countering talent scarcity that delays ASIL-D certification cycles. Deepen backward integration into silicon carbide power module packaging to defend margin position against Chinese domestic suppliers capturing MIIT homologation slots through cost absorption. For New Entrants and Emerging Players: Anchor in commercial fleet retro-fit channels where mechanical adapter engineering requirements deter integrated Tier-1s from low-volume orders. Target municipal electrification programs in California and Texas with CAN bus gateway integration capabilities. Pursue direct procurement relationships with logistics asset managers unbundling steering service contracts from traditional vehicle maintenance agreements. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors firmware-agnostic ECU platforms with over-the-air update architectures over hardware-locked legacy suppliers. Long-term viability through the technology transition window hinges on steer-by-wire qualification pathways. Acquisition candidates should demonstrate Japan METI autonomous driving roadmap compliance or China's GB standards localization. The signal to watch is Tier-2 supplier qualification velocity under national safety frameworks.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Firmware Development Center | German and Chinese automakers internalize steering system roadmaps for autonomous platforms. |
| 48V Rack-Assisted ECU Localization | Foreign suppliers transfer assembly to Jiangsu and Guangdong to satisfy MIIT domestic sourcing ratios. |
| Commercial Fleet Retro-Fit Channel | Direct procurement relationships with logistics asset managers bypass Tier-1 distribution. |
| ASIL-D Functional Safety Certification | Japanese METI autonomous driving roadmap mandates digital architectures for lane-keeping interventions. |
| Rare-Earth Magnet Supply Agreement | Long-term offtake contracts with Chinese processors secure torque motor production capacity. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of vehicle production databases, IHS Markit registration data, SEC filings from listed automotive suppliers, and MIIT new-energy vehicle homologation records. Interviews conducted with Tier-1 supplier procurement directors, OEM platform engineers, aftermarket distributors, and dealership operations managers. Bottom-up unit shipment estimates triangulate against top-down OEM production schedules across voltage classes and steering architectures.
Segmentation dimensions modeled include product architecture (column-assisted, rack-assisted, electro-hydraulic, electro-mechanical), end-user channel (OEM direct, aftermarket, Tier-1, vehicle assembler), technology generation (digital, analog, hybrid, wireless), and installation type (factory-fitted, retro-fitted, integrated, direct replacement). CAGRs derive from regression analysis of historical procurement patterns and OEM platform launch timelines, incorporating 48V electrical architecture transition curves and steer-by-wire adoption rates across the projection horizon.
Decision-makers should treat outputs as directional under assumptions of sustained MIIT enforcement of domestic sourcing ratios and stable semiconductor supply normalization; material deviation in either factor would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electrical & Electronics
India Automotive Sensors Market
Automotive Electrical & Electronics
Global Automotive Electronic Lock Differential Market
Automotive Electrical & Electronics
Global Automotive Charge Air Cooler Market
Automotive Electrical & Electronics
Automotive Pressure Sensors Market
Automotive Electrical & Electronics
Switchrack Assemblies Market
Automotive Electrical & Electronics
Automotive Rotor Position Sensor for E-Axle Market
Automotive Electrical & Electronics
Automotive Electronic Manufacturing Services Market
Automotive Electrical & Electronics
Jump Starter Market
Automotive Electrical & Electronics
UK Automotive Eps Market
Automotive Electrical & Electronics
Automotive Engine Management Sensors Market
Automotive Electrical & Electronics
Automotive Thermoelectric Generator Market
Automotive Electrical & Electronics
Africa and Middle East Automotive Tpms Market
Automotive Electrical & Electronics
Automotive Esim Market
Automotive Electrical & Electronics
Bicycle Electronic Drivetrain Market
Automotive Electrical & Electronics
New Energy Automotive Antenna Module Market
Automotive Electrical & Electronics
Car Satellite Antenna Market