
 Australia Recreational Vehicle Rental Market | 2026-2036
Australia Recreational Vehicle Rental Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Recreational Vehicle Rental Market Outlook
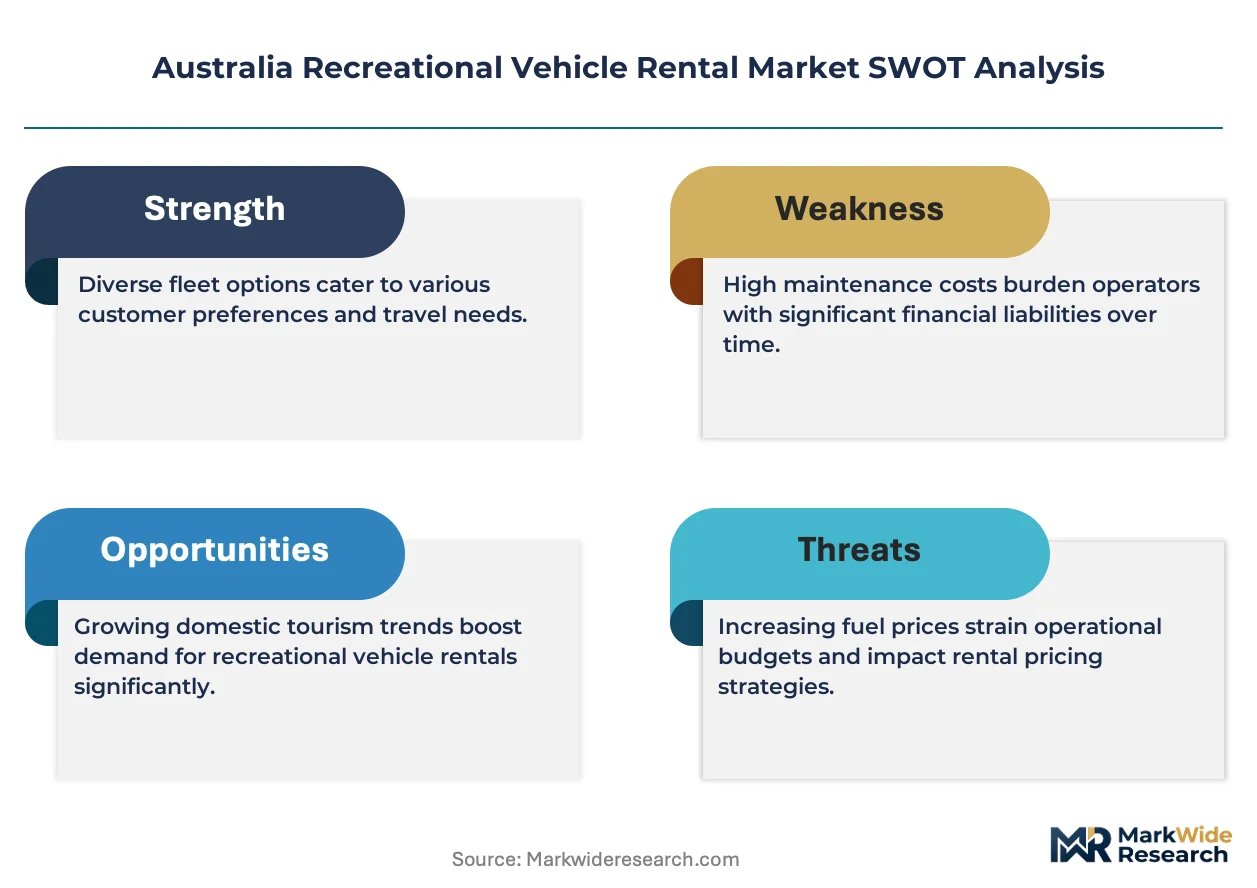
Qualified RV technician shortages across Queensland and New South Wales is unwinding fleet expansion plans for several operators. Apollo Motorhomes leverages its captive maintenance network to sustain higher vehicle utilization rates than regional peers. Britz Campervans dominates the premium motorhome tier through controlled distribution at major airport hubs. Cheapa Campa competes aggressively on entry-level caravan pricing, anchoring volume in the budget-conscious domestic segment.
Recreational vehicle rental denotes the short-term commercial provision of self-propelled or towable living accommodations, typically featuring sleeping berths, kitchenettes, and onboard sanitation systems with gross vehicle masses ranging from 2.5 to 7.5 tonnes, primarily serving holiday travelers seeking mobile lodging alternatives. Motorhome configurations command the largest revenue share due to integrated drivetrain convenience and all-weather habitability, while campervan rentals represent the fastest-growing vehicle type among solo travelers and couples prioritizing fuel economy and urban maneuverability. Online platforms now capture the dominant booking channel as direct-to-consumer interfaces reduce intermediary commissions and enable dynamic fleet pricing.
TGA vehicle safety standards govern RV structural integrity and roadworthiness certification, directly shaping fleet replacement cycles and capital deployment timelines. State-level environmental regulations in Queensland and Western Australia increasingly restrict overnight parking in sensitive coastal zones, redirecting demand toward designated holiday park infrastructure. Stakeholders must monitor evolving state tourism board funding allocations for RV-friendly infrastructure, as these commitments determine the geographic viability of new depot openings and one-way rental corridor profitability.
Market Dynamics
Queensland's coastal tourism corridors concentrate rental demand while TGA safety mandates compress fleet replacement cycles, forcing operators to accelerate capital deployment toward compliant vehicle configurations.
Growth Catalysts
- Domestic leisure travel normalization:Australians are prioritizing intrastate road-based holidays over international aviation, concentrating booking volume in self-drive accommodation formats.
- TGA structural integrity standards:Updated roadworthiness certification requirements are retiring older rental stock and stimulating demand for newer, safer vehicle categories.
- Airport hub distribution density:Major gateway cities including Brisbane, Sydney, and Melbourne now host consolidated pickup infrastructure that reduces friction for fly-drive itineraries.
Market Restraints
- Qualified technician scarcity:Maintenance labor shortages across Queensland and New South Wales limit fleet utilization rates and extend vehicle downtime.
- Coastal overnight parking restrictions:Queensland and Western Australia environmental regulations prohibit free camping in sensitive zones, forcing demand toward paid holiday park infrastructure.
- Petroleum price volatility:Fuel cost swings directly impact operating margins for heavy motorhome configurations with sub-15 L/100km consumption profiles.
Strategic Opportunities
- Tasmanian route expansion:The island state's wilderness tourism positioning remains underserved by national operators, creating whitespace for dedicated depot networks.
- Campervan electrification:Battery-electric drivetrains paired with solar auxiliary systems are opening zero-emission corridor development along the Great Ocean Road.
- State tourism board infrastructure grants:Queensland and Victoria funding commitments for RV-friendly dump stations and power hookups reduce operator site development costs.
Industry Challenges
- Certification timeline compression:TGA's accelerated compliance deadlines strain engineering resources for fleet-wide structural modifications.
- One-way rental logistics:Asymmetric demand flows between Queensland pickup and southern state returns create costly vehicle repositioning requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Recreational Vehicle Rental Market |
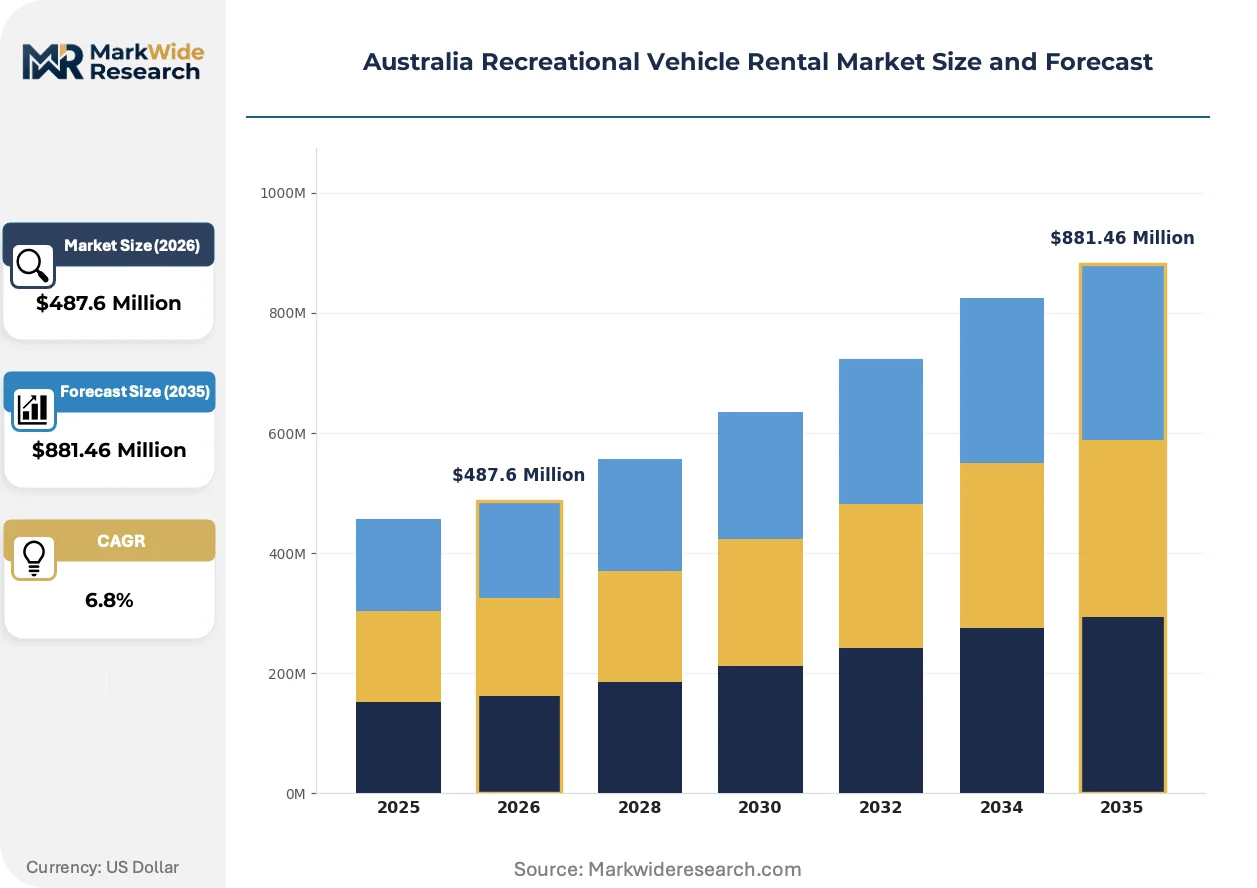
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Campervan, Motorhome, Travel Trailer, Caravan Rental Duration: Short-term, Long-term, One-way, Weekend Customer Segment: Families, Couples, Solo Travelers, Adventure Seekers Booking Channel: Online Platforms, Travel Agents, Direct Rentals, Affiliates |
| Companies Covered | Mighty Motorhomes, Travellers Autobarn, Maui Motorhomes, Cheapa Campa, Let's Go Motorhomes, Apollo Motorhomes, Jucy Campervan, Star RV, Britz Campervans, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Recreational Vehicle Rental Market Strategic Shifts
Telematics-enabled fleet management is supplanting manual dispatch systems across Australian RV rental operations, compressing turnaround times and enabling dynamic pricing architectures.
Integrated solar-battery auxiliary power systems are supplanting onboard generator dependency in mid-tier motorhome configurations. Solo travelers and couples operating two-berth campervans are adopting these silent-charging setups fastest. The shift is compressing generator maintenance revenue streams while opening subscription-based energy monitoring services.
TGA's updated vehicle safety mandates governing structural integrity and roadworthiness certification are accelerating fleet replacement investments. Operators must retire non-compliant stock ahead of traditional depreciation schedules. Queensland-based rental firms face the steepest compliance costs due to concentration of aging high-utilization vehicles.
Direct-to-consumer online booking platforms are capturing reservation volume previously held by travel agent intermediaries. Domestic leisure travelers now expect real-time availability transparency and instant confirmation. This channel migration is most pronounced among millennial and Generation Z demographic segments planning Great Barrier Reef coastal circuits.
Australia Recreational Vehicle Rental Market Segmentation
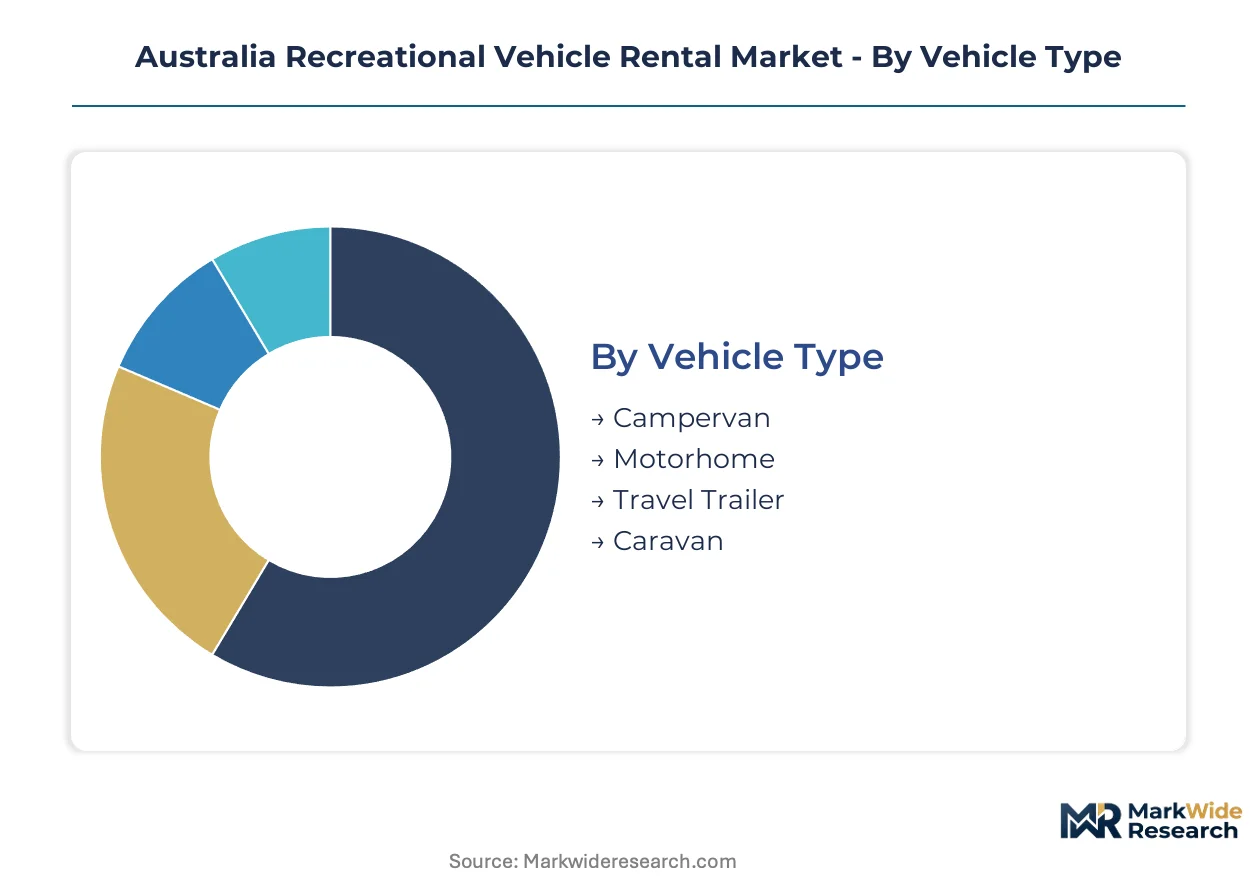
Vehicle configuration and booking pathway choices directly determine fleet utilization economics and depot network placement for Australian operators. Channel migration patterns are compressing commission structures while segment-specific demand cycles reshape seasonal staffing models.
Vehicle Type:
Online platforms now dominate reservation flow for self-propelled categories, while towable configurations retain stronger travel agent involvement due to complexity in matching vehicle-to-tow ratings.
- Motorhome:Integrated drivetrain with gross vehicle mass between 3.5 and 7.5 tonnes, featuring permanent sleeping berths and onboard sanitation. Queensland coastal corridors concentrate the heaviest booking density, with TGA structural integrity mandates accelerating fleet turnover among aging high-utilization units.
- Campervan:Compact two-berth configurations built on light commercial van chassis prioritizing fuel economy and urban maneuverability. Solo travelers and couples along the Great Ocean Road are adopting these fastest, drawn by lower per-kilometer operating costs and simplified parking logistics.
- Travel Trailer:Towable living accommodations requiring compatible tow vehicles, typically featuring expandable sections and outdoor kitchen setups. Domestic families with existing SUV fleets represent the core demand pool.
- Caravan:Traditional towable configurations with rigid wall construction and fixed interior layouts. Regional holiday park infrastructure determines viable rental corridors for this segment.
Motorhome dominates installed base. Campervan is where expansion concentrates.
Rental Duration:
Margin structure varies sharply by duration tier, with short-term bookings carrying higher per-day rates but disproportionate cleaning and turnaround overhead.
- Short-term:Rental periods spanning 3 to 7 days, typically aligned with school holiday windows and peak domestic tourism periods. Airport hub pickups in Brisbane and Sydney generate the densest booking volume.
- Long-term:Extended rentals exceeding 14 days, common among retirees executing circumnavigation itineraries. These bookings stabilize fleet utilization during shoulder seasons.
- One-way:Asymmetric corridor rentals between non-matching pickup and return depots. Queensland-to-southern-state flows create costly vehicle repositioning requirements.
- Weekend:Brief 2 to 3-day rentals concentrated within 200-kilometer radius of major metropolitan centers. Spontaneous booking patterns dominate this tier.
Short-term dominates installed base. Long-term is where margin protection concentrates.
Customer Segment:
Demographic targeting shapes fleet composition, with family-oriented operators maintaining larger berth configurations and adventure-focused competitors emphasizing off-road capability.
- Families:Multi-berth configurations with child safety anchor points and expanded storage for recreational equipment. School holiday periods drive peak demand concentration.
- Couples:Two-berth motorhomes and campervans prioritized for privacy and compact footprint. This segment shows highest adoption of solar-battery auxiliary systems.
- Solo Travelers:Single-occupant rentals concentrated in campervan categories, with strong preference for online platform booking and flexible cancellation terms.
- Adventure Seekers:Off-road capable configurations with increased ground clearance and ruggedized suspension. Western Australia's remote tourism zones attract disproportionate share.
Families dominate installed base. Adventure Seekers is where fleet differentiation concentrates.
Booking Channel:
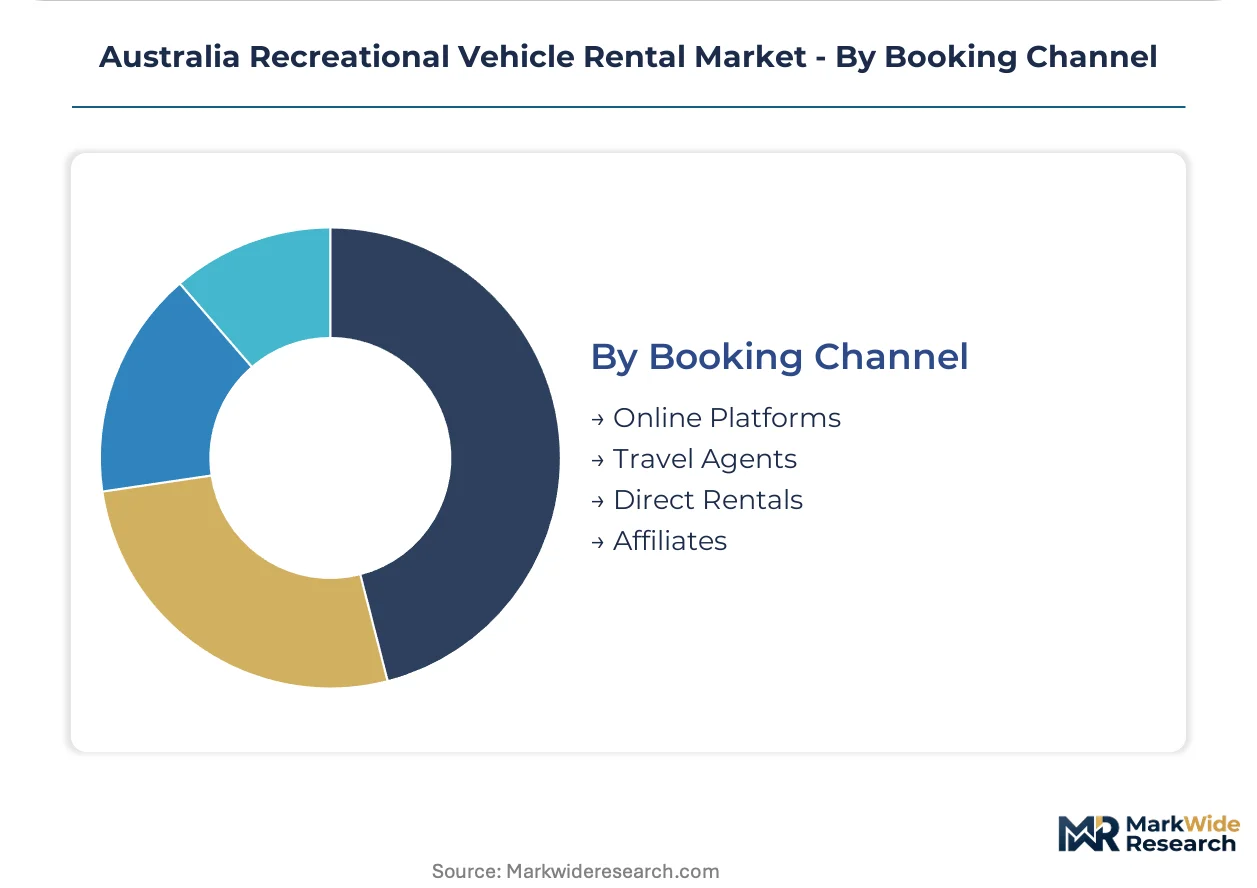
Commission economics and customer acquisition cost structures diverge substantially across reservation pathways, with direct channels capturing margin previously allocated to intermediaries.
- Online Platforms:Direct-to-consumer interfaces enabling real-time availability transparency and dynamic pricing adjustments. Millennial and Generation Z demographics planning Great Barrier Reef circuits show strongest platform affinity.
- Travel Agents:Intermediary bookings retaining relevance for complex multi-leg itineraries and international visitor segments. Commission structures compress operator margins by 12 to 18 percent.
- Direct Rentals:Phone or walk-in reservations at depot locations, common among repeat customers and last-minute bookings. Loyalty program enrollment concentrates here.
- Affiliates:Third-party referral arrangements with tourism boards, accommodation providers, and complementary travel services. Queensland state tourism funding amplifies affiliate channel reach.
Online Platforms dominate installed base. Direct Rentals is where margin recovery concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Queensland's coastal tourism corridors concentrate Australia's heaviest RV rental demand, while southern states favor compact campervans for fuel efficiency on extended touring routes. Western Australia's remote wilderness zones attract specialized off-road configurations unavailable in eastern markets.
New South Wales
Sydney's airport hub infrastructure generates densest short-term rental pickup volume during school holiday windows. TGA roadworthiness certification requirements compress fleet replacement cycles for aging high-utilization vehicles. The Pacific Highway corridor between Sydney and Brisbane anchors one-way rental flows with costly vehicle repositioning logistics.
Victoria
Melbourne's consolidated depot network serves fly-drive itineraries targeting the Great Ocean Road's scenic coastal circuit. State tourism board infrastructure grants for RV-friendly dump stations and power hookups reduce operator site development costs. The Mornington Peninsula and Phillip Island clusters concentrate weekend rental demand within 200-kilometer radius of the metropolitan center.
Queensland
Cairns and Brisbane airport hubs dominate premium motorhome pickup density for Great Barrier Reef coastal circuits. Environmental regulations increasingly restrict overnight parking in sensitive coastal zones, redirecting demand toward designated holiday park infrastructure. The Gold Coast-to-Whitsundays corridor sustains highest fleet utilization rates among national operators.
Western Australia
Perth-based depots serve adventure-seeking segments targeting remote wilderness tourism in the Kimberley and Pilbara regions. Petroleum price volatility directly impacts operating margins for heavy motorhome configurations traversing vast distances between service points. The state maintains lighter regulatory burden on coastal overnight parking compared to eastern jurisdictions.
South Australia
Adelaide's depot network captures circumnavigation itineraries and long-term retiree bookings stabilizing shoulder-season utilization. The Barossa Valley and Flinders Ranges wine tourism circuits generate concentrated demand for compact two-berth configurations. Operators face lower technician labor scarcity compared to Queensland and New South Wales markets.
Australia Recreational Vehicle Rental Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with maintenance network scale and airport hub distribution density determining utilization economics. The market structure rewards backward integration into captive maintenance capabilities and penalizes operators dependent on third-party technician labor. Three archetypes dominate: national integrated networks with owned service infrastructure, regional specialists concentrating on specific state corridors, and budget-focused volume players competing on entry-level pricing. Competitive moves center on fleet electrification partnerships and Tasmanian route expansion to capture underserved wilderness tourism positioning.
Among the integrated national tier, Apollo Motorhomes and Britz Campervans exemplify divergent strategic positioning—one leveraging captive maintenance networks for utilization advantage, the other dominating premium-tier airport hub distribution. Cheapa Campa anchors the budget-volume archetype with aggressive entry-level caravan pricing. Maui Motorhomes and Mighty Motorhomes occupy positions within the mid-market spectrum, while Jucy Campervan represents the compact urban-specialist format. Star RV and Let's Go Motorhomes sit within the long-term rental and retiree-focused segment, with Travellers Autobarn capturing the international visitor and backpacker demographic through flexible one-way corridor offerings.
| Leading Market Players |
|---|
| Mighty Motorhomes |
| Travellers Autobarn |
| Maui Motorhomes |
| Cheapa Campa |
| Let's Go Motorhomes |
| Apollo Motorhomes |
| Jucy Campervan |
| Star RV |
| Britz Campervans |
| Others |
Value Chain & Pricing Dynamics
Long-term fleet procurement contracts with chassis manufacturers lock in vehicle acquisition pricing and delivery schedules for Australian operators, insulating against spot-market volatility while committing capital eighteen to twenty-four months ahead of TGA compliance deadlines. This structure concentrates pricing power among integrated national networks with sufficient balance sheet depth to pre-order compliant configurations.
Pricing Analysis
Project-based seasonal pricing dominates the Australian RV rental market, with operators adjusting per-day rates dynamically around Queensland school holiday windows and Great Barrier Reef peak visitation periods. Price differentiation separates premium motorhome tiers with integrated drivetrain convenience from economy campervan configurations competing on fuel efficiency. Pricing pressure stems from petroleum cost volatility directly impacting heavy motorhome operating margins. Domestic leisure travelers show highest price sensitivity in entry-level caravan segments, while international visitors demonstrate lower elasticity for premium airport hub pickups.
Supply Chain Analysis
Inventory lead times for TGA-compliant chassis and habitation modules now stretch well beyond traditional procurement cycles, forcing operators to accelerate order commitments. Manufacturing concentrates in Australia for final assembly, with critical drivetrain components sourced from Japan and Germany. Raw material dependencies include aluminum framing, lithium auxiliary batteries, and specialized RV-grade insulation. Single-source vulnerability sits with qualified technician labor for maintenance networks. Distribution runs through airport hub depots in Brisbane, Sydney, and Melbourne, supplemented by regional coastal corridor locations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Maintenance technician scarcity across Queensland and New South Wales now constrains fleet utilization economics more severely than vehicle availability, creating a structural bottleneck that favors operators with captive service infrastructure over third-party dependent competitors.
For Market Incumbents: Consolidate technician training pipelines through apprenticeship partnerships with Queensland technical institutes, securing labor supply ahead of TGA's accelerated compliance deadlines. Expand captive maintenance network density along the Gold Coast-to-Whitsundays corridor to sustain utilization premiums over regional peers. Backward integration into vehicle refurbishment capabilities reduces third-party service dependency. For New Entrants and Emerging Players: Anchor in Tasmania's underserved wilderness tourism positioning, where national operator depot networks remain sparse and one-way rental logistics create whitespace for dedicated regional specialists. Target compact campervan electrification along the Great Ocean Road, leveraging Victoria's state tourism board infrastructure grants for zero-emission corridor development. Pursue direct-to-consumer platform launches to bypass incumbent travel agent commission structures. For Investors and Strategic Acquirers: Regional specialists with established depot networks in South Australia and Tasmania represent compelling acquisition targets, offering geographic diversification away from Queensland's technician-constrained competitive intensity. Long-term viability hinges on electrification readiness and TGA compliance engineering capabilities. Monitor state tourism board funding allocations for RV-friendly infrastructure as the primary demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Technician Apprenticeship Pipeline | Addresses qualified labor scarcity constraining fleet utilization across Queensland and New South Wales. |
| Tasmanian Depot Network Expansion | Captures underserved wilderness tourism demand with limited incumbent presence. |
| Campervan Electrification Partnership | Opens zero-emission corridor development along Victoria's Great Ocean Road. |
| Direct-to-Consumer Platform Launch | Eliminates 12-18% travel agent commission compression on domestic leisure bookings. |
| Captive Maintenance Network Buildout | Sustains vehicle utilization premiums through controlled service scheduling. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with fleet operations directors, depot network managers, maintenance technicians, and state tourism board infrastructure planners. Secondary validation drew from TGA vehicle safety mandate documentation, Queensland and Victoria state tourism funding disclosures, Australian Bureau of Statistics domestic travel expenditure data, and industry association fleet registration records. Bottom-up vehicle deployment modeling triangulated against top-down tourism corridor demand estimates.
The projection horizon spans from base-year market sizing through the full forecast window. Segmentation dimensions modeled include vehicle configuration, rental duration tier, customer demographic, and booking channel pathway. CAGRs were derived from trend-line analysis of fleet replacement cycles, TGA compliance timeline compression, and infrastructure grant allocation trajectories. Industry-specific inputs incorporated petroleum price elasticity assumptions for heavy motorhome configurations and solar-battery auxiliary system adoption curves.
Material uncertainties — regulatory deadline shifts, state tourism funding reallocations, and technician labor market tightening — sit outside the modeled envelope. Forecasts reflect assumptions around TGA enforcement consistency and domestic leisure travel preference persistence. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recreational Vehicles
Europe Luxury Yacht Market
Recreational Vehicles
Low-Speed Electric Vehicle Market
Recreational Vehicles
Recreational Boats Market
Recreational Vehicles
Luxury Van Market
Recreational Vehicles
Europe Motor Home Market
Recreational Vehicles
Global Segway Consumption Market
Recreational Vehicles
Teardrop Trailer Market
Recreational Vehicles
Asia-Pacific Motor Home Market
Recreational Vehicles
Europe Personal Watercraft Market
Recreational Vehicles
RV Solar Panels Market
Recreational Vehicles
Electric Baby Car Market
Recreational Vehicles
Jon Boat Market
Recreational Vehicles
Motorhome Market
Recreational Vehicles
Golf Cart Market
Recreational Vehicles
Malaysia Trailer Market
Recreational Vehicles
North America Motorhome Market