
 Automotive Thermal Systems Market | 2026-2036
Automotive Thermal Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Thermal Systems Market Analysis
The EU Green Deal is pivoting automotive thermal system priorities toward low-GWP refrigerants and heat pump architectures. Denso Corporation leverages its in-house compressor and heat exchanger production to control component costs across Asian and European supply chains. MAHLE GmbH anchors its competitive position through specialized e-thermal modules for battery and power electronics cooling. Valeo SA differentiates via integrated heat pump systems that consolidate cabin comfort and battery thermal regulation into single architectures.
Automotive thermal systems encompass the engineered assemblies, heat exchangers, refrigerant loops, and control modules that manage temperature across powertrains, passenger compartments, and electronic subsystems, typically operating within coolant temperature ranges of 80°C to 120°C for combustion applications and broader gradients for electrified platforms. These systems prevent thermal derating of lithium-ion cells, maintain inverter efficiency, and ensure occupant comfort under varying ambient and load conditions. Heat exchangers and electric cooling technologies command concentrated margin pools as electrification raises performance requirements and refrigerant transitions drive replacement cycles. Phase change materials remain nascent but represent a fast-growing technology segment for transient thermal buffering in battery packs where fluid-based solutions face packaging constraints.
The EPA, ECHA through REACH and the F-Gas Regulation, and China's MEE enforce progressively stricter limits on refrigerant global warming potential and thermal system energy consumption, directly shaping product development roadmaps and factory certification requirements for component suppliers. NHTSA fuel economy standards and the EU AI Act's emerging requirements for thermal management in autonomous computing platforms add compliance layers that favor suppliers with multi-jurisdiction testing capabilities. Stakeholders must monitor refrigerant phase-down schedules and battery energy density trajectories to align thermal architecture investments with next-generation platform requirements.
Market Dynamics
Electric vehicle platform proliferation is forcing thermal architecture redesigns across powertrain, battery, and cabin systems simultaneously, compressing development cycles and raising component integration requirements beyond legacy combustion-era capabilities.
Growth Catalysts
- EU F-Gas Regulation phase-down:Mandates for low-GWP refrigerants accelerate heat pump adoption across European OEM platforms, creating replacement demand for compressor and heat exchanger assemblies.
- Battery energy density trajectories:Cell manufacturers push thermal runaway containment requirements, expanding procurement of liquid cooling plates and phase change material buffering systems.
- China NEV subsidies:Domestic electric vehicle production quotas concentrate demand for integrated thermal management modules in Jiangsu and Guangdong manufacturing clusters.
Market Restraints
- Copper and aluminum price volatility:Heat exchanger manufacturers face margin compression when commodity cycles spike, with limited pass-through power against consolidated OEM procurement.
- Refrigerant supply concentration:HFO-1234yf production concentrates among three chemical suppliers, exposing thermal system assemblers to allocation risk during patent-protected supply crunches.
- Packaging density limits:Front-end module space constraints prevent oversized heat exchanger deployment in compact electric crossovers, capping thermal dissipation capacity.
Strategic Opportunities
- India PLI scheme for auto components:Localized thermal module production incentives attract tier-one suppliers to Tamil Nadu and Maharashtra manufacturing corridors.
- Autonomous computing thermal loads:LiDAR and AI processor cooling emerges as a discrete application segment with specialized cold plate and immersion cooling requirements.
- Vehicle-to-grid integration:Bidirectional charging architectures require battery thermal conditioning during stationary discharge cycles, extending system duty profiles.
Industry Challenges
- Systems engineering talent scarcity:Cross-domain expertise spanning refrigerant thermodynamics, battery electrochemistry, and controls software commands premium compensation and extends hiring timelines.
- Multi-jurisdiction certification parallelism:Simultaneous EPA SNAP approval, EU F-Gas compliance, and China GB standard testing stretches validation resources across divergent protocol requirements.
- Legacy HVAC integration complexity:Heat pump retrofits into existing vehicle architectures encounter control software conflicts and physical packaging incompatibilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Thermal Systems Market |
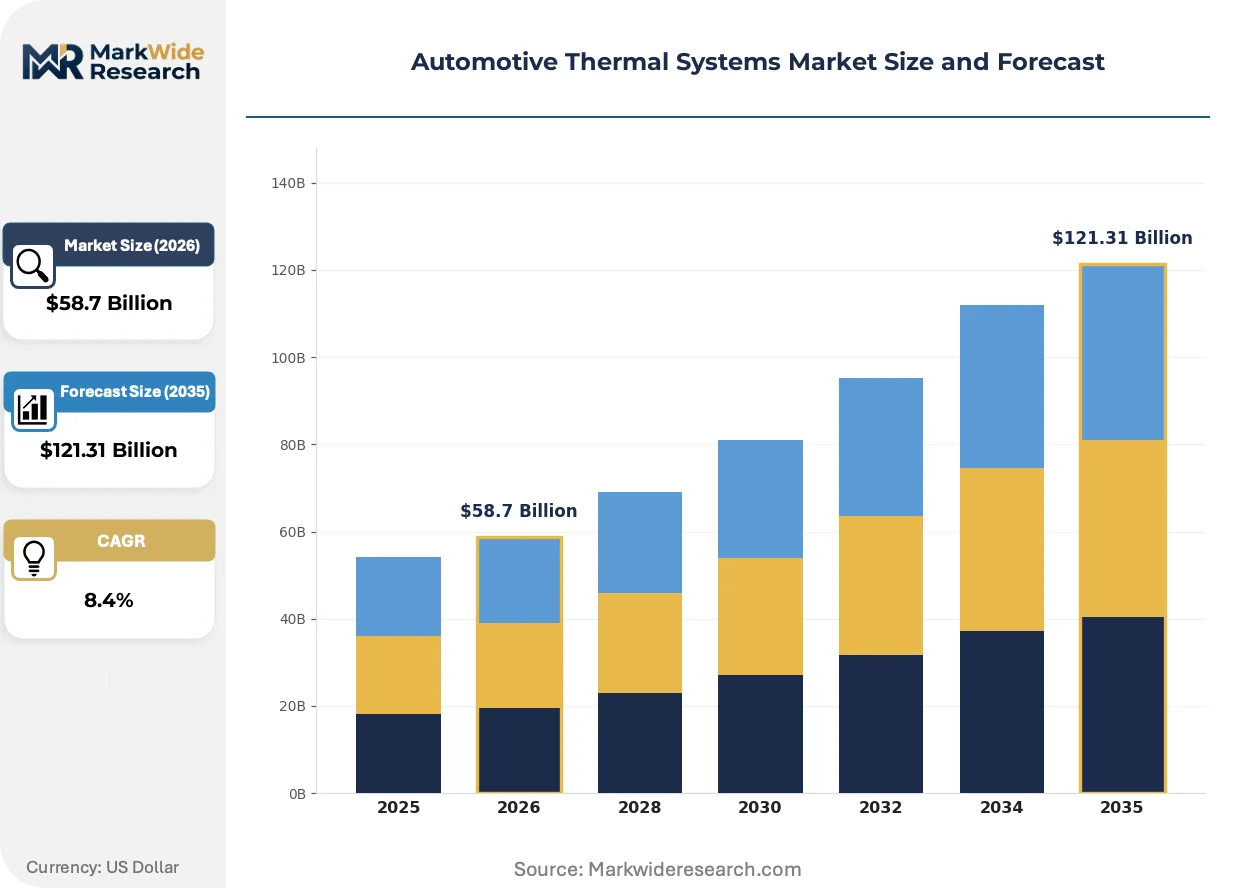
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $121.31 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radiators, Condensers, Heater Cores, Heat Exchangers Technology: Electric Cooling, Hybrid Systems, Phase Change Materials, Fluid-Based End User: OEM Manufacturers, Aftermarket Providers, Suppliers, Distributors Application: Passenger Vehicles, Commercial Vehicles, Electric Vehicles, Hybrid Vehicles |
| Companies Covered | Denso Corporation, Hanon Systems, MAHLE GmbH, BorgWarner Inc., Valeo SA, Robert Bosch GmbH, Continental AG, Gentherm Incorporated, Dana Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Thermal Systems Market Emerging Trajectories
Refrigerant chemistry transitions and electrified thermal architectures are compressing technology replacement cycles, forcing suppliers to synchronize R&D roadmaps with OEM platform timelines that now refresh every four years rather than seven.
CO2 transcritical heat pump systems are electrifying thermal management strategies for cold-climate electric vehicles. Scandinavian and northern Chinese OEMs deploy these systems to maintain cabin heating without range penalty. The technology is electrifying competitive positioning among suppliers capable of delivering 150-bar compressor and gas cooler assemblies.
EPA SNAP program approvals for next-generation refrigerant blends are tightening compliance timelines for thermal system suppliers. Alternative chemistry submissions require expanded toxicity and flammability testing protocols. North American passenger vehicle platforms face the most compressed certification schedules as 2027 model year preparation accelerates.
Fleet operators and leasing companies now specify thermal system durability metrics in procurement contracts, displacing component-cost-only evaluation. Long-term total cost of ownership calculations weight predictive maintenance and warranty claim probability. This behavioral shift is most pronounced in European commercial vehicle segments where electrification mandates concentrate buying power among large logistics aggregators.
Automotive Thermal Systems Market Segmentation
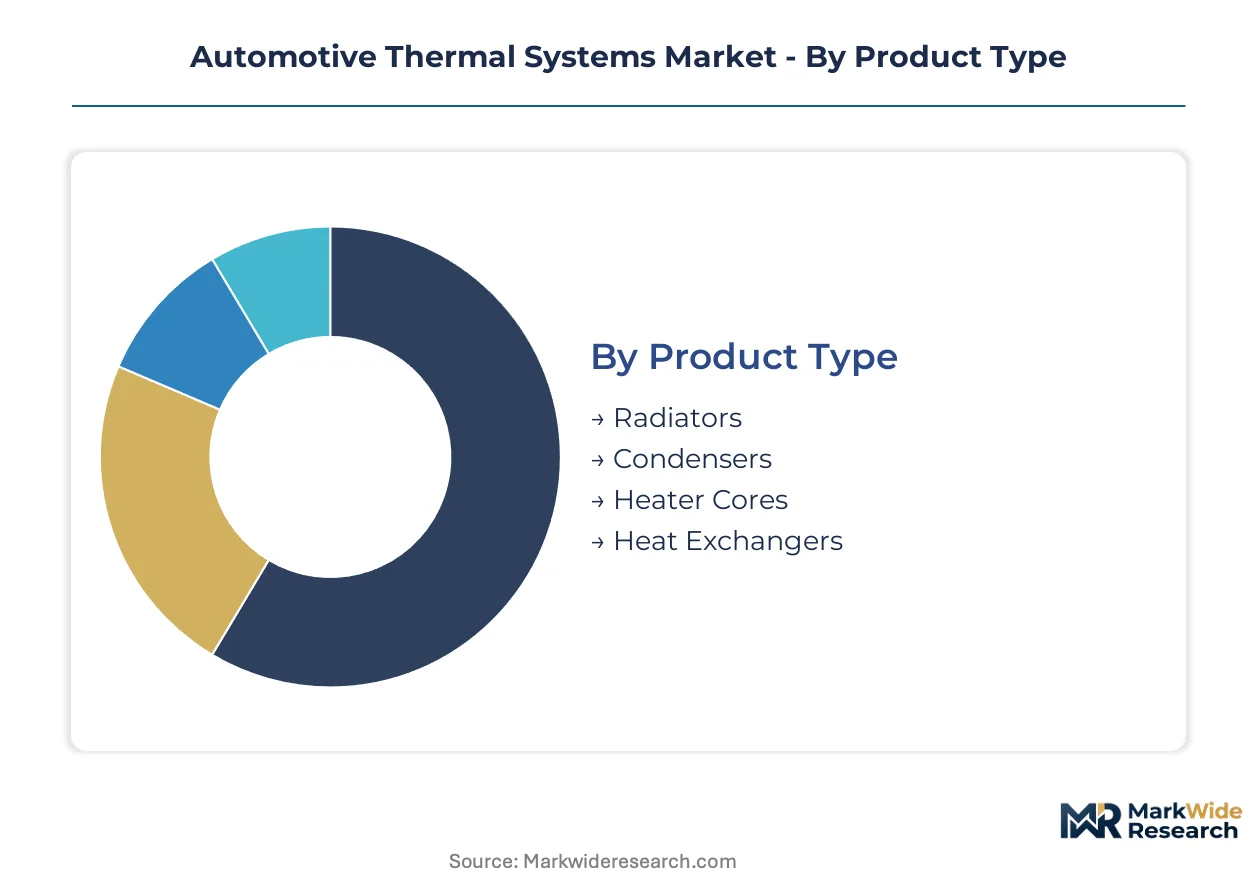
Thermal system architectures diverge sharply across powertrain electrification levels, forcing suppliers to maintain parallel production lines for combustion-era components and emerging battery-cooling technologies. Segment boundaries blur as heat pump modules consolidate functions once handled by discrete radiators, condensers, and heater cores.
Product Type:
Volume production concentrates in stamped-aluminum heat exchangers, while premium margins migrate toward integrated thermal modules serving electric platforms.
- Radiators:Cross-flow and down-flow aluminum-core assemblies dominate thermal dissipation for internal combustion powertrains, with demand concentrating in legacy truck and SUV platforms across Michigan and Stuttgart manufacturing corridors. EPA CAFE standards and EU fleet CO2 rules are compressing procurement volumes as electrification accelerates.
- Heat Exchangers:Brazed aluminum plate-and-fin architectures serve battery cooling loops, power electronics, and cabin heat pumps simultaneously, with Jiangsu and Bavaria production clusters absorbing capacity expansion for NEV platforms. Cell thermal runaway containment requirements are expanding specification complexity beyond combustion-era benchmarks.
- Condensers:Microchannel aluminum designs integrate with R-1234yf and CO2 refrigerant loops across passenger and commercial vehicle HVAC systems.
- Heater Cores:Compact aluminum tube-and-fin assemblies face displacement by heat pump gas coolers in battery electric architectures.
Today's leader: Heat Exchangers. Tomorrow's challenger: Integrated modules absorbing discrete component functions.
Technology:
Application context determines technology selection, with electric platforms demanding active thermal management unavailable from passive fluid loops.
- Electric Cooling:High-voltage compressor drives, electric water pumps, and smart valve actuators enable precise thermal control across battery, motor, and cabin zones. Scandinavian OEMs and northern Chinese manufacturers specify these systems for cold-climate range preservation, with 150-bar CO2 compressor technology gaining specification share.
- Phase Change Materials:Paraffin and salt-hydrate formulations buffer transient thermal loads in battery packs where liquid cooling plates face packaging constraints. Cell manufacturers in South Korea and Japan are qualifying these materials for pouch and prismatic cell configurations.
- Hybrid Systems:Combustion-electric thermal architectures bridge powertrain transitions in plug-in hybrid platforms.
- Fluid-Based:Ethylene glycol and dielectric coolant loops retain dominance in cost-optimized combustion applications.
Electric Cooling commands current procurement volumes. Phase Change Materials offer the steepest expansion trajectory as energy density pressures intensify.
End User:
Procurement authority concentrates among consolidated OEM engineering centers, though aftermarket channels retain significance for refrigerant transition replacement cycles.
- OEM Manufacturers:Volkswagen Group, Toyota, BYD, and Tesla thermal engineering centers specify module-level architectures rather than discrete components, compressing tier-one supplier margins while demanding systems integration capabilities. Platform refresh cycles compressed to four years strain R&D amortization.
- Suppliers:Denso, MAHLE, and Valeo maintain captive module assembly for compressor, heat exchanger, and control integration, with vertical integration into refrigerant loop components protecting margin pools.
- Aftermarket Providers:Independent distributors and service chains handle R-134a to R-1234yf conversion demand and collision repair thermal system replacement.
- Distributors:Regional warehousing networks serve fragmented commercial vehicle and agricultural equipment thermal component demand.
OEM Manufacturers dictate specification roadmaps. Suppliers capture value through integration depth.
Application:
Powertrain electrification level determines thermal architecture complexity, with pure electric platforms requiring three to four discrete cooling circuits versus one or two for combustion equivalents.
- Electric Vehicles:Battery thermal management, power electronics cooling, and cabin heat pump integration demand synchronized control across coolant, refrigerant, and phase change material loops. Tesla's Texas and Berlin gigafactories, BYD's Shenzhen and Changzhou plants, and Volkswagen's Zwickau facility concentrate procurement for integrated thermal modules.
- Hybrid Vehicles:Dual powertrain thermal loads require parallel combustion cooling and battery conditioning circuits, with Toyota and Honda platforms in Kentucky and Indiana representing concentrated demand.
- Passenger Vehicles:Sedan, crossover, and SUV segments span combustion, hybrid, and electric architectures with varying thermal intensity.
- Commercial Vehicles:Heavy-duty trucking and bus applications prioritize durability and service interval extension over thermal precision.
Electric Vehicles absorb engineering talent and capital investment. Hybrid Vehicles bridge volume during powertrain transition.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive thermal systems trace their industrial lineage to Stuttgart and Detroit, where combustion-era cooling architectures first achieved mass production scale before electrification demands rewired global supply chains toward battery-centric thermal management.
China
Jiangsu and Guangdong manufacturing clusters absorb the bulk of NEV thermal module procurement as BYD and Tesla's Shanghai gigafactory compress platform refresh cycles. MEE enforcement of dual carbon goals tightens energy efficiency mandates for heat pump assemblies. Shenzhen and Changzhou plants concentrate demand for integrated battery cooling circuits where liquid cold plates face packaging density pressures.
Germany
Volkswagen's Zwickau facility and BMW's Leipzig plant anchor European demand for CO2 transcritical heat pump systems in cold-climate electric architectures. EU F-Gas Regulation phase-down schedules accelerate low-GWP refrigerant transitions across Bavarian supply chains. Stuttgart engineering centers specify module-level architectures that compress tier-one supplier margins while demanding systems integration capabilities.
United States
EPA SNAP program approvals for next-generation refrigerant blends compress certification timelines for thermal system suppliers serving Michigan and Kentucky manufacturing corridors. NHTSA fuel economy standards shape heat exchanger specifications for legacy truck platforms. Tesla's Texas gigafactory concentrates procurement for battery thermal management where three to four discrete cooling circuits replace combustion-era simplicity.
Japan
Toyota's thermal engineering centers in Aichi Prefecture and Honda's operations in Tochigi drive hybrid vehicle thermal architecture demand spanning parallel combustion cooling and battery conditioning circuits. METI carbon neutrality roadmaps redirect R&D investment toward heat pump integration. Nagoya-area suppliers maintain captive module assembly for compressor and heat exchanger integration.
South Korea
Hyundai Motor Group's Ulsan complex and Kia's Sohari plant concentrate procurement for electric vehicle thermal modules serving domestic and export markets. MFDS-aligned safety standards for battery thermal runaway containment expand specification complexity for liquid cooling plates. Seoul Capital Area cell manufacturers qualify phase change materials for pouch and prismatic configurations.
Automotive Thermal Systems Market Vendor Landscape
Premium-margin players sit above commodity-margin players across integration depth, with captive refrigerant loop component production protecting value pools while standalone heat exchanger fabricators face OEM procurement consolidation. The supplier base organizes into three tiers: diversified automotive conglomerates with thermal divisions, specialized thermal system houses, and component-focused metalformers. Strategic moves concentrate on backward integration into compressor manufacturing and geographic expansion toward NEV production clusters.
Within the diversified conglomerate tier, Denso Corporation and Robert Bosch GmbH exemplify players with in-house production spanning compressors, heat exchangers, and control modules. MAHLE GmbH occupies a position among specialized thermal system houses focused on e-thermal modules. Valeo SA represents European suppliers differentiating through integrated heat pump architectures. These three anchors illustrate how competitive positioning depends on integration depth rather than scale alone.
| Leading Market Players |
|---|
| Denso Corporation |
| Hanon Systems |
| MAHLE GmbH |
| BorgWarner Inc. |
| Valeo SA |
| Robert Bosch GmbH |
| Continental AG |
| Gentherm Incorporated |
| Dana Incorporated |
| Others |
Supply Flow & Price Mechanics
Systems engineering talent scarcity in Stuttgart and Bavaria compresses labor-cost differentials between premium integrated module suppliers and commodity heat exchanger fabricators, widening pricing-tier spreads across European NEV procurement clusters.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates Denso and MAHLE's integrated thermal modules from standalone heat exchanger suppliers. Price differentiation hinges on refrigerant loop integration depth and EU F-Gas certification tier. Pricing pressure stems from OEM procurement consolidation toward module-level architectures. Aftermarket distributors exhibit highest price sensitivity; OEM engineering centers prioritize performance metrics over unit cost.
Supply Chain Analysis
Freight cost volatility from Shanghai to Detroit and Rotterdam strains just-in-time thermal module delivery schedules. Supply concentrates in China, Germany, and Japan for compressor and heat exchanger production. Raw material dependencies center on aluminum sheet, copper tubing, and HFO-1234yf refrigerant feedstock. Single-source vulnerability from three-chemical-supplier refrigerant concentration exposes assemblers to allocation risk. Distribution runs through tier-one captive module assembly to OEM platform engineering centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive thermal systems function as a stable compounder anchored by irreversible powertrain electrification, with battery thermal management creating recurring platform-level demand across four-year OEM refresh cycles.
For Market Incumbents: Extend backward integration into compressor manufacturing to protect margin pools against OEM procurement consolidation. Deepen capacity presence in Jiangsu and Guangdong manufacturing corridors to align with BYD and Tesla production concentration. Counter refrigerant supply concentration risk through long-term offtake agreements with HFO-1234yf chemical suppliers. For New Entrants and Emerging Players: Launch via specialized cold plate and immersion cooling systems for autonomous computing thermal loads, where LiDAR and AI processor cooling demands outpace incumbent R&D bandwidth. Target India PLI scheme corridors in Tamil Nadu and Maharashtra for localized thermal module production. Pursue vehicle-to-grid integration applications as a white-space segment with extended duty profiles. For Investors and Strategic Acquirers: Tier 1 automotive suppliers with captive thermal divisions are the most active acquirers in this space, seeking phase change material specialists and CO2 compressor technology. Long-term viability centers on integration depth rather than scale alone over the next decade. Acquisition target archetype: mid-cap e-thermal module houses with OEM platform engineering relationships. Monitor battery energy density trajectories as the inflection signal for phase change material adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Reduces thermal architecture complexity across Volkswagen Group and Tesla multi-vehicle lineups. |
| Battery Supply Agreement | Secures lithium-ion cell allocation for integrated cooling plate specification alignment. |
| Software-Defined Vehicle Investment | Enables predictive thermal control algorithms across battery, cabin, and power electronics zones. |
| Geographic Manufacturing Footprint | Positions capacity within Jiangsu, Guangdong, and Zwickau NEV production clusters. |
| Charging Infrastructure Partnership | Extends thermal system duty profiles into vehicle-to-grid bidirectional discharge cycles. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with OEM platform engineers, tier-one supplier procurement leads, aftermarket distributors, and thermal systems R&D directors with secondary validation from EPA SNAP filings, EU F-Gas Regulation databases, vehicle production registries, and IHS Markit registration data. Bottom-up segment sizing and top-down macroeconomic triangulation anchored volume and value estimates.
Segment-weighting approaches distributed value across product type, technology, end user, and application dimensions, with propulsion architecture and content per vehicle serving as automotive-specific modeling variables. CAGRs were derived from fitted growth curves applied to segment-level baselines, incorporating battery energy density trajectories and refrigerant phase-down schedules as industry-specific forecast inputs across the projection horizon.
Forecast precision tightens around the base case; tail outcomes carry wider variance under commodity price spikes and refrigerant supply allocation crunches. Forecasts reflect documented assumptions regarding OEM platform refresh cadence and electrification penetration curves. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Electromagnetic Clutch System Market
Automotive Parts
Camshaft Lifters Market
Automotive Parts
Morocco Automotive Engine Oils Market
Automotive Parts
North America Automotive Actuators Market
Automotive Parts
Automotive Propeller Shaft Market
Automotive Parts
Automatic Bus Door System Market
Automotive Parts
Egypt Automotive Engine Oils Market
Automotive Parts
Automotive Trailing Arm Bushing Market
Automotive Parts
France Automotive Actuators Market
Automotive Parts
Global All Wheel Drive Market
Automotive Parts
Automotive Fuel Rail Market
Automotive Parts
Norway Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Windshield Washer System Market
Automotive Parts
AWD Coupling System Market
Automotive Parts
Lug Wrench Market
Automotive Parts
Germany Automotive Parts Aluminium Die Casting Market