
 Automotive Trailing Arm Bushing Market | 2026-2036
Automotive Trailing Arm Bushing Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Trailing Arm Bushing Market Outlook
Aftermarket distribution channels for chassis components is reshaping how trailing arm bushings reach repair shops and fleet operators. ZF Friedrichshafen AG leverages its integrated suspension systems portfolio to control tier-1 supply relationships with major OEMs. Continental competes through polyurethane formulation expertise that extends bushing service intervals under severe duty cycles. Mevotech anchors the North American aftermarket with broad SKU coverage across domestic and import vehicle applications.
An automotive trailing arm bushing is an elastomeric or metallic cylindrical component installed between a vehicle's trailing arm and chassis subframe, typically molded from natural rubber, synthetic polybutadiene, or thermoplastic polyurethane with steel outer sleeves bonded via vulcanization or press-fit assembly, functioning to isolate road-induced vibrations while maintaining precise wheel alignment geometry under lateral and longitudinal loads. Rubber formulations still dominate OEM fitments for their cost-efficiency and noise-damping characteristics, though polyurethane variants are capturing margin pools in performance and commercial segments where durability premiums command higher replacement values. Composite hybrid constructions incorporating aramid fiber reinforcement represent the fastest-growing material category as manufacturers target weight reduction mandates without sacrificing load-bearing capacity.
EPA emissions standards and NHTSA Federal Motor Vehicle Safety Standards govern material composition and structural integrity requirements for chassis-mounted components in the United States, while ISO 9001 and IATF 16949 quality frameworks shape supplier qualification thresholds across OEM supply bases. The EU's REACH regulation restricts certain curative chemicals in rubber compounding, compelling reformulation investments among European-serving manufacturers. Stakeholders must monitor evolving durability test protocols and material disclosure requirements as regulators tighten lifecycle performance expectations for underbody components.
Market Dynamics
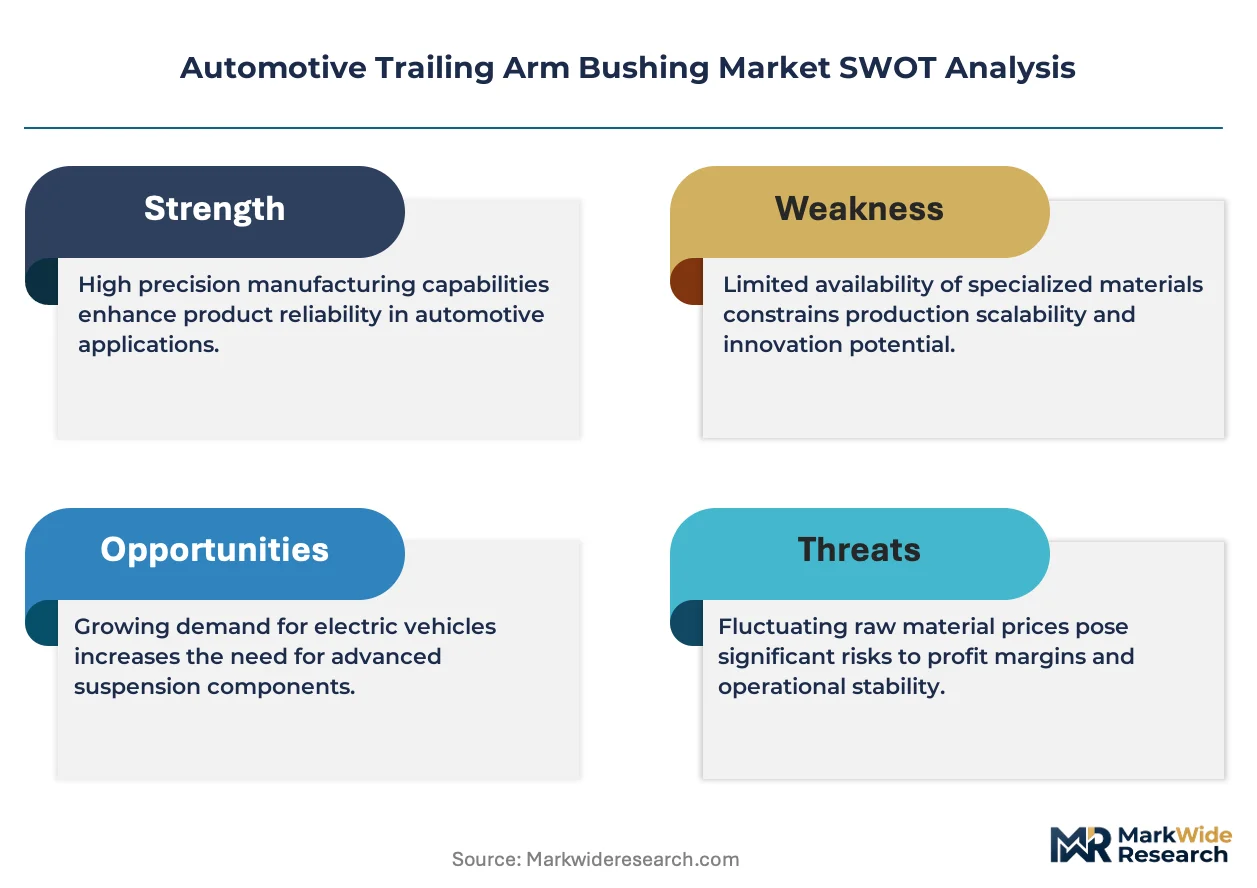
Polyurethane formulation advances are compressing replacement cycles for aging vehicle fleets while EPA durability mandates force material upgrades across OEM supply chains. Tier-1 suppliers now face dual pressure from aftermarket price competition and regulatory compliance costs.
Growth Catalysts
- NHTSA Federal Motor Vehicle Safety Standards:Tightened structural integrity requirements for chassis-mounted components are accelerating bushing replacement rates in commercial vehicle segments.
- Polyurethane material science:Extended service intervals under severe duty cycles are capturing margin pools in performance and fleet applications.
- Michigan and Ohio manufacturing corridors:Concentrated OEM and tier-1 presence creates dense supplier ecosystems for prototype-to-production acceleration.
Market Restraints
- Natural rubber price volatility:Commodity input fluctuations compress margins for rubber-dominant OEM fitments.
- REACH chemical restrictions:EU curative chemical limitations force reformulation investments without immediate volume offsets.
- Steel sleeve supply concentration:Bonded metal component sourcing concentrates in specific foundry regions, creating single-point vulnerabilities.
Strategic Opportunities
- Aramid fiber composite hybrids:Weight reduction mandates without load-bearing sacrifice open premium positioning in electric vehicle platforms.
- Independent repair channel digitization:Direct-to-shop platforms bypass traditional distributor markups for aftermarket volume capture.
- Commercial fleet telematics integration:Predictive maintenance algorithms create attached sales for preemptive bushing replacement.
Industry Challenges
- IATF 16949 certification timelines:Extended supplier qualification periods delay new entrant market access.
- Vulcanization-to-press-fit process migration:Equipment retooling demands capital allocation conflicting with short-term margin targets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Trailing Arm Bushing Market |
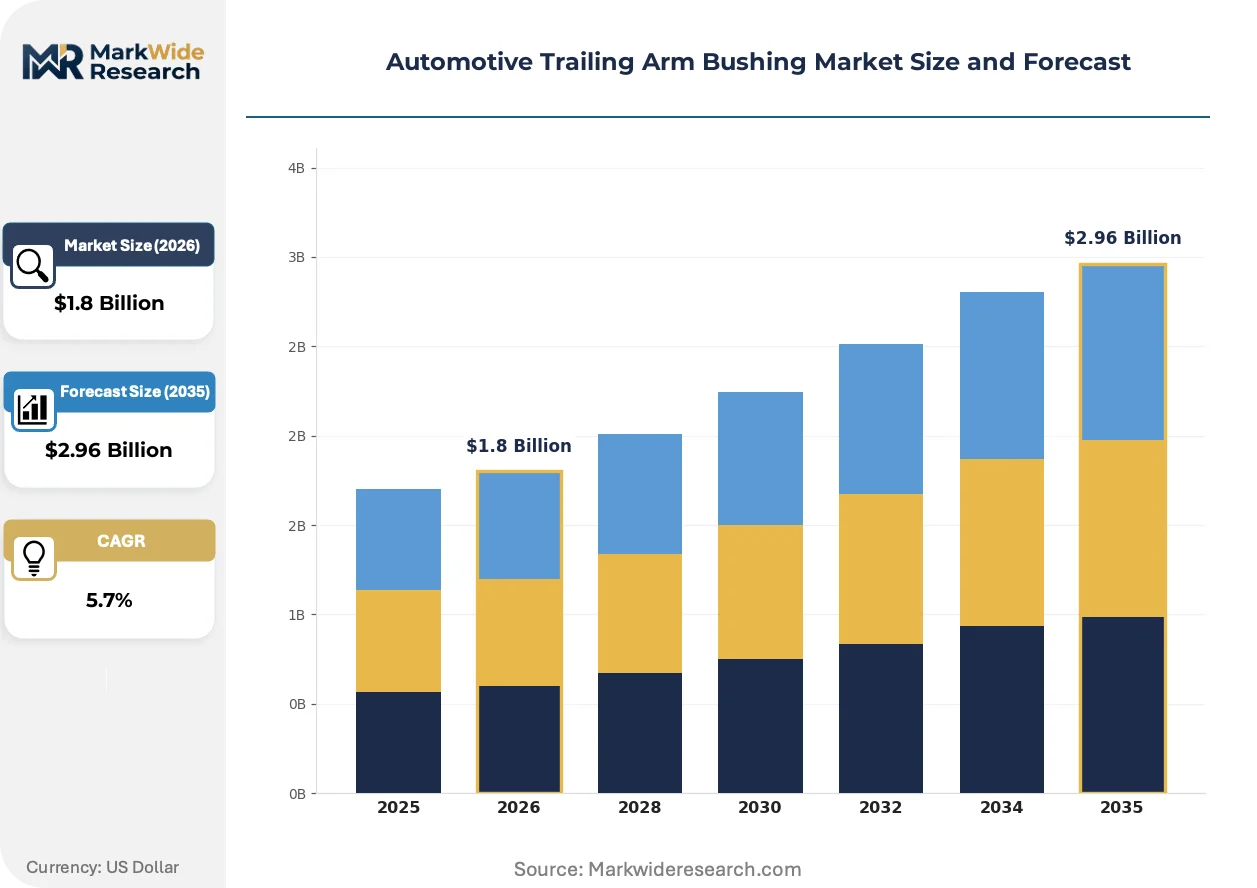
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rubber, Polyurethane, Metal, Composite Vehicle Type: SUV, Sedan, Truck, Van End User: OEMs, Aftermarket Providers, Fleet Operators, Repair Shops Application: Suspension, Steering, Chassis, Stability Control |
| Companies Covered | ZF Friedrichshafen AG, Continental, ACDelco, Mevotech, Federal Mogul LLC, Vibracoustic GmbH, Sumitomo Riko, Tenneco, Hyundai Polytech India, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Trailing Arm Bushing Market Strategic Shifts
Material substitution and predictive maintenance integration are redefining value capture across the trailing arm bushing value chain. Suppliers now compete on data-enabled service models rather than unit economics alone.
Smart bushing sensors embedded with strain gauges and accelerometers are digitizing condition monitoring for fleet operators. Heavy-duty trucking companies in the United States adopt these units fastest, replacing time-based maintenance with usage-triggered replacement protocols. Real-time load data is digitizing procurement decisions, compressing distributor influence in favor of direct manufacturer relationships.
EPA emissions standards now incorporate lifecycle durability testing for underbody chassis components, extending test protocols beyond historical static load assessments. Manufacturers serving the United States market must validate formulations across temperature extremes and chemical exposure scenarios. Commercial vehicle segments bear the heaviest compliance burden, passing certification costs through to fleet customers via extended warranty offerings.
Fleet procurement departments now unbundle after-sales service from component supply, selecting bushings and installation labor through separate competitive bids. Independent repair shops in Ohio and Michigan gain volume as national fleet operators disintermediate dealer networks. This pattern concentrates most visibly in Class 6-8 truck segments where downtime costs exceed parts premiums.
Automotive Trailing Arm Bushing Market Segmentation
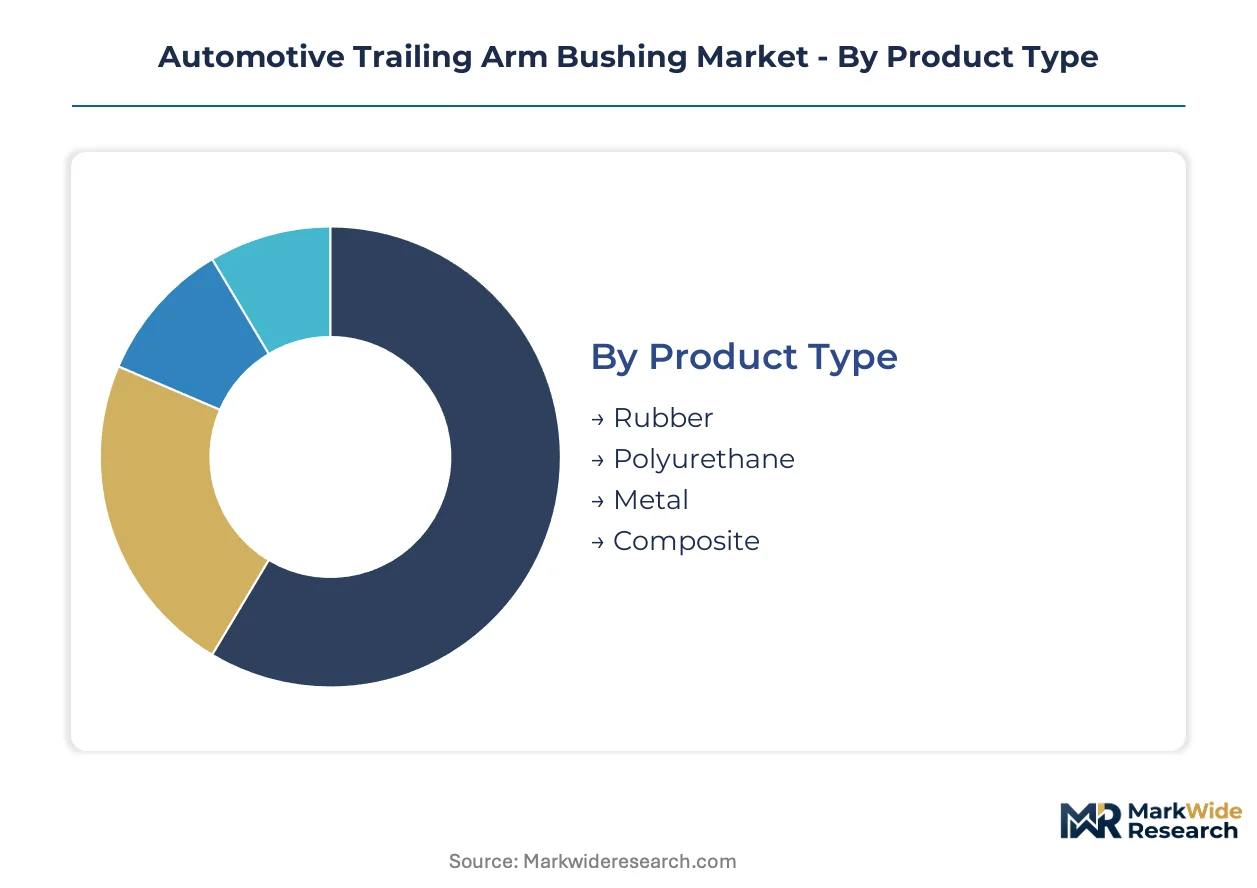
Trailing arm bushing procurement cycles vary dramatically by material chemistry and duty exposure, with commercial fleets turning over polyurethane units fastest while rubber formulations persist longest in passenger OEM fitments. Understanding these velocity differentials shapes inventory positioning and margin capture across the value chain.
Product Type:
Rubber compounds turn over slowest in light-duty applications but face accelerated replacement in severe-service commercial environments, while polyurethane and composite variants command divergent cycle times based on load severity and formulation grade.
- Rubber:Natural and synthetic polybutadiene formulations dominate OEM fitments through cost-efficient noise damping and vibration isolation. Michigan-based light-truck manufacturers specify these compounds for standard-duty chassis applications where replacement intervals extend beyond vehicle warranty periods.
- Polyurethane:Thermoplastic elastomer formulations withstand higher load deformation and chemical exposure, extending service intervals two to three times beyond rubber in Class 6-8 trucking fleets operating across Ohio corridor routes. Fleet operators in the United States absorb higher unit costs to compress maintenance downtime.
- Metal:Press-fit steel sleeve constructions serve heavy-load suspension nodes where elastomeric creep would compromise alignment geometry.
- Composite:Aramid fiber reinforced hybrids target electric vehicle platforms demanding mass reduction without structural sacrifice.
Rubber anchors the volume base while composite formulations gain share at the steepest rate.
Vehicle Type:
Commercial trucks generate the highest per-vehicle bushing counts and fastest replacement velocities, while passenger car segments concentrate volume through fleet scale rather than individual unit intensity.
- SUV:Unibody and body-on-frame architectures demand multi-point bushing arrays at rear suspension trailing arms, with all-wheel-drive variants specifying upgraded durometer ratings for torque reaction management.
- Sedan:McPherson strut and multi-link rear suspensions in compact and mid-size configurations represent the highest production volume segment, though per-vehicle bushing counts trail utility vehicle architectures.
- Truck:Solid axle and multi-leaf spring configurations in heavy-duty segments expose bushings to maximum shear loads and contamination, driving aftermarket premiumization for severe-duty polyurethane upgrades.
- Van:Commercial delivery and passenger shuttle applications prioritize durability over refinement, with fleet-specified maintenance protocols compressing replacement cycles below retail ownership patterns.
Sedan production delivers the highest absolute unit volumes while truck applications generate the steepest aftermarket value expansion.
End User:
Procurement authority is fragmenting as fleet operators unbundle component supply from installation labor, reshaping how manufacturers and distributors capture margin across direct and indirect channels.
- OEMs:Tier-1 suppliers deliver bonded assemblies to vehicle assembly plants under long-term blanket orders, with specification lock-in extending through platform life cycles.
- Aftermarket Providers:Independent distributors and private-label specialists stock broad SKU portfolios covering twenty-plus model years of domestic and import vehicle parc.
- Fleet Operators:National trucking and logistics companies negotiate direct manufacturer relationships for high-volume polyurethane procurement, bypassing traditional wholesale markups.
- Repair Shops:Independent service facilities in Michigan and Ohio manufacturing corridors capture volume as fleet operators disintermediate dealer networks for chassis maintenance.
Aftermarket providers anchor the volume base while fleet operators gain procurement influence at the steepest rate.
Application:
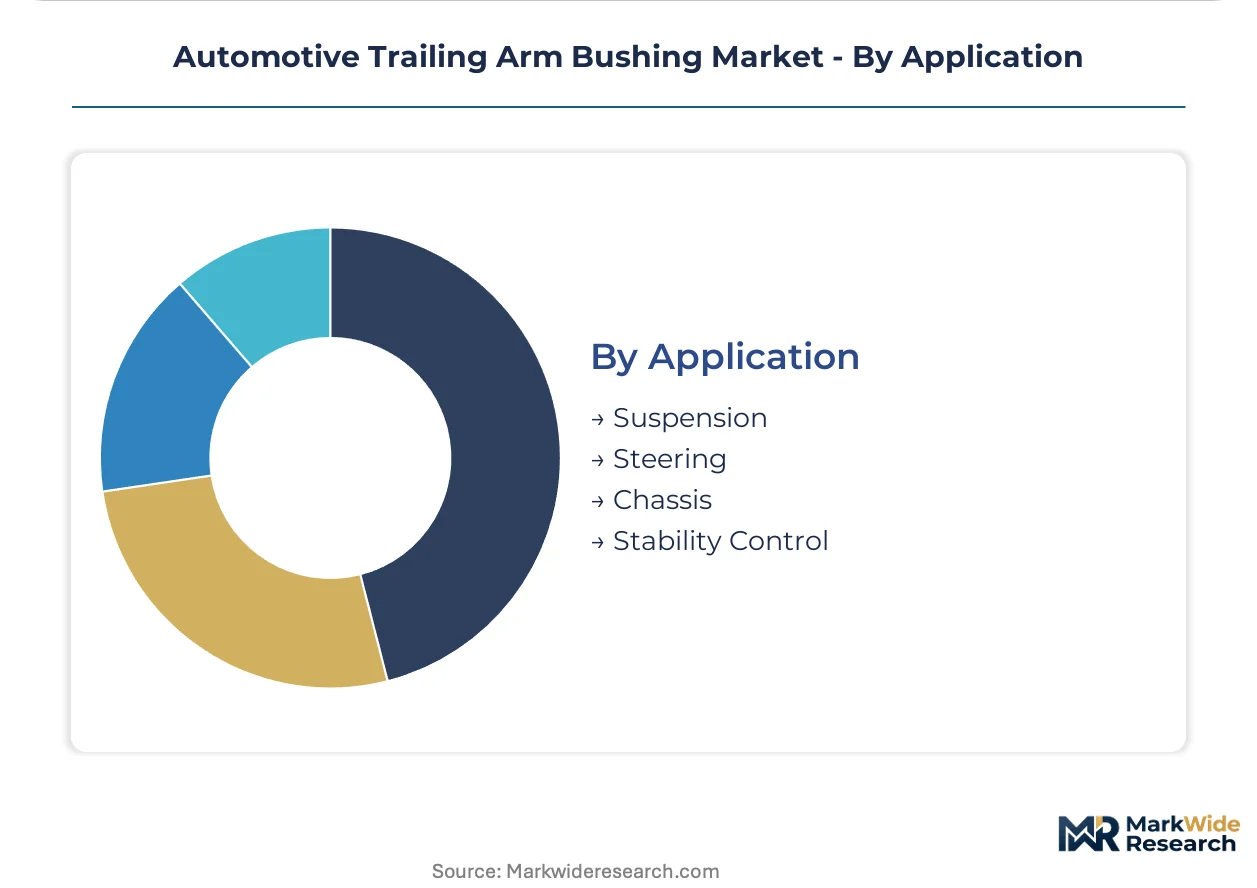
Functional location within the chassis architecture determines load vector complexity and regulatory scrutiny intensity, with suspension-mounted units facing the most severe durability validation requirements.
- Suspension:Trailing arm pivot points experience multi-axis loading from vertical wheel travel, longitudinal braking forces, and lateral cornering inputs, demanding bonded construction with steel outer sleeves for load distribution.
- Steering:Rack-and-pinion or recirculating ball steering gear mounts utilize smaller-diameter bushings with tighter tolerance bands to maintain precise alignment geometry under torsional loads.
- Chassis:Subframe and cradle isolation points prioritize noise and vibration suppression over precise kinematic control, permitting softer durometer formulations.
- Stability Control:Electronic stability system anchor points require minimal compliance to preserve sensor calibration accuracy under dynamic maneuvering.
Suspension applications anchor the volume base while stability control mounting points gain specification intensity at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Detroit-Windsor automotive corridor anchors North American chassis component production, with integrated rail and highway networks connecting Michigan assembly plants to Ontario steel suppliers and Ohio polymer compounders.
United States
Class 6-8 trucking fleets across the Ohio River Valley generate concentrated polyurethane bushing demand for severe-duty replacement cycles. NHTSA Federal Motor Vehicle Safety Standards govern structural integrity validation for chassis-mounted components in commercial vehicle segments. Michigan-based OEM assembly plants in Detroit and Flint source bonded bushing assemblies from tier-1 suppliers clustered along Interstate 75.
Germany
European premium vehicle manufacturers specify advanced composite formulations for electric platform weight reduction targets. ECHA REACH regulations restrict curative chemicals in rubber compounding, forcing reformulation investments across supplier networks. Stuttgart and Munich engineering centers prototype aramid-reinforced hybrid constructions for next-generation suspension architectures.
China
Domestic electric vehicle producers accelerate localized bushing procurement for cost-competitive chassis systems. MIIT national standards align with GB technical specifications for automotive rubber and plastic components. Yangtze River Delta manufacturing zones in Shanghai and Jiangsu province concentrate molding capacity for both OEM fitment and export aftermarket volumes.
Japan
Keiretsu supply relationships lock in long-term bushing specifications for hybrid and fuel-cell vehicle platforms. METI industrial policy supports lightweight material R&D through designated technology development programs. Aichi Prefecture production clusters around Toyota City and Nagoya maintain integrated rubber-to-assembly supply chains for domestic and Southeast Asian vehicle exports.
India
Commercial vehicle parc expansion drives aftermarket polyurethane adoption for aging medium- and heavy-duty fleets. BIS automotive component standards govern material testing protocols for chassis elastomeric parts. Tamil Nadu and Maharashtra manufacturing corridors near Chennai and Pune attract tier-1 supplier investments serving domestic OEMs and export markets.
Automotive Trailing Arm Bushing Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream with formulation and molding expertise. The supplier base organizes around three functional layers: full-system suspension providers, dedicated bushing compounders, and aftermarket distribution specialists. Consolidation pressure runs highest among mid-scale compounders facing dual certification burdens from IATF 16949 and EPA durability mandates. Strategic repositioning centers on backward integration into polymer feedstocks and forward integration into sensor-enabled smart bushing variants.
Among diversified automotive suppliers, ZF Friedrichshafen AG and Continental exemplify platform-integrator archetypes with chassis system control, while Mevotech occupies a position within the aftermarket specialist tier focused on broad SKU coverage. These three entities represent distinct competitive vectors: system bundling, material science premiumization, and distribution density.
| Leading Market Players |
|---|
| ZF Friedrichshafen AG |
| Continental |
| ACDelco |
| Mevotech |
| Federal Mogul LLC |
| Vibracoustic GmbH |
| Sumitomo Riko |
| Tenneco |
| Hyundai Polytech India |
| Others |
Value Chain & Pricing Dynamics
The Yangtze River Delta molding clusters in Shanghai and Jiangsu province concentrate polyurethane compounding capacity, feeding tier-1 suppliers who negotiate annual contract adjustments based on polybutadiene feedstock indices from Sinopec and CNPC. This geographic concentration grants compounders pricing leverage over aftermarket distributors while OEMs lock in multi-year fixed pricing through platform lifecycle agreements.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates IATF 16949-certified OEM supply from aftermarket polyurethane upgrades and unbranded rubber replacements. Fleet operators absorb premium pricing for severe-duty formulations to compress maintenance downtime, while independent repair shops in Michigan and Ohio corridors negotiate volume rebates for broad SKU coverage. Cost compression in standard rubber tiers is intensifying because natural rubber futures volatility transfers directly to compounder margins. Price sensitivity peaks among independent distributors serving aging passenger vehicle parc, whereas commercial fleet procurement departments prioritize total cost of ownership over unit pricing.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculations for steel sleeve sourcing and polyurethane resin imports. Production gravity centers on Germany, China, and Japan for bonded bushing assemblies, with secondary molding capacity in Mexico serving North American OEM just-in-sequence requirements. Raw material dependencies rest on Malaysian natural rubber plantations, Saudi Arabian polyol feedstocks, and domestic steel foundries in Ohio and Pennsylvania. Single-source vulnerability concentrates in aramid fiber supply from DuPont and Teijin facilities. Distribution runs through tier-1 direct delivery to assembly plants, independent warehouse distributors for aftermarket, and emerging direct-to-fleet platforms bypassing traditional wholesale markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in a cyclical recovery phase as commercial vehicle fleet replacement accelerates following deferred maintenance during prior economic contraction. Aging Class 6-8 truck parc in the Ohio River Valley generates sustained polyurethane demand that outpaces passenger vehicle production volatility.
For Market Incumbents: Harden IATF 16949 certification barriers by accelerating vulcanization-to-press-fit process migration before new entrants complete qualification timelines. Backward integration into polybutadiene compounding secures margin control against commodity volatility from Asian feedstock suppliers. Channel control through exclusive fleet service agreements defends against disintermediation by direct-to-shop digital platforms.
For New Entrants and Emerging Players: India's Tamil Nadu and Maharashtra manufacturing corridors present underpenetrated aftermarket opportunity as commercial vehicle parc expansion outpaces localized polyurethane supply. Target independent repair shops serving aging medium-duty fleets with severe-duty formulations priced below Continental and ZF tier-1 premiums. Launch through distributor partnerships offering technical training and inventory consignment to overcome established SKU coverage advantages.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because mid-scale compounders face dual certification burdens from EPA durability mandates and IATF 16949 timelines that favor scaled platform integrators. Acquisition targets cluster among regional polyurethane specialists with captive fleet relationships in the United States commercial vehicle corridor. Monitor NHTSA rulemaking on lifecycle durability testing as the inflection signal for reformulation investment requirements that will force sub-scale exits.
| Strategic Initiative | Industry Significance |
|---|---|
| Polyurethane Formulation Scale-Up | Extends service intervals for Class 6-8 fleets operating across Ohio corridor routes. |
| Smart Bushing Sensor Integration | Enables predictive maintenance algorithms for heavy-duty trucking fleet operators. |
| Aramid Fiber Composite Development | Targets electric vehicle platform weight reduction mandates without load sacrifice. |
| Direct-to-Fleet Platform Launch | Bypasses traditional distributor markups for national logistics company procurement. |
| REACH Compliance Reformulation | Compounds alternative curative chemistry for European-serving manufacturer qualification. |
Study Parameters
A standing panel of tier-1 supplier procurement directors, OEM platform engineers, aftermarket distribution managers, and commercial fleet maintenance supervisors provided ongoing calibration across the study period. Primary fieldwork combined structured interviews with chassis component specialists and validation sessions with polyurethane compounder technical directors. Secondary sources encompassed EPA emissions compliance filings, NHTSA Federal Motor Vehicle Safety Standards documentation, vehicle production databases from IHS Markit, and customs trade records for rubber and polymer feedstock flows. Bottom-up unit volume estimates triangulated against top-down OEM platform content analysis.
Scenario-bracketing framed the analytical approach, with base, optimistic, and conservative cases tested against regulatory acceleration and commercial fleet replacement cycle assumptions. Segmentation dimensions modeled across the analysis window included material chemistry tier, vehicle class architecture, end-user procurement authority, and regional production cluster. CAGRs derived from regression analysis of historical replacement velocities correlated with vehicle miles traveled and fleet age distributions. Industry-specific forecast inputs incorporated EPA durability test protocol evolution and polyurethane formulation service interval extension trends.
Practitioners should monitor NHTSA rulemaking timelines, REACH chemical restriction amendments, and natural rubber futures volatility for early signals requiring forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive Control Arms Market
Automotive Parts
Windshield Lifters Market
Automotive Parts
Automotive Thermal Management Systems for Electric Vehicles Market
Automotive Parts
Automotive Engine Oil Coolers Market
Automotive Parts
Electric Vehicle Aluminum Die Casting Parts Market
Automotive Parts
Gearshift Sleeves Market
Automotive Parts
UK Automotive Parts Magnesium Die Casting Market
Automotive Parts
Global Rubber Transmission Belts Market
Automotive Parts
Constant Velocity Joint Market
Automotive Parts
Automotive Hydraulic Filters Market
Automotive Parts
Automotive Pinion Gear Market
Automotive Parts
Automotive Brake Friction Materials Market
Automotive Parts
Canada Automotive Pneumatic Actuators Market
Automotive Parts
Global Automotive Ignition Market
Automotive Parts
Windshield Repair Kit Market
Automotive Parts
Powerglide Shifter Market