
 AWD Coupling System Market | 2026-2036
AWD Coupling System Market Size, Share, and Industry Trends Forecast 2026-2036
AWD Coupling System Market Insights
Premium torque-vectoring architectures is decoupling from commodity open-differential couplings on engineering specifications and pricing. BorgWarner leverages its clutch-pack expertise to dominate high-performance electric AWD platforms. ZF Friedrichshafen AG anchors European supply through integrated electro-hydraulic module production.
An AWD coupling system is a torque-transfer device that distributes power between axles or wheels through viscous, electromagnetic, or electro-hydraulic mechanisms, typically operating within 50-200 millisecond engagement cycles to maintain traction. Its primary purpose is to optimize vehicle stability, fuel efficiency, and launch performance across varying road conditions. Electromagnetic coupling is capturing margin pools as automakers electrify drivelines, while mechanical coupling sustains volume in cost-sensitive commercial vehicle segments. Hydraulic actuation technology leads in off-highway applications where shock loads demand proven durability.
EPA tailpipe standards, EU F-Gas Regulation on fluorinated lubricants, and China's MIIT new-energy vehicle mandates collectively reshape coupling material specifications and thermal management requirements. NHTSA rollover-resistance protocols in the US and ECE braking harmonization rules further constrain design freedom for suppliers seeking multi-regional homologation. Stakeholders must monitor how battery-electric platform architectures eliminate traditional mechanical couplings or create demand for integrated e-axle torque management.
Market Dynamics
Electrification of vehicle architectures is fragmenting the AWD coupling supply base into electromagnetic specialists and legacy mechanical suppliers, with EPA tailpipe rules forcing automakers to prioritize torque-vectoring efficiency over cost-minimized open-differential designs.
Growth Catalysts
- EPA Tier 3 tailpipe standards:Passenger car OEMs in the United States must improve launch traction efficiency, expanding procurement of electro-hydraulic coupling modules that reduce parasitic losses during highway cruising.
- Torque-vectoring software integration:Electric vehicle platforms in China demand coupling systems with sub-100 millisecond response cycles, pulling advanced electromagnetic architectures into mass-market segments previously served by viscous units.
- MIIT new-energy vehicle mandates:Domestic automakers face production quotas requiring intelligent driveline management, creating dedicated supply contracts for coupling suppliers with integrated thermal control capabilities.
Market Restraints
- Rare-earth magnet cost volatility:Neodymium and dysprosium price swings constrain electromagnetic coupling margins, forcing suppliers to absorb input spikes or pass through to concentrated OEM buyer pools.
- German clutch-pack supply concentration:High-performance torque-vectoring architectures depend on a narrow base of precision-forging suppliers in Baden-Württemberg, creating geographic vulnerability to energy cost shocks.
- EU F-Gas lubricant restrictions:Fluorinated hydraulic fluids face phase-down schedules, requiring reformulation of sealed coupling units and extending validation timelines for electro-hydraulic designs.
Strategic Opportunities
- India commercial vehicle electrification:Tractor and construction equipment OEMs lack domestic electromagnetic coupling sources, opening white space for joint ventures with local axle manufacturers.
- Vehicle-to-grid bidirectional charging:Coupling systems with integrated torque management enable stationary power export, creating new specification layers for smart-grid-ready electric platforms.
- Japan METI carbon-neutral technology roadmap:Subsidies for next-generation driveline components incentivize development of magnet-free electromagnetic coupling alternatives using switched reluctance principles.
Industry Challenges
- Embedded software certification:ISO 26262 functional safety validation for torque-vectoring control algorithms extends development cycles by 14-18 months, compressing supplier R&D bandwidth.
- Multi-regional homologation complexity:Simultaneous NHTSA rollover-resistance testing, ECE braking harmonization, and China GB standard compliance forces redundant engineering teams and duplicate test fleets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AWD Coupling System Market |
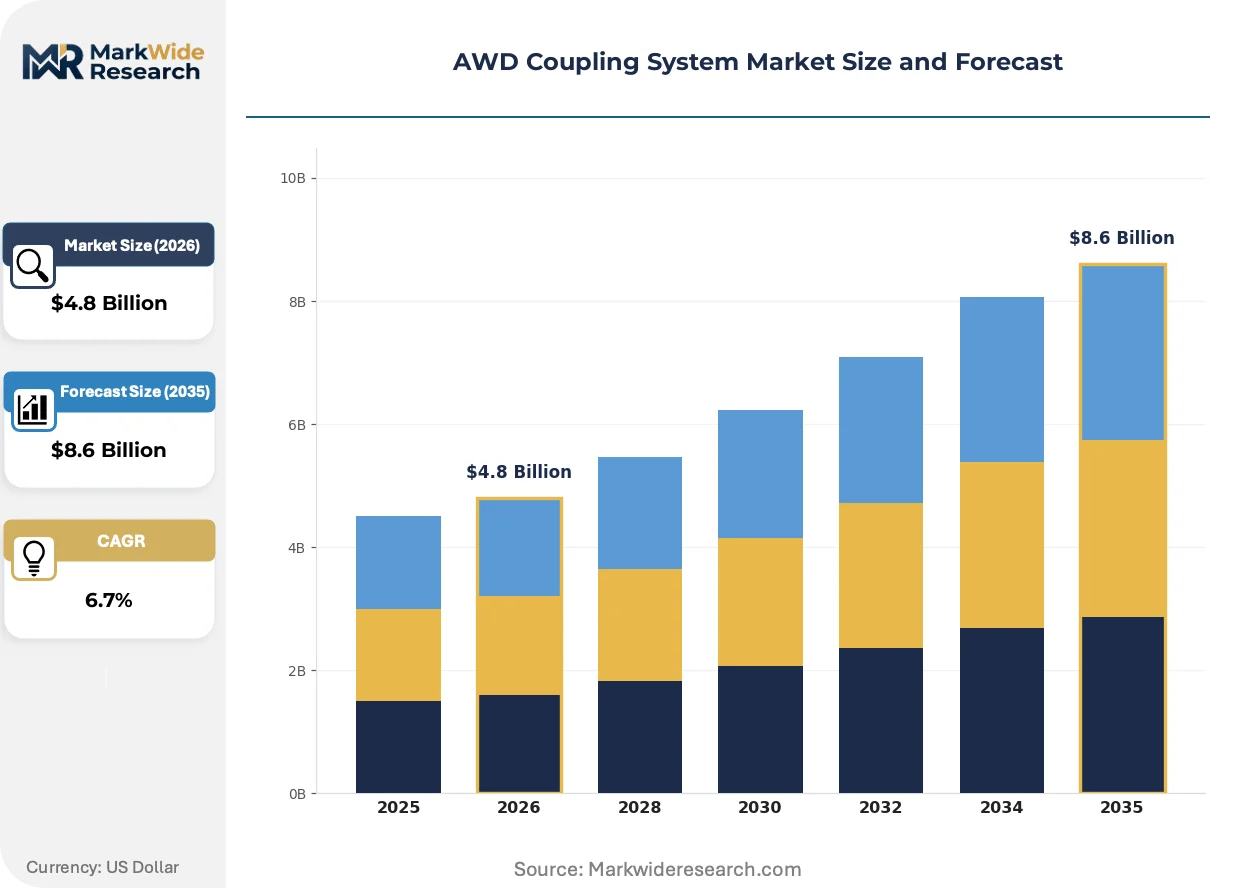
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Viscous Coupling, Electro-Hydraulic Coupling, Mechanical Coupling, Electromagnetic Coupling Technology: Hydraulic Actuation, Electric Actuation, Mechanical Engagement, Magnetic Engagement Vehicle Type: Passenger Cars, Commercial Vehicles, Off-highway Vehicles, Specialty Vehicles End User: OEMs, Aftermarket Suppliers, Fleet Operators, Vehicle Assemblers |
| Companies Covered | BorgWarner, ZF Friedrichshafen AG, GKN Automotive, Magna International, Aisin Corporation, JTEKT Corporation, Schaeffler AG, Dana Incorporated, Continental AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AWD Coupling System Market Trends and Innovations
Active torque management is migrating from mechanical differentials toward software-defined electromagnetic architectures, with thermal efficiency and millisecond response latency becoming the primary competitive battlegrounds.
Electromagnetic coupling is absorbing engineering talent and capital from legacy viscous coupling divisions. Tier-1 suppliers in Germany and Japan are retooling clutch-pack lines for eddy-current and multi-plate electromagnetic designs. This technology shift is compressing the addressable market for purely mechanical torque-transfer devices in passenger car segments.
China's MIIT enforcement of dual carbon goals is tightening material specifications for coupling lubricants and housing alloys. Suppliers must document embodied carbon in aluminum die-castings and shift to PFAS-free hydraulic fluids. Electric SUV platforms targeting domestic consumers face the steepest compliance ramps.
Fleet procurement managers at commercial vehicle operators are unbundling coupling systems from axle assemblies, sourcing modules directly from specialized vendors rather than through drivetrain integrators. This channel disintermediation is most pronounced in North American heavy-duty pickup segments, where end-users prioritize field-serviceability and standardized mounting interfaces over OEM-locked designs.
AWD Coupling System Market Segmentation
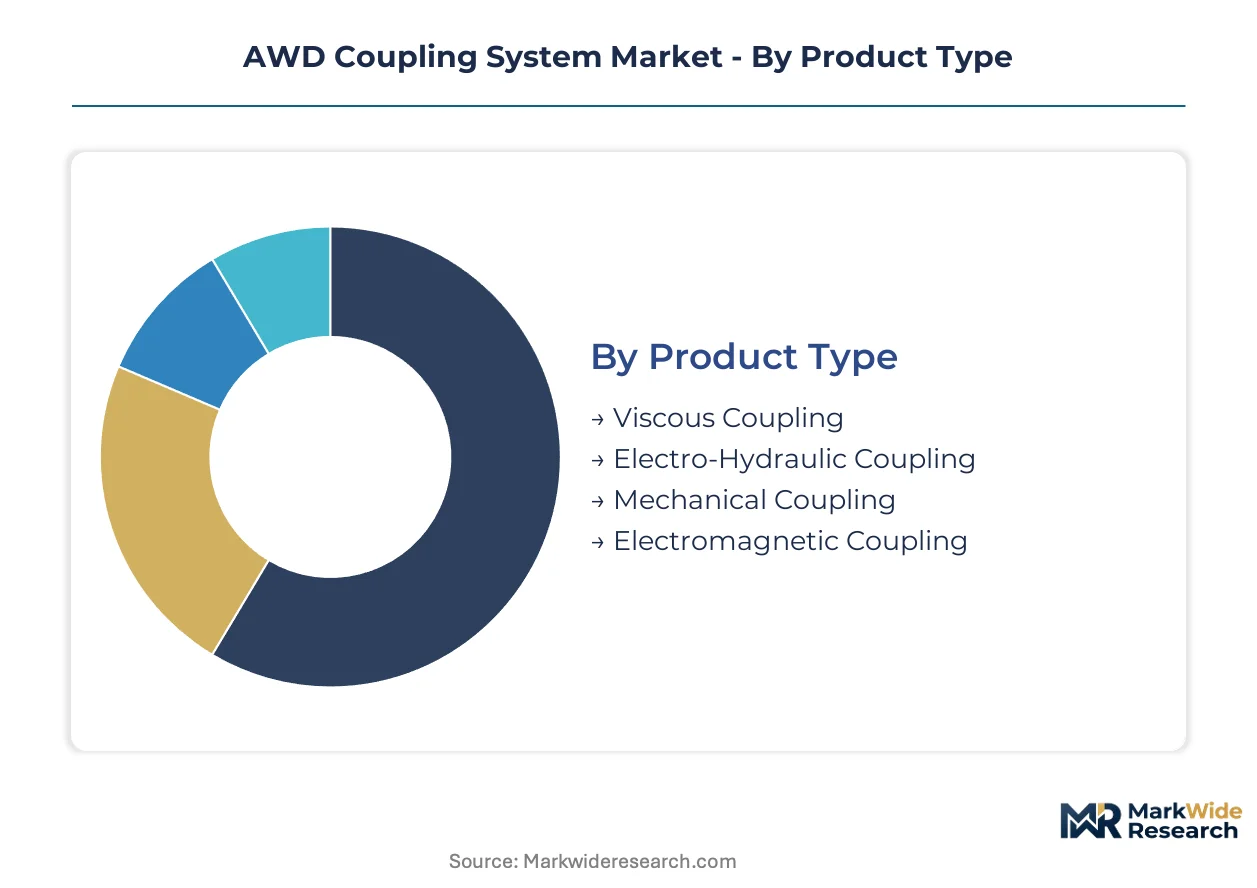
Segmentation in the AWD coupling market reveals how certification burdens, thermal requirements, and electrification roadmaps split procurement patterns across product architectures. Understanding these divides exposes where margin pools concentrate and where volume commoditization threatens supplier returns.
Product Type:
ISO 26262 functional safety certification applies differentially across this category, with electromagnetic architectures facing the steepest validation burdens while mechanical variants clear homologation through established SAE protocols.
- Electromagnetic Coupling:Eddy-current and multi-plate designs achieve sub-100 millisecond response cycles through precision-wound copper coils and rare-earth magnet arrays. Chinese EV platforms demanding torque-vectoring precision now pull this technology into mass-market segments previously served by viscous alternatives.
- Electro-Hydraulic Coupling:Integrated pump-valve-clutch modules modulate torque transfer through pressurized fluid circuits with electronic control. EPA Tier 3 compliance in the United States expands procurement of these units for their parasitic loss reduction during highway cruising.
- Viscous Coupling:Silicone-fluid shear mechanisms provide passive torque bias without electronic control, sustaining volume in cost-sensitive emerging markets where simplified serviceability outweighs efficiency optimization.
- Mechanical Coupling:Dog-clutch and synchronizer designs persist in commercial vehicle segments where durability under shock loads trumps response speed, particularly in Indian tractor and construction equipment applications.
Electro-hydraulic coupling sits at the top of the volume ranking, with electromagnetic coupling climbing the fastest.
Technology:
Cost tier stratification separates premium electric and magnetic engagement systems from economy mechanical and hydraulic alternatives, with thermal management complexity driving the wedge.
- Electric Actuation:Servo-motor and ball-screw mechanisms deliver precise clutch pack pressure control with minimal energy consumption. Japanese METI carbon-neutral subsidies accelerate development of magnet-free switched reluctance variants for next-generation drivelines.
- Hydraulic Actuation:Proven pressure-modulation systems dominate off-highway equipment where contamination resistance and field-serviceability outweigh packaging efficiency, particularly in German and Japanese mining vehicle exports.
- Magnetic Engagement:Eddy-current and hysteresis principles enable contactless torque transfer with zero mechanical wear, capturing specification wins in high-cycle electric SUV platforms targeting Chinese domestic consumers.
- Mechanical Engagement:Spring-loaded and cam-actuated designs retain share in emerging market commercial vehicles where electromagnetic complexity creates service network vulnerabilities.
Hydraulic actuation retains the largest installed base, though electric actuation gains share fastest as battery-electric platforms proliferate.
Vehicle Type:
Application severity determines thermal specification tiers, with off-highway and specialty segments demanding sealed housings and high-temperature alloys absent from passenger car designs.
- Passenger Cars:Crossover and SUV platforms in China, Germany, and Japan concentrate demand for compact, lightweight coupling modules with integrated thermal management, driven by MIIT dual carbon compliance and EU F-Gas lubricant restrictions.
- Commercial Vehicles:Heavy-duty pickup and delivery van fleets in North America increasingly source coupling modules directly from specialized vendors rather than axle integrators, prioritizing standardized mounting interfaces.
- Off-highway Vehicles:Mining and agricultural equipment requires shock-rated hydraulic actuation with filtration systems capable of operating in contaminated environments.
- Specialty Vehicles:Military and emergency service platforms demand redundant control architectures with MIL-STD electromagnetic compatibility certification.
Passenger cars anchor procurement volume, with commercial vehicles expanding most quickly through fleet direct-sourcing trends.
End User:
Customer type shapes margin structure, with OEM captive supply agreements compressing pricing while aftermarket and fleet channels reward modular serviceability.
- OEMs:Integrated vehicle manufacturers in China, Germany, and Japan negotiate multi-year coupling supply contracts tied to platform-specific thermal and response specifications, with NHTSA rollover-resistance protocols constraining design freedom.
- Fleet Operators:North American heavy-duty pickup and delivery van operators now unbundle coupling systems from axle assemblies, creating procurement channels for standardized, field-serviceable modules.
- Aftermarket Suppliers:Independent distributors serve replacement demand in regions with aging vehicle populations, particularly for mechanical and viscous coupling rebuild kits.
- Vehicle Assemblers:Contract manufacturers and kit-car builders source coupling modules through distributor networks rather than direct Tier-1 relationships.
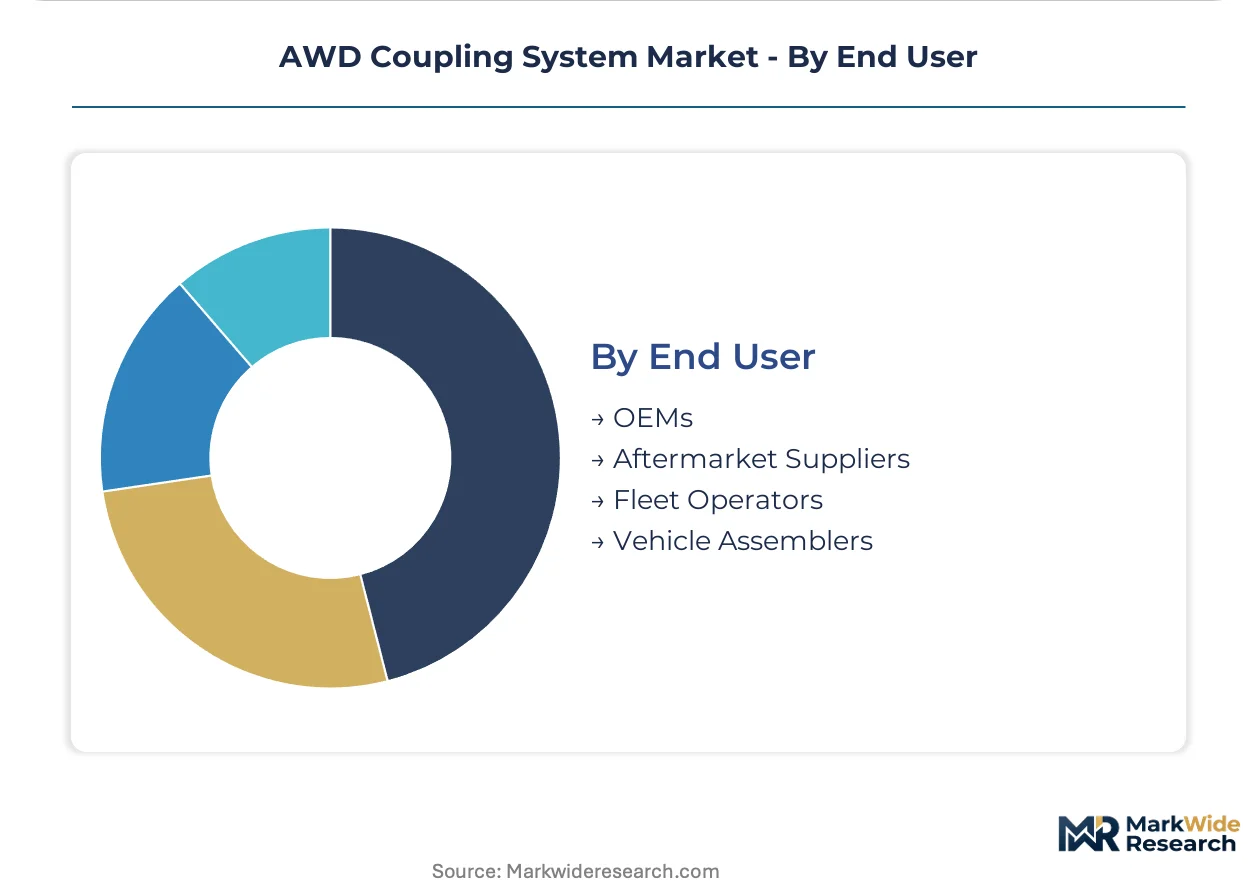
OEMs command the dominant procurement volume, with fleet operators representing the steepest expansion trajectory through disintermediation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent clusters in Stuttgart, Nagoya, and Shanghai anchor the AWD coupling industry's geographic footprint. These metropolitan concentrations house the precision-forging, electromagnetic design, and systems integration capabilities that define competitive positioning across major automotive markets.
United States
EPA Tier 3 tailpipe standards drive passenger car OEMs toward electro-hydraulic coupling modules that cut parasitic losses during highway cruising. NHTSA rollover-resistance protocols constrain design freedom for suppliers seeking multi-regional homologation. Detroit-area engineering centers concentrate procurement teams for next-generation torque-vectoring architectures.
Germany
Baden-Württemberg's precision-forging suppliers anchor high-performance clutch-pack production for torque-vectoring systems. EU F-Gas Regulation phase-down schedules force reformulation of sealed coupling units and extend validation timelines for electro-hydraulic designs. ZF Friedrichshafen AG's integrated electro-hydraulic module production anchors European supply chains.
China
MIIT new-energy vehicle mandates require domestic automakers to meet production quotas for intelligent driveline management. Dual carbon goals tighten material specifications for coupling lubricants and aluminum die-castings. Shanghai and Yangtze River Delta engineering clusters concentrate development of sub-100 millisecond response electromagnetic architectures for electric SUV platforms.
Japan
METI carbon-neutral technology roadmap subsidies incentivize magnet-free electromagnetic coupling alternatives using switched reluctance principles. JIS standards compliance shapes thermal management specifications for domestic electric vehicle platforms. Nagoya-area suppliers retool clutch-pack lines for eddy-current and multi-plate electromagnetic designs.
India
Commercial vehicle electrification creates white space for joint ventures with local axle manufacturers in tractor and construction equipment segments. BIS certification requirements for automotive components extend validation timelines for imported electromagnetic systems. Maharashtra and Gujarat industrial corridors concentrate domestic procurement for cost-sensitive mechanical coupling applications.
AWD Coupling System Market Competitive Landscape
Top-tier vendors anchor high-performance torque-vectoring architectures, while mid-tier specialists occupy cost-optimized mechanical and viscous coupling segments. The vendor base stratifies around electromagnetic expertise, hydraulic actuation legacy, and integrated systems integration capabilities. Three archetypes dominate: clutch-pack precision specialists, electro-hydraulic module integrators, and electromagnetic architecture innovators. Consolidation pressures manifest through strategic partnerships for thermal management technology and backward integration into rare-earth magnet supply chains.
Within the electromagnetic architecture tier, BorgWarner exemplifies clutch-pack expertise leveraged for high-performance electric AWD platforms. ZF Friedrichshafen AG occupies a position as the anchor of European supply through integrated electro-hydraulic production. GKN Automotive represents the precision-forging and systems integration archetype that spans both mechanical legacy and electrified future architectures.
| Leading Market Players |
|---|
| BorgWarner |
| ZF Friedrichshafen AG |
| GKN Automotive |
| Magna International |
| Aisin Corporation |
| JTEKT Corporation |
| Schaeffler AG |
| Dana Incorporated |
| Continental AG |
| Others |
Pricing and Supply Chain Analysis
Neodymium and dysprosium price indices cascade through electromagnetic coupling architectures, compressing margins for rare-earth-dependent suppliers while amplifying pricing power for magnet-free switched reluctance innovators serving EPA Tier 3 and MIIT compliance buyers.
Pricing Analysis
Bundled axle-assembly contracts dominate OEM procurement, yet fleet operator unbundling in North American heavy-duty segments creates modular spot-market tiers. Three-tier pricing structure across torque-vectoring precision, standard electro-hydraulic, and economy viscous levels reflects ISO 26262 certification grade and thermal management complexity. Pricing pressure stems from rare-earth cost pass-through constraints, with Chinese EV platforms most price-sensitive due to volume procurement mandates and German luxury OEMs least sensitive given performance-tier prioritization.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from China, Germany, and Japan, while specialized distributors serve fleet direct-sourcing and aftermarket rebuild segments. Precision-forging capacity concentrates in Baden-Württemberg, Yangtze River Delta, and Nagoya industrial corridors, drawing from copper coil windings, rare-earth magnet arrays, and PFAS-free hydraulic fluid formulations. Single-source vulnerability in German clutch-pack forging creates geographic concentration risk. Distribution runs through Tier-1 integrators for passenger car platforms and direct vendor relationships for commercial vehicle fleet operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where EPA Tier 3, EU F-Gas, and MIIT dual carbon mandates collectively reshape procurement specifications and thermal management requirements across all vehicle architectures.
For Market Incumbents: Anchor clutch-pack precision expertise in high-performance electric AWD platforms through backward integration into rare-earth magnet supply chains. Defend against magnet-free switched reluctance substitutes by accelerating JIS and ISO 26262 certification investments for next-generation electromagnetic architectures. Prioritize captive forging capacity additions in Baden-Württemberg to mitigate energy cost shock exposure.
For New Entrants and Emerging Players: Capture white space in Indian commercial vehicle electrification through joint ventures with Maharashtra and Gujarat axle manufacturers lacking domestic electromagnetic coupling sources. Target tractor and construction equipment segments where mechanical coupling displacement creates specification windows for cost-optimized electro-hydraulic modules. Pursue fleet direct-sourcing channels in North American heavy-duty pickup segments through standardized mounting interface offerings.
For Investors and Strategic Acquirers: Asymmetric upside sits with electromagnetic architecture innovators possessing magnet-free patent positions and integrated thermal control capabilities. Long-term viability hinges on regulatory compliance technology rather than mechanical legacy volume. Monitor Japan METI subsidy disbursement velocity as inflection indicator for switched reluctance commercialization timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Magnet-Free Electromagnetic Development | METI carbon-neutral subsidies accelerate switched reluctance alternatives reducing rare-earth dependency. |
| Precision Forging Capacity Expansion | Baden-Württemberg clutch-pack investments secure supply for torque-vectoring architectures. |
| Fleet Direct-Sourcing Channel Buildout | North American heavy-duty pickup unbundling creates modular procurement bypassing axle integrators. |
| PFAS-Free Hydraulic Fluid Reformulation | EU F-Gas compliance extends validation timelines for sealed electro-hydraulic coupling units. |
| Sub-100 Millisecond Response Certification | Chinese EV platform specifications pull advanced electromagnetic architectures into mass-market segments. |
Research Methodology
Direct dialogue with Tier-1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and fleet maintenance directors grounded qualitative findings in operational reality. Secondary validation drew from vehicle production databases, IHS Markit registration data, EPA certification filings, and MIIT new-energy vehicle quota disclosures. Bottom-up unit economics triangulated against top-down regulatory mandate sizing across the analysis window.
Segment-level outputs reflect propulsion architecture, vehicle class, content per vehicle, and regional production cluster dimensions throughout the forecast period. CAGRs emerged from regression against regulatory compliance timelines and electrification penetration curves. Forecast inputs incorporated thermal management specification ramps, rare-earth price elasticity assumptions, and fleet procurement channel shift velocities.
Rare-earth magnet cost volatility, German energy price shocks, and China dual carbon enforcement acceleration are the dominant revision risks to base-case projections. Forecasts embed assumptions regarding MIIT quota stringency and EU F-Gas phase-down adherence. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
France Automotive Hydraulic Actuators Market
Automotive Parts
Leaf Spring Shackle Side Bar Market
Automotive Parts
Camshaft Lifters Market
Automotive Parts
Daytime Running Lights Market
Automotive Parts
Battery Jump Starters Market
Automotive Parts
Automotive Brake Fluid Market
Automotive Parts
Asia-Pacific Electric Power Steering Market
Automotive Parts
Global Automotive Gasket and Seal Market
Automotive Parts
Automotive Power Window Regulator Market
Automotive Parts
India Automotive Hydraulic Actuators Market
Automotive Parts
Automotive Evaporators and Blowers Market
Automotive Parts
Automotive Air Lift Jack Market
Automotive Parts
Cylinder Head Cover Market
Automotive Parts
Automotive Coolant Market
Automotive Parts
Air Springs Market
Automotive Parts
Global Auto Parts and Accessories Market