
 France Automotive Actuators Market | 2026-2036
France Automotive Actuators Market Size, Share, and Industry Trends Forecast 2026-2036
France Automotive Actuators Market Foresight
European actuator production capacity is consolidating around electromechanical platforms serving hybrid and battery-electric vehicle programs. Robert Bosch GmbH leverages its Stuttgart-Paris R&D corridor to sustain development of high-torque electric actuators for powertrain control. Continental AG anchors supply relationships with French OEMs through its specialized chassis management actuator lines. Sonceboz SA competes from its Swiss-French border manufacturing base, differentiating through precision micro-actuators for body electronics.
France automotive actuators are electromechanical, electrohydraulic, or piezoelectric devices that convert electrical or fluid energy into precise mechanical motion, typically achieving positioning accuracy within micrometers to millimeters depending on application. These components enable automated control of engine valves, suspension geometry, climate flaps, and safety locks across vehicle platforms. Electric actuators now lead product type demand as powertrain electrification eliminates vacuum and hydraulic assist sources. Electromechanical technology occupies the fastest-growing tier within technology segmentation, driven by motor-inverter integration trends and reduced part counts. Safety mechanisms represent a concentrated margin pool within application segmentation, where regulatory mandates for autonomous emergency braking and active hood systems enforce actuator redundancy.
France's national regulator ANSM oversees component safety certifications, while EU REACH and RoHS frameworks restrict hazardous substances in actuator materials and coatings. The EU AI Act and forthcoming cyber-security standards for connected vehicles are forcing actuator suppliers to embed encrypted position feedback and over-the-air update capabilities. Stakeholders must monitor how France's implementation of the EU Green Deal alters carbon-border calculations for imported actuator subcomponents from Asia.
Market Dynamics
Powertrain electrification is eliminating vacuum and hydraulic assist sources across French OEM lineups, forcing a wholesale actuator technology transition from pneumatic and hydraulic systems to electromechanical platforms that integrate motor-inverter architectures.
Growth Catalysts
- EU Green Deal implementation:France's national low-carbon vehicle incentives tighten emissions benchmarks and mandate electrified powertrains, expanding actuator demand for battery thermal management and e-motor positioning.
- Paris-Saclay automotive cluster concentration:R&D proximity between OEM engineering centers and tier-one suppliers accelerates prototype-to-production cycles for chassis management actuators.
- Electromechanical motor-inverter integration:Reduced part counts and simplified assembly architectures lower system costs while improving positioning accuracy for safety-critical applications.
Market Restraints
- Rare-earth magnet supply concentration:Permanent magnet motors in high-torque actuators depend on neodymium processing concentrated in Asian supply chains, exposing French manufacturers to price volatility and export restriction risks.
- EU REACH substance restrictions:Hazardous substance limitations on actuator coatings and housing materials force reformulation of corrosion-resistant surface treatments, extending qualification timelines.
- Hydraulic actuator installed base:Legacy chassis systems in commercial vehicle fleets create substitution drag, as hydraulic platforms retain cost advantages in heavy-load positioning applications.
Strategic Opportunities
- Autonomous emergency braking mandates:Regulatory requirements for active hood systems and redundant brake actuators create dedicated demand pools in safety mechanism segments.
- Northern manufacturing corridor expansion:Lille-Douai production zones offer underutilized capacity for precision micro-actuator assembly serving body electronics programs.
- Over-the-air update integration:Cyber-security standards for connected vehicles enable actuator suppliers to embed encrypted position feedback and recurring software revenue streams.
Industry Challenges
- Embedded systems engineering talent scarcity:Shortages of firmware developers capable of integrating motor control algorithms with automotive-grade functional safety standards constrain product development velocity.
- EU AI Act compliance timeline:Certification requirements for machine-learning-enabled position prediction algorithms introduce validation bottlenecks that extend time-to-market for smart actuator variants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Automotive Actuators Market |
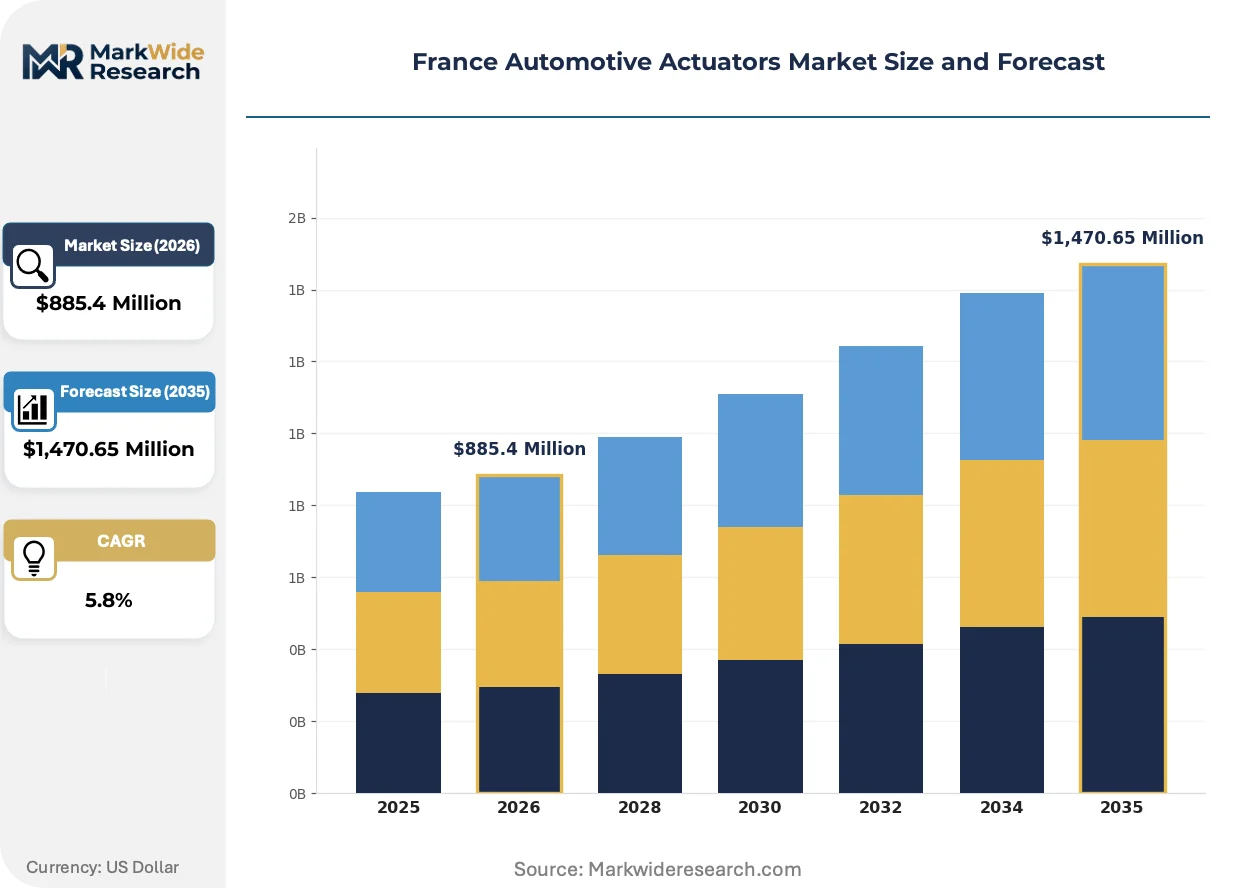
| Market Size in 2026 | $885.4 Million |
| Market Size in 2035 | $1,470.65 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Linear Actuators, Rotary Actuators, Pneumatic Actuators, Hydraulic Actuators, Electric Actuators Technology: Electromechanical, Electrohydraulic, Piezoelectric, Shape Memory Alloy, Magnetic Application: Powertrain Control, Chassis Management, HVAC Systems, Body Electronics, Safety Mechanisms End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers |
| Companies Covered | Mitsubishi Electric, Nidec Corporation, Robert Bosch GmbH, BorgWarner Inc, Hella KGaA Hueck & Co., Denso Corporation, Aptiv PLC, Sonceboz SA, Continental AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Automotive Actuators Market Shifts & Advancements
Actuator architectures are fragmenting into application-specific platforms as electrification eliminates universal pneumatic backbones. Three convergent forces are compressing development cycles and reshaping supplier technical roadmaps.
Integrated motor-inverter units are modularizing power electronics packaging for chassis and powertrain actuators. Tier-one suppliers serving Stellantis and Renault electrification programs are adopting standardized inverter daughterboards that slot across brake-by-wire and steer-by-wire applications. This convergence is modularizing actuator supply chains, allowing French manufacturers to source power stages from semiconductor specialists while retaining mechanical integration expertise.
France's ANSM and EU-level regulators are tightening component safety certification protocols under the EU AI Act and forthcoming cyber-security standards. Encrypted position feedback and secure boot capabilities are becoming mandatory for connected vehicle actuators. The safety mechanism segment is responding fastest, with redundant encoder architectures now baseline for autonomous emergency braking systems.
French OEM procurement organizations are consolidating actuator suppliers around electromechanical platform providers capable of spanning powertrain, chassis, and body electronics applications. Long-term framework agreements are displacing spot purchasing for commodity pneumatic components. This concentration is most visible in the Paris-Saclay cluster, where Renault and Stellantis engineering teams co-locate supplier technical centers to compress design iteration cycles.
France Automotive Actuators Market Segmentation
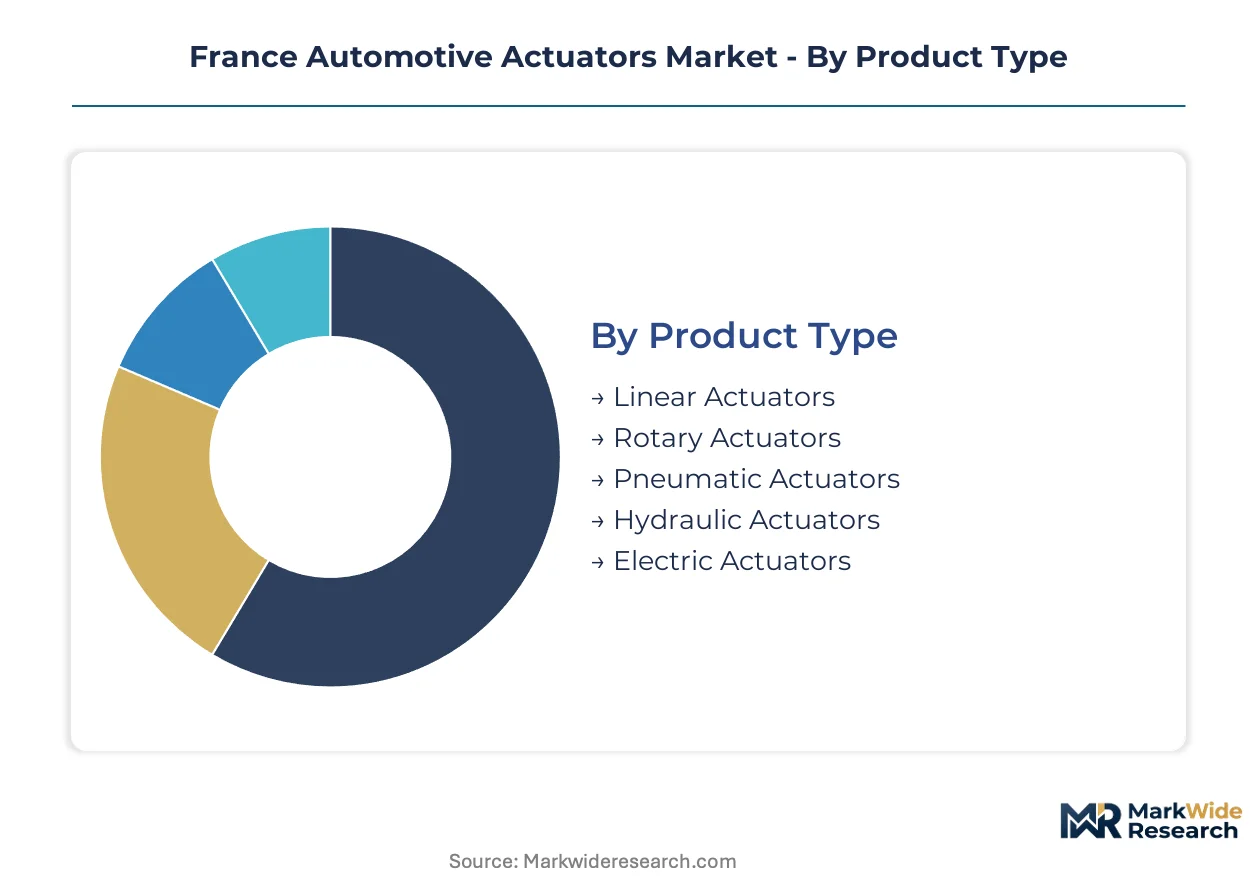
Actuator segmentation in France reflects divergent technical requirements across electrified powertrains, chassis digitization, and safety mandates. Procurement patterns vary sharply by customer sophistication and integration depth.
Product Type:
OEMs select actuator architectures based on force density needs, control precision, and compatibility with legacy vehicle electrical systems.
- Electric Actuators:Brushless DC and stepper motor platforms deliver positioning accuracy within micrometers for throttle bodies and battery thermal valves. Demand concentrates around Renault's ElectriCity manufacturing complex in northern France as the automaker phases out vacuum-assisted engine controls. ANSM safety certifications for autonomous emergency braking systems mandate redundant encoder feedback in these units.
- Linear Actuators:Ball-screw and belt-drive mechanisms convert rotary motor motion into precise linear displacement for active suspension and seat adjustment. Paris-Saclay engineering centers prioritize compact stroke-to-length ratios that preserve cabin packaging space in compact EV architectures. The EU Green Deal's weight reduction targets accelerate aluminum housing adoption.
- Rotary Actuators:Geared motor assemblies producing torque outputs from 5 Nm to 500 Nm for steering column tilt and mirror positioning.
- Pneumatic Actuators:Compressed-air diaphragm and piston systems retaining cost advantages in commercial vehicle brake actuation and door control.
- Hydraulic Actuators:Cylinder-and-piston platforms with force multiplication for heavy-load chassis positioning in vocational trucks.
Electric actuators lead volumes today; linear actuators are gaining share fastest.
Technology:
Technology selection hinges on response time requirements, energy efficiency thresholds, and thermal operating envelopes.
- Electromechanical:Integrated motor-inverter architectures eliminate discrete power electronics packaging through silicon carbide MOSFET integration. French tier-one suppliers serving Stellantis electrification programs source standardized inverter daughterboards from semiconductor specialists while retaining mechanical integration. REACH substance restrictions on housing coatings force reformulation of corrosion-resistant surface treatments.
- Piezoelectric:Ceramic stack actuators achieving nanometer-scale displacement resolution for fuel injector control and precision optical alignment. The Lille-Douai manufacturing corridor hosts specialized assembly operations for these high-voltage ceramic platforms. EU AI Act certification timelines constrain validation of machine-learning-enabled position prediction algorithms.
- Electrohydraulic:Servo-valve controlled fluid power systems bridging electric signal precision with hydraulic force density.
- Shape Memory Alloy:Nickel-titanium wire actuators enabling compact, silent motion for HVAC flap control and grille shutter systems.
- Magnetic:Voice coil and solenoid platforms providing rapid response for transmission shift control and active engine mounting.
Electromechanical platforms dominate current procurement; piezoelectric systems show the steepest expansion trajectory.
Application:
Application segmentation tracks divergent safety criticality levels, environmental exposure, and OEM integration responsibility.
- Safety Mechanisms:Redundant brake actuators, active hood lifters, and steering column locks requiring ASIL-D functional safety ratings. Regulatory mandates for autonomous emergency braking enforce dual-channel encoder architectures and encrypted position feedback. Cyber-security standards for connected vehicles compel over-the-air update capability embedding.
- Powertrain Control:Throttle bodies, wastegate actuators, and transmission shift mechanisms managing torque delivery in hybrid and battery-electric architectures. Northern France's vehicle assembly plants specify high-temperature resilience for e-motor thermal management valves. Rare-earth magnet supply concentration in Asian processing chains exposes manufacturers to price volatility.
- Chassis Management:Active suspension, brake-by-wire, and steer-by-wire actuators governing vehicle dynamics.
- HVAC Systems:Blend door, recirculation flap, and compressor clutch actuators regulating cabin climate.
- Body Electronics:Window lift, seat adjustment, and mirror positioning actuators with lower functional safety requirements.
Safety mechanisms command premium pricing today; powertrain control applications are climbing the fastest.
End User:
End-user categories reflect distinct technical capabilities, volume scales, and specification authority in France's automotive value chain.
- OEMs:Renault, Stellantis, and Alpine exercise direct actuator specification for powertrain and safety-critical systems, maintaining captive engineering teams for integration validation. Long-term framework agreements with electromechanical platform providers displace spot purchasing for commodity components. Co-location of supplier technical centers in the Paris-Saclay cluster compresses design iteration cycles.
- Tier-1 Suppliers:Bosch, Continental, and Valeo aggregate actuator demand across multiple OEM programs, achieving scale economies in motor-inverter integration. These suppliers face embedded systems engineering talent scarcity as firmware development velocity constrains product roadmaps.
- Vehicle Assemblers:Contract manufacturers and niche EV producers sourcing pre-integrated actuator modules.
- Aftermarket Providers:Independent distributors and repair networks addressing replacement demand for legacy hydraulic and pneumatic systems.
OEMs direct the highest-value procurement today; tier-1 suppliers are capturing share fastest through platform consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping actuator production geography as manufacturers seek cost-of-compliance advantages. France's implementation of REACH substance restrictions and EU AI Act certification timelines creates compliance premiums that some suppliers offset through strategic facility placement.
Île-de-France
Renault and Stellantis engineering centers in the Paris-Saclay cluster drive specification authority for safety-critical actuators. ANSM certification protocols for autonomous emergency braking systems enforce redundant encoder architectures. Supplier technical centers co-locate with OEM teams to compress design iteration cycles for chassis management programs.
Hauts-de-France
The Lille-Douai manufacturing corridor hosts underutilized capacity for precision micro-actuator assembly serving body electronics. EU Green Deal carbon-border calculations incentivize domestic production of electromechanical platforms over imported subcomponents. Northern vehicle assembly plants specify high-temperature resilience for e-motor thermal management valves.
Auvergne-Rhône-Alpes
Piezoelectric ceramic stack operations concentrate near specialized high-voltage assembly infrastructure. REACH restrictions on housing coatings force reformulation of corrosion-resistant surface treatments, extending qualification timelines. The region's precision manufacturing heritage supports nanometer-scale displacement resolution for fuel injector control applications.
Provence-Alpes-Côte d'Azur
Alpine's electrification programs generate demand for lightweight linear actuators in compact EV architectures. EU cyber-security standards for connected vehicles compel over-the-air update capability embedding in safety mechanism segments. Mediterranean logistics corridors facilitate semiconductor sourcing for integrated motor-inverter units.
France Automotive Actuators Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue electromechanical platform specialization through motor-inverter integration. The supplier base concentrates around electromechanical platform providers capable of spanning powertrain, chassis, and body electronics applications. Three archetypes dominate: diversified industrial conglomerates with captive automotive divisions, specialized motion control firms with precision micro-actuator expertise, and semiconductor-forward suppliers leveraging power electronics integration. Competitive moves center on long-term framework agreements displacing spot purchasing, and co-location of technical centers within OEM engineering clusters.
Among diversified industrial groups, Robert Bosch GmbH and Continental AG exemplify platform consolidation strategies. Sonceboz SA occupies a position within the precision micro-actuator specialist tier. These three entities represent the dominant competitive anchors as French OEM procurement organizations consolidate supplier relationships around electromechanical capabilities.
| Leading Market Players |
|---|
| Mitsubishi Electric |
| Nidec Corporation |
| Robert Bosch GmbH |
| BorgWarner Inc |
| Hella KGaA Hueck & Co. |
| Denso Corporation |
| Aptiv PLC |
| Sonceboz SA |
| Continental AG |
| Others |
Supply & Pricing Matrix
Neodymium oxide price volatility cascades through French actuator manufacturing tiers, compressing margins for electromechanical platforms while amplifying cost advantages for hydraulic alternatives in heavy-load commercial vehicle segments. ANSM certification timelines and REACH compliance premiums stratify procurement costs across OEM direct contracts and tier-one supplier aggregations.
Pricing Analysis
Distributor margins for aftermarket pneumatic actuators sit 12-18 points above direct-to-OEM electromechanical contracts, compressing as Renault and Stellantis consolidate supplier frameworks. Three-tier pricing structure across ASIL-D certified safety mechanisms, standard chassis actuators, and economy body electronics segments reflects certification grade and volume scale differentiation. Cost compression in standard-tier electromechanical units is intensifying because motor-inverter integration eliminates discrete power electronics packaging. Aftermarket providers serving legacy hydraulic fleets exhibit highest price sensitivity; OEM safety-critical procurement shows lowest elasticity due to regulatory mandate enforcement.
Supply Chain Analysis
EU AI Act certification and ANSM safety protocols gate supplier qualification, extending onboarding timelines for Asian component sources. Permanent magnet motors draw from neodymium processing concentrated in China and Myanmar, while silicon carbide MOSFETs feed from Taiwanese and South Korean foundries. Single-source vulnerability in rare-earth magnet supply chains exposes French manufacturers to export restriction risks. Distribution runs through tier-one supplier technical centers co-located in the Paris-Saclay cluster, with direct OEM delivery for safety-critical platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
France's actuator market rewards geographic arbitrage between REACH-compliant domestic electromechanical production and carbon-border-exposed Asian subcomponent sourcing, with compliance premiums widening as EU Green Deal implementation tightens.
For Market Incumbents: Hedge rare-earth magnet supply exposure through backward integration into magnet recycling or alternative motor topologies, while defending chassis actuator margins via long-term framework agreements with Stellantis and Renault that lock in volume commitments against emerging piezoelectric substitutes. For New Entrants and Emerging Players: Capture white-space in precision micro-actuator assembly for body electronics programs targeting the Lille-Douai manufacturing corridor, where underutilized capacity and EU Green Deal carbon-border incentives favor domestic production over imported alternatives. For Investors and Strategic Acquirers: Asymmetric upside sits with electromechanical platform specialists possessing motor-inverter integration capabilities and ANSM certification track records, with long-term viability hinging on software-defined actuator architectures. Watch for EU cyber-security standard finalization as the inflection signal triggering consolidation around encrypted feedback capability providers.| Strategic Initiative | Industry Significance |
|---|---|
| Motor-Inverter Integration Investment | Eliminates discrete power electronics packaging, reducing part counts for Stellantis electrification programs. |
| ANSM Certification Acceleration | Compresses time-to-market for autonomous emergency braking actuator variants ahead of regulatory deadlines. |
| Rare-Earth Magnet Recycling Partnership | Secures neodymium supply independence from Asian processing concentration and export restriction exposure. |
| Paris-Saclay Technical Center Co-location | Compresses design iteration cycles with Renault and Stellantis engineering teams for chassis programs. |
| Encrypted Position Feedback Embedding | Enables over-the-air update revenue streams under EU cyber-security standards for connected vehicles. |
Research Methodology
Bottom-up vehicle production modeling reconciled against top-down supplier shipment tracking forms the analytical core, combining primary interviews with OEM platform engineers, tier-one procurement leads, aftermarket distributors, and ANSM certification specialists against secondary validation through IHS Markit registration data, vehicle production databases, EU REACH substance restriction filings, and SEC disclosures from listed automotive suppliers.
Input-output matrices map electromechanical, piezoelectric, and electrohydraulic technology penetration across powertrain control, chassis management, safety mechanism, HVAC, and body electronics applications, with segmentation by vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster. CAGRs derive from regression analysis of historical content-per-vehicle trajectories and electrification program announcements, with motor-inverter integration adoption curves and EU regulatory compliance timelines as primary forecast inputs across the projection horizon.
Rare-earth export restrictions, EU AI Act certification delays, and REACH substance reformulation bottlenecks are the dominant revision risks. Deviation in neodymium supply security would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive Adaptive Engine Mounts Market
Automotive Parts
Saudi Arabia Vehicle Exhaust Hose Market
Automotive Parts
Automotive Washer System Market
Automotive Parts
Indonesia Automotive Engine Oils Market
Automotive Parts
Germany Automotive Hydraulic Actuators Market
Automotive Parts
Rammer Market
Automotive Parts
Automotive Step Plate Market
Automotive Parts
Automotive Tonneau Market
Automotive Parts
Spare Wheel Carrier Market
Automotive Parts
Global Automotive Motor Oil Market
Automotive Parts
Germany Automotive Parts Die Casting Market
Automotive Parts
Global Auto Parts and Accessories Market
Automotive Parts
Automotive Axle and Propeller Shaft Market
Automotive Parts
Automotive Parts Magnesium Die Casting Market
Automotive Parts
Automotive Engine Cooling System Market
Automotive Parts
Camshaft Lifters Market