
 North America Automotive Actuators Market | 2026-2036
North America Automotive Actuators Market Size, Share, and Industry Trends Forecast 2026-2036
North America Automotive Actuators Market Analytics
The EPA's phased tailpipe emission standards for light-duty vehicles is recalibrating actuator procurement across the supply base. Robert Bosch GmbH leverages its integrated mechatronics platform to dominate electromechanical throttle and exhaust gas recirculation actuator supply. Denso Corporation anchors its position through thermal management actuators engineered for hybrid and battery-electric powertrains. Continental AG competes via brake-by-wire and steer-by-wire actuator systems that eliminate hydraulic fluid circuits entirely.
Automotive actuators are electromechanical or fluid-power devices that convert control signals into precise mechanical motion, typically operating with positional accuracy within micrometers and response times under milliseconds for safety-critical functions such as anti-lock braking and active steering intervention. Their primary purpose is to execute real-time commands from vehicle control modules across powertrain, chassis, and body electronics subsystems. Electric actuators now lead product type demand as automakers retire hydraulic architectures to meet efficiency mandates, while the electric vehicle end-user segment represents the fastest-expanding margin pool due to multi-actuator requirements per battery platform. Within applications, brake systems and steering systems command premium positioning as regulatory bodies mandate advanced driver-assistance compatibility.
The National Highway Traffic Safety Administration enforces Federal Motor Vehicle Safety Standards that dictate actuator reliability thresholds for brake and steering systems, while EPA emission regulations indirectly shape demand by penalizing parasitic losses from belt-driven hydraulic pumps. Transport Canada aligns with U.S. safety harmonization protocols, ensuring cross-border component certification efficiency. Stakeholders must monitor the divergence between NHTSA's proposed automatic emergency braking mandates and state-level zero-emission vehicle rules to anticipate actuator specification shifts.
Market Dynamics
The EPA's phased tailpipe emission standards for light-duty vehicles are recalibrating actuator procurement across the supply base, forcing automakers to retire hydraulic architectures in favor of precision electric alternatives. This regulatory compression is redrawing competitive positioning as suppliers race to eliminate parasitic losses from belt-driven pumps.
Growth Catalysts
- EPA Emission Mandates:Tightened tailpipe standards compel automakers to replace hydraulic components with electric actuators, directly expanding addressable demand for electromechanical throttle and exhaust gas recirculation systems.
- Battery Thermal Management:Electric vehicle manufacturers across the United States and Canada are expanding actuator procurement for multi-zone battery cooling circuits, with each platform requiring 8-12 thermal actuators versus 2-3 in conventional powertrains.
- NHTSA Safety Harmonization:Automatic emergency braking compatibility requirements are mandating redundant brake-by-wire architectures, creating specification pull-through for high-reliability steering and braking actuators.
Market Restraints
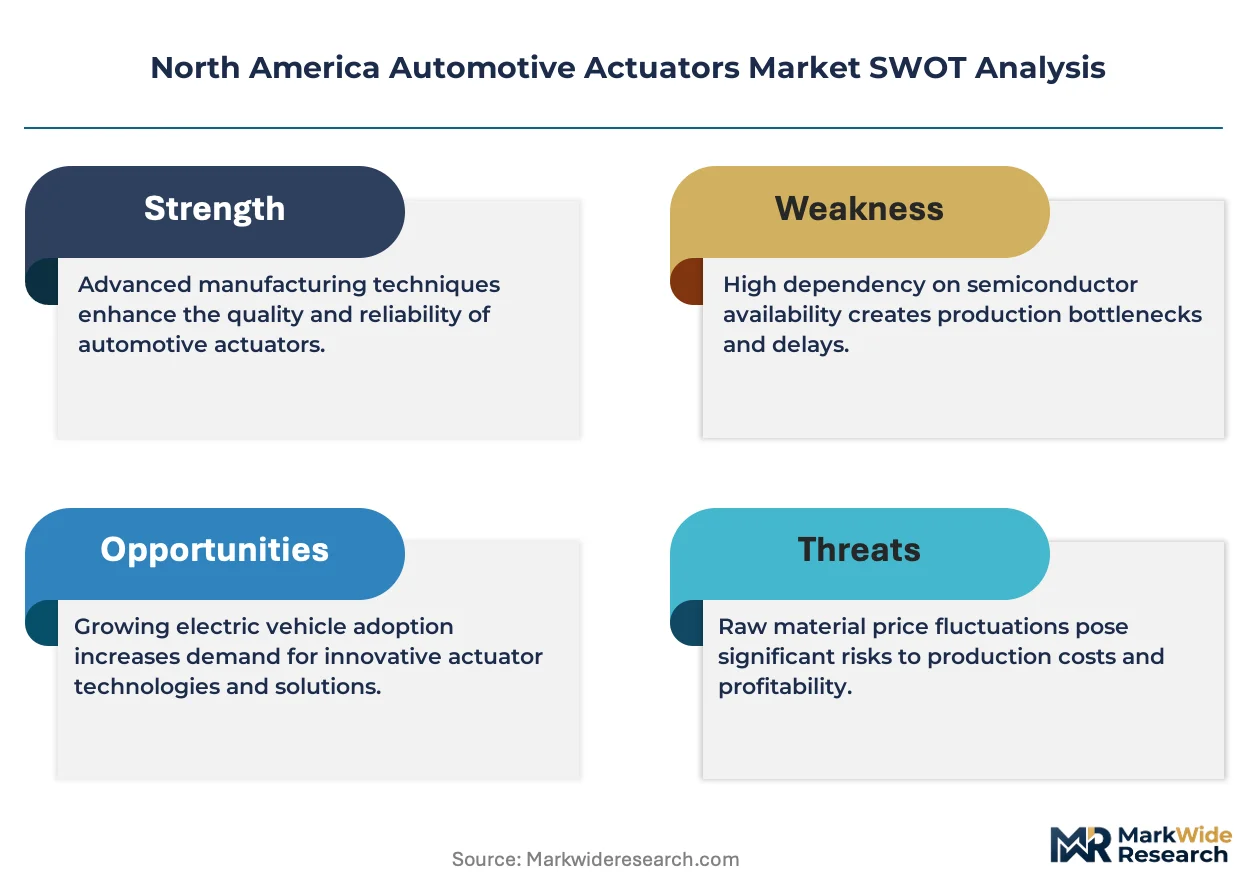
- Rare Earth Magnet Dependency:Neodymium and dysprosium supply concentration in China's processing infrastructure exposes North American actuator manufacturers to input cost volatility and potential export restriction cascades.
- Legacy Hydraulic Fleet Inertia:The installed base of hydraulic steering and braking systems in vehicles aged 8-15 years creates aftermarket replacement demand that competes for capital against electrification investments.
- Cross-Border Certification Friction:Divergence between NHTSA's proposed automatic emergency braking mandates and Transport Canada's implementation timeline forces suppliers to maintain dual validation pathways.
Strategic Opportunities
- California ZEV Assembly Hubs:The state's zero-emission vehicle rules are concentrating EV production in the Central Valley and Bay Area, creating geographic demand density for localized actuator logistics and technical service centers.
- Regenerative Braking Convergence:Integration of brake-by-wire actuators with energy recovery systems is opening specification windows for suppliers capable of delivering torque-vectoring precision within 50-millisecond response thresholds.
- Midwest Manufacturing Corridor:The Michigan-Ohio automotive belt retains dense stamping and machining infrastructure that supports captive actuator component production for OEMs pursuing backward integration into mechatronics assembly.
Industry Challenges
- Mechatronics Talent Scarcity:The intersection of mechanical engineering, embedded software, and motor control expertise required for smart actuator development outpaces North American university pipeline output, particularly in firmware architecture and sensor fusion domains.
- Functional Safety Certification Burden:ISO 26262 ASIL-D validation for brake and steering actuators demands 18-24 month timeline commitments and seven-figure testing investments that compress margin structures for mid-tier suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Automotive Actuators Market |
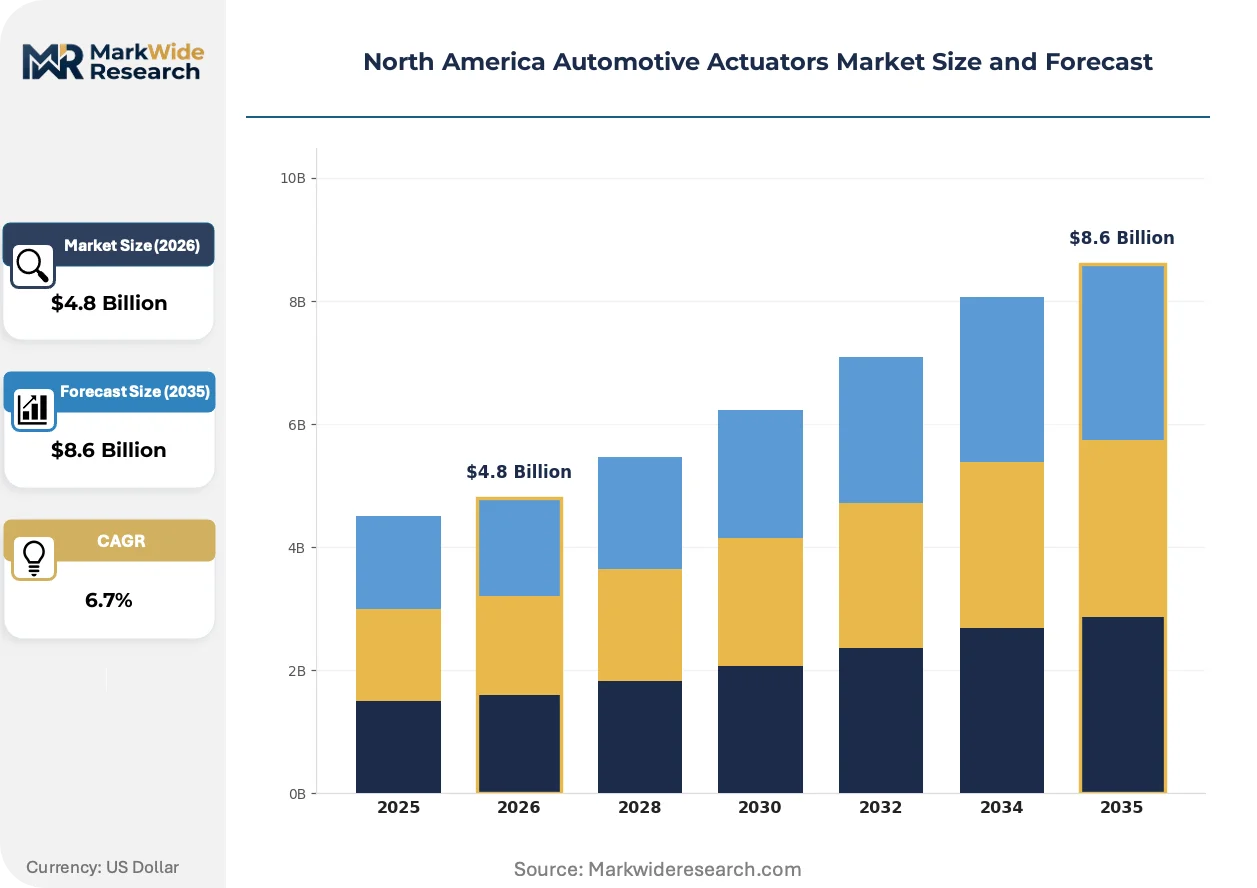
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Actuators, Hydraulic Actuators, Pneumatic Actuators, Mechanical Actuators End User: Passenger Vehicles, Commercial Vehicles, Two-wheelers, Electric Vehicles Application: Steering Systems, Transmission Systems, Brake Systems, Climate Control Systems Technology: Position Control, Flow Control, Pressure Control, Motion Control |
| Companies Covered | Robert Bosch GmbH, Denso Corporation, Continental AG, Johnson Electric Holdings Limited, Nidec Corporation, Mitsubishi Electric Corporation, Aptiv PLC, BorgWarner Inc, ZF Friedrichshafen AG, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Automotive Actuators Market Evolving Landscape
Actuator architectures are converging around integrated mechatronics platforms that embed position sensing, motor control, and diagnostic capability within sealed housing units. This integration is compressing supplier tiers and redrawing procurement specifications.
Brushless DC motor technology with integrated position feedback is rewriting actuator design paradigms across chassis and powertrain applications. Tier 1 suppliers are adopting these compact electromechanical units at accelerating pace for steer-by-wire and active suspension systems. The technology is rewriting cost structures by eliminating separate sensor modules and reducing wiring harness complexity.
NHTSA's automatic emergency braking mandate proposals are forcing brake system architecture decisions before final rule publication. The regulatory uncertainty is accelerating pre-compliant platform development among Detroit Three automakers. The mandate's 2029 implementation target is compressing validation timelines for brake-by-wire actuator suppliers serving the full-size truck segment.
Consolidated procurement contracts are displacing discrete component sourcing as OEMs seek single-supplier accountability for integrated brake or steering modules. Tier 1 integrators are capturing specification authority previously held by actuator specialists. This concentration is most visible in Michigan-Ohio supply chain reconfigurations, where brake system suppliers are acquiring captive actuator production capability.
North America Automotive Actuators Market Segmentation
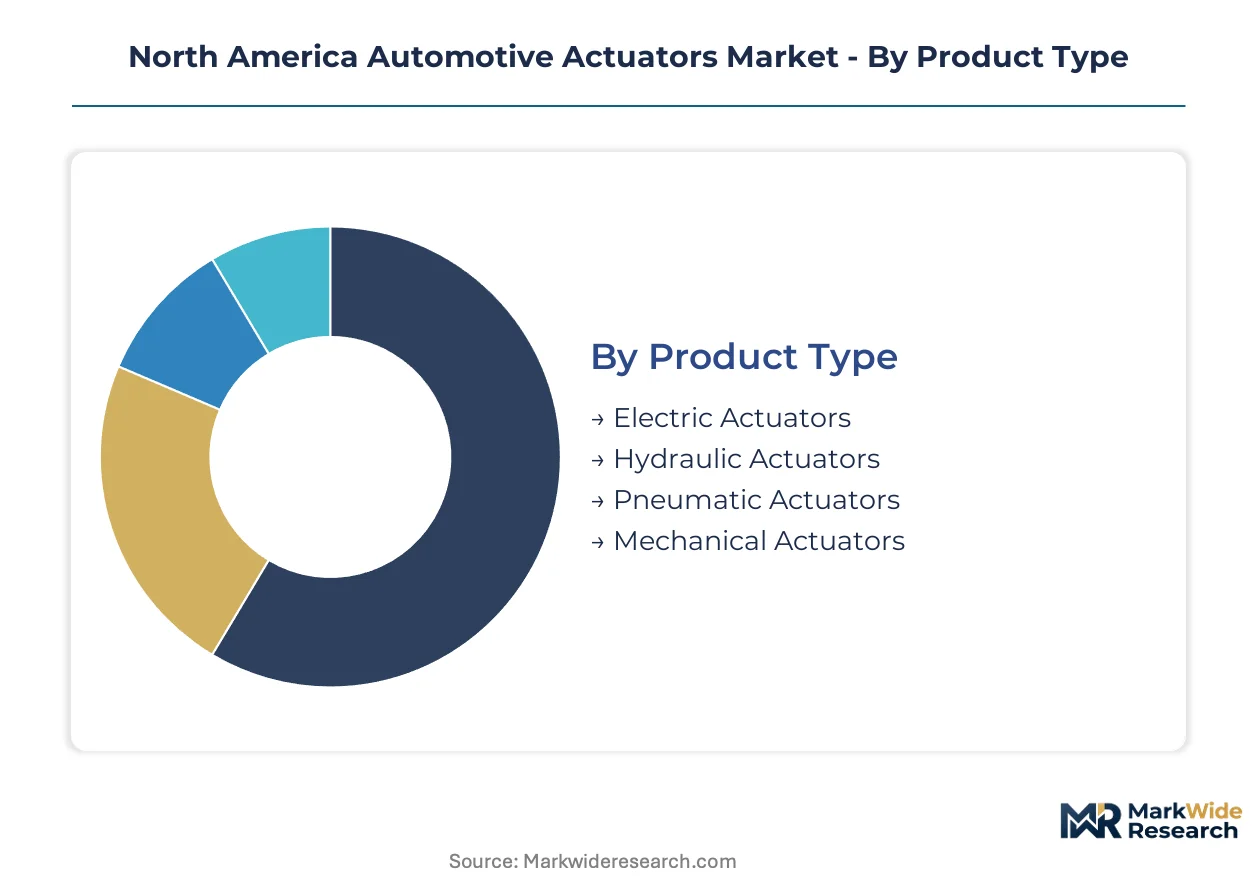
Actuator segmentation in North America reflects divergent certification burdens across powertrain architectures. EPA emission mandates and NHTSA safety standards create asymmetric compliance costs that reshape procurement priorities by product type and end-use application.
Product Type:
ISO 26262 functional safety certification demands scale directly with electrification intensity, placing ASIL-D validation requirements on electric architectures while hydraulic legacy systems face grandfathered compliance pathways.
- Electric Actuators:Brushless DC motor platforms with integrated position sensing and sealed housing designs dominate new platform specifications. Michigan-Ohio corridor OEMs are consolidating procurement around electromechanical throttle and exhaust gas recirculation units to satisfy EPA tailpipe mandates. These actuators eliminate parasitic losses from belt-driven hydraulic pumps.
- Hydraulic Actuators:Fluid-power architectures persist in heavy-duty commercial applications and legacy fleet servicing. California's EV assembly hubs have nearly eliminated hydraulic procurement for new platforms, though aftermarket replacement demand competes for capital against electrification investments in vehicles aged 8-15 years.
- Pneumatic Actuators:Compressed-air systems retain niche positioning in commercial vehicle suspension and auxiliary braking functions where electrical infrastructure weight penalties outweigh efficiency gains.
- Mechanical Actuators:Cable and linkage mechanisms survive in cost-optimized entry segments and certain manual transmission linkages where electronic control cost premiums are prohibitive.
Electric Actuators sits at the top of the volume ranking, with Pneumatic Actuators climbing the fastest as commercial vehicle air suspension adoption expands.
End User:
Customer-type segmentation maps directly to actuator density per platform, with battery-electric architectures requiring 8-12 thermal actuators versus 2-3 in conventional powertrains.
- Passenger Vehicles:Light-duty platforms integrate electromechanical units across steering, braking, and throttle functions. NHTSA automatic emergency braking compatibility requirements are mandating redundant brake-by-wire architectures for this segment.
- Electric Vehicles:Multi-zone battery cooling circuits and regenerative braking convergence create the steepest expansion trajectory. Each EV platform demands precision thermal management actuators for cell-level temperature uniformity.
- Commercial Vehicles:Heavy-duty specifications retain hydraulic persistence in steering and braking where load-bearing capacity exceeds electric actuator torque density.
- Two-wheelers:Compact electromechanical units for throttle and brake functions serve the smallest addressable volume pool in North America, concentrated in urban mobility fleets.
Passenger Vehicles command the revenue concentration, with Electric Vehicles gaining share fastest as California ZEV rules concentrate production in Central Valley and Bay Area assembly hubs.
Application:
Application-tier segmentation aligns with safety-critical classification under Federal Motor Vehicle Safety Standards, elevating brake and steering actuator reliability thresholds above climate and transmission functions.
- Brake Systems:Brake-by-wire architectures with torque-vectoring precision within 50-millisecond response thresholds are opening specification windows for integrated energy recovery systems. NHTSA's proposed mandate is compressing validation timelines for full-size truck suppliers.
- Steering Systems:Steer-by-wire actuators eliminate hydraulic fluid circuits entirely, with redundant motor configurations required for ASIL-D certification. These systems command premium positioning as regulatory bodies mandate advanced driver-assistance compatibility.
- Transmission Systems:Gear selection and clutch actuation functions are transitioning to electromechanical control in dual-clutch and automated manual architectures.
- Climate Control Systems:HVAC flap and valve actuators operate below ASIL-B thresholds, reducing certification burden and enabling cost-optimized sourcing from tier-two suppliers.
Brake Systems anchor the specification authority, with Steering Systems expanding most quickly as Detroit Three automakers accelerate pre-compliant platform development.
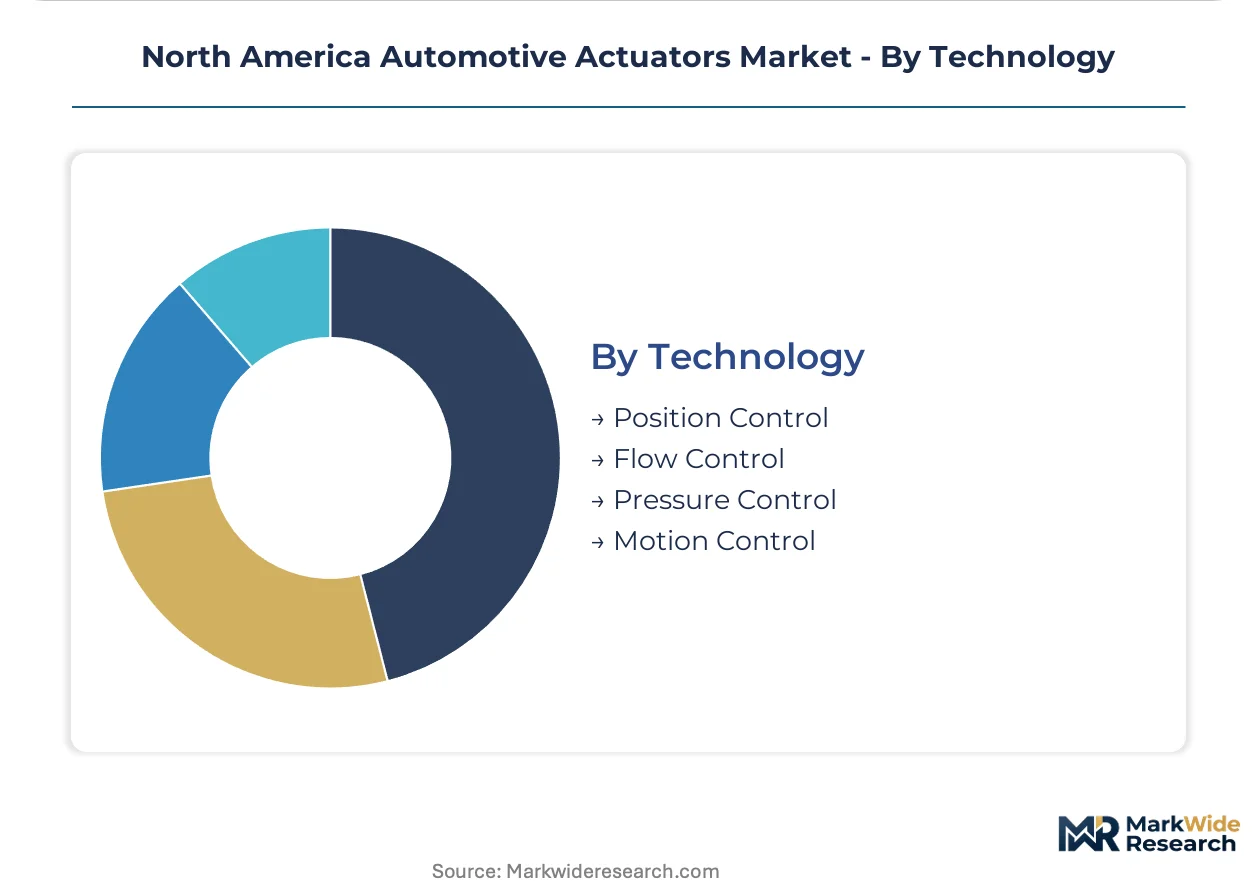
Technology:
Technology segmentation reflects control-loop sophistication, with position and motion control architectures embedding sensor fusion and diagnostic capability within sealed housing units.
- Position Control:Closed-loop feedback systems with micrometer accuracy dominate throttle body and exhaust gas recirculation applications where EPA emission compliance depends on precise valve positioning.
- Motion Control:Trajectory planning algorithms for active suspension and steer-by-wire functions are rewriting cost structures by eliminating separate sensor modules and reducing wiring harness complexity.
- Flow Control:Variable orifice and valve modulation technologies serve thermal management circuits in battery-electric powertrains.
- Pressure Control:Hydraulic pressure modulation retains relevance in anti-lock braking system architectures and certain transmission clutch control functions.
Position Control leads the installed base, with Motion Control climbing the fastest as integrated mechatronics platforms compress supplier tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mechatronics engineering talent concentrates in the Michigan-Ohio automotive corridor and California's EV assembly hubs, anchoring actuator design and validation capacity across North America. EPA emission mandates and NHTSA safety regulations are redrawing procurement geography as suppliers co-locate technical service centers near OEM engineering headquarters.
United States
Detroit Three automakers are consolidating brake-by-wire and steer-by-wire actuator procurement around redundant ASIL-D architectures. NHTSA's proposed automatic emergency braking mandate compresses validation timelines for full-size truck suppliers through 2029. The Michigan-Ohio manufacturing belt retains dense stamping and machining infrastructure that supports captive mechatronics assembly for backward-integrated OEMs.
Canada
Transport Canada aligns with U.S. safety harmonization protocols, ensuring cross-border component certification efficiency for brake and steering actuators. The country's national automotive regulator maintains equivalent reliability thresholds to NHTSA Federal Motor Vehicle Safety Standards. Ontario's Windsor-Toronto corridor hosts technical service centers serving Detroit Three engineering requirements.
Mexico
Expanding EV assembly capacity in Nuevo León and the Bajío Region is pulling actuator logistics networks southward from traditional U.S. border concentrations. The country's national automotive regulatory framework adopts UN ECE technical standards for brake system homologation. Querétaro and Guanajuato industrial parks are attracting thermal management actuator suppliers for battery platform production.
North America Automotive Actuators Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the North America automotive actuators market, with integrated Tier 1 suppliers holding specification authority previously fragmented among component specialists. The supplier base concentrates around three strategic archetypes: diversified mechatronics conglomerates with captive motor production, precision motion specialists focused on position control algorithms, and brake system integrators acquiring in-house actuator manufacturing. Dominant competitive moves include backward integration into rare earth magnet supply chains and strategic partnerships with battery-electric platform architects to secure multi-actuator procurement contracts.
Among diversified mechatronics conglomerates, Robert Bosch GmbH and Denso Corporation exemplify the integrated platform approach, while Continental AG occupies a position within the brake system integrator tier. These German and Japanese-origin suppliers anchor the premium specification segment through captive electromechanical throttle and thermal management actuator production. Their geographic positioning reflects engineering headquarters proximity to Detroit Three and California EV OEM decision centers.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Denso Corporation |
| Continental AG |
| Johnson Electric Holdings Limited |
| Nidec Corporation |
| Mitsubishi Electric Corporation |
| Aptiv PLC |
| BorgWarner Inc |
| ZF Friedrichshafen AG |
| Others |
Value Network & Pricing Analysis
NHTSA's proposed automatic emergency braking mandate is compressing brake-by-wire actuator validation timelines, forcing suppliers to absorb ASIL-D certification costs that stratify pricing across premium reliability tiers and economy-grade alternatives. Tier 1 integrators capture specification authority through bundled module procurement, while discrete actuator specialists face margin compression from consolidated sourcing contracts.
Pricing Analysis
Bundled brake and steering module procurement dominates OEM sourcing patterns, with unbundled discrete actuator supply relegated to aftermarket replacement channels. Three-tier pricing structure across ASIL-D certified, ASIL-B compliant, and non-safety-critical economy levels reflects certification burden differentiation. Cost compression in economy-grade thermal actuators is intensifying because battery-electric platform volumes concentrate procurement leverage with Detroit Three and California EV assemblers. Aftermarket distributors exhibit highest price sensitivity due to legacy hydraulic fleet inertia, while OEM platform engineers prioritize reliability premiums over unit cost.
Supply Chain Analysis
Reverse-logistics flows for remanufactured brake and steering actuators are expanding as Detroit Three OEMs extend certified pre-owned component programs for vehicles aged 8-15 years. Manufacturing concentration centers on Germany, Japan, and Mexico, with Nuevo León assembly hubs pulling thermal actuator production southward from traditional U.S. border infrastructure. Rare earth magnet supply draws from China's processing infrastructure, exposing North American suppliers to neodymium and dysprosium export restriction cascades. Distribution runs through Tier 1 system integrators with captive mechatronics assembly, compressing tier-two component specialists into subordinate supplier roles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EPA tailpipe mandates and NHTSA safety harmonization create successive specification upgrade cycles that expand addressable demand for electric actuator architectures.
For Market Incumbents: Acquire captive rare earth magnet supply chains to secure input cost stability against Chinese export restriction exposure. Backward integration into brushless DC motor production defends margin structure from Tier 1 system integrators consolidating procurement authority. Denso Corporation and Robert Bosch GmbH anchor competitive positioning through integrated mechatronics platforms that eliminate separate sensor module dependencies. For New Entrants and Emerging Players: EV thermal management specialists represent the most penetrable white-space target, with each battery platform requiring 8-12 precision actuators versus 2-3 in conventional powertrains. California's Central Valley and Bay Area assembly hubs concentrate geographic demand density for localized technical service centers. Position control algorithm expertise offers entry pathway through firmware architecture differentiation rather than capital-intensive motor manufacturing. For Investors and Strategic Acquirers: Asymmetric upside sits with precision motion control specialists possessing ISO 26262 ASIL-D certification capability and embedded software architectures for steer-by-wire applications. Five-to-ten year viability hinges on regulatory mandate acceleration rather than cyclical automotive production volumes. Monitor NHTSA automatic emergency braking rule finalization and EPA emission standard phase-in schedules as inflection indicators for brake-by-wire specification pull-through.| Strategic Initiative | Industry Significance |
|---|---|
| ASIL-D Certification Investment | Validates brake and steering actuators for NHTSA automatic emergency braking mandates. |
| Rare Earth Magnet Supply Agreement | Secures neodymium and dysprosium access against Chinese processing infrastructure concentration. |
| Battery Thermal Management Partnership | Captures multi-actuator procurement contracts from California ZEV assembly hub expansion. |
| Steer-by-Wire Platform Integration | Eliminates hydraulic fluid circuits entirely for Detroit Three pre-compliant architecture development. |
| Mexico Manufacturing Footprint Expansion | Positions thermal actuator production adjacent to Nuevo León EV battery platform assembly. |
Research Methodology
Coverage spans the United States, Canada, and Mexico, with primary inputs from each national automotive regulatory jurisdiction combined with secondary validation. Tier 1 supplier procurement directors, OEM platform engineers, aftermarket distributors, and thermal management specialists contributed interview perspectives. Secondary sources include NHTSA Federal Motor Vehicle Safety Standards filings, EPA emission regulation dockets, vehicle production databases, and IHS Markit registration data. Bottom-up actuator unit demand modeling triangulates against top-down powertrain electrification scenario analysis.
Rate-of-change decomposition separates volume growth from value-per-unit expansion across the projection horizon. Segmentation dimensions encompass product type, end-user vehicle class, application safety-criticality, and control-loop technology sophistication. CAGRs derive from regression analysis of historical procurement patterns against regulatory mandate implementation schedules. Industry-specific forecast inputs include battery-electric platform rollout timelines and ASIL-D certification completion rates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to rare earth export restriction cascades and NHTSA mandate implementation delays. Forecasts reflect assumptions regarding regulatory harmonization between Transport Canada and NHTSA protocols. Practitioners should monitor EPA tailpipe standard litigation outcomes and Chinese rare earth processing policy announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Nigeria Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Exhaust Heat Recovery System Market
Automotive Parts
China Automotive Parts Magnesium Die Casting Market
Automotive Parts
Japan Automotive Parts Zinc Die Casting Market
Automotive Parts
Fuel Injection Cleaning Machine Market
Automotive Parts
France Automotive Parts Aluminium Die Casting Market
Automotive Parts
Global Bearing Isolators Market
Automotive Parts
Passenger Car Wiper Blade Market
Automotive Parts
Egypt Automotive Engine Oils Market
Automotive Parts
Two Speed Gearbox Market
Automotive Parts
Industrial V Belt Market
Automotive Parts
Connecting Rods Market
Automotive Parts
Brazil Automotive Parts Magnesium Die Casting Market
Automotive Parts
United States Automotive Parts Die Casting Market
Automotive Parts
Qatar Passenger Vehicles Lubricants Market
Automotive Parts
United States Automotive Glass Market