
 Morocco Automotive Engine Oils Market | 2026-2036
Morocco Automotive Engine Oils Market Size, Share, and Industry Trends Forecast 2026-2036
Morocco Automotive Engine Oils Market Foresight
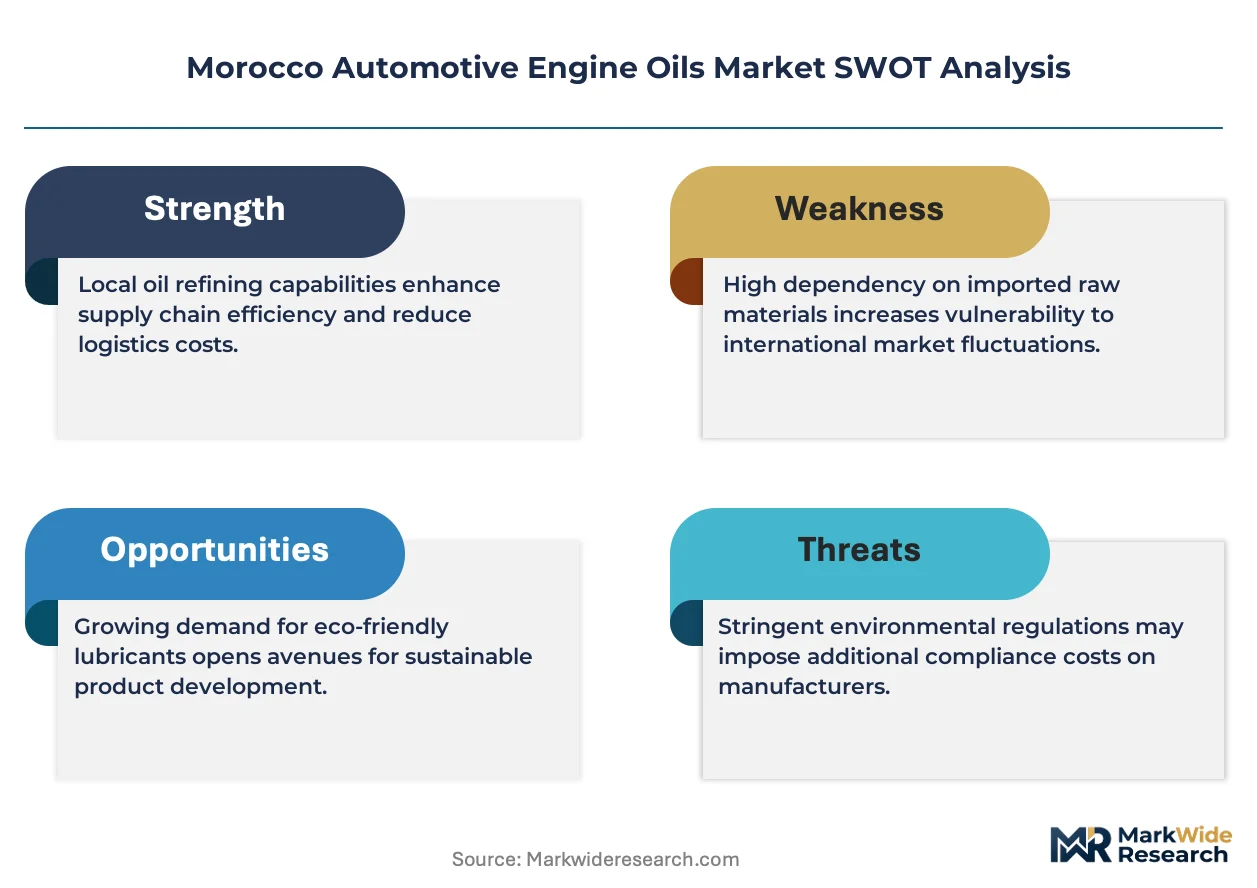
Morocco's alignment with EU Green Deal-inspired carbon benchmarks is restructuring procurement criteria across the automotive value chain. TotalEnergies Morocco leverages its integrated refining network to secure feedstock continuity for high-performance formulations. Afriquia Lubrifiants anchors its position through extensive service station coverage along trans-Maghreb transport corridors. FUCHS Lubricants Morocco differentiates via specialized industrial and automotive blends tailored to severe operating conditions.
Automotive engine oils are formulated lubricants comprising base stocks and additive packages designed to reduce friction, dissipate heat, and prevent wear in internal combustion engines, with viscosity grades such as 5W-30 and 10W-40 specifying flow characteristics across temperature ranges. Synthetic formulations command premium positioning due to extended drain intervals and thermal stability under Morocco's high-ambient-temperature operating environments. Mineral oils retain volume leadership in price-sensitive segments, while semi-synthetic grades capture fleet conversions seeking balanced performance economics. Distribution through service stations dominates the aftermarket, though online platforms are gaining traction among independent workshops in urban centers.
Morocco's Ministry of Industry and Trade enforces technical standards harmonized with European ACEA and API specifications, while the country's environmental regulator applies waste oil recovery mandates that shape reverse logistics obligations for lubricant marketers. BIS-equivalent conformity assessment procedures govern import clearance, creating compliance barriers for non-certified suppliers. Stakeholders must monitor evolving Euro VI-equivalent engine standards and their cascading impact on low-SAPS oil demand.
Market Dynamics
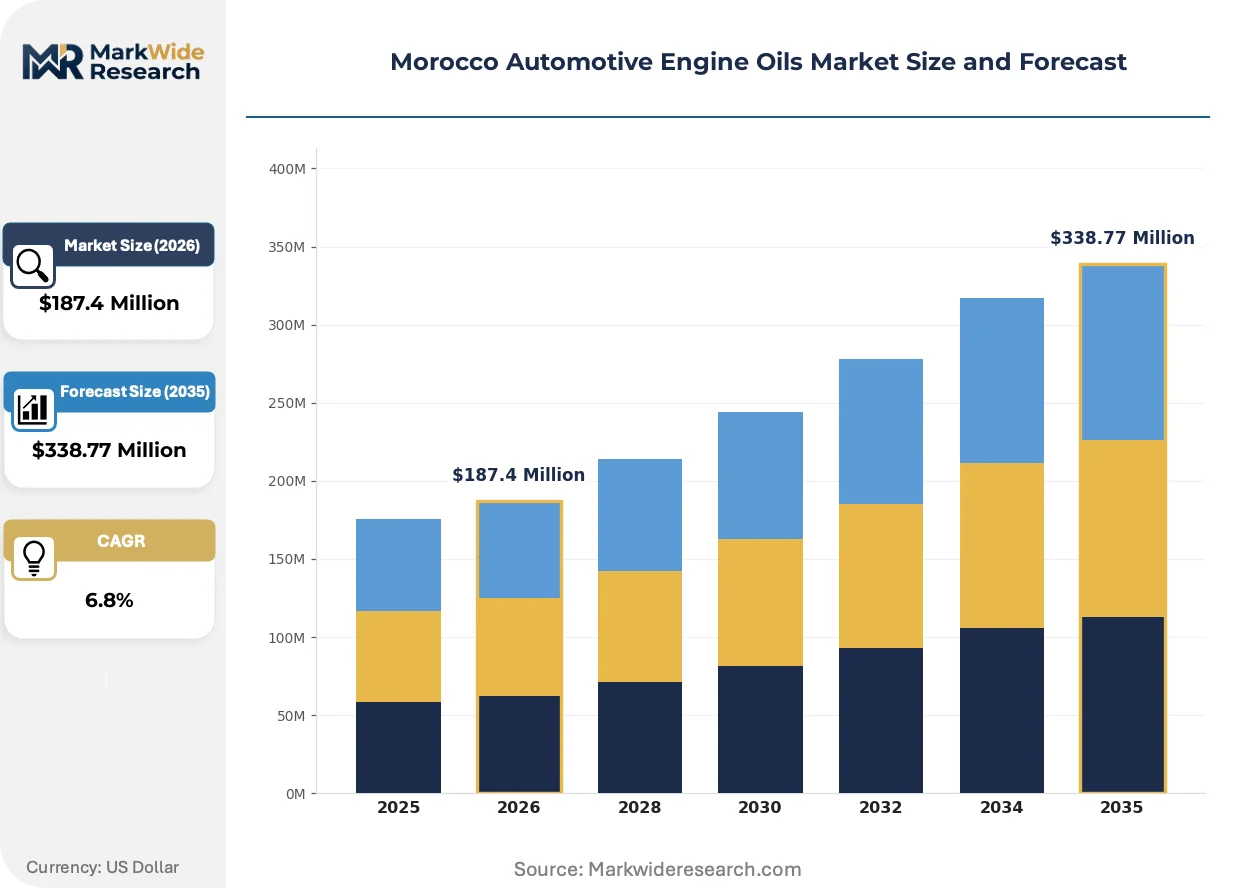
Morocco's automotive engine oils sector is restructuring around Euro VI-equivalent emission mandates and the geographic clustering of vehicle assembly plants. The tension between high-performance synthetic formulations and mineral oil price sensitivity defines competitive positioning.
Growth Catalysts
- Fleet preventive maintenance expansion:Commercial transport operators are extending service intervals across the Casablanca-Settat corridor. This drives demand for extended-drain synthetic formulations.
- Euro-equivalent emission standards:Morocco's Ministry of Industry and Trade is tightening lubricant specifications to align with ACEA C-sequence low-SAPS requirements. OEM fill specifications are cascading into aftermarket demand.
- Tangier-Mediterranean manufacturing concentration:The automotive assembly cluster generates captive demand for factory-fill and service-fill lubricants. Proximity to the Renault-Nissan sourcing ecosystem anchors volume.
Market Restraints
- Base oil supply concentration:Morocco lacks domestic Group II/III base oil production. Refiners depend on imported feedstocks subject to freight and currency volatility.
- Price-sensitive independent workshop segment:Mineral oils retain volume leadership in the aftermarket. Synthetic conversion rates stall where drain interval education is weak.
- BIS-equivalent import certification:Conformity assessment procedures create clearance delays for non-established suppliers. Technical documentation requirements favor incumbents with regulatory affairs capacity.
Strategic Opportunities
- Reverse logistics infrastructure:Morocco's environmental regulator mandates waste oil recovery. First movers in collection-network density secure regulatory goodwill and feedstock for re-refining.
- Online platform penetration:Independent workshops in urban centers are migrating procurement to digital channels. Early platform partnerships bypass traditional distributor markups.
- Industrial lubricant cross-selling:FUCHS Lubricants Morocco demonstrates pathway from automotive to mining and construction fluids. Shared technical service infrastructure dilutes customer acquisition costs.
Industry Challenges
- Technical service talent scarcity:Formulation chemists and application engineers with ACEA/API specification expertise are concentrated among multinational affiliates. Local training pipelines remain underdeveloped.
- Certification timeline compression:Euro VI-equivalent engine introductions are accelerating faster than lubricant qualification cycles. OEM approval delays risk specification mismatches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Morocco Automotive Engine Oils Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Synthetic, Semi-Synthetic, Mineral, Bio-Based Viscosity Grade: 0W-20, 5W-30, 10W-40, 15W-50 Service Type: Preventive Maintenance, Engine Repair, Diagnostic Services, Oil Change Distribution Channel: Retail Stores, Online Platforms, Service Stations, Wholesalers |
| Companies Covered | FUCHS Lubricants Morocco, OLA Energy, TotalEnergies Morocco, Vivo Energy Morocco, Petrom, Afriquia Lubrifiants, Motul Maroc, Ziz Lubrifiants, Shell Morocco, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Morocco Automotive Engine Oils Market Shifts & Advancements
Formulation chemistry and distribution architecture are converging to reshape how lubricants reach Moroccan vehicles. Three distinct vectors are compressing traditional competitive moats.
Additive package technology is modularizing around discrete performance bundles for stop-start, turbocharged, and hybrid powertrains. Moroccan OEM service fill specifications are fragmenting into application-specific SKUs. This is modularizing blender operations toward flexible batch systems that reduce minimum order quantities and inventory carrying costs.
Morocco's Ministry of Industry and Trade is harmonizing technical standards with European ACEA sequences ahead of full Euro VI adoption. Domestic blenders must retest portfolios against updated oxidation and deposit control protocols. The Casablanca-Settat aftermarket is responding fastest, with workshops upgrading to C2/C3 low-SAPS grades for modern diesel fleets.
Fleet procurement is consolidating around annual volume contracts with technical service attachments. Large transport operators in the Tangier-Mediterranean corridor are displacing spot purchases with negotiated supply agreements. This behavior is most visible among refrigerated logistics providers where downtime costs exceed lubricant price differentials.
Morocco Automotive Engine Oils Market Segmentation
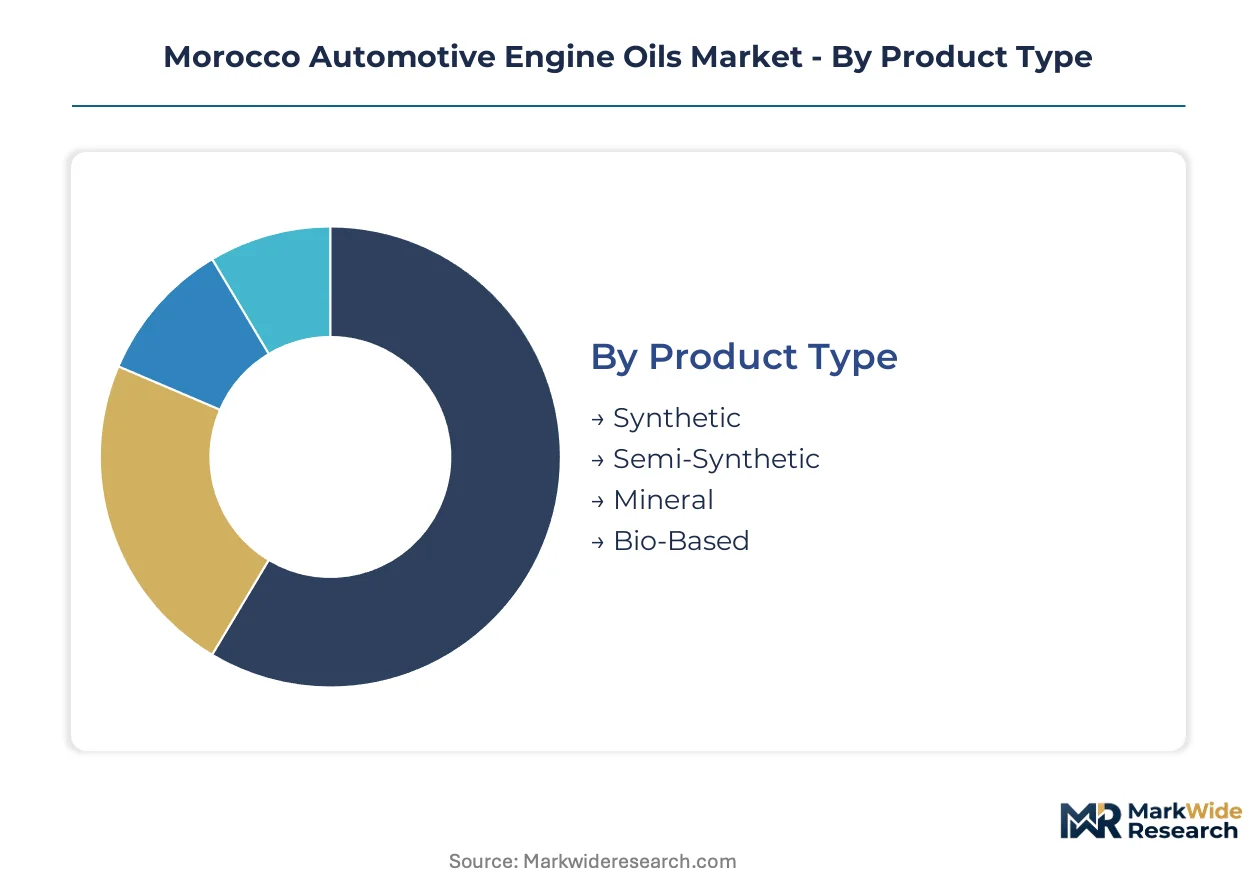
Morocco's automotive engine oils market fragments across formulation chemistry, viscosity specifications, service modalities, and channel architecture. Each segmentation dimension carries distinct margin profiles and regulatory exposure that shape supplier strategy.
Product Type:
Synthetic formulations command premium positioning while mineral oils anchor volume leadership across price-sensitive segments.
- Synthetic:Formulated from Group III/IV base stocks with advanced additive packages delivering extended drain intervals and thermal stability under Morocco's high-ambient-temperature operating environments. Demand concentrates among fleet operators along the Casablanca-Settat corridor where downtime costs exceed lubricant price differentials.
- Mineral:Refined from crude oil distillates with conventional additive treatment, offering lower unit economics for independent workshops and older vehicle parcs. Volume leadership persists in rural service points where drain interval education remains underdeveloped.
- Semi-Synthetic:Blended formulations balancing performance economics for fleet conversions seeking middle-ground solutions.
- Bio-Based:Vegetable-derived base stocks with biodegradable additive systems targeting environmental compliance mandates.
Today's leader: Mineral. Tomorrow's challenger: Synthetic.
Viscosity Grade:
Grade selection tracks engine technology evolution and climate adaptation requirements across Morocco's operating environments.
- 5W-30:Multi-grade formulation optimized for modern gasoline direct injection and light diesel engines, delivering cold-crank protection and high-temperature film strength. Moroccan OEM fill specifications from Renault-Nissan Tangier-Mediterranean operations cascade into aftermarket demand for this grade.
- 10W-40:Workhorse specification dominating commercial transport and older passenger vehicle segments, with thermal shear stability suited to Morocco's ambient temperature extremes. Fleet procurement in the refrigerated logistics sector standardizes on this grade for mixed-age vehicle parcs.
- 0W-20:Ultra-low viscosity grade for hybrid and downsized turbocharged powertrains requiring minimal hydrodynamic friction.
- 15W-50:High-viscosity reserve for severe-duty commercial applications and high-mileage engines with increased bearing clearances.
10W-40 retains volume dominance. 5W-30 gains share fastest as Euro VI-equivalent fleets expand.
Service Type:
Service modality segmentation reflects the shift from reactive breakdown repair to predictive maintenance economics.
- Preventive Maintenance:Scheduled lubricant replacement programs with condition monitoring attachments, capturing fleet operators extending service intervals across commercial transport corridors.
- Oil Change:Standalone rapid-service format dominating independent workshop revenue streams with high-frequency, low-margin transaction economics.
- Engine Repair:Corrective intervention following lubricant-related failures or wear incidents, typically involving flushing and specification upgrade.
- Diagnostic Services:Oil analysis and predictive assessment offerings emerging among premium service providers.
Preventive maintenance climbs the fastest. Oil change retains transaction frequency leadership.
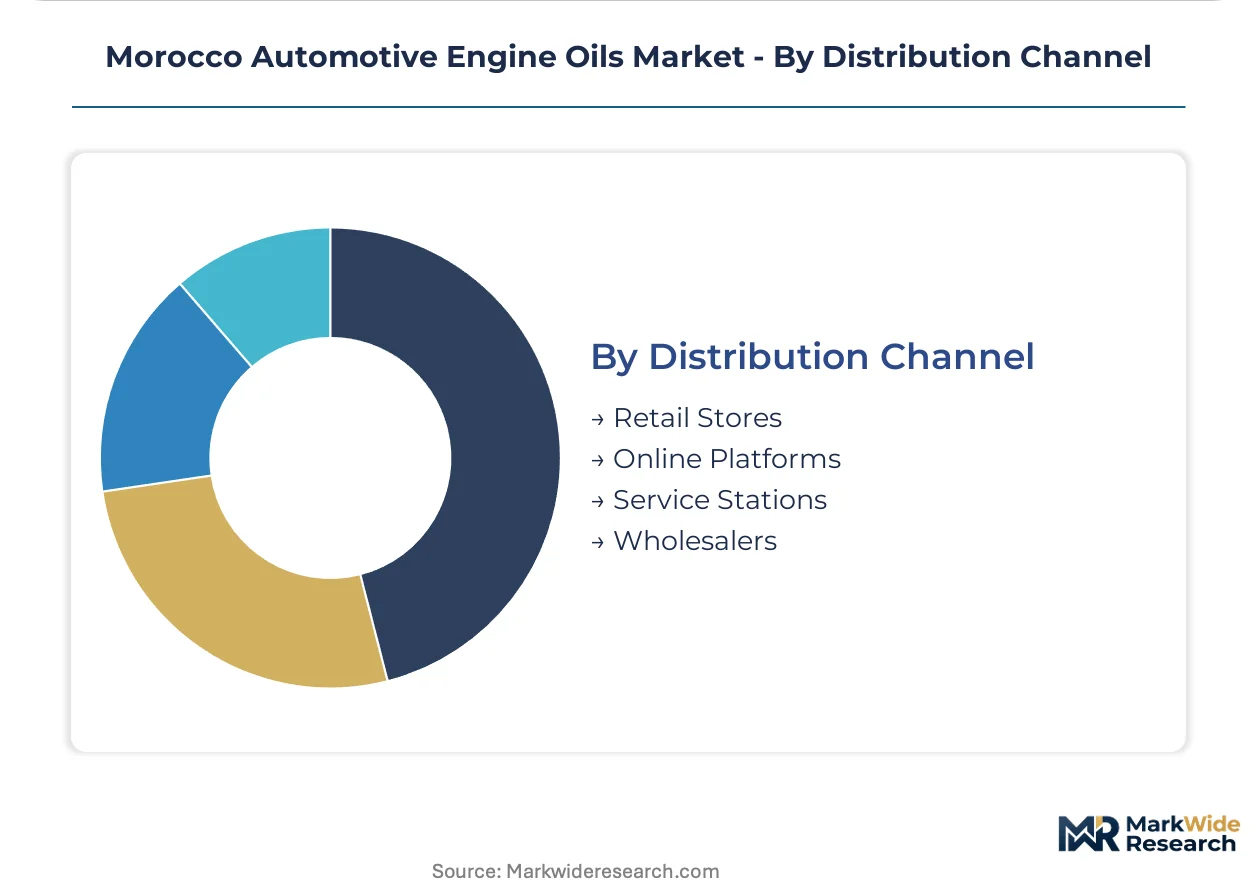
Distribution Channel:
Channel structure determines customer access economics and brand control intensity for lubricant marketers.
- Service Stations:Integrated fuel-and-lube retail network dominating aftermarket volume through convenience positioning and established motorist traffic patterns along trans-Maghreb transport corridors.
- Online Platforms:Digital procurement channels gaining traction among independent workshops in urban centers, bypassing traditional distributor markups through direct-to-garage fulfillment.
- Retail Stores:Automotive parts specialists and hypermarket formats serving DIY maintenance segments and rural markets with limited service infrastructure.
- Wholesalers:Bulk distribution intermediaries supplying workshop networks with volume pricing and extended credit terms.
Service stations anchor current volume. Online platforms represent the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled formulation chemists and application engineers concentrate around Morocco's automotive manufacturing clusters, anchoring technical service capacity in the Casablanca-Settat and Tangier-Mediterranean corridors. This talent distribution shapes regional demand patterns for high-performance lubricant specifications.
Casablanca-Settat
Commercial transport fleet operators dominate lubricant procurement across this corridor, extending preventive maintenance schedules to minimize downtime costs. Morocco's Ministry of Industry and Trade enforces ACEA C-sequence low-SAPS specifications here ahead of full national rollout. The Casablanca industrial zone hosts blending operations serving aftermarket workshops upgrading to synthetic formulations.
Tangier-Mediterranean
Renault-Nissan assembly operations generate captive demand for factory-fill and service-fill lubricants in this northern cluster. The country's environmental regulator applies waste oil recovery mandates that shape reverse logistics infrastructure development. Port-advantaged positioning enables feedstock imports for Group III base oil formulations targeting OEM specifications.
Fès-Meknès
Agricultural equipment and light commercial vehicle parcs sustain mineral oil volume leadership in this central region. Morocco's technical standards harmonization with European ACEA sequences pressures local distributors to upgrade inventory. Urban workshops in Fès are migrating procurement to digital platforms, bypassing traditional wholesaler networks.
Marrakech-Safi
Tourism-related commercial transport and rental fleet operations drive seasonal lubricant demand fluctuations. BIS-equivalent conformity assessment procedures create compliance barriers for non-established suppliers entering this market. The Marrakech automotive service corridor is consolidating around multi-brand preventive maintenance providers.
Oriental
Cross-border trade with Algeria positions this eastern region as a distribution node for bulk lubricant movements. Morocco's waste oil recovery mandates are less enforced here, creating regulatory arbitrage opportunities for informal collectors. The Oujda logistics hub anchors trans-Maghreb transport corridor service points.
Morocco Automotive Engine Oils Market Competitive Landscape
Capital-heavy integrated refiners compete with asset-light blenders and specialized formulators across Morocco's automotive engine oils sector. The market structures around three tiers: multinational affiliates with captive feedstock security, domestic distributors with service station network density, and niche specialists targeting severe-duty applications. Strategic moves concentrate on reverse logistics infrastructure buildout and online platform partnerships that displace traditional distributor markups.
Within the multinational affiliate tier, TotalEnergies Morocco and Shell Morocco anchor positions through integrated refining networks and established fuel retail footprints. Afriquia Lubrifiants exemplifies the domestic network-density archetype with extensive service station coverage along trans-Maghreb corridors. FUCHS Lubricants Morocco occupies the specialized industrial-automotive crossover position, leveraging shared technical service infrastructure across application segments.
| Leading Market Players |
|---|
| FUCHS Lubricants Morocco |
| OLA Energy |
| TotalEnergies Morocco |
| Vivo Energy Morocco |
| Petrom |
| Afriquia Lubrifiants |
| Motul Maroc |
| Ziz Lubrifiants |
| Shell Morocco |
| Others |
Supply & Pricing Matrix
Group II/III base oil import indices from Northwest Europe and the Middle East Gulf cascade directly into Morocco's lubricant pricing tiers, with freight differentials and dirham-euro volatility amplifying spreads between synthetic formulations and mineral blends. This feedstock cost architecture forces blenders to segment offerings across performance tiers that mirror the Casablanca-Settat fleet upgrade cycle.
Pricing Analysis
Bundled technical service contracts versus unbundled product-only transactions define Morocco's pricing architecture. Three-tier pricing structure across premium synthetic, standard semi-synthetic, and economy mineral levels tracks ACEA certification grades and drain interval guarantees. Price differentiation rests on OEM approval status and volume scale commitments from Tangier-Mediterranean assembly operations. Cost compression in the mineral tier is intensifying because independent workshops resist education on total cost of ownership. Fleet operators with refrigerated logistics assets show least price sensitivity; rural service points anchored to older vehicle parcs exhibit highest.
Supply Chain Analysis
Dual-sourcing requirements from TotalEnergies Morocco and Shell Morocco's integrated networks compel independent blenders to qualify multiple Group III feedstock suppliers across Spain, Belgium, and the UAE. Raw material dependencies center on polyalphaolefin base stocks, viscosity index improvers, and detergent-dispersant additive packages. Supply chain risk concentrates in single-source vulnerability for advanced additive systems manufactured in Germany and the Netherlands. Distribution runs through Afriquia Lubrifiants' service station network along trans-Maghreb corridors, with digital platforms emerging as parallel fulfillment channels for Casablanca workshops.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Morocco's automotive engine oils sector functions as a stable compounder anchored by Euro VI-equivalent regulatory ratchets that force continuous specification upgrades across the vehicle parc. This regulatory momentum sustains replacement demand regardless of macroeconomic volatility.
For Market Incumbents: To counter synthetic formulation margin compression from feedstock currency exposure, TotalEnergies Morocco and Shell Morocco should deepen backward integration into additive package blending within the Tangier-Mediterranean free zone. Certification investment in ACEA C3/C2 sequences ahead of full Euro VI enforcement secures OEM fill lock-in. Channel control through exclusive service station partnerships along the Casablanca-Settat corridor defends volume against digital disintermediation.
For New Entrants and Emerging Players: Online platform partnerships with independent workshop aggregators in Fès and Marrakech offer the lowest customer acquisition cost route into Morocco's aftermarket. White-space targets concentrate on bio-based formulations for tourism fleet operators in Marrakech-Safi seeking sustainability credentials, and on re-refined base oil offerings that exploit waste oil recovery mandates. Direct-to-garage fulfillment bypassing traditional wholesaler markups captures price-sensitive conversions from mineral to semi-synthetic grades.
For Investors and Strategic Acquirers: Consolidation pressure builds where technical service talent scarcity and regulatory compliance costs outpace local blender margins. The five-to-ten year viability window favors acquisition of mid-scale blenders with established BIS-equivalent certification capacity and Casablanca-Settat distribution density. The signal to watch is Renault-Nissan Tangier-Mediterranean sourcing policy shifts toward captive lubricant supply agreements that would displace aftermarket volumes.
| Strategic Initiative | Industry Significance |
|---|---|
| Reverse Logistics Network Buildout | Waste oil collection density secures regulatory goodwill and re-refining feedstock for circular economy positioning. |
| ACEA C-Sequence Pre-Certification | Early compliance with Morocco's Ministry of Industry and Trade specifications locks in OEM fill approvals ahead of competitors. |
| Digital Platform Partnership | Direct-to-garage fulfillment partnerships with Casablanca workshop aggregators bypass traditional distributor markups. |
| Additive Package Localization | In-house blending of detergent-dispersant systems reduces dependency on German and Dutch single-source suppliers. |
| Fleet Annual Contract Conversion | Preventive maintenance agreements with refrigerated logistics operators displace spot purchasing with technical service attachments. |
Research Methodology
Bottom-up fleet operator demand modeling reconciled against top-down blender production tracking forms the analytical core of this study. Primary interviews with lubricant procurement managers at commercial transport fleets, blending plant operations directors, and aftermarket workshop owners were validated against secondary sources including Moroccan customs import records, ACEA specification documentation, and Ministry of Industry and Trade regulatory filings. This dual approach triangulates volume estimates across synthetic, semi-synthetic, and mineral formulation tiers.
Input-output matrices mapping base oil feedstock availability to finished lubricant production capacity generate volume and value estimates across the projection horizon. Segmentation dimensions span formulation chemistry, viscosity grade, service modality, and distribution channel, with additional granularity on OEM versus aftermarket demand splits. CAGRs derive from regression analysis against vehicle parc growth, fleet expansion rates, and regulatory specification upgrade timelines. Key forecast inputs include Renault-Nissan Tangier-Mediterranean production schedules and Euro VI-equivalent adoption curves.
The model assumes a particular technology adoption path; alternative pathways for hybrid powertrain penetration or accelerated electric vehicle displacement would alter the outlook for low-viscosity synthetic demand. Deviation in Moroccan Ministry of Industry and Trade regulatory enforcement timelines or base oil import tariff structures would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Center and Drag Link Market
Automotive Parts
Automotive Remanufactured Parts Market
Automotive Parts
Automotive Exhaust Heat Recovery System Market
Automotive Parts
Global Automotive Ignition Market
Automotive Parts
South America Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Electric Parking Brakes Market
Automotive Parts
Automotive Aluminum Parts High Pressure Die Casting (HPDC) Market
Automotive Parts
Electric Brake Booster Market
Automotive Parts
Automotive Step Plate Market
Automotive Parts
Australia Automotive Parts Magnesium Die Casting Market
Automotive Parts
Automotive Parking Heater Market
Automotive Parts
Global Automotive Springs and Damper Market
Automotive Parts
Automotive Windshield Washer System Market
Automotive Parts
Global Automotive Cooler Market
Automotive Parts
Automotive Electric Fuel Pumps Market
Automotive Parts
Cylinder Head Cover Market