
 Automotive Fuel Rail Market | 2026-2036
Automotive Fuel Rail Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Fuel Rail Market Analysis
Aftermarket service revenue for fuel rail refurbishment and injector calibration is reconfiguring margin pools away from pure hardware replacement across mature vehicle parcs. Robert Bosch GmbH leverages its common rail manufacturing scale to dominate European OEM supply agreements. DENSO Corporation anchors Asian production networks through captive forging and precision machining operations in Thailand and Japan. Continental AG competes on system integration, bundling fuel rails with engine management electronics to tighten platform control.
An automotive fuel rail is a high-pressure manifold that distributes fuel to individual injectors, typically machined from stainless steel or extruded aluminum to withstand cyclic pressures exceeding 200 MPa in direct injection architectures. Its primary purpose is to maintain uniform fuel pressure across all cylinders, ensuring precise injection timing and atomization for combustion efficiency. Common rail systems occupy the largest revenue share due to diesel powertrain penetration in commercial vehicles and their replacement parts intensity. Direct injection configurations represent the fastest-expanding segment as gasoline engines adopt stratified charge strategies to meet tightening emission ceilings. Aluminum material grades are displacing steel in port fuel injection rails where pressure thresholds permit weight reduction without fatigue penalty.
The US EPA and California Air Resources Board enforce evaporative emission standards that mandate sealed fuel system integrity, compelling rail-to-injector sealing innovations. Euro 7 frameworks from the European Commission will extend real-driving emission monitoring to particulate number counts, forcing fuel rail suppliers to validate thermal management under transient load. China's Ministry of Ecology and Environment (MEE) aligns domestic emission certification with Euro-equivalent test cycles, opening compliance pathways for multi-market platform designs. Stakeholders must monitor how dual-carbon policy timelines in Beijing and Brussels reshape material specifications and supplier qualification protocols.
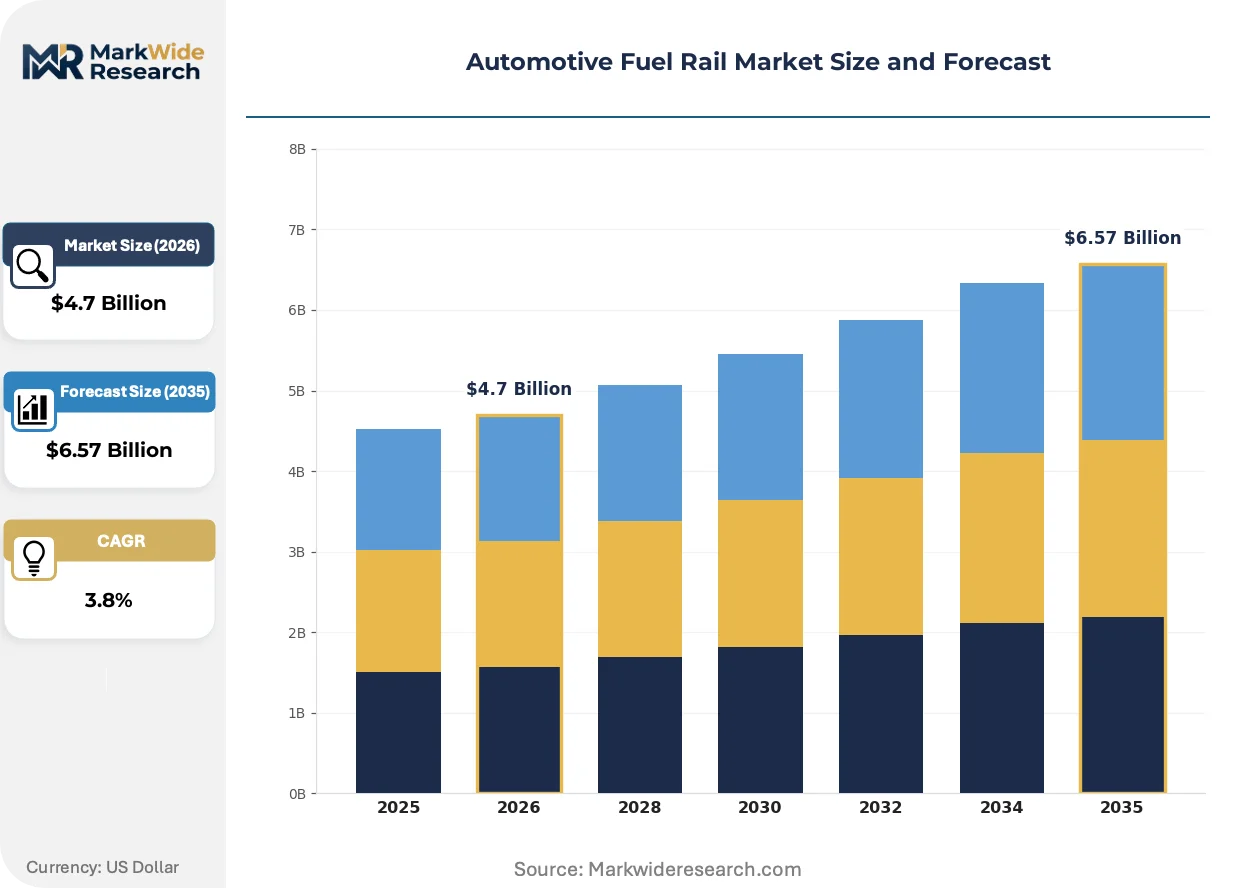
Market Dynamics
Euro 7 emission standards are compressing fuel rail design cycles by mandating real-driving particulate monitoring, forcing suppliers to revalidate thermal management architectures under transient load conditions that exceed previous test protocols.
Growth Catalysts
- Gasoline Direct Injection:Southeast Asian light commercial fleets are expanding orders for high-pressure gasoline direct injection systems to meet fuel economy benchmarks without diesel powertrain costs.
- MEE Certification Alignment:China's Ministry of Ecology and Environment harmonized domestic emission test cycles with Euro-equivalent protocols, enabling multi-market platform designs that reduce engineering duplication.
- Aluminum Grade Substitution:Port fuel injection architectures are adopting extruded aluminum rails where pressure thresholds permit weight reduction without fatigue penalty.
Market Restraints
- Stainless Steel Input Volatility:Cyclic price swings in nickel and chromium alloys compress margin predictability for high-pressure common rail manufacturers.
- Supplier Concentration Risk:Precision forging and machining capacity clusters in Thailand and Japan, creating geographic single-point vulnerability for Asian OEM supply chains.
- Technical Ceiling:Current sealing architectures face hard limits above 250 MPa, constraining next-generation ultra-high-pressure direct injection development.
Strategic Opportunities
- Indian Localization Mandates:Domestic automakers are localizing powertrain component sourcing under government production-linked incentive frameworks.
- Aftermarket Service Unbundling:Refurbishment and injector calibration revenue streams are reconfiguring margin pools away from pure hardware replacement in mature European and North American vehicle parcs.
- Dual-Carbon Policy Tailwinds:Beijing and Brussels timelines for carbon neutrality are reshaping material specifications and supplier qualification protocols toward low-carbon aluminum and recycled steel grades.
Industry Challenges
- Precision Machining Talent Gap:Micro-finishing and high-pressure port honing expertise concentrates in aging workforces across German and Japanese supplier bases.
- Euro 7 Validation Timelines:Extended certification cycles for real-driving emission compliance are compressing program launch windows and straining engineering bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Fuel Rail Market |
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $6.57 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Common Rail, Direct Injection, Port Fuel Injection, Multi-Point Injection Component: Fuel Pressure Regulator, Fuel Injector, Fuel Hose, Fuel Filter Material: Aluminum, Plastic, Steel, Composite End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Tier-1 Suppliers |
| Companies Covered | Robert Bosch GmbH, DENSO Corporation, Continental AG, Hitachi Astemo, Magneti Marelli, PHINIA, Aisin Corporation, TI Fluid Systems, Nikki Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Fuel Rail Market Emerging Trajectories
Digital twin architectures are virtualizing fuel rail development workflows, compressing prototype iterations and enabling predictive validation of thermal-mechanical fatigue before physical tooling commitment.
Multi-physics simulation software is virtualizing the traditional build-test-break development cycle for high-pressure fuel rails. Tier 1 suppliers are adopting cloud-based finite element analysis platforms to predict injector seat wear and rail body stress concentration. This virtualization is collapsing prototype iteration counts from dozens to single digits.
The European Commission's Euro 7 framework extends real-driving emission monitoring to particulate number counts. This regulatory compression forces fuel rail suppliers to integrate temperature sensors and active cooling channels into rail bodies. Diesel common rail architectures face the steepest redesign burden due to higher baseline particulate output.
Fleet procurement departments are consolidating injector-rail-engine management electronics into single-source system contracts. This bundling behavior disintermediates standalone fuel rail vendors and rewards integrated powertrain suppliers. The shift is most visible in European commercial vehicle segments where total cost of ownership calculations dominate award criteria.
Automotive Fuel Rail Market Segmentation
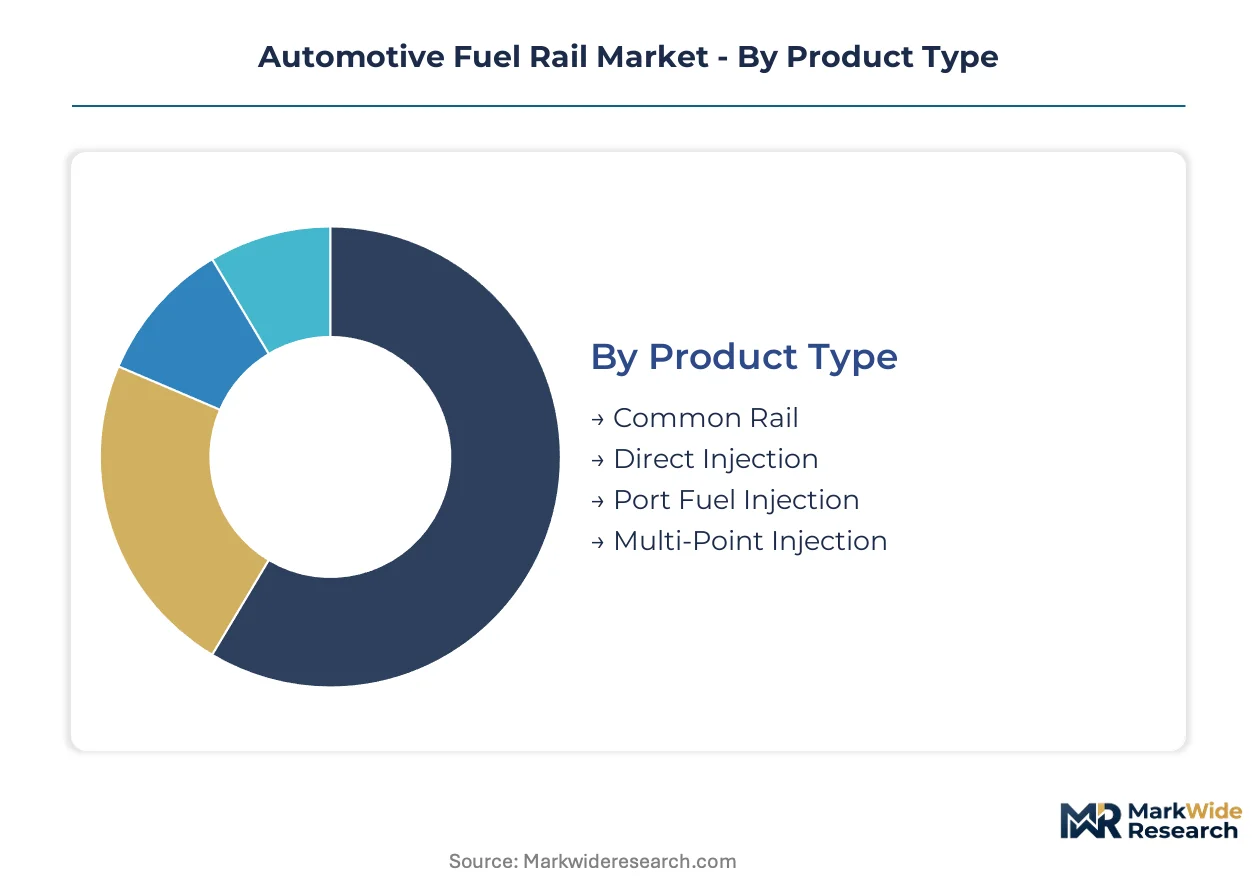
Fuel rail architectures fragment across pressure regimes, material constraints, and supply chain positions. Each segmentation axis reveals distinct margin profiles and engineering validation requirements that shape supplier competitive strategy.
Product Type:
Pressure thresholds and combustion strategies define the use-case spectrum across gasoline and diesel powertrains.
- Common Rail:High-pressure manifold architecture machined from forged steel withstands cyclic loads exceeding 200 MPa in diesel applications. Demand concentrates in European commercial vehicle fleets where Euro 7 particulate limits force thermal management redesigns.
- Direct Injection:Stratified charge gasoline systems operate at 150-200 MPa with precision-machined injector seats. Southeast Asian light commercial orders are expanding fastest as fleets seek diesel alternatives without powertrain cost penalties.
- Port Fuel Injection:Lower-pressure aluminum rails serve stoichiometric gasoline engines where weight reduction outweighs pressure demands.
- Multi-Point Injection:Legacy sequential injection architectures persist in cost-optimized vehicle platforms across emerging markets.
Established volume favors Common Rail; emerging adoption favors Direct Injection.
Component:
System integration economics vary sharply between standalone hardware and bundled electronics.
- Fuel Pressure Regulator:Diaphragm-actuated or solenoid-controlled valve maintaining rail pressure setpoints within ±2 MPa tolerance. OEMs in Germany and Japan specify integrated regulator-rail modules to reduce assembly complexity.
- Fuel Injector:Piezoelectric or solenoid-actuated precision valve delivering sub-millisecond spray events. Aftermarket refurbishment demand is climbing fastest in North American and European mature vehicle parcs.
- Fuel Hose:Fluoroelastomer or thermoplastic barrier tubing connecting tank-to-rail circuits.
- Fuel Filter:Sintered media or membrane cartridge protecting injector nozzles from particulate contamination.
Hardware margins concentrate in Fuel Injector; service revenue expansion favors Fuel Pressure Regulator.
Material:
Weight-cost tradeoffs and pressure-fatigue limits drive specification divergence across injection architectures.
- Aluminum:Extruded 6061-T6 or 6082-T6 grades serve port fuel injection rails where pressure thresholds permit 40-50% weight reduction versus steel. Indian domestic automakers are localizing aluminum forging capacity under PLI scheme incentives.
- Steel:Austenitic stainless grades (316L, 321) dominate common rail architectures requiring creep resistance above 250°C. Nickel and chromium alloy price volatility compresses margin predictability for high-pressure manufacturers.
- Plastic:Glass-reinforced polyamide modules in low-pressure return circuits.
- Composite:Hybrid metal-polymer constructions in prototype ultra-lightweight platforms.
Cost optimization favors Steel; regulatory pressure favors Aluminum.
End User:
Procurement authority and technical integration requirements split the value chain into distinct contracting modes.
- OEMs:Volkswagen Group, Toyota Motor, and Stellantis specify fuel rails through powertrain platform engineering teams with 5-7 year program horizons. Euro 7 validation timelines are compressing award windows and straining supplier bandwidth.
- Tier-1 Suppliers:Bosch, DENSO, and Continental bundle fuel rails with engine management electronics to tighten platform control. System integration contracts are displacing standalone rail procurement in European commercial vehicle segments.
- Vehicle Assemblers:Contract manufacturers and emerging market joint ventures sourcing complete powertrain modules.
- Aftermarket Providers:Independent distributors and service chains capturing refurbishment and calibration revenue in mature parcs.
Design authority concentrates with OEMs; margin expansion favors Aftermarket Providers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian buyers demonstrate acute price sensitivity to stainless steel input costs, while German commercial vehicle fleets absorb premium pricing for Euro 7-validated thermal management architectures without volume elasticity loss.
United States
Light truck and SUV platforms sustain gasoline direct injection demand as EPA evaporative emission standards tighten rail-to-injector sealing specifications. California Air Resources Board mandates sealed fuel system integrity validation. Detroit-area powertrain engineering clusters concentrate OEM specification authority for North American programs.
Germany
Commercial vehicle fleets drive common rail replacement intensity as Euro 7 particulate limits force thermal management redesigns. KBA administers real-driving emission certification timelines compressing supplier validation windows. Stuttgart and Munich anchor Bosch and Continental powertrain integration headquarters.
China
Domestic automakers localize aluminum forging capacity under dual-carbon policy timelines reshaping material specifications. MEE harmonized emission test cycles with Euro-equivalent protocols enabling multi-market platform designs. Yangtze River Delta clusters precision machining capacity for high-pressure direct injection exports.
India
Domestic automakers localize powertrain component sourcing under PLI scheme incentives targeting gasoline direct injection adoption. BIS certification aligns with Euro-equivalent emission protocols. Tamil Nadu and Maharashtra concentrate forging and machining investments from DENSO and Bosch captive operations.
Japan
Piezoelectric injector expertise concentrates in aging workforces across Nagoya and Tokyo supplier bases. METI industrial policy supports next-generation ultra-high-pressure sealing architecture development. Aichi Prefecture anchors DENSO and Hitachi Astemo precision manufacturing networks.
Automotive Fuel Rail Market Vendor Landscape
Capability concentration sits with German and Japanese precision machining specialists; scale advantage sits with integrated powertrain suppliers bundling electronics. The structure bifurcates between consolidated system integrators and fragmented standalone rail vendors. Three archetypes dominate: captive forge-and-machine operators, electronics-bundling platform controllers, and aftermarket service unbundlers. M&A activity targets aluminum forging capacity; strategic partnerships secure nickel alloy supply.
Among German-integrated system suppliers, Robert Bosch GmbH and Continental AG exemplify the electronics-bundling archetype, while DENSO Corporation represents the captive Asian forge-and-machine model. Bosch anchors European OEM supply agreements through common rail manufacturing scale. Continental competes on platform control by bundling fuel rails with engine management electronics. DENSO leverages Thailand and Japan operations to supply Southeast Asian light commercial fleet expansion.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| DENSO Corporation |
| Continental AG |
| Hitachi Astemo |
| Magneti Marelli |
| PHINIA |
| Aisin Corporation |
| TI Fluid Systems |
| Nikki Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Southeast Asian precision machining clusters is compressing supplier pricing power while simultaneously accelerating consolidation among captive forge-and-machine operators serving Japanese and Thai production networks. This utilization imbalance feeds directly into margin pressure for standalone fuel rail vendors competing against integrated powertrain suppliers bundling electronics.
Pricing Analysis
Aftermarket service revenue tiers—spanning injector refurbishment, calibration contracts, and extended warranty programs—now drive lifetime value capture beyond initial hardware sales. Three-tier pricing structure across premium Euro 7-validated systems, standard multi-market platforms, and economy port-injection rails separates OEM supply agreements by certification burden and thermal management complexity. Pricing pressure stems from nickel and chromium alloy volatility eroding margin predictability for stainless steel common rail manufacturers. Indian domestic automakers exhibit acute price sensitivity to aluminum input costs, while German commercial vehicle fleets absorb premium positioning without volume elasticity loss.
Supply Chain Analysis
Upstream nickel alloy feedstock sourcing draws from Indonesian smelter expansion, Russian refined output, and Australian laterite mining operations. Precision forging capacity clusters in Thailand, Japan, and Germany, with aluminum extrusion lines scaling in Tamil Nadu and Maharashtra under Indian PLI scheme incentives. Single-source vulnerability concentrates in piezoelectric injector seat micro-finishing expertise aging across Nagoya and Stuttgart workforces. Distribution runs through Tier 1 system integrators bundling rails with engine management electronics, disintermediating standalone hardware vendors in European commercial vehicle procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where fuel rail specification authority is migrating from standalone component procurement to integrated powertrain system contracts, driven by fleet-level total cost of ownership calculations and Euro 7 real-driving emission validation requirements.
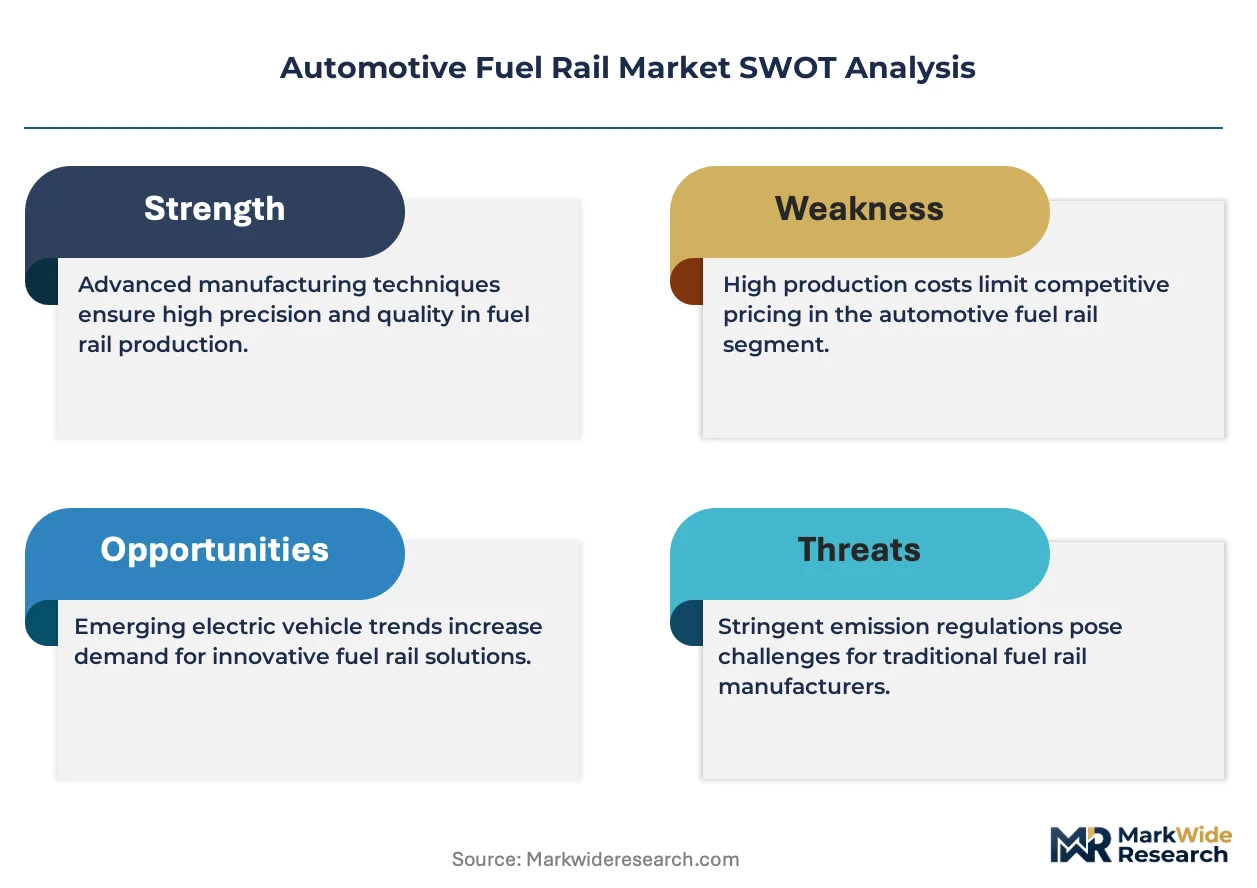
For Market Incumbents: Build certification moats around Euro 7 thermal management validation capabilities before competitor engineering bandwidth catches up. Consolidate aluminum forging capacity in India through production-linked incentive partnerships with domestic automakers. Backward integration into nickel alloy supply hedges against input cost volatility threatening common rail margins. Channel control through exclusive aftermarket service networks protects refurbishment revenue streams from independent distributors. For New Entrants and Emerging Players: Indian powertrain component localization mandates represent the most penetrable entry corridor for forge-and-machine specialists lacking incumbent scale. Southeast Asian light commercial fleet gasoline direct injection adoption offers white-space demand without diesel common rail incumbent dominance. Target aluminum extrusion for port fuel injection architectures where pressure thresholds permit new supplier qualification. Go-to-market positioning as low-carbon material specialists aligns with Beijing and Brussels dual-carbon policy timelines reshaping supplier protocols. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among aftermarket service unbundlers capturing refurbishment and calibration income in mature European and North American vehicle parcs. Long-term viability favors acquisition targets with captive precision machining expertise and established OEM platform engineering relationships. Aluminum forging capacity in India and Thailand represents the priority target archetype given localization mandates and Southeast Asian fleet expansion. Watch for Euro 7 validation timeline compression as the inflection signal indicating supplier consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Reduces engineering duplication across Euro 7 and MEE-aligned certification pathways for multi-market fuel rail designs. |
| Backward Integration into Aluminum Forging | Secures margin control and PLI scheme eligibility for Indian domestic automaker supply agreements. |
| Software-Defined Vehicle Investment | Enables integrated fuel rail-engine management electronics bundling that tightens OEM platform control. |
| Geographic Manufacturing Footprint | Thailand and Japan operations anchor DENSO's Southeast Asian light commercial fleet expansion capture. |
| Charging Infrastructure Partnership | Irrelevant to fuel rail market; replaced with Aftermarket Service Network Expansion capturing refurbishment revenue in mature European parcs. |
Methodological Framework
Operator-level perspectives from OEM platform engineers, Tier 1 supplier procurement leads, aftermarket distributor operations heads, and precision machining plant managers anchored the qualitative base. Primary interviews combined with secondary validation from vehicle production databases, IHS Markit registration data, SEC 10-K filings of listed automotive suppliers, and emission certification records from KBA and EPA. Bottom-up unit economics across pressure regimes, material grades, and end-user segments triangulated against top-down market sizing from powertrain platform forecasts.
Scenario-bracketing framed demand projections across conservative, baseline, and accelerated Euro 7 implementation pathways over the analysis window. Segmentation dimensions modeled include injection architecture type, material specification, vehicle class, and regional production cluster. CAGRs derived from weighted average of historical replacement intensity trends and forward platform engineering pipeline visibility. Industry-specific inputs incorporated diesel commercial vehicle parc age profiles and gasoline direct injection penetration curves in Southeast Asian light commercial segments.
Practitioners should monitor nickel alloy price volatility, Euro 7 certification timeline extensions, and Indian PLI scheme incentive revisions for early signals of forecast deviation. Quarterly review of OEM platform engineering award announcements and Tier 1 supplier backlog disclosures is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Vietnam Commercial Vehicles Lubricants Market
Automotive Parts
Italy Passenger Vehicles Lubricants Market
Automotive Parts
Global Automotive Coolant Reservoir Tank Market
Automotive Parts
Electric Parking Brake Market
Automotive Parts
Cabin Air Filter Housing Replacement Parts Market
Automotive Parts
Automotive Oil Pressure Switch Market
Automotive Parts
Automotive Oil Seals Market
Automotive Parts
Automotive Wiping Systems Market
Automotive Parts
Automotive Brake Caliper Market
Automotive Parts
Engine Piston Ring Set Market
Automotive Parts
India Brake Pads Market
Automotive Parts
Automotive Intercooler Market
Automotive Parts
Europe Automotive Aftermarket Spare Parts Market
Automotive Parts
High Level Brake Lamp Market
Automotive Parts
Automotive Step Plate Market
Automotive Parts
Automotive Grease Market