
 Automotive Windshield Washer System Market | 2026-2036
Automotive Windshield Washer System Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Windshield Washer System Market Analysis
Electromechanical engineering talent scarcity in precision fluid management is redrawing competitive boundaries across the supply base. Robert Bosch GmbH leverages its embedded systems heritage to dominate sensor-integrated washer architectures. Continental AG anchors European OEM relationships through captive development of heated nozzle technologies. Valeo sustains cost leadership in pump module manufacturing across high-volume Asian assembly contracts.
An automotive windshield washer system comprises a reservoir, pump, tubing, nozzles, and control electronics delivering pressurized cleaning fluid to windshields, with operating pressures typically ranging from 45 to 90 psi depending on nozzle configuration and vehicle class. The assembly ensures optical clarity under adverse weather, road debris, and contaminant exposure critical to operator safety and regulatory compliance. Heated systems command premium positioning in cold-climate markets where ice mitigation justifies higher bill-of-material costs, while pump systems retain volume leadership across mass-market OEM platforms. Microcontroller-based fluid management is displacing simple relay controls as automakers integrate washer function into centralized body-domain architectures.
NHTSA Federal Motor Vehicle Safety Standard 104 governs windshield wiping and washing system performance in the United States, mandating minimum field-of-view restoration speeds that drive pump specification and nozzle placement. ECE R43 in Europe and China's GB 9656 standard impose parallel optical clarity and durability requirements that shape regional product differentiation. The EU F-Gas Regulation constrains refrigerant choices in heated washer systems, while EPA VOC limits in North America affect washer fluid formulation and compatible materials. Stakeholders must monitor divergence between cybersecurity-hardened body-domain integration and legacy electromechanical replacement demand as fleet electrification accelerates platform redesign cycles.
Market Dynamics
Centralized body-domain architectures are compressing washer system electronics into consolidated vehicle control modules, forcing pump and nozzle suppliers to embed intelligence at the component level rather than rely on discrete relay logic.
Growth Catalysts
- NHTSA FMVSS 104 mandates:Minimum field-of-view restoration speeds in the United States require higher-pressure pump specifications and precision nozzle placement, pulling advanced fluid management into mainstream vehicle platforms.
- EU pedestrian-safety directives:Enhanced visibility requirements for autonomous emergency braking compatibility are expanding heated washer system penetration in cold-climate European markets.
- Silicon carbide MOSFETs:Wide-bandgap semiconductor adoption in pump motor drives is enabling higher-efficiency electromechanical designs with reduced thermal management overhead.
Market Restraints
- Polypropylene resin volatility:Reservoir and tubing material costs fluctuate with petrochemical feedstock pricing, compressing margin buffers for high-volume pump module manufacturers.
- German electromechanical engineering concentration:Precision fluid management talent scarcity in Baden-Württemberg and Bavaria clusters limits supplier scaling for sensor-integrated architectures.
- EPA VOC formulation limits:North American washer fluid composition restrictions constrain compatible elastomer selections and accelerate material qualification timelines.
Strategic Opportunities
- India PLI scheme for auto components:Production-linked incentives for advanced automotive electronics create localization pathways for microcontroller-based washer control modules serving domestic OEM assembly.
- Camera-lidar fusion cleaning:Convergent sensor protection requirements for Level 2+ ADAS platforms are opening dedicated nozzle architectures beyond traditional windshield applications.
- EU F-Gas Regulation phase-down:Refrigerant constraints in heated washer systems are accelerating resistive heating technology substitution, rewarding suppliers with thermal management IP.
Industry Challenges
- Embedded firmware certification:ISO 26262 functional safety compliance for body-domain-integrated washer controls demands automotive-grade software engineering capacity that outstrips available talent pools.
- Legacy platform coexistence:Electrification-driven platform redesign cycles force suppliers to maintain parallel relay-based and CAN-integrated product lines, fragmenting engineering resources and test infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Windshield Washer System Market |
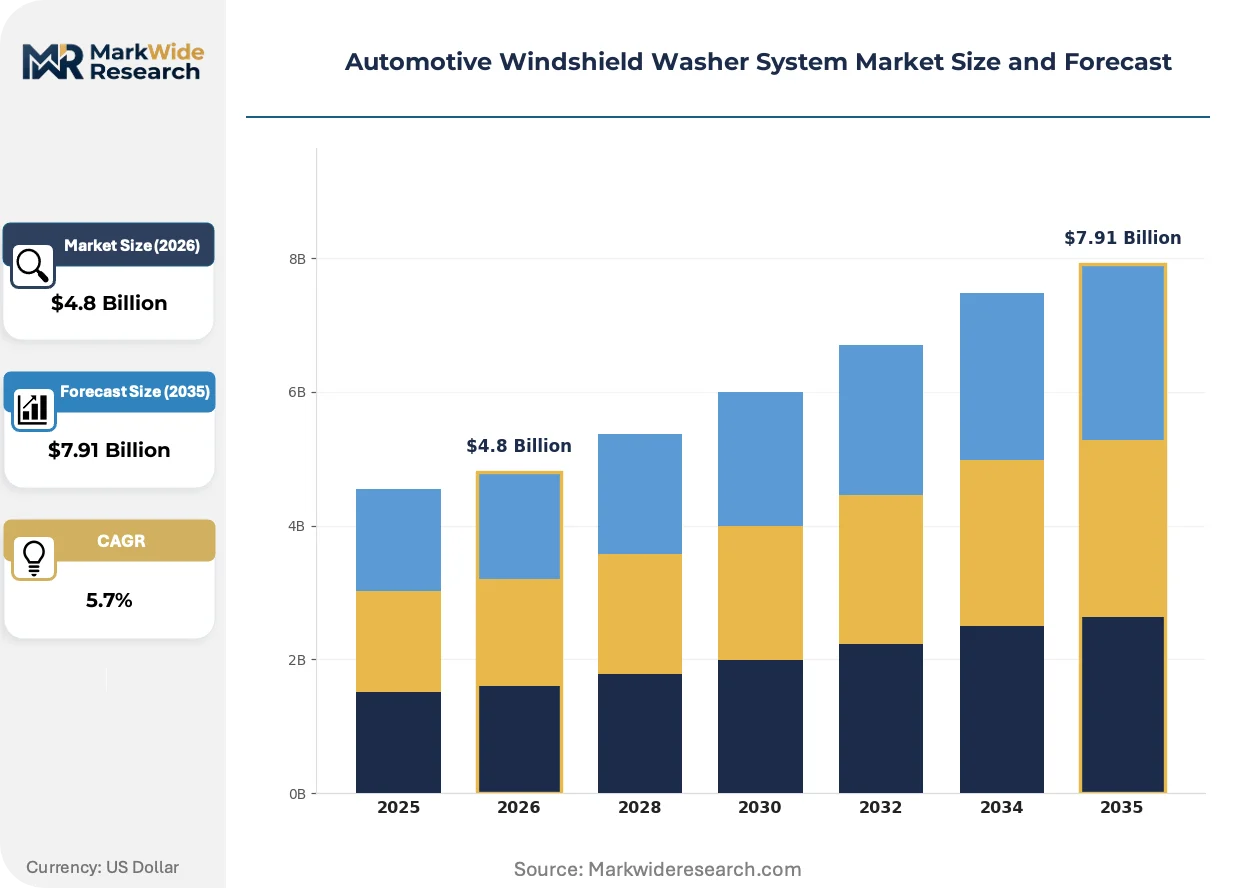
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conventional Systems, Heated Systems, Pump Systems, Electric Systems Technology: Microcontrollers, Sensors, Actuators, Fluid Management End User: OEMs, Aftermarket Brands, Vehicle Assemblers, Component Suppliers Installation: Professional Installation, DIY Kits, Integrated Systems, Modular Systems |
| Companies Covered | DENSO Corporation, Continental AG, HELLA GmbH & Co. KGaA, Robert Bosch GmbH, Valeo, Mitsuba Corporation, dlhBOWLES, DOGA Inc., Trico Products Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Windshield Washer System Market Emerging Trajectories
Electrification and software-defined vehicle architectures are dissolving traditional electromechanical boundaries, repositioning washer systems as sensor-protection subsystems within broader visibility management domains.
Microcontroller-based fluid management is displacing simple relay controls across mass-market and premium OEM platforms alike. Tier 1 suppliers are embedding diagnostic-capable pump drivers with LIN bus connectivity to satisfy centralized body-domain integration requirements. This displacement is compressing the addressable market for discrete electromechanical components while expanding firmware and systems-integration service opportunities.
The EU F-Gas Regulation constrains refrigerant choices in heated washer systems, forcing resistive and PTC heating technology substitution in European OEM specifications. German and French automakers are accelerating supplier qualification for fluorinated-gas-free thermal architectures ahead of 2030 phase-down milestones. Cold-climate markets in Scandinavia and Alpine regions are experiencing the most acute specification pressure as fleet electrification removes engine-waste-heat alternatives.
Fleet operators and leasing companies are consolidating aftermarket procurement through authorized service networks, compressing independent distributor channels for replacement pumps and nozzles. This channel concentration favors suppliers with captive service relationships and diagnostic tool compatibility. North American commercial vehicle fleets and European corporate leasing pools are exhibiting the most pronounced procurement centralization, with multi-year service contracts bundling washer system maintenance into broader visibility package agreements.
Automotive Windshield Washer System Market Segmentation
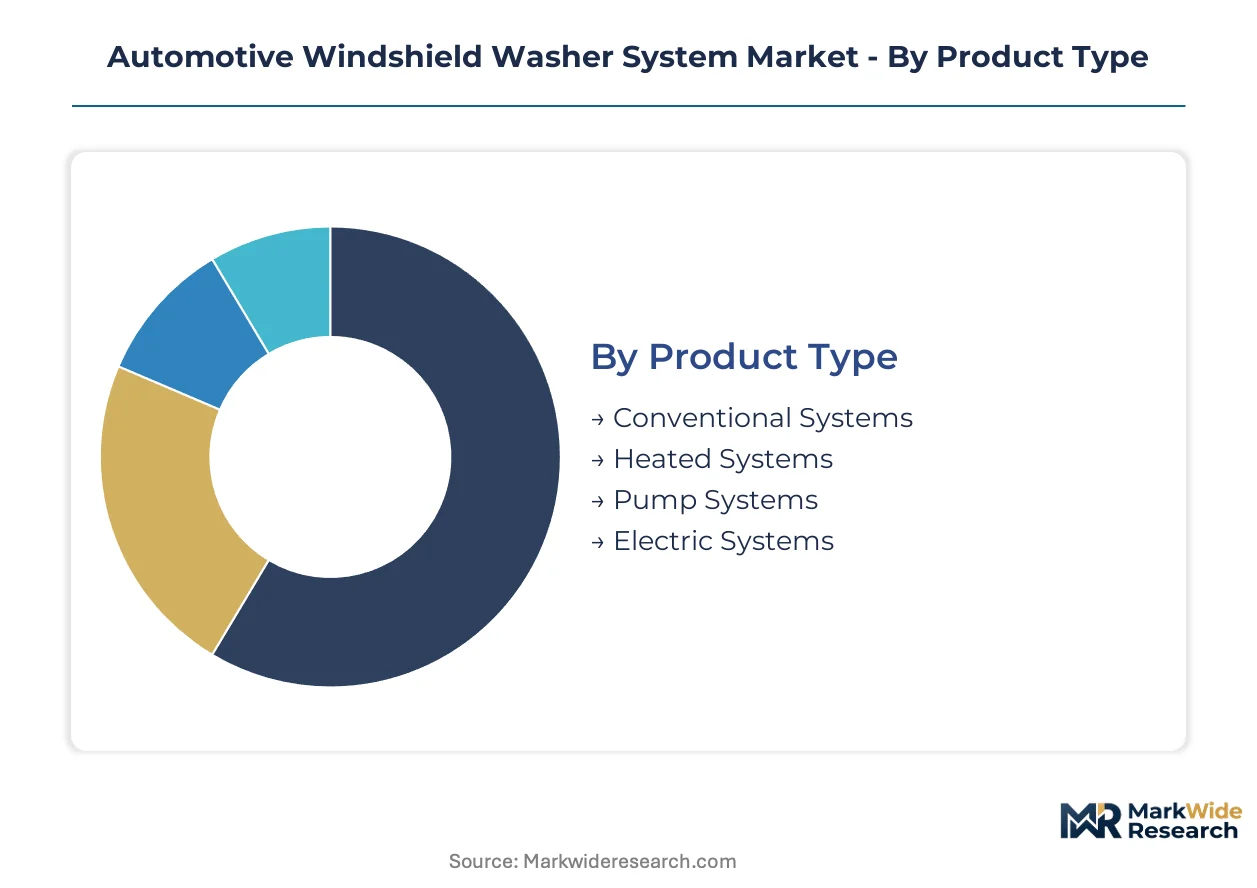
Segmentation in the automotive windshield washer system market reveals how electrification and software-defined architectures are fragmenting traditional electromechanical supply relationships. Suppliers must align portfolio depth against diverging technology roadmaps across OEM body-domain integration strategies.
Product Type:
Heated systems face the most acute substitution pressure as EU F-Gas Regulation phase-downs force refrigerant-free thermal architectures, while conventional pump configurations confront margin compression from microcontroller displacement.
- Conventional Systems:Relay-based pump and nozzle assemblies without integrated diagnostics dominate legacy platform production. Demand concentrates in emerging-market vehicle assembly where cost minimization overrides electrification timelines, though EPA VOC limits constrain compatible fluid formulations.
- Heated Systems:Resistive and PTC heating elements integrated into nozzle or reservoir architectures prevent ice formation in sub-zero operating conditions. Scandinavian and Alpine OEM specifications are driving fastest qualification activity as engine-waste-heat alternatives disappear from electric platforms.
- Pump Systems:Centrifugal and diaphragm pump modules deliver 45-90 psi fluid pressure across vehicle classes.
- Electric Systems:Electronically commutated motor drives with LIN bus connectivity enable body-domain integration.
Conventional systems retain volume leadership; heated systems hold the steepest expansion curve.
Technology:
Cost tier stratification separates diagnostic-capable architectures from commodity electromechanical components, with premium positions commanding firmware development overhead and standard tiers competing on manufacturing scale.
- Microcontrollers:Automotive-grade 8-bit and 16-bit MCUs with LIN/CAN protocol stacks replace discrete relay logic. German and Chinese OEM programs are concentrating demand for ISO 26262 ASIL-B compliant body-domain integration, compressing addressable markets for simple electromechanical suppliers.
- Sensors:Fluid level, temperature, and pressure transducers enable predictive maintenance algorithms. Cold-climate fleets in Canada and northern China are adopting sensor-integrated reservoirs fastest as warranty cost reduction justifies hardware premiums.
- Actuators:Solenoid-driven nozzle positioning motors enable dynamic spray pattern adjustment.
- Fluid Management:Reservoir design and tubing routing optimization for vehicle packaging constraints.
Microcontrollers capture the premium tier; sensors are climbing the fastest as ADAS proliferation extends to camera cleaning applications.
End User:
Application concentration varies sharply between captive OEM supply relationships and fragmented aftermarket channels, with procurement centralization favoring integrated system suppliers over component specialists.
- OEMs:Vehicle manufacturers specify complete washer subsystems for platform integration. Volkswagen, Toyota, and Ford programs in Germany, Japan, and Michigan are consolidating sourcing through Tier 1 system integrators with body-domain architecture experience.
- Aftermarket Brands:Independent distributors and private-label suppliers serve replacement demand. North American commercial fleet operators are compressing this channel through authorized service network consolidation.
- Vehicle Assemblers:Contract manufacturers and regional assembly operations sourcing specified components.
- Component Suppliers:Specialized pump, nozzle, or reservoir manufacturers selling to system integrators.
OEMs retain volume leadership; aftermarket brands face the steepest channel restructuring.
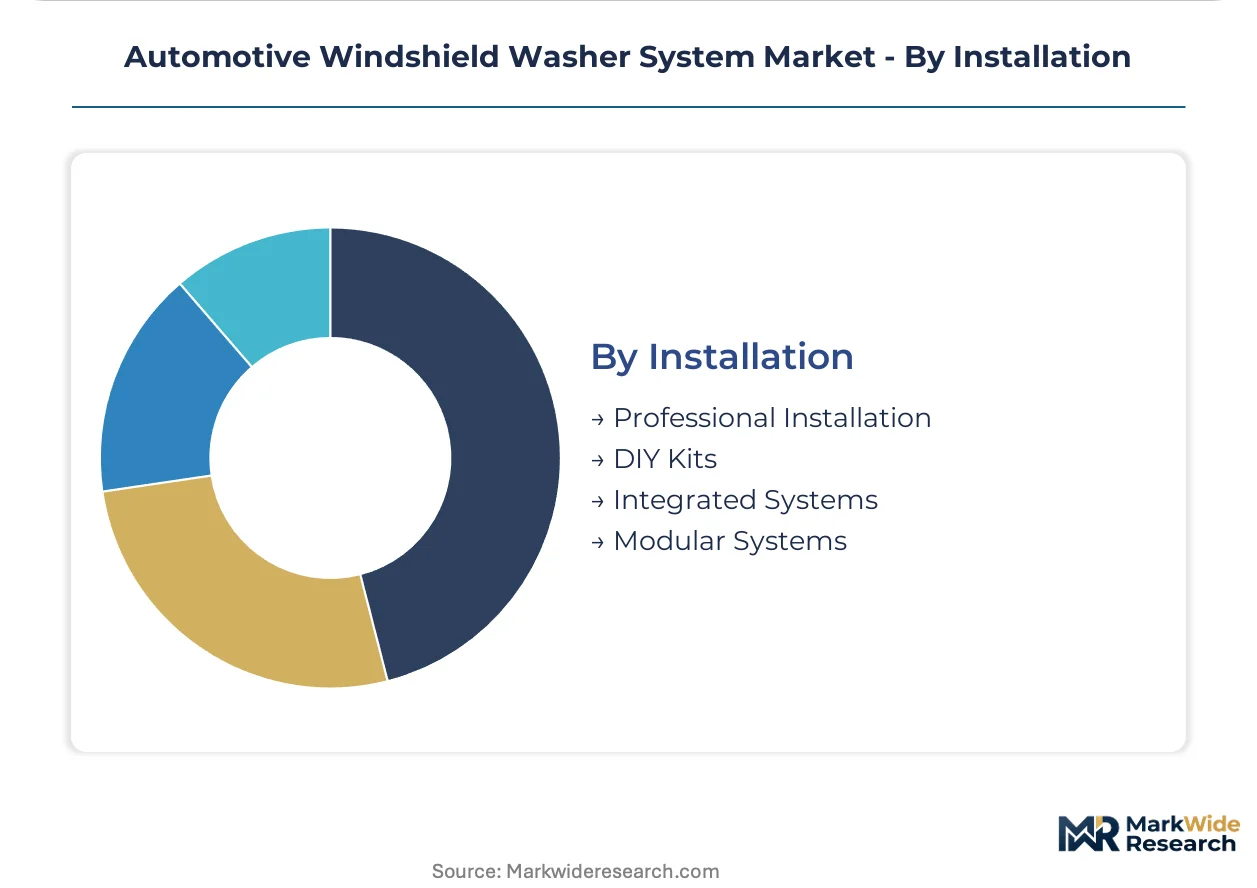
Installation:
Customer type divergence separates factory-integrated production from service-bay retrofit activity, with professional installation commanding system-level warranty responsibility and DIY competing on unit economics.
- Professional Installation:Dealer and authorized service network fitting with diagnostic tool integration. European corporate leasing pools are bundling multi-year maintenance contracts fastest as total-cost-of-ownership optimization displaces transactional parts procurement.
- DIY Kits:Consumer-retail pump and nozzle replacements for legacy vehicle populations. Rural and aging-vehicle markets in the United States sustain demand despite channel consolidation pressure.
- Integrated Systems:Factory-installed complete washer architectures with body-domain connectivity.
- Modular Systems:Field-replaceable pump or nozzle subassemblies without full system replacement.
Professional installation retains volume leadership; integrated systems hold the steepest expansion curve as electrification accelerates platform redesign cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by climate severity and electrification pace. Cold-climate markets prioritize heated nozzle architectures, while tropical and subtropical regions optimize for dust-debris filtration and high-volume fluid delivery. Regulatory stringency separates mature automotive markets from emerging assembly hubs.
United States
NHTSA FMVSS 104 mandates drive specification intensity for pump pressure and nozzle placement across Detroit Three platforms. EPA VOC limits constrain washer fluid formulations, forcing elastomer requalification cycles. Michigan's automotive corridor concentrates Tier 1 system integration activity for North American OEM programs.
Germany
EU pedestrian-safety directives and autonomous braking compatibility requirements accelerate heated system penetration in premium vehicle segments. The EU F-Gas Regulation forces refrigerant-free thermal architectures by 2030 phase-down milestones. Baden-Württemberg and Bavaria clusters face acute electromechanical engineering talent scarcity for precision fluid management development.
China
GB 9656 optical clarity standards shape domestic OEM specifications as EV platform volumes scale. MIIT new energy vehicle mandates remove engine-waste-heat alternatives, forcing resistive heating adoption. Yangtze River Delta assembly plants concentrate demand for microcontroller-integrated pump modules serving BYD and Tesla Shanghai output.
Japan
METI automotive electrification roadmaps compress legacy relay-based system timelines. JIS durability standards maintain rigorous nozzle and reservoir material specifications. Toyota City and Nagoya industrial zones anchor captive supplier development for heated washer architectures on next-generation hybrid platforms.
India
PLI scheme production-linked incentives for advanced automotive electronics create localization pathways for body-domain-integrated washer controls. BIS certification requirements for automotive components extend material qualification timelines. Tamil Nadu and Gujarat assembly corridors concentrate Maruti Suzuki and Hyundai sourcing for cost-optimized pump module contracts.
Automotive Windshield Washer System Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in the supply base. The upper tier commands body-domain architecture relationships and firmware development capacity, while mid-scale fabricators compete on pump module manufacturing scale. Three archetypes dominate: diversified automotive electronics conglomerates with embedded systems heritage, dedicated visibility system specialists with thermal management IP, and regional component fabricators serving cost-sensitive assembly markets. Competitive moves concentrate on strategic partnerships for microcontroller integration and geographic expansion into PLI-subsidized manufacturing zones.
Among diversified automotive electronics conglomerates, Robert Bosch GmbH and Continental AG occupy positions reflecting embedded systems and European OEM relationship depth. Valeo exemplifies the dedicated visibility system specialist archetype with manufacturing scale advantages. DENSO Corporation anchors the Japanese industrial cluster with captive development pathways for hybrid and electric platform integration. These three represent distinct competitive positioning vectors rather than interchangeable substitutability.
| Leading Market Players |
|---|
| DENSO Corporation |
| Continental AG |
| HELLA GmbH & Co. KGaA |
| Robert Bosch GmbH |
| Valeo |
| Mitsuba Corporation |
| dlhBOWLES |
| DOGA Inc. |
| Trico Products Corporation |
| Others |
Supply Flow & Price Mechanics
ISO 26262 functional safety certification gates both supplier qualification and price differentiation across microcontroller-integrated washer architectures, compressing margins for uncertified component vendors while rewarding firmware-capable Tier 1s with premium positioning.
Pricing Analysis
Long-term offtake contracts dominate OEM supply relationships, with annual volume commitments securing preferential unit economics against spot-market component procurement. Pricing stratifies across ASIL-B certified body-domain integration, standard LIN-bus diagnostic tiers, and legacy relay-based commodity modules. Cost compression in conventional pump assemblies intensifies as microcontroller displacement accelerates through German and Chinese OEM programs. Aftermarket distributors exhibit highest price sensitivity, while integrated system suppliers to Volkswagen and Toyota platforms command lowest elasticity through captive development relationships.
Supply Chain Analysis
Inventory buffers and qualification lead times stretch longest for automotive-grade microcontrollers sourced from Taiwan and South Korea, compressing production scheduling flexibility for European pump module integrators. Polypropylene resin for reservoirs and tubing draws from petrochemical feedstock networks centered on Germany, China, and the United States. Single-source vulnerability concentrates in precision fluid management talent clusters across Baden-Württemberg. Distribution runs through Tier 1 system integrators with direct OEM platform engineering access, bypassing independent component channels for new vehicle production.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive windshield washer systems sit in early-cycle expansion as Level 2+ ADAS penetration forces dedicated camera-lidar cleaning nozzle architectures beyond traditional windshield applications.
For Market Incumbents: Fortify body-domain integration capabilities through captive firmware development capacity, securing ISO 26262 ASIL-B certification ahead of German OEM consolidation timelines. Deepen backward integration into heated nozzle thermal architectures as EU F-Gas phase-downs eliminate refrigerant-dependent competitors. Prioritize service network diagnostic tool compatibility to capture fleet operator procurement centralization in North America and Europe. For New Entrants and Emerging Players: BIS certification fast-tracks for India PLI scheme localization create viable entry pathways serving Maruti Suzuki and Hyundai assembly in Tamil Nadu and Gujarat corridors. Target microcontroller-based pump control modules for domestic OEM programs where precision fluid management talent scarcity limits incumbent scaling. Pursue camera cleaning nozzle development partnerships with ADAS sensor fusion suppliers as the most penetrable white-space beyond saturated windshield applications. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across heated system thermal management as resistive and PTC technology substitution demands specialized IP portfolios. Five-to-ten year viability favors acquisition of dedicated visibility system specialists with captive European OEM relationships and refrigerant-free heating architectures. Monitor EU F-Gas Regulation enforcement acceleration as the primary inflection signal for heated system supplier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Reduces engineering overhead across Volkswagen MEB and Toyota e-TNGA electric architectures. |
| Software-Defined Vehicle Investment | Enables LIN-bus pump integration into centralized body-domain controllers at BYD and Tesla Shanghai. |
| Geographic Manufacturing Footprint | Captures India PLI scheme subsidies for microcontroller-based washer controls serving domestic OEM assembly. |
| Backward Integration into Thermal IP | Secures resistive heating technology advantage as EU F-Gas phase-downs eliminate refrigerant competitors. |
| ADAS Sensor Cleaning Partnership | Opens dedicated nozzle architectures for camera-lidar fusion systems on Level 2+ platforms. |
Methodological Framework
Initial hypotheses were tested against primary input from Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and heated system thermal specialists, then refined through secondary validation across vehicle production databases, IHS Markit registration data, NHTSA FMVSS 104 regulatory filings, and EU F-Gas Regulation implementation reports. Bottom-up pump module shipment estimates triangulated against top-down OEM platform content analysis.
Variance decomposition across vehicle class, propulsion architecture, and regional production clusters shaped the analytical framework over the projection horizon. CAGRs derived from segment-level volume trajectories weighted by content-per-vehicle assumptions for heated versus conventional configurations. Forecast inputs incorporated MIIT new energy vehicle mandate timelines and EPA VOC formulation constraint evolution.
The analysis sits within stated boundaries; outcomes outside sustained electrification investment levels or accelerated EU refrigerant phase-down schedules would require recalibration. Forecasts reflect documented assumptions regarding platform redesign cycle timing and body-domain integration adoption curves. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
India Automotive Parts Aluminum Die Casting Market
Automotive Parts
Industrial Gearbox and Gear Motors Market
Automotive Parts
Industrial Shock Absorbers Market
Automotive Parts
Italy Passenger Vehicles Lubricants Market
Automotive Parts
Clutch Pedal Kit Market
Automotive Parts
Automotive Engine Cam Cover Market
Automotive Parts
Full Synthetic Motor Oil Market
Automotive Parts
Connecting Rods Market
Automotive Parts
United States Automotive Parts Die Casting Market
Automotive Parts
Global Automotive Brake Hose Market
Automotive Parts
Fluid Couplings Market
Automotive Parts
Automotive Suspension System Market
Automotive Parts
UK Automotive Parts Magnesium Die Casting Market
Automotive Parts
Automotive Metal Wheel Market
Automotive Parts
Automotive Coolant Pump Market
Automotive Parts
Global Inductive Loop Vehicle Detector Market