
 Electromagnetic Clutch System Market | 2026-2036
Electromagnetic Clutch System Market Size, Share, and Industry Trends Forecast 2026-2036
Electromagnetic Clutch System Market Analysis
German automotive component suppliers is repositioning electromagnetic clutch production toward electromechanical architectures for hybrid vehicle transmission systems. Ogura Industrial Corp leverages its manufacturing scale in precision magnetic field clutches for industrial automation across East Asian markets. Mitsubishi Electric anchors its clutch portfolio in power transfer applications for factory automation, competing with Altra Industrial Motion's specialized offerings in marine and aerospace drive systems.
An electromagnetic clutch system transmits mechanical torque through magnetic flux engagement between a field coil and rotating armature, typically operating at engagement speeds up to 6,000 RPM with response times under 50 milliseconds for automated machinery cycles. The device enables precise start-stop control in power transmission without mechanical linkage wear, serving critical functions in robotic positioning equipment and vehicle drivetrain modules. Multi-plate configurations dominate automotive transmission applications where compact axial packaging and high heat dissipation capacity command premium positioning, while single-plate designs sustain volume leadership in general industrial machinery due to lower unit costs and standardized maintenance protocols. Magnetic field technology leads the technology segmentation with mature supply chains, though electromechanical variants are gaining traction in aerospace automated systems requiring redundant fail-safe disengagement.
EPA tailpipe emissions standards and NHTSA fuel economy mandates in the United States compel automakers to specify electromagnetic clutch systems that reduce parasitic losses in engine-driven accessories. Japan's METI energy efficiency directives and JIS standards for industrial machinery safety shape product certification requirements for clutch manufacturers targeting precision equipment OEMs. China's MIIT dual carbon goals and GB standards for motor system efficiency are tightening market access for imported clutch assemblies that fail domestic energy consumption benchmarks. Stakeholders must monitor evolving electromagnetic compatibility regulations across major manufacturing jurisdictions as clutch system integration with variable-frequency drives becomes standard in next-generation automated production lines.
Market Dynamics
Hybrid drivetrain integration is compressing clutch system specifications toward electromechanical architectures that eliminate parasitic losses while maintaining torque density in compact axial envelopes.
Growth Catalysts
- EPA Tailpipe Standards:NHTSA fuel economy mandates compel US automakers to specify electromagnetic clutches for engine-driven accessories, reducing mechanical drag losses in accessory drive systems.
- East Asian Manufacturing Corridor:China's eastern seaboard automation equipment builders specify locally produced electromechanical clutch assemblies for robotics and CNC machinery integration.
- EU Green Deal Industrial Decarbonization:Mandates accelerate replacement of mechanical clutch systems with precision electromagnetic alternatives in German automotive component supply chains.
Market Restraints
- Rare Earth Magnet Cost Volatility:Neodymium and dysprosium price swings destabilize field coil production economics for high-torque multi-plate configurations.
- Supply Concentration Risk:Precision magnetic field clutch manufacturing clusters in Japan and Germany create single-source vulnerability for automotive OEM qualification timelines.
- Technical Limitation:Heat dissipation constraints above 6,000 RPM engagement speeds restrict adoption in high-performance aerospace turbine applications.
Strategic Opportunities
- Underpenetrated Robotics Segment:Collaborative robot arm manufacturers in South Korea seek compact electromagnetic clutch modules for force-limited joint actuation.
- Technology Convergence:Integration of variable-frequency drives with electromagnetic clutch controllers enables synchronized start-stop cycles in next-generation automated production lines.
- India PLI Scheme:Production-linked incentives for advanced automotive components attract clutch system localization for domestic hybrid vehicle programs.
Industry Challenges
- Electromagnetic Compatibility Certification:GB standards for motor system efficiency in China extend approval timelines for imported clutch assemblies failing domestic energy consumption benchmarks.
- Legacy System Integration Complexity:Retrofitting electromagnetic clutches into existing mechanical power transmission architectures requires custom adapter engineering and extended validation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electromagnetic Clutch System Market |
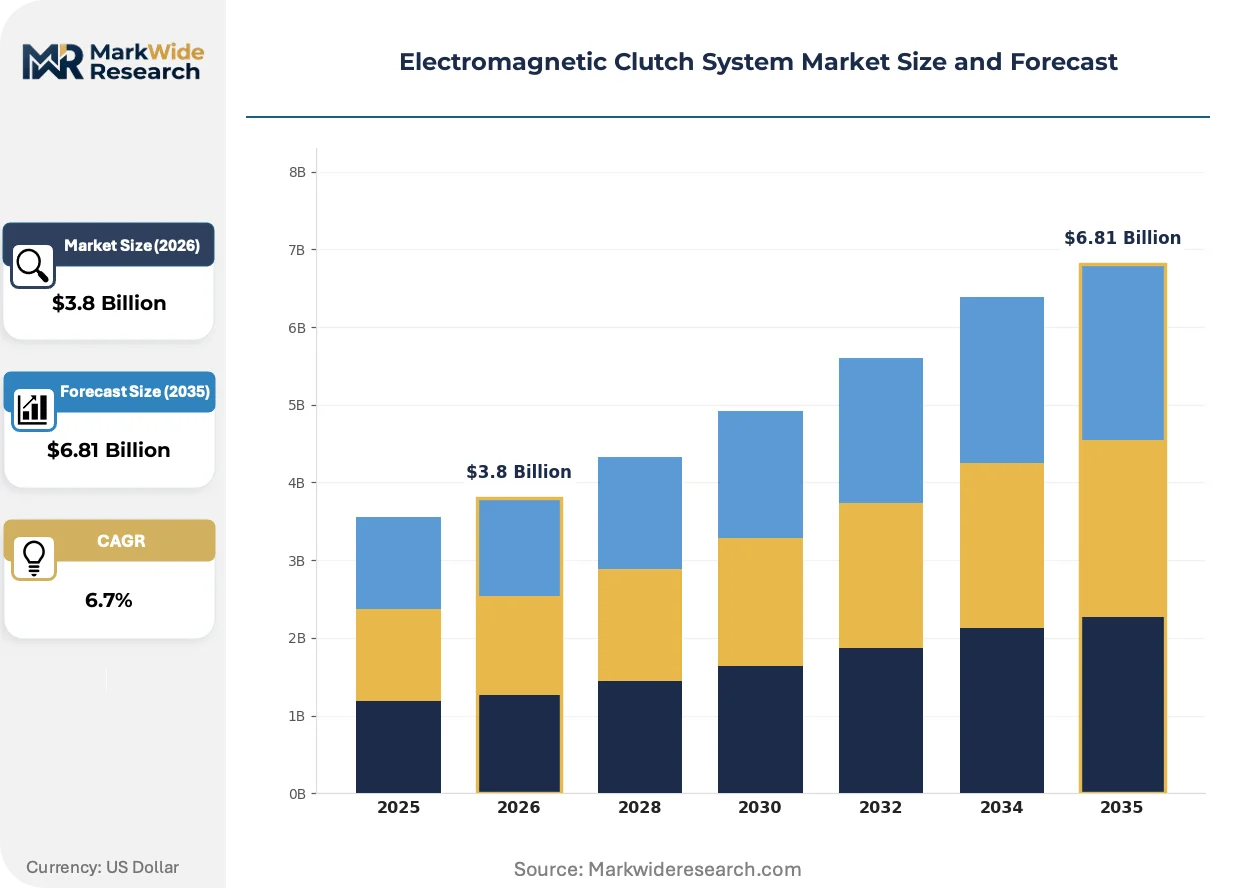
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Plate, Multi-Plate, Cone Clutch, Rubber Clutch Technology: Magnetic Field, Electromechanical, Hydraulic, Pneumatic End User: Automotive, Industrial Machinery, Aerospace, Marine Application: Transmission Systems, Power Transfer, Drive Systems, Automated Systems |
| Companies Covered | Altra Industrial Motion, Ogura Industrial Corp, Carlyle Johnson, Industrial Clutch Parts Ltd, Pethe Industrial Marketing, Modimaz Engineers, Motherson Sumi Systems, Stearns, Mitsubishi Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electromagnetic Clutch System Market Emerging Trajectories
Magnetic field architectures are fragmenting into application-specific configurations as end-users demand clutch systems optimized for precise torque envelopes rather than general-purpose ratings.
Multi-plate electromagnetic clutch technology is modularizing into standardized cartridge subassemblies that separate field coil, armature, and friction plate modules for field-replaceable maintenance. German transmission suppliers adopt these configurations to compress hybrid drivetrain development cycles. The approach is enabling parallel sourcing strategies that reduce single-supplier dependency for critical torque transfer components.
Japan's METI energy efficiency directives and JIS standards for industrial machinery safety are mandating redundant fail-safe disengagement protocols for automated equipment. Clutch manufacturers must certify dual-channel coil de-energization circuits to maintain precision equipment OEM qualification. Factory automation integrators in Nagoya and Osaka industrial clusters are prioritizing suppliers with pre-certified safety architectures.
Buyer concentration among tier-one automotive suppliers is compressing specification cycles for electromagnetic clutch procurement. German and Japanese OEMs now issue consolidated global tenders covering multi-year hybrid platform volumes, displacing regional spot purchasing. This consolidation is most visible in powertrain module sourcing for compact crossover vehicle segments where clutch system qualification locks in three-to-five-year supply agreements.
Electromagnetic Clutch System Market Segmentation
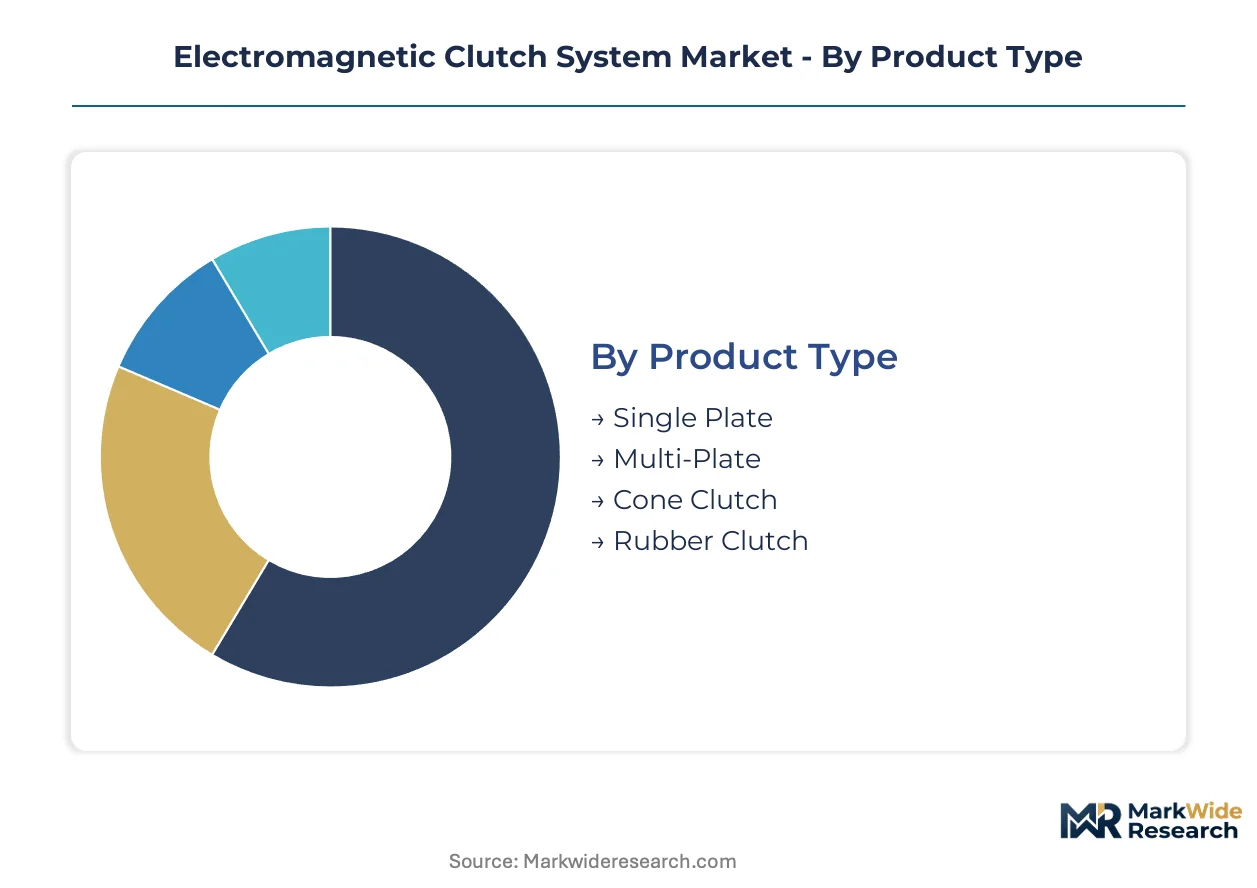
Electromagnetic clutch system procurement diverges sharply across torque requirements, thermal envelopes, and duty cycle specifications. End-users specify fundamentally different architectures for intermittent robotic positioning versus continuous automotive power transmission.
Product Type:
Axial packaging density and heat dissipation capacity distinguish competitive positioning across mechanical configurations.
- Single Plate:A single friction interface between armature and rotor delivers cost-optimized torque transmission up to moderate thermal loads. General industrial machinery OEMs in China's eastern manufacturing corridor specify these for standardized maintenance protocols and lower unit economics.
- Multi-Plate:Stacked friction plates multiply torque density within compact axial envelopes while distributing thermal load across multiple interfaces. German and Japanese automakers procure these for hybrid drivetrain integration where space constraints and heat rejection requirements are severe.
- Cone Clutch:Conical friction surfaces provide self-energizing engagement characteristics for moderate torque applications.
- Rubber Clutch:Elastomeric torque transmission elements absorb vibration and permit limited misalignment in specialized industrial drives.
Mature deployment sits with Single Plate configurations. Newer deployment is concentrated in Multi-Plate architectures.
Technology:
Actuation energy source determines response precision, fail-safe behavior, and integration complexity with surrounding control systems.
- Magnetic Field:Field coil excitation generates flux linkage between stationary and rotating members, enabling sub-50 millisecond engagement with no mechanical wear. Factory automation integrators in Japan's Nagoya and Osaka clusters favor this for precision positioning cycles.
- Electromechanical:Solenoid-driven mechanical linkage provides redundant fail-safe disengagement independent of electrical power state. Aerospace automated systems specify these where JIS-mandated safety protocols require dual-channel coil de-energization circuits.
- Hydraulic:Pressurized fluid actuation delivers high force density for heavy-duty power transmission.
- Pneumatic:Compressed air systems serve explosive atmosphere applications and coarse industrial indexing.
Magnetic Field architectures dominate volume. Electromechanical variants are climbing the fastest on safety-critical specifications.
End User:
Customer technical requirements fragment across mobility, manufacturing, and infrastructure applications with divergent certification regimes.
- Automotive:EPA tailpipe standards and NHTSA fuel economy mandates compel specification of electromagnetic clutches for engine-driven accessories. US automakers target parasitic loss reduction through precision engagement of alternators, air conditioning compressors, and cooling pumps.
- Industrial Machinery:Robotics and CNC machinery lines demand precise start-stop control without mechanical linkage wear. China's MIIT dual carbon goals and GB standards for motor system efficiency shape procurement toward locally produced electromechanical assemblies.
- Aerospace:Redundant fail-safe protocols and weight constraints define clutch specification for flight control surface actuation.
- Marine:Corrosion-resistant sealing and high torque density serve propulsion and winch applications.
Volume concentration rests with Automotive. Specification complexity is expanding most quickly in Industrial Machinery.
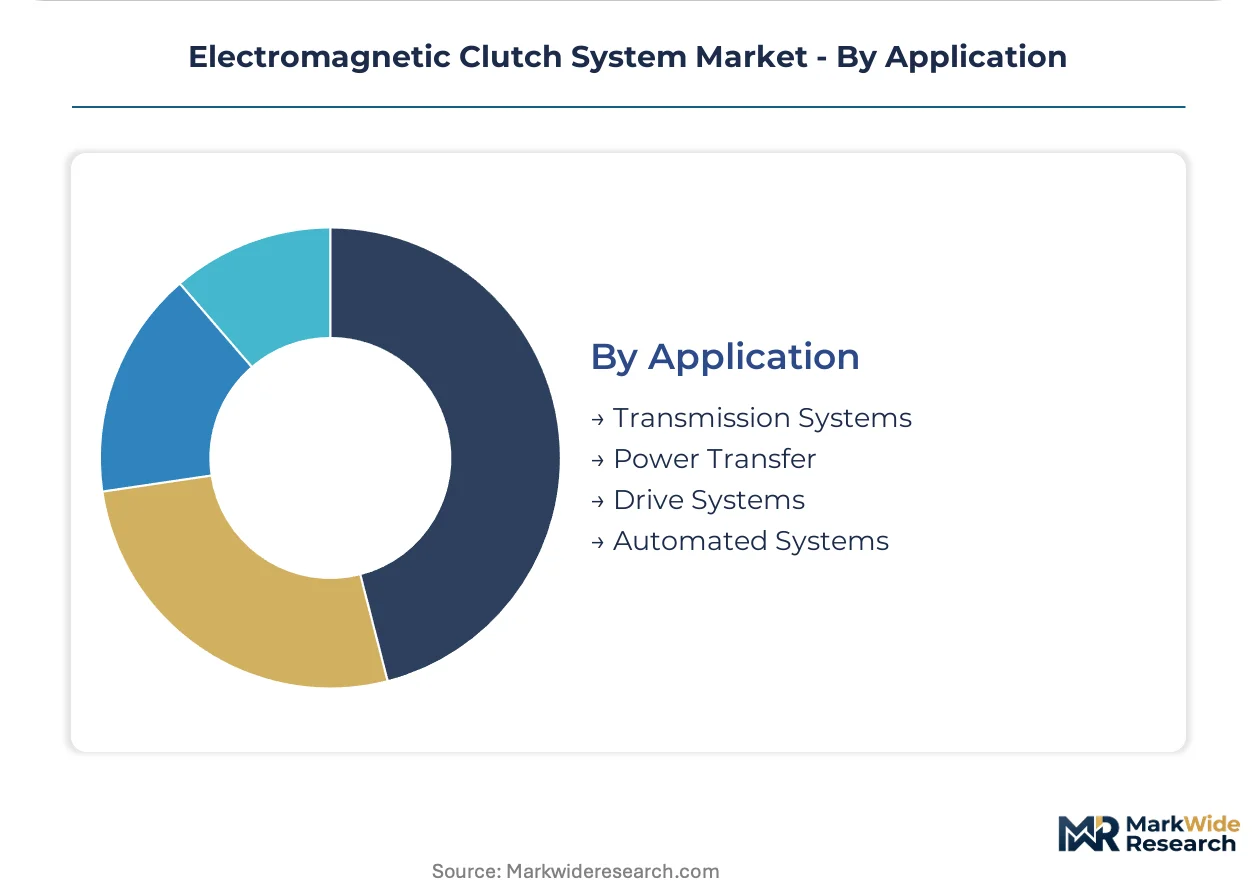
Application:
Functional role within power transmission architecture determines engagement frequency, thermal duty, and control system interface requirements.
- Transmission Systems:Gearbox-integrated clutch modules manage power flow between engine and driveline with synchronized speed matching. Hybrid drivetrain development in Germany compresses specification cycles toward electromechanical architectures.
- Power Transfer:Shaft-to-shaft torque transmission serves auxiliary drives and PTO applications across agricultural and construction equipment.
- Drive Systems:Primary motion control for conveyor, pump, and fan loads requires programmable engagement profiles.
- Automated Systems:Robotic joint actuation and positioning equipment demands force-limited, repeatable engagement cycles.
Established integration patterns dominate Transmission Systems. Automated Systems represent the steepest expansion trajectory on collaborative robotics demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rare earth magnet processing capacity in China anchors regional supply security for electromagnetic clutch field coil production. German automotive component engineering and Japanese precision manufacturing clusters shape demand specifications. Hybrid drivetrain procurement concentrates in three industrial corridors.
United States
NHTSA fuel economy mandates and EPA tailpipe standards compel domestic automakers to specify electromagnetic clutches for engine-driven accessory systems. The regulatory pressure targets parasitic loss reduction in alternator and air conditioning compressor engagement. Detroit-area powertrain engineering centers coordinate qualification timelines with tier-one suppliers.
Germany
EU Green Deal industrial decarbonization mandates accelerate replacement of mechanical clutch systems in automotive supply chains. KBA certification requirements shape product development cycles for hybrid transmission integration. Bavarian transmission engineering clusters specify multi-plate electromechanical architectures for compact crossover platforms.
China
MIIT dual carbon goals and GB standards for motor system efficiency tighten market access for imported clutch assemblies. The eastern manufacturing corridor from Shanghai to Suzhou concentrates domestic automation equipment builders specifying locally produced electromechanical assemblies. Robotics and CNC machinery lines drive specification volume.
Japan
METI energy efficiency directives and JIS standards for industrial machinery safety mandate redundant fail-safe disengagement protocols. Nagoya and Osaka industrial clusters prioritize suppliers with pre-certified dual-channel coil de-energization circuits. Factory automation integrators concentrate procurement among qualified precision equipment OEMs.
India
PLI scheme production-linked incentives for advanced automotive components attract clutch system localization for domestic hybrid vehicle programs. Tamil Nadu and Maharashtra automotive manufacturing corridors expand component sourcing from domestic suppliers. Tier-one suppliers establish captive production to meet qualification timelines.
Electromagnetic Clutch System Market Vendor Landscape
Global majors compete with regional champions across certification depth and hybrid platform qualification timelines. The vendor base separates into three tiers: scale-driven industrial conglomerates with multi-sector portfolios, precision-focused specialists serving automotive transmission OEMs, and regional fabricators capturing localization incentives. Consolidation pressure concentrates in automotive qualification pathways where three-to-five-year supply agreements lock in volume. Competitive moves center on strategic partnerships for rare earth magnet supply security and geographic expansion to capture India PLI scheme benefits.
Among Japan-based precision manufacturers, Mitsubishi Electric exemplifies the electromechanical architecture specialist serving factory automation safety requirements. Ogura Industrial Corp occupies a position within the scale-driven tier, leveraging manufacturing presence across East Asian markets. Altra Industrial Motion represents the diversified industrial conglomerate archetype with cross-sector clutch applications. These three anchors illustrate the competitive structure: technology certification specialists, regional scale players, and diversified industrial groups each pursue distinct qualification pathways.
| Leading Market Players |
|---|
| Altra Industrial Motion |
| Ogura Industrial Corp |
| Carlyle Johnson |
| Industrial Clutch Parts Ltd |
| Pethe Industrial Marketing |
| Modimaz Engineers |
| Motherson Sumi Systems |
| Stearns |
| Mitsubishi Electric |
| Others |
Supply Flow & Price Mechanics
Tier-one automotive supplier concentration in Germany and Japan compresses procurement toward multi-year contract pricing with embedded volume commitments. Electromagnetic clutch manufacturers bundle field coil replacement warranties and technical certification support into base unit economics, while unbundling predictive maintenance software and rare earth magnet price hedging as premium service tiers.
Pricing Analysis
Warranty bundling separates premium-tier suppliers offering five-year field coil coverage from standard-tier competitors with one-year limited warranties. Three-tier pricing structure across premium, standard, and economy levels reflects JIS certification grade, MIIT GB standard compliance, and volume scale commitments. Cost compression in economy-tier single-plate configurations intensifies as Chinese domestic automation builders shift procurement to locally certified alternatives. Industrial machinery OEMs in China's eastern corridor exhibit highest price sensitivity, while German hybrid drivetrain programs prioritize thermal performance over unit economics.
Supply Chain Analysis
Direct-to-OEM channels handle hybrid platform procurement from German and Japanese transmission engineering centers, while distributor networks serve aftermarket replacement demand across industrial automation sectors. Field coil manufacturing draws from rare earth processing concentrated in China, precision magnet fabrication in Japan, and copper winding supply from Germany. Neodymium and dysprosium price volatility creates margin instability for high-torque multi-plate configurations. Single-source vulnerability clusters in Japanese precision magnetic field clutch qualification pathways threaten automotive OEM timeline compliance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure concentrates among mid-tier suppliers lacking hybrid platform qualification or rare earth magnet supply security, with EPA tailpipe enforcement and EU Green Deal mandates accelerating displacement of mechanical clutch incumbents.
For Market Incumbents: Lock in three-to-five-year supply agreements with German and Japanese OEM hybrid programs before qualification windows close. Secure backward integration into rare earth magnet supply chains through offtake partnerships with Chinese processors. Certification investment in dual-channel coil de-energization architectures defends against electromechanical specialist entrants targeting JIS-mandated safety segments. For New Entrants and Emerging Players: Enter via collaborative robotics joint actuation modules in South Korea, where force-limited clutch specifications remain underpenetrated by established automotive-qualified suppliers. Target India's PLI scheme localization requirements for domestic hybrid vehicle component sourcing. Position as certified aftermarket service providers for existing CNC machinery lines in China's eastern manufacturing corridor, bypassing direct OEM qualification barriers. For Investors and Strategic Acquirers: The window for entry favors precision electromechanical specialists with pre-certified safety architectures and captive rare earth supply relationships. Mid-cap targets with hybrid drivetrain qualification but limited geographic diversification present consolidation candidates. Watch for MIIT GB standard enforcement tightening as the signal for import displacement acceleration in China's automation equipment sector.| Strategic Initiative | Industry Significance |
|---|---|
| Rare Earth Magnet Supply Agreement | Secures neodymium and dysprosium offtake from Chinese processors for multi-plate field coil production. |
| JIS Safety Certification Investment | Enables dual-channel coil de-energization qualification for Nagoya and Osaka factory automation integrators. |
| India PLI Scheme Localization | Captures production-linked incentives for Tamil Nadu and Maharashtra hybrid vehicle component supply. |
| Multi-Plate Cartridge Modularization | Compresses German transmission supplier development cycles through field-replaceable subassembly standardization. |
| Variable-Frequency Drive Integration Partnership | Synchronizes clutch controller architectures with next-generation automated production line specifications. |
Methodological Framework
Independent corroboration across OEM procurement executives, Tier 1 supplier engineering directors, and factory automation integrators underwrites the qualitative findings. Primary interviews with maintenance directors at robotics and CNC machinery lines, aftermarket service heads, and rare earth magnet procurement specialists combined with secondary validation from customs trade data, MIIT GB standard filings, JIS certification registries, and SEC supplier disclosures. Bottom-up segment sizing and top-down market reconciliation triangulate volume estimates across product type, technology, and end-use dimensions.
Rate-of-change decomposition isolates volume growth from price mix effects across the projection horizon. Segmentation modeling incorporates torque density requirements, thermal envelope specifications, duty cycle intensity, and regional regulatory cluster alignment. CAGRs derive from fitted trend extrapolation moderated by technology substitution elasticity and platform qualification timeline constraints. Hybrid drivetrain penetration curves and industrial automation capital expenditure cycles inform sector-specific trajectory assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under rare earth price spike scenarios or accelerated EPA enforcement timelines. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive Trim Part Market
Automotive Parts
Mexico Automotive Air Filters Market
Automotive Parts
Automotive Hydraulic Filters Market
Automotive Parts
Global Plastics for Passenger Cars Market
Automotive Parts
Automotive Ignition Coil Market
Automotive Parts
Automotive Power Window Regulator Market
Automotive Parts
Norway Passenger Vehicles Lubricants Market
Automotive Parts
Commercial Vehicle Brake Chambers Market
Automotive Parts
Canada Automotive Parts Die Casting Market
Automotive Parts
Automotive Brake Shims Market
Automotive Parts
Daytime Running Lights Market
Automotive Parts
Australia Automotive Airfilters Market
Automotive Parts
Insert Drive for Torque Wrench Market
Automotive Parts
China Automotive Parts Aluminum Die Casting Market
Automotive Parts
Tire Tread Cutting Machines Market
Automotive Parts
Friction Pads Market