
 Global All Wheel Drive Market | 2026-2036
Global All Wheel Drive Market Size, Share, and Industry Trends Forecast 2026-2036
Global All Wheel Drive Market Analysis
China is tilting toward electric all-wheel-drive capacity as domestic automakers scale dual-motor platforms. BorgWarner Inc. leverages its integrated powertrain division to supply torque-vectoring systems for hybrid architectures. Magna International Inc. sustains manufacturing scale across North American and European assembly corridors. JTEKT Corporation anchors the Asian supply base through specialized torque-transfer coupling production.
All wheel drive distributes engine torque across all four wheels through mechanical, hydraulic, or electric coupling systems, with modern variants employing clutch packs or dual-motor electric layouts to vary torque split ratios between axles. The architecture serves primarily to enhance vehicle stability, launch traction, and off-road capability across variable surface conditions. SUVs and crossovers lead volume within product type segmentation due to consumer preference for elevated ride height combined with weather-ready traction. Full-time AWD systems retain margin density in premium applications, while electric drive system variants expand fastest as battery-electric platforms proliferate.
NHTSA mandates in the United States, ECE regulations administered under United Nations frameworks, and China's MIIT new-energy vehicle standards collectively shape AWD system certification, efficiency benchmarking, and electrification roadmaps. EPA corporate average fuel economy requirements and Euro 7 emission protocols from the European Commission further compel suppliers to optimize driveline losses and integrate electric assist. Stakeholders must monitor how battery-electric platform standardization alters the addressable market for mechanical coupling hardware versus software-defined torque management.
Market Dynamics
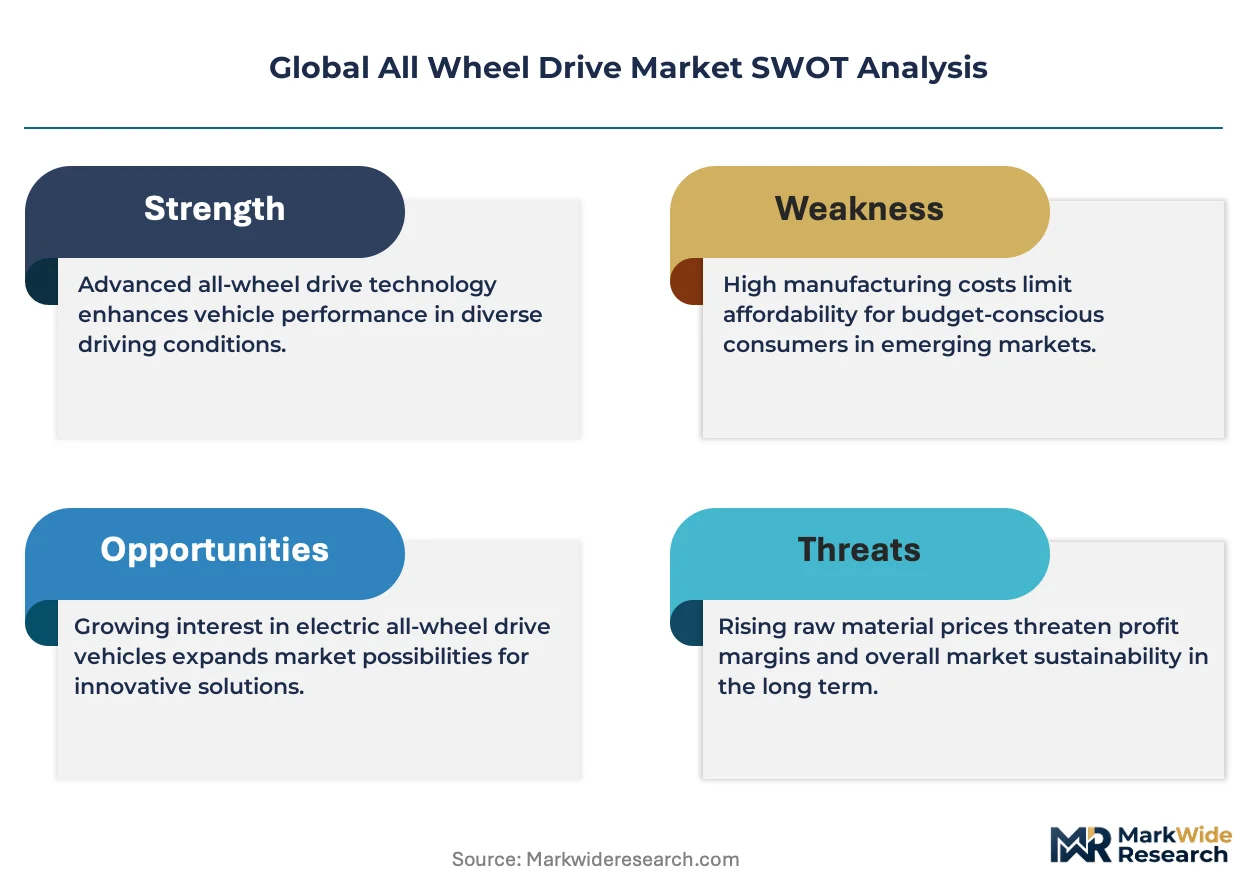
Electrification of powertrain architectures is collapsing the mechanical complexity that once defined all-wheel-drive systems, forcing suppliers to pivot from clutch-pack engineering toward dual-motor torque management and software-defined traction control.
Growth Catalysts
- Dual-motor electric platforms:Battery-electric vehicle architectures from domestic Chinese automakers eliminate mechanical differentials entirely, creating new demand for integrated torque-vectoring electronics.
- NHTSA traction mandates:Federal requirements for electronic stability control in light vehicles sustain baseline AWD penetration across US passenger-car segments.
- Euro 7 emission protocols:The European Commission's tightening limits on driveline friction losses compel suppliers to redesign coupling hardware for parasitic drag reduction.
Market Restraints
- Rare earth magnet cost volatility:Neodymium and dysprosium price swings in Chinese export markets squeeze margins on electric motor production for AWD systems.
- German supplier concentration:ZF Friedrichshafen and Continental together anchor critical torque-transfer engineering clusters around Lake Constance, creating single-source vulnerability.
- Mechanical coupling obsolescence:Dual-motor electric layouts bypass center differentials entirely, threatening long-term demand for traditional clutch-pack hardware.
Strategic Opportunities
- Indian SUV electrification:Domestic automakers in the subcontinent remain underpenetrated by torque-vectoring technology, offering first-mover positioning for dual-motor platform suppliers.
- US Inflation Reduction Act:Domestic content requirements for electric vehicle tax credits incentivize North American assembly of integrated powertrain modules.
- Software-defined torque management:Convergence of vehicle control units with cloud-based traction mapping enables subscription revenue models for over-the-air calibration updates.
Industry Challenges
- Embedded systems talent scarcity:Recruitment of motor-control firmware engineers lags demand across European and North American engineering centers.
- Homologation timeline compression:Simultaneous certification against EPA fuel-economy protocols, NHTSA safety mandates, and UN ECE regulations strains validation resources.
- Legacy platform integration friction:Retrofitting torque-vectoring electronics onto existing internal-combustion vehicle architectures requires costly harness redesign and control-unit reprogramming.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global All Wheel Drive Market |
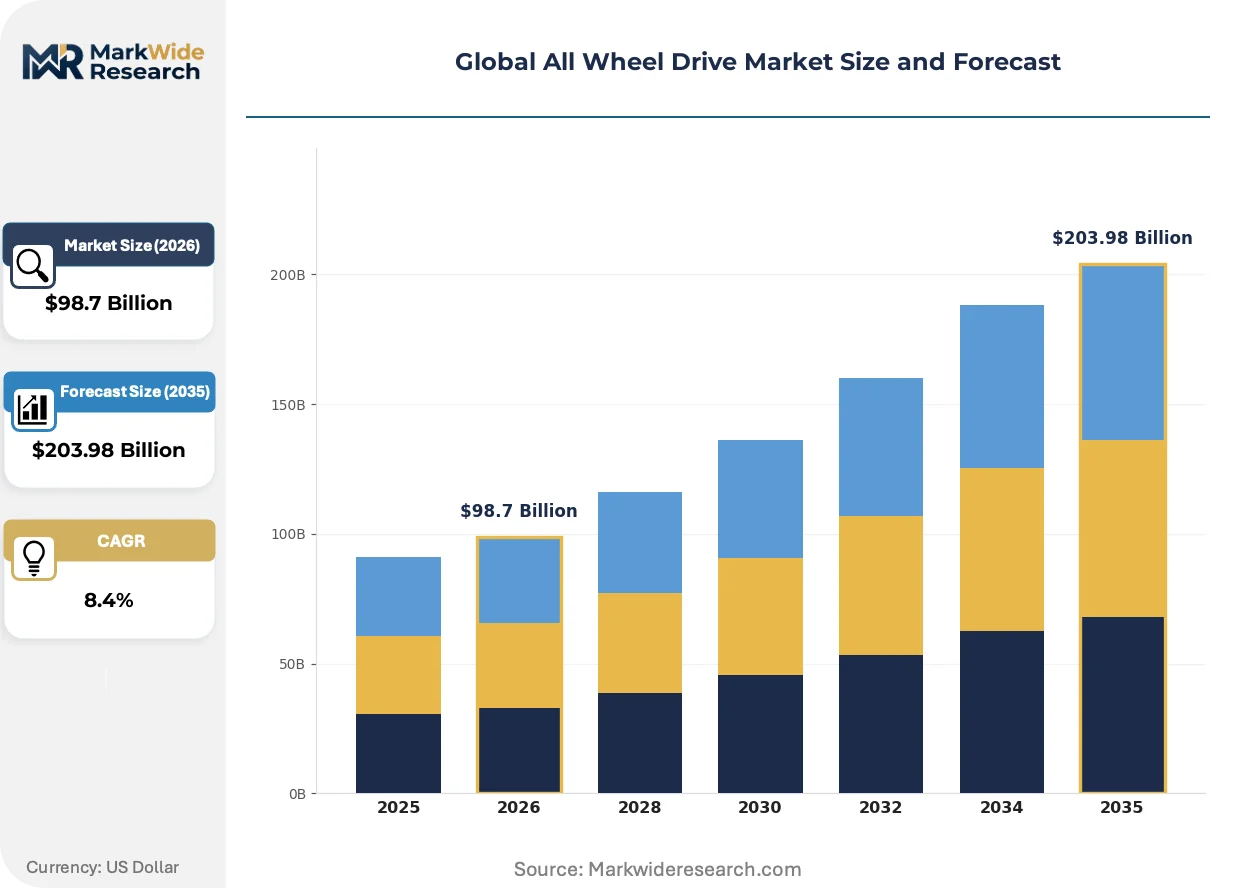
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $203.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: SUVs, Passenger Cars, Commercial Vehicles, Crossovers Technology: Full-Time AWD, Part-Time AWD, Automatic AWD, Manual AWD End User: Consumers, Fleet Operators, Manufacturers, Ride-Sharing Services Drive System: Hydraulic, Mechanical, Electric, Others |
| Companies Covered | BorgWarner Inc., ZF Friedrichshafen AG, Magna International Inc., Continental AG, JTEKT Corporation, Toyota Motor Corporation, Volkswagen AG, Honda Motor Company Ltd., Tesla Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global All Wheel Drive Market Emerging Trajectories
Software-defined vehicle architectures are dissolving the boundary between mechanical driveline hardware and electronic control systems, enabling real-time torque allocation through over-the-air updates rather than fixed mechanical ratios.
Silicon carbide power semiconductors are collapsing thermal management constraints in electric motor inverters, allowing dual-motor AWD systems to sustain peak torque output without liquid cooling loops. Premium battery-electric SUVs from Korean and German automakers have adopted these modules since 2023, compressing the cost gap against silicon-based alternatives faster than forecast.
China's MIIT new-energy vehicle standards now mandate energy-consumption reporting that includes driveline efficiency losses, forcing domestic automakers to disclose parasitic drag from all-wheel-drive hardware. This transparency requirement is accelerating adoption of disconnecting front-axle couplings in range-sensitive electric crossovers, particularly among second-tier domestic brands seeking certification compliance.
Fleet procurement managers at North American rental-car operators have compressed replacement cycles for AWD-equipped crossovers from 36 to 24 months, responding to accelerated wear on coupling clutches in high-mileage duty. This behavioral shift concentrates volume with suppliers capable of rapid-turn refurbishment programs and certified pre-owned driveline warranties, favoring vertically integrated service networks over component-only vendors.
Global All Wheel Drive Market Segmentation
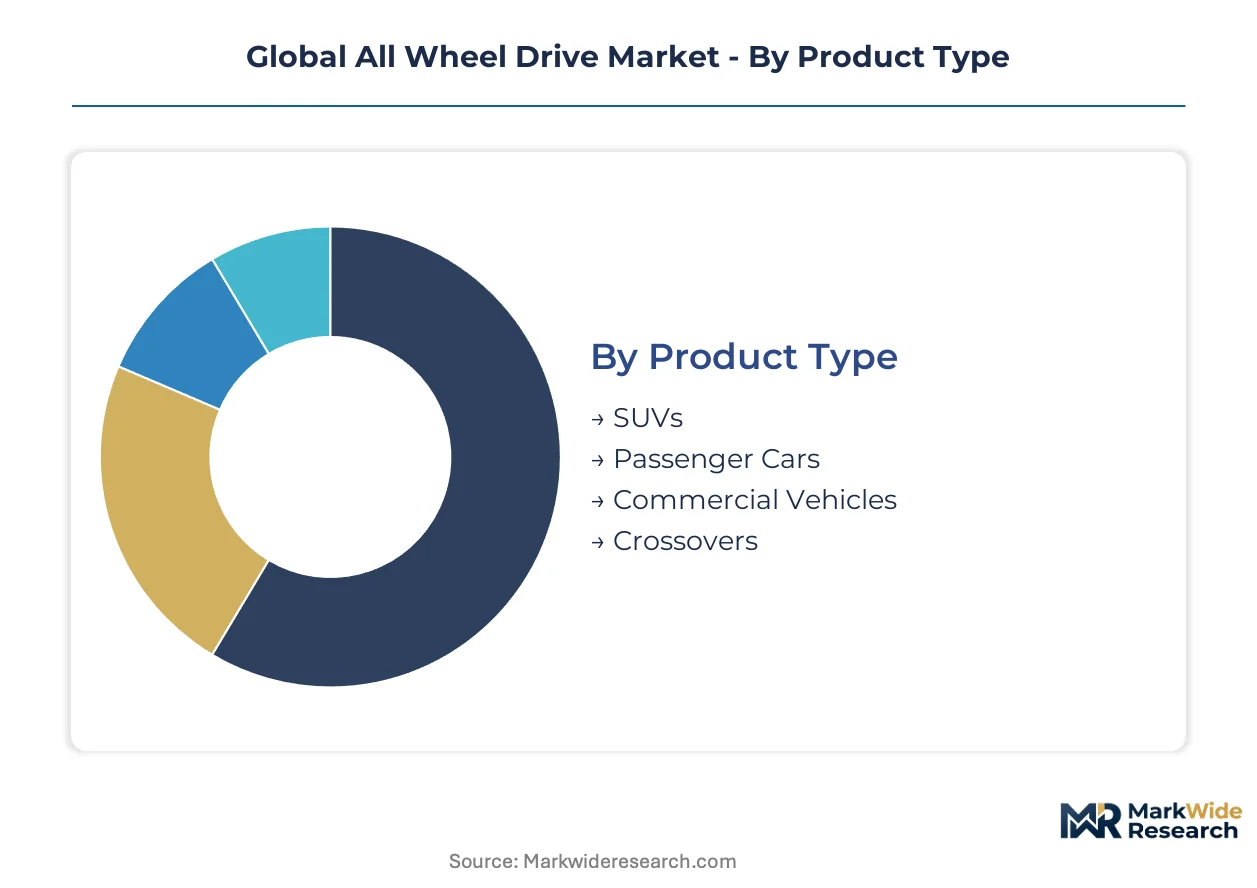
AWD system configurations vary dramatically across vehicle architectures and duty cycles, with replacement intervals and technology refresh rates creating distinct investment profiles for suppliers. Understanding which segments turn over fastest versus which sustain longest production runs shapes capital allocation and R&D prioritization.
Product Type:
SUVs and crossovers refresh platforms every five to seven years, compressing development cycles for driveline suppliers, while commercial vehicles extend service lives past fifteen years with minimal hardware changes.
- SUVs:Body-on-frame and unibody architectures demand robust torque-transfer hardware capable of off-road articulation cycles. North American consumers in snow-belt states drive highest penetration rates, with NHTSA stability mandates reinforcing baseline fitment across mid-size and full-size segments.
- Crossovers:Car-based unibody platforms prioritize packaging efficiency and weight reduction, favoring compact coupling systems with disconnect capability for fuel economy. European assembly corridors around Stuttgart and Wolfsburg concentrate sourcing for premium compact crossovers targeting wet-climate markets.
- Passenger Cars:Sedan and hatchback applications concentrate in German and Japanese premium segments where all-weather performance differentiates brand positioning.
- Commercial Vehicles:Pickup trucks and delivery vans prioritize durability over refinement, with torque ratings exceeding passenger-car systems by three to four multiples.
SUVs dominate installed base. Crossovers are where expansion concentrates.
Technology:
Cost tier stratification separates premium full-time systems from value-oriented part-time architectures, with automatic engagement commanding mid-market positioning.
- Full-Time AWD:Continuous torque distribution through mechanical center differentials or dual-motor electric layouts eliminates driver intervention. Premium German and Korean battery-electric SUVs specify these configurations as standard equipment, with silicon carbide inverters enabling sustained high-output operation.
- Part-Time AWD:Driver-selectable engagement via transfer cases or locking hubs serves cost-sensitive segments and off-road specialty applications. Chinese domestic brands leverage these systems in entry-level SUVs to meet MIIT energy-consumption reporting thresholds without full electrification expense.
- Automatic AWD:On-demand coupling activation triggered by wheel-slip sensors balances traction security with parasitic loss minimization.
- Manual AWD:Driver-controlled mechanical engagement persists in emerging-market commercial vehicles and enthusiast-oriented performance cars.
Full-Time AWD captures premium pricing. Automatic AWD climbs the fastest on volume.
End User:
Customer type determines specification rigor, with fleet procurement demanding standardized service intervals and consumers prioritizing initial purchase price over lifetime operating cost.
- Consumers:Individual purchasers respond to weather-driven traction anxiety and resale value retention, particularly in US Northeast and Midwest markets where AWD commands transaction price premiums.
- Fleet Operators:Rental-car and corporate fleet managers compress replacement cycles for AWD-equipped crossovers from thirty-six to twenty-four months, concentrating volume with suppliers offering rapid-turn refurbishment and certified pre-owned driveline warranties.
- Manufacturers:OEM assembly plants specify AWD hardware for platform differentiation and regulatory compliance across export markets.
- Ride-Sharing Services:High-mileage urban duty cycles accelerate coupling wear, creating aftermarket demand for reinforced friction materials and extended-warranty programs.
Consumers anchor volume demand. Fleet operators drive fastest specification turnover.
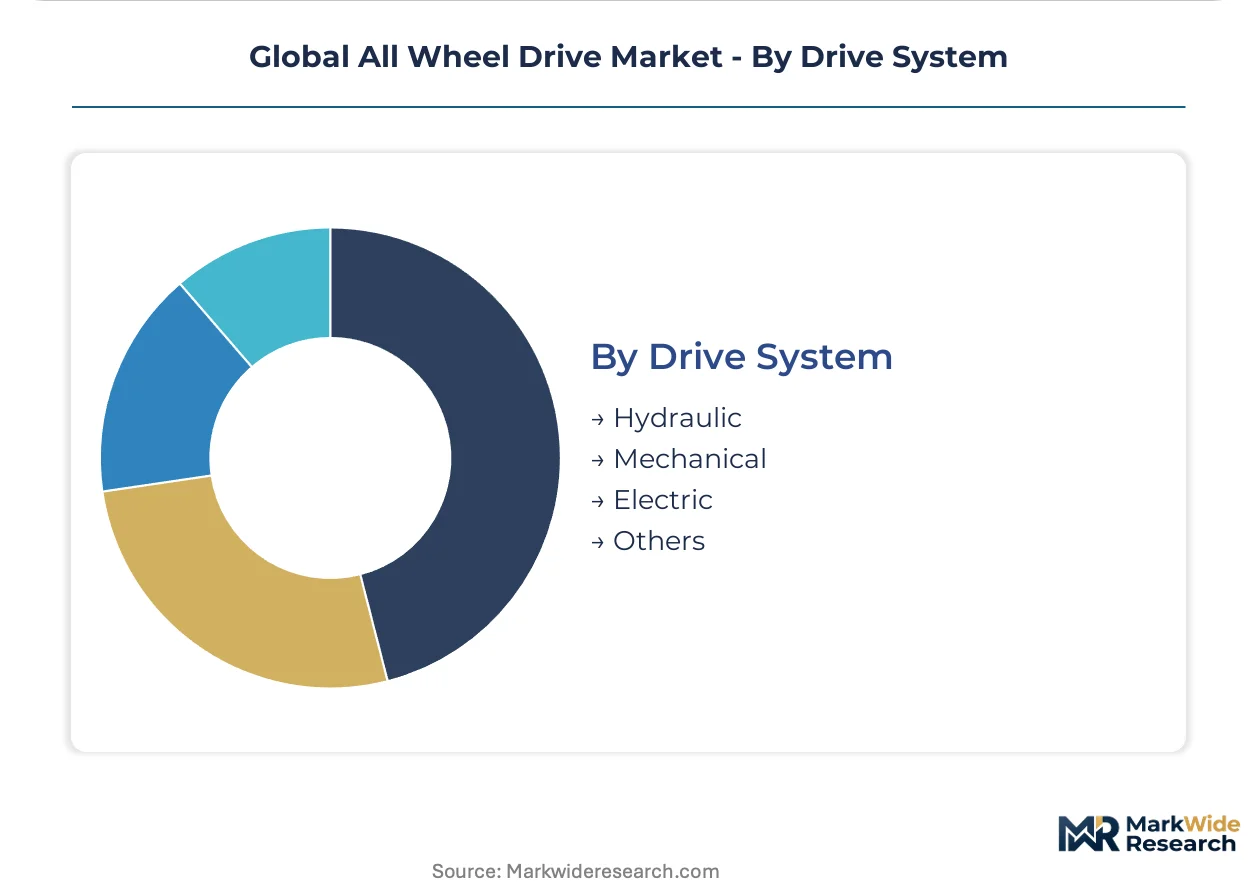
Drive System:
Supply concentration around Lake Constance engineering clusters favors hydraulic and mechanical architectures, while electric drive systems disperse manufacturing across Asian battery and motor production corridors.
- Electric:Dual-motor layouts with independent axle control eliminate mechanical differentials entirely, enabling software-defined torque vectoring. Chinese automakers BYD and NIO have scaled these platforms fastest, with MIIT standards mandating driveline efficiency disclosure accelerating adoption.
- Mechanical:Gear-based torque transfer through center differentials and viscous couplings retains cost advantage in internal-combustion applications. German suppliers ZF Friedrichshafen and Continental anchor production for European premium OEMs.
- Hydraulic:Multi-plate clutch packs with pressure-modulated engagement serve part-time and automatic AWD architectures requiring rapid torque redistribution.
- Others:Magnetorheological and electromagnetic coupling technologies occupy niche performance and prototyping applications.
Mechanical systems dominate installed base. Electric drive systems are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
AWD consumption patterns diverge sharply by geography: Chinese automakers deploy dual-motor electric layouts as standard equipment, while German and US markets retain mechanical coupling architectures in premium internal-combustion segments.
United States
NHTSA electronic stability control mandates sustain baseline AWD fitment across light-vehicle segments, with snow-belt states driving highest penetration rates. The Inflation Reduction Act's domestic content requirements incentivize North American assembly of integrated powertrain modules. Detroit-area engineering corridors concentrate torque-vectoring software development for hybrid truck platforms.
Germany
Premium OEMs specify full-time AWD as standard equipment across SUV and crossover lineups, with Euro 7 emission protocols compelling driveline friction reduction. KBA type-approval processes enforce stringent efficiency benchmarking for torque-transfer hardware. Lake Constance engineering clusters around Friedrichshafen anchor ZF Friedrichshafen and Continental torque-coupling production.
China
Domestic automakers BYD and NIO scale dual-motor electric platforms fastest globally, eliminating mechanical differentials entirely. MIIT new-energy vehicle standards mandate driveline efficiency disclosure, accelerating adoption of disconnecting front-axle couplings. Yangtze River Delta manufacturing corridors concentrate silicon carbide inverter production for sustained high-output motor operation.
Japan
JTEKT Corporation anchors Asian supply base through specialized torque-transfer coupling production for hybrid architectures. METI carbon-neutrality roadmaps push automakers toward electric AWD variants in compact crossover segments. Nagoya-area engineering centers concentrate motor-control firmware development for dual-motor layouts.
India
Domestic SUV electrification remains underpenetrated by torque-vectoring technology, offering positioning for dual-motor platform suppliers. PLI scheme incentives for advanced automotive components attract powertrain module assembly investments. Maharashtra and Gujarat manufacturing corridors concentrate emerging capacity for electric driveline hardware.
Global All Wheel Drive Market Vendor Landscape
Capability concentration sits with integrated powertrain specialists; scale advantage sits with diversified tier-one suppliers. The vendor base stratifies across three tiers: German driveline engineering houses with Lake Constance clustering, North American diversified automotive suppliers with cross-segment manufacturing breadth, and Asian specialists in torque-transfer coupling production. Two dominant competitive moves define positioning: backward integration into silicon carbide semiconductor sourcing and geographic expansion of electric motor assembly capacity to capture IRA tax credit eligibility.
Within the diversified tier-one segment, BorgWarner Inc. and Magna International Inc. exemplify scale-driven positioning across multiple powertrain architectures. Among specialized driveline engineering houses, ZF Friedrichshafen AG represents capability concentration in torque-vectoring system integration. JTEKT Corporation occupies a position as the anchor Asian supplier for torque-transfer coupling production. These three company structures illustrate the geographic and technological segmentation shaping competitive dynamics.
| Leading Market Players |
|---|
| BorgWarner Inc. |
| ZF Friedrichshafen AG |
| Magna International Inc. |
| Continental AG |
| JTEKT Corporation |
| Toyota Motor Corporation |
| Volkswagen AG |
| Honda Motor Company Ltd. |
| Tesla Inc. |
| Others |
Supply Flow & Price Mechanics
Friedrichshafen's Lake Constance engineering corridor anchors European torque-coupling capacity, concentrating pricing power with ZF Friedrichshafen and Continental for premium full-time AWD systems while Chinese silicon carbide inverter production erodes margin structures at the mid-market tier.
Pricing Analysis
Chinese domestic brands command 20-30% price spreads below German premium equivalents for dual-motor electric platforms, with three-tier pricing structure across premium, standard, and economy levels differentiated by certification grade and after-sales service bundling. Price differentiation stems from vertical integration depth and volume scale, with margins tightening due to rare earth magnet cost volatility. Fleet operators exhibit highest price sensitivity, while premium OEMs prioritize performance benchmarks over unit economics.
Supply Chain Analysis
Neodymium and dysprosium feedstock draws from Chinese export markets, with silicon carbide wafers sourced from Yangtze River Delta fabrication corridors and torque-transfer hardware concentrated in German and Japanese manufacturing clusters. Raw material dependencies span rare earth magnets, high-grade steel alloys, and power semiconductors. Single-source vulnerability around Lake Constance engineering clusters threatens supply continuity. Distribution runs through Tier 1 supplier-direct-to-OEM channels with limited aftermarket penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment, where NHTSA stability mandates and Euro 7 emission protocols create certification barriers that compound switching costs for established suppliers.
For Market Incumbents: Entrench position through backward integration into silicon carbide semiconductor sourcing and capacity expansion across North American assembly corridors to capture IRA domestic content eligibility. Dual-motor electric platform proliferation from Chinese automakers threatens mechanical coupling revenue streams. Prioritize software-defined torque-vectoring firmware development as the priority capability anchor. For New Entrants and Emerging Players: Indian SUV electrification offers the most penetrable white-space opportunity, with domestic automakers underindexed on torque-vectoring technology and PLI scheme incentives reducing capital barriers. Target Maharashtra and Gujarat manufacturing corridors for electric driveline module assembly partnerships. Pursue fleet operator procurement channels with rapid-turn refurbishment capabilities as the go-to-market angle. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because dual-motor platform standardization will collapse the addressable market for mechanical coupling hardware, favoring integrated powertrain specialists with software capabilities over component-only vendors. Acquisition target archetype: mid-cap torque-vectoring firmware developers with OEM validation relationships. Monitor MIIT energy-consumption disclosure mandates as the inflection signal for disconnecting coupling adoption rates.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Inverter Integration | Enables sustained peak torque output in dual-motor AWD systems without liquid cooling infrastructure. |
| Software-Defined Vehicle Investment | Positions suppliers for subscription revenue from over-the-air torque calibration updates. |
| North American Manufacturing Footprint | Captures IRA domestic content requirements for electric vehicle tax credit eligibility. |
| Battery Supply Agreement | Secures cell allocation for integrated powertrain module production scaling. |
| Charging Infrastructure Partnership | Aligns AWD system specifications with high-output fast-charging thermal management protocols. |
Methodological Framework
Operator-level perspectives from OEM platform engineers, Tier 1 supplier procurement leads, aftermarket distributors, and dealership operations anchored the qualitative base, cross-referenced with vehicle production databases, IHS Markit registration data, SEC filings from listed suppliers, and MIIT new-energy vehicle certification records. Bottom-up segment sizing triangulated against top-down macroeconomic indicators.
Scenario-bracketing framed the analytical approach across the analysis window, modeling vehicle class, propulsion architecture, content per vehicle, and regional production cluster as primary segmentation dimensions. CAGRs derived from historical penetration rate trajectories and technology substitution curves, with silicon carbide cost compression timelines and NHTSA regulatory compliance deadlines as key forecast inputs.
Practitioners should monitor rare earth export quota adjustments, Euro 7 implementation timing, and dual-motor platform share trajectories for early signals of forecast revision. Cross-checking against IHS Markit powertrain forecast benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Global Automotive Cylinder Liner Market
Automotive Parts
Center and Drag Link Market
Automotive Parts
Global Automotive Leaf Spring Market
Automotive Parts
India Brake Pads Market
Automotive Parts
Universal Joint Shafts Market
Automotive Parts
Air Filter for Automotive Market
Automotive Parts
Plastic Fuel Tanks Market
Automotive Parts
Mechanical Performance Tuning Components Market
Automotive Parts
Power Steering Oil Market
Automotive Parts
United States Automotive Parts Die Casting Market
Automotive Parts
Steel Cords for Radial Tyres Market
Automotive Parts
Cheetah Friction Reduction Technologies Market
Automotive Parts
Egypt Passenger Vehicles Lubricants Market
Automotive Parts
Rear Spoiler Market
Automotive Parts
Global Automotive Springs and Damper Market
Automotive Parts
Brazil Automotive Hydraulic Actuators Market