
 Ship Heat Exchanger Market | 2026-2036
Ship Heat Exchanger Market Size, Share, and Industry Trends Forecast 2026-2036
Ship Heat Exchanger Market Analysis
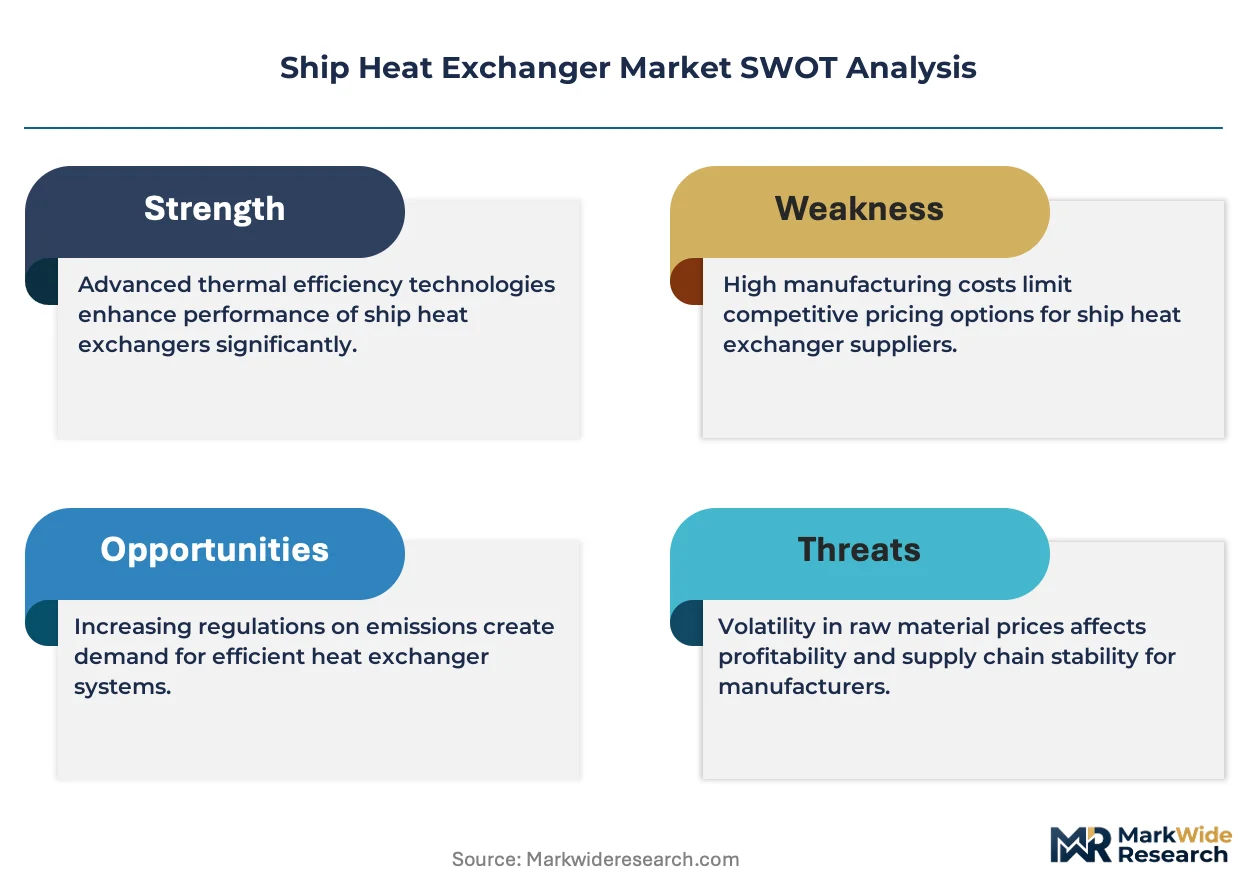
ISO 9001 and ASME U-stamp certification is rotating as the primary gating mechanism for supplier qualification in marine thermal systems. Alfa Laval Mid Europe leverages its Scandinavian engineering heritage to dominate high-efficiency plate heat exchanger supply for cruise and ferry segments. DongHwa Entec anchors Korean shipyard relationships through localized production and naval certification depth. Mersen competes with specialized graphite and silicon carbide solutions targeting corrosive seawater and chemical tanker applications.
A ship heat exchanger transfers thermal energy between fluids aboard vessels, typically fabricated from titanium or duplex stainless steel to withstand chloride corrosion at seawater inlet temperatures of 32°C, serving engine cooling, fuel preheating, and HVAC functions. Plate configurations command premium margins in space-constrained machinery rooms where compact footprint offsets higher unit cost. Shell and tube architectures sustain volume leadership in main engine lubricating oil cooling where pressure ratings exceed 16 bar. Titanium material grades are displacing copper-nickel alloys in ballast water treatment systems as IMO biological treatment standards harden.
IMO, ASME, and Lloyd's Register frame the regulatory architecture governing marine heat exchanger design approval, material traceability, and welding qualification. IMO's EEDI and CII metrics force shipowners to specify higher-efficiency thermal equipment during retrofit cycles or face operational penalties. Stakeholders must monitor how EU Green Deal requirements and emerging carbon border adjustments reshape material sourcing decisions for European-flagged fleets.
Market Dynamics
IMO 2023 carbon intensity regulations are compressing replacement cycles for marine thermal equipment as shipowners face operational penalties under CII metrics, forcing specification upgrades ahead of historical maintenance schedules.
Growth Catalysts
- LNG carrier newbuild programs:South Korean shipyards at Geoje and Ulsan are expanding heat exchanger procurement for liquefaction duty, with plate configurations specified for compact machinery room footprints.
- IMO biological treatment standards:Ballast water management systems are mandating titanium-grade heat exchangers, displacing copper-nickel alloys in retrofit installations across international fleets.
- Scandinavian engineering heritage:Nordic suppliers leverage ASME U-stamp and ISO 9001 certification depth to dominate high-efficiency segments in cruise and ferry thermal systems.
Market Restraints
- Titanium price volatility:Seawater-grade titanium sheet remains exposed to sponge supply concentration, compressing fabricator margins when aerospace demand spikes.
- Korean shipyard cluster risk:Production gravity at Geoje and Ulsan creates single-geography dependency for qualified suppliers serving LNG carrier programs.
- Pressure rating limitations:Plate heat exchanger architectures face technical ceiling below 16 bar, ceding main engine lubricating oil cooling to shell and tube designs.
Strategic Opportunities
- Graphite and silicon carbide solutions:Corrosive chemical tanker applications represent underpenetrated territory for specialized ceramic heat exchanger suppliers.
- EU Green Deal carbon border adjustments:European-flagged fleets face material sourcing disclosure requirements, creating certification advantage for EU-based fabricators.
- Digital twin integration:Convergence of thermal monitoring sensors with predictive maintenance platforms enables performance-based service contracting for cruise operators.
Industry Challenges
- Welding qualification scarcity:Lloyd's Register and ASME Section IX certified welders for titanium and duplex stainless steel remain concentrated at established Korean and Scandinavian facilities.
- Retrofit integration complexity:Legacy shell and tube installations in existing engine rooms require custom manifold reconfiguration when upgrading to compact plate designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ship Heat Exchanger Market |
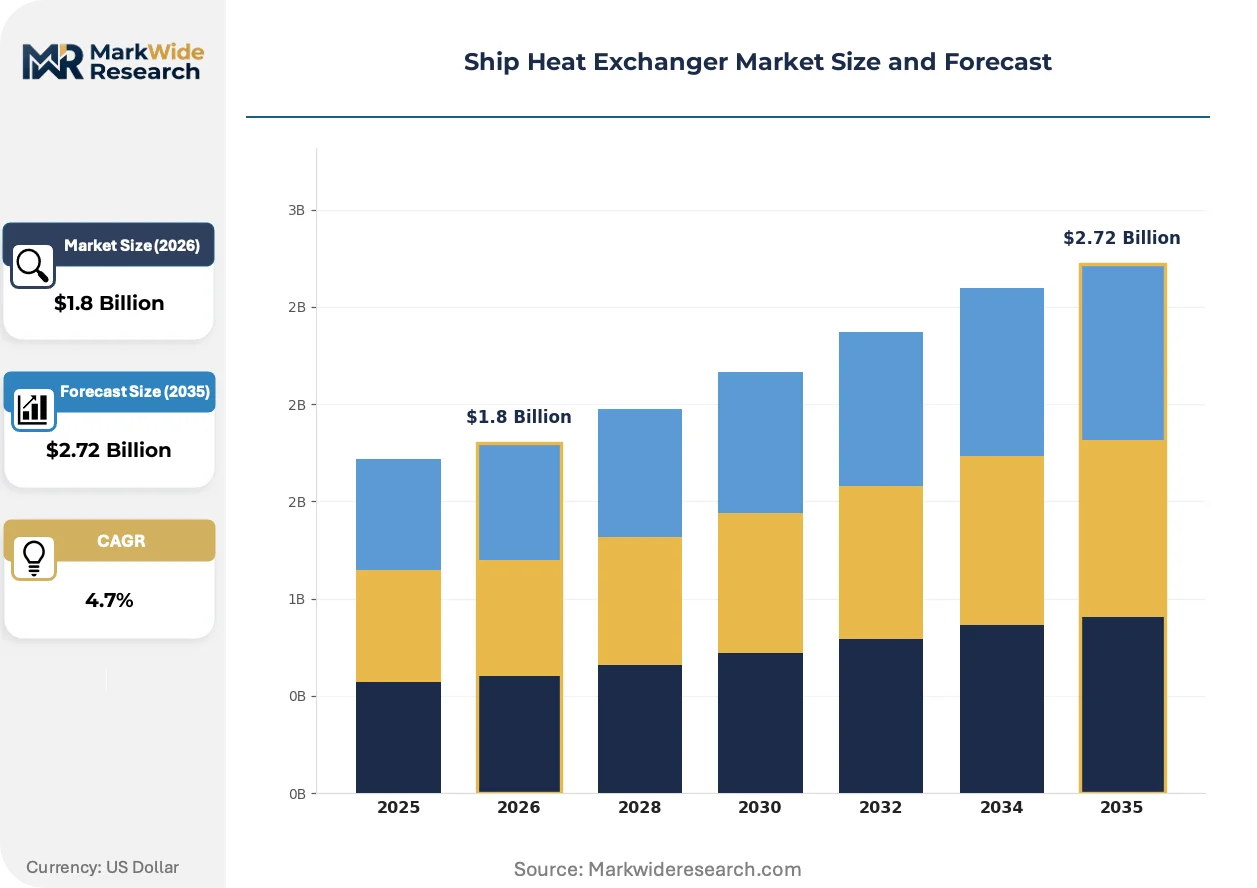
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shell & Tube, Plate, Air Cooled, Double Pipe Application: Marine Propulsion, HVAC, Ballast Water Treatment, Refrigeration Material: Stainless Steel, Copper, Titanium, Carbon Steel End User: Shipbuilders, Shipping Companies, Oil & Gas, Military |
| Companies Covered | Alfa Laval Mid Europe, ETB Energietechnik Bremen GmbH, Mersen, DongHwa Entec, E. J. Bowman, Blokland Non-ferro, Pomar Water, Teknotherm, Vineta, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ship Heat Exchanger Market Emerging Trajectories
Marine thermal systems are undergoing material substitution and digital integration as regulatory pressure tightens efficiency requirements and biological treatment standards harden against legacy alloy performance.
Additive manufacturing is decomposing traditional fabrication timelines for complex titanium heat exchanger manifolds. Norwegian cruise operators are piloting topology-optimized geometries for space-constrained machinery rooms. This technology is decomposing the historical trade-off between thermal efficiency and pressure rating in compact designs.
EU F-Gas Regulation is phasing down hydrofluorocarbon refrigerants in marine HVAC systems, forcing heat pump and chiller redesigns. Shipowners operating European routes must specify compatible thermal equipment or face port access restrictions. Cruise segments with heavy Mediterranean and Baltic deployment are accelerating specification changes ahead of 2027 phase-down milestones.
Shipyard direct procurement is consolidating vendor relationships as Korean builders bundle thermal systems into integrated machinery packages. Traditional marine equipment distributors are losing position to fabricators with localized production and naval certification depth. This consolidation is most visible in Ulsan, where Hyundai Heavy Industries and Samsung Heavy Industries have reduced qualified heat exchanger suppliers to three-tier certification tiers.
Ship Heat Exchanger Market Segmentation
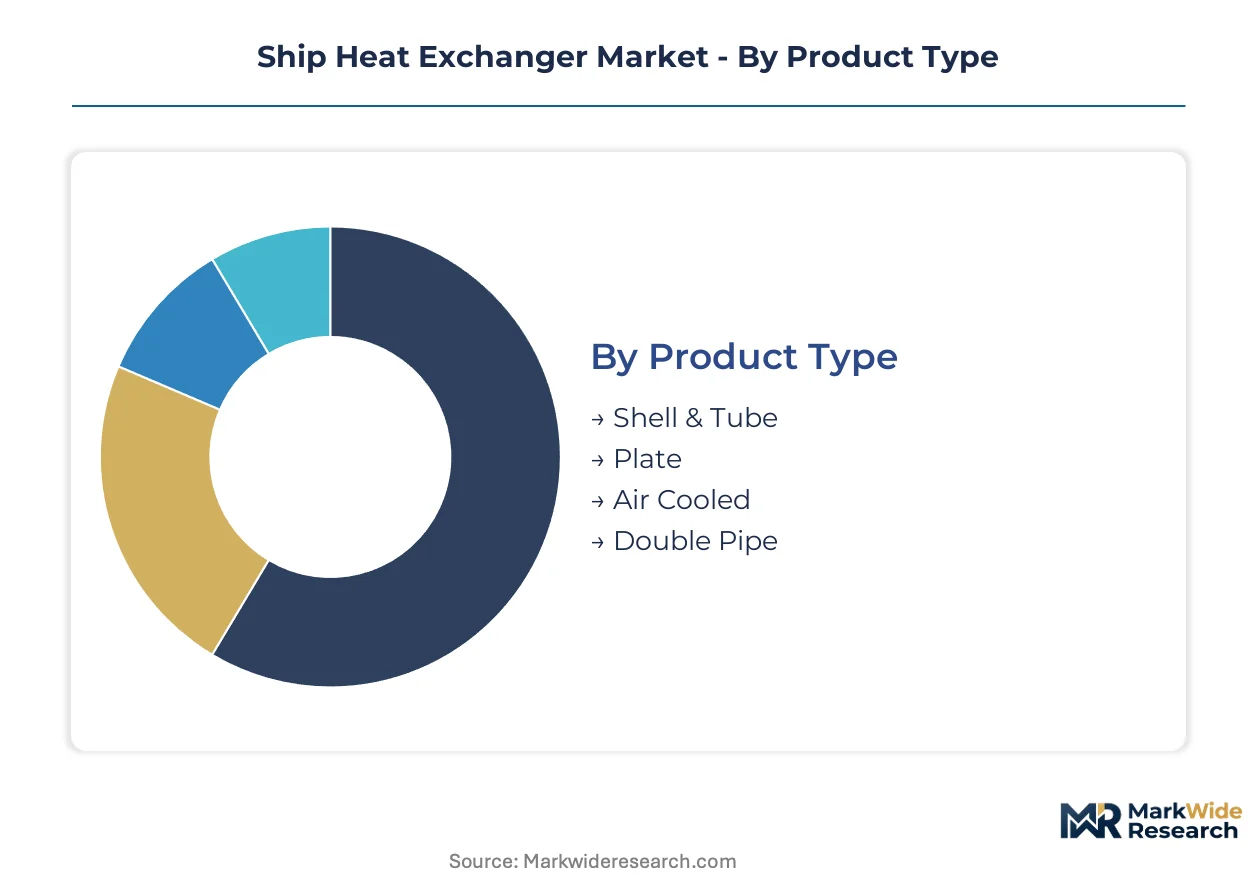
Segmentation in ship heat exchangers reveals how material substitution pressures and regulatory mandates reshape procurement patterns across vessel types. Product architecture, application duty, material grade, and end-user certification requirements each create distinct competitive battlegrounds with diverging margin structures.
Product Type:
Plate configurations face the most intense substitution pressure as additive manufacturing decomposes traditional fabrication constraints on titanium manifolds.
- Shell & Tube:Cylindrical pressure vessel designs with tube bundles handle main engine lubricating oil cooling above 16 bar ratings. Korean shipyards at Geoje specify these for LNG carrier propulsion systems where pressure integrity overrides footprint concerns.
- Plate:Corrugated metal plates in stacked configurations maximize surface area density for space-constrained machinery rooms. Scandinavian cruise operators prioritize these for HVAC and fuel preheating duties where thermal efficiency offsets premium unit cost.
- Air Cooled:Finned-tube arrays eliminate seawater dependency for auxiliary cooling circuits in chemical tankers. Deployed where corrosion risk or port water quality restrictions complicate wet cooling.
- Double Pipe:Concentric tube arrangements serve low-flow, high-temperature differential applications like fuel oil heaters. Favored in retrofit installations where piping modifications must minimize.
Shell & Tube anchors the volume base while Plate gains share at the steepest rate.
Application:
Cost tier stratification separates commoditized auxiliary cooling from premium-specification biological treatment systems.
- Marine Propulsion:Main and auxiliary engine cooling circuits demand pressure-rated designs with Lloyd's Register welding certification. Korean LNG carrier newbuilds concentrate procurement for dual-fuel engine thermal management.
- HVAC:Climate control systems face EU F-Gas Regulation redesign pressure as hydrofluorocarbon refrigerants phase down. Mediterranean cruise routes accelerate specification changes ahead of port access restrictions.
- Ballast Water Treatment:IMO biological standards mandate titanium-grade heat exchangers resistant to chlorinated seawater. Retrofit installations across international fleets displace legacy copper-nickel alloys.
- Refrigeration:Cargo hold cooling for reefers and fish carriers operates at lower pressure differentials. Specified primarily by shipping companies with specialized temperature-controlled logistics.
Marine Propulsion commands the revenue concentration while Ballast Water Treatment expands most quickly.
Material:
Supply concentration in titanium sponge production creates margin volatility that reshapes material selection economics.
- Stainless Steel:Austenitic and duplex grades balance corrosion resistance with fabricability for general seawater service. Dominates HVAC and auxiliary cooling where chloride exposure remains moderate.
- Copper:Copper-nickel alloys retain legacy position in older fleet cooling circuits. IMO biological treatment standards are accelerating displacement by titanium in ballast water applications.
- Titanium:Seawater-grade titanium sheet withstands 32°C inlet temperatures and aggressive chlorination regimes. Specified for ballast water treatment and chemical tanker duties where material longevity justifies cost premium.
- Carbon Steel:Low-alloy constructions serve closed-loop fresh water cooling with corrosion inhibitors. Lowest cost option for land-based test facilities and non-marine industrial applications.
Stainless Steel maintains the broadest deployment base while Titanium climbs the fastest.
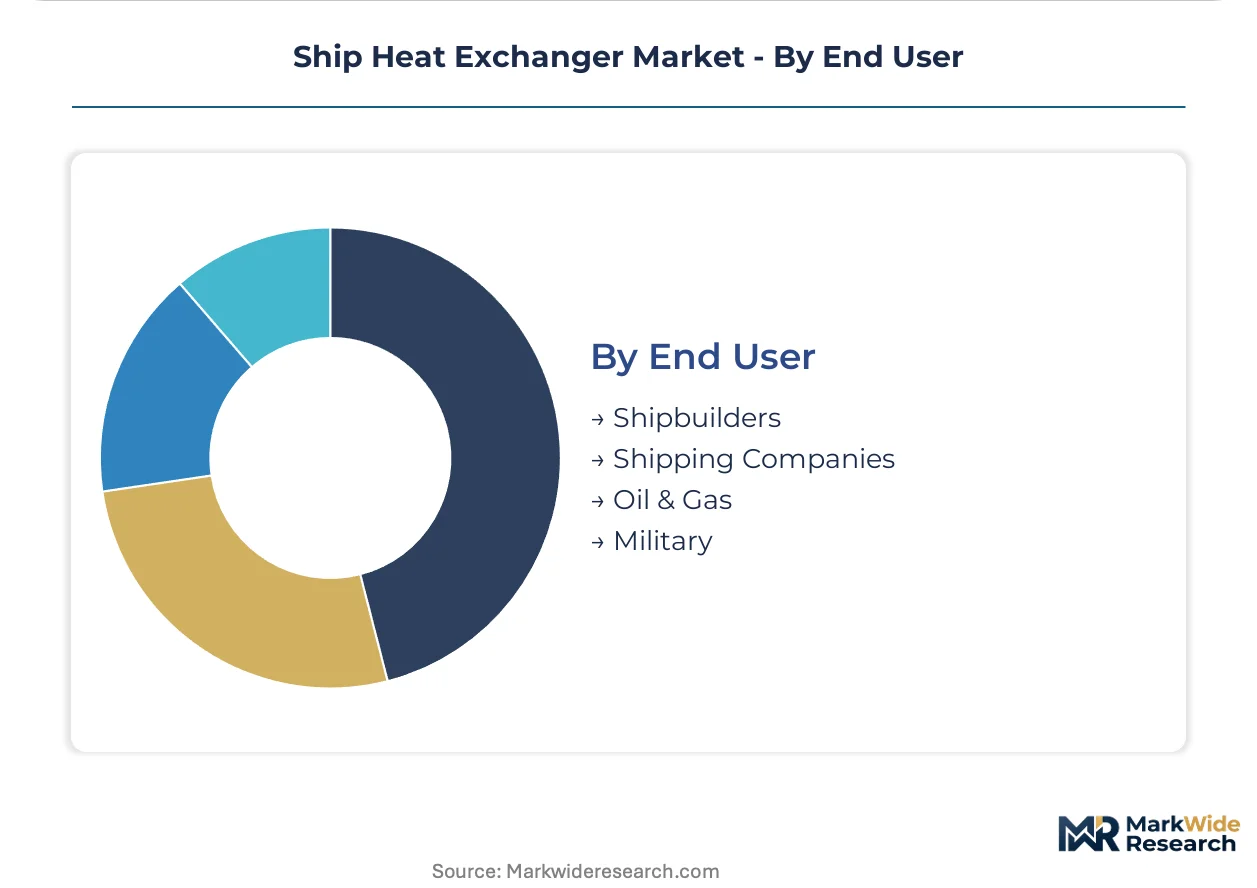
End User:
Customer type determines certification depth requirements and procurement channel structure.
- Shipbuilders:Korean yards at Ulsan bundle thermal systems into integrated machinery packages with three-tier supplier certification. Direct procurement consolidation reduces distributor role.
- Shipping Companies:Fleet operators drive retrofit demand under IMO CII compliance pressure. Specify higher-efficiency equipment ahead of historical replacement cycles to avoid operational penalties.
- Oil & Gas:Offshore platform support vessels and FPSO thermal systems require ASME U-stamp and API compliance. Specialized graphite and silicon carbide solutions target corrosive production fluid duties.
- Military:Naval certification programs demand traceable material documentation and qualified welding procedures. Procurement flows through defense contractors with established security clearances.
Shipbuilders capture the procurement volume concentration while Shipping Companies generate the steepest retrofit expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shipbuilders and fleet operators cluster procurement decisions around three dominant geographies. Korean yards bundle thermal systems into integrated machinery packages. Scandinavian engineering heritage anchors premium-specification demand. Chinese commercial shipbuilding scales auxiliary cooling procurement for bulk carrier and container programs.
South Korea
LNG carrier newbuild programs at Geoje and Ulsan drive concentrated heat exchanger procurement for liquefaction duty. MFDS certification requirements govern marine equipment qualification alongside Lloyd's Register welding standards. Hyundai Heavy Industries and Samsung Heavy Industries have consolidated qualified suppliers to three-tier certification tiers at their Ulsan complexes.
Norway
Cruise and ferry operators prioritize high-efficiency plate configurations for space-constrained machinery rooms. EU F-Gas Regulation accelerates HVAC system redesigns ahead of 2027 phase-down milestones. Norwegian cruise operators pilot additive manufacturing for topology-optimized titanium manifolds in Bergen and Oslo maritime clusters.
China
Commercial shipbuilding at Dalian and Shanghai scales auxiliary cooling procurement for bulk carrier and container segments. MEE environmental standards tighten material traceability for ballast water treatment system components. Jiangnan Shipyard and CSSC facilities in Shanghai concentrate demand for stainless steel heat exchanger architectures.
Germany
Specialized chemical tanker and offshore support vessel fabricators specify corrosion-resistant solutions for North Sea and Baltic routes. REACH compliance governs material sourcing disclosure for European-flagged fleet equipment. Hamburg and Bremen harbor industrial zones anchor procurement for dual-fuel engine thermal management systems.
United States
Offshore platform support vessels and Jones Act-compliant tankers drive demand for ASME U-stamp certified equipment. EPA ballast water discharge standards mandate biological treatment system retrofits across coastal fleets. Gulf Coast shipyards at Pascagoula and Houston concentrate procurement for deepwater production vessel thermal systems.
Ship Heat Exchanger Market Vendor Landscape
Player mix skews toward engineering-intensive specialists with certification depth rather than diversified industrial conglomerates. Market structure exhibits tiered consolidation with Scandinavian and Korean fabricators anchoring premium supply relationships. Two strategic archetypes dominate: heritage engineering houses leveraging ASME and Lloyd's Register qualification depth, and localized producers embedding directly into shipyard procurement channels. Competitive moves center on additive manufacturing capability acquisition and naval certification program expansion.
Among European heritage engineering houses, Alfa Laval Mid Europe and Mersen occupy positions exemplifying certification-driven competitive advantage. DongHwa Entec represents the localized producer archetype with Korean shipyard integration. ETB Energietechnik Bremen GmbH anchors German industrial fabricator positioning for chemical tanker and offshore applications.
| Leading Market Players |
|---|
| Alfa Laval Mid Europe |
| ETB Energietechnik Bremen GmbH |
| Mersen |
| DongHwa Entec |
| E. J. Bowman |
| Blokland Non-ferro |
| Pomar Water |
| Teknotherm |
| Vineta |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at Korean titanium sponge refineries shapes both supply concentration and price floors for seawater-grade sheet. ASME U-stamp certification depth at Geoje and Ulsan shipyards creates tiered procurement power, compressing margins for non-certified fabricators while sustaining premium capture for heritage engineering houses.
Pricing Analysis
Cost-plus contracts with London Metal Exchange titanium sponge indexation dominate procurement for LNG carrier programs. Three-tier pricing structure across premium, standard, and economy levels separates Lloyd's Register-certified fabricators from ISO 9001-only suppliers and uncertified aftermarket providers. Cost compression in standard-grade stainless steel architectures is intensifying because Chinese commercial shipbuilding scales auxiliary cooling procurement. Shipping companies with retrofit-driven fleet specifications exhibit highest price sensitivity; naval certification programs show lowest.
Supply Chain Analysis
Inventory lead times for seawater-grade titanium sheet extend 18-24 weeks when aerospace demand spikes compete for sponge allocation. Supply concentrates in Japan, Russia, and Kazakhstan for titanium sponge feedstock; South Korea and China for fabrication. Raw material dependencies include titanium sponge, duplex stainless steel billet, and graphite precursor for specialized chemical tanker solutions. Single-source vulnerability runs through Kobe Steel and VSMPO-AVISMA for aerospace-grade sponge diversion. Distribution runs through shipyard direct procurement channels with declining distributor role.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents early-cycle expansion as IMO 2023 carbon intensity regulations force specification upgrades ahead of historical replacement cycles. Ballast water treatment retrofits and LNG carrier newbuild programs create durable demand tailwinds.
For Market Incumbents: Compound certification depth advantage by acquiring additive manufacturing capability for topology-optimized titanium manifolds. Expand Lloyd's Register welding qualification programs to capture naval retrofit demand. Vertical integration into titanium sponge offtake agreements defends margin position against aerospace competition for seawater-grade sheet. For New Entrants and Emerging Players: Differentiate on graphite and silicon carbide solutions for corrosive chemical tanker applications where heritage fabricators lack specialized ceramic expertise. Target German offshore support vessel fabricators in Hamburg and Bremen with REACH-compliant material sourcing disclosure. Pursue EU Green Deal carbon border adjustment certification to access European-flagged fleet procurement. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors engineering-intensive specialists with ASME U-stamp and naval certification depth over diversified industrial conglomerates. Long-term viability rests on additive manufacturing capability acquisition and shipyard direct procurement channel embedding. Watch Korean shipyard supplier consolidation at Ulsan as inflection indicator for tier compression.| Strategic Initiative | Industry Significance |
|---|---|
| Additive Manufacturing Capability Acquisition | Norwegian cruise operators pilot topology-optimized titanium manifolds for space-constrained machinery rooms. |
| Naval Certification Program Expansion | Defense contractors with established security clearances capture procurement for traceable material documentation. |
| Titanium Sponge Offtake Agreements | Long-term supply contracts hedge against aerospace demand spikes compressing seawater-grade sheet margins. |
| EU Green Deal Certification Investment | European-flagged fleets face material sourcing disclosure requirements creating advantage for EU-based fabricators. |
| Digital Twin Integration Development | Thermal monitoring sensors with predictive maintenance platforms enable performance-based service contracting. |
Methodological Framework
A spread of perspectives from shipyard procurement managers, marine engineering consultants, classification society surveyors, and titanium alloy suppliers converged on the working assumptions. Primary interviews combined with secondary validation from Lloyd's Register technical bulletins, ASME Section IX welding qualification records, and Korean shipyard annual procurement disclosures. Customs data from Japan, Russia, and Kazakhstan tracked titanium sponge trade flows. Bottom-up vessel installation counts triangulated against top-down shipbuilding orderbook values.
Segmentation dimensions modeled include product architecture, application duty, material grade, and end-user certification requirements across the projection horizon. CAGRs derived from regression analysis of historical installation patterns against regulatory mandate timelines. Industry-specific forecast inputs incorporated IMO CII compliance penalty schedules and EU F-Gas Regulation phase-down milestones for hydrofluorocarbon refrigerants.
The analysis sits within stated boundaries; outcomes outside sustained Korean LNG carrier newbuild rates or titanium sponge supply stability would require recalibration. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and shipowner retrofit expenditure willingness. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine
Global Submarine Market
Marine
Marine Fasteners Market
Marine
LNG Bunkering Vessel Market
Marine
Marine Dynamic Positioning System Market
Marine
Hydrogen Ships Market
Marine
Electric Ship Market
Marine
Marine Spreader Lights Market
Marine
Ship Rudders Market
Marine
Boat Ladder Market
Marine
Sailboat Propellers Market
Marine
Marine Engine Cooling Systems Market
Marine
Boat Cleat Market
Marine
Marine LED Lights Market
Marine
Global Maritime Information Market
Marine
Marine Fender Systems Market
Marine
Marine Electronics Market