
 Camshaft Lifters Market | 2026-2036
Camshaft Lifters Market Size, Share, and Industry Trends Forecast 2026-2036
Camshaft Lifters Market Outlook
Modular valvetrain kits bundling lifters with pushrods and rocker arms is expanding buyer choice across both OEM and aftermarket channels. Schaeffler leverages its integrated manufacturing footprint to supply hydraulic lifter modules directly to European and Asian automakers. BorgWarner anchors its position through R&D intensity in roller lifter friction reduction for turbocharged engines. Tenneco competes on geographic dominance, operating dedicated lifter production facilities across multiple continents to serve regional OEM just-in-time requirements.
Camshaft lifters are precision-engineered cylindrical components that transmit motion from the camshaft lobe to the pushrod or valve stem, maintaining precise valve timing through hydraulic self-adjusting clearance compensation or fixed mechanical tolerances depending on design type. These components serve the essential industrial purpose of eliminating valve lash, reducing noise, and optimizing engine breathing efficiency across internal combustion powertrains. Hydraulic lifters dominate OEM installations due to their maintenance-free operation and emissions compliance advantages, while roller lifters capture the fastest growth trajectory among performance tuners seeking reduced friction and higher RPM capability. Solid lifters retain a mature but stable position in racing and specialized commercial applications where precise manual adjustment outweighs convenience priorities.
EPA tailpipe emissions standards and NHTSA corporate average fuel economy mandates directly shape OEM lifter specifications by requiring tighter valve control for optimized combustion phasing. ISO 9001 and IATF 16949 quality frameworks govern supplier qualification, creating market access barriers for uncertified manufacturers seeking tier-one automotive contracts. Stakeholders must monitor the pace of hybrid powertrain penetration and its impact on camshaft-driven valvetrain architectures versus camless or electromechanical alternatives.
Market Dynamics
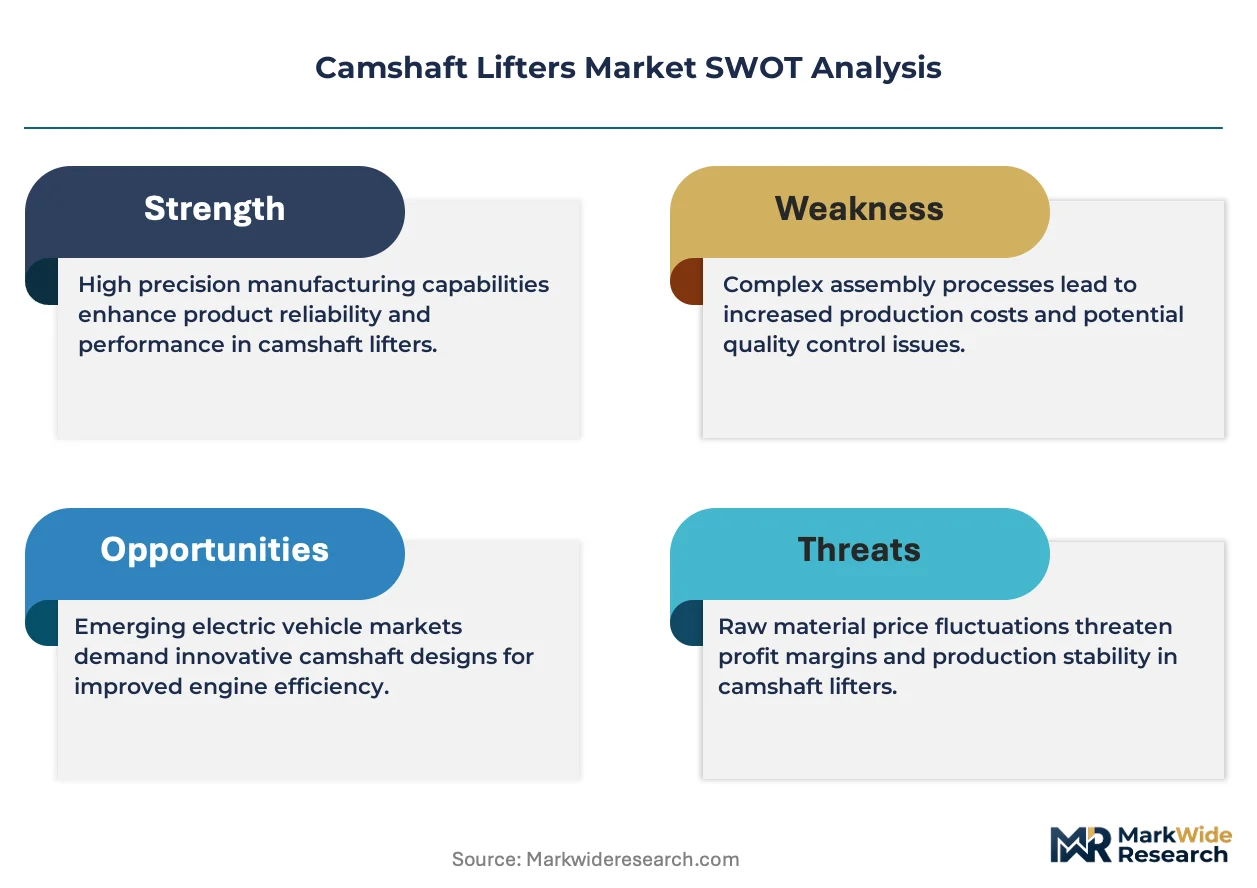
EPA tailpipe emissions standards and NHTSA corporate average fuel economy mandates are compressing valve lash tolerances across OEM lifter specifications, forcing hydraulic self-adjusting designs into tighter combustion control architectures.
Growth Catalysts
- EPA Tier 3 Emissions Standards:Tighter nitrogen oxide limits compel automakers to specify precision hydraulic lifters that eliminate valve timing variation and optimize exhaust gas recirculation efficiency.
- Performance Tuner Segment Expansion:Enthusiast builders upgrading V8 and forced-induction powertrains are sourcing roller lifter kits for reduced friction and extended high-RPM durability.
- Modular Valvetrain Kits:Bundled lifter-pushrod-rocker assemblies are streamlining aftermarket procurement decisions across both professional installers and DIY channels.
Market Restraints
- Alloy Steel Input Volatility:Chrome-molybdenum billet pricing fluctuations directly compress margin structures for precision-ground roller lifter manufacturers.
- Supply Concentration in Midwestern United States:Domestic forging and heat-treatment capacity clusters create geographic vulnerability to regional logistics disruptions.
- Electromechanical Valve Actuation:Camless valvetrain architectures under development by several powertrain engineering groups threaten long-term displacement of camshaft-driven lifter systems in hybrid applications.
Strategic Opportunities
- Underpenetrated Mexican Aftermarket:Growing vehicle parc and limited local precision component manufacturing create import substitution potential for US-based lifter suppliers.
- IRA Clean Vehicle Tax Credits:Domestic content requirements for assembled powertrains incentivize reshoring of lifter production to qualify for consumer rebate eligibility.
- Additive Manufacturing Convergence:Binder-jet metal printing of complex hydraulic piston geometries is unifying rapid prototyping with low-volume production flexibility.
Industry Challenges
- IATF 16949 Certification Timelines:New supplier qualification periods extending 18-24 months delay market entry for emerging manufacturers targeting tier-one OEM contracts.
- Metrology Skill Scarcity:Precision grinding and surface finish inspection expertise is concentrating among aging specialist workforces without adequate replacement pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Camshaft Lifters Market |
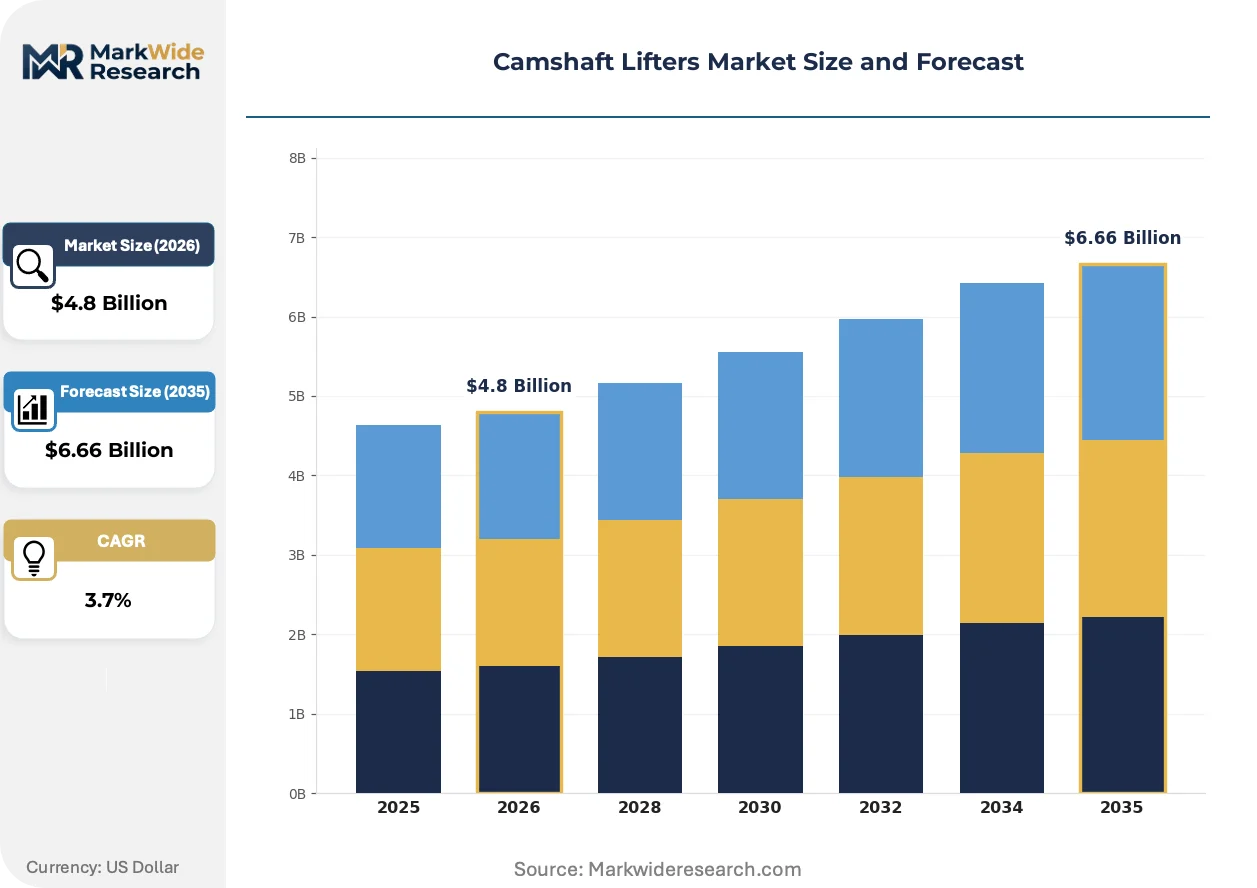
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Lifters, Solid Lifters, Roller Lifters, Pneumatic Lifters Material: Steel, Aluminum, Composite, Cast Iron End User: OEMs, Aftermarket Providers, Repair Shops, Performance Tuners Vehicle Type: Passenger Vehicles, Commercial Vehicles, Motorcycles, Off-road Vehicles |
| Companies Covered | Aisin Seiki, BorgWarner, Eaton, Rane Holdings Limited, Schaeffler, Tenneco, Comp Cams, Hyundai Kefico, Schrick GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Camshaft Lifters Market Strategic Shifts
Diamond-like carbon coatings and additive manufacturing are converging with regulatory pressure on combustion efficiency to reshape lifter surface engineering and production economics.
Modular hydraulic lifter cartridges integrating self-contained metering valves and pressure-balanced pistons are unifying multiple discrete components into single replaceable units. OEM powertrain engineers specify these modules to reduce assembly line complexity and warranty exposure. This unification is compressing supplier margins on standalone lifter sales while elevating contract values for integrated system providers.
EPA greenhouse gas standards for light-duty vehicles are mandating valve event optimization that exceeds mechanical fixed-clearance lifter capability. Hydraulic roller lifters with reduced internal leakage paths are displacing flat-tappet designs in turbocharged direct-injection engines. Tier-one suppliers are responding by dedicating R&D capacity to low-friction needle bearing architectures that satisfy both durability and emissions test cycles.
Performance enthusiasts are consolidating purchases through specialized e-commerce platforms that aggregate specifications, dyno validation data, and installation guidance. Traditional warehouse distributors are losing share to direct-to-builder channels that bypass counter staff and deliver technical content through video documentation. This channel rotation is most visible in the United States, where domestic V8 engine culture sustains substantial aftermarket volume and information-seeking behavior.
Camshaft Lifters Market Segmentation
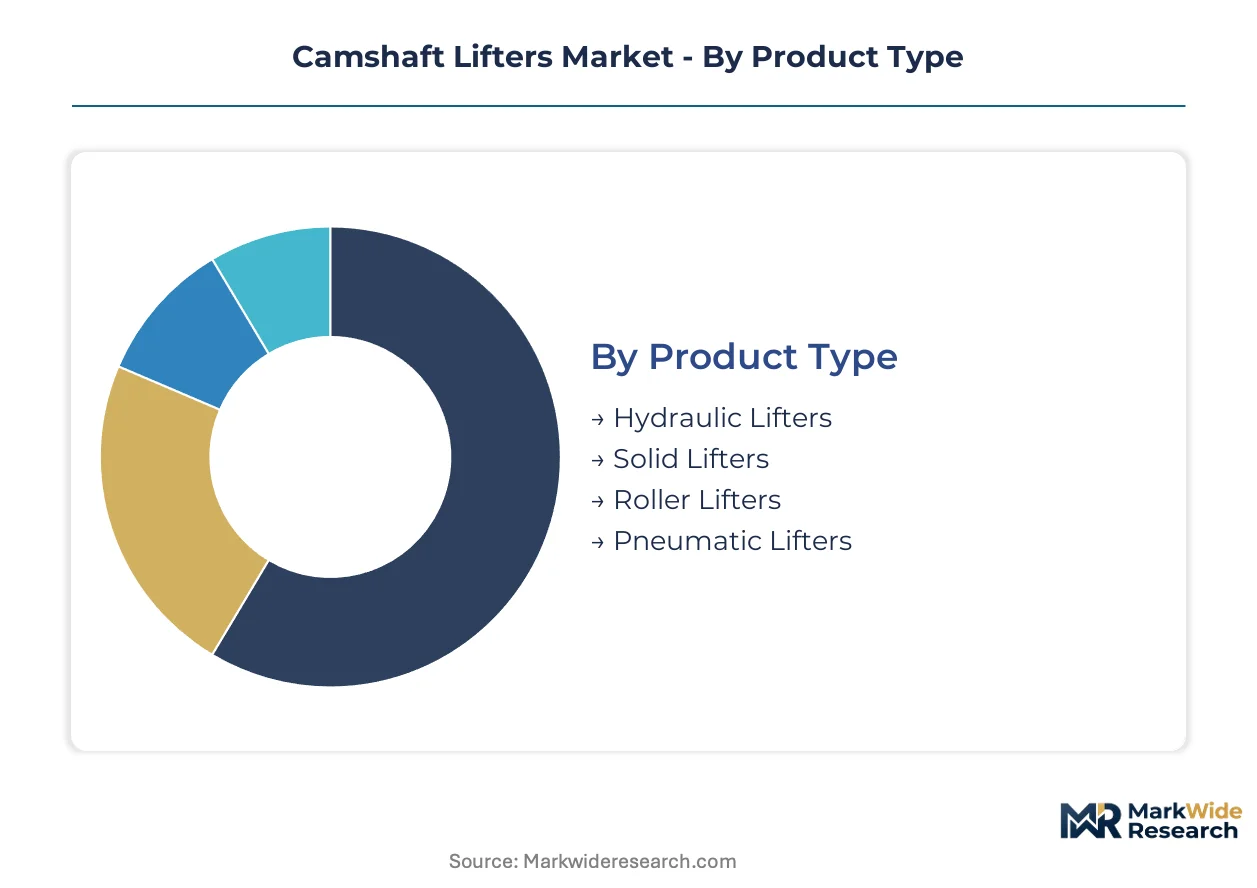
Segmentation in camshaft lifters reveals distinct procurement patterns between integrated powertrain contracts and standalone aftermarket replacement. Material specifications and valve actuation architectures vary sharply across OEM compliance requirements versus performance tuner customization priorities.
Product Type:
Hydraulic lifters dominate as embedded self-adjusting systems within OEM valvetrain modules, while mechanical alternatives serve standalone replacement and racing applications.
- Hydraulic Lifters:Self-adjusting cylindrical assemblies utilizing pressurized engine oil to maintain zero valve lash automatically. EPA Tier 3 emissions compliance in the United States compels automakers to specify these for precise combustion phasing and exhaust gas recirculation efficiency.
- Roller Lifters:Needle-bearing equipped cylinders that reduce friction against camshaft lobes through rolling contact rather than sliding. Performance tuners upgrading forced-induction V8 builds in the United States source these for sustained high-RPM durability and reduced valvetrain wear.
- Solid Lifters:Fixed-clearance mechanical components requiring periodic manual adjustment via shims or screw mechanisms. Racing teams and specialized commercial operators accept the maintenance burden for absolute timing precision.
- Pneumatic Lifters:Compressed-air actuated valve control systems experimental in prototype camless architectures. Development programs at several European powertrain engineering groups evaluate these for hybrid powertrain integration.
Volume placements concentrate in hydraulic lifters; the faster expansion belongs to roller lifters.
Material:
Material selection tracks directly against friction reduction targets, thermal load tolerance, and unit cost constraints across production scale tiers.
- Steel:Chrome-molybdenum alloy billet dominates roller lifter bodies for strength under Hertzian contact stress. Midwestern United States forging clusters supply this grade to precision grinding operations serving domestic OEM and aftermarket channels.
- Aluminum:Lightweight alloy hydraulic piston construction reduces reciprocating mass in high-RPM passenger car engines. Japanese and German automakers specify aluminum pistons within integrated lifter cartridges for turbocharged direct-injection architectures.
- Composite:Polymer-matrix bearing surfaces and coatings emerging in experimental low-friction applications. Limited commercial deployment concentrates in motorsport prototyping where weight reduction outweighs durability concerns.
- Cast Iron:Traditional material for flat-tappet lifters in mature pushrod V8 production. Declining specification share reflects displacement by roller and hydraulic alternatives in new engine programs.
Steel commands the highest unit placement volumes; aluminum is gaining share fastest in next-generation integrated modules.
End User:
End user segmentation separates consolidated procurement through vehicle manufacturer supply chains from fragmented aftermarket demand patterns.
- OEMs:Tier-one powertrain divisions and engine manufacturing joint ventures sourcing lifters through multi-year blanket purchase agreements. NHTSA corporate average fuel economy mandates drive specification of precision hydraulic modules with reduced internal leakage.
- Aftermarket Providers:Warehouse distributors and e-commerce platforms aggregating lifter sales alongside complementary valvetrain hardware. United States V8 engine culture sustains substantial catalog depth for domestic pushrod applications.
- Repair Shops:Professional installers performing valvetrain service on aging vehicle parc. Mexican aftermarket growth is expanding import demand for US-manufactured replacement lifters.
- Performance Tuners:Enthusiast builders and racing teams seeking upgraded components for modified powertrains. Direct-to-builder e-commerce channels are displacing traditional counter distribution for this specification-intensive segment.
Procurement value concentrates with OEMs; performance tuners are expanding most quickly as a customer class.
Vehicle Type:
Vehicle architecture determines valvetrain complexity, duty cycle severity, and replacement frequency across application categories.
- Passenger Vehicles:Light-duty cars and light trucks comprising the core volume base for hydraulic lifter specifications. Turbocharged direct-injection gasoline engines in this class require low-friction roller hydraulic designs to meet EPA greenhouse gas standards.
- Commercial Vehicles:Heavy-duty diesel and gasoline powertrains in trucking and vocational applications. Extended service intervals and severe thermal cycling drive demand for hardened steel roller lifters with premium surface coatings.
- Motorcycles:Compact single and multi-cylinder engines with overhead cam or pushrod architectures. Niche specification volumes concentrate in cruiser and touring segments with traditional air-cooled V-twin designs.
- Off-road Vehicles:Agricultural, construction, and recreational equipment engines subject to dust contamination and irregular maintenance. Solid lifter retention is highest in this category where mechanical simplicity outweighs emissions optimization.
Passenger vehicles anchor absolute unit demand; commercial vehicles show the steepest specification upgrade trajectory for durability-rated components.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Mexico and domestic content incentives under the US Inflation Reduction Act are redrawing manufacturing footprints. EPA emissions mandates and NHTSA fuel economy rules continue compressing valve lash tolerances across North American supply chains.
United States
Domestic V8 engine culture sustains substantial aftermarket procurement through specialized e-commerce platforms. EPA Tier 3 nitrogen oxide limits compel automakers to specify precision hydraulic lifters for optimized exhaust gas recirculation. Midwestern forging clusters in Ohio and Michigan supply chrome-molybdenum billet to precision grinding operations serving both OEM and aftermarket channels.
Germany
Integrated powertrain engineering groups drive specification of low-friction needle bearing architectures for turbocharged direct-injection gasoline engines. EU Green Deal emissions targets and the F-Gas Regulation pressure combustion efficiency optimization beyond mechanical fixed-clearance lifter capability. Baden-Württemberg and Bavaria host tier-one supplier R&D facilities developing modular hydraulic lifter cartridges for European automakers.
China
Domestic automakers and joint ventures source hydraulic lifter modules for light-duty turbocharged gasoline engines amid MIIT fuel consumption standards. Dual carbon goals and GB standards for vehicle emissions accelerate displacement of flat-tappet designs. Yangtze River Delta manufacturing bases concentrate forging and heat-treatment capacity for regional OEM just-in-time requirements.
Japan
Lightweight aluminum hydraulic piston specifications dominate next-generation integrated lifter cartridges for high-RPM passenger car engines. METI energy efficiency guidelines and JIS quality frameworks govern supplier qualification for domestic and export powertrain contracts. Kanto and Chubu industrial corridors anchor precision component manufacturing for hybrid powertrain architectures.
Mexico
Growing vehicle parc and limited local precision component manufacturing create import substitution potential for US-based lifter suppliers. Nearshoring incentives under the USMCA trade agreement attract tier-one supplier production investments. Bajío Region and Nuevo León automotive corridors concentrate engine assembly operations driving regional procurement demand.
Camshaft Lifters Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across tiered supply positions. The vendor base spans integrated automotive suppliers with multi-product powertrain portfolios alongside dedicated valvetrain component manufacturers. Three archetypes dominate: diversified industrial groups with captive forging capacity, precision grinding specialists serving aftermarket channels, and regional fabrication houses supplying emerging market OEMs. Capacity expansion and backward integration into alloy steel billet sourcing represent the dominant competitive moves.
Within the diversified industrial tier, Schaeffler and BorgWarner exemplify integrated manufacturing footprints supplying hydraulic lifter modules directly to European, Asian, and North American automakers. Tenneco occupies a position emphasizing geographic dominance through dedicated lifter production facilities across multiple continents. Among focused specialists, Comp Cams represents the performance tuner channel through direct-to-builder distribution models.
| Leading Market Players |
|---|
| Aisin Seiki |
| BorgWarner |
| Eaton |
| Rane Holdings Limited |
| Schaeffler |
| Tenneco |
| Comp Cams |
| Hyundai Kefico |
| Schrick GmbH |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap precision grinding specialists in Ohio and Michigan anchor North American forging capacity, translating captive chrome-molybdenum billet access into pricing discipline against commodity-exposed competitors. Their geographic clustering near Midwestern heat-treatment facilities compresses logistics costs while alloy steel input volatility forces margin defense through long-term offtake contracts with domestic steel mills.
Pricing Analysis
Margin tightening in aftermarket roller lifter tiers reflects chrome-molybdenum pricing volatility and EPA-driven specification upgrades. Three-tier pricing structure across premium, standard, and economy levels separates diamond-like carbon coated racing components from OEM-grade hydraulic modules and entry-level flat-tappet replacements. Cost-down pressure on standard-grade hydraulic lifters accelerates because automakers consolidate procurement through integrated valvetrain cartridge contracts. Performance tuners exhibit the lowest price sensitivity, prioritizing dyno-validated durability over per-unit cost, while repair shops in price-sensitive emerging markets drive volume through economy-grade imports.
Supply Chain Analysis
Single-source vulnerability sits with Midwestern United States forging clusters that supply precision-ground billet to both domestic OEM channels and aftermarket grinding operations. Raw material flows draw from domestic chrome-molybdenum steel producers, Japanese needle bearing suppliers, and German surface coating specialists. Tariff exposure on alloy steel imports threatens margin structures for non-vertically integrated manufacturers lacking captive melting capacity. Distribution runs through tier-one supplier direct-to-OEM contracts, warehouse distributor networks serving repair shops, and specialized e-commerce platforms reaching performance tuner direct-to-builder channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical-integration momentum is accelerating as players pursue captive control over chrome-molybdenum billet supply to defend margin structures against alloy input volatility.
For Market Incumbents: To counter electromechanical valve actuation displacement threats in hybrid powertrains, deepen R&D allocation to low-friction hydraulic roller architectures and secure IATF 16949 certification renewal ahead of 18-24 month qualification windows. Capacity addition in Mexico's Bajío Region captures USMCA nearshoring incentives and IRA domestic content requirements for assembled powertrains. For New Entrants and Emerging Players: Capture underpenetrated Mexican aftermarket demand through direct import partnerships with US-based forging operations, leveraging limited local precision component manufacturing and growing vehicle parc. Specialist e-commerce platforms serving performance tuners offer the most penetrable channel, with video-based installation guidance displacing traditional counter distribution. For Investors and Strategic Acquirers: Distressed-cycle entries favor precision grinding specialists with captive heat-treatment capability in Ohio and Michigan industrial corridors, where aging specialist workforces without replacement pipelines create acquisition discounts. The signal to watch is additive manufacturing convergence timelines for low-volume hydraulic piston prototyping, indicating inflection points for production economics disruption.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alloy Steel Billet | Captive chrome-molybdenum supply from Midwestern forging clusters insulates margin structures against commodity volatility. |
| Modular Hydraulic Lifter Cartridge Development | Integrated self-contained metering valves reduce OEM assembly complexity and compress standalone lifter supplier margins. |
| Mexican Manufacturing Footprint Expansion | USMCA trade agreement incentives and IRA domestic content rules attract tier-one production investments to Bajío Region. |
| Diamond-Like Carbon Coating Scale-Up | Surface engineering advances from German R&D facilities satisfy EPA greenhouse gas standards for friction reduction. |
| Direct-to-Builder E-Commerce Platform Launch | Video documentation and dyno validation data displace traditional warehouse distributors in United States V8 enthusiast channels. |
Study Parameters
Document review covered EPA Tier 3 regulatory filings, NHTSA corporate average fuel economy rulemakings, and IHS Markit vehicle production databases, complemented by interviews with tier-one supplier procurement managers, OEM powertrain platform engineers, aftermarket distributor category buyers, and precision grinding operation plant managers. Secondary validation drew from SEC 10-K disclosures of diversified industrial suppliers, trade customs data on alloy steel billet flows, and IATF 16949 certification registry records. Bottom-up unit demand modeling triangulated against top-down powertrain architecture forecasts.
Segmentation outputs across product type, material specification, end-user channel, and vehicle architecture fed into volume and value projections over the modeling period. CAGRs derived from regression analysis against historical powertrain production correlations, with specific weighting for turbocharged direct-injection penetration rates and EPA emissions compliance phase-in schedules. Hybrid powertrain valvetrain architecture displacement scenarios provided sensitivity bounds for long-range hydraulic lifter demand.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to electromechanical valve actuation commercialization timelines and alloy steel pricing volatility. Forecasts reflect assumptions around IATF 16949 certification maintenance, Midwestern forging capacity stability, and IRA domestic content rule durability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive Electric Vacuum Pump Market
Automotive Parts
Motorcycle Battery Chargers Market
Automotive Parts
Automotive Fastener Market
Automotive Parts
Africa Automotive Engine Oils Market
Automotive Parts
Europe Automotive Parts Zinc Die Casting Market
Automotive Parts
Automotive Piston Engine System Market
Automotive Parts
Automotive Evaporators and Blowers Market
Automotive Parts
North America Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Electric Parking Brakes Market
Automotive Parts
China Ceramic Ball Bearing Market
Automotive Parts
Sintered Silencer Market
Automotive Parts
Electric Coolant Pump Market
Automotive Parts
Saudi Arabia Automotive Lubricants Market
Automotive Parts
Automotive Seat Track Market
Automotive Parts
Japan Automotive Parts Zinc Die Casting Market
Automotive Parts
Philippines Passenger Vehicles Lubricants Market