
 Automotive Coolant Market | 2026-2036
Automotive Coolant Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Coolant Market Intelligence
Fleet operators and EV manufacturers are collapsing the traditional dominance of individual vehicle owners in coolant procurement volumes. ExxonMobil Corporation leverages its integrated refining base to secure feedstock cost advantages across ethylene glycol supply chains. BASF SE anchors its position through backward integration into specialty additive chemistry for hybrid organic acid technology formulations. Shell plc competes via its global lubricant distribution network that extends coolant reach into emerging market service bays.
Automotive coolant is a heat-transfer fluid formulated from glycol bases, corrosion inhibitors, and stabilizers, typically operating between minus thirty-seven degrees Celsius and one hundred eight degrees Celsius to regulate internal combustion and electric powertrain temperatures. Its primary purpose is preventing engine overheating, freeze damage, and galvanic corrosion in closed-loop cooling systems. Ethylene glycol formulations dominate volume due to established cost economics, though propylene glycol is gaining preference in applications requiring lower toxicity profiles. Long life coolant technology captures expanding margin pools as OEM service intervals stretch and thermal management complexity rises in electrified platforms.
The EPA regulates glycol disposal under hazardous waste protocols, while REACH restricts certain corrosion inhibitor chemistries in European formulations, collectively forcing reformulation investments across multinational suppliers. China's SAMR enforces GB standards on coolant boiling point and pH stability, creating compliance barriers for imported products. Stakeholders must monitor thermal conductivity specifications for direct battery cooling applications as EV architectures diverge from traditional engine-based thermal loops.
Market Dynamics
Electric vehicle thermal architectures are forcing a wholesale redesign of coolant chemistry specifications, as battery cooling loops demand dielectric properties and thermal conductivity profiles incompatible with traditional internal combustion formulations.
Growth Catalysts
- EPA Hazardous Waste Protocols:Stricter glycol disposal mandates in the United States accelerate demand for recyclable and biodegradable coolant formulations that reduce cradle-to-grave environmental liability.
- China SAMR GB Standards:Mandatory boiling point and pH stability requirements create compliance barriers that favor established suppliers with certified testing infrastructure.
- Direct Battery Cooling:EV manufacturers are specifying specialized coolants with enhanced dielectric strength and low electrical conductivity for immersion and cold plate applications.
Market Restraints
- Ethylene Glycol Feedstock Volatility:Crude oil and natural gas price swings transmit directly to glycol production costs, compressing margins for non-integrated blenders.
- REACH Corrosion Inhibitor Restrictions:ECHA limitations on certain chemistries force expensive reformulation cycles and eliminate legacy additive packages from European formulations.
- Propylene Glycol Performance Ceiling:Lower thermal conductivity and higher viscosity limit propylene glycol adoption in high-performance thermal management systems despite its toxicity advantages.
Strategic Opportunities
- India Automotive Production:Underpenetrated coolant service infrastructure and expanding domestic vehicle assembly create whitespace for packaged coolant-distribution partnerships.
- EU Green Deal Chemistry Incentives:Regulatory tailwinds favor bio-based glycol feedstocks and additive packages with verified carbon intensity reductions.
- Hybrid Organic Acid Technology Convergence:HOAT formulations combining organic acid corrosion protection with extended service intervals capture margin pools from conventional inorganic additive technology.
Industry Challenges
- Electrochemistry Skill Gap:Battery thermal management engineering requires coolant chemists to master dielectric property optimization and ionic contamination control unfamiliar to traditional automotive fluid formulators.
- Dual Certification Timelines:Simultaneous OEM approval for ICE and EV coolant specifications stretches validation resources and delays product commercialization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Coolant Market |
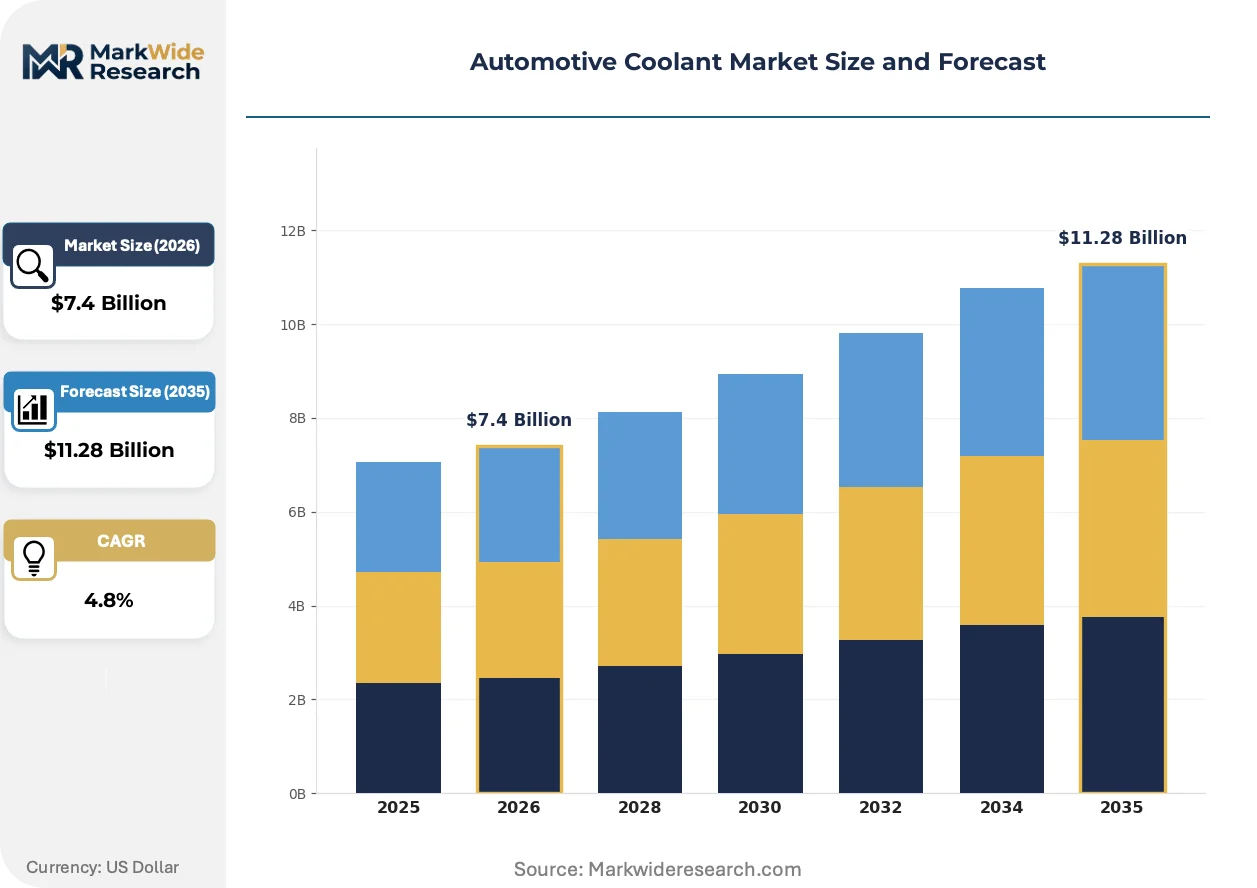
| Market Size in 2026 | $7.4 Billion |
| Market Size in 2035 | $11.28 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ethylene Glycol, Propylene Glycol, Hybrid Organic Acid Technology, Inorganic Acid Technology, Silicone-based Technology: Conventional Coolant, Long Life Coolant, Extended Life Coolant, Hybrid Coolant, Organic Acid Technology Application: Passenger Vehicles, Light Commercial Vehicles, Heavy Duty Vehicles, Two-wheelers End User: OEMs, Aftermarket Repair Shops, Vehicle Assemblers, Tier-1 Suppliers, Dealerships |
| Companies Covered | TotalEnergies SE, Prestone Products Corporation, ExxonMobil Corporation, FUCHS Petrolub SE, BP PLC, Shell plc, BASF SE, Old World Industries, Chevron Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Coolant Market Strategic Shifts & Innovations
Thermal management complexity in electrified platforms is fragmenting the historically unified coolant specification landscape into chemistry variants purpose-built for battery, power electronics, and motor cooling subsystems.
Dielectric coolant formulations engineered for direct battery contact are supplanting conventional glycol-water mixtures in EV architectures. Cell manufacturers and pack integrators specify fluids with electrical resistivity above 10^12 ohm-cm and thermal conductivity exceeding 0.15 W/m·K. This transition compresses addressable volume for traditional ethylene glycol suppliers while opening formulation partnerships between chemical specialists and battery OEMs.
REACH Annex XIV authorization requirements for certain boron- and amine-based corrosion inhibitors are eliminating established additive chemistries from European formulations. Compounders must validate replacement packages through accelerated corrosion testing protocols. Passenger vehicle OEMs with pan-European distribution face the steepest compliance burden, while commercial vehicle operators with regionalized fleets adapt more gradually.
Fleet procurement centralization is consolidating coolant purchasing authority away from individual service bays and owner-operators. Logistics operators and ride-hail platforms negotiate direct supply agreements with compounders, disintermediating traditional jobber and distributor channels. This concentration is most visible in North American long-haul trucking and European last-mile delivery segments where vehicle uptime contracts bundle fluid supply with preventive maintenance.
Automotive Coolant Market Segmentation
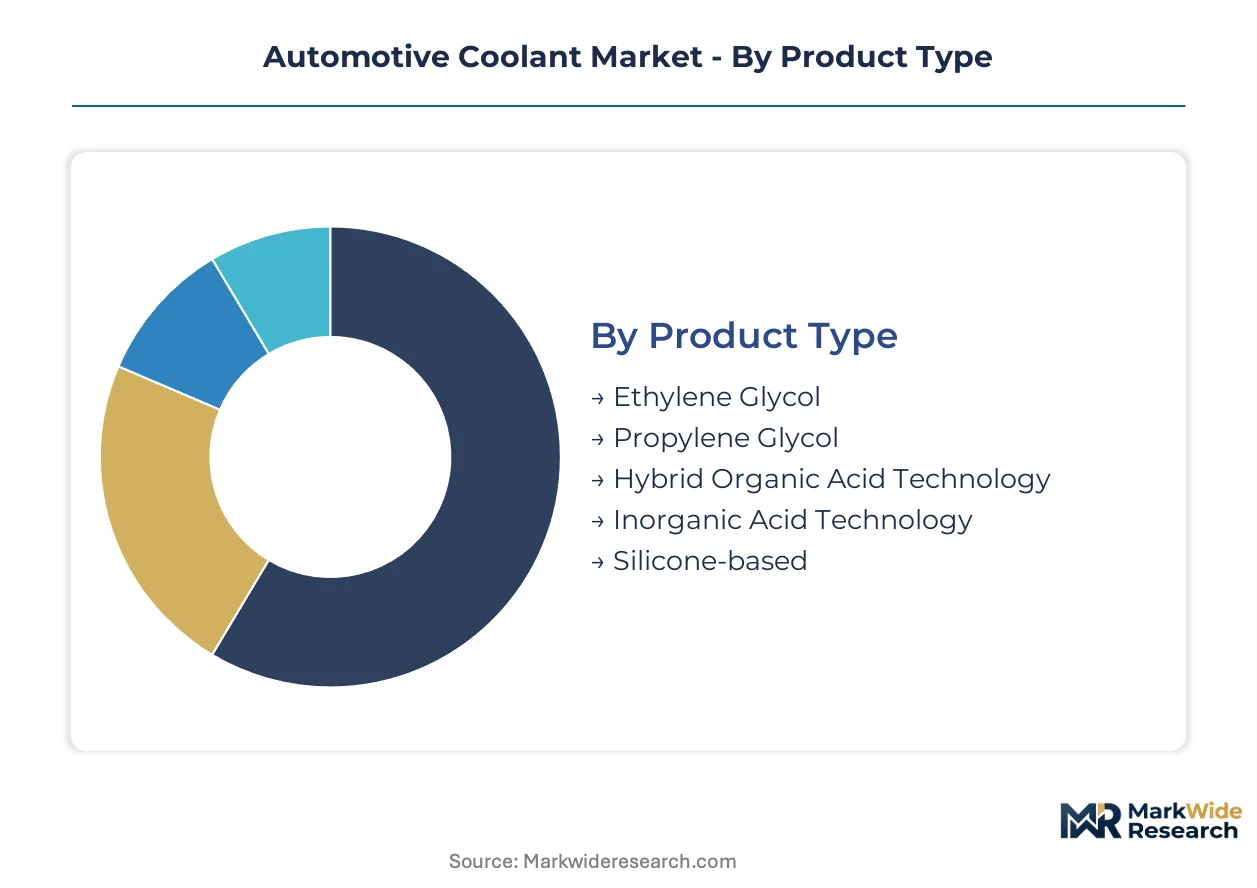
Automotive coolant segmentation reflects diverging thermal management requirements across electrified and combustion powertrains. Chemistry specifications fragment as battery cooling loops demand dielectric properties incompatible with traditional engine formulations.
Product Type:
EPA hazardous waste protocols and REACH chemical restrictions create divergent compliance burdens across glycol chemistries, reshaping regional formulation preferences.
- Ethylene Glycol:Dominant volume chemistry derived from petrochemical feedstocks with established cost economics and thermal conductivity profiles. ICE vehicle production in China and commercial fleet operations in the United States sustain procurement concentration despite toxicity handling requirements.
- Propylene Glycol:Lower toxicity alternative favored in applications with environmental discharge exposure or worker safety sensitivity. Food-grade processing equipment and marine cooling systems in the European Union drive adoption where REACH restrictions on hazardous substance handling apply.
- Hybrid Organic Acid Technology:Combines organic acid corrosion inhibitors with extended service intervals for modern aluminum engine architectures.
- Inorganic Acid Technology:Legacy formulation with silicate and phosphate packages for older cast-iron engine designs.
- Silicone-based:Premium thermal stability chemistry for extreme temperature aerospace and racing applications.
Established volume favors Ethylene Glycol; emerging adoption favors Hybrid Organic Acid Technology.
Technology:
Service interval extension and thermal management complexity drive margin differentiation across coolant lifecycle technologies.
- Long Life Coolant:Organic acid inhibitor packages deliver five-year or longer replacement cycles, reducing total cost of ownership for fleet operators. OEM service interval stretching in Germany and Japan concentrates demand as vehicle electrification raises thermal system replacement costs.
- Extended Life Coolant:Intermediate duration formulations balancing upfront cost against maintenance frequency for price-sensitive commercial segments.
- Conventional Coolant:Two-year replacement cycle products with inorganic additive packages dominate emerging market aftermarket channels.
- Hybrid Coolant:Transition chemistry bridging conventional and organic acid technologies for mixed fleet compatibility.
- Organic Acid Technology:Silicate-free formulations protecting aluminum radiators and water pumps in modern engine designs.
Fleet procurement concentrates on Long Life Coolant; price-sensitive aftermarket channels sustain Conventional Coolant.
Application:
Powertrain electrification fragments thermal management requirements across vehicle weight classes and duty cycles.
- Passenger Vehicles:Light-duty thermal systems with aluminum-intensive cooling circuits requiring HOAT-compatible chemistries. Battery electric production in China and hybrid platform launches in South Korea drive specialized coolant specification divergence.
- Heavy Duty Vehicles:High-thermal-load engines in long-haul trucking and construction equipment demand robust corrosion protection and extended drain intervals.
- Light Commercial Vehicles:Mixed urban delivery and highway service profiles with moderate thermal stress and standardized maintenance protocols.
- Two-wheelers:Air-cooled dominant designs with limited coolant penetration; liquid-cooled premium motorcycles in Italy and Japan represent niche demand.
Technology transition accelerates fastest in Passenger Vehicles; thermal load intensity sustains Heavy Duty specification premiums.
End User:
Procurement authority consolidation reshapes channel economics and volume concentration across the value chain.
- OEMs:Factory-fill specifications with direct compounder relationships and multi-year supply agreements. Electric vehicle startups in the United States and established automotive groups in Germany negotiate dielectric coolant partnerships for battery thermal architectures.
- Aftermarket Repair Shops:Fragmented service bay network dependent on distributor jobber relationships and brand recognition.
- Vehicle Assemblers:Contract manufacturing operations with specified coolant procurement tied to OEM technical requirements.
- Tier-1 Suppliers:Thermal system integrators specifying coolant compatibility for radiators, pumps, and heat exchangers.
- Dealerships:Authorized service networks with captive OEM-branded fluid programs and warranty compliance obligations.
Specification authority concentrates with OEMs; service volume concentrates with Aftermarket Repair Shops.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports specialized coolant formulations to automotive OEMs across Central and Eastern Europe, establishing a trade corridor that shapes regional supply patterns.
China
Domestic EV production and ICE vehicle assembly dominate procurement volumes. SAMR enforces GB standards on boiling point and pH stability, creating compliance barriers for imported products. Shanghai and Guangdong manufacturing clusters concentrate thermal management system integration for battery electric platforms.
Germany
Passenger vehicle OEM factory-fill specifications and commercial fleet operations drive demand concentration. REACH Annex XIV restrictions on boron-based corrosion inhibitors force reformulation investments across compounders. Bavaria and Baden-Württemberg host thermal system engineering centers developing dielectric coolant specifications.
United States
Long-haul trucking fleet procurement and aftermarket service bay networks sustain volume distribution. EPA hazardous waste protocols on glycol disposal accelerate demand for recyclable formulations. Michigan and Texas automotive corridors concentrate coolant blending capacity near assembly operations.
India
Expanding domestic vehicle assembly and underpenetrated service infrastructure create whitespace for packaged coolant partnerships. BIS certification requirements and state-level pollution control mandates shape product entry pathways. Maharashtra and Tamil Nadu manufacturing belts concentrate thermal component sourcing for emerging OEM platforms.
Japan
Hybrid platform thermal system complexity and extended service interval specifications drive premium formulation demand. METI industrial standards and JIS certification protocols govern coolant chemistry approvals. Kanto and Kansai industrial zones concentrate precision additive manufacturing for organic acid technology packages.
Automotive Coolant Market Key Industry Players
Listed leaders compete with private specialists across integrated refining and additive chemistry capabilities. The vendor base organizes around three tiers: multinational oil majors with captive ethylene glycol supply, specialty chemical compounders with backward integration into corrosion inhibitor packages, and regional blenders dependent on merchant feedstock purchases. Two strategic archetypes dominate competitive positioning—vertically integrated refiners securing feedstock cost advantages and technology-forward compounders capturing margin pools from extended-life formulations. M&A activity concentrates on additive technology acquisitions, while capacity expansion targets EV-specific dielectric coolant production.
Within the integrated oil major tier, ExxonMobil Corporation and Shell plc occupy positions defined by captive refining infrastructure and global lubricant distribution networks. BASF SE represents the specialty chemical archetype, anchoring its competitive stance through in-house production of organic acid additive packages. These three companies exemplify the structural divide between feedstock-driven and technology-driven competitive advantages in coolant formulation.
| Leading Market Players |
|---|
| TotalEnergies SE |
| Prestone Products Corporation |
| ExxonMobil Corporation |
| FUCHS Petrolub SE |
| BP PLC |
| Shell plc |
| BASF SE |
| Old World Industries |
| Chevron Corporation |
| Others |
Cost & Logistics Intelligence
Sixty-to-ninety-day ethylene glycol inventory cycles in non-integrated blending operations compress pricing power for merchant-dependent compounders while amplifying margin capture for refiners with captive feedstock supply. This lead-time asymmetry concentrates cost advantage with integrated oil majors and forces technology-driven pricing premiums from specialty additive producers.
Pricing Analysis
The technology-generation pricing gap separating conventional inorganic additive formulations from hybrid organic acid technology and emerging dielectric coolant chemistries widens as service intervals extend and thermal management complexity rises. Three-tier pricing structure across premium dielectric, standard HOAT, and economy conventional levels reflects certification grade and volume scale differentiation. Cost compression in conventional ethylene glycol blends intensifies because feedstock volatility transmits directly from crude oil and natural gas markets. Fleet procurement concentrates as the least price-sensitive segment due to uptime contracting, while fragmented aftermarket service bays exhibit highest sensitivity to per-liter differentials.
Supply Chain Analysis
Strategic stockpile preferences among integrated refiners contrast with just-in-time inventory management at regional blending operations dependent on merchant glycol purchases. Geographic supply concentration centers on China, the United States, and Germany as dominant production clusters for both petrochemical feedstocks and formulated coolants. Raw material dependencies rest on ethylene oxide, corrosion inhibitor additive packages, and specialized dielectric base fluids. Single-source vulnerability from concentrated additive chemistry suppliers in Germany and Japan threatens formulation continuity. Distribution runs through lubricant jobber networks, direct OEM factory-fill agreements, and emerging fleet procurement platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive coolant market functions as a service-attach opportunity where long-life formulation technology and thermal management system monitoring generate recurring revenue streams expanding faster than base fluid hardware sales.
For Market Incumbents: Fortify backward integration into specialty additive chemistry to defend margin pools from REACH-driven reformulation cycles and dielectric coolant specification divergence. Capture channel control through direct fleet procurement partnerships that disintermediate traditional distributor networks. Prioritize certification investment for dual ICE-EV OEM approval timelines stretching validation resources. For New Entrants and Emerging Players: Anchor in India's underpenetrated coolant service infrastructure where expanding domestic vehicle assembly outpaces established distribution coverage. Target packaged coolant partnerships with emerging OEM platforms in Maharashtra and Tamil Nadu manufacturing belts. Pursue dielectric coolant formulation alliances with battery OEMs seeking thermal management system integration partners. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compression play because EPA hazardous waste protocols and REACH chemical restrictions continuously eliminate legacy additive packages and force reformulation investment cycles. Acquisition candidates include specialty additive compounders with backward integration into organic acid technology and regional blenders positioned for EV-specific dielectric production scale-up. Watch for battery thermal architecture standardization across cell manufacturers as inflection indicator for dielectric coolant specification consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Additive Chemistry | REACH Annex XIV restrictions force in-house corrosion inhibitor production to control reformulation timelines. |
| Dielectric Coolant Capacity Expansion | Direct battery cooling specifications from EV manufacturers create first-mover advantage in thermal conductivity optimization. |
| Fleet Procurement Platform Partnerships | Long-haul trucking operators in the United States consolidate purchasing authority away from jobber channels. |
| Dual Certification Investment | Simultaneous OEM approval for ICE and EV specifications stretches resources but locks in factory-fill volume. |
| Green Feedstock Transition | EU Green Deal incentives favor bio-based glycol pathways with verified carbon intensity reductions. |
Research Approach
The analysis maps ethylene glycol, propylene glycol, hybrid organic acid technology, and dielectric coolant sub-sectors, each validated through procurement directors at fleet operators, thermal system engineers at battery OEMs, additive chemistry specialists, and aftermarket distribution managers. Primary interview intelligence triangulates against customs and trade data, SEC filings from integrated oil majors, EPA hazardous waste protocol documentation, and REACH Annex XIV substance restriction updates. Bottom-up volume modeling from vehicle production databases and top-down value estimates from compounder revenue disclosures converge through iterative reconciliation.
Consistency checks against external benchmarks validate volume and value outputs across the projection horizon. The analytical framework segments by chemistry type, technology generation, vehicle propulsion architecture, and end-user procurement channel. CAGRs derive from modeled adoption curves for extended-life formulations and dielectric coolant penetration in electrified platforms. Industry-specific inputs include thermal conductivity specification divergence across battery cooling architectures and service interval extension trends in OEM maintenance schedules.
Material uncertainties — crude oil and natural gas price volatility, REACH authorization timeline delays, battery thermal architecture standardization outcomes — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory enforcement intensity and EV production scaling. Revision becomes warranted when ethylene glycol feedstock cost swings exceed historical bands or dielectric coolant specification fragmentation accelerates beyond modeled scenarios.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Electromagnetic Clutches Market
Automotive Parts
UAE Automotive Lubricants Market
Automotive Parts
Global Automotive Damper Market
Automotive Parts
Automotive Electric Drive Axle Market
Automotive Parts
Global Automotive Closure Market
Automotive Parts
Electric Parking Brake Actuator Components Market
Automotive Parts
Australia Automotive Airfilters Market
Automotive Parts
Apron Bus Market
Automotive Parts
RV Gear Reducer Market
Automotive Parts
HCV Brake Components Market
Automotive Parts
Engine Bearings Market
Automotive Parts
Electric Vehicle Aluminum Electric Drive Parts Market
Automotive Parts
Automotive Crankcase Additives Market
Automotive Parts
Automotive Brake Wheel Cylinder Market
Automotive Parts
Transfer Case Market
Automotive Parts
India Automotive Lubricants Market