
 EGR Coolers Market | 2026-2036
EGR Coolers Market Size, Share, and Industry Trends Forecast 2026-2036
EGR Coolers Market Foresight
Aftermarket service revenue is narrowing as OEMs extend powertrain warranties and integrate longer-life cooler designs. BorgWarner Inc. leverages its turbocharger-EGR bundling relationships to lock in platform sourcing across European and North American truck programs. Mahle GmbH anchors its position through captive aluminum casting capacity and in-house vacuum brazing lines that control thermal fatigue margins. Denso Corporation competes on high-volume passenger car contracts where plate-fin miniaturization meets Japanese OEM packaging constraints.
EGR coolers are heat exchangers that reduce recirculated exhaust gas temperatures before reintroduction into the combustion chamber, typically operating between 150°C and 450°C with stainless steel or aluminum cores brazed under vacuum or controlled atmosphere. Their primary purpose is to lower NOx formation by enabling higher exhaust gas recirculation rates without compromising charge density or engine knock margins. Liquid-cooled configurations lead in heavy-duty applications where thermal loads exceed air-cooled capacity, while plate technology dominates light-duty automotive programs seeking packaging efficiency. The aftermarket segment shows structural expansion potential as commercial fleets extend vehicle lifecycles and replacement intervals compress under severe-duty cycles.
EPA Phase 2 standards in the United States, Euro VII proposals under EMA review, and China's Stage VI emissions enforcement through MEE collectively mandate lower NOx thresholds that expand EGR cooler duty cycles and material specifications. These frameworks force suppliers to validate cores for extended corrosion resistance and thermal cycling durability, raising barriers for non-integrated manufacturers. Stakeholders must monitor how Euro VII final test protocols and China's Stage VIb implementation timing reshape OEM thermal management architectures and supplier qualification windows.
Market Dynamics
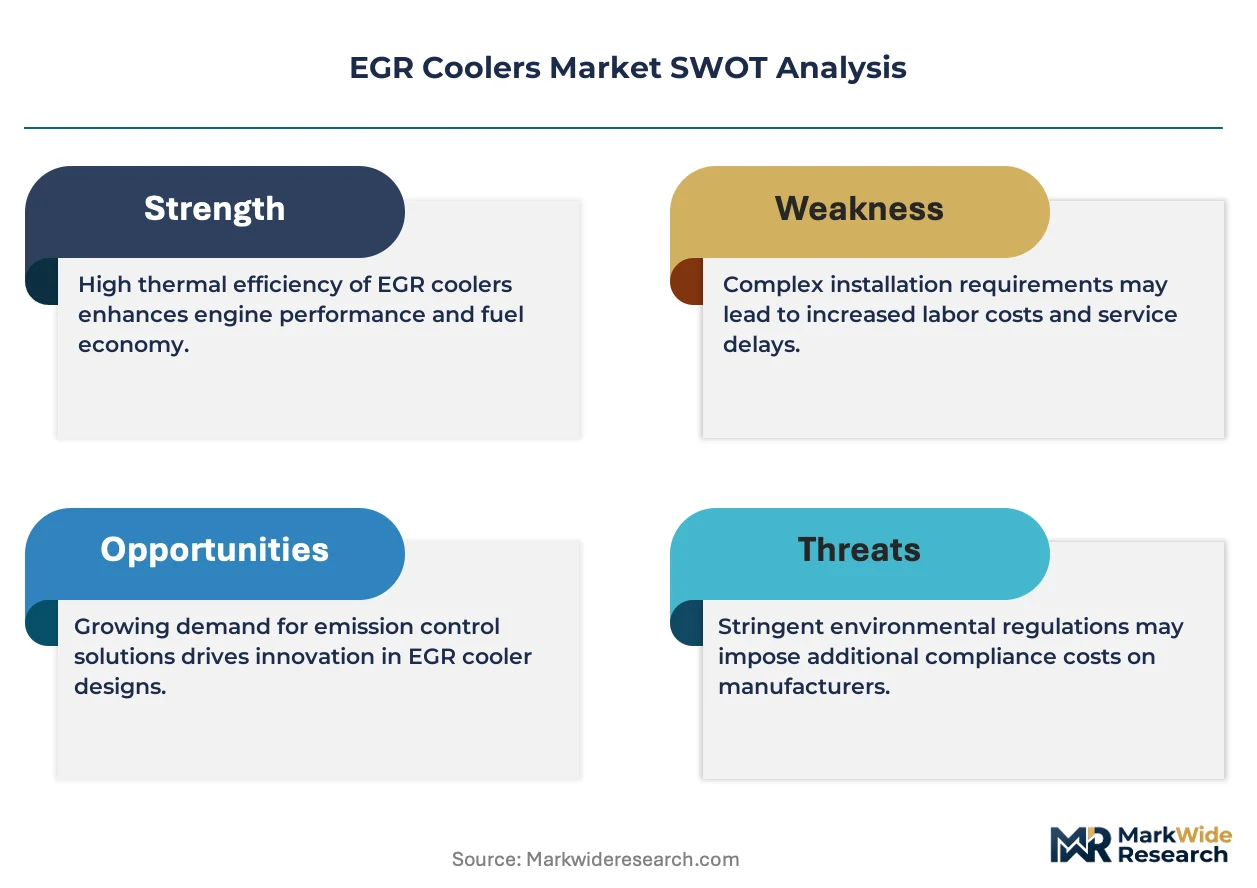
EGR cooler procurement is tightening around stainless steel vacuum-brazed architectures as EPA Phase 2 and Euro VII test cycles force thermal fatigue validation at extended duty cycles, compressing supplier qualification timelines and concentrating sourcing among integrated heat exchanger specialists.
Growth Catalysts
- EPA Phase 2 greenhouse gas standards:Heavy-duty fleet operators in the United States face escalating NOx compliance thresholds that expand EGR cooler sizing requirements and replacement frequency under severe-duty cycles.
- Stainless steel brazing technology:Vacuum-brazed 300-series stainless cores now dominate OEM platforms by delivering corrosion resistance against acidic condensate that degrades aluminum alternatives in stop-start urban duty.
- Commercial vehicle lifecycle extension:North American heavy-duty fleets operating beyond 800,000 miles generate structural aftermarket demand as extended warranties expire and thermal cycling accumulates.
Market Restraints
- Nickel and chromium price volatility:Stainless steel input costs swing with London Metal Exchange pricing, squeezing margin structures for captive brazing operations and spot-market material buyers alike.
- Supplier concentration in Baden-Württemberg:German vacuum brazing capacity clusters around Stuttgart industrial corridors, creating single-source risk for European OEMs qualifying new platform variants.
- Electric powertrain substitution:Battery-electric commercial vehicle pilots by major North American fleet operators threaten long-term EGR cooler attachment rates in Class 8 highway tractors.
Strategic Opportunities
- China Stage VIb enforcement timeline:MEE implementation schedules for heavy-duty diesel certification create qualification windows for brazing specialists with existing Stage VIa validation records.
- Natural gas engine variants:Spark-ignited methane combustion runs cooler than diesel, requiring redesigned EGR cooler architectures with modified fin density and flow distribution.
- Remanufactured cooler channels:Independent distributors in the United States are building core exchange programs that capture value from stainless steel reusability and bypass OEM captive parts pricing.
Industry Challenges
- Vacuum brazing technician scarcity:Precision furnace operation and leak-rate testing demand specialized metallurgical skills that outpace vocational training pipeline output in industrial regions.
- Corrosion test protocol fragmentation:Divergent salt spray and thermal shock requirements between EPA, EMA, and MEE certification cycles force redundant validation runs that extend program timelines.
- Platform integration complexity:Compact plate-fin designs must accommodate turbocharger routing and aftertreatment packaging in increasingly dense engine bays without compromising thermal margin.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | EGR Coolers Market |
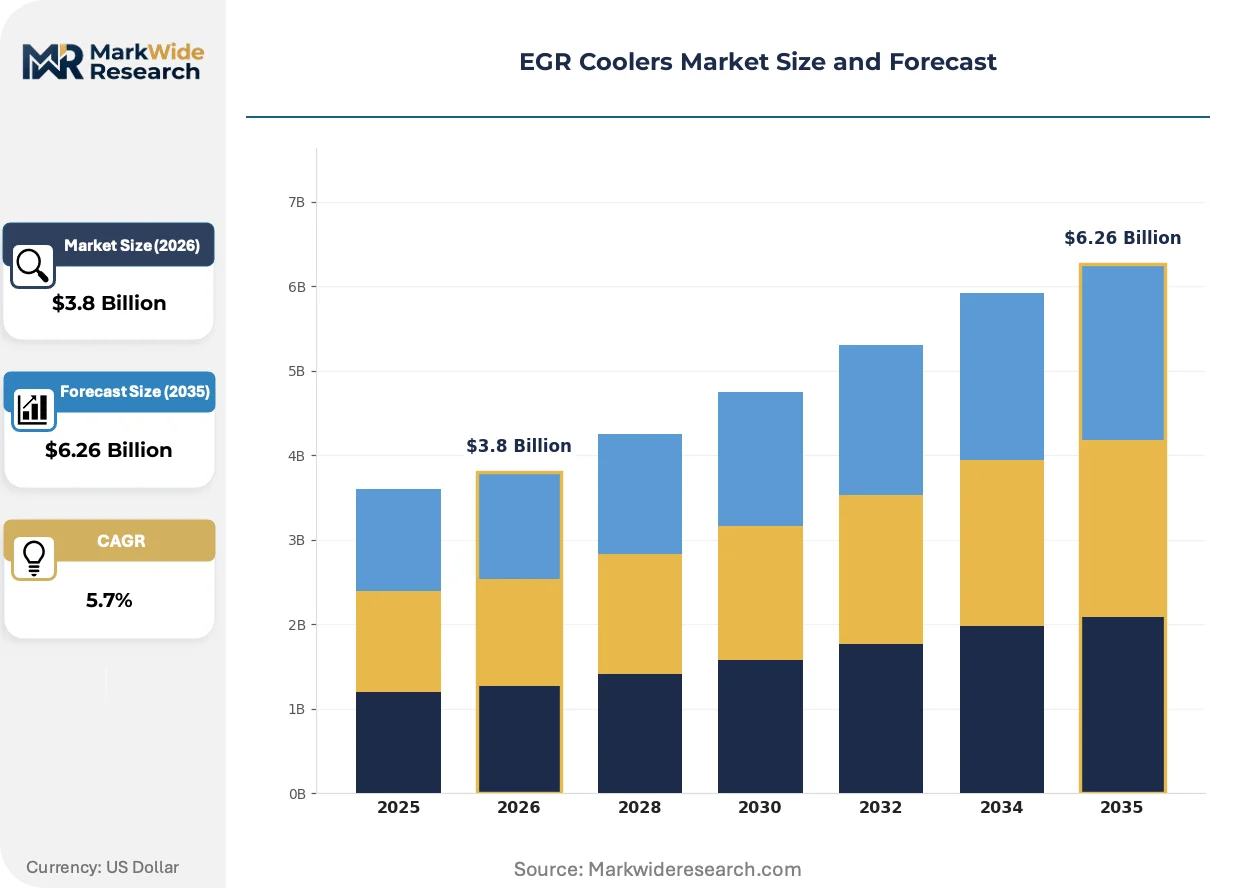
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
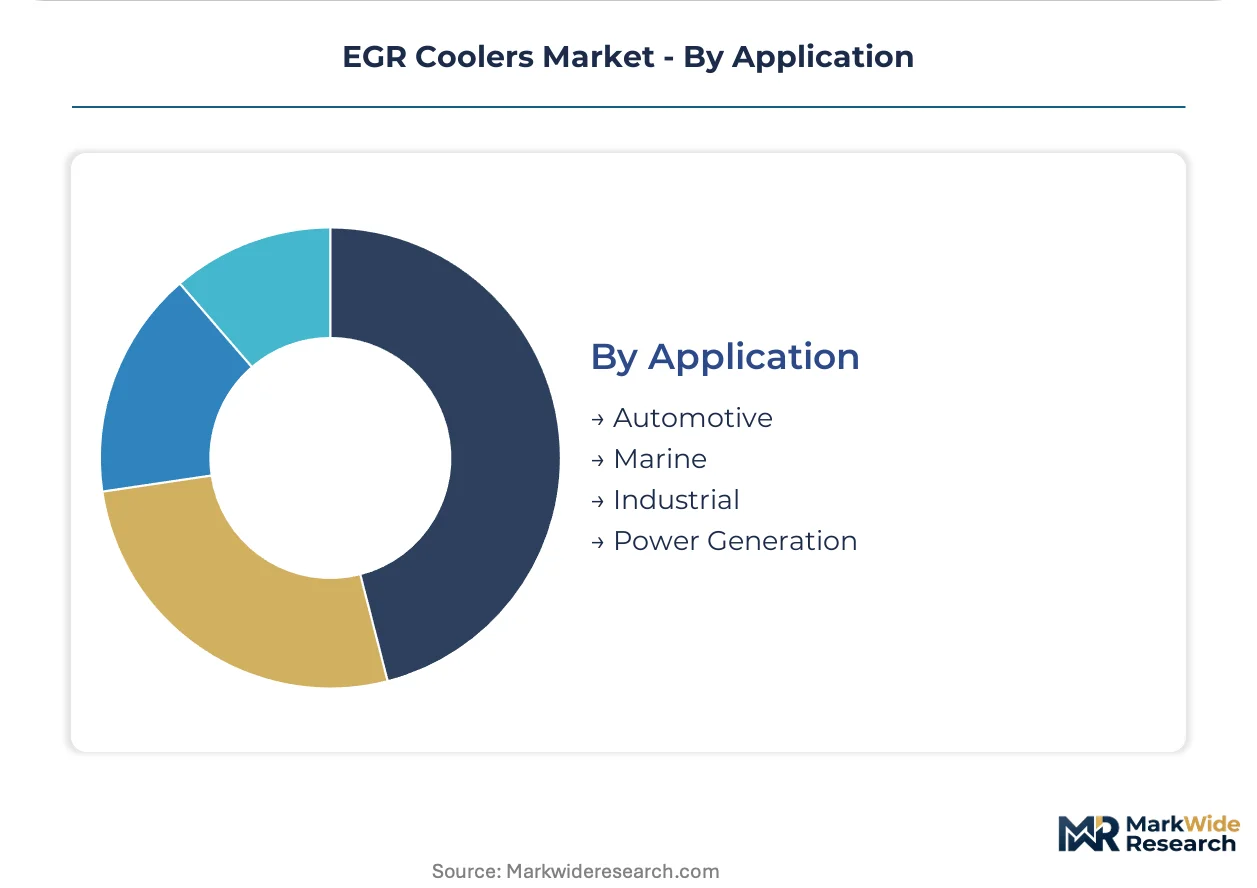
| Segmentation | Product Type: Air-Cooled, Liquid-Cooled, Dual-Cooled, High-Performance End User: OEMs, Aftermarket, Heavy-Duty Vehicles, Light-Duty Vehicles Technology: Plate, Tubular, Spiral, Shell-and-Tube Application: Automotive, Marine, Industrial, Power Generation |
| Companies Covered | BorgWarner Inc., Mahle GmbH, Denso Corporation, Valeo S.A., Continental AG, Friedrich Boysen GmbH & Co KG, Senior Flexonics, Faurecia SE, Hanon Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
EGR Coolers Market Shifts & Advancements
Material science advances and regulatory test protocol harmonization are compressing development cycles while reshaping how thermal management suppliers engage OEM powertrain engineering teams.
Plate-fin architectures with enhanced surface area density are hybridizing with traditional tube-and-shell construction to serve hybrid commercial vehicle applications where intermittent engine operation intensifies thermal shock loading. European truck manufacturers are qualifying these hybrid cores for 48-volt mild-hybrid platforms where stop-start frequency exceeds conventional diesel duty by an order of magnitude. The resulting component consolidation is compressing supplier tier structures as brazing specialists assume full module responsibility.
EMA review of Euro VII test protocols is forcing recalibration of thermal fatigue validation matrices to include extended low-load urban cycles that accumulate acidic condensate in cooler passages. Core suppliers must now demonstrate 4,000-hour corrosion resistance under modified test sequences that simulate refuse collection and urban delivery duty. German and Swedish OEMs are responding by pre-qualifying duplex stainless grades that exceed current material specifications.
Fleet procurement departments are unbundling EGR cooler replacement from full engine overhaul contracts, creating standalone thermal management service lines with compressed turnaround requirements. Independent service networks in the United States are capturing this demand through mobile brazing repair units that address pinhole leaks without full core replacement. The shift is most visible in California port drayage fleets where CARB compliance deadlines accelerate maintenance intervals.
EGR Coolers Market Segmentation
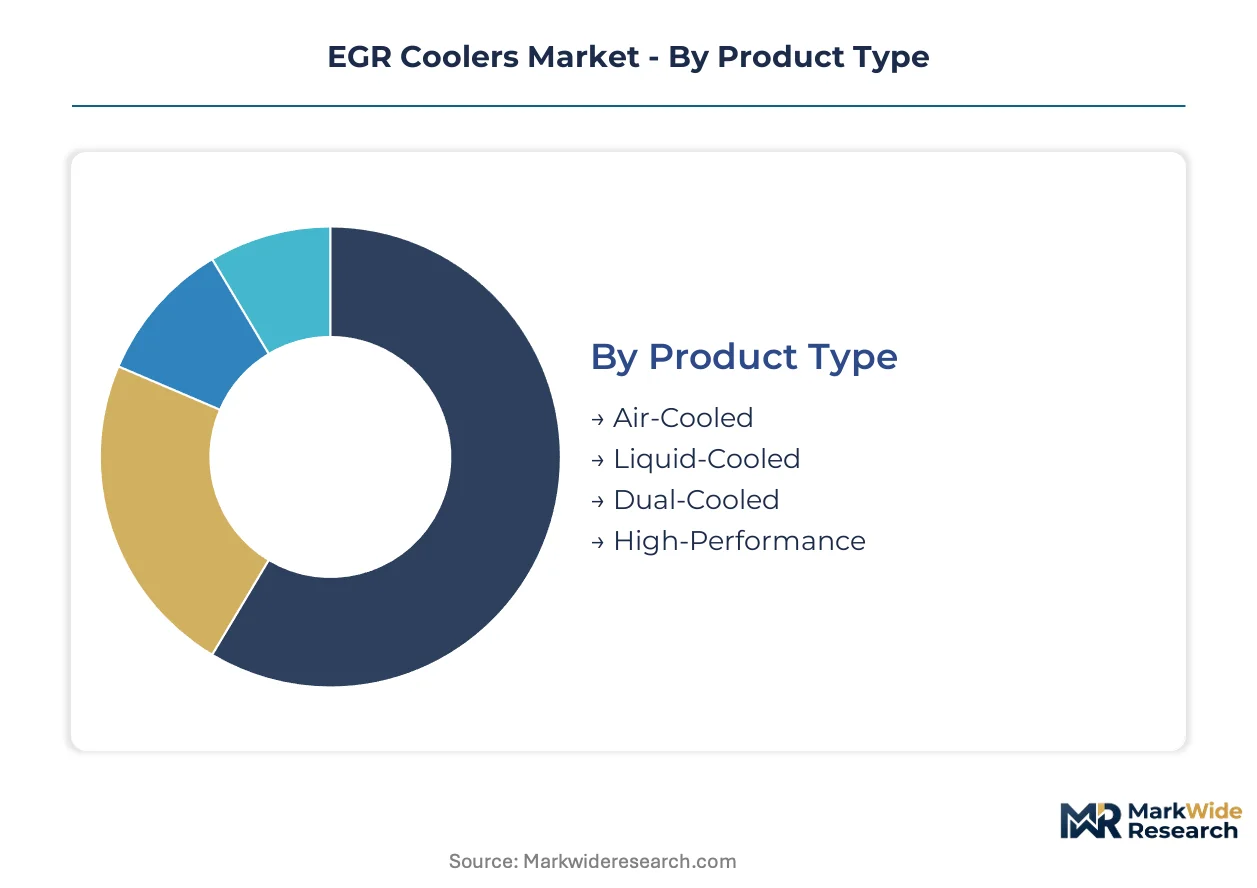
EGR cooler procurement patterns diverge sharply between OEM platform sourcing and aftermarket replacement cycles. Segment boundaries reflect thermal load requirements, packaging constraints, and regulatory validation timelines that reshape supplier engagement models across heavy-duty and light-duty applications.
Product Type:
After-sales service intensity varies dramatically by cooling architecture, with liquid-cooled units demanding more frequent inspection intervals in severe-duty fleets.
- Liquid-Cooled:Vacuum-brazed stainless steel cores circulate engine coolant to manage exhaust gas temperatures up to 450°C. North American Class 8 truck operators specify these for EPA Phase 2 compliance, though nickel price volatility squeezes maintenance budgets.
- Air-Cooled:Finned aluminum constructions eliminate coolant circuit complexity and reduce weight in packaging-constrained engine bays. Light-duty automotive programs in Germany favor these for cost-sensitive passenger car platforms where thermal loads remain moderate.
- Dual-Cooled:Hybrid architectures combine liquid and air paths for intermittent high-load operation.
- High-Performance:Duplex stainless grades with enhanced surface area density serve 48-volt mild-hybrid platforms.
By volume, Liquid-Cooled leads. By growth pace, High-Performance is ahead.
End User:
Cost tier stratification separates captive OEM supply agreements from independent aftermarket channels with divergent margin structures.
- OEMs:Platform sourcing contracts lock in multi-year supply with integrated heat exchanger specialists. BorgWarner and Mahle dominate European and North American truck program qualifications through turbocharger-EGR bundling relationships.
- Aftermarket:Independent distributors build core exchange programs around stainless steel reusability. California port drayage fleets generate compressed turnaround demand as CARB compliance deadlines accelerate replacement intervals.
- Heavy-Duty Vehicles:Fleets operating beyond 800,000 miles create structural replacement demand as extended warranties expire.
- Light-Duty Vehicles:Passenger car programs prioritize packaging efficiency and cost minimization over thermal margin.
OEMs capture the largest revenue share. Aftermarket channels are expanding most quickly.
Technology:
Volume concentration favors plate architectures, yet application requirements push diversification across construction methods.
- Plate:Compact fin-density designs maximize surface area in dense engine bays. Japanese OEMs specify these for passenger car programs where packaging constraints override thermal shock tolerance.
- Tubular:Traditional tube-and-fin constructions offer serviceability advantages for independent repair networks. United States mobile brazing units target pinhole leaks in these cores without full replacement.
- Spiral:Coiled flow paths suit natural gas engine variants with modified thermal profiles.
- Shell-and-Tube:Robust pressure containment serves marine and industrial applications with extended duty cycles.
Plate technology dominates unit volume. Spiral configurations are gaining share fastest as natural gas adoption spreads.
Application:
Geographic deployment patterns concentrate procurement in regions with active emissions enforcement and established engine manufacturing infrastructure.
- Automotive:Light-duty and heavy-duty vehicle programs drive the majority of unit demand. China's Stage VI enforcement through MEE and Euro VII proposals under EMA review reshape cooler sizing requirements across German, Swedish, and Chinese OEM platforms.
- Marine:Salt spray corrosion resistance mandates duplex stainless specifications. International Maritime Organization guidelines and port authority regulations in Rotterdam and Singapore shape qualification protocols.
- Industrial:Stationary diesel generators and construction equipment operate under divergent regulatory frameworks.
- Power Generation:Backup generator sets require extended corrosion validation for intermittent operation patterns.
Automotive applications lead by volume. Marine segments are climbing the fastest on regulatory tightening in major port jurisdictions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany demonstrate the lowest price elasticity, absorbing premium stainless steel specifications without procurement friction, while Indian fleet operators exhibit acute sensitivity to nickel-driven cost swings that compress replacement intervals.
United States
Class 8 highway tractor fleets generate sustained demand as EPA Phase 2 compliance deadlines tighten NOx thresholds for heavy-duty diesel platforms. CARB enforcement in California accelerates maintenance cycles for port drayage operators serving Los Angeles and Long Beach harbors. Detroit-Warren industrial corridors concentrate vacuum brazing capacity for OEM platform sourcing.
Germany
Commercial vehicle manufacturers specify duplex stainless grades exceeding baseline thermal fatigue requirements under EMA-reviewed Euro VII test protocols. KBA certification cycles compress supplier qualification windows for Stuttgart-based engineering centers. Baden-Württemberg industrial clusters anchor European vacuum brazing specialization with captive metallurgical expertise.
China
Domestic heavy-duty engine production scales to meet Stage VIb enforcement timelines through MEE certification pathways. Yangtze River Delta manufacturing bases concentrate plate-fin fabrication capacity for passenger car and light commercial programs. Shanghai-based thermal management specialists validate cores for extended corrosion resistance under accelerated urban duty cycles.
Japan
PMDA-aligned industrial standards shape validation protocols for compact plate-fin architectures serving domestic OEM packaging constraints. METI technology roadmaps emphasize thermal efficiency gains in hybrid commercial vehicle platforms. Nagoya industrial corridors host integrated heat exchanger specialists with captive brazing furnace networks.
EGR Coolers Market Competitive Landscape
Capability concentration sits with integrated metallurgical specialists commanding vacuum brazing furnace networks and captive stainless steel supply chains; scale advantage sits with diversified thermal management conglomerates bundling EGR coolers with turbocharger and aftertreatment module sourcing. The vendor base stratifies across three archetypes: captive OEM suppliers with platform-locked contracts, independent brazing specialists serving aftermarket channels, and diversified automotive component groups leveraging cross-product bundling. Dominant competitive moves include backward integration into stainless steel coil processing and strategic partnerships with heavy-duty engine manufacturers for Euro VII pre-qualification programs.
Among diversified automotive component groups, BorgWarner Inc., Mahle GmbH, and Denso Corporation exemplify distinct competitive positioning archetypes. BorgWarner occupies a bundling-advantaged position where turbocharger-EGR module integration secures multi-year platform commitments. Mahle anchors the captive-metallurgy tier through in-house aluminum casting and vacuum brazing capacity that controls thermal margin specifications. Denso represents the high-volume passenger car specialist segment where plate-fin miniaturization meets stringent Japanese OEM packaging requirements.
| Leading Market Players |
|---|
| BorgWarner Inc. |
| Mahle GmbH |
| Denso Corporation |
| Valeo S.A. |
| Continental AG |
| Friedrich Boysen GmbH & Co KG |
| Senior Flexonics |
| Faurecia SE |
| Hanon Systems |
| Others |
Supply & Pricing Matrix
Nickel price volatility on the London Metal Exchange determines both the spread between stainless steel and aluminum cooler tiers and the geographic clustering of vacuum brazing capacity. Buyers face compressed procurement timelines as EPA Phase 2 and Euro VII validation cycles force early qualification commitments that lock in material cost exposure.
Pricing Analysis
Aftermarket service revenue drives lifetime value as commercial fleets extend vehicle lifecycles beyond 800,000 miles. Contract-based long-term offtake dominates OEM platform sourcing, with price differentiation anchored in vacuum brazing certification grade and captive stainless steel coil processing. Cost compression in the aftermarket tier is intensifying because independent distributors build core exchange programs that bypass OEM captive parts pricing. Heavy-duty fleet operators in North America show the lowest price sensitivity, absorbing premium duplex stainless specifications, while Indian fleet operators exhibit acute nickel-driven cost sensitivity.
Supply Chain Analysis
Baden-Württemberg industrial corridors around Stuttgart hold the densest concentration of vacuum brazing contract manufacturers serving European OEM qualification programs. Manufacturing capacity clusters in Germany, China, and the United States, with raw material supply drawing from 300-series stainless coil processors, nickel refiners, and aluminum foundries. Single-source vulnerability concentrates in German vacuum brazing technician pools where specialized metallurgical skills outpace vocational training output. Distribution runs through captive OEM supply agreements for platform sourcing and independent aftermarket channels for replacement cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vacuum brazing technician scarcity constrains capacity expansion regardless of capital availability, making metallurgical workforce development the binding constraint on supplier growth.
For Market Incumbents: Insulate platform sourcing relationships through turbocharger-EGR bundling contracts that extend across multiple engine generations. Lock in Baden-Württemberg brazing capacity via workforce apprenticeship pipelines and furnace network expansion before Euro VII qualification windows compress. Battery-electric commercial vehicle pilots by North American fleet operators threaten long-term attachment rates; defend against substitution by qualifying natural gas engine cooler architectures. For New Entrants and Emerging Players: India's aftermarket channels show structural underpenetration as domestic heavy-duty fleets scale without integrated thermal management service networks. Target mobile brazing repair units for California port drayage fleets where CARB compliance deadlines accelerate maintenance intervals. Pursue joint qualification programs with Chinese Stage VIb engine manufacturers seeking brazing specialists with existing Stage VIa validation records. For Investors and Strategic Acquirers: The market sits at a pre-consolidation phase that favors integrated metallurgical specialists with captive furnace networks over diversified component groups. Long-term viability rests on backward integration into stainless steel coil processing and control over thermal fatigue validation protocols. Watch for battery-electric Class 8 highway tractor pilot scale-up as the signal indicating EGR cooler attachment rate inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Stainless Steel Coil Processing | Captive metallurgical supply secures margin control against LME nickel volatility for vacuum brazing operations. |
| Natural Gas Engine Cooler Architecture Development | Spark-ignited methane combustion variants require redesigned fin density and flow distribution specifications. |
| Mobile Brazing Repair Unit Deployment | California port drayage fleets generate compressed turnaround demand as CARB compliance deadlines accelerate. |
| Duplex Stainless Grade Pre-Qualification | German and Swedish OEMs demand 4,000-hour corrosion resistance under modified Euro VII urban duty cycles. |
| Workforce Apprenticeship Pipeline Investment | Specialized vacuum furnace operation and leak-rate testing skills outpace vocational training output in industrial regions. |
Research Methodology
Cross-validation between OEM platform engineering interviews and aftermarket distributor operational data anchors the qualitative findings. Primary fieldwork engaged thermal management procurement leads at heavy-duty engine manufacturers, vacuum brazing furnace operators in Baden-Württemberg and Detroit-Warren corridors, fleet maintenance directors at North American Class 8 operators, and independent aftermarket service network managers. Secondary validation drew from EPA certification filings, KBA type-approval documentation, MEE Stage VI enforcement bulletins, and vehicle production databases. Bottom-up unit demand modeling triangulated against top-down thermal management market sizing.
Calibration against historical EPA Phase 1 adoption curves and Euro VI implementation patterns shaped the projection framework across the analysis window. Segmentation dimensions modeled include cooling architecture, end-user channel, construction technology, and application vertical, with regional regulatory cluster as an additional automotive-specific dimension. CAGRs derived from regression analysis of emissions standard implementation timelines and engine certification cycle phasing. Industry-specific forecast inputs incorporated nickel price volatility assumptions and electric powertrain substitution scenarios.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese plate-fin fabricators or accelerated battery-electric adoption by North American fleets would shift outcomes. Quarterly review of LME nickel pricing, Euro VII final protocol publication, and Class 8 electric tractor pilot deployment rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Aluminum Alloy Wheel Market
Vehicle Components
Two-Wheeled Containers Market
Vehicle Components
High Precision Heavy Load Bearings Market
Vehicle Components
Locomotive Pantographs Market
Vehicle Components
Vehicle Exhaust Hose Market
Vehicle Components
Automotive Air Flow Sensors Market
Vehicle Components
Global Automotive Composite Liftgate Market
Vehicle Components
Canada Automotive Carbon Fiber Composites Market
Vehicle Components
Motorcycle Side Box Market
Vehicle Components
Hooklift Trailer Market
Vehicle Components
Global Automotive Battery Sensor Market
Vehicle Components
Asia-Pacific Industrial Brakes Market
Vehicle Components
HCV Suspension System Market
Vehicle Components
India Automotive Steering System Market
Vehicle Components
Digital Tire Inflator Market
Vehicle Components
Locomotive Drive Shaft Market