
 Norway Passenger Vehicles Lubricants Market | 2026-2036
Norway Passenger Vehicles Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Norway Passenger Vehicles Lubricants Market Analytics
Fleet operator procurement is shifting toward consolidated national service contracts, reducing the fragmented independent workshop base that historically dominated lubricant purchasing in Norway. Shell PLC leverages its integrated fuel-retail network to anchor downstream distribution across Scandinavian coastal routes. TotalEnergies SE competes through specialized synthetic formulations calibrated for cold-climate Nordic operating conditions. FUCHS sustains its position in fleet maintenance channels with technical service programs targeting commercial vehicle operators.
Passenger vehicle lubricants comprise formulated oils and functional fluids engineered to reduce friction, dissipate heat, and protect powertrain components under thermal cycling between sub-zero Arctic temperatures and moderate summer loads, with viscosity grades typically spanning 0W-20 to 5W-30 for gasoline engines and lower HTHS formulations for hybrid applications. Engine oil formulations dominate value capture due to extended drain intervals and OEM specification complexity, while synthetic grades within the formulation dimension absorb disproportionate margin pools as thermal stability requirements intensify. Bio-based lubricants represent the fastest-growing formulation category, though from a minimal base, as Norway's maritime and terrestrial environmental standards tighten biodegradability thresholds for workshop waste streams.
Norwegian Pollution Control Authority regulations and EU REACH compliance frameworks govern chemical substance registration and restrict specific additive chemistries in lubricant formulations sold domestically. The country's national CO2 taxation structure and zero-emission vehicle mandates compress demand for conventional internal combustion engine lubricants while redirecting formulation investment toward thermal management fluids for hybrid architectures. Stakeholders must monitor Oslo's municipal fleet electrification timeline and corresponding service infrastructure conversion to calibrate product portfolio transitions.
Market Dynamics
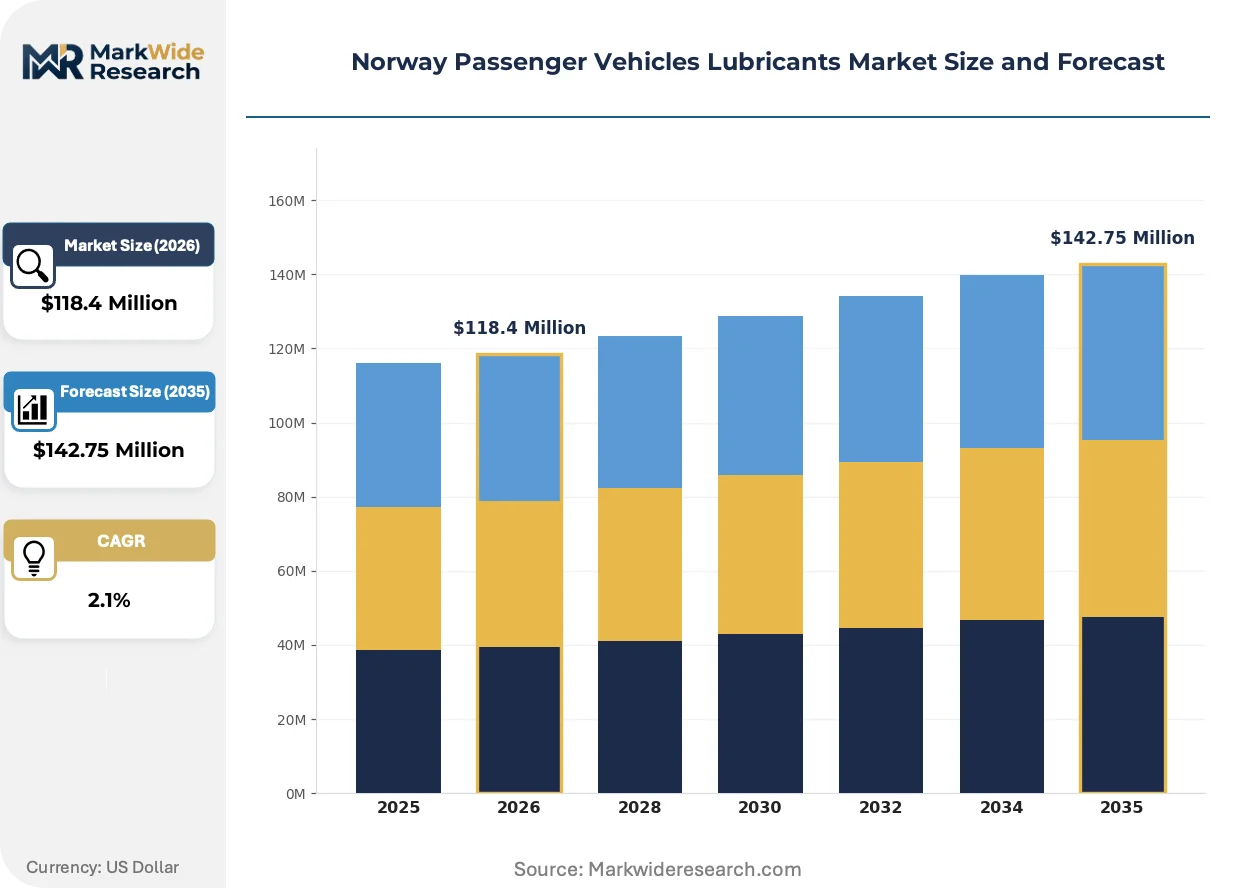
Norway's CO2-based vehicle taxation scheme and zero-emission mandates are compressing demand for conventional internal combustion engine lubricants while redirecting formulation investment toward thermal management fluids for hybrid architectures. Fleet electrification timelines in Oslo and western port logistics clusters are accelerating this structural transition.
Growth Catalysts
- Fleet electrification policies:Norway's national zero-emission vehicle mandates create demand for specialized thermal management fluids in hybrid powertrains. Municipal fleet conversion programs in Oslo drive service infrastructure upgrades.
- Cold-climate operating requirements:Arctic temperature cycling between sub-zero winters and moderate summers necessitates advanced synthetic formulations with enhanced thermal stability. These specifications command formulation complexity premiums.
- Bio-based lubricant standards:The Norwegian Pollution Control Authority's tightening biodegradability thresholds for workshop waste streams redirect R&D investment toward renewable base stocks.
Market Restraints
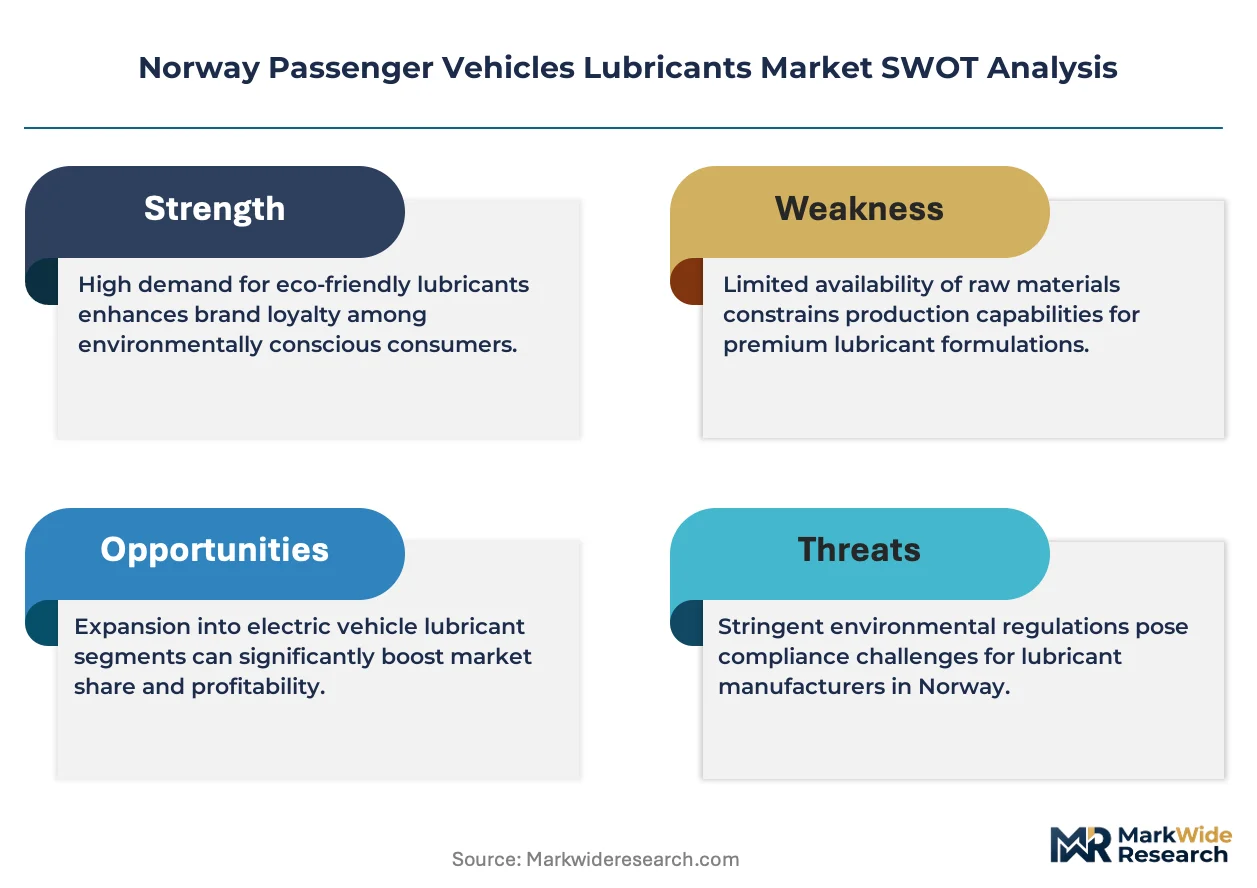
- Base oil supply concentration:Synthetic base stock production concentrates among a limited set of European refiners, exposing Norwegian blenders to input cost volatility and supply security risks.
- EV transition velocity:Battery electric vehicle penetration in Norway outpaces lubricant formulation development cycles, compressing the addressable market for conventional engine oils faster than product portfolios can pivot.
- REACH compliance friction:EU REACH additive chemistry restrictions limit formulation flexibility for extreme cold-climate performance, forcing trade-offs between environmental compliance and technical specifications.
Strategic Opportunities
- Western port logistics clusters:Commercial vehicle service infrastructure around Bergen and Stavanger remains underpenetrated by integrated fluid management programs, creating whitespace for technical service partnerships.
- Thermal fluid convergence:Battery thermal management and electric motor cooling requirements are unifying specification standards, enabling platform-scale formulation development across hybrid architectures.
- Consolidated national service contracts:Fleet operator procurement centralization favors suppliers with integrated technical service capabilities, compressing the fragmented independent workshop channel.
Industry Challenges
- Formulation talent scarcity:Expertise in electric vehicle thermal fluid engineering remains concentrated among a limited pool of specialists, constraining product development velocity for Norwegian blenders.
- Certification timeline compression:OEM specification cycles for hybrid powertrains are shortening faster than traditional fluid approval processes, creating compliance gaps for market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Norway Passenger Vehicles Lubricants Market |
| Market Size in 2026 | $118.4 Million |
| Market Size in 2035 | $142.75 Million |
| CAGR (2026 – 2036) | 2.1% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Transmission Fluid, Brake Fluid, Grease Formulation: Synthetic, Mineral, Semi-Synthetic, Bio-Based End User: OEMs, Aftermarket Providers, Fleet Operators, Dealerships Distribution Channel: Retail Stores, Online Retail, Service Stations, Wholesale |
| Companies Covered | BP PLC (Castrol), Shell PLC, ExxonMobil Corporation, Chevron Corporation, TotalEnergies SE, FUCHS, Motul, PETRONAS Lubricants International, Valvoline Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Norway Passenger Vehicles Lubricants Market Evolving Landscape
Formulation chemistry and procurement architecture are undergoing parallel transformation as electrification redefines fluid performance requirements and buyer-seller relationships consolidate. Technical specifications and commercial structures are both compressing toward platform-standardized solutions.
Multi-functional thermal management fluids are unifying battery cooling, electric motor lubrication, and power electronics protection within single formulation architectures. Fleet operators in Oslo's metropolitan corridor are adopting these unified specifications at accelerated rates. This convergence is compressing the historical segmentation between engine oils and functional fluids into integrated platform offerings.
Norwegian Pollution Control Authority regulations governing workshop waste stream biodegradability are tightening additive chemistry permissions. These restrictions are forcing reformulation of cold-climate performance packages. Synthetic base stocks with enhanced environmental profiles are capturing disproportionate technical investment as blenders navigate compliance-performance trade-offs.
Buyer concentration among national fleet operators is disintermediating the independent workshop channel that historically fragmented lubricant purchasing. Consolidated service contracts now specify fluid brands, technical support obligations, and waste management protocols. This shift is most visible in western Norway's port logistics corridors where commercial vehicle density supports centralized procurement scale.
Norway Passenger Vehicles Lubricants Market Segmentation
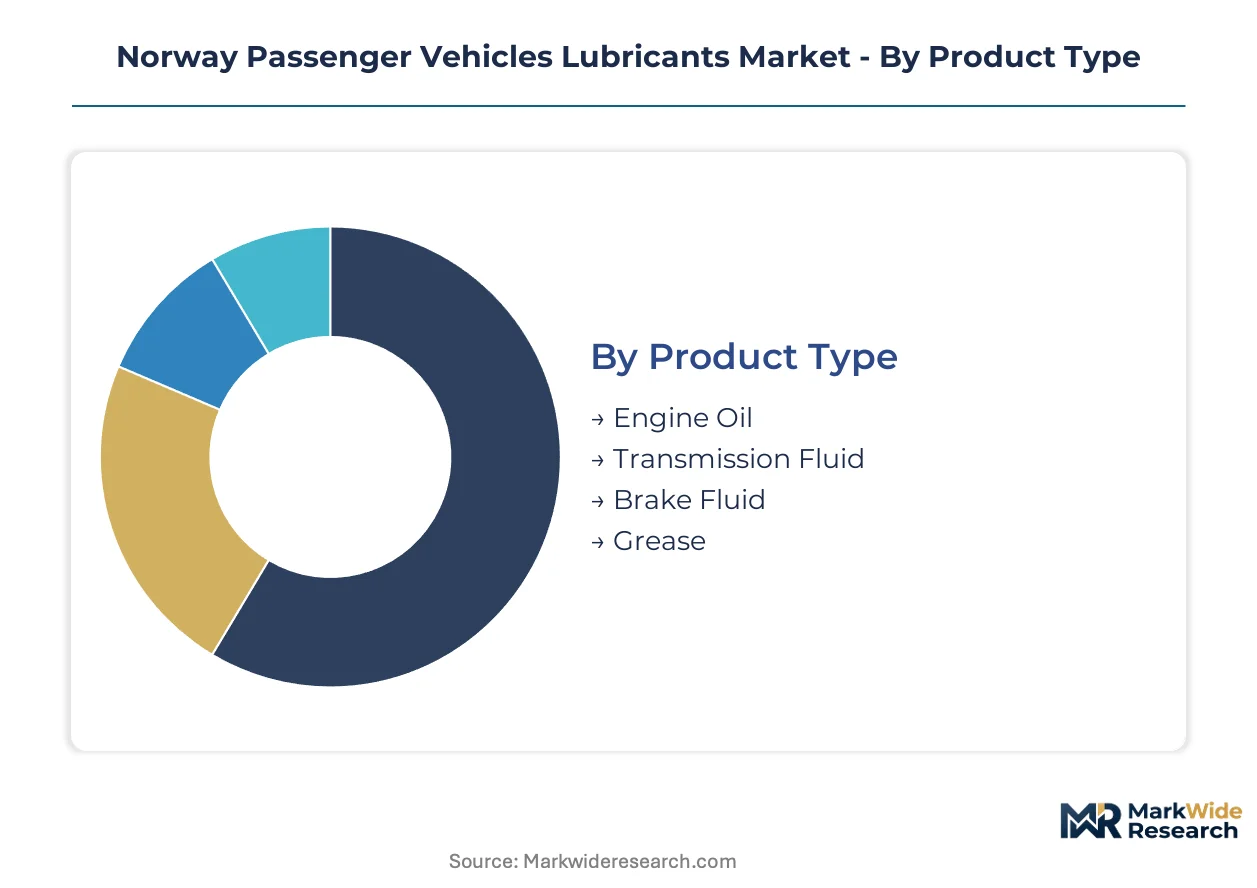
Segmentation in Norway's passenger vehicle lubricants market reveals how electrification policies and cold-climate specifications reshape product portfolios. Upgrade cycles for hybrid thermal management fluids now outpace traditional engine oil replacement intervals, compressing formulation development timelines.
Product Type:
Replacement cycles vary dramatically across fluid categories as powertrain electrification accelerates in Oslo's municipal fleets and western logistics corridors.
- Engine Oil:Formulations span 0W-20 to 5W-30 viscosity grades for gasoline powertrains, with lower HTHS variants engineered for hybrid stop-start cycling. Demand concentrates around independent workshops in Oslo's metropolitan service corridor, though fleet procurement centralization erodes this channel's purchasing share.
- Transmission Fluid:Dual-clutch and continuously variable transmission specifications command premium formulation complexity as thermal loads intensify under Arctic temperature cycling. Bergen and Stavanger port logistics clusters drive commercial vehicle transmission service volume, with extended drain intervals compressing per-unit consumption.
- Brake Fluid:DOT 4 and DOT 5.1 silicone formulations serve conventional hydraulic systems, with hygroscopic degradation dictating shorter replacement windows in coastal humidity conditions.
- Grease:Lithium-complex and polyurea-thickened formulations protect chassis and wheel bearing components, with bio-based alternatives gaining traction under Norwegian Pollution Control Authority waste stream regulations.
Engine oil sits at the top of the volume ranking, with transmission fluid climbing the fastest as hybrid powertrain penetration deepens.
Formulation:
Cost tier stratification separates premium synthetic grades from commodity mineral bases, with margin pools concentrating at the specification-intensive end of the spectrum.
- Synthetic:Polyalphaolefin and ester base stocks deliver thermal stability across sub-zero to moderate temperature ranges, capturing disproportionate technical investment from blenders navigating REACH additive restrictions. Oslo's fleet electrification timeline accelerates synthetic adoption for hybrid thermal management applications.
- Mineral:Group I and Group II base oils serve price-sensitive segments and older vehicle parc, with demand compressing faster than supply chain reconfiguration permits.
- Semi-Synthetic:Blended formulations balance cost and performance for mid-market passenger vehicles, occupying a narrowing band as specification polarization intensifies.
- Bio-Based:Renewable ester and vegetable-derived base stocks address Norwegian Pollution Control Authority biodegradability mandates, expanding most quickly from a minimal installed base in maritime-adjacent service operations.
Synthetic formulations command the largest value share, with bio-based alternatives gaining share fastest as environmental compliance tightens.
End User:
Customer type determines procurement architecture, with consolidated national contracts displacing fragmented workshop purchasing.
- OEMs:Factory-fill specifications and warranty-mandated service fluids anchor brand loyalty through dealer networks, with electrification compressing first-fill volumes for battery electric platforms.
- Aftermarket Providers:Independent workshops and regional distributors face disintermediation as fleet procurement centralizes, retaining residual share in rural service territories outside Oslo's electrification corridor.
- Fleet Operators:Commercial vehicle pools in western port logistics clusters negotiate integrated fluid management contracts specifying technical support obligations and waste handling protocols.
- Dealerships:Authorized service centers capture warranty work and premium synthetic upgrades, with thermal fluid convergence unifying battery and motor cooling specifications.
Fleet operators represent the steepest expansion trajectory, with aftermarket providers losing ground fastest to procurement consolidation.
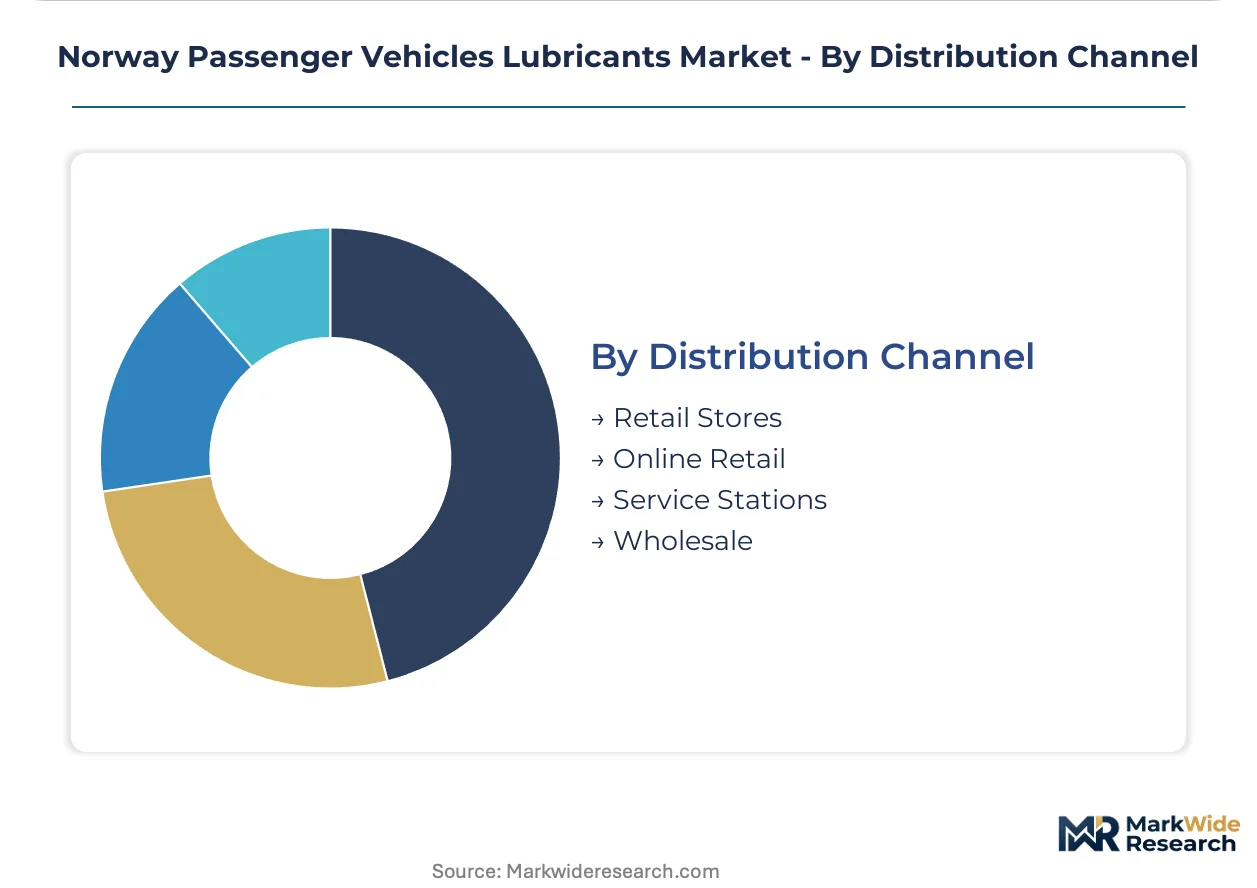
Distribution Channel:
Supply concentration favors integrated fuel-retail networks over fragmented wholesale intermediaries.
- Retail Stores:Automotive parts chains and hypermarkets serve DIY consumers and small independent workshops, with shelf space contracting as synthetic SKUs proliferate.
- Online Retail:E-commerce platforms capture specification-savvy consumers and remote service operations, with logistics infrastructure limiting penetration in Arctic coastal territories.
- Service Stations:Integrated fuel-lubricant retail networks along Scandinavian coastal routes anchor Shell PLC's downstream presence, with convenience-driven purchasing reinforcing brand lock-in.
- Wholesale:Bulk distribution to commercial workshops and fleet maintenance depots concentrates around Bergen and Stavanger logistics clusters, with technical service bundling displacing commodity transactions.
Service stations hold the dominant volume position, with online retail expanding most quickly as procurement digitization penetrates fleet operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Formulation chemists and cold-climate fluid engineers cluster around Oslo's research corridors and western port logistics hubs, anchoring Norway's specialized lubricant development capacity.
Oslo Metropolitan Corridor
Municipal fleet electrification and hybrid thermal management trials concentrate demand for advanced synthetic formulations. The Norwegian Pollution Control Authority enforces tightening biodegradability thresholds for workshop waste streams. Oslo's service infrastructure conversion accelerates specification shifts toward unified battery and motor cooling fluids.
Bergen Port Logistics Cluster
Commercial vehicle density and maritime-adjacent cold-climate operations sustain transmission fluid and grease demand. EU REACH compliance frameworks restrict additive chemistries for extreme low-temperature performance. Bergen's underpenetrated fleet maintenance channels attract technical service program investments from integrated suppliers.
Stavanger Energy Corridor
Offshore-industry workforce mobility and high-performance vehicle ownership support premium synthetic consumption. Norway's CO2-based vehicle taxation scheme compresses conventional engine oil demand while elevating thermal fluid specifications. Stavanger's logistics clusters drive consolidated national service contract negotiations among fleet operators.
Trondheim Technology Hub
Academic research partnerships and automotive testing facilities anchor formulation development for Arctic operating conditions. The Norwegian Environment Agency coordinates with EU regulators on chemical substance registration protocols. Trondheim's engineering talent pool supplies blenders navigating REACH-compliant cold-climate performance trade-offs.
Tromsø Arctic Territory
Sub-zero temperature extremes and remote service logistics necessitate specialized viscosity grade distribution. National transport infrastructure subsidies support fluid logistics to northern maintenance depots. Tromsø's isolation limits online retail penetration, reinforcing integrated fuel-retail network dominance.
Norway Passenger Vehicles Lubricants Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Norway's lubricant channels, producing a tiered structure where scale-driven fuel-retail integrators anchor downstream distribution while technical service specialists capture fleet maintenance contracts. Three archetypes dominate: integrated energy majors with coastal logistics networks, European blenders with cold-climate formulation heritage, and niche specialists in bio-based and thermal management fluids. Competitive moves concentrate on M&A to secure synthetic base stock supply security and strategic partnerships to embed technical service capabilities within fleet procurement centralization.
Within the integrated energy major tier, Shell PLC and BP PLC exemplify scale-driven downstream control through Scandinavian coastal route networks. TotalEnergies SE occupies a position bridging European formulation heritage with specialized cold-climate synthetic development. FUCHS represents the technical service archetype, anchoring fleet maintenance channel relationships through bundled fluid management programs. These three players illustrate how geographic integration, formulation specialization, and service bundling constitute the primary competitive vectors in Norway's contracting conventional lubricant market and expanding thermal fluid segments.
| Leading Market Players |
|---|
| BP PLC (Castrol) |
| Shell PLC |
| ExxonMobil Corporation |
| Chevron Corporation |
| TotalEnergies SE |
| FUCHS |
| Motul |
| PETRONAS Lubricants International |
| Valvoline Inc. |
| Others |
Value Network & Pricing Analysis
Fleet operator procurement consolidation across Norway's western port logistics clusters is compressing price premiums for conventional engine oils while elevating thermal fluid specification requirements. Synthetic base stock suppliers must reconfigure capacity allocations toward polyalphaolefin and ester formulations calibrated for hybrid powertrain thermal management, compressing margins on legacy mineral oil portfolios.
Pricing Analysis
Capacity additions in Belgium and the Netherlands are reshaping price floors for Group III and polyalphaolefin base stocks entering Norwegian blending operations. Three-tier pricing structure across premium synthetic, mid-grade semi-synthetic, and economy mineral tiers stratifies around REACH compliance certification levels and cold-climate performance ratings. Price erosion runs through the mineral oil segment as fleet electrification compresses demand faster than supply reconfiguration permits. Independent workshops exhibit highest price sensitivity, while national fleet operators prioritize technical service bundling over per-liter cost.
Supply Chain Analysis
Freight cost differentials between North Sea routes and overland trucking from Central European refiners concentrate synthetic base stock sourcing decisions around Rotterdam and Antwerp hub economics. Norwegian blenders draw from Belgian, Dutch, and German supply nodes for polyalphaolefin and ester inputs, with additive packages anchored in French and Italian specialty chemical production. Single-source vulnerability concentrates around a limited European refiner set for Group III+ base oils. Distribution runs through integrated fuel-retail networks along Scandinavian coastal routes, with bulk wholesale serving Bergen and Stavanger fleet maintenance depots.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Norway's lubricant market functions as a geographic-arbitrage play where thermal fluid expertise developed for Arctic operating conditions commands premium positioning in adjacent Nordic markets with less stringent environmental compliance. The regulatory gap between Norwegian Pollution Control Authority biodegradability mandates and Swedish or Finnish standards creates formulation export opportunities.
For Market Incumbents: Deepen technical service program investments targeting western port logistics clusters where fleet procurement centralization is displacing independent workshop channels. Secure backward integration into synthetic base stock supply through long-term offtake agreements with Rotterdam and Antwerp refiners to defend margin position against REACH-driven additive chemistry cost inflation. Prioritize hybrid thermal fluid certification pipelines as battery electric vehicle penetration compresses conventional engine oil addressable market.
For New Entrants and Emerging Players: EU REACH additive chemistry restrictions in Norway open a window for bio-based lubricant specialists with renewable ester formulation capabilities that bypass petroleum-derived base stock dependencies. Target maritime-adjacent service operations in Bergen where Norwegian Pollution Control Authority waste stream regulations favor biodegradable grease and hydraulic fluid alternatives. Pursue technical partnership entry with municipal fleet electrification programs in Oslo seeking unified thermal management fluid specifications.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized thermal fluid engineering firms possessing Arctic climate testing infrastructure and hybrid powertrain certification relationships. The five-to-ten-year viability window favors acquisition targets with platform-scale formulation architectures spanning battery cooling, electric motor lubrication, and power electronics protection. Monitor Oslo municipal fleet electrification procurement announcements as the signal to watch for thermal fluid specification standardization inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Synthetic Base Stock Backward Integration | Long-term offtake agreements with Rotterdam refiners secure REACH-compliant supply for Norwegian blenders. |
| Hybrid Thermal Fluid Platform Development | Unified battery and motor cooling specifications capture Oslo fleet electrification procurement volumes. |
| Bio-Based Formulation Certification | Norwegian Pollution Control Authority biodegradability compliance opens maritime service channel access. |
| Technical Service Program Expansion | Bundled fluid management contracts penetrate Bergen and Stavanger fleet maintenance whitespace. |
| Arctic Climate Testing Infrastructure Investment | Trondheim-based R&D partnerships anchor cold-climate performance differentiation for Nordic export markets. |
Research Methodology
Multiple input streams — formulation chemist interviews, fleet procurement manager consultations, refinery operations assessments, and regulatory filing analysis — were reconciled to construct demand and supply estimates. Primary fieldwork engaged lubricant blenders, commercial vehicle fleet operators, automotive OEM technical service directors, and Norwegian Pollution Control Authority compliance officers. Secondary validation drew from EU REACH substance registration databases, Scandinavian customs trade statistics, SEC filings of integrated energy majors, and Norwegian Environment Agency chemical substance protocols. Bottom-up volume modeling triangulated against top-down market sizing from base stock trade flow analysis.
Historical consumption patterns were cross-referenced against expert panel inputs on electrification timeline acceleration and thermal fluid specification convergence. Segmentation modeling spanned product type, formulation chemistry, end-user procurement architecture, and distribution channel structure across the projection horizon. CAGRs were derived from regression analysis of parc composition shifts and replacement interval compression. Forecast inputs incorporated hybrid powertrain penetration curves, municipal fleet conversion schedules, and additive chemistry restriction trajectories.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated battery electric vehicle adoption or synthetic base stock supply disruption scenarios. Model outputs reflect assumptions on REACH enforcement consistency and fleet operator procurement centralization velocity. A model refresh is warranted upon material change in Norwegian zero-emission vehicle mandate implementation timelines or EU additive chemistry restriction amendments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Global Automotive Leaf Spring Market
Automotive Parts
Automotive Steering Knuckle Market
Automotive Parts
Bulgaria Automotive Engine Oils Market
Automotive Parts
Automotive Axle and Propeller Shaft Market
Automotive Parts
Automotive Exhaust System Market
Automotive Parts
Automotive Parts Die Casting Market
Automotive Parts
Motorcycle Catalyst Market
Automotive Parts
United States Ceramic Ball Bearings Market
Automotive Parts
Car Refrigerator Market
Automotive Parts
Thailand Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Fuel Rail Market
Automotive Parts
Automotive Pinion Gear Market
Automotive Parts
Automotive Bellows Market
Automotive Parts
Automotive Piston Pin Market
Automotive Parts
Automotive Composite Leaf Springs Market
Automotive Parts
South America Automotive Engine Oils Market