
 Crossover Vehicle Market | 2026-2036
Crossover Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Crossover Vehicle Market Analysis
EPA Tier 3 tailpipe standards is hardening the cost-of-entry calculus for crossover manufacturers serving the United States market. Toyota sustains hybrid powertrain leadership across its RAV4 and Highlander lines, while Ford anchors its position through the Escape and Explorer portfolios with substantial manufacturing scale in Michigan and Kentucky. Kia differentiates via design-forward compact offerings that compete aggressively on price-to-content ratios.
A crossover vehicle combines unibody construction with elevated ground clearance, typically riding on a car-based platform rather than a truck-derived frame, yielding improved fuel efficiency alongside expanded cargo capacity. The primary commercial purpose spans family transportation, light-duty hauling, and all-weather commuting where sedan utility proves insufficient. Compact crossovers occupy the largest volume tier as entry-price accessibility attracts first-time buyers and urban commuters, while electric powertrains represent the fastest-expanding margin pool as battery costs decline and charging infrastructure proliferates. Luxury crossovers command premium positioning among business professionals seeking advanced safety systems and refined infotainment integration.
NHTSA crashworthiness protocols and EPA corporate average fuel economy benchmarks jointly dictate platform architecture decisions across Detroit, Stuttgart, and Seoul engineering centers. The EU Green Deal and associated CO2 fleet targets are accelerating powertrain diversification for European-bound exports from Hyundai and BMW assembly plants. Stakeholders must monitor regulatory divergence between California Air Resources Board stringency and federal rollback pressures, as this tension will determine which powertrain portfolios warrant capital allocation across the next product cycle.
Market Dynamics
EPA Tier 3 tailpipe standards and NHTSA crashworthiness mandates are compressing development cycles for internal-combustion platforms while elevating hybrid-electric engineering priorities across Detroit, Stuttgart, and Seoul engineering centers.
Growth Catalysts
- EPA emissions benchmarks:Tier 3 standards force powertrain diversification, accelerating hybrid-electric adoption among suburban households seeking elevated ride height with car-like fuel efficiency.
- Last-mile logistics:Fleet operators across United States logistics networks are expanding crossover procurement for urban delivery routes where cargo capacity and maneuverability converge.
- Battery cost decline:Lithium-ion cell prices enable electric powertrain penetration into compact segments, attracting first-time buyers previously priced out of electrified options.
Market Restraints
- Semiconductor supply concentration:Taiwan and South Korea fabs control advanced chip supply for powertrain controllers and infotainment systems, exposing assembly schedules to geopolitical friction.
- Steel and aluminum volatility:Unibody construction depends on rolled steel and aluminum sheet pricing that fluctuates with energy costs and tariff regimes.
- Charging infrastructure gaps:Rural United States markets lack DC fast-charging density sufficient to support electric crossover adoption outside urban corridors.
Strategic Opportunities
- EU Green Deal tailwinds:CO2 fleet targets for European-bound exports create regulatory pull for plug-in hybrid variants from Hyundai and BMW assembly plants.
- Subscription mobility models:Urban United States consumers increasingly favor flexible access over ownership, opening fleet-as-a-service channels for compact crossovers.
- Vehicle-to-grid integration:Bidirectional charging technology convergence with home energy management systems positions electric crossovers as residential storage assets.
Industry Challenges
- Software-defined vehicle talent scarcity:Embedded systems engineering and over-the-air update architecture expertise concentrates among Silicon Valley and Munich technology clusters, constraining legacy automaker recruitment pipelines.
- Homologation timeline compression:Simultaneous EPA, NHTSA, and CARB certification requirements demand parallel validation tracks that strain testing facility capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Crossover Vehicle Market |
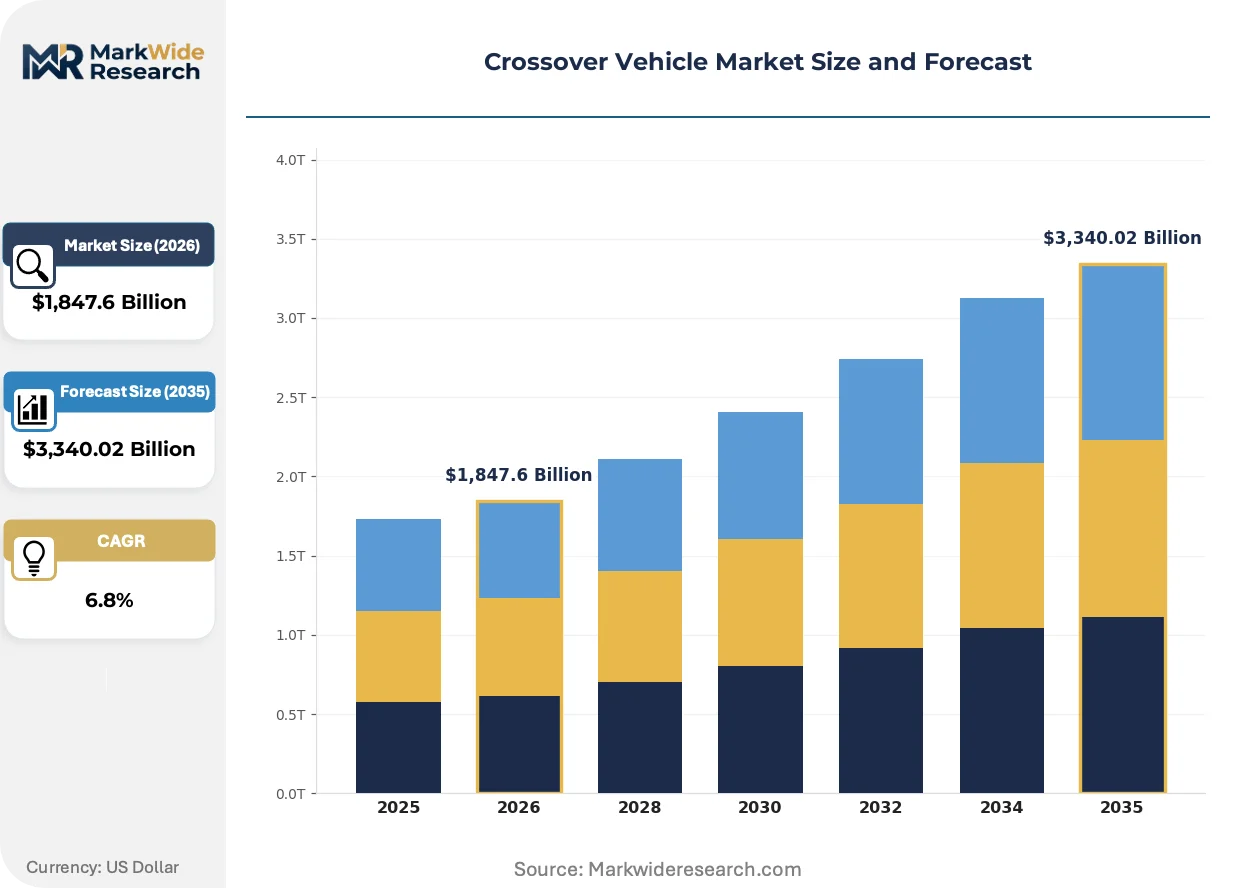
| Market Size in 2026 | $1,847.6 Billion |
| Market Size in 2035 | $3,340.02 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Compact Crossover, Mid-size Crossover, Full-size Crossover, Luxury Crossover Powertrain: Gasoline, Diesel, Hybrid, Electric Feature: Advanced Safety Systems, Infotainment, All-wheel Drive, Towing Capacity Target Customer: Families, Outdoor Enthusiasts, Urban Commuters, Business Professionals |
| Companies Covered | Kia, Ford, Toyota, BMW, Mazda, Honda, Subaru, Chevrolet, Hyundai, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Crossover Vehicle Market Emerging Trajectories
Powertrain electrification, regulatory stringency divergence, and fleet procurement model evolution are restructuring competitive positioning across the crossover segment.
Modular battery pack architectures are absorbing platform development costs while enabling scale economies across vehicle size classes. United States fleet operators and suburban households are adopting these standardized cell-to-pack designs at accelerated replacement cycles. This technology is absorbing engineering resources previously allocated to internal-combustion refinement, compressing powertrain variety in entry segments.
California Air Resources Board stringency creates regulatory divergence from federal rollback pressures that manufacturers must navigate through dual-certification strategies. This friction forces capital allocation toward flexible assembly lines capable of producing both compliance and non-compliance variants. The United States market splits between CARB-aligned states and federal-standard regions, complicating inventory management and pricing architecture.
Direct-to-consumer sales channels are displacing traditional dealer networks in select United States states where franchise laws permit manufacturer-owned retail. Tesla and Rivian pioneered this model; incumbent brands now pilot similar approaches in urban markets. Younger buyers in coastal United States metropolitan areas show strongest preference for fixed-price digital transactions over negotiated dealership experiences.
Crossover Vehicle Market Segmentation
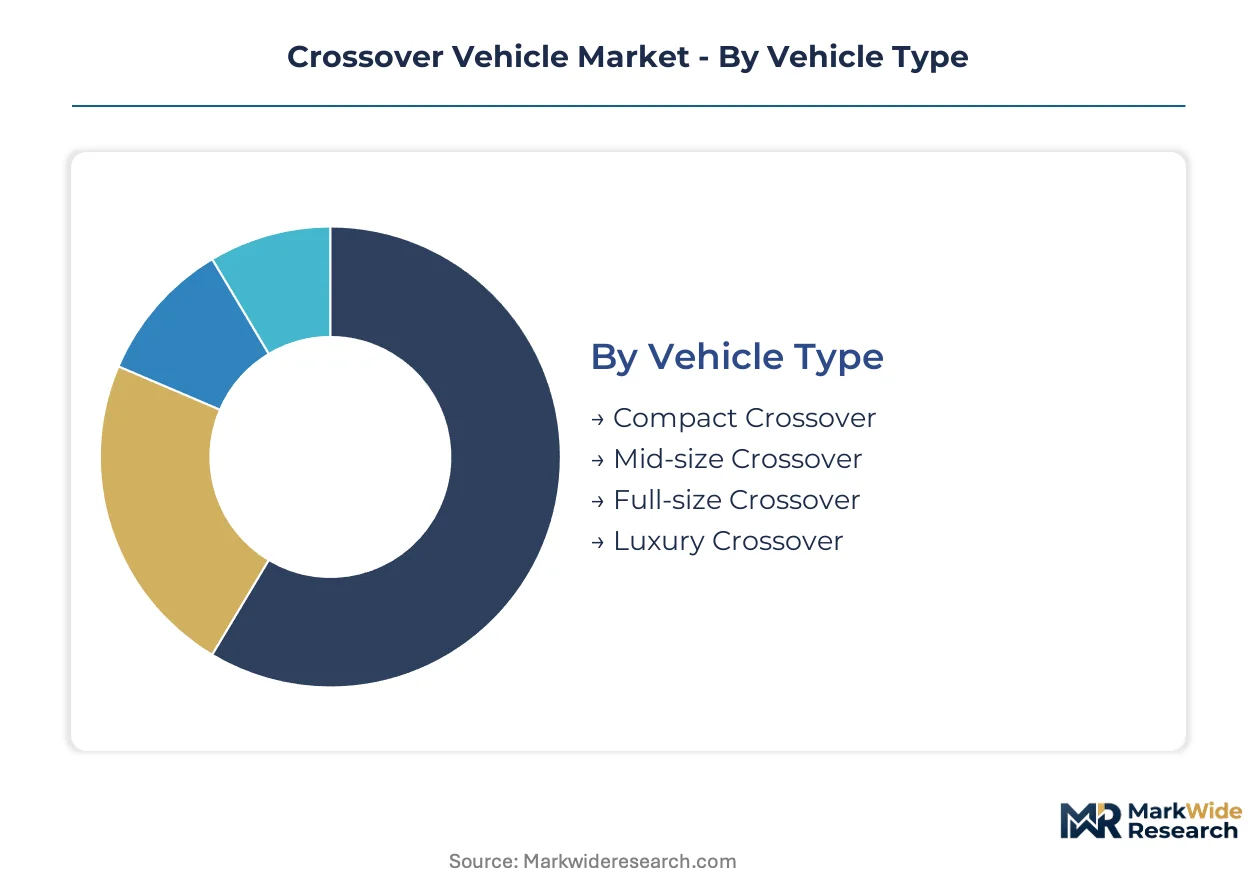
Crossover manufacturers architect product portfolios around four intersecting dimensions that determine engineering resource allocation and factory tooling decisions. Vehicle type and powertrain selections dominate capital expenditure planning, while feature bundling and customer targeting shape transaction pricing and margin capture.
Vehicle Type:
Volume concentration sits at the entry tier, with premium extraction climbing through larger platforms and luxury appointments.
- Compact Crossover:Unibody construction on front-wheel-drive architectures dominates first-time buyer acquisition and urban fleet procurement. United States suburban households favor elevated ride height with sedan-comparable fuel economy, while last-mile logistics operators value maneuverability in dense delivery zones. Today's leader: Compact Crossover. Tomorrow's challenger: Electric variants within this footprint.
- Mid-size Crossover:Three-row configurations anchor family transportation demand across United States heartland states, balancing cargo capacity with garage-friendly dimensions. EPA fuel economy benchmarking pressures manufacturers to deploy hybrid powertrains as standard equipment in this tier. Mid-size platforms absorb the highest engineering investment per unit given their volume centrality.
- Full-size Crossover:Extended wheelbases serve multi-child households and commercial shuttle operators requiring maximum interior volume. Towing capacity ratings and trailer sway control systems differentiate competitive positioning.
- Luxury Crossover:Premium materials and advanced driver-assistance suites command transaction prices substantially above mass-market equivalents. Business professionals in coastal United States metropolitan areas drive replacement-cycle compression through lease-driven turnover.
Compact platforms generate the highest unit economics through scale; luxury tiers capture superior margin per vehicle.
Powertrain:
Regulatory stringency and battery cost curves are reordering engineering priorities across propulsion architectures.
- Gasoline:Turbocharged direct-injection four-cylinder engines remain the default for compact and mid-size segments, though EPA Tier 3 compliance costs erode powertrain diversity. Internal-combustion development cycles compress as capital shifts toward electrification.
- Diesel:Compression-ignition options concentrate in full-size and luxury tiers where torque demands favor high-displacement applications. United States market penetration remains constrained by emissions certification complexity and fuel price differentials.
- Hybrid:Toyota's dual-motor planetary gear systems and Ford's power-split architectures define the competitive standard for fuel economy without range anxiety. Suburban United States households expanding across exurban corridors favor hybrid technology for commuting flexibility.
- Electric:Skateboard battery platforms with cell-to-pack architectures enable flat-floor interiors and maximum cargo utility. Charging infrastructure density in rural United States markets constrains adoption velocity outside urban corridors. Electric powertrains are gaining share fastest among coastal metropolitan registrants.
Hybrid systems bridge the present infrastructure gap; battery-electric architectures claim the steepest expansion trajectory.
Feature:
Content differentiation increasingly concentrates in software-defined systems rather than mechanical hardware.
- Advanced Safety Systems:Automatic emergency braking and lane-keeping assist satisfy NHTSA compliance mandates while reducing insurance premium differentials. Forward collision warning sensors and radar fusion processors add bill-of-materials cost that manufacturers recover through trim-level stratification.
- Infotainment:Large-format touchscreens with wireless smartphone integration dominate showroom appeal and customer satisfaction scoring. Over-the-air update capability extends functional relevance across ownership cycles.
- All-wheel Drive:On-demand torque-vectoring systems attract outdoor enthusiasts and snow-belt households seeking weather traction without truck-based fuel penalties.
- Towing Capacity:Class III and IV hitch ratings with integrated trailer brake controllers serve recreational boat and camper owners in United States lake and mountain regions.
Safety systems have become table stakes; infotainment integration separates winners from also-rans.
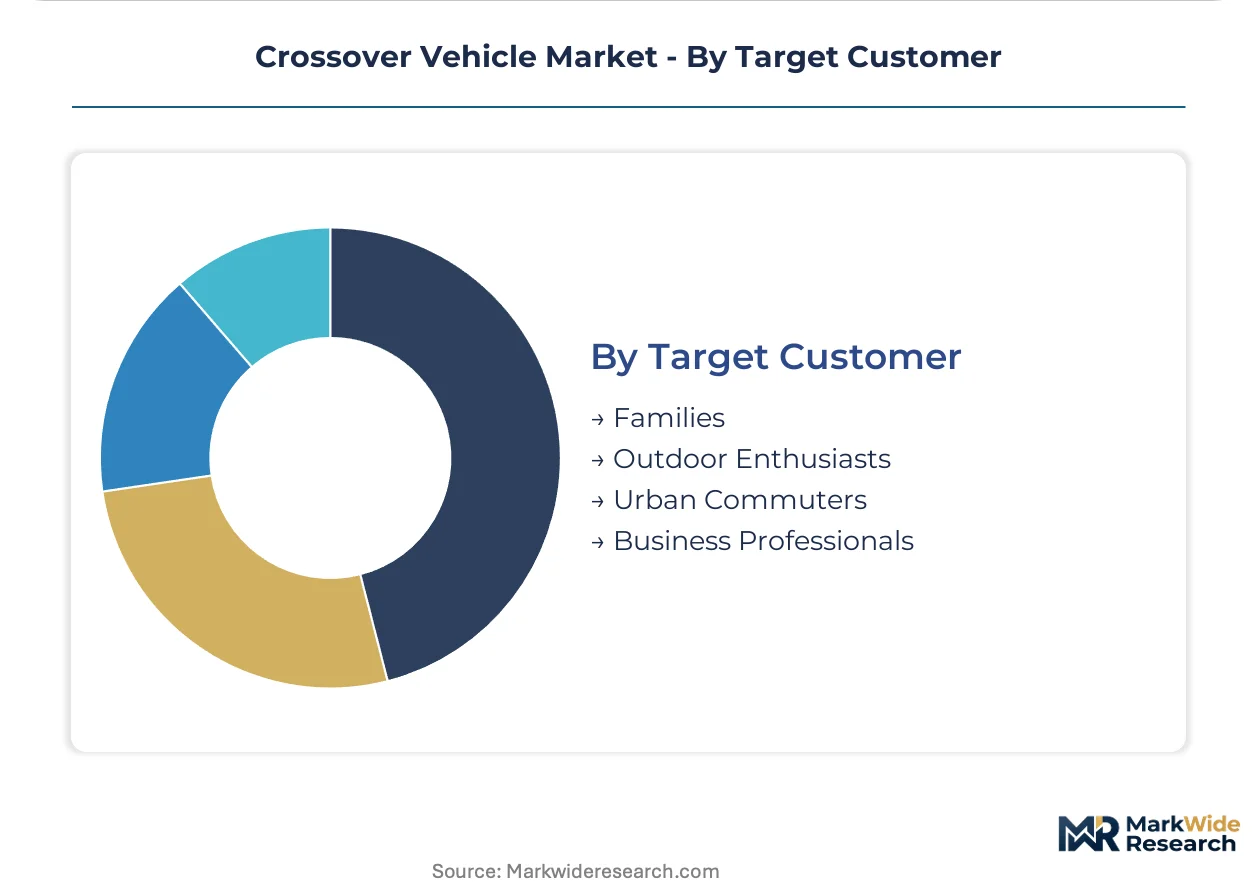
Target Customer:
Demographic concentration determines powertrain mix and feature bundling strategy.
- Families:Child-seat accommodation and rear entertainment systems drive three-row mid-size and full-size procurement across United States suburban school districts.
- Outdoor Enthusiasts:Roof-rail load ratings and all-wheel-drive ground clearance specifications attract camping and skiing participants in Rocky Mountain and Pacific Northwest states.
- Urban Commuters:Compact footprints with parking-assist technology serve apartment-dwellers in United States dense metropolitan cores where garage dimensions constrain vehicle size.
- Business Professionals:Premium audio, massaging seats, and semi-autonomous highway driving systems support executive lease programs and corporate fleet allocations.
Family demand anchors volume; professional segments sustain premium pricing power.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent pools in Stuttgart, Detroit, and Seoul anchor crossover development cycles, with regulatory stringency in each jurisdiction dictating powertrain portfolio allocation and factory tooling decisions.
United States
Suburban household demand for elevated ride height and commercial fleet procurement for last-mile logistics drive volume concentration. EPA Tier 3 tailpipe standards and NHTSA crashworthiness mandates compress development timelines for internal-combustion platforms. Michigan and Kentucky assembly plants anchor Ford's manufacturing footprint for Escape and Explorer lines.
Germany
Luxury crossover demand from business professionals and export-oriented production for European markets shape strategic priorities. EU Green Deal CO2 fleet targets and KBA homologation requirements accelerate plug-in hybrid engineering. Stuttgart engineering centers concentrate BMW's powertrain diversification investments for X-series portfolios.
Japan
Hybrid powertrain expertise and domestic market preference for compact footprints sustain competitive differentiation. METI energy efficiency benchmarks and JIS safety standards guide platform architecture decisions. Toyota's Aichi Prefecture facilities anchor global RAV4 and Highlander supply chains.
South Korea
Design-forward compact offerings and aggressive price-to-content positioning capture first-time buyer segments. MFDS vehicle safety protocols and national EV subsidy programs elevate electric powertrain priorities. Hyundai's Ulsan complex and Kia's Sohari Plant concentrate export-oriented assembly capacity.
China
Domestic brand ascendancy and battery supply chain integration reshape competitive dynamics. MIIT new energy vehicle mandates and GB standards compliance requirements dictate local product specifications. Shanghai and Guangzhou metropolitan clusters concentrate NIO, BYD, and Li Auto design studios targeting premium electric crossovers.
Crossover Vehicle Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The structure concentrates volume among five integrated manufacturers with multi-brand portfolios spanning mass-market and luxury segments. Three archetypes dominate: full-line conglomerates with truck and sedan heritage, premium specialists with motorsport lineage, and battery-electric natives with software-first architectures. Competitive moves center on modular platform sharing across segments and strategic cell supply partnerships with Asian battery manufacturers.
Within the full-line conglomerate tier, Toyota and Ford exemplify manufacturing scale advantages through hybrid powertrain leadership and truck-based SUV heritage respectively. Kia occupies a position between value-engineered mass-market penetration and design-forward differentiation. These three anchors represent distinct strategic postures: Toyota's dual-motor planetary systems, Ford's Michigan-Kentucky manufacturing density, and Kia's aggressive price-to-content ratios in compact segments.
| Leading Market Players |
|---|
| Kia |
| Ford |
| Toyota |
| BMW |
| Mazda |
| Honda |
| Subaru |
| Chevrolet |
| Hyundai |
| Others |
Supply Flow & Price Mechanics
Captive battery supply from Korean and Chinese cell manufacturers anchors pricing power for electric crossover variants, while outsourced semiconductor sourcing exposes margin compression when foundry capacity tightens. Tier 1 suppliers with in-house powertrain controller production capture premium positioning against competitors dependent on merchant chip markets.
Pricing Analysis
Bundled powertrain warranties and unbundled over-the-air feature subscriptions split transaction structures across the crossover segment. Three-tier pricing structure across premium, standard, and economy levels separates luxury appointments from mass-market content, with EPA certification grade and all-wheel-drive capability as primary differentiation drivers. Cost compression in compact hybrid tiers is intensifying because lithium-ion cell demand outpaces contracted supply. Fleet procurement managers exhibit highest price sensitivity; lease-driven business professionals show lowest.
Supply Chain Analysis
Dual-sourcing mandates from Detroit and Stuttgart OEMs require multi-supplier qualification for battery cell and power semiconductor procurement. Taiwan, South Korea, and China concentrate advanced chip fabrication, while Australia, Chile, and Indonesia feed critical mineral inputs into cathode active material production. The supply chain rests on single-source vulnerability for automotive-grade microcontroller units. Distribution runs through franchised dealer networks in most United States states, with direct-to-consumer channels gaining permitted access in select coastal markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The crossover segment reads as a late-cycle quality story where suburban household demand shifts toward premium electrified specifications with advanced driver-assistance content. Fleet operators simultaneously upgrade procurement standards for last-mile logistics applications.
For Market Incumbents: Anchor hybrid powertrain leadership through Michigan and Kentucky manufacturing density against emerging battery-electric specialists. Secure long-term cathode supply agreements with Korean material processors. Invest in over-the-air software architecture to defend against Silicon Valley talent poaching. Control dealer network relationships in CARB-aligned states where compliance complexity advantages established players.
For New Entrants and Emerging Players: Rural United States households underserved by DC fast-charging infrastructure represent a penetrable white-space target for plug-in hybrid variants with extended electric range. Fleet-as-a-service subscription models in secondary metropolitan areas offer channel access without franchise law entanglement. Pursue vehicle-to-grid certification partnerships with regional utilities to differentiate residential storage positioning.
For Investors and Strategic Acquirers: Roll-up economics work for vertically integrated battery pack assemblers because cell-to-pack standardization enables scale across multiple OEM customer programs. The five-to-ten year viability window favors platform technology specialists with captive software-defined vehicle architectures. Target acquisition archetype: mid-tier suppliers with homologation expertise in dual-certification markets. Watch EPA-NHTSA regulatory divergence resolution as inflection indicator for capital allocation toward compliance-variant production capacity.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Long-term cell offtake contracts with Korean manufacturers secure cathode supply for electric crossover ramp. |
| Platform Standardization | Modular unibody architectures shared across compact and mid-size segments absorb EPA compliance engineering costs. |
| Software-Defined Vehicle Investment | Over-the-air update capability extends functional relevance and creates recurring revenue streams from feature subscriptions. |
| Geographic Manufacturing Footprint | Michigan and Kentucky assembly concentration supports Ford's hybrid powertrain scale and logistics fleet procurement relationships. |
| Charging Infrastructure Partnership | Utility collaboration on bidirectional charging integration positions electric crossovers as residential storage assets in suburban markets. |
Methodological Framework
Multiple input streams — OEM platform engineering disclosures, Tier 1 supplier procurement data, and vehicle registration databases — were reconciled to construct segment-level volume estimates. Primary interviews with powertrain development directors, fleet procurement managers, dealership operations heads, and regulatory compliance officers at Detroit, Stuttgart, and Seoul engineering centers informed demand-side assumptions. Secondary validation drew from EPA certification filings, NHTSA crash test databases, IHS Markit production data, and state-level registration statistics. Bottom-up build from model-level transaction prices and top-down reconciliation against manufacturer revenue disclosures ensured cross-verification.
Historical volume trajectories were cross-referenced against panel input from industry participants to anchor growth assumptions across the analysis window. The analytical framework modeled vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster as segmentation dimensions. CAGRs were derived from fitted trend lines adjusted for regulatory inflection points and technology cost curves. Forecast inputs incorporated battery cell price decline trajectories, charging infrastructure deployment schedules, and EPA Tier 3 compliance timeline assumptions without year-specific anchoring.
Underlying measurement precision varies by segment; electric powertrain variants carry tighter precision than emerging subscription mobility models due to registration data availability. Forecasts reflect assumptions about regulatory stability, commodity price normalization, and semiconductor supply recovery that could shift materially. Deviation in EPA-NHTSA regulatory divergence resolution or lithium supply contract renegotiations would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hybrid Vehicles
India Hybrid Vehicles Market
Hybrid Vehicles
Hybrid Truck Market
Hybrid Vehicles
Plug-In Hybrid Electric Vehicles (PHEV) Market
Hybrid Vehicles
Hybrid Electric Self-Driving Car Market
Hybrid Vehicles
Asia-Pacific Micro-Hybrid Vehicles Market
Hybrid Vehicles
United Arab Emirates Hybrid and Electric Vehicles Market
Hybrid Vehicles
Hybrid Train Market
Hybrid Vehicles
Smart Hybrid Vehicle Market
Hybrid Vehicles
Europe Mild Hybrid Vehicles Market
Hybrid Vehicles
Hybrid Powertrain Systems Market
Hybrid Vehicles
United States Hybrid Electric Vehicle Battery Market
Hybrid Vehicles
Hydrogen Vehicles Market
Hybrid Vehicles
Middle East and Africa Hybrid Electric Vehicle Battery Market
Hybrid Vehicles
Global Hybrid-Electric Vehicle Insulation Market
Hybrid Vehicles
Global Hybrid Vehicle Transmission Market
Hybrid Vehicles
Asia-Pacific Mild-Hybrid Vehicles Market