
 Germany Automotive Parts Aluminium Die Casting Market | 2026-2036
Germany Automotive Parts Aluminium Die Casting Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Automotive Parts Aluminium Die Casting Market Foresight
Multi-source supplier networks for complex transmission housings is consolidating around fewer Tier-1 foundry partners with captive machining capacity. Rheinmetall AG anchors its position through backward integration into aluminium smelting and precision finishing operations. KSM Casting Group GmbH differentiates via dedicated high-pressure cells for structural battery tray components serving Stuttgart-based OEMs. GF Casting Solutions competes through its Swiss-German cross-border production footprint that navigates divergent carbon-border adjustment exposures.
Germany Automotive Parts Aluminium Die Casting involves injecting molten aluminium alloys—typically AlSi10Mg or AlSi12Cu—into hardened steel molds at pressures exceeding 1,000 bar to produce near-net-shape automotive components with wall thicknesses below 3 millimeters. The process yields parts with tensile strengths of 240–290 MPa, serving primarily to reduce vehicle curb weight while maintaining crashworthiness standards for structural and powertrain applications. Engine Components and Transmission Housings dominate current volume demand, reflecting ICE powertrain persistence amid electrification transition. Structural Framework applications represent the fastest-expanding segment, driven by aluminium-intensive battery enclosures and crash-management beams for electric vehicle platforms.
Germany's KBA enforces type-approval standards that shape alloy composition requirements and dimensional tolerances for safety-critical castings. REACH and the EU Green Deal's embedded carbon reporting obligations compel foundries to document primary aluminium sourcing and energy-intensive process emissions across supply chains. OEMs and Tier-1 suppliers must now decide whether captive foundry investments or long-term offtake agreements better secure qualified capacity for next-generation structural die-cast programmes.
Market Dynamics
The EU Green Deal's embedded carbon reporting obligations are forcing foundries to restructure supplier relationships and energy sourcing strategies for aluminium-intensive automotive programmes.
Growth Catalysts
- Powertrain electrification mandates:Stuttgart-based OEMs are accelerating procurement of structural battery tray die-castings to meet fleet CO2 reduction targets under EU automotive emissions regulations.
- KBA recyclability quotas:Germany's vehicle certification standards now mandate minimum recycled aluminium content thresholds, pulling secondary alloy demand through Bavarian supplier networks.
- AlSi10Mg alloy advances:High-pressure die-casting cells achieving sub-3mm wall thicknesses are unlocking crash-management beam applications previously reserved for stamped steel.
Market Restraints
- Primary aluminium price volatility:Energy-intensive smelting costs tied to European natural gas benchmarks create margin compression for foundries without captive energy hedging.
- Smelter concentration risk:German automotive die-casters remain dependent on a narrow base of European primary aluminium producers for alloy feedstock qualification.
- Steel substitution persistence:Hot-stamped boron steel retains cost advantages for certain crash-structure applications, limiting aluminium penetration in A-pillar and roof-rail segments.
Strategic Opportunities
- Thuringia supplier corridor:Underdeveloped foundry capacity in eastern German states offers greenfield investment sites with proximity to emerging EV battery cell manufacturing clusters.
- CSRD-aligned carbon accounting:Early compliance with EU Corporate Sustainability Reporting Directive requirements positions Tier-1 suppliers for preferential OEM sourcing terms.
- Digital twin convergence:Integration of real-time thermal simulation with high-pressure cell controls is reducing tooling iteration cycles for complex transmission housing programmes.
Industry Challenges
- Tooling engineer scarcity:Germany's vocational pipeline produces insufficient numbers of die-design specialists capable of managing multi-cavity moulds for structural EV components.
- REACH substance authorization timelines:Extended chemical safety assessment periods for novel alloy additives delay qualification of next-generation high-ductility formulations.
- Legacy machining integration:Foundries with captive finishing operations face capital-intensive retooling to accommodate larger structural castings with tighter geometric tolerances.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Automotive Parts Aluminium Die Casting Market |
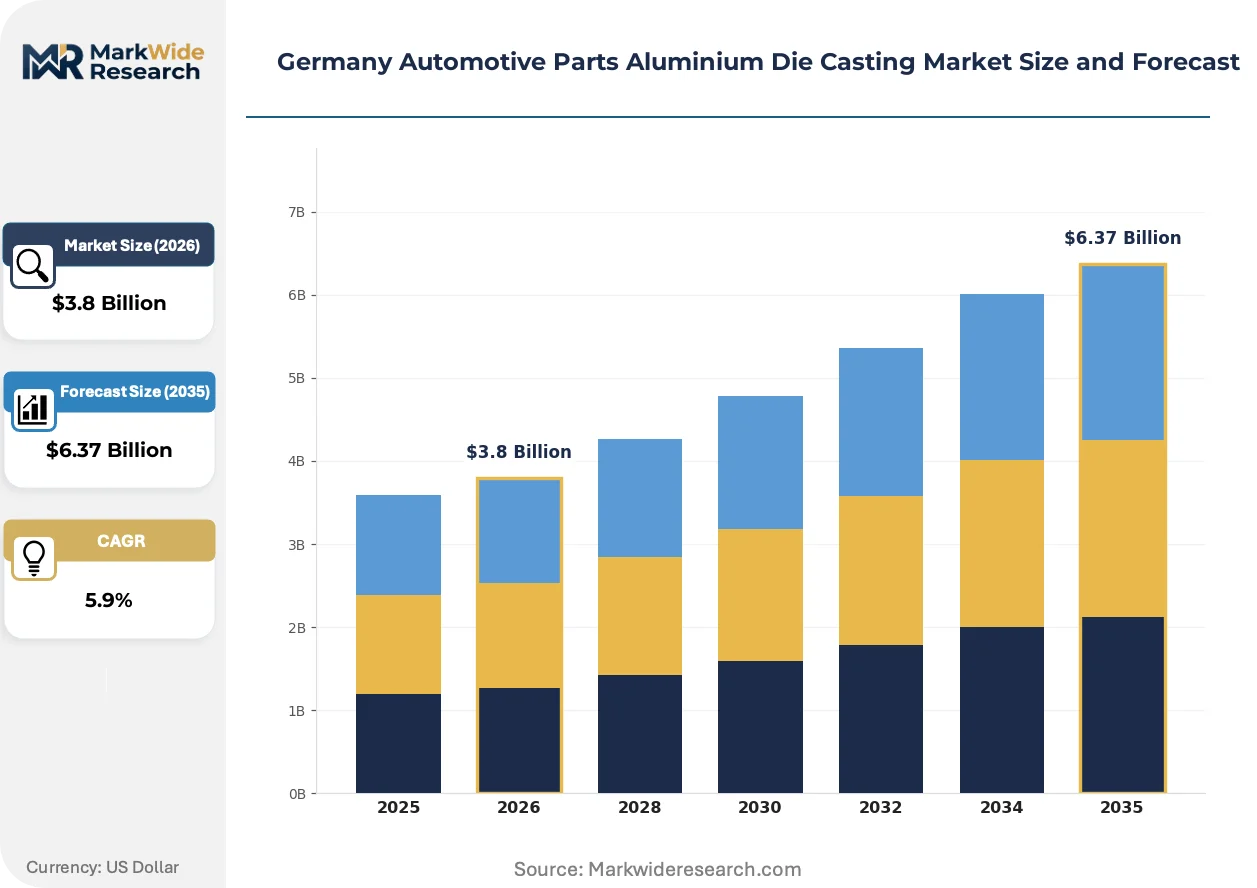
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.37 Billion |
| CAGR (2026 – 2036) | 5.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Components, Transmission Housings, Chassis Parts, Suspension Elements, Brake Components, Cooling System Parts Technology: High Pressure Die Casting, Low Pressure Die Casting, Gravity Die Casting, Squeeze Die Casting, Thixoforming Application: Powertrain Systems, Structural Framework, Thermal Management, Safety Equipments, Interior Components End User: OEMs, Tier-1 Suppliers, Vehicle Assemblers, Aftermarket Providers |
| Companies Covered | Ryobi Limited, KSPG AG, Nemak, GF Casting Solutions, Interplex Holdings Ltd., Rheinmetall AG, KSM Casting Group GmbH, Amtek Group, Handtmann Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Automotive Parts Aluminium Die Casting Market Shifts & Advancements
Process digitization and alloy formulation advances are compressing development timelines while regulatory carbon accounting reshapes competitive positioning across German automotive supply chains.
Real-time thermal monitoring systems using embedded sensor arrays are automating temperature gradient control in high-pressure die-casting cells. Tier-1 suppliers serving Munich-based OEMs are deploying these systems across new structural component programmes. The technology is automating quality assurance workflows that previously required manual inspection protocols, reducing porosity-related scrap rates.
REACH substance restrictions on certain release agents and lubricant formulations are compelling foundries to reformulate die-spray chemistries. Industrial consequence includes extended process validation periods and higher per-shot consumable costs. Bavarian structural casting specialists are responding by consolidating supplier relationships with chemical partners holding early authorization dossiers.
Consolidated procurement frameworks are displacing fragmented spot purchasing for qualified die-casting capacity. Stuttgart-headquartered OEMs are shifting toward multi-year offtake agreements with captive machining provisions, compressing the vendor base. This concentration is most visible in transmission housing programmes where single-source qualification timelines exceed 18 months.
Germany Automotive Parts Aluminium Die Casting Market Segmentation
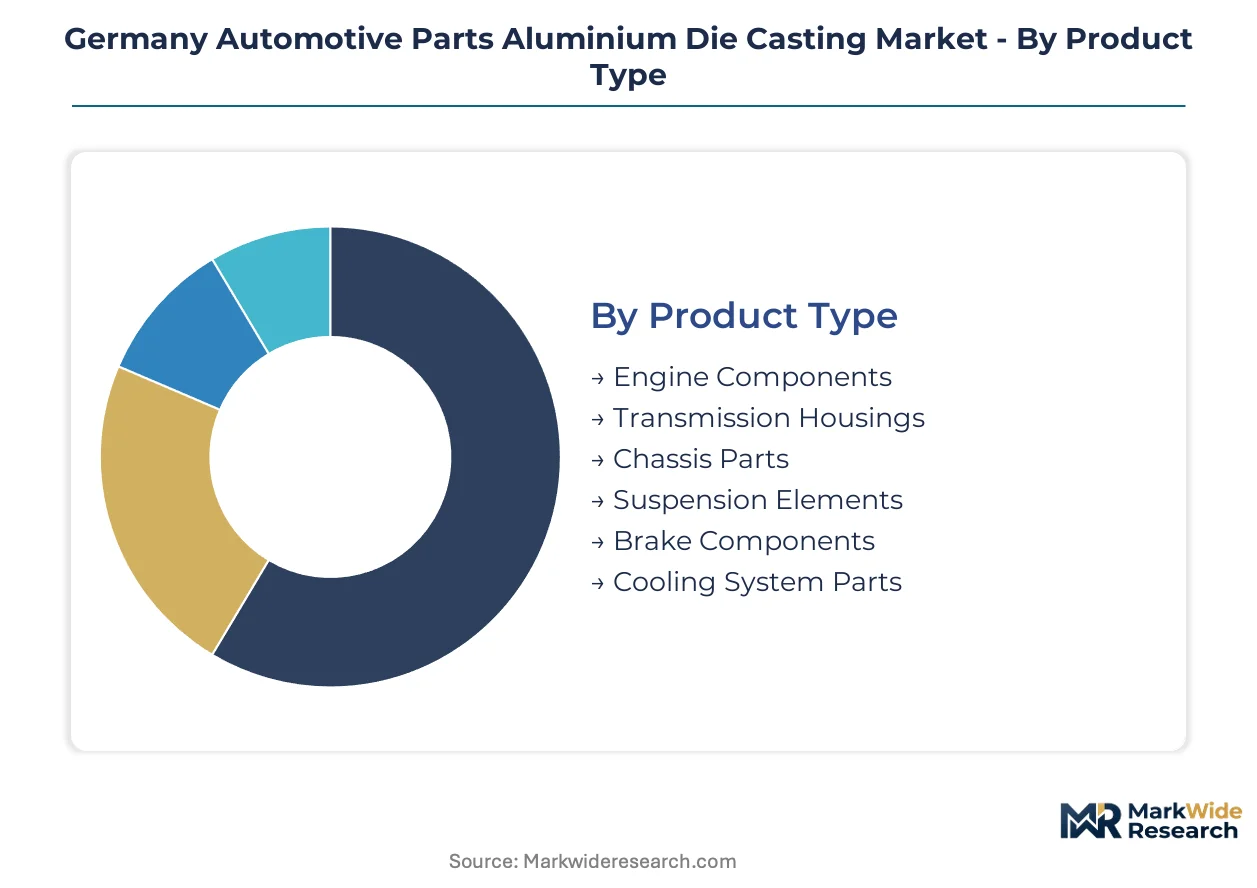
Segmentation in German automotive die-casting reveals how capital deployment, regulatory thresholds, and OEM sourcing strategies concentrate value across distinct technical and commercial boundaries. Each dimension carries implications for foundry investment cycles, alloy qualification timelines, and competitive positioning within Bavaria's supplier corridors.
Product Type:
Capital intensity varies sharply across product categories, with multi-cavity tooling for structural transmission housings demanding the highest upfront investment in hardened steel dies and thermal management systems.
- Engine Components:Cylinder heads, engine blocks, and oil pans fabricated from AlSi10Mg or AlSi12Cu alloys serve persistent ICE production lines while accommodating hybrid powertrain adaptations. Demand concentrates in Stuttgart and Munich supplier ecosystems where Porsche and BMW maintain legacy foundry partnerships for high-volume engine programmes.
- Transmission Housings:Complex multi-part assemblies with integrated cooling channels and mounting bosses require 1,000+ bar injection pressures and precision finishing operations. Bavarian Tier-1 suppliers anchor capacity here, driven by dual-clutch and electric axle gearbox procurement from Ingolstadt and Munich-based OEMs.
- Chassis Parts:Subframes and cross-members prioritize fatigue resistance over ultimate tensile strength.
- Suspension Elements:Control arms and knuckles demand post-cast heat treatment for dimensional stability.
- Brake Components:Caliper housings and master cylinders favor gravity die-casting for porosity control.
- Cooling System Parts:Thermostat housings and water pump bodies serve thermal management across powertrain architectures.
Transmission Housings absorb the bulk of installed capacity; Structural Framework applications (via Chassis Parts cross-over) are expanding most quickly.
Technology:
Process selection directly determines achievable wall thickness, surface finish, and cycle economics, with high-pressure cells dominating structural applications requiring sub-3mm precision.
- High Pressure Die Casting:Molten alloy injection above 1,000 bar produces near-net-shape components with wall thicknesses below 3 millimeters and tensile strengths of 240–290 MPa. KSM Casting Group and GF Casting Solutions deploy these cells across Bavaria for battery tray and crash-management beam programmes serving Stuttgart-based OEMs.
- Low Pressure Die Casting:Controlled fill rates reduce turbulence and porosity in thick-walled structural castings. Foundries in Baden-Württemberg favor this approach for suspension knuckles and steering components where fatigue performance is critical.
- Gravity Die Casting:Simple tooling and lower energy intensity suit brake and cooling components with moderate mechanical demands.
- Squeeze Die Casting:Applied pressure during solidification eliminates shrinkage porosity in safety-critical parts.
- Thixoforming:Semi-solid processing enables complex geometries with reduced thermal history.
High Pressure Die Casting commands the greatest capital deployment; Thixoforming is gaining share fastest among emerging EV structural programmes.
Application:
Application segmentation tracks how electrification is reallocating die-casting volume from rotating ICE assemblies to stationary battery enclosures and crash structures.
- Powertrain Systems:Engine blocks, transmission cases, and electric motor housings constitute the historical volume base. Rheinmetall AG's backward integration into aluminium smelting secures alloy feedstock for these programmes across German OEM supply chains.
- Structural Framework:Battery enclosures, crash-management beams, and body-in-white nodes represent the steepest expansion trajectory. AlSi10Mg alloys with sub-3mm wall thicknesses now substitute for stamped steel in A-pillar and floor pan applications previously reserved for higher-strength materials.
- Thermal Management:Heat exchanger housings and coolant manifolds bridge ICE and EV architectures.
- Safety Equipments:Airbag housings and seat belt anchors demand traceable mechanical properties.
- Interior Components:Dashboard carriers and seat frames prioritize weight reduction over structural load-bearing.
Powertrain Systems retain the deepest supplier relationships; Structural Framework is climbing the fastest as OEMs redesign platforms around battery integration.
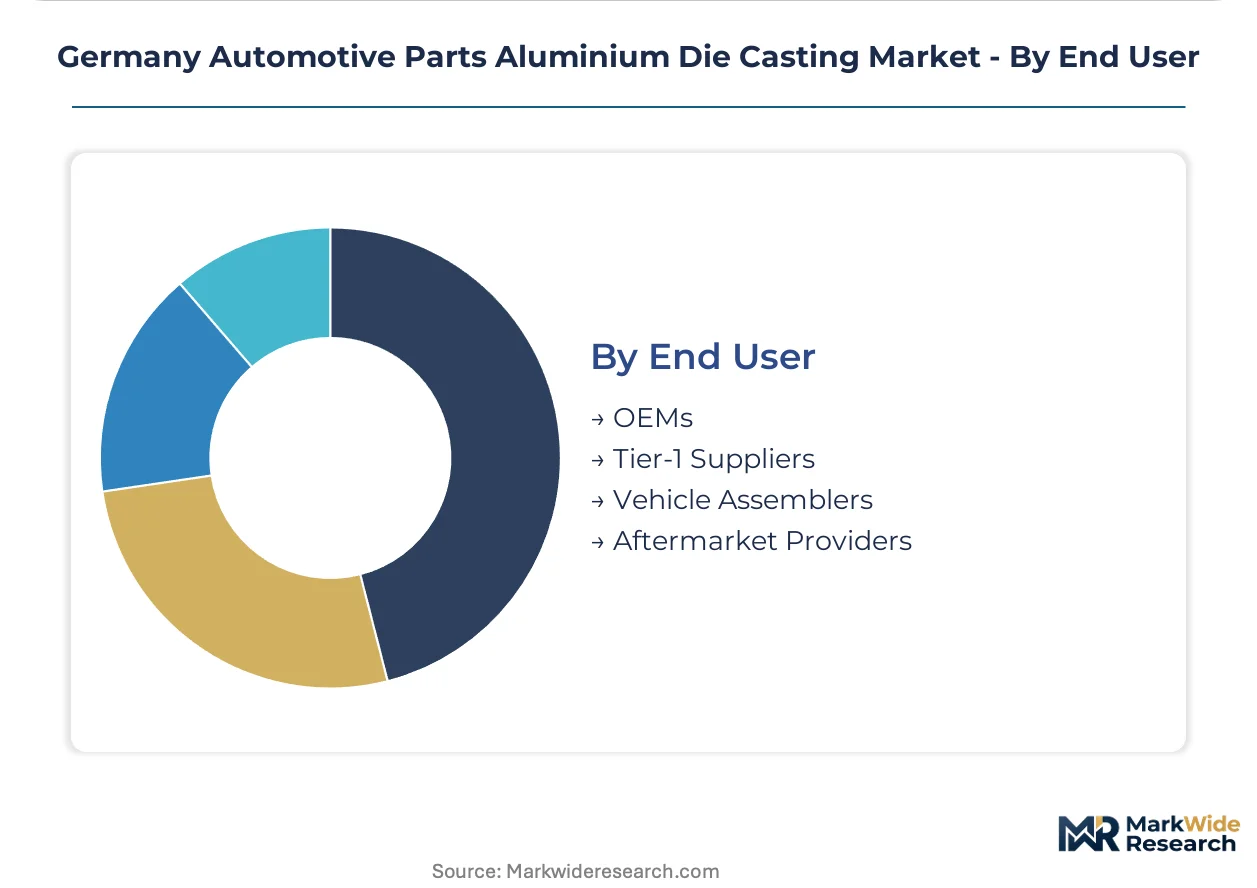
End User:
Customer type segmentation exposes divergent procurement rhythms, with OEM direct sourcing consolidating around multi-year offtake agreements while aftermarket channels fragment across spot purchasing.
- OEMs:BMW, Mercedes-Benz, and Volkswagen Group headquarters in Munich, Stuttgart, and Wolfsburg drive qualified capacity investment through 18-month single-source qualification timelines. KBA type-approval standards and REACH compliance requirements filter the supplier base to foundries with documented carbon accounting and captive machining.
- Tier-1 Suppliers:Rheinmetall AG, KSM Casting Group, and GF Casting Solutions intermediate between foundries and vehicle assemblers, adding precision finishing and logistics integration. These players are consolidating procurement frameworks and compressing vendor bases for transmission housing programmes.
- Vehicle Assemblers:Contract manufacturers and specialty producers source standardized housings and brackets.
- Aftermarket Providers:Replacement part distributors operate through fragmented spot purchasing with lower qualification barriers.
OEMs direct the largest qualified capacity allocations; Tier-1 Suppliers are expanding most quickly through backward integration and captive machining investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive die-casting demand clusters along three industrial corridors where OEM headquarters and qualified supplier ecosystems overlap. Bavaria, Baden-Württemberg, and North Rhine-Westphalia concentrate the bulk of high-pressure cell capacity serving Stuttgart and Munich-based vehicle programs.
Bavaria
BMW and Audi procurement teams drive structural battery tray demand through Munich and Ingolstadt supplier networks. KBA type-approval standards enforce recyclability quotas that pull secondary alloy through Bavarian foundries. The Munich-Augsburg corridor hosts KSM Casting Group and GF Casting Solutions cells dedicated to EV platform components.
Baden-Württemberg
Porsche and Mercedes-Benz electrification programs sustain transmission housing volumes amid powertrain transition. REACH substance restrictions on die-spray chemistries extend validation timelines for Stuttgart-area foundries. The Stuttgart metropolitan region anchors Rheinmetall AG's backward-integrated smelting and precision finishing operations.
North Rhine-Westphalia
Volkswagen Group sourcing from Wolfsburg channels die-casting demand through western German supplier networks. EU Green Deal embedded carbon reporting compels foundries to document primary aluminium energy intensity. The Rhine-Ruhr industrial zone retains legacy engine component capacity serving hybrid powertrain adaptations.
Lower Saxony
Volkswagen's Wolfsburg headquarters proximity sustains qualified supplier relationships for powertrain castings. CSRD-aligned carbon accounting requirements filter Tier-1 selection toward foundries with documented supply chain emissions. The Hanover-Brunswick corridor hosts machining-integrated operations serving transmission housing programs.
Hesse
Supplier networks radiating from Frankfurt support logistics-intensive just-in-sequence delivery to multiple OEMs. Energy-intensive smelting costs tied to European natural gas benchmarks create margin pressure for foundries without captive hedging. The Rhine-Main region concentrates chemical supplier relationships for REACH-compliant die-spray formulations.
Germany Automotive Parts Aluminium Die Casting Market Competitive Landscape
Backward integration dominates the current landscape as foundries secure alloy feedstock and machining capacity. The supplier base concentrates around Tier-1 specialists with captive smelting, precision finishing, or cross-border production footprints. Three archetypes define competitive positioning: integrated smelter-foundry operators, high-pressure cell specialists for structural EV components, and Swiss-German cross-border producers navigating carbon-border adjustments. Consolidation through multi-year offtake agreements and captive machining provisions compresses vendor counts for qualified transmission housing programs.
Within the integrated operator tier, Rheinmetall AG exemplifies backward integration into aluminium smelting and precision finishing. KSM Casting Group GmbH occupies a position among high-pressure cell specialists serving Stuttgart-based OEM structural programs. GF Casting Solutions represents the cross-border archetype with production footprints spanning German and Swiss jurisdictions to manage divergent carbon-border adjustment exposures.
| Leading Market Players |
|---|
| Ryobi Limited |
| KSPG AG |
| Nemak |
| GF Casting Solutions |
| Interplex Holdings Ltd. |
| Rheinmetall AG |
| KSM Casting Group GmbH |
| Amtek Group |
| Handtmann Group |
| Others |
Supply & Pricing Matrix
London Metal Exchange primary aluminium benchmark pricing cascades through German automotive die-casting supply chains, compressing margins for foundries lacking captive smelting or long-term hedging instruments against European natural gas volatility.
Pricing Analysis
High-volume transmission housing programmes trade margin for guaranteed offtake, while structural EV component specialists capture premium pricing through KBA qualification timelines and CSRD-aligned carbon accounting. Price differentiation hinges on alloy traceability documentation and captive machining integration. Cost compression in standard-grade engine components intensifies as hybrid powertrain demand softens. Aftermarket distributors exhibit highest price sensitivity; OEM direct procurement teams prioritize qualification reliability over unit cost.
Supply Chain Analysis
Primary aluminium feedstock rests on Norwegian hydroelectric smelters, Icelandic low-carbon producers, and German remelt operations for secondary alloy qualification. German foundries draw from hardened steel die manufacturers in Italy and Austria, plus specialty release agent formulators in the Rhine-Main chemical corridor. Single-source vulnerability concentrates in qualified high-pressure cell tooling exceeding 18-month replacement cycles. Distribution runs through just-in-sequence logistics networks radiating from Munich, Stuttgart, and Wolfsburg OEM assembly plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
German automotive aluminium die-casting functions as a cost-of-compliance market where REACH substance authorizations and KBA recyclability quotas erect structural barriers against unqualified competitors.
For Market Incumbents: Cement qualification moats by accelerating CSRD-aligned carbon accounting documentation and securing captive machining capacity for structural battery tray programmes. Steel substitution persistence in A-pillar segments demands alloy formulation R&D investment. Backward integration into secondary aluminium smelting insulates margin positions against LME volatility.
For New Entrants and Emerging Players: Tier-2 foundry partnerships offer the fastest qualification pathway into transmission housing supply chains without bearing full KBA certification burden. Thuringia's underdeveloped capacity and proximity to emerging EV battery clusters represents the most penetrable geography. Target digital twin convergence capabilities to compress tooling iteration cycles for complex multi-cavity moulds.
For Investors and Strategic Acquirers: Distressed-cycle entries favor Swiss-German cross-border producers with divergent carbon-border adjustment exposure management. Long-term viability across the analysis window depends on structural EV component qualification pipelines rather than legacy ICE engine block volumes. Watch tooling engineer scarcity indices as inflection signal for qualified capacity constraints.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Secondary Smelting | Captive alloy supply secures margin insulation against LME volatility and REACH traceability mandates. |
| High-Pressure Cell Capacity Expansion | Sub-3mm wall thickness capability unlocks structural battery tray procurement from Stuttgart-based OEMs. |
| Digital Twin Process Convergence | Real-time thermal simulation integration reduces porosity scrap rates in complex transmission housing programmes. |
| CSRD-Aligned Carbon Accounting Certification | Documented supply chain emissions positioning enables preferential OEM sourcing terms under EU Green Deal. |
| Thuringia Greenfield Development | Eastern German foundry sites capture proximity advantages to emerging EV battery cell manufacturing clusters. |
Research Methodology
Independent corroboration across OEM platform engineering directors, Tier-1 foundry procurement leads, and KBA type-approval specialists underwrites the qualitative findings. Primary fieldwork encompassed technical discussions with high-pressure cell operators, die-design specialists, and REACH compliance officers at Bavarian and Baden-Württemberg production facilities. Secondary validation drew from German Federal Motor Transport Authority certification databases, EU ETS emissions registries, and aluminium industry trade association capacity surveys. Bottom-up segment sizing triangulated against top-down OEM procurement volume estimates.
Rate-of-change decomposition across product type, technology platform, application segment, and end-user category anchored the analytical framework. The projection horizon spans powertrain electrification transition curves, KBA regulatory phase-in schedules, and alloy substitution dynamics in crash-structure applications. CAGRs derived from installed capacity utilization trends, OEM platform launch cadences, and foundry investment cycle timing. Industry-specific inputs encompassed AlSi10Mg alloy adoption rates and high-pressure die-casting cell deployment pipelines.
Several conditions sit outside the modeled scope, including abrupt REACH substance restriction expansions, unanticipated primary aluminium supply disruptions, and steel-aluminium cost parity inflections. Forecasts reflect documented assumptions regarding OEM electrification commitment durability and secondary alloy qualification timeline stability. A small set of named triggers warrants ongoing watch: tooling engineer pipeline output rates, Nordic smelter energy cost positions, and EU carbon border adjustment mechanism implementation scope.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
France Automotive Parts Magnesium Die Casting Market
Automotive Parts
Friction Pads Market
Automotive Parts
Global Car Air Filter Market
Automotive Parts
Fluid Couplings Market
Automotive Parts
Russia Automotive Parts Magnesium Die Casting Market
Automotive Parts
Automotive Pinion Gear Market
Automotive Parts
Europe Automotive Parts Zinc Die Casting Market
Automotive Parts
South America Automotive Lubricants Market
Automotive Parts
Suspension Bump Stopper Market
Automotive Parts
Asia-Pacific Electric Power Steering Market
Automotive Parts
Automotive Seat Adjusters Market
Automotive Parts
North America Automotive Parts Zinc Die Casting Market
Automotive Parts
Battery Jump Starters Market
Automotive Parts
Uae Commercial Vehicles Lubricants Market
Automotive Parts
Automotive Disc Brake Market
Automotive Parts
Global All Wheel Drive Market