
 Automatic Bus Door System Market | 2026-2036
Automatic Bus Door System Market Size, Share, and Industry Trends Forecast 2026-2036
Automatic Bus Door System Market Analytics
Transit agency procurement consolidation across European metropolitan networks is expanding the addressable market for integrated door-and-access platforms. AB Volvo leverages its captive chassis production to bundle door systems with electric bus platforms. Continental sustains R&D intensity in sensor-integrated electric actuators that reduce maintenance intervals. Schaltbau Holding AG anchors its position through rail-derived sealing technology adapted for severe-service bus environments.
An automatic bus door system comprises electromechanical or pneumatic door panels, drive units, control electronics, and safety sensors engineered to open and close passenger entryways with cycle times under three seconds and obstacle detection sensitivity to twenty-five millimeters. These systems serve the dual purpose of passenger throughput maximization and regulatory compliance with accessibility and safety mandates. Sliding configurations dominate premium electric bus contracts where low-floor architectures demand minimal intrusion into cabin space, while pneumatic technology retains share in retrofit markets where compressed air infrastructure already exists. Electric actuation represents the fastest-growing technology segment as OEMs pursue weight reduction and energy recuperation compatibility.
The European Union enforces CE marking and MDR-adjacent safety expectations through ECHA REACH compliance for polymer components in door seals and friction surfaces. The US Department of Transportation applies ADA accessibility standards and NHTSA motor vehicle safety regulations that dictate door width, threshold height, and emergency release mechanisms. China's MIIT publishes GB standards for urban bus component interoperability that gate market access for imported systems. Stakeholders must monitor how evolving accessibility mandates and electrification timelines reshape specification requirements before committing to platform architectures.
Market Dynamics
Electrification mandates across municipal transit fleets are forcing synchronous redesign of door architectures, as low-floor electric buses demand lighter, more compact entry systems that preserve battery range and cabin space.
Growth Catalysts
- EU Clean Vehicle Directive:Procurement quotas for zero-emission buses in Germany, France, and the Netherlands are accelerating replacement cycles and bundling door system upgrades with chassis orders.
- ADA accessibility thresholds:US transit agencies must meet revised doorway width and threshold height standards, triggering retrofit demand across aging diesel fleets in Chicago, Los Angeles, and New York.
- Sensor fusion architectures:Lidar and radar integration into door control electronics is enabling sub-25 millimeter obstacle detection that satisfies insurer liability requirements.
Market Restraints
- Neodymium magnet supply:Electric actuator motors depend on rare earth elements concentrated in Chinese processing facilities, exposing OEMs to export quota volatility.
- Pneumatic infrastructure lock-in:Legacy compressed air systems in Eastern European depots create switching costs that delay electric actuator adoption in retrofit markets.
- REACH polymer compliance:ECHA restrictions on seal compounds force reformulation cycles that extend qualification timelines by 8-14 months.
Strategic Opportunities
- India urban bus procurement:State transport undertakings in Maharashtra and Karnataka are issuing tenders for 12-meter electric buses with specified low-floor door configurations.
- Bus rapid transit corridors:Dedicated lane systems in Jakarta, Istanbul, and Bogotá require high-cycle door systems with sub-2.5 second open-close sequences.
- GB standard harmonization:China's MIIT interoperability protocols create pathways for foreign suppliers to access provincial electric bus subsidy programs.
Industry Challenges
- Embedded software validation:ISO 26262 functional safety certification for door control units demands specialized automotive firmware engineers in short supply across Central European engineering clusters.
- Legacy fleet integration:Retrofit electric actuators onto 2010-2018 bus models requires mechanical adapters that prolong installation downtime and disrupt depot scheduling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automatic Bus Door System Market |
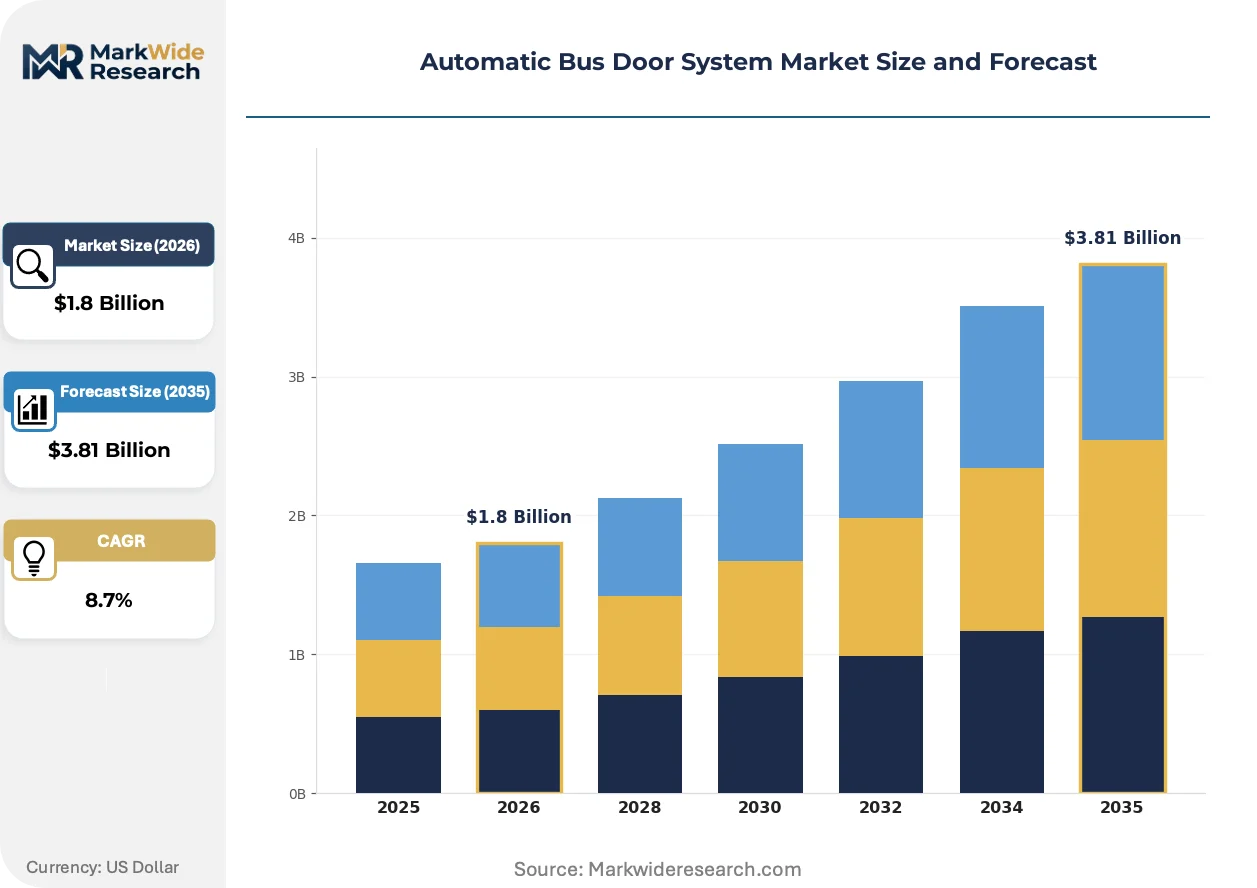
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Leaf, Double Leaf, Bi-Folding, Sliding Technology: Pneumatic, Electric, Hydraulic, Manual End User: Public Transport, Private Operators, School Buses, Shuttle Services Installation Type: OEM, Retrofit, Aftermarket, Integrated Solutions |
| Companies Covered | Ventura Systems CV, Vapor Ricon Europe, AB Volvo, IVY MACHINERY (NANJING) CO., LTD., MASATS S.A., Schaltbau Holding AG, Continental, Bode Sud, kbt gmbh, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automatic Bus Door System Market Evolving Landscape
Door system engineering is converging with autonomous vehicle perception stacks, as transit operators demand predictive maintenance capabilities and real-time passenger flow analytics integrated into entry mechanisms.
Intelligent edge computing modules embedded in door controllers is rewriting how maintenance intervals are calculated. Transit agencies in Stockholm and Singapore are piloting systems that process vibration and current-draw signatures locally to predict seal wear and motor degradation. This distributed processing architecture is compressing warranty claim rates and enabling condition-based service contracts that displace fixed-interval maintenance schedules.
REACH Annex XVII amendments restricting per- and polyfluoroalkyl substances are compelling seal manufacturers to validate fluorine-free compounds for severe-service environments. German KBA type-approval processes now require extended salt-spray testing for alternative materials. Suppliers with pre-validated polymer portfolios are securing preferred-vendor status in Nordic markets where road de-icing chemicals accelerate seal degradation.
Fleet-as-a-service contracting is altering how door systems are specified and financed. Transit authorities in London and Sydney are transferring capital risk to operating lessors who demand modular, swappable door subassemblies to maximize residual vehicle value. This model favors suppliers with standardized platform architectures over custom-engineered legacy configurations.
Automatic Bus Door System Market Segmentation
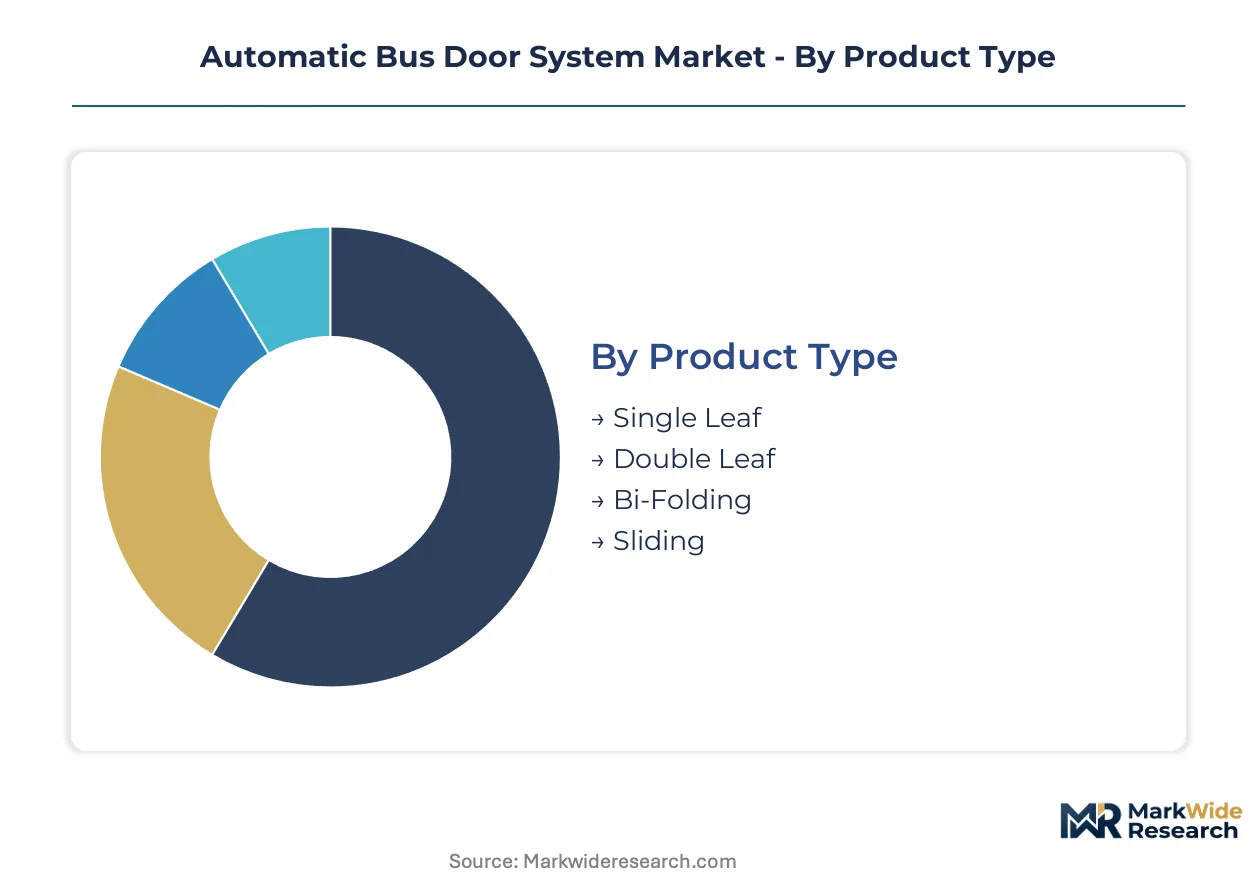
Door system specifications vary sharply across transit applications, with electric bus architectures demanding fundamentally different sealing, actuation, and control electronics than legacy diesel platforms. Procurement patterns fragment further between municipal fleet standardization and private operator cost sensitivity.
Product Type:
Configurations differ in panel count, kinematics, and cabin intrusion, with low-floor electric bus designs favoring minimal spatial footprint.
- Single Leaf:One rigid panel swings outward or slides laterally. This configuration dominates school bus retrofits in the United States where narrow roadway clearances limit panel width.
- Double Leaf:Two symmetrical panels meet at centerline with synchronized drive units. Urban transit agencies in Germany specify double-leaf systems for 12-meter electric buses to achieve ADA-compliant 1,300-millimeter clearances without excessive outward swing.
- Bi-Folding:Panels articulate mid-span to reduce sweep radius. Bi-folding designs concentrate in London's constrained streetscape where sidewalk encroachment triggers regulatory penalties.
- Sliding:Panels translate parallel to the vehicle body. Sliding systems serve premium intercity coaches where aerodynamic sealing and thermal insulation outweigh acquisition cost premiums.
Double Leaf leads on scale; Sliding leads on momentum.
Technology:
Actuation methods determine weight, energy consumption, and maintenance cadence, with electrification timelines accelerating technology transitions.
- Pneumatic:Compressed air drives cylinder-actuated panels through valve-controlled circuits. Eastern European depots in Poland and Czechia retain pneumatic infrastructure from Soviet-era fleet legacies, delaying electric conversion.
- Electric:Brushless DC motors with integrated position sensors enable precise motion profiles and regenerative braking compatibility. Electric actuation gains share fastest in Chinese electric bus production where MIIT subsidy rules favor energy recuperation systems.
- Hydraulic:Pressurized fluid circuits deliver high force density for heavy-duty applications. Hydraulic systems persist in articulated bus applications serving Bogotá's TransMilenio corridors where 18-meter vehicles impose severe door loading.
- Manual:Unpowered panels with mechanical latches serve emergency exits and auxiliary doors. Manual configurations concentrate in Indian state transport undertakings where acquisition cost constraints override automation requirements.
Pneumatic retains installed base dominance; Electric commands new-build preference.
End User:
Procurement authority and operating economics shape specification stringency and contract structure across user categories.
- Public Transport:Municipal agencies with dedicated capital budgets and regulatory compliance mandates. Transit authorities in Chicago and Los Angeles bundle door system upgrades with federal ADA remediation grants.
- Private Operators:Commercial fleet owners prioritizing total cost of ownership and residual value. Intercity operators in Turkey select modular door subassemblies to maximize second-hand export value to Central Asian markets.
- School Buses:District-level procurement with federally mandated safety specifications. US NHTSA regulations dictate automatic door interlocks with stop-arm deployment systems.
- Shuttle Services:Airport and corporate campus operators with high-frequency, low-distance cycles. Singapore Changi Airport specifies sub-2.5-second cycle times to minimize apron congestion.
Public Transport concentrates procurement volume; Shuttle Services exhibit steepest specification escalation.
Installation Type:
Channel structure determines supplier margin capture and customer relationship durability.
- OEM:Factory-integrated systems specified during chassis design. AB Volvo and Daimler Buses source door platforms through multi-year supply agreements with tier-one system integrators.
- Retrofit:Replacement installations on in-service vehicles. Retrofit demand surges in Germany as KBA type-approval deadlines force accessibility upgrades on pre-2015 diesel fleets.
- Aftermarket:Component-level replacement of seals, actuators, and control modules. Aftermarket revenue concentrates in Nordic markets where salt-induced seal degradation accelerates consumable turnover.
- Integrated Solutions:Door-access-platform bundles combining entry systems with fare collection and passenger counting. Integrated offerings gain traction in Sydney where Transport for New South Wales mandates data interoperability across subsystem vendors.
OEM captures value-chain margin; Integrated Solutions expand addressable revenue per vehicle.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent clusters in Stuttgart, Wolfsburg, and Munich anchor German design authority for electromechanical door architectures. Chinese manufacturing scale in Changzhou and Xiamen drives cost-efficient electric actuator production. Indian state transport procurement in Maharashtra and Karnataka is accelerating specification upgrades for low-floor urban bus fleets.
United States
Federal transit capital grants from the Federal Transit Administration are channeling $5.6 billion annually into bus fleet modernization. NHTSA motor vehicle safety regulations and ADA accessibility mandates enforce 1,300-millimeter doorway clearances and emergency release mechanisms. Chicago Transit Authority and Los Angeles Metro are bundling door system replacements with zero-emission bus procurements.
Germany
KBA type-approval deadlines for accessibility compliance are forcing retrofit cycles on pre-2015 diesel fleets. The EU Clean Vehicle Directive mandates 45% zero-emission bus procurement quotas by 2025, accelerating electric platform adoption. Stuttgart-based engineering clusters supply integrated door-and-chassis platforms to Daimler Buses and MAN Truck & Bus.
China
MIIT GB standards for urban bus component interoperability gate market access for imported door systems. Provincial subsidy programs in Jiangsu and Guangdong favor energy recuperation-compatible electric actuators. BYD and Yutong are vertically integrating door production through captive supply arrangements in Changzhou and Zhengzhou.
India
FAME-II subsidy extensions are funding 12-meter electric bus tenders by Maharashtra State Road Transport Corporation and Bangalore Metropolitan Transport Corporation. BIS certification requirements for automotive components create qualification barriers for unvalidated seal compounds. Tamil Nadu and Gujarat are emerging as assembly hubs for door system localization.
Brazil
PROCONVE emission standards are accelerating fleet turnover in São Paulo and Rio de Janeiro metropolitan networks. ANVISA technical regulations govern passenger safety equipment certification for urban transport. Marcopolo and Caio Induscar are sourcing pneumatic-to-electric conversion kits for articulated bus platforms serving Bogotá and Santiago export markets.
Automatic Bus Door System Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across technology tiers. The vendor base organizes around three strategic archetypes: integrated chassis-door platform suppliers, standalone electromechanical system specialists, and regional retrofit service providers. Consolidation pressure is intensifying as OEMs demand multi-year supply agreements with embedded software validation capabilities. Competitive moves center on backward integration into seal compound formulation and geographic expansion through provincial distributor networks.
Within the diversified industrial tier, AB Volvo and Continental exemplify platform-scale positioning through captive chassis production and sensor-integrated actuator R&D respectively. Schaltbau Holding AG occupies a specialist position derived from rail-sealing technology adaptation. Among European fabricators, MASATS S.A. and Bode Sud represent mid-scale electromechanical engineering capabilities focused on transit-specific kinematic solutions. Ventura Systems CV anchors the Benelux regional cluster with distribution reach into Nordic retrofit markets.
| Leading Market Players |
|---|
| Ventura Systems CV |
| Vapor Ricon Europe |
| AB Volvo |
| IVY MACHINERY (NANJING) CO., LTD. |
| MASATS S.A. |
| Schaltbau Holding AG |
| Continental |
| Bode Sud |
| kbt gmbh |
| Others |
Value Network & Pricing Analysis
Federal ADA remediation grants bundling door system replacements with zero-emission bus procurements are compressing supplier margins while forcing capacity reallocation toward electric actuator platforms that command certification premiums.
Pricing Analysis
Capacity additions in Changzhou and Xiamen are reshaping price floors for electric actuators, displacing pneumatic legacy systems in new-build contracts. Three-tier pricing structure across premium sensor-integrated, standard electromechanical, and economy pneumatic levels stratifies by certification grade and after-sales service bundling. Cost compression in economy tiers is intensifying because Chinese OEMs are vertically integrating door production. Private operators in Turkey exhibit highest price sensitivity; transit authorities in Germany show lowest sensitivity due to federal grant absorption.
Supply Chain Analysis
Transit agencies in Chicago and Los Angeles now mandate dual-source qualification for door control electronics to mitigate single-source vulnerability. Manufacturing concentrates in Germany, China, and the United States. Electric actuator motors draw from rare earth processing concentrated in Chinese facilities; seal compounds hinge on polymer feedstocks subject to ECHA REACH restrictions. Tariff exposure on processed neodymium creates supply chain risk. Distribution runs through tier-one system integrators holding multi-year OEM supply agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play: European accessibility mandates enforce premium pricing for certified systems while Indian FAME-II subsidies compress margins on volume tenders, creating divergent margin pools.
For Market Incumbents: Cement platform-scale positioning through captive supply of sensor-integrated actuators to defend against emerging Chinese OEMs vertically integrating door production. Deepen backward integration into fluorine-free seal compound formulation ahead of REACH Annex XVII amendments to lock in preferred-vendor status with Nordic transit agencies. For New Entrants and Emerging Players: State transport undertakings in Maharashtra and Karnataka represent an underserved buyer archetype with specified low-floor door configurations and limited incumbent relationships. Penetrate through modular subassembly offerings that align with fleet-as-a-service contracting models spreading from London and Sydney. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale electromechanical specialists holding rail-derived sealing technology adapted for severe-service bus environments. Long-term viability centers on software validation capabilities for ISO 26262 functional safety certification. Watch for inflection when Indian BIS certification barriers force consolidation among unvalidated seal compound suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Seal Compound Formulation | ECHA REACH compliance ahead of fluorine-free mandates secures Nordic preferred-vendor status. |
| Sensor-Integrated Electric Actuator R&D Investment | Sub-25 millimeter obstacle detection satisfies insurer liability requirements in US transit agencies. |
| Provincial Distributor Network Expansion | MIIT GB standard harmonization in Jiangsu and Guangdong opens subsidy program access. |
| Modular Subassembly Platform Development | Swappable door architectures maximize residual vehicle value under fleet-as-a-service contracts. |
| ISO 26262 Functional Safety Certification | Door control unit validation addresses firmware engineer scarcity in Central European clusters. |
Research Methodology
Bottom-up transit agency procurement modeling reconciled against top-down electric bus production tracking forms the analytical core. Primary interviews with OEM platform engineers, tier-one system integrator procurement leads, transit authority fleet managers, and aftermarket service heads combined with secondary validation against MIIT GB standard filings, KBA type-approval databases, FTA capital grant disclosures, and IHS Markit vehicle production data. Triangulation across supply-side capacity announcements and demand-side tender awards anchors volume estimates.
Historical trendline analysis of door system content per vehicle across electric and diesel platforms informs projection parameters. Segmentation dimensions span propulsion architecture, actuation technology, door configuration kinematics, and regional regulatory cluster. CAGRs derive from regression against fleet electrification timelines and accessibility mandate deadlines. Forecast inputs incorporate neodymium magnet supply quota volatility and REACH polymer reformulation cycle durations.
Underlying measurement precision varies by segment; OEM factory-integrated installations carry tighter precision than aftermarket component replacement due to disclosed supply agreement volumes. Forecasts reflect assumptions on electrification subsidy continuity and accessibility compliance enforcement intensity. Deviation in Chinese rare earth export policy or ECHA substance restriction timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Industrial Brakes Market
Automotive Parts
Argentina Automotive Actuators Market
Automotive Parts
Global Automotive Brake Hose Market
Automotive Parts
Global Automotive Flywheel Market
Automotive Parts
Automotive Belts and Hoses Market
Automotive Parts
Automotive Tire Molds Market
Automotive Parts
South America Automotive Engine Oils Market
Automotive Parts
Automotive Exhaust System Market
Automotive Parts
Automotive Variable Valve Timing Market
Automotive Parts
Nigeria Commercial Vehicles Lubricants Market
Automotive Parts
France Automotive Lubricants Market
Automotive Parts
India Automotive Parts Aluminum Die Casting Market
Automotive Parts
Philippines Automotive Engine Oils Market
Automotive Parts
North America Automotive Parts Aluminum Die Casting Market
Automotive Parts
Latin America Automotive Parts Zinc Die Casting Market
Automotive Parts
Automotive Belts Market