
 Automotive Propeller Shaft Market | 2026-2036
Automotive Propeller Shaft Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Propeller Shaft Market Analysis
Multi-source procurement for forged and machined shaft components is broadening as OEMs reduce dependency on captive driveline supply. Dana Incorporated leverages its integrated casting-to-assembly footprint across North American heavy-duty corridors. GKN Automotive anchors European supply through its constant-velocity joint and shaft systems specialization. ZF Friedrichshafen AG competes on modular e-axle architectures that incorporate propeller shafts into electrified drivetrain packages.
An automotive propeller shaft is a rotating mechanical component, typically tubular and hollow, that transmits torque from the transmission to the differential at operational speeds up to 6,000 RPM while accommodating angular misalignment through universal joints. Its primary purpose is to deliver engine power to the drive wheels without synchronous speed loss across variable suspension travel. Carbon fiber and composite material segments command premium positioning due to their mass reduction advantage in electric vehicle platforms where every kilogram extends range. Multi-piece shaft configurations dominate commercial vehicle and heavy-duty truck applications where extended wheelbases require segmented torque transmission with intermediate bearing supports.
NHTSA crashworthiness standards and EPA fuel economy regulations in the United States compel manufacturers to validate shaft integrity under frontal and side-impact loading while reducing rotating mass. ECE R94 and ECE R95 homologation requirements in Europe enforce similar structural and safety performance thresholds for driveline components in passenger and commercial vehicles. Stakeholders must monitor how battery-electric platform proliferation reshapes shaft count per vehicle and whether in-wheel motor architectures eventually eliminate the need for central propeller shafts entirely.
Market Dynamics
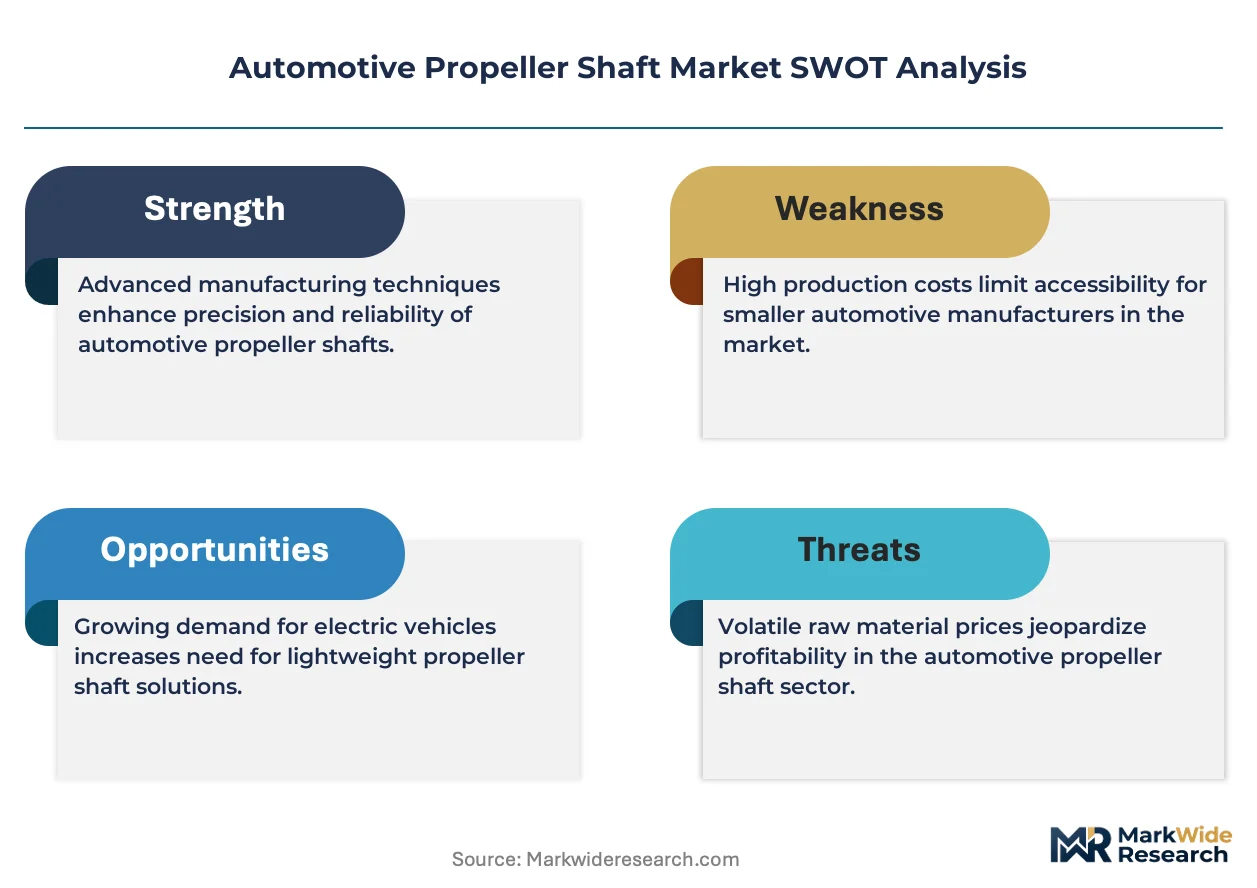
Material substitution from steel to aluminum and carbon fiber composites is compressing traditional forging capacity while expanding precision machining requirements across the supply base. EPA fuel economy standards and EU CO2 emission targets are accelerating this transition in light commercial vehicle fleets.
Growth Catalysts
- EPA Fuel Economy Standards:US regulatory pressure on light commercial vehicle fleets is mandating mass reduction in driveline components, directly expanding specification for hollow tubular shaft architectures.
- Electric Vehicle Range Optimization:Battery-electric platforms in premium passenger segments are specifying carbon fiber propeller shafts to recover kilogram-for-kilometer range extension.
- German Production Concentration:Premium passenger vehicle manufacturing clusters around Stuttgart and Munich are driving multi-piece and flexible shaft architecture upgrades across European supply chains.
Market Restraints
- Carbon Fiber Input Volatility:Polyacrylonitrile precursor supply concentration in Japanese and US chemical producers creates price instability for composite shaft manufacturers.
- Steel Forging Capacity Lock-in:Established Tier-1 suppliers with captive forging operations face stranded asset risk during aluminum and composite transition, slowing material substitution timelines.
- In-Wheel Motor Substitution Threat:Hub motor architectures in urban delivery vehicle prototypes eliminate central propeller shaft requirements entirely, threatening long-term demand in specific duty cycles.
Strategic Opportunities
- Indian Commercial Vehicle Expansion:Heavy-duty truck production growth under the PLI scheme creates demand for multi-piece shaft configurations with intermediate bearing supports.
- Modular E-Axle Integration:Convergence of electric drive units with propeller shaft systems enables suppliers to capture value previously lost to transmission specialists.
- EU Green Deal Manufacturing Incentives:Carbon border adjustment mechanisms and sustainable production certifications favor European-based composite shaft manufacturing investments.
Industry Challenges
- Composite Repair Technician Scarcity:Carbon fiber shaft damage assessment and field repair requires specialized training programs that OEM service networks have not yet scaled.
- NHTSA Crashworthiness Validation:Frontal and side-impact loading certification for lightweight shaft materials extends development timelines by 8-14 months compared to conventional steel.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Propeller Shaft Market |
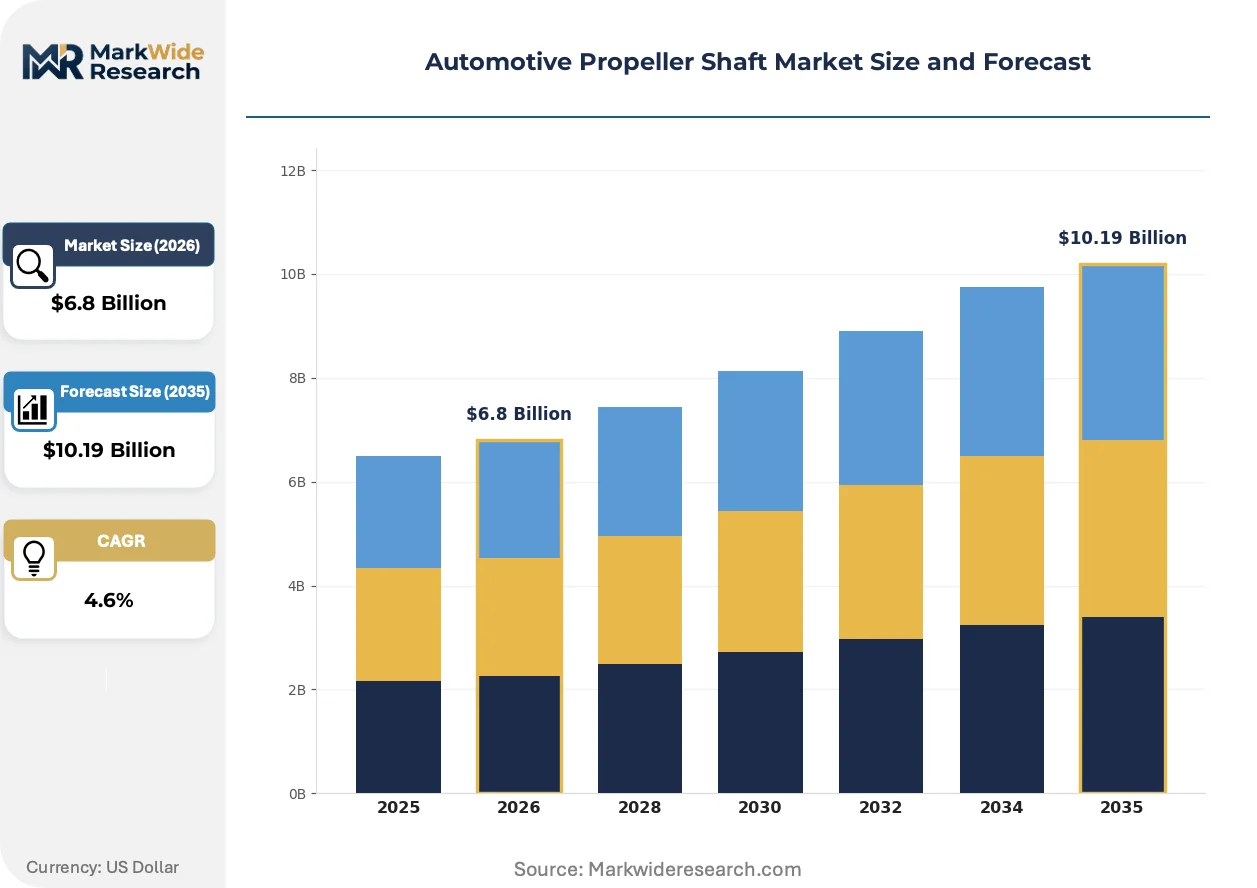
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Piece, Multi Piece, Flexible, Rigid Material: Steel, Aluminum, Carbon Fiber, Composite End User: Passenger Vehicles, Commercial Vehicles, Heavy-Duty Trucks, Off-Road Vehicles Installation Type: OEM, Aftermarket, Custom Fit, Standard Fit |
| Companies Covered | ZF Friedrichshafen AG, American Axle & Manufacturing, Inc., Dana Incorporated, GKN Automotive, Meritor, Inc., JTEKT Corporation, Hyundai WIA Corporation, Neapco, Showa Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Propeller Shaft Market Emerging Trajectories
Active torque vectoring requirements and electrified drivetrain packaging are forcing simultaneous evolution in shaft geometry, material stack, and assembly integration. The convergence of these pressures is compressing traditional component boundaries.
Carbon fiber filament winding with localized metal end-fitting integration is unifying the structural and joint functions previously handled by separate forged yoke assemblies. Premium electric SUV platforms from German and Korean manufacturers are adopting this architecture at production scale. The technology is unifying what were historically discrete forging, machining, and assembly supplier tiers into single-source composite system providers.
ECE R94 and ECE R95 homologation requirements are mandating validated shaft integrity under offset frontal and pole-side impact loading scenarios. European passenger vehicle manufacturers must now submit composite shaft architectures for structural durability testing that steel designs previously bypassed. The regulation is compressing development cycles for lightweight material adoption in EU type-approval pathways.
Fleet procurement for North American light commercial vehicles is consolidating specification authority at the OEM level, displacing historical upfitter-driven component selection. Large rental and logistics fleet operators are negotiating direct driveline component warranties with Tier-1 suppliers, bypassing traditional dealer channel service agreements. This concentration is most visible in last-mile delivery vehicle segments where total cost of ownership calculations now dominate initial acquisition price.
Automotive Propeller Shaft Market Segmentation
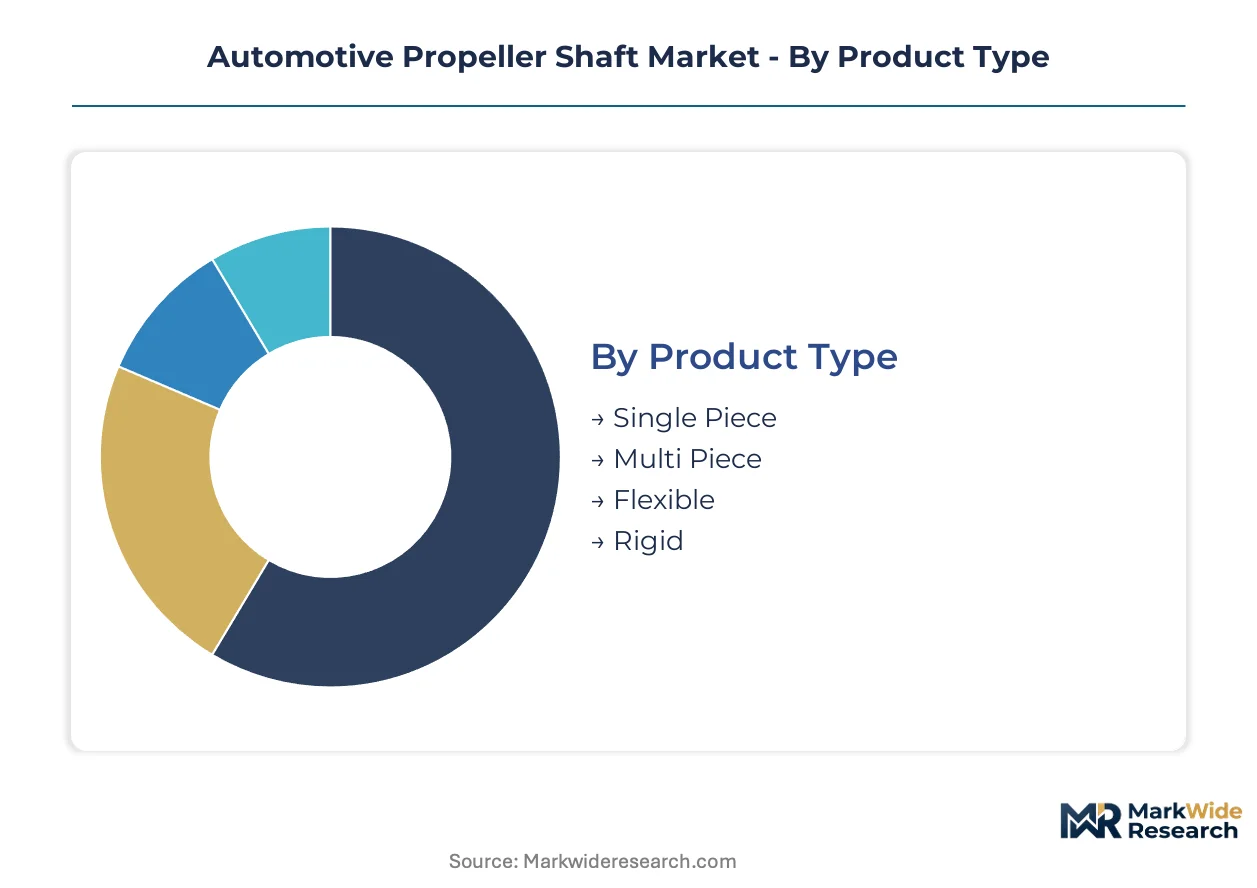
Propeller shaft specification varies sharply across duty cycles, with torque transmission requirements and packaging constraints dictating architecture selection. Material composition and installation channel further stratify supplier relationships and margin structures within each vehicle category.
Product Type:
Shaft architecture selection hinges on wheelbase length, suspension travel, and driveline packaging complexity across vehicle platforms.
- Multi Piece:Segmented shaft configurations incorporate intermediate bearing supports to transmit torque across extended wheelbases. Heavy-duty truck production in India under the PLI scheme and North American commercial fleets drive specification for this architecture where single spans exceed 1.8 meters.
- Flexible:Constant-velocity joint integration and elastomeric coupling elements accommodate angular misalignment up to 25 degrees. German premium passenger vehicle clusters around Stuttgart specify these shafts for adaptive air suspension systems where axle articulation varies dynamically.
- Single Piece:Hollow tubular steel or aluminum shafts serve compact passenger cars with short wheelbases and limited suspension travel.
- Rigid:Fixed-geometry shafts without articulation joints transmit torque in straight-line industrial applications and specialized racing platforms.
Mature deployment sits with Single Piece configurations in mass-market passenger cars. Newer deployment is concentrated in Flexible shafts for electrified premium platforms.
Material:
Mass reduction imperatives from EPA fuel economy standards and EU CO2 targets are rebalancing procurement specifications across the material stack.
- Carbon Fiber:Filament-wound composite shafts with localized metal end-fittings achieve 60-70% mass reduction versus steel equivalents. Korean and German electric SUV platforms specify this material to recover range, though polyacrylonitrile precursor volatility constrains supply scaling.
- Aluminum:Extruded and drawn aluminum tubes serve light commercial vehicle fleets seeking intermediate mass reduction without carbon fiber cost exposure. North American EPA compliance timelines accelerate aluminum substitution in this segment.
- Steel:Conventional forged and machined steel shafts retain cost advantage in heavy-duty and price-sensitive applications.
- Composite:Glass-fiber and hybrid material shafts occupy niche applications in off-road vehicles where impact resistance outweighs absolute mass targets.
Steel dominates installed base volume. Carbon fiber is climbing the fastest as electrification penetrates premium segments.
End User:
Duty cycle severity and annual mileage determine shaft durability specifications and replacement frequency across vehicle categories.
- Commercial Vehicles:Light commercial fleets in North America negotiate direct driveline warranties with Tier-1 suppliers, bypassing dealer channels. Last-mile delivery duty cycles with high stop-start frequency accelerate wear and expand aftermarket attachment rates.
- Heavy-Duty Trucks:Multi-piece shaft configurations with serviceable intermediate bearings dominate long-haul applications where million-kilometer durability is specified.
- Passenger Vehicles:OEM specification authority concentrates at German and Korean premium manufacturers driving carbon fiber adoption.
- Off-Road Vehicles:Mining and construction equipment demand impact-resistant rigid shafts with reinforced yoke assemblies.
Passenger vehicle specification drives technology innovation. Commercial vehicle procurement is gaining share fastest as fleet consolidation accelerates.
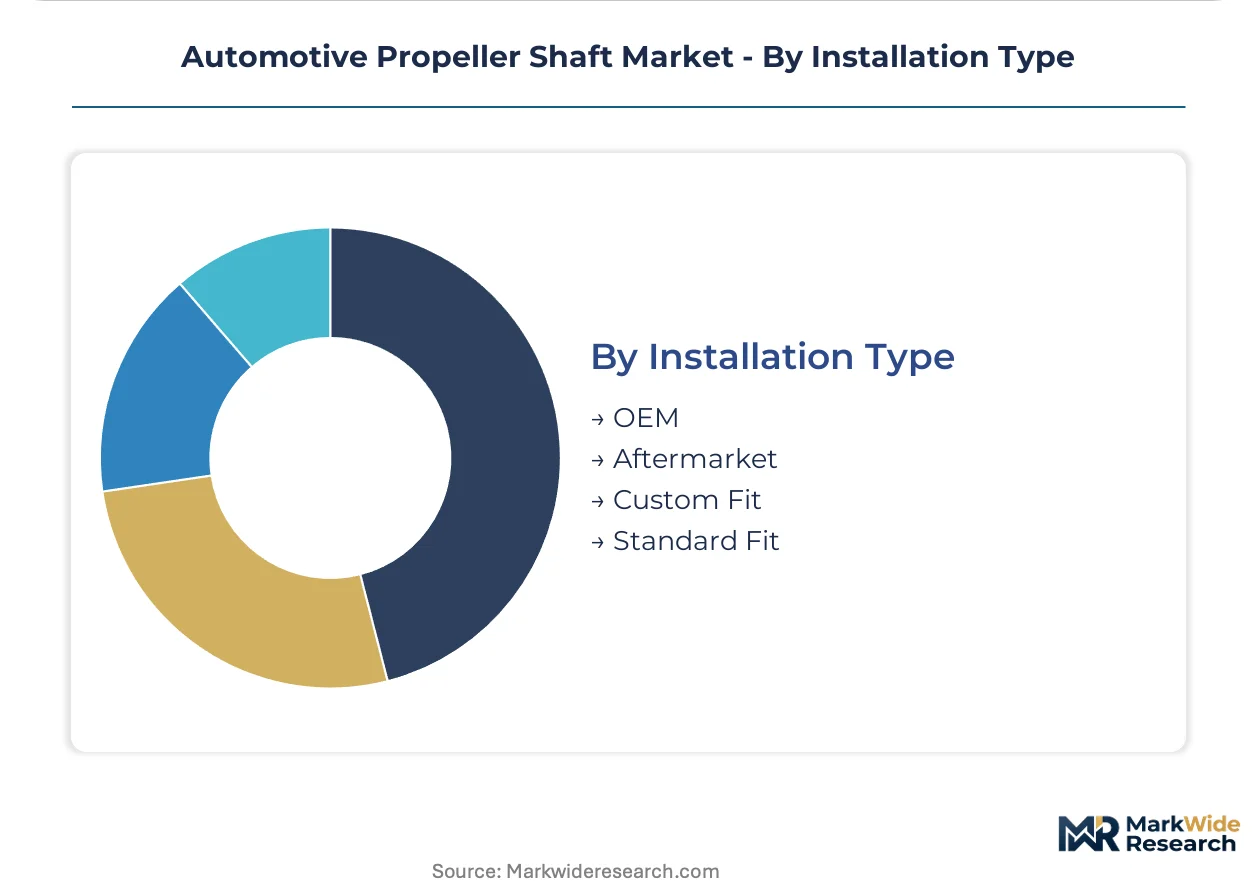
Installation Type:
Channel structure determines warranty liability, technical support obligations, and margin capture for shaft suppliers.
- OEM:Factory-installed shafts carry full vehicle warranty integration and require NHTSA crashworthiness validation for US type approval. ECE R94 and ECE R95 homologation requirements in Europe extend development timelines for lightweight materials.
- Aftermarket:Independent service channels face composite repair technician scarcity, constraining carbon fiber shaft addressability despite growing installed base.
- Custom Fit:Specialized upfitters configure shafts for modified wheelbases in recreational vehicle and emergency vehicle conversions.
- Standard Fit:Catalog replacement shafts match original specifications for direct replacement without dimensional modification.
OEM installation commands technology premium. Aftermarket channels are expanding most quickly as early electrified vehicles exit warranty coverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for automotive propeller shafts concentrates in manufacturing clusters serving premium electrified platforms and heavy-duty commercial fleets. Material substitution timelines and regulatory compliance windows vary sharply across national production bases.
Germany
Premium passenger vehicle manufacturers around Stuttgart and Munich specify multi-piece and flexible shaft architectures for adaptive air suspension systems. ECE R94 and ECE R95 homologation requirements mandate validated shaft integrity under offset frontal and pole-side impact loading. The Baden-Württemberg cluster anchors European supply chain specification authority for carbon fiber composite adoption.
United States
Light commercial vehicle fleets negotiate direct driveline warranties with suppliers, bypassing traditional dealer channels for last-mile delivery vehicles. NHTSA crashworthiness standards and EPA fuel economy regulations compel manufacturers to validate shaft integrity under frontal impact while reducing rotating mass. The Midwest manufacturing corridor spanning Michigan and Ohio retains heavy-duty forging capacity for steel shaft production.
China
Domestic electric SUV platforms specify filament-wound composite shafts to recover range in battery-heavy architectures. MIIT fuel consumption standards and dual carbon goals accelerate material substitution from conventional steel. The Yangtze River Delta cluster around Shanghai concentrates precision machining capacity for aluminum shaft production.
India
Heavy-duty truck production growth under the PLI scheme creates demand for multi-piece shaft configurations with intermediate bearing supports. BIS automotive component standards govern durability testing for commercial vehicle driveline systems. The Tamil Nadu and Maharashtra industrial corridors attract forging and machining investments serving domestic and export markets.
Japan
Precision component manufacturers supply constant-velocity joint integration for flexible shaft architectures in hybrid platforms. METI energy efficiency targets and JIS standards govern material specifications for mass reduction in passenger vehicle drivelines. The Aichi Prefecture cluster around Nagoya anchors specialized machining capacity for high-RPM shaft applications.
Automotive Propeller Shaft Market Vendor Landscape
Strategic partnerships dominate the current landscape as suppliers position for e-axle integration and composite material transitions. The vendor base exhibits moderate consolidation with distinct capability tiers separating integrated system providers from component specialists. Three archetypes prevail: full-system integrators with casting-to-assembly footprints, composite material specialists with filament winding expertise, and forged component houses defending steel capacity positions. Geographic expansion and technology licensing represent the primary competitive vectors as regional production requirements multiply.
Among European-based integrated suppliers, ZF Friedrichshafen AG and GKN Automotive exemplify the system-integration archetype through their driveline packaging capabilities. Dana Incorporated occupies a position among North American fabricators with heavy-duty corridor presence. These three entities represent contrasting geographic anchors for competitive positioning across material transition timelines and electrification pathways.
| Leading Market Players |
|---|
| ZF Friedrichshafen AG |
| American Axle & Manufacturing, Inc. |
| Dana Incorporated |
| GKN Automotive |
| Meritor, Inc. |
| JTEKT Corporation |
| Hyundai WIA Corporation |
| Neapco |
| Showa Corporation |
| Others |
Supply Flow & Price Mechanics
Polyacrylonitrile precursor pricing volatility cascades through carbon fiber shaft manufacturing into three distinct procurement tiers, with Japanese and US chemical producers anchoring input costs that OEMs pass through to electrified platform specifications.
Pricing Analysis
Volume concentration in steel shaft production compresses margins at the commodity end, while carbon fiber architectures command premium positioning through kilogram-for-kilometer range recovery value. Three-tier pricing structure across premium composite, intermediate aluminum, and economy steel levels stratifies procurement pools, with EPA compliance timelines intensifying cost compression in the aluminum tier. Fleet procurement consolidation in North American last-mile delivery segments elevates price sensitivity, whereas German premium OEMs exhibit lowest sensitivity due to specification authority concentration.
Supply Chain Analysis
Dual-sourcing qualification mandates from German and Korean OEMs fragment forging capacity across Germany, China, and Japan, preventing single-supplier lock-in for critical shaft assemblies. Polyacrylonitrile precursor, aluminum billet, and forged steel yoke dependencies tether production schedules to chemical and metallurgical commodity cycles. Tariff exposure on Chinese-machined aluminum tubes constitutes the primary structural risk, with distribution running through captive Tier-1 assembly plants rather than independent wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Material transition economics favor consolidation plays as stranded steel forging assets force weaker suppliers toward exit or acquisition, with carbon fiber filament winding expertise concentrating among integrated system providers.
For Market Incumbents: Deepen backward integration into polyacrylonitrile precursor supply or captive aluminum extrusion capacity to defend margin position against composite specialists. Prioritize ECE R94 and ECE R95 homologation investment ahead of EU type-approval deadlines to lock out unqualified competitors from premium passenger vehicle platforms. For New Entrants and Emerging Players: Carbon fiber repair technician certification programs offer a technology-first wedge into aftermarket channels constrained by service network scarcity. Target Indian heavy-duty truck production clusters under the PLI scheme with multi-piece shaft architectures, leveraging direct fleet warranty negotiations as the primary go-to-market mechanism. For Investors and Strategic Acquirers: Distressed-cycle entries favor integrated forging-to-assembly suppliers in the US Midwest corridor where steel capacity overhang creates acquisition opportunities below replacement cost. Monitor in-wheel motor architecture development in urban delivery prototypes as the critical inflection signal for long-term propeller shaft demand erosion.| Strategic Initiative | Industry Significance |
|---|---|
| Composite Material Transition | Filament winding capability unlocks access to Korean and German electric SUV platform specifications. |
| E-Axle Modular Integration | Convergence with ZF and GKN driveline packages captures value from transmission specialists. |
| Indian PLI Scheme Localization | Tamil Nadu and Maharashtra forging investments serve domestic heavy-duty truck demand. |
| Aftermarket Service Network Buildout | Carbon fiber repair certification addresses technician scarcity constraining addressable market expansion. |
| EU Green Deal Manufacturing Certification | Sustainable production credentials favor European-based composite shaft investments under carbon border adjustments. |
Methodological Framework
Multi-period observation of vehicle production volumes, material substitution rates, and regulatory compliance timelines anchored the trend analysis, supplemented by interviews with Tier-1 supplier procurement directors, OEM platform engineers, aftermarket distributors, and dealership operations managers. Secondary validation drew from EPA fuel economy filings, ECE homologation databases, NHTSA crashworthiness reports, and IHS Markit vehicle registration data. Bottom-up shaft content-per-vehicle estimates triangulated against top-down market value reconstructions.
Input-output matrix framing connected propulsion architecture penetration, wheelbase distribution, and material cost curves to derive volume and value projections across the modeling period. Segmentation dimensions spanned vehicle class, shaft architecture type, material composition, and regional production cluster. CAGRs emerged from iterative convergence of production forecasts and content-per-vehicle elasticity assumptions, with electric vehicle range optimization specifications and commercial vehicle fleet procurement patterns serving as primary demand drivers.
Several conditions sit outside the modeled scope, including breakthrough in-wheel motor commercialization, radical polyacrylonitrile precursor supply disruption, and unilateral tariff regime shifts. Forecasts reflect documented assumptions regarding EPA and EU regulatory trajectory stability. Deviation in battery-electric platform proliferation pace or hub motor architecture viability would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
India Brake Pads Market
Automotive Parts
Industrial Shock Absorbers Market
Automotive Parts
Automotive Parking Heater Market
Automotive Parts
Mexico Automotive Parts Zinc Die Casting Market
Automotive Parts
Germany Automotive Pneumatic Actuators Market
Automotive Parts
Nigeria Automotive Engine Oils Market
Automotive Parts
VVT Actuators Market
Automotive Parts
Global Automotive Plastic Fuel Tank Market
Automotive Parts
Automotive Common Rail System Market
Automotive Parts
Automatic Gearbox Valves Market
Automotive Parts
Die Cast Parts for Electric Vehicle Market
Automotive Parts
Car Refrigerator Market
Automotive Parts
Malaysia Brake Pads Market
Automotive Parts
Rear Spoiler Market
Automotive Parts
Electric Power Steering System (EPS) Market
Automotive Parts
Global Climate Control System for Commercial Vehicle Market