
 Australia Automotive Pneumatic Actuators Market | 2026-2036
Australia Automotive Pneumatic Actuators Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Automotive Pneumatic Actuators Market Outlook
Fleet operators and heavy commercial vehicle assemblers are rotating procurement focus toward integrated pneumatic braking systems, displacing standalone maintenance-provider purchasing. Bosch Rexroth AG leverages its hydraulics-pneumatics crossover expertise to anchor supply relationships with Australian truck OEMs. SMC Corporation specializes in compact actuator configurations for space-constrained cab designs, while Festo AG & Co. KG competes through localized technical support networks in Victoria and Queensland.
An automotive pneumatic actuator converts compressed air into linear or rotary mechanical motion, typically operating at pressures between 0.4 and 1.0 MPa to control engine valves, braking mechanisms, and suspension systems in vehicle assemblies. Double acting actuators dominate OEM installations due to their bidirectional force output and faster cycle times, while rodless designs are gaining share in electric-hybrid powertrain packaging where axial space is restricted. The aftermarket supplier channel remains fragmented, with maintenance providers favoring standardized replacement units over field retrofit configurations.
The Australian Design Rules administered by the Department of Infrastructure enforce crashworthiness and emissions compliance that directly shape pneumatic component specifications for domestic vehicle certification. TGA-equivalent pressure equipment standards and state-level workplace safety regulations in Victoria and New South Wales further constrain product entry for non-compliant imports. Stakeholders must monitor ADR amendment cycles and state procurement preferences for locally manufactured subsystems to anticipate qualification requirements and competitive positioning shifts.
Market Dynamics
Fleet operators across Victoria and Queensland are consolidating pneumatic actuator procurement under long-term supply agreements with Tier-1 brake system integrators, compressing the aftermarket channel and elevating certification requirements for direct OEM qualification.
Growth Catalysts
- Modern Manufacturing Strategy incentives:Federal production credits for locally manufactured automotive subsystems are pulling component assembly back into Victoria's precision engineering corridor.
- Heavy commercial vehicle brake system upgrades:Fleet operators are mandating integrated pneumatic braking configurations to meet stricter ADR crashworthiness protocols for articulated trucks.
- Double acting actuator technology:Faster cycle times and bidirectional force output are displacing single-acting units in new OEM installations for suspension control systems.
Market Restraints
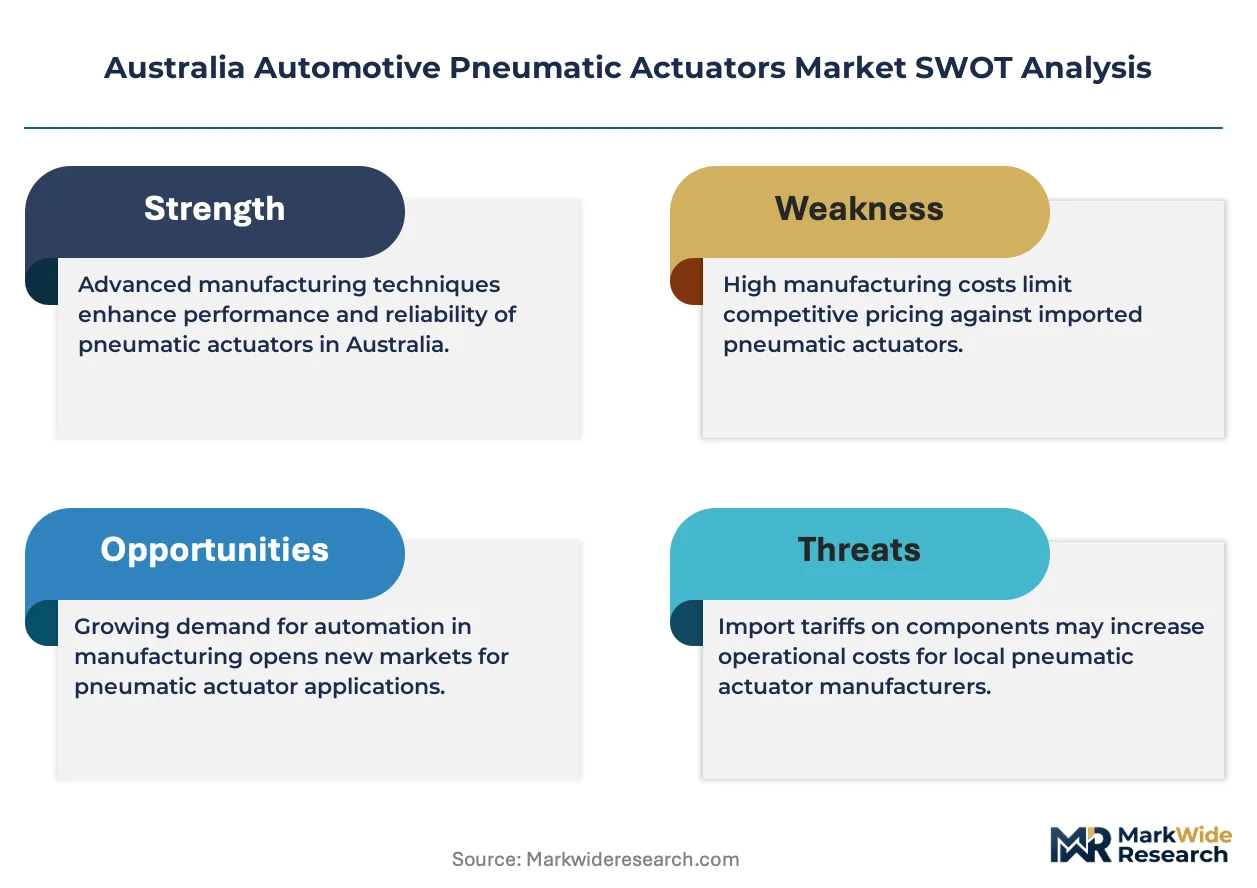
- Aluminum alloy input cost volatility:Cylinder housing material prices fluctuate with global commodity markets, squeezing margin stability for domestic fabricators.
- Supply concentration in German and Japanese component sources:Critical seal and valve subassemblies depend on a narrow import base vulnerable to shipping lane disruptions.
- Compressed air energy efficiency limitations:Pneumatic systems face substitution pressure from electromechanical actuators in electric-hybrid powertrain architectures where energy recovery is prioritized.
Strategic Opportunities
- Queensland mining vehicle retrofit demand:Off-road haulage fleets in the Bowen Basin require heavy-duty pneumatic suspension actuators for load stability on unsealed haul roads.
- ADR amendment cycles:Upcoming revisions to crashworthiness rules will force recertification of existing brake actuator designs, opening qualification windows for compliant domestic suppliers.
- Pneumatic-electric hybrid integration:Convergence of traditional compressed air systems with CAN-bus electronic control units enables smart actuator positioning for autonomous braking feedback loops.
Industry Challenges
- Precision machining skill scarcity:Victoria's tooling clusters face recruitment gaps for CNC operators capable of holding the tight tolerances required for rodless actuator cylinder bores.
- TGA-equivalent pressure equipment certification timelines:State-level safety assessments in New South Wales and Victoria extend product launch schedules by four to six months for imported actuator assemblies.
- Legacy fleet maintenance complexity:Maintenance providers struggle to source standardized replacement units compatible with mixed-vintage pneumatic braking systems still operating in aging commercial vehicle pools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Automotive Pneumatic Actuators Market |
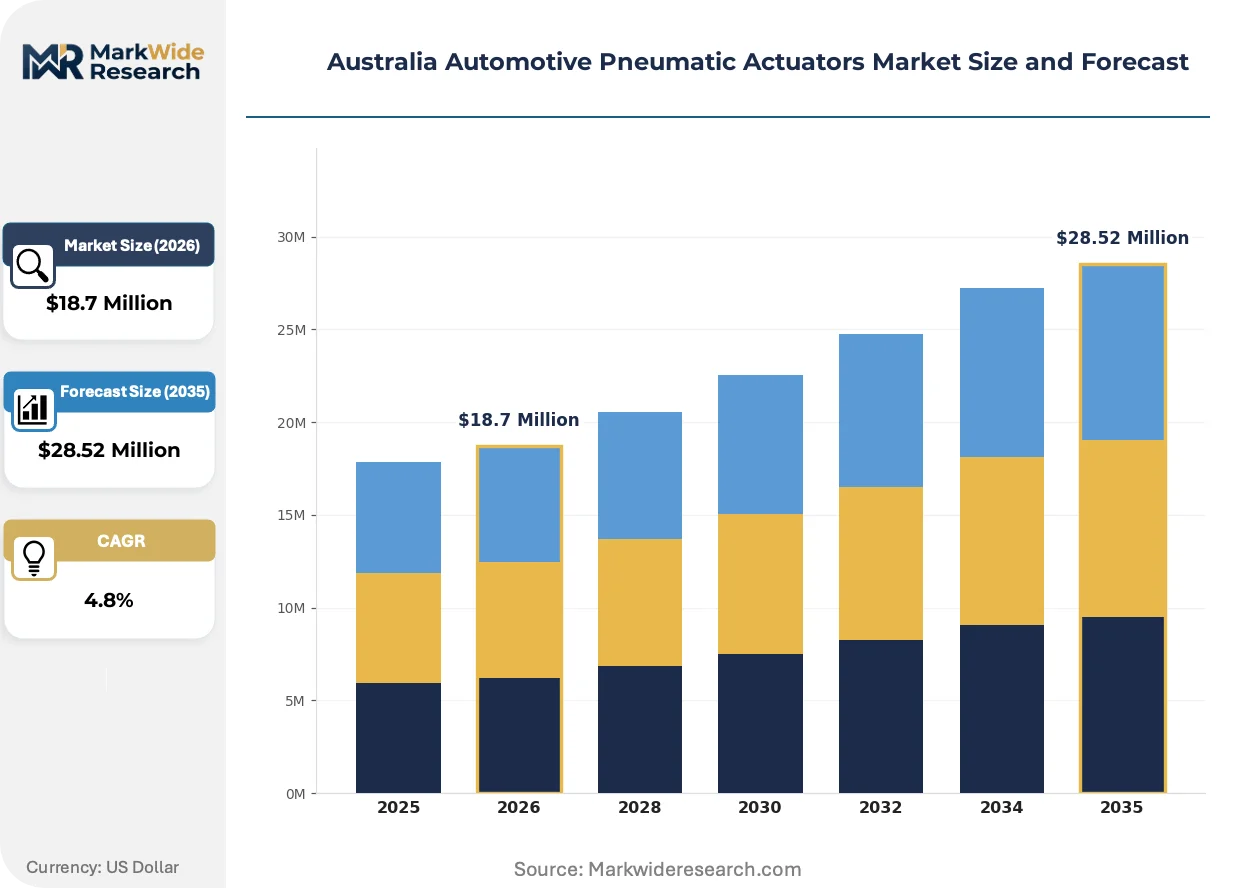
| Market Size in 2026 | $18.7 Million |
| Market Size in 2035 | $28.52 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Acting, Double Acting, Rodless, Compact Technology: Pneumatic, Electric, Hybrid, Mechanical End User: OEMs, Maintenance Providers, Aftermarket Suppliers, Vehicle Assemblers Installation: Standard, Automated, Field Retrofit, System Integration |
| Companies Covered | Bosch Rexroth AG, Nidec Corporation, Denso Corporation, SMC Corporation, Emerson Electric Co, Continental AG, Robert Bosch GmbH, Festo AG & Co. KG, Parker Hannifin Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Automotive Pneumatic Actuators Market Strategic Shifts
Rodless pneumatic actuator architectures are penetrating electric-hybrid vehicle platforms where packaging constraints demand axial space compression. Three technology and demand shifts are restructuring competitive positioning.
Compact rodless cylinder designs are decomposing traditional double-acting actuator dominance in powertrain packaging applications. Electric-hybrid OEMs in Victoria's automotive corridor are specifying these configurations for battery-proximate installations where stroke length must fit within restricted longitudinal envelopes. The technology is decomposing established supplier relationships by rewarding vendors with in-house extrusion and anodizing capabilities rather than conventional machining competencies.
ADR crashworthiness amendments administered by the Department of Infrastructure are tightening pneumatic brake component specifications for domestic vehicle certification. The regulatory pressure is forcing redesign cycles for existing actuator families to meet revised impact resistance and pressure cycling durability thresholds. Heavy commercial vehicle assemblers in Melbourne's western suburbs are responding by pre-qualifying dual-source supply arrangements before amendment deadlines take effect.
Fleet procurement offices are consolidating actuator purchasing under integrated brake system contracts rather than standalone component orders. The aftermarket maintenance channel is losing volume to OEM-captive service networks as operators seek warranty-aligned lifecycle cost structures. This concentration is most visible among interstate logistics operators running articulated fleets between Melbourne and Brisbane corridors.
Australia Automotive Pneumatic Actuators Market Segmentation
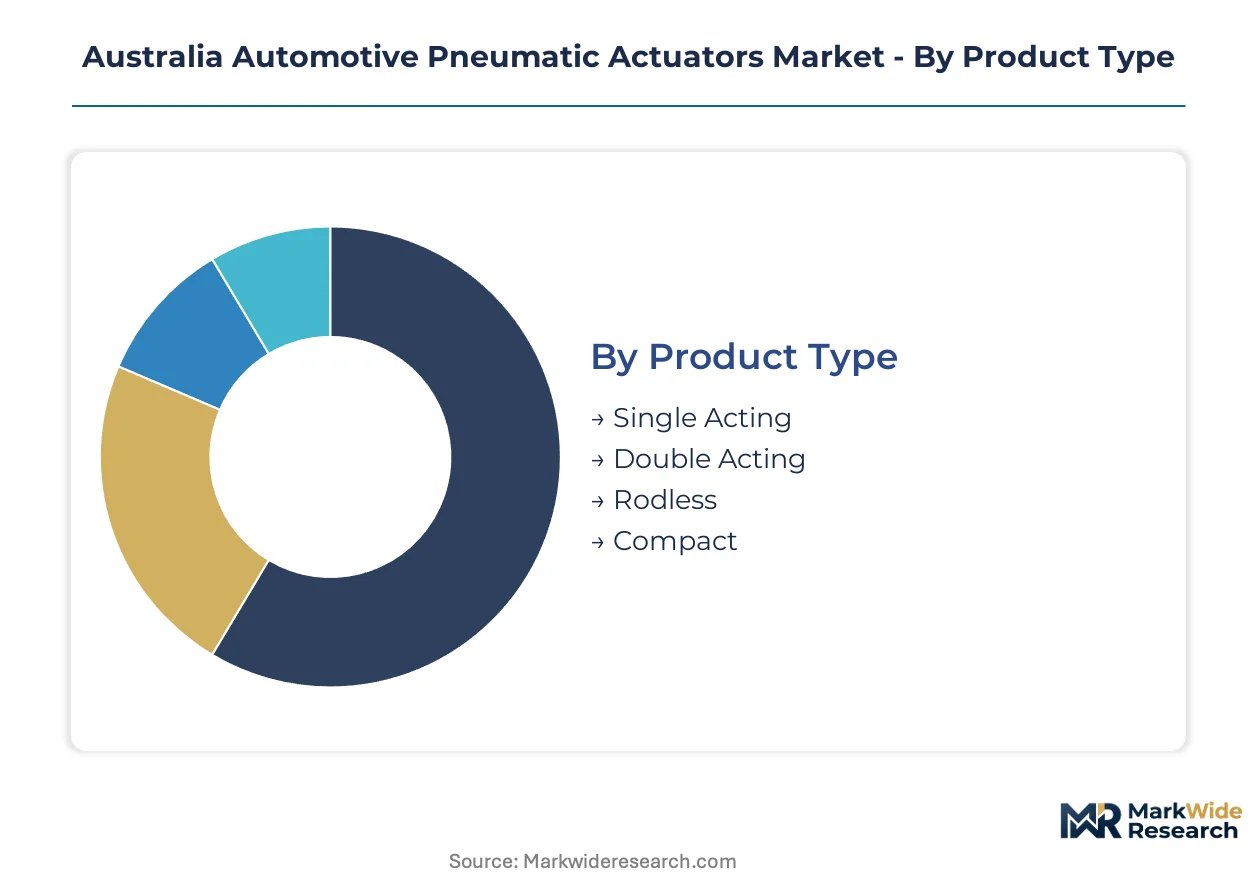
Pneumatic actuator procurement in Australia fragments across four structural dimensions, each shaping channel economics differently. Fleet consolidation and ADR compliance pressures are compressing some channels while expanding others, making segment-specific positioning critical for supplier survival.
Product Type:
Double acting and rodless configurations dominate OEM direct procurement, while single acting units flow through maintenance provider channels. Compact variants split between system integrators and aftermarket distributors depending on vehicle platform age.
- Double Acting:Bidirectional force output enables faster cycle times for suspension control systems. Victorian heavy commercial vehicle assemblers specify these for integrated brake system contracts under long-term supply agreements. Fleet operators in the Melbourne-Brisbane corridor prioritize this technology for warranty-aligned lifecycle cost structures.
- Rodless:Axial space compression suits electric-hybrid powertrain packaging where battery-proximate installations demand restricted longitudinal envelopes. Queensland mining vehicle retrofits and Victoria's automotive component corridor drive specification growth for load stability applications.
- Single Acting:Unidirectional force limits these to legacy fleet maintenance where standardized replacement units dominate procurement.
- Compact:Space-constrained cab designs in articulated trucks favor these configurations for brake and clutch actuation.
By volume, double acting leads. By growth pace, rodless is ahead.
Technology:
Cost tiers separate these segments, with pneumatic occupying economy positioning, hybrid commanding premium margins, and electric threatening substitution in energy-recovery-focused architectures.
- Pneumatic:Compressed air systems at 0.4-1.0 MPa operating pressure remain dominant for brake and suspension applications. TGA-equivalent pressure equipment standards and state-level workplace safety regulations in Victoria constrain non-compliant imports, protecting domestic fabricator margins.
- Hybrid:Convergence of compressed air with CAN-bus electronic control units enables smart actuator positioning for autonomous braking feedback loops. Federal production credits under the Modern Manufacturing Strategy pull assembly toward Victoria's precision engineering corridor for these advanced configurations.
- Electric:Electromechanical alternatives face substitution pressure from fleet operators prioritizing energy recovery in electric-hybrid powertrain architectures.
- Mechanical:Legacy compatibility requirements sustain residual demand from aging commercial vehicle pools requiring field retrofit solutions.
Pneumatic captures the largest installed base. Hybrid commands the steepest expansion trajectory.
End User:
Customer type determines contract structure, with OEMs and vehicle assemblers consolidating procurement under integrated system agreements while maintenance providers lose volume to captive service networks.
- OEMs:Direct qualification requirements dominate procurement, with Bosch Rexroth AG and SMC Corporation anchoring supply relationships through hydraulics-pneumatics crossover expertise and compact configuration specialization respectively.
- Vehicle Assemblers:Heavy commercial vehicle producers in Melbourne's western suburbs pre-qualify dual-source supply arrangements ahead of ADR amendment deadlines.
- Maintenance Providers:Fragmented aftermarket channel faces compression as fleet procurement offices consolidate purchasing under integrated brake system contracts.
- Aftermarket Suppliers:Standardized replacement unit sourcing struggles against mixed-vintage system complexity in aging fleet pools.
OEMs command the highest contract values. Vehicle assemblers are gaining share fastest.
Installation:
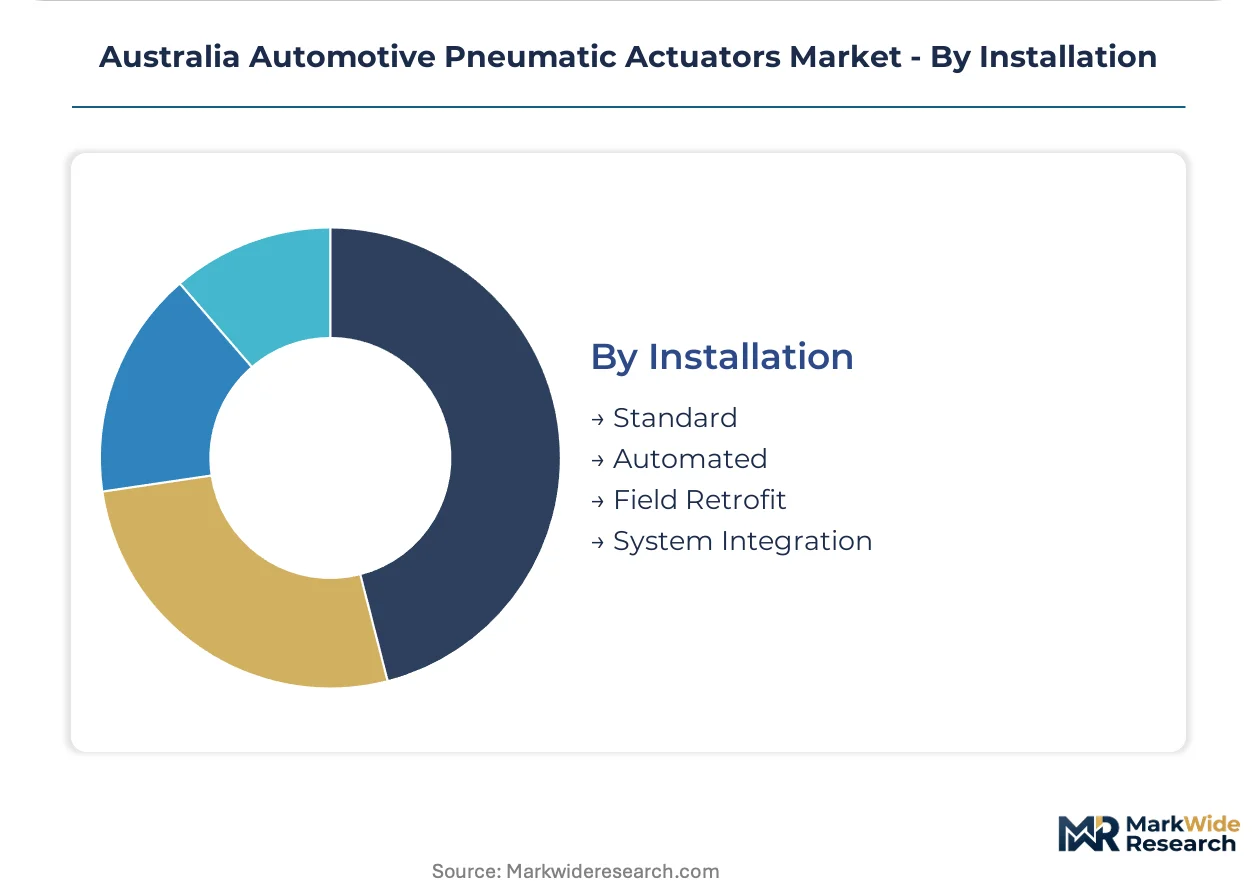
Application maturity varies, with standard and automated installations dominating new vehicle production while field retrofit addresses legacy fleet requirements.
- System Integration:Tier-1 brake system integrators consolidate actuator procurement under long-term agreements, elevating certification requirements and compressing direct component sales channels.
- Automated:Production line installation at vehicle assembly plants aligns with Modern Manufacturing Strategy incentives for locally manufactured subsystems.
- Standard:Conventional fitment procedures apply to high-volume commercial vehicle platforms with established supply relationships.
- Field Retrofit:Queensland mining vehicle demand in the Bowen Basin requires heavy-duty pneumatic suspension actuators for off-road haulage fleet upgrades.
System integration leads by revenue concentration. Field retrofit climbs fastest on mining fleet demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fleet procurement offices and heavy commercial vehicle assemblers concentrate actuator demand along Australia's eastern seaboard, with state-level manufacturing incentives and ADR compliance pathways reshaping supplier geography.
Victoria
Melbourne's western suburbs host heavy commercial vehicle assemblers pre-qualifying dual-source supply arrangements ahead of ADR amendment deadlines. The Modern Manufacturing Strategy pulls component assembly into Victoria's precision engineering corridor through federal production credits. Bosch Rexroth AG and SMC Corporation anchor supply relationships with local tooling clusters around Melbourne's automotive component corridor.
Queensland
Bowen Basin mining fleets drive heavy-duty pneumatic suspension actuator demand for off-road haulage upgrades on unsealed haul roads. State-level workplace safety regulations constrain non-compliant imports, protecting domestic fabricator margins. Brisbane-based procurement offices consolidate purchasing under integrated brake system contracts for interstate logistics operators running articulated fleets.
New South Wales
Sydney's aftermarket maintenance channel faces compression as fleet operators shift volume to OEM-captive service networks. TGA-equivalent pressure equipment certification timelines extend product launch schedules by four to six months for imported actuator assemblies. Western Sydney industrial zones sustain residual demand for standardized replacement units compatible with mixed-vintage pneumatic braking systems.
Western Australia
Pilbara mining operations require robust pneumatic actuators for autonomous haul truck braking systems operating in extreme dust conditions. State procurement preferences for locally manufactured subsystems intersect with federal incentive structures. Perth-based distributors serve remote maintenance networks where field retrofit complexity exceeds standardized replacement capabilities.
South Australia
Adelaide's remaining automotive assembly footprint focuses on specialized commercial vehicle platforms with niche pneumatic system requirements. The state's precision engineering sector supplies seal and valve subassemblies to Victorian actuator fabricators. Local manufacturers leverage South Australia's lower operating costs to compete for Tier-2 component contracts in the national supply chain.
Australia Automotive Pneumatic Actuators Market Competitive Environment
Player mix skews toward diversified industrial conglomerates with hydraulics-pneumatics crossover capabilities, compressing margins for standalone pneumatic specialists. Market structure exhibits moderate consolidation around German and Japanese parent companies with established Australian distribution networks. Three archetypes dominate: diversified motion control conglomerates, compact actuator specialists, and integrated brake system integrators. Competitive moves center on dual-source pre-qualification arrangements and localized technical support network expansion.
Among diversified industrial conglomerates, Bosch Rexroth AG and Emerson Electric Co. occupy positions leveraging hydraulics-pneumatics crossover expertise to anchor supply relationships with Australian truck OEMs. SMC Corporation exemplifies the compact actuator specialist archetype, while Festo AG & Co. KG sits within the localized technical support tier with established presence in Victoria and Queensland. These three companies represent distinct competitive positioning vectors without exclusive segment dominance.
| Leading Market Players |
|---|
| Bosch Rexroth AG |
| Nidec Corporation |
| Denso Corporation |
| SMC Corporation |
| Emerson Electric Co |
| Continental AG |
| Robert Bosch GmbH |
| Festo AG & Co. KG |
| Parker Hannifin Corporation |
| Others |
Value Chain & Pricing Dynamics
Aluminum alloy substitution for cast iron cylinder housings is compressing raw material costs while simultaneously pulling actuator fabrication toward Victoria's extrusion-capable precision engineering clusters and flattening price premiums for domestically sourced versus imported units.
Pricing Analysis
Cost-plus contracts with aluminum London Metal Exchange indexation dominate procurement between Tier-1 brake system integrators and Victorian heavy commercial vehicle assemblers. Price differentiation stratifies across ADR certification grade, volume commitment scale, and localized technical support bundling. Pricing pressure intensifies as electromechanical alternatives gain specification share in electric-hybrid powertrain architectures. Fleet operators running articulated interstate corridors exhibit highest price sensitivity, while mining vehicle retrofit buyers in Queensland prioritize durability over unit cost.
Supply Chain Analysis
Singapore-Melbourne shipping lane congestion functions as a critical chokepoint for seal and valve subassemblies originating from German and Japanese parent facilities. Geographic supply concentration centers on Germany, Japan, and China for precision-machined valve bodies, nitrile rubber seals, and anodized aluminum extrusions. Raw material dependencies rest on bauxite-aluminum smelting chains, specialty polymer feedstocks, and high-grade tool steel for CNC machining centers. Single-source vulnerability in rodless actuator cylinder bore finishing equipment elevates risk exposure. Distribution runs through Bosch Rexroth AG and SMC Corporation regional warehousing networks serving Melbourne and Brisbane corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Australia automotive pneumatic actuators market represents early-cycle expansion as ADR crashworthiness amendments force recertification waves across heavy commercial vehicle brake systems, opening qualification windows ahead of compliance deadlines.
For Market Incumbents: Shield established OEM supply relationships by accelerating dual-source pre-qualification arrangements with Melbourne's western suburbs assemblers before ADR amendment cycles conclude. Deepen backward integration into aluminum extrusion and anodizing capabilities to capture rodless actuator specification growth in electric-hybrid platforms. Prioritize certification investment in TGA-equivalent pressure equipment standards to extend state-level procurement preferences.
For New Entrants and Emerging Players: Differentiate on localized technical support density in Queensland's Bowen Basin mining corridors where field retrofit complexity exceeds standardized replacement capabilities. Target heavy-duty pneumatic suspension actuator demand for off-road haulage fleet upgrades as the most penetrable segment. Pursue go-to-market alignment with interstate logistics operators consolidating procurement under integrated brake system contracts rather than fragmented aftermarket channels.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with precision engineering fabricators in Victoria's automotive component corridor holding Modern Manufacturing Strategy production credits and in-house CNC machining competencies. Long-term viability over the coming decade hinges on ADR amendment cycle timing and electromechanical substitution velocity. Monitor Queensland mining fleet procurement consolidation as the inflection signal for demand trajectory revision.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Extrusion | Captures rodless actuator growth in Victoria's electric-hybrid powertrain packaging applications. |
| Dual-Source Pre-Qualification Arrangement | Secures OEM supply relationships ahead of ADR crashworthiness amendment enforcement deadlines. |
| Localized Technical Support Network Expansion | Penetrates Queensland mining vehicle retrofit demand in the Bowen Basin haulage corridor. |
| TGA-Equivalent Certification Investment | Unlocks state procurement preferences in New South Wales and Victoria safety equipment tenders. |
| Pneumatic-Electric Hybrid Platform Development | Positions for smart actuator integration with CAN-bus autonomous braking feedback loops. |
Study Parameters
Desk research of Australian Bureau of Statistics trade data, Department of Infrastructure ADR amendment documentation, and Modern Manufacturing Strategy incentive disclosures preceded structured interviews with Tier-1 brake system procurement directors, Victorian precision engineering plant managers, Queensland mining fleet maintenance heads, and aftermarket distributor channel partners. Secondary validation drew from vehicle production databases, state-level workplace safety regulatory filings, and aluminum commodity market assessments. Bottom-up actuator shipment estimates triangulated against top-down heavy commercial vehicle assembly forecasts.
Variance decomposition across product type, technology tier, end-user category, and installation mode shaped the analytical framework over the projection horizon. Modeled segmentation captured double acting versus rodless configuration splits, pneumatic-hybrid-electric technology transitions, OEM-assembler-maintenance provider customer structures, and system integration versus field retrofit deployment patterns. CAGRs derived from regression-weighted historical shipment trajectories and elasticity-adjusted demand drivers. Industry-specific forecast inputs incorporated ADR amendment implementation timelines and Modern Manufacturing Strategy credit uptake rates.
The analysis sits within stated boundaries; outcomes outside sustained federal production credit availability or accelerated electromechanical substitution would require recalibration. Forecasts reflect documented assumptions regarding aluminum input cost stability and German-Japanese component supply continuity. Practitioners should keep alternative scenarios live as ADR enforcement timing and electric-hybrid powertrain penetration rates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Ignition Box Market
Automotive Components
Global Automotive Acoustic Materials Market
Automotive Components
Automotive Buffers Market
Automotive Components
Automotive Refrigerant Market
Automotive Components
Germany Automotive Carbon Fiber Composites Market
Automotive Components
Automotive Sheet Metal Components Market
Automotive Components
UAE Automotive Composites Market
Automotive Components
Global Automotive Interior Component Market
Automotive Components
Automotive Carbon Thermoplastic Market
Automotive Components
Automotive Distributor O Ring Market
Automotive Components
North America Heat Shrink Tubing for Automotive Market
Automotive Components
Global Automotive Carbon Ceramic Brake Rotors Market
Automotive Components
Electronic Clutch Actuators Market
Automotive Components
Automotive Tailgate Market
Automotive Components
Automotive Glass Fiber Composites Market
Automotive Components
Polyamide in E-Mobility Market