
 Automotive Interior Bovine Leather Market | 2026-2036
Automotive Interior Bovine Leather Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Interior Bovine Leather Market Insights
Digital leather grading and cutting systems are reshaping how automotive hides are processed, replacing manual inspection with spectral imaging and AI-driven defect mapping. Bader GmbH & Co. KG leverages captive tannery operations across four continents to secure consistent dye lots for luxury seating programs. Gruppo Mastrotto anchors its position through vertical control from raw hide sourcing to finished automotive crust, while Eagle Ottawa competes on color-matching precision for dashboard and door panel applications.
Automotive interior bovine leather refers to chrome- or vegetable-tanned cattle hides engineered for abrasion resistance, UV stability, and flame-retardant compliance within passenger compartments, typically finished to thicknesses between 0.9 mm and 1.4 mm depending on seating versus trim applications. Finished leather commands the dominant value share among product types due to the capital intensity of dyeing, embossing, and protective coating steps that OEMs increasingly outsource. Full grain grades sustain premium pricing in executive vehicle lines where natural pore structure and patina development differentiate cabin experiences, while bonded leather occupies entry-luxury segments where cost targets override authenticity requirements.
REACH in Europe and EPA discharge guidelines in the United States both constrain chromium and sulfide effluent from tanneries, raising compliance costs for suppliers serving multiple regulatory jurisdictions. California Proposition 65 labeling requirements and evolving EPA volatile organic compound standards for automotive interior materials further shape formulation choices and regional sourcing decisions. Stakeholders must monitor how biomaterial alternatives and synthetic protein coatings evolve alongside regulatory pressure to determine whether bovine leather retains its position as the default premium surface or c share to lab-grown substitutes.
Market Dynamics
REACH chemical restrictions in Europe are tightening chromium discharge limits from tanneries, forcing hide processors to reconfigure effluent treatment systems and reformulate tanning chemistries while maintaining abrasion resistance and UV stability specifications demanded by OEM seating programs.
Growth Catalysts
- Premium vehicle seating programs:Mercedes-Benz, BMW, and Volkswagen in Germany maintain dedicated leather design studios and finishing partnerships that expand hide procurement volumes for executive vehicle lines.
- REACH compliance investments:European tanneries adopting metal-free and vegetable-tanning alternatives are capturing preferential supplier status with sustainability-focused OEMs.
- Spectral imaging adoption:Digital leather grading and cutting systems replace manual inspection, reducing defect rates and yield loss in high-volume automotive hide processing.
Market Restraints
- Raw hide supply concentration:Brazil and Argentina dominate global cattle hide exports, creating geographic vulnerability for tanneries dependent on South American raw material flows.
- Chromium tanning chemistry:Traditional chrome-tanning faces escalating compliance costs under EPA discharge guidelines in the United States and REACH chromium limits in Europe.
- Synthetic protein coatings:Lab-grown leather alternatives and biofabricated materials threaten to displace bovine leather in entry-luxury vehicle segments where cost targets override authenticity requirements.
Strategic Opportunities
- Metal-free tanning expansion:Vegetable-tanned and synthetic-tanned automotive leathers command premium positioning with sustainability-certified vehicle lines in Germany and Scandinavia.
- Dashboard and door panel applications:Color-matching precision requirements for interior trim surfaces create specialized niches distinct from commodity seating leather.
- California Proposition 65 compliance:Tanneries achieving formaldehyde-free and chromium-free certification gain preferential access to US West Coast OEM assembly plants.
Industry Challenges
- Spectral imaging technician scarcity:Digital grading system deployment requires operators trained in AI-driven defect mapping and automated cutting optimization.
- Multi-jurisdiction certification timelines:Tanneries serving European, US, and Asian OEMs simultaneously face overlapping REACH, EPA, and GB standard compliance audits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Interior Bovine Leather Market |
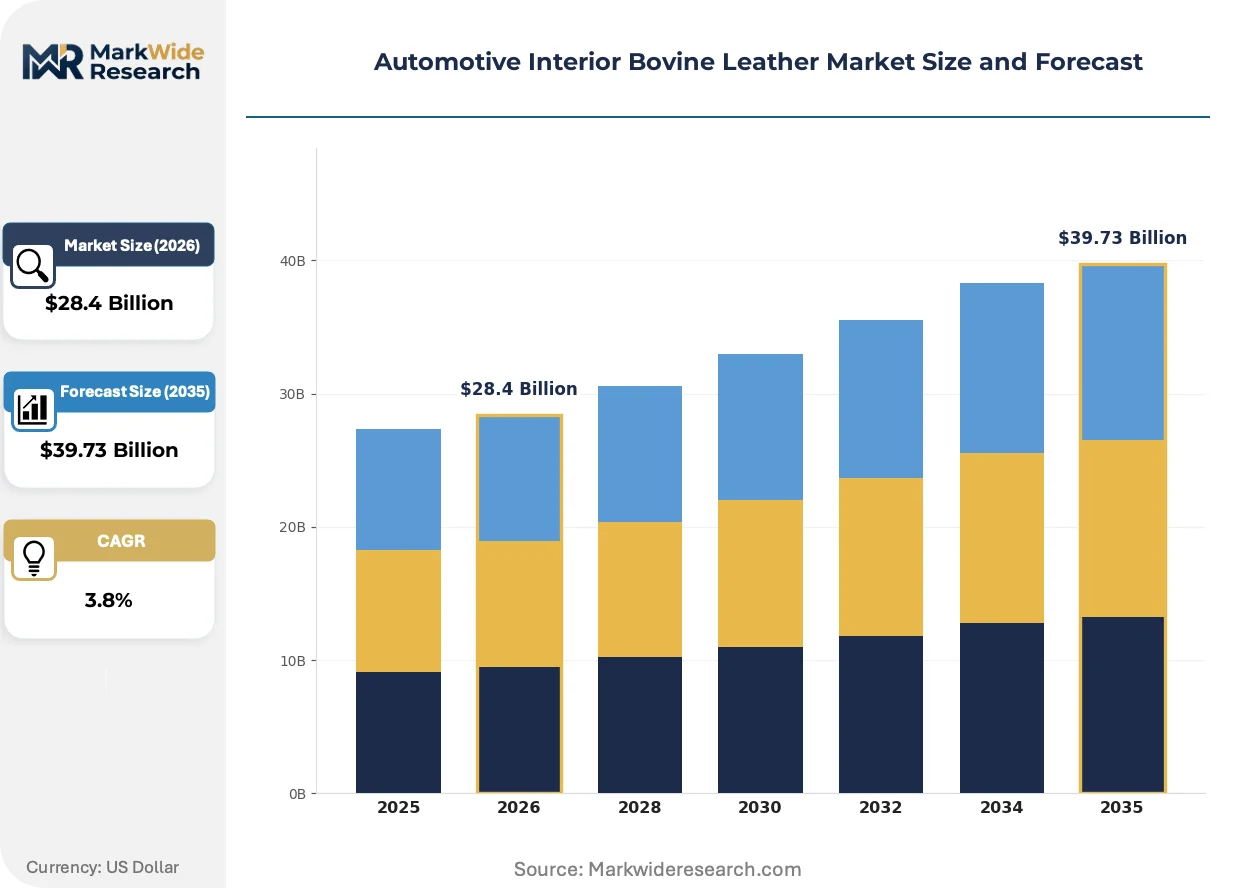
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $39.73 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Raw Leather, Finished Leather, Upholstery, Trimmings Quality Grade: Top Grain, Full Grain, Split Grain, Bonded Leather Application: Seating, Dashboard, Door Panels, Headliners End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers |
| Companies Covered | Bader GmbH & Co. KG, GST Autoleather Inc, Eagle Ottawa, CTL Leather Inc., Boxmark Leather GmbH & Co. KG, Gruppo Mastrotto, Wollsdorf Leder Schmidt & Co Ges, DK Leather Corporation, Scottish Leather Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Interior Bovine Leather Market Trends and Innovations
Digital processing technologies and regulatory chemistry shifts are reconfiguring how automotive hides move from raw material to finished interior surfaces. Three developments dominate this transformation.
Spectral imaging systems paired with AI-driven defect mapping are hybridizing traditional hide grading with automated quality control. Tier-1 seating suppliers in Germany and Italy deploy these systems to reduce manual inspection labor while improving consistency across multi-continent tannery networks. The technology compresses variation in dye lot matching and enables real-time sorting for full-grain versus corrected-grain allocation.
REACH Annex XVII restrictions on chromium VI compounds are accelerating metal-free tanning chemistry adoption across European tanneries. The regulation forces reformulation of wet-blue processing sequences and investment in vegetable-tanning infrastructure. Suppliers serving Mercedes-Benz and BMW sustainability programs face compressed timelines to certify chrome-free supply chains before model-year changeovers.
Automotive OEMs are consolidating leather procurement through direct finishing partnerships rather than arm's-length spot purchasing. Tier-1 seating manufacturers in Germany and the US Midwest now negotiate multi-year dye lot consistency agreements that bypass traditional distributor channels. This concentration is most visible in executive vehicle programs where natural pore structure and patina development specifications require tannery-level customization unavailable through commodity sourcing.
Automotive Interior Bovine Leather Market Segmentation
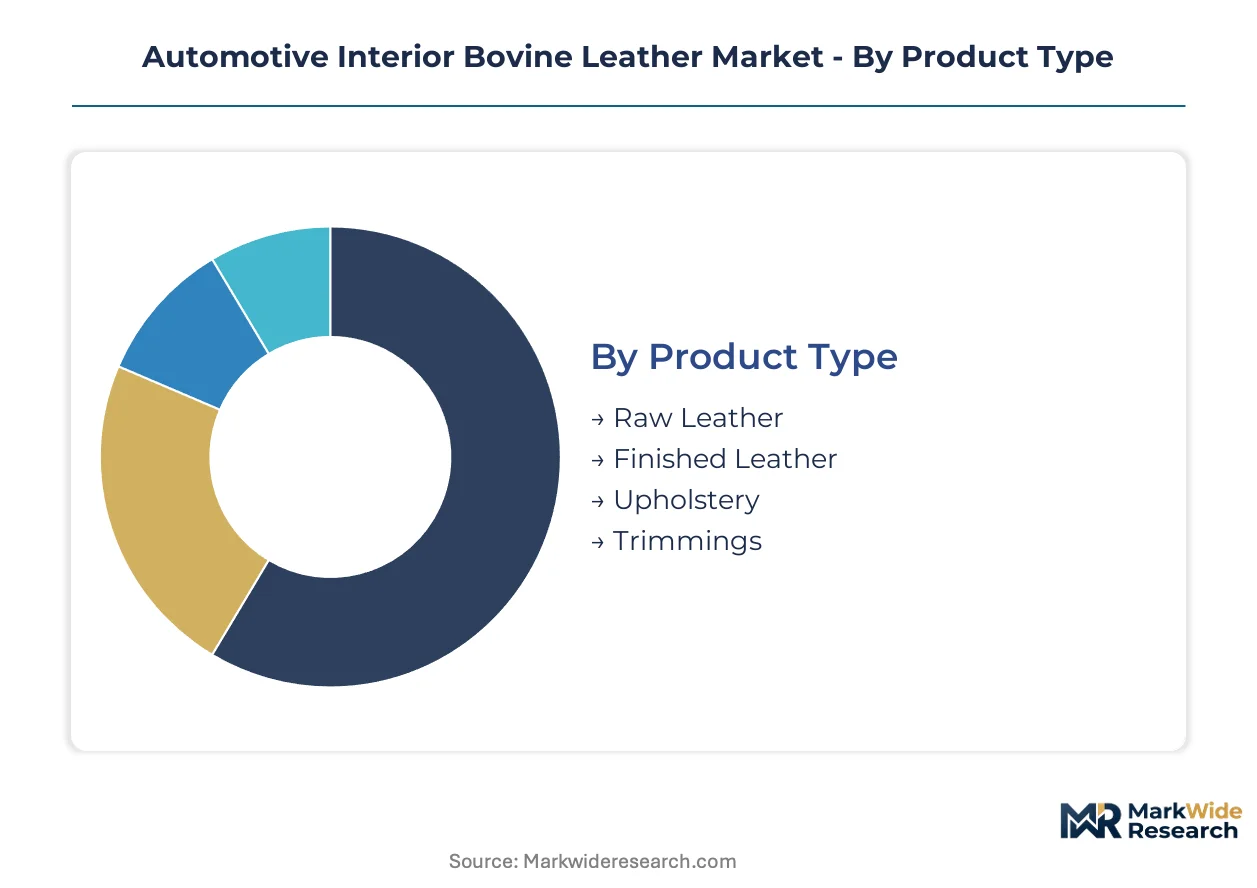
Automotive interior bovine leather segments reflect divergent processing intensities and OEM specification tiers. Each dimension—product type, quality grade, application, and end user—channels capital allocation and compliance requirements differently across supplier networks.
Product Type:
Mature processing stages dominate value capture, with capital-heavy finishing commanding premium positioning over commodity raw inputs.
- Finished Leather:Chrome- or vegetable-tanned hides undergo dyeing, embossing, and protective coating to meet OEM abrasion resistance and UV stability specifications. Mercedes-Benz, BMW, and Volkswagen procurement programs concentrate demand in Germany for multi-year dye lot consistency agreements.
- Raw Leather:Unprocessed cattle hides at the wet-blue or wet-white stage require further tanning and finishing before automotive qualification. Brazil and Argentina export concentration creates geographic vulnerability for tanneries dependent on South American hide flows.
- Upholstery:Pre-cut and partially stitched leather components supplied to seating manufacturers for final assembly integration.
- Trimmings:Smaller leather pieces for accent applications including steering wheel wraps and gear shift boots.
Finished leather retains volume leadership; raw leather holds the steepest expansion curve as tanneries backward integrate into hide sourcing.
Quality Grade:
Cost tiers separate authentic hide structures from engineered composites, with natural grain specifications commanding substantial premiums over reconstructed alternatives.
- Full Grain:Retains complete natural pore structure and surface character, enabling patina development over vehicle lifecycle. Executive vehicle lines at German OEMs specify full grain for differentiation in cabin experience.
- Top Grain:Slightly sanded or corrected surface removes minor imperfections while preserving strength characteristics. Entry-luxury segments balance authenticity targets with yield optimization.
- Split Grain:Lower fibrous layer separated from top grain, typically finished with polymer coatings for durability.
- Bonded Leather:Reconstituted leather fibers bonded with polyurethane occupy cost-sensitive applications where authenticity requirements are minimal.
Full grain commands the highest margin tier; bonded leather is gaining share fastest in cost-constrained vehicle programs.
Application:
Volume concentration in seating contrasts with specialized technical requirements for dashboard and door panel integration.
- Seating:Largest surface area application requiring flame-retardant compliance, abrasion resistance, and multi-year durability certification. Spectral imaging adoption concentrates in high-volume seating programs to reduce defect rates and yield loss.
- Dashboard:Demands precise color-matching across leather and synthetic surfaces with UV stability for direct sun exposure.
- Door Panels:Combines leather inserts with structural substrates, requiring adhesion compatibility and acoustic damping properties.
- Headliners:Smaller leather accent areas with weight minimization priorities and overhead mounting safety requirements.
Seating dominates procurement volumes; dashboard applications are climbing the fastest as interior design differentiation intensifies.
End User:
Customer type determines contract structure, with direct OEM partnerships replacing traditional distributor channels in premium segments.
- OEMs:Direct procurement relationships with Mercedes-Benz, BMW, and Volkswagen leather design studios specify custom finishing and exclusive dye formulations.
- Tier-1 Suppliers:Bader GmbH and Gruppo Mastrotto negotiate multi-year supply agreements covering hide procurement through finished component delivery.
- Vehicle Assemblers:Contract manufacturers and regional assembly operations sourcing pre-certified leather components for platform-sharing programs.
- Aftermarket Providers:Independent upholstery shops and restoration specialists purchasing smaller volumes without OEM certification requirements.
OEM direct procurement retains volume leadership; Tier-1 supplier consolidation is gaining share fastest as finishing partnerships deepen.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Raw hide export flows from Brazil and Argentina dominate upstream supply, while finished leather value concentrates in European and Asian automotive manufacturing clusters. Germany, the United States, China, Italy, and Mexico represent the critical nodes where tannery capacity, OEM design studios, and regulatory frameworks intersect.
Germany
Mercedes-Benz, BMW, and Volkswagen leather design studios in Stuttgart, Munich, and Wolfsburg drive demand for full-grain automotive grades. REACH Annex XVII chromium VI restrictions force tanneries serving these OEMs to certify metal-free supply chains before model-year transitions. Bader GmbH maintains captive finishing partnerships across Bavaria and Baden-Württemberg to secure dye lot consistency for executive vehicle programs.
United States
EPA discharge guidelines constrain chromium and sulfide effluent from tanneries supplying Detroit Three and transplant OEM assembly plants. California Proposition 65 labeling requirements for formaldehyde and chromium content shape formulation choices for West Coast vehicle production. Eagle Ottawa operates finishing facilities in Michigan to serve dashboard and door panel color-matching specifications for domestic premium vehicle lines.
China
GB standards for automotive interior materials and MIIT dual carbon goals accelerate domestic tannery investment in metal-free tanning chemistry. Domestic OEMs including BYD and NIO expand leather-trimmed cabin specifications for premium EV segments. Yangtze River Delta tannery clusters in Zhejiang and Jiangsu provinces scale vegetable-tanning capacity to meet export compliance requirements for European-bound vehicle components.
Italy
Gruppo Mastrotto anchors automotive leather production through vertical control from raw hide sourcing to finished crust in Veneto and Tuscany. ECHA enforcement of REACH chemical restrictions drives reformulation investments across Arzignano tanning district operations. Milan-based design houses collaborate with tanneries on exclusive embossing patterns for limited-production vehicle interiors.
Mexico
USMCA rules of origin and proximity to North American vehicle assembly plants position Mexican tanneries as finishing hubs for US-bound automotive leather. Nuevo León and Guanajuato industrial corridors attract Tier-1 seating supplier investments to serve BMW San Luis Potosí and Audi Puebla operations. Mexican tanneries import wet-blue hides from Argentina and Brazil for final finishing and component cutting.
Automotive Interior Bovine Leather Market Competitive Landscape
On the supply side, the industry is consolidating around tanneries with captive raw material sourcing and certified metal-free processing capabilities. Mid-scale regional finishers compete on color-matching precision for dashboard and trim applications, while commodity operators face margin compression from synthetic leather alternatives. Two strategic archetypes dominate: vertically integrated hide-to-crust specialists and design-focused finishing partners with OEM-direct relationships. Competitive moves center on backward integration into South American hide sourcing and multi-year dye lot consistency agreements that bypass traditional distributor channels.
Within the European integrated tier, Bader GmbH & Co. KG and Gruppo Mastrotto exemplify archetypes of scale-driven captive tannery networks and vertical control from raw hide through finished automotive crust. Eagle Ottawa occupies a position emphasizing color-matching specialization for interior trim surfaces distinct from commodity seating leather. These three entities anchor the competitive structure through differentiated approaches to OEM partnership depth and processing scope.
| Leading Market Players |
|---|
| Bader GmbH & Co. KG |
| GST Autoleather Inc |
| Eagle Ottawa |
| CTL Leather Inc. |
| Boxmark Leather GmbH & Co. KG |
| Gruppo Mastrotto |
| Wollsdorf Leder Schmidt & Co Ges |
| DK Leather Corporation |
| Scottish Leather Group |
| Others |
Pricing and Supply Chain Analysis
Santos-Santos port freight corridors from Brazil to European tanneries transmit raw hide cost volatility directly into finished leather pricing tiers, while REACH compliance investments and spectral imaging adoption create divergent margin structures across chrome-free and conventional processing lines.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term offtake structure where full-grain grades command substantial premiums over bonded leather alternatives based on natural pore authenticity and patina development specifications. Price differentiation rests on certification level—REACH Annex XVII chrome-free status—and volume scale under multi-year dye lot consistency agreements. Cost compression in entry-luxury segments is intensifying because synthetic protein coatings and biofabricated materials expand acceptable substitution thresholds. Fleet procurement teams at volume vehicle programs exhibit highest price sensitivity, while German OEM leather design studios maintain lowest sensitivity due to cabin experience differentiation requirements.
Supply Chain Analysis
Tariff exposure between Brazil and European Union member states dominates supply chain risk calculus for tanneries dependent on South American wet-blue hide flows. Raw material sourcing draws from Brazil, Argentina, and Uruguay for cattle hides, with Germany, Italy, and China anchoring finishing capacity. Chrome-tanning chemistry and vegetable-tanning infrastructure represent critical capital-intensive dependencies. Distribution runs through Tier-1 seating supplier networks rather than arm's-length distributor channels as OEMs consolidate procurement through direct finishing partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment—REACH compliance certification timelines and multi-jurisdiction audit requirements—creates substantial barriers against commodity substitution and new entrant disruption.
For Market Incumbents: Harden captive supply positions through backward integration into Argentine and Brazilian hide sourcing to secure volume commitments before competitor offtake. Expand metal-free tanning capacity ahead of model-year changeover deadlines to capture preferential supplier status with sustainability-certified OEM programs. Synthetic leather alternatives and lab-grown protein coatings represent the primary substitution threat requiring continuous R&D monitoring.
For New Entrants and Emerging Players: Build out dashboard and door panel color-matching specialization as a white-space entry vector distinct from saturated seating leather competition. Target California Proposition 65 compliance certification as the most penetrable regulatory pathway, enabling preferential access to West Coast OEM assembly plants underserved by incumbent East Coast and European finishing networks. Pursue direct OEM design studio relationships rather than Tier-1 supplier subcontracts to bypass established channel control.
For Investors and Strategic Acquirers: Carve-out targets emerge from automotive divisions of diversified leather conglomerates with underutilized chrome-free processing assets and dormant OEM certification relationships. Long-term viability hinges on whether bovine leather retains premium cabin positioning against biofabricated substitutes across the next product cycle generation. Monitor synthetic leather adoption rates in entry-luxury EV segments as the critical inflection signal for authentic hide demand trajectories.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Raw Hide Sourcing | Captive supply from Brazilian and Argentine tanneries secures volume commitments against competitor offtake. |
| Metal-Free Tanning Capacity Expansion | REACH Annex XVII compliance certification unlocks preferential supplier status with Mercedes-Benz and BMW sustainability programs. |
| Spectral Imaging System Deployment | AI-driven defect mapping reduces yield loss in high-volume seating programs at Bader GmbH and Gruppo Mastrotto operations. |
| Direct OEM Design Studio Partnerships | Multi-year dye lot consistency agreements bypass traditional distributor channels and anchor executive vehicle program allocations. |
| California Proposition 65 Compliance Certification | Formaldehyde-free and chromium-free status enables preferential access to West Coast OEM assembly plants. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs and trade data, vehicle production databases, SEC 10-K filings, and IHS Markit registration data to establish baseline volume and value estimates. Primary interviews engaged Tier-1 supplier procurement directors, OEM platform engineers, tannery operations managers, and aftermarket distribution specialists across Germany, the United States, Italy, China, and Mexico. Bottom-up hide flow analysis from Brazilian and Argentine export statistics triangulates against top-down OEM seating program specifications.
Forecast inputs incorporate vehicle class segmentation, propulsion architecture mix, leather content per vehicle by interior trim level, OEM tier positioning, and regional production cluster capacity utilization across the projection horizon. CAGRs derive from regression analysis against historical hide procurement volumes and projected executive vehicle program launches. Metal-free tanning chemistry adoption curves and synthetic leather substitution elasticity inform scenario-weighted outcomes.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese tanneries or breakthrough cost reductions in biofabricated leather would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Cabin Insulation Material Market
Automotive Interior & Exterior
Automotive Sound Proofing Material Market
Automotive Interior & Exterior
Global Automotive Side Window Sunshades Market
Automotive Interior & Exterior
Automotive Exterior Smart Lighting Market
Automotive Interior & Exterior
Automotive Body-In-White Market
Automotive Interior & Exterior
Automotive Fridge Market
Automotive Interior & Exterior
Zero Gravity Seat Market
Automotive Interior & Exterior
Car Door Latch Market
Automotive Interior & Exterior
Automotive Interior Cleaner Market
Automotive Interior & Exterior
China Automotive Sunroof Market
Automotive Interior & Exterior
Global Automotive Roof Systems Market
Automotive Interior & Exterior
Automotive Heated Steering Wheel Market
Automotive Interior & Exterior
Mexico Automotive OEM Coatings Market
Automotive Interior & Exterior
Paint Protection Film Market
Automotive Interior & Exterior
Automotive Lighting Market
Automotive Interior & Exterior
Global Automotive Luggage Trim Market