
 Africa Automotive Lubricants Market | 2026-2036
Africa Automotive Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Automotive Lubricants Market Outlook
The EU Green Deal's extraterritorial reach into African supply chains is realigning lubricant procurement standards for export-oriented fleet operators. Shell plc leverages its coastal storage infrastructure to dominate West African distribution corridors. TotalEnergies anchors its position through integrated refining at the SARA complex in Côte d'Ivoire. Engen Petroleum competes via dense retail networks across Southern African highway corridors.
Automotive lubricants are formulated base oil and additive packages engineered to reduce friction, dissipate heat, and prevent wear in powertrain assemblies operating across viscosity grades from SAE 0W-16 to 85W-140. Their primary commercial purpose is extending equipment life and maintaining fuel efficiency under thermal stress, contamination exposure, and extended drain intervals demanded by modern engine architectures. Engine oil commands the largest volume pool across African markets, though transmission fluid generates disproportionate margin contribution per liter due to technical specification density and limited local blending capacity. Aftermarket Providers represent the fastest-growing end user channel as independent workshop chains consolidate purchasing power across Nigeria, Kenya, and Ghana.
South Africa's National Regulator for Compulsory Specifications enforces SABS Mark certification for lubricants sold within SACU borders, creating a compliance threshold that filters informal imports. The East African Community's harmonized standards framework under EAC-CROS is gradually displacing national-level variance across Kenya, Tanzania, and Uganda. Nigeria's Standards Organisation of Nigeria maintains mandatory SONCAP product conformity assessment for all imported lubricant consignments. Stakeholders must monitor whether AfCFTA rules of origin negotiations will treat lubricant blending as qualifying manufacturing or residual transshipment activity.
Market Dynamics
Fleet formalization across East African corridors is compressing purchasing cycles and elevating specification requirements as commercial operators consolidate under centralized maintenance contracts.
Growth Catalysts
- EU Green Deal extraterritoriality:Export-oriented fleet operators in Nigeria and Kenya face procurement audits that favor higher-tier lubricant formulations meeting European emissions benchmarks.
- Aftermarket workshop consolidation:Independent chains across Lagos, Nairobi, and Accra aggregate volume demand and negotiate direct supply agreements with blenders.
- SACU enforcement elevation:South Africa's National Regulator for Compulsory Specifications tightens SABS Mark surveillance, filtering substandard imports and formalizing compliant supply channels.
Market Restraints
- Base oil import dependency:African blending capacity relies on Group II and III base stock shipments from Middle Eastern and Asian refiners, exposing margins to freight volatility and currency fluctuation.
- Technical specification density:Modern dual-clutch and continuously variable transmissions require fluid chemistries that exceed local formulation expertise, constraining domestic value capture.
- Counterfeit infiltration:Informal packaging operations in Nigeria's northern trade corridors dilute brand integrity and compress legitimate pricing power.
Strategic Opportunities
- AfCFTA rules of origin clarification:Pending determinations on whether lubricant blending qualifies as manufacturing or transshipment will reshape tariff positioning for regional hub operators.
- Extended drain interval chemistry:Synthetic and semi-synthetic formulations aligned with OEM service specifications offer margin expansion as fleet operators prioritize uptime over unit cost.
- Digital fleet management integration:Telematics-enabled oil condition monitoring creates predictive replacement scheduling, embedding lubricant suppliers into maintenance workflow software.
Industry Challenges
- Additive chemistry expertise scarcity:Formulation engineering talent concentrates in European and Asian technical centers, limiting African R&D autonomy.
- SONCAP certification latency:Nigeria's Standards Organisation of Nigeria product conformity assessments create import clearance delays that strain just-in-time inventory models.
- Used oil collection infrastructure gaps:Environmental compliance obligations for waste lubricant handling outpace regulatory enforcement capacity in secondary cities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Automotive Lubricants Market |
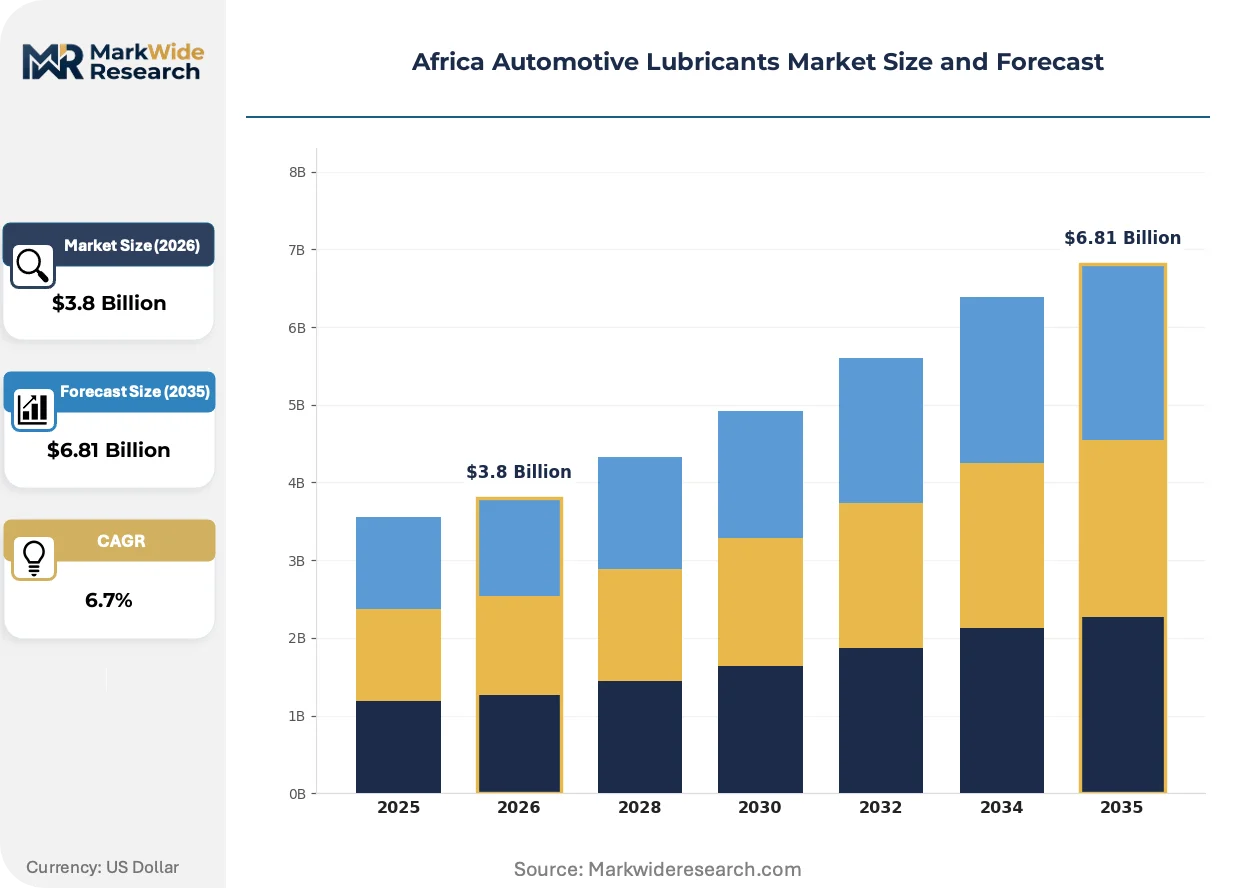
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Gear Oil, Transmission Fluid, Hydraulic Oil Application: Commercial Vehicles, Passenger Cars, Motorcycles, Marine End User: OEMs, Aftermarket Providers, Workshop Services, Fleet Operators Packaging Type: Drum, Barrel, Bottle, Pail |
| Companies Covered | BP plc, Chevron Corporation, Shell plc, Fuchs Petrolub, Vivo Energy, TotalEnergies, Engen Petroleum, KenolKobil, ExxonMobil Corporation, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Automotive Lubricants Market Strategic Shifts
Digitalization of fleet maintenance workflows and additive chemistry advancement are compressing traditional distribution hierarchies while elevating technical service expectations among commercial buyers.
Low-viscosity engine oil formulations are modularizing service protocols across African fleet operations. SAE 0W-20 and 0W-16 grades reduce cold-start wear and improve fuel efficiency metrics that telematics systems now track in real time. Large transport operators in Kenya and Ghana adopt these specifications faster than independent owner-drivers, creating a two-speed specification market.
South Africa's Department of Transport emissions testing protocols now incorporate lubricant quality verification as a secondary checkpoint. Workshops must document oil grade compliance to pass vehicle roadworthiness certification, elevating documentation burdens on informal service providers. This regulatory tightening accelerates consolidation toward certified workshop chains with audit-ready inventory systems.
Buyer concentration among consolidated fleet operators is displacing fragmented retail purchasing as the dominant demand signal. National logistics companies and ride-hail platforms in Nigeria negotiate annual volume contracts directly with blender-distributors, bypassing traditional wholesale layers. This channel compression concentrates pricing power with buyers who possess usage data and specification expertise.
Africa Automotive Lubricants Market Segmentation
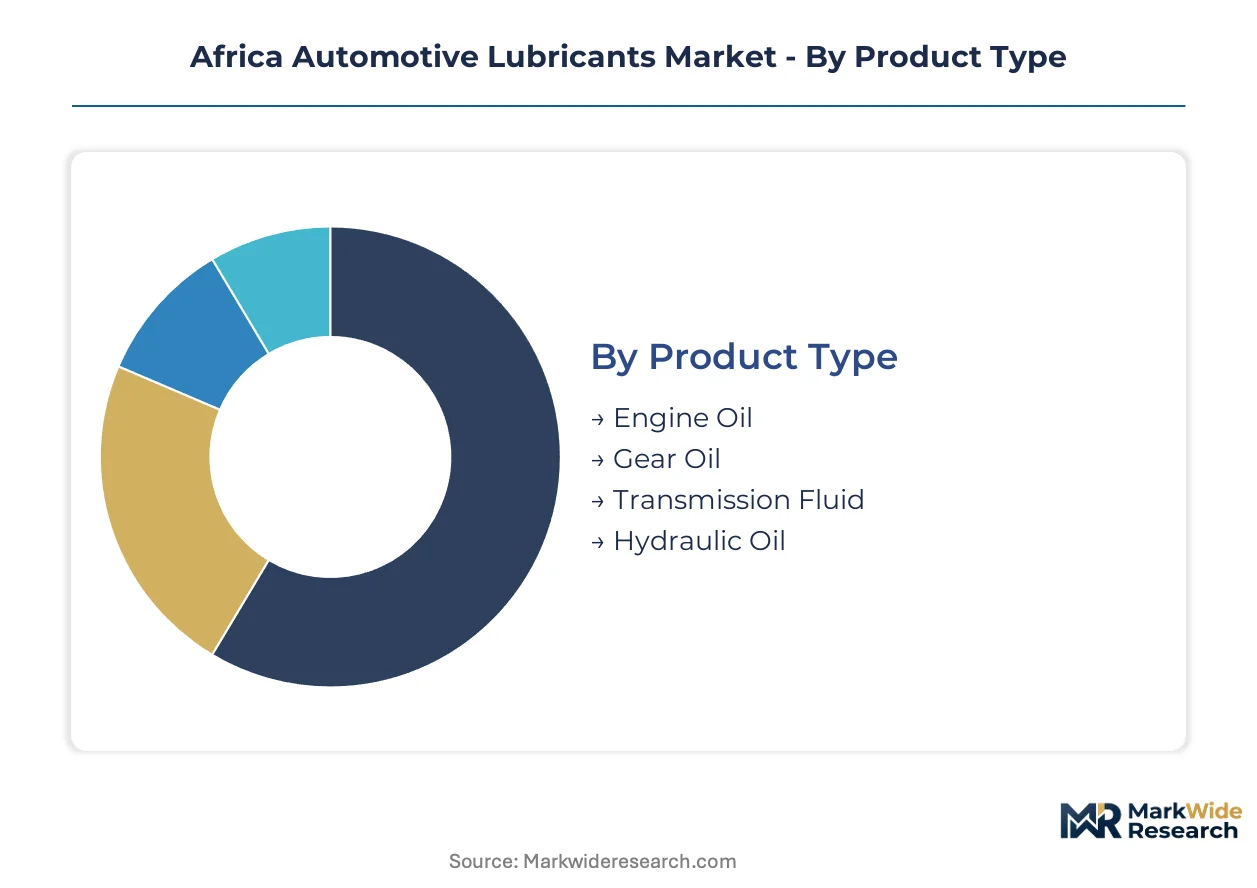
Product differentiation across viscosity grades and additive packages determines procurement patterns for fleet operators versus independent workshops. Specification density varies sharply between high-volume engine oils and technically complex transmission fluids, creating divergent margin structures across distribution channels.
Product Type:
Standalone lubricant products dominate commercial procurement, while additive-integrated formulations serve embedded OEM service protocols.
- Engine Oil:Formulated from Group II/III base stocks with detergent-dispersant additive packages across SAE 0W-16 to 15W-40 viscosity grades. Demand concentrates in Nigeria's Lagos-Ibadan corridor where informal transport networks and emerging fleet formalization create dual-track consumption—bulk drums for commercial operators versus retail bottles for independent owner-drivers. Base oil import dependency from Middle Eastern refiners exposes margins to freight volatility and currency fluctuation.
- Transmission Fluid:Chemically complex formulations for dual-clutch, CVT, and conventional automatic transmissions requiring precise friction modification. Kenya's consolidated logistics fleets negotiate direct supply agreements for synthetic ATF grades that exceed local blending expertise, constraining domestic value capture while generating disproportionate margin per liter. Technical specification density limits qualified supplier pools.
- Gear Oil:Extreme-pressure lubricants for axle and differential assemblies, typically SAE 75W-90 to 85W-140 grades. Mining and construction equipment operators in South Africa's Northern Cape specify synthetic variants for extended drain intervals under heavy load conditions.
- Hydraulic Oil:Anti-wear formulations for power transmission in commercial vehicle ancillary systems. Agricultural mechanization across Ghana's northern regions drives seasonal demand spikes tied to planting and harvest cycles.
Engine Oil leads volumes today; Transmission Fluid is gaining share fastest.
Application:
Vehicle duty cycles determine specification intensity, with continuous-operation commercial fleets demanding higher-tier chemistries than intermittent-use passenger vehicles.
- Commercial Vehicles:Heavy-duty trucks and buses accumulating high annual kilometers across East African corridors. Fleet formalization compresses purchasing cycles and elevates requirements as operators consolidate under centralized maintenance contracts with documented oil grade compliance.
- Passenger Cars:Private vehicles and ride-hail platforms with variable utilization patterns. South Africa's emissions testing protocols now incorporate lubricant quality verification, elevating documentation burdens on informal service providers.
- Motorcycles:Two-stroke and four-stroke engine oils for Africa's dominant informal transport mode. Northern Nigeria's trade corridors face counterfeit infiltration that dilutes brand integrity and compresses legitimate pricing power.
- Marine:Outboard and inboard engine lubricants for coastal fishing and transport vessels. West African port cities generate concentrated demand tied to artisanal fishing fleet maintenance.
Commercial Vehicles anchor current demand; Fleet Operators within this segment are expanding scheduled maintenance programs most aggressively.
End User:
Channel structure determines pricing power concentration, with consolidated buyers leveraging usage data against fragmented retail purchasing.
- Aftermarket Providers:Independent workshop chains consolidating across Lagos, Nairobi, and Accra. These buyers aggregate volume demand and negotiate direct supply agreements with blender-distributors, bypassing traditional wholesale layers.
- Fleet Operators:National logistics companies and ride-hail platforms with centralized procurement functions. Nigeria's emerging fleet formalization creates dual-track consumption patterns alongside informal networks.
- OEMs:Vehicle assemblers and authorized dealer networks specifying factory-fill and service-fill lubricants. South Africa's automotive manufacturing base maintains captive supply relationships with integrated oil companies.
- Workshop Services:Individual repair establishments with fragmented purchasing and limited specification expertise. SONCAP certification latency strains just-in-time inventory models for imported consignments.
Aftermarket Providers represent the fastest-growing channel; OEMs retain the most concentrated contract values.
Packaging Type:
Container format aligns with customer scale and inventory turnover velocity across distribution tiers.
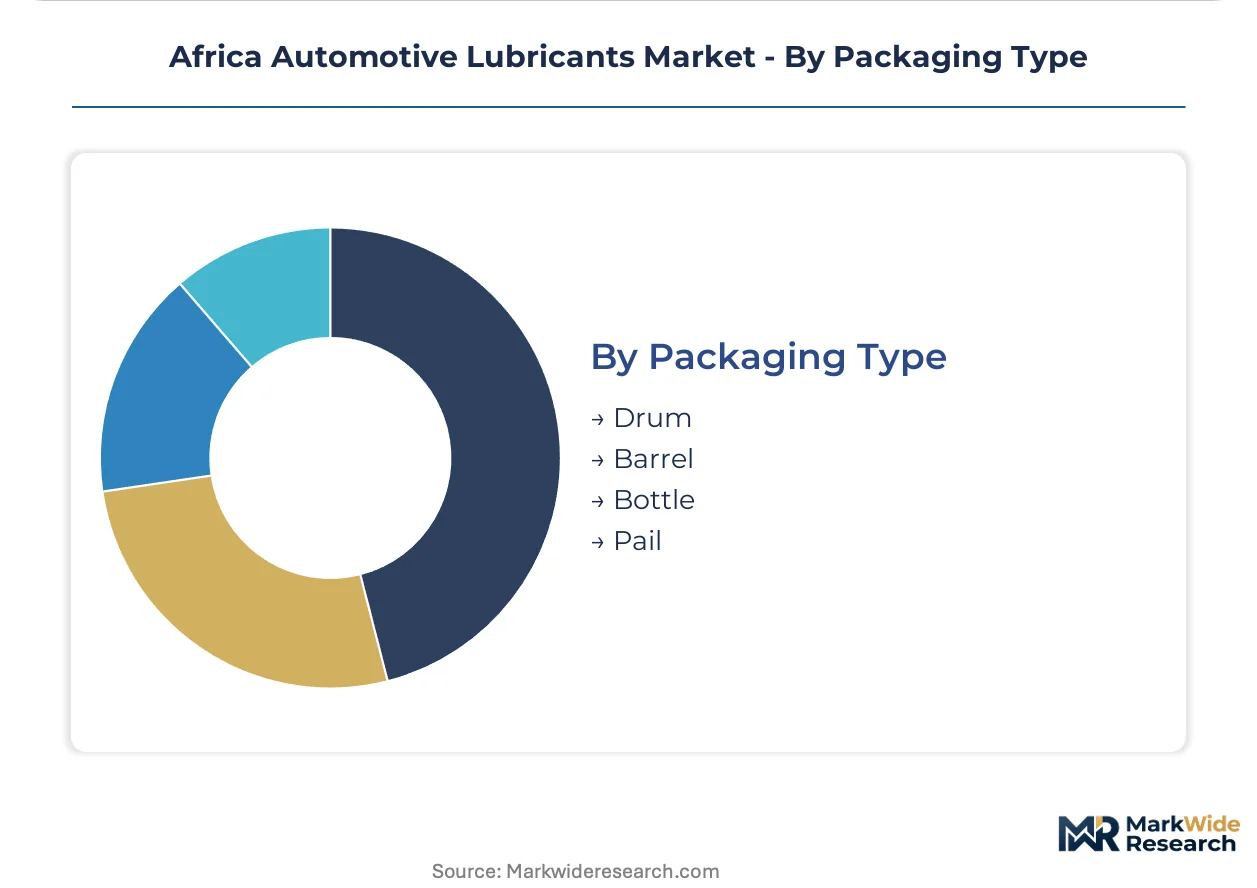
- Drum:200-liter steel containers for high-volume fleet and industrial accounts. Coastal storage infrastructure at West African ports enables bulk breakdown into downstream packaging.
- Barrel:Intermediate bulk formats for regional distributor stocks. East African Community harmonized standards under EAC-CROS gradually displace national-level variance in container specifications.
- Bottle:Retail consumer and small workshop packaging. Counterfeit infiltration in Nigeria's northern trade corridors targets this format most intensively.
- Pail:20-25 liter plastic containers for mid-tier workshop and agricultural customers. Ghana's mechanizing farm sector drives seasonal pail demand.
Drum format leads commercial volumes; Bottle packaging faces the steepest competitive pressure from informal repackaging operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized lubricant formulation engineers concentrate in South Africa's industrial corridors, while East African logistics hubs develop maintenance technician pools to support fleet formalization. Regional demand patterns diverge sharply between coastal import gateways and inland consumption centers.
Nigeria
Lagos-Ibadan industrial corridor hosts Africa's most fragmented lubricant demand, with informal transport networks consuming retail-packaged products alongside emerging fleet operators purchasing bulk drums. The Standards Organisation of Nigeria enforces SONCAP product conformity assessments that create import clearance bottlenecks. Northern trade corridors around Kano face counterfeit infiltration that compresses legitimate pricing power for branded formulations.
South Africa
Gauteng Province anchors continental blending capacity with integrated refining infrastructure serving SACU markets. The National Regulator for Compulsory Specifications tightens SABS Mark surveillance, filtering substandard imports through laboratory verification protocols. Northern Cape mining operators specify synthetic gear oils for extended drain intervals under heavy load conditions.
Kenya
Nairobi-based logistics fleets negotiate direct supply agreements for synthetic transmission fluids that exceed local formulation expertise. The East African Community harmonized standards framework under EAC-CROS gradually displaces national-level variance across Kenya, Tanzania, and Uganda. Mombasa port storage infrastructure enables bulk breakdown for regional distribution.
Ghana
Accra workshop chains consolidate purchasing power through direct blender-distributor agreements, bypassing traditional wholesale layers. Agricultural mechanization across the northern regions drives seasonal pail demand tied to planting and harvest cycles. The emerging ride-hail platform economy creates concentrated fleet procurement with documented oil grade compliance requirements.
Côte d'Ivoire
Abidjan's SARA refining complex anchors West African base stock supply for regional blending operations. Coastal storage infrastructure enables transshipment to landlocked Sahel markets. The industrial zone around the port generates concentrated demand from construction equipment and commercial trucking fleets.
Africa Automotive Lubricants Market Competitive Environment
Capital-heavy producers with integrated refining assets compete with asset-light distributors relying on third-party blending tolling. The market structures around three tiers: multinational oil majors with captive supply chains, regional distributors with dense retail networks, and independent blenders serving price-sensitive informal segments. Strategic moves concentrate on coastal storage expansion and workshop chain direct contracting.
Among integrated oil majors, Shell plc, TotalEnergies, and BP plc occupy positions defined by coastal infrastructure control and refinery-linked supply security. Shell plc exemplifies the storage-dominant archetype through West African port terminal leverage. TotalEnergies anchors the integrated refining tier via the SARA complex. BP plc represents the multinational distributor model with brand-licensed local partnerships. Regional specialists including Engen Petroleum and Vivo Energy compete through highway corridor retail density and fleet direct sales forces.
| Leading Market Players |
|---|
| BP plc |
| Chevron Corporation |
| Shell plc |
| Fuchs Petrolub |
| Vivo Energy |
| TotalEnergies |
| Engen Petroleum |
| KenolKobil |
| ExxonMobil Corporation |
| Others |
Value Chain & Pricing Dynamics
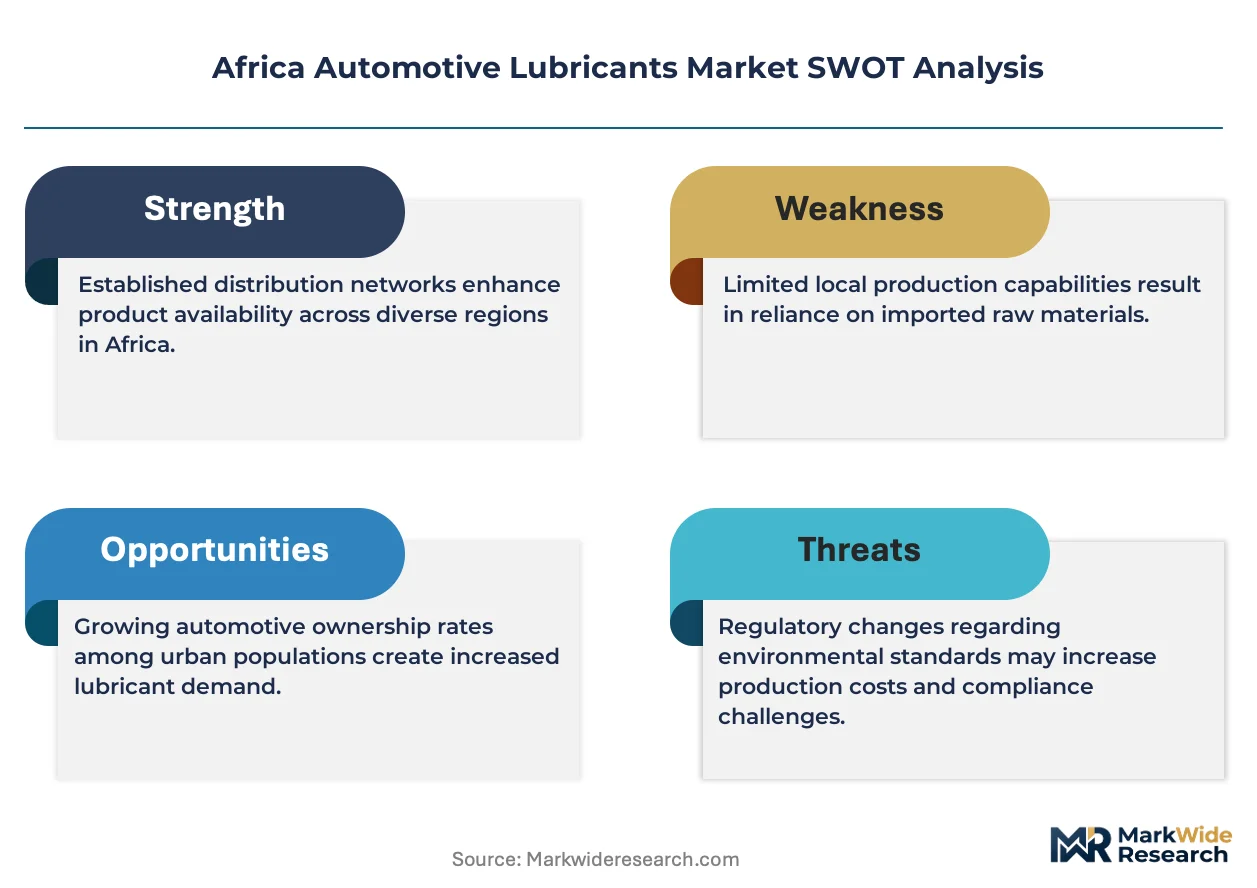
The EU Green Deal's extraterritorial emissions benchmarks gate qualified supply and premium-tier pricing access for African fleet operators serving export corridors. Compliance documentation requirements elevate procurement costs for higher-specification formulations while filtering informal blenders from certified channels.
Pricing Analysis
Bundled technical service contracts versus unbundled product-only sales split pricing power across buyer segments. Three-tier pricing structure across premium synthetic, standard mineral, and economy re-refined levels tracks SABS Mark and SONCAP certification status. Price differentiation stems from additive package complexity and documented drain interval performance. Cost compression in the economy tier intensifies because counterfeit infiltration erodes brand premium capture. Independent owner-drivers in Nigeria's northern corridors exhibit highest price sensitivity; consolidated logistics fleets in Kenya prioritize uptime metrics over unit cost.
Supply Chain Analysis
AfCFTA rules of origin negotiations and emerging local-content mandates for state fleet procurement are reshaping sourcing decisions toward regional blending hubs. Base oil supply concentrates in the Middle East, Singapore, and South Africa's SARA complex. African formulation capacity draws from Group II and III base stock shipments, additive packages from European and Asian technical centers, and steel drum packaging from Egyptian and South African metalworks. Single-source vulnerability runs through Middle Eastern refiner export scheduling. Distribution runs through coastal storage terminals at Lagos, Mombasa, and Abidjan with bulk breakdown into drum and pail formats for inland corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Africa Automotive Lubricants Market functions as a stable compounder underpinned by fleet formalization's irreversible compression of purchasing cycles toward centralized maintenance contracts.
For Market Incumbents: Anchor coastal storage infrastructure at West and East African port terminals to defend against toll-blending competitors seeking tariff arbitrage. Deepen backward integration into base oil sourcing through long-term offtake agreements with Middle Eastern refiners. Counter additive chemistry expertise scarcity by embedding technical service teams within consolidated fleet operator maintenance workflows. For New Entrants and Emerging Players: Launch via direct contracting with emerging ride-hail platform fleets in Ghana and Nigeria's Lagos-Ibadan corridor, bypassing wholesale layers that incumbent networks control. Target agricultural mechanization demand across Ghana's northern regions with seasonal pail-format offerings timed to planting cycles. Exploit SONCAP certification latency among established importers by building pre-certified inventory buffers. For Investors and Strategic Acquirers: Valuations sit cheapest among independent blenders with coastal storage leases but lacking brand-licensed distribution networks. The 5-to-10-year viability window favors targets with demonstrated compliance navigation across SABS Mark, SONCAP, and EAC-CROS frameworks. Watch AfCFTA rules of origin determinations on lubricant blending qualification as the inflection signal for regional hub operator repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Coastal Storage Expansion | Shell plc's West African terminal leverage demonstrates port control as competitive moat. |
| Direct Fleet Contracting | Engen Petroleum's highway corridor sales forces bypass wholesale margin capture. |
| Additive Chemistry Partnership | Local blenders licensing European technical packages overcome formulation expertise gaps. |
| Digital Fleet Integration | Telematics-enabled oil condition monitoring embeds suppliers into predictive maintenance workflows. |
| Refining Asset Integration | TotalEnergies' SARA complex secures base stock supply security for regional blending. |
Study Parameters
Coverage spans West, East, and Southern Africa, with primary inputs from each regional cluster triangulated against secondary validation. Interviews with lubricant blending plant managers, fleet procurement directors at logistics operators, aftermarket workshop chain owners, and technical R&D directors at additive suppliers informed demand-side and supply-side dynamics. Secondary sources include customs and trade data from Nigerian and Kenyan port authorities, SABS and SONCAP certification registries, SEC filings from integrated oil majors, and East African Community harmonized standards documentation. Bottom-up volume modeling from fleet operator consumption patterns and top-down value estimation from import value data were cross-referenced for convergence.
Granularity-level modeling addressed product type at viscosity grade and base stock group tier, application at vehicle duty cycle intensity, end user at channel concentration level, and packaging format at container size and material specifications. CAGRs were derived from segment-level volume trajectories and price evolution assumptions across the projection horizon. Industry-specific forecast inputs incorporated commercial vehicle kilometer accumulation rates from East African corridor telematics and South African emissions testing protocol enforcement timelines.
Several conditions sit outside the modeled scope, including potential AfCFTA tariff reclassification, currency devaluation episodes beyond historical volatility bands, and geopolitical disruption to Middle Eastern base oil export routes. Forecasts reflect documented assumptions regarding fleet formalization velocity and regulatory enforcement consistency. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Carbon Thermoplastic Market
Automotive Components
Global Automotive Pneumatic Valve Market
Automotive Components
Automotive Stamped Component Market
Automotive Components
Automotive Key Market
Automotive Components
Automotive Active Suspension System Market
Automotive Components
Global Cylinder Deactivation System Market
Automotive Components
Russia Automotive Electric Actuators Market
Automotive Components
Automotive HVAC Ducts Market
Automotive Components
Asia Pacific Automotive Bearing Market
Automotive Components
Automotive Evaporative Emission Control (EVAP) System Market
Automotive Components
India Automotive Stamping Market
Automotive Components
India Passenger Vehicles Lubricants Market
Automotive Components
Germany Automotive Carbon Fiber Composites Market
Automotive Components
Global Automotive Interior Plastic Components Market
Automotive Components
Automotive Defroster Market
Automotive Components
Global Automotive Collapsible Steering Column Market