
 Russia Automotive Pneumatic Actuators Market | 2026-2036
Russia Automotive Pneumatic Actuators Market Size, Share, and Industry Trends Forecast 2026-2036
Russia Automotive Pneumatic Actuators Market Analytics
Russian actuator manufacturing is pivoting toward import-substitution programs as Western supply chains contract. IMI Norgren leverages its established distribution footprint to sustain aftermarket coverage across the Central Federal District. Bosch Rexroth AG anchors its position through localized technical service networks for heavy-duty vehicle applications. Festo competes on modular pneumatic cylinder platforms designed for rapid assembly-line integration.
Russia automotive pneumatic actuators are electromechanical devices that convert compressed air into linear or rotary mechanical motion, typically operating at pressures between 0.4 and 1.0 MPa to control engine intake systems, braking mechanisms, and suspension components. These devices serve as critical motion-control elements in powertrain and chassis systems where pneumatic response speed exceeds hydraulic alternatives. Linear actuators dominate OEM procurement volumes due to standardized mounting interfaces for throttle and clutch control modules. Smart pneumatics represents the fastest-expanding technology segment as vehicle assemblers demand sensor-integrated units with real-time position feedback. Electropneumatic systems command premium positioning in integrated braking architectures where electronic stability control mandates precise pressure modulation.
Russia's technical regulation framework under Rosstandart and the Eurasian Economic Union's TR CU 018/2011 safety certification shapes product compliance requirements for pneumatic braking and steering components. The country's national automotive regulator enforces GOST-R conformity assessment protocols that limit market access for non-certified actuator suppliers. Domestic producers must navigate both EAC marking obligations and Russia's import substitution directives favoring localized component sourcing. Stakeholders should monitor how evolving EEU technical regulations and domestic industrial policy realign supplier qualification criteria for pneumatic control systems.
Market Dynamics
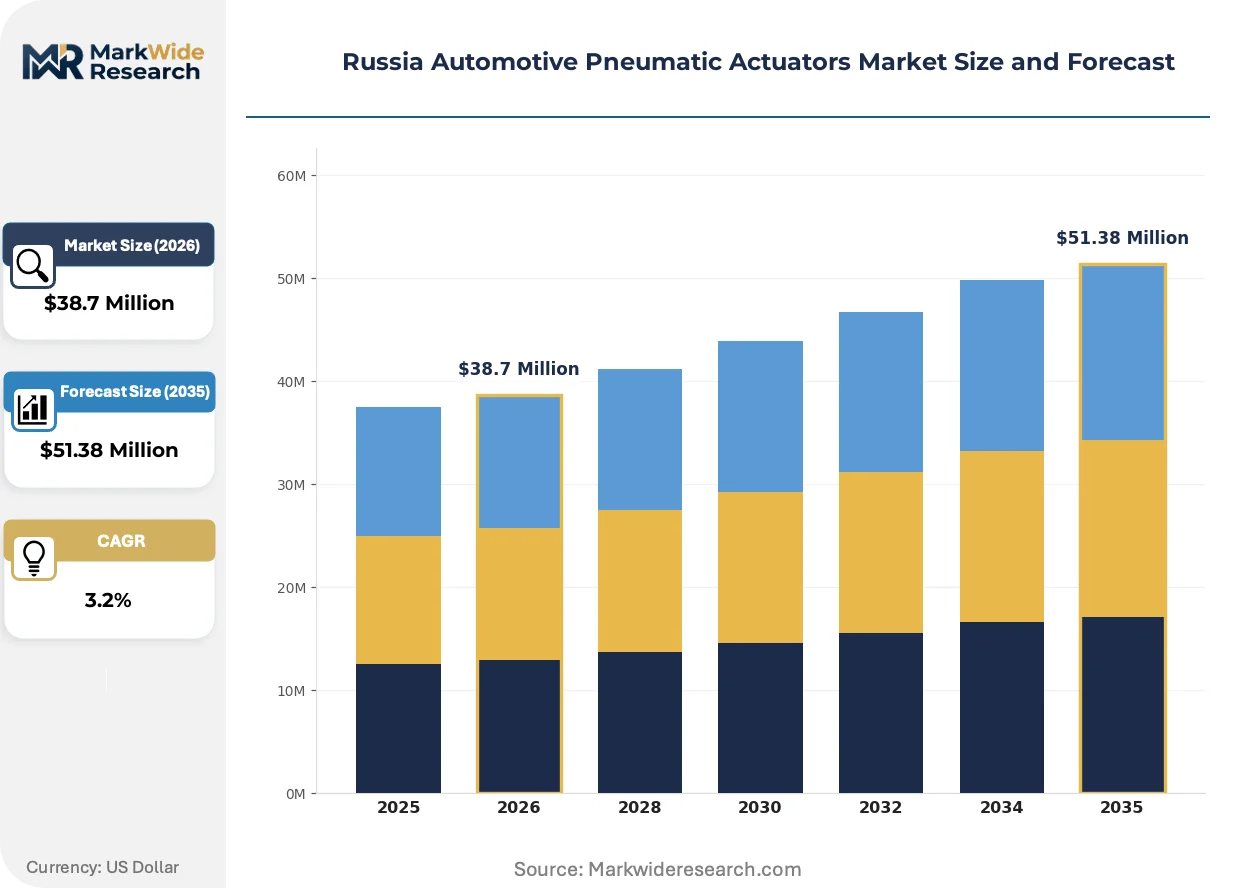
Domestic safety certification tightening under TR CU 018/2011 is forcing commercial vehicle OEMs to requalify pneumatic braking suppliers, compressing procurement timelines and privileging electropneumatic architectures with embedded diagnostic capability.
Growth Catalysts
- Electropneumatic braking mandates:TR CU 018/2011 certification requirements are accelerating replacement of pure pneumatic braking with electronically modulated systems in heavy-duty vehicle platforms.
- Smart pneumatic clusters:Moscow and Tatarstan manufacturing hubs are concentrating demand for sensor-integrated actuators with real-time position feedback capabilities.
- Import substitution directives:Russia's industrial policy framework is redirecting procurement toward domestic actuator assembly to reduce Western component dependency.
Market Restraints
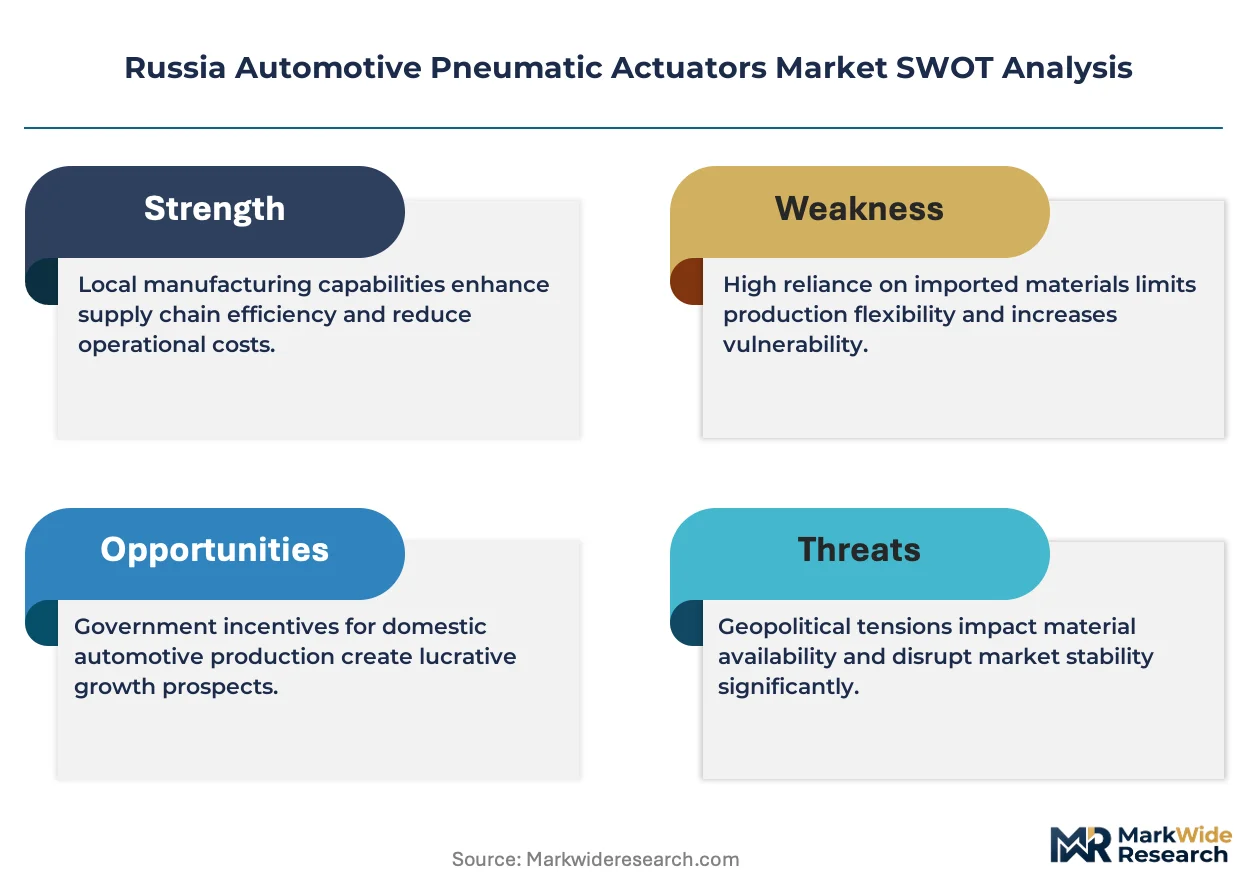
- Specialized alloy supply concentration:High-grade aluminum and specialty steel inputs for pneumatic cylinder bodies face sourcing bottlenecks from contracted Western metallurgical suppliers.
- Electromechanical substitution pressure:All-electric actuators in throttle and clutch control modules are displacing pneumatic alternatives in passenger vehicle powertrain architectures.
- GOST-R certification friction:Extended conformity assessment timelines for pneumatic steering and braking components delay new supplier market entry by 12-18 months.
Strategic Opportunities
- Volga Federal District commercial vehicle expansion:Heavy-duty truck and bus OEMs in this region are expanding electropneumatic braking actuator procurement volumes.
- Integrated diagnostic convergence:Combining IO-Link connectivity with pneumatic position sensing is opening premium pricing tiers in automated assembly applications.
- Aftermarket service channel innovation:Authorized service networks for pneumatic braking systems are capturing replacement demand from aging commercial vehicle fleets.
Industry Challenges
- Mechatronics skill scarcity:Qualified technicians for electropneumatic system calibration and repair are concentrated in Moscow and Saint Petersburg, limiting service network expansion.
- Legacy pneumatic integration complexity:Retrofitting smart pneumatic modules into existing vehicle architectures requires custom mounting interface engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Russia Automotive Pneumatic Actuators Market |
| Market Size in 2026 | $38.7 Million |
| Market Size in 2035 | $51.38 Million |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Linear Actuators, Rotary Actuators, Pneumatic Cylinders, Pressure Switches End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Installation Type: Integrated Systems, Add-on Solutions, Retrofits, Modular Applications Technology: Electropneumatic, Analog Systems, Smart Pneumatics, High Efficiency Solutions |
| Companies Covered | IMI Norgren, Bosch Rexroth AG, Denso Corporation, Festo, SMC Corporation, Robert Bosch GmbH, Parker Hannifin Corp., Emerson Electric Co, Continental AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Russia Automotive Pneumatic Actuators Market Evolving Landscape
Sensor-integrated pneumatic architectures are displacing standalone mechanical actuators across Russian commercial vehicle platforms, with regulatory pressure and fleet telematics demands converging to reshape supplier technical roadmaps.
Smart pneumatic cylinders with embedded magnetostrictive position sensors are unifying motion control and condition monitoring functions in single hardware units. Heavy-duty brake system OEMs in the Central Federal District are specifying these integrated modules for electronic stability control architectures. This unification is compressing the supplier base by eliminating separate sensor and actuator vendors from qualified procurement lists.
Rosstandart enforcement of EAC marking amendments for pneumatic braking components is tightening traceability requirements across the supply chain. Domestic actuator manufacturers must now document material provenance and testing protocols for EEU customs union compliance. Commercial vehicle assemblers in Tatarstan are responding by consolidating supplier qualification around vertically integrated producers with in-house testing laboratories.
Fleet operators are compressing actuator replacement cycles from condition-based to predictive maintenance schedules driven by telematics data. Authorized distributors in the Volga Federal District are unbundling after-sales service from hardware supply, creating standalone diagnostic and calibration revenue streams. This behavioral shift is most visible among long-haul logistics operators managing Kamaz and GAZ vehicle platforms.
Russia Automotive Pneumatic Actuators Market Segmentation
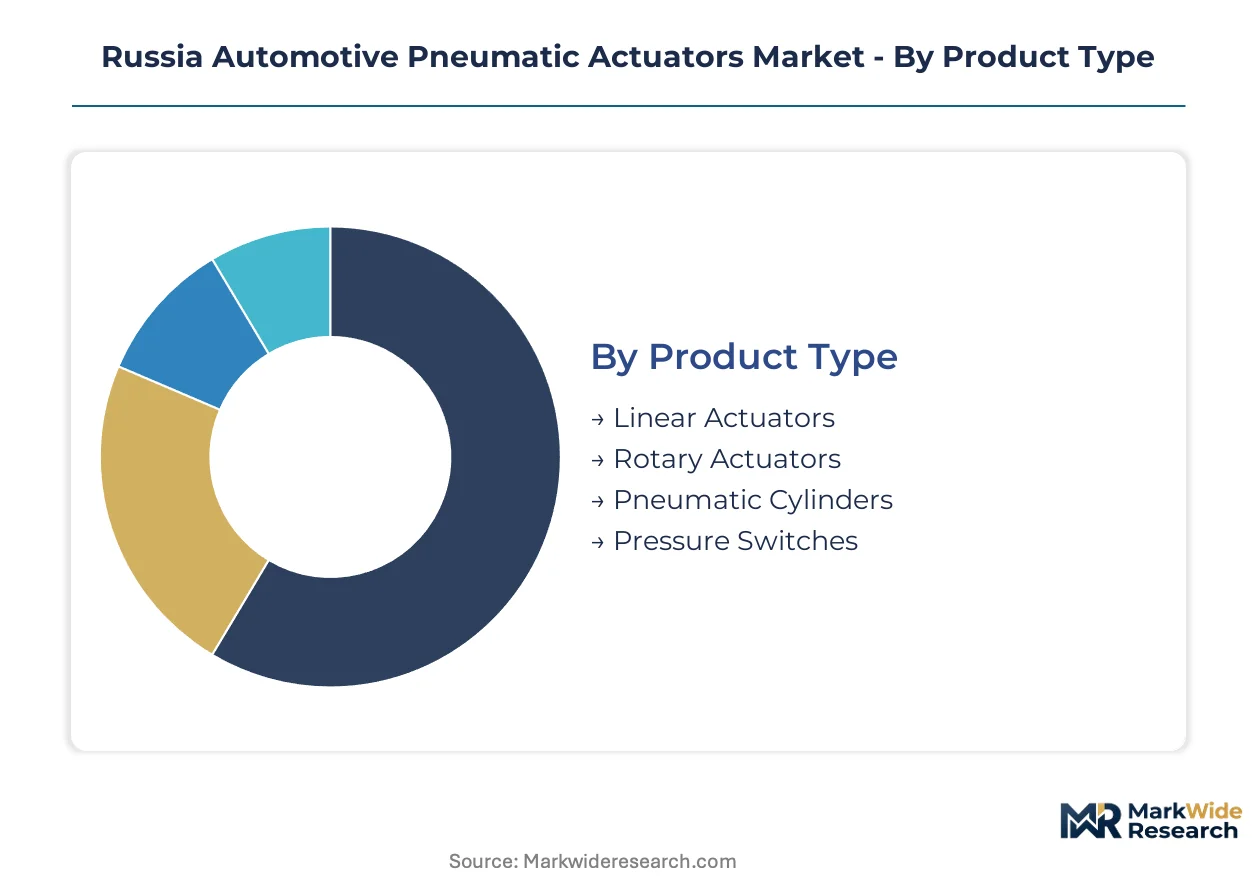
Segmentation in Russia's automotive pneumatic actuators market reveals how regulatory pressure and supply chain restructuring reshape procurement patterns across distinct technical and commercial axes. Understanding these divisions exposes where import substitution directives concentrate investment and which technology platforms command premium positioning.
Product Type:
Product specifications determine pressure ratings, stroke lengths, and mounting interfaces that align with specific vehicle system architectures.
- Linear Actuators:These devices convert compressed air into straight-line mechanical motion through piston-rod assemblies, typically operating at 0.4-1.0 MPa for throttle and clutch control modules. OEM procurement volumes in the Central Federal District favor standardized ISO 15552 mounting interfaces that accelerate assembly-line integration.
- Rotary Actuators:Rack-and-pinion or vane-style mechanisms deliver angular motion output for steering assistance and valve positioning applications. Demand clusters around Tatarstan-based vehicle assemblers seeking compact envelope dimensions for chassis packaging constraints.
- Pneumatic Cylinders:Single-acting and double-acting cylinder bodies form the core hardware substrate across braking and suspension systems.
- Pressure Switches:Electromechanical sensors monitor system pressure thresholds for safety interlock and diagnostic functions.
Linear actuators lead on scale; smart pneumatic variants lead on momentum.
End User:
Customer type determines volume commitments, certification requirements, and technical service expectations across the procurement chain.
- OEMs:Original equipment manufacturers in the Volga Federal District specify electropneumatic braking architectures under tightening TR CU 018/2011 mandates. These buyers demand embedded diagnostic capability and EAC marking documentation that compresses supplier qualification timelines.
- Tier-1 Suppliers:Subsystem integrators consolidate pneumatic component sourcing for transmission and chassis module assembly. Procurement concentrates among Moscow-region suppliers with in-house testing laboratories for GOST-R conformity assessment.
- Aftermarket Providers:Independent distributors capture replacement demand from aging commercial vehicle fleets across Siberian and Far Eastern logistics corridors.
- Vehicle Assemblers:Final production facilities integrate actuator systems into complete powertrain and braking platforms.
OEMs dominate absolute volume; aftermarket providers show the steepest expansion trajectory.
Installation Type:
System architecture choices reflect vehicle generation, platform flexibility requirements, and fleet operator maintenance strategies.
- Integrated Systems:Factory-installed electropneumatic modules with sensor feedback loops serve electronic stability control architectures. Kamaz and GAZ production lines in Tatarstan specify these units for new heavy-duty platform launches.
- Add-on Solutions:Supplementary pneumatic kits upgrade existing vehicle capabilities without full system replacement. Regional bus operators in the Volga Federal District deploy these for accessibility equipment retrofits.
- Retrofits:Field-installed upgrades adapt legacy vehicles to evolving safety certification requirements.
- Modular Applications:Standardized pneumatic building blocks enable rapid configuration changes across mixed fleet operations.
Integrated systems command the largest share; retrofit demand is climbing fastest amid fleet renewal pressures.
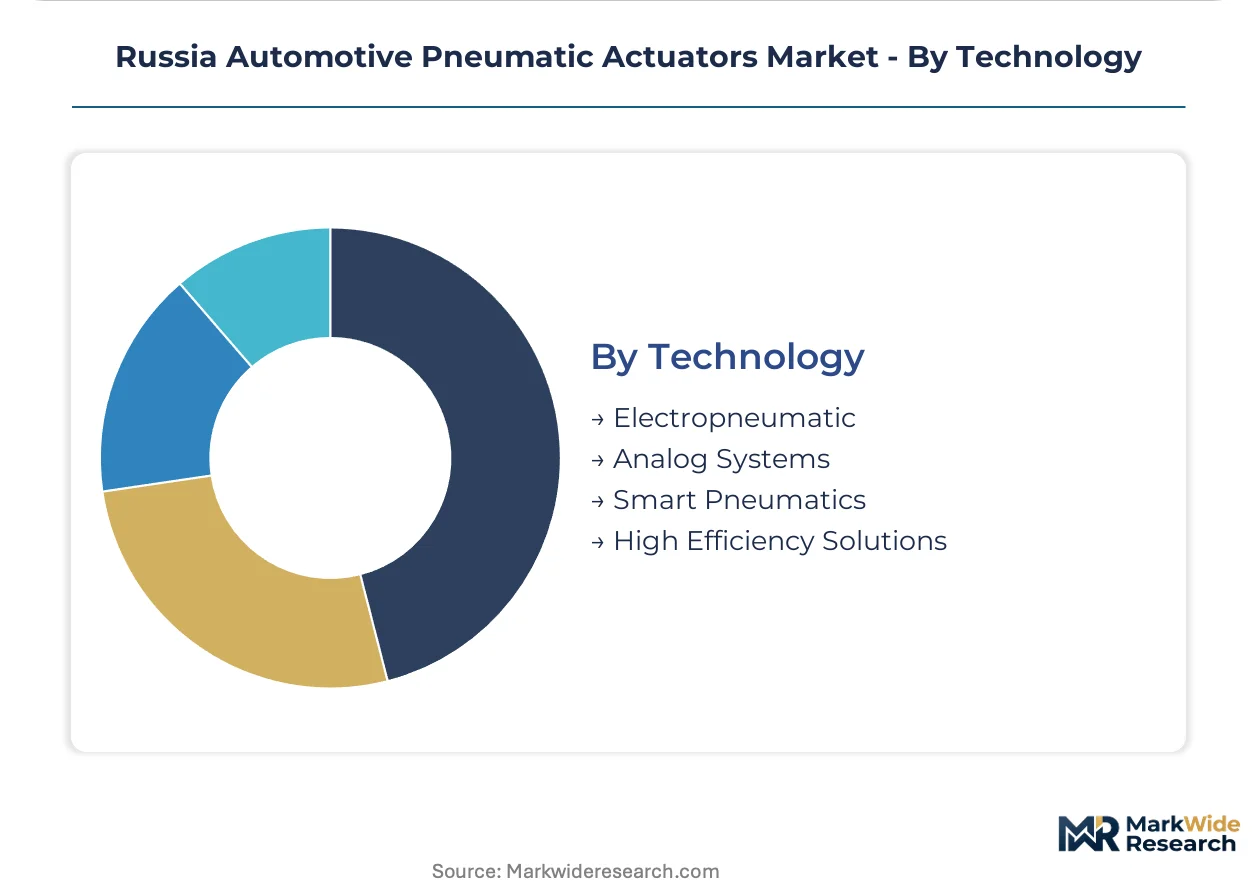
Technology:
Technical sophistication tiers separate commodity pneumatic hardware from premium electromechanical platforms with embedded intelligence.
- Electropneumatic:Electronically modulated pressure control enables precise braking force distribution and stability intervention. These systems anchor supplier portfolios for heavy-duty commercial vehicle OEMs facing Rosstandart enforcement of amended EAC marking protocols.
- Smart Pneumatics:IO-Link connected actuators with magnetostrictive position sensing unify motion control and condition monitoring. Moscow manufacturing clusters drive specification of these units for automated assembly and predictive maintenance architectures.
- Analog Systems:Pure pneumatic circuits without electronic modulation persist in cost-sensitive applications and legacy platform support.
- High Efficiency Solutions:Optimized air consumption designs reduce compressor load and energy draw in continuous-duty applications.
Electropneumatic platforms dominate current procurement; smart pneumatics is gaining share fastest through fleet telematics convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's automotive pneumatic actuator demand diverges sharply from Russia's import-substitution trajectory, with German OEMs prioritizing electropneumatic integration for export-certified platforms while Russian assemblers navigate localized sourcing mandates.
Central Federal District
Moscow anchors Russia's smart pneumatic demand, with sensor-integrated actuator procurement accelerating for automated assembly lines. Rosstandart enforces EAC marking amendments that compress supplier qualification timelines. Technical service networks for heavy-duty vehicle applications cluster around the capital, sustaining aftermarket coverage for electropneumatic braking systems.
Volga Federal District
Commercial vehicle OEMs in this region expand electropneumatic braking actuator procurement as TR CU 018/2011 certification rules tighten. Kamaz production facilities specify integrated diagnostic modules for new heavy-duty platform launches. Tatarstan-based assemblers consolidate supplier qualification around vertically integrated producers with in-house testing laboratories.
Northwestern Federal District
Saint Petersburg concentrates mechatronics technician expertise for electropneumatic system calibration, limiting service network expansion to this metro. GOST-R conformity assessment protocols delay new supplier market entry by 12-18 months. Fleet operators managing aging commercial vehicles drive replacement demand through authorized distributors.
Siberian Federal District
Long-haul logistics corridors across Siberia generate aftermarket actuator demand from aging Kamaz and GAZ vehicle platforms. Import substitution directives redirect procurement toward domestic assembly to reduce Western component dependency. Regional distributors unbundle after-sales service from hardware supply, creating standalone diagnostic revenue streams.
Southern Federal District
Bus operators deploy add-on pneumatic kits for accessibility equipment retrofits, upgrading existing capabilities without full system replacement. Specialized alloy supply bottlenecks from contracted Western metallurgical suppliers constrain high-grade aluminum sourcing for cylinder bodies. Modular pneumatic building blocks enable rapid configuration changes across mixed fleet operations.
Russia Automotive Pneumatic Actuators Market Competitive Landscape
Western European producers anchor the premium electropneumatic tier; East Asian specialists hold positions in high-volume pneumatic cylinder supply. The vendor base stratifies across three functional layers: integrated system architects with embedded diagnostic portfolios, modular component fabricators serving rapid assembly-line integration, and aftermarket service networks capturing replacement cycles. Consolidation pressure favors suppliers with in-house EAC marking documentation and GOST-R testing capabilities. Dominant competitive moves include backward integration into specialty alloy sourcing and technology licensing partnerships for IO-Link connectivity modules.
Among Germany-based industrial automation groups, Festo and Bosch Rexroth AG exemplify the integrated system architect archetype, occupying positions that privilege localized technical service networks. IMI Norgren represents the aftermarket coverage specialist tier, with distribution footprints sustaining replacement demand across federal districts where Western supply chains have contracted. These three anchors illustrate how geographic origin and organizational structure map onto divergent strategic postures within Russia's import-substitution environment.
| Leading Market Players |
|---|
| IMI Norgren |
| Bosch Rexroth AG |
| Denso Corporation |
| Festo |
| SMC Corporation |
| Robert Bosch GmbH |
| Parker Hannifin Corp. |
| Emerson Electric Co |
| Continental AG |
| Others |
Value Network & Pricing Analysis
Mechatronics technician scarcity in the Northwestern Federal District widens labor-cost spreads between Moscow-region assemblers and peripheral service networks, compressing margin structures for aftermarket providers while premium-tier electropneumatic modules capture pricing power through embedded diagnostic certification.
Pricing Analysis
Capacity additions in Tatarstan manufacturing hubs are reshaping price floors for pneumatic cylinder assemblies as vertically integrated domestic producers achieve scale economies in ISO 15552 mounting interface fabrication. Three-tier pricing structure across premium, standard, and economy levels separates EAC-marked electropneumatic braking systems from GOST-R certified analog alternatives and unbranded replacement units. Pricing pressure stems from electromechanical actuator substitution in passenger vehicle throttle modules, forcing pneumatic suppliers to defend positioning through after-sales service bundling. Fleet operators in Siberian logistics corridors exhibit highest price sensitivity, while OEM platform engineers in the Volga Federal District prioritize certification compliance over unit cost.
Supply Chain Analysis
High-grade aluminum billet supply rests on contracted Western metallurgical suppliers, with specialty steel for pneumatic cylinder bodies drawing from German and Japanese precision forging operations. Magnetostrictive position sensors and IO-Link connectivity modules feed from South Korean and Taiwanese electronics manufacturing clusters. Single-source vulnerability concentrates in specialty alloy procurement, where Rosstandart material provenance documentation requirements limit rapid supplier switching. Distribution runs through authorized technical service networks anchored in Moscow and Saint Petersburg, with regional distributors in Siberia and the Far East unbundling diagnostic capabilities from hardware fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Russia's automotive pneumatic actuators market functions as a geographic-arbitrage play where EEU regulatory alignment costs in Moscow-region assembly clusters diverge from lower-compliance aftermarket channels in Siberian logistics corridors.
For Market Incumbents: Cement positioning through captive supply of specialty aluminum alloys and in-house GOST-R testing laboratory accreditation, insulating against Western metallurgical supply contraction while accelerating EAC marking documentation for electropneumatic braking platforms facing Rosstandart enforcement tightening. For New Entrants and Emerging Players: Authorized service network partnerships in the Siberian Federal District unlock replacement demand from aging Kamaz and GAZ commercial vehicle fleets, with predictive maintenance diagnostic capabilities representing the most penetrable white-space segment for IO-Link integrated pneumatic modules. For Investors and Strategic Acquirers: Heavy-duty commercial vehicle OEMs are the most active acquirer in this space, targeting vertically integrated actuator producers with in-house EAC marking capabilities and established technical service footprints. Acquisition focus centers on domestic assembly operations with backward integration into pneumatic cylinder body forging. Watch for Rosstandart amendments to TR CU 018/2011 certification timelines as the inflection signal for supplier consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Alloy Sourcing | Captive aluminum supply secures cylinder body production against Western metallurgical export restrictions. |
| IO-Link Connectivity Module Licensing | Magnetostrictive position sensing integration enables predictive maintenance revenue streams for fleet operators. |
| In-House GOST-R Testing Laboratory Accreditation | Rosstandart-recognized facilities compress supplier qualification timelines for electropneumatic braking architectures. |
| Authorized Service Network Expansion | Siberian and Far Eastern distributor partnerships capture replacement cycles from aging commercial vehicle fleets. |
| Electropneumatic Braking Platform Standardization | TR CU 018/2011 compliance modules anchor OEM procurement specifications across Kamaz and GAZ production lines. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary field engagement with Tier 1 supplier procurement teams, OEM platform engineers, aftermarket service network managers, and Rosstandart certification specialists with secondary validation against EEU customs union trade data, vehicle production databases, and GOST-R conformity assessment registries. Bottom-up segment sizing triangulated against top-down macroeconomic anchors.
Segment-weighting across product type, end user, installation configuration, and technology tiers informed volume and value projections over the analysis window. CAGRs derived from regression analysis of historical procurement patterns and regulatory implementation schedules. Forecast inputs incorporated TR CU 018/2011 certification adoption curves and import substitution directive compliance trajectories specific to pneumatic braking and steering component sourcing.
Revisions become necessary when Rosstandart enforcement intensity shifts, Western metallurgical supply access changes, or electromechanical actuator substitution accelerates beyond modeled penetration rates in passenger vehicle powertrain architectures. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Braking Component Market
Automotive Components
Automotive Active Suspension System Market
Automotive Components
Automotive Active Grille Shutter Actuator Gear Market
Automotive Components
Automotive Defroster Market
Automotive Components
Global Automotive Thermal Management Market
Automotive Components
Automotive Stabilizer Bar Link Market
Automotive Components
Automotive Aftermarket for Brake Components Market
Automotive Components
Automotive Fender Market
Automotive Components
Africa and Middle East Automotive Actuators Market
Automotive Components
Japan Automotive Electric Actuators Market
Automotive Components
Europe Automotive Bearing Market
Automotive Components
Automotive Pressure Plate Market
Automotive Components
Automotive Carbon Brake Rotor Market
Automotive Components
China Automotive Actuators Market
Automotive Components
France Automotive Market
Automotive Components
Active Suspension Damper Actuator Systems Market