
 Electric Passenger Cars Market | 2026-2036
Electric Passenger Cars Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Passenger Cars Market Intelligence
Lithium iron phosphate is rebalancing cell economics across entry-level and mid-range electric passenger cars as nickel and cobalt price exposure diminishes. Tesla leverages its in-house 4680 cell program to sustain vertical integration advantages across North American production. BYD Company Ltd. anchors its cost position through proprietary blade battery manufacturing and dominant domestic market share in China. Volkswagen AG competes with its unified MEB platform, extending scalable architecture across multiple brands and price tiers.
Electric passenger cars are road vehicles propelled exclusively or primarily by electric motors, with energy stored in rechargeable battery packs typically ranging from 40 kWh to over 100 kWh in capacity, designed for personal transportation with zero tailpipe emissions. Battery Electric Vehicles dominate volume shipments as manufacturing scale and charging infrastructure maturity converge, while Plug-in Hybrid Electric Vehicles retain structural importance in markets with intermittent grid reliability or apartment-dwelling populations. DC Fast Charging infrastructure expansion is concentrating investment flows, though AC Charging persists as the dominant residential and workplace modality due to lower installation costs and adequate overnight dwell times.
The EPA tailpipe standards and California Air Resources Board mandates in the United States, alongside the EU Green Deal vehicle CO2 targets and F-Gas Regulation refrigerant constraints in Europe, are tightening compliance pathways and reshaping product planning cycles. China's MIIT new energy vehicle credit system and dual carbon goals enforce domestic production quotas that manufacturers must navigate for market access. Stakeholders must monitor battery raw material supply agreements and regional subsidy phase-out schedules to calibrate capacity commitments against demand volatility.
Market Dynamics
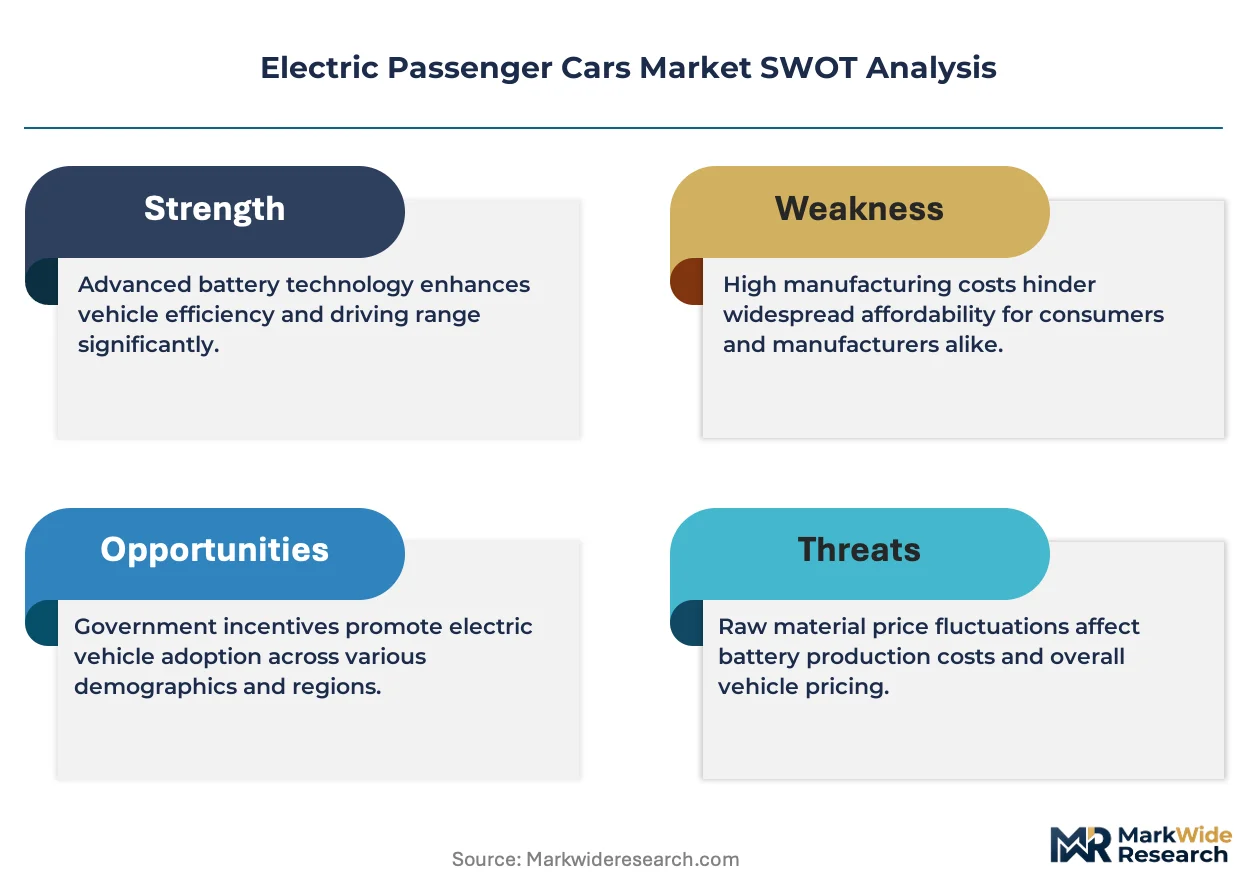
Cell chemistry migration from nickel-cobalt-manganese to lithium iron phosphate is compressing battery pack costs and redrawing supplier hierarchies across mass-market segments.
Growth Catalysts
- US EPA tailpipe standards:Manufacturers face tightening fleet-average emissions requirements through 2032, forcing accelerated battery electric vehicle rollout timelines.
- Fleet operator procurement:Total cost of ownership advantages now favor battery electric vehicles for high-utilization commercial and rental fleets.
- China MIIT credit system:Domestic production quotas enforce minimum new energy vehicle ratios, sustaining manufacturing scale and cost reduction curves.
Market Restraints
- Lithium carbonate price volatility:Concentrated South American and Australian supply creates input cost instability for cathode active material producers.
- Charging infrastructure gaps:Rural and apartment-dwelling populations in Germany and the United States lack reliable residential charging access.
- Grid capacity constraints:Distribution network limitations in California and Bavaria restrict DC fast charging deployment density.
Strategic Opportunities
- India PLI scheme:Production-linked incentives for advanced chemistry cell manufacturing attract investment for domestic battery supply chains.
- Bidirectional charging integration:Vehicle-to-grid capability convergence with home energy storage creates new revenue streams for residential customers.
- Subscription mobility models:Battery-as-a-service and flexible leasing channels reduce upfront purchase barriers for price-sensitive urban buyers.
Industry Challenges
- High-voltage systems engineering talent:Shortages of power electronics and thermal management specialists delay platform development cycles.
- Homologation timeline compression:Simultaneous EU F-Gas refrigerant compliance and UN R100 battery safety certification strain validation resources.
- Semiconductor supply reconfiguration:Silicon carbide inverter sourcing requires multi-year capacity commitments amid automotive demand competition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Passenger Cars Market |
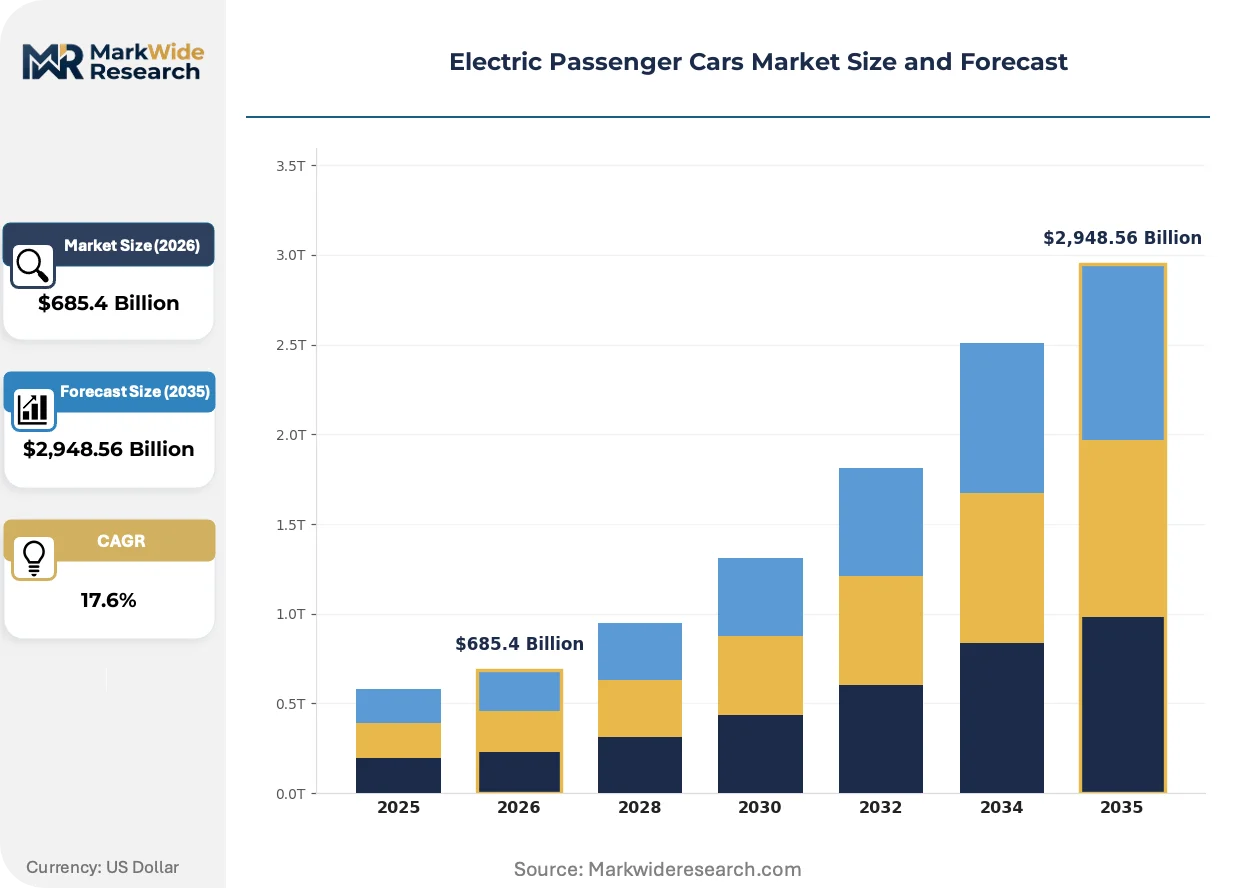
| Market Size in 2026 | $685.4 Billion |
| Market Size in 2035 | $2,948.56 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Battery Electric Vehicles, Plug-in Hybrid Electric Vehicles, Fuel Cell Electric Vehicles, Extended Range Electric Vehicles Charging Technology: AC Charging, DC Fast Charging, Wireless Charging, Solar Charging Consumer Segment: Individual Consumers, Fleets, Ride-Sharing Services, Rental Services Battery Type: Lithium-ion, Solid State, Nickel-Metal Hydride, Lead Acid |
| Companies Covered | Tesla, BYD Company Ltd., Volkswagen AG, Ford Motor Company, General Motors Company, Nissan Motor Company, SAIC Motor Corporation Limited, Toyota Motor Corporation, Daimler AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Passenger Cars Market Strategic Shifts & Innovations
Battery manufacturing automation and chemistry standardization are compressing production costs while regulatory frameworks accelerate electrification mandates across major automotive markets.
Cell-to-pack architecture is automating assembly steps previously requiring module-level handling. Automakers in China and Germany are adopting this structural integration for their mid-range platforms. The technology is automating labor-intensive manufacturing stages and reducing pack-level part counts by eliminating redundant housings and interconnects.
The EU F-Gas Regulation is phasing down hydrofluorocarbon refrigerants with high global warming potential in vehicle climate systems. This mandate forces redesign of thermal management circuits and adoption of CO2-based heat pumps. Premium electric passenger cars face the steepest compliance timeline, with manufacturers accelerating R744 system validation programs.
Fleet procurement departments are consolidating purchase decisions through direct manufacturer relationships rather than traditional dealer networks. Rental and corporate buyers in the United States and Germany negotiate volume contracts with guaranteed residual values and bundled charging infrastructure. This channel compression concentrates pricing power with large-volume purchasers and reduces margin capture for retail-focused distribution.
Electric Passenger Cars Market Segmentation
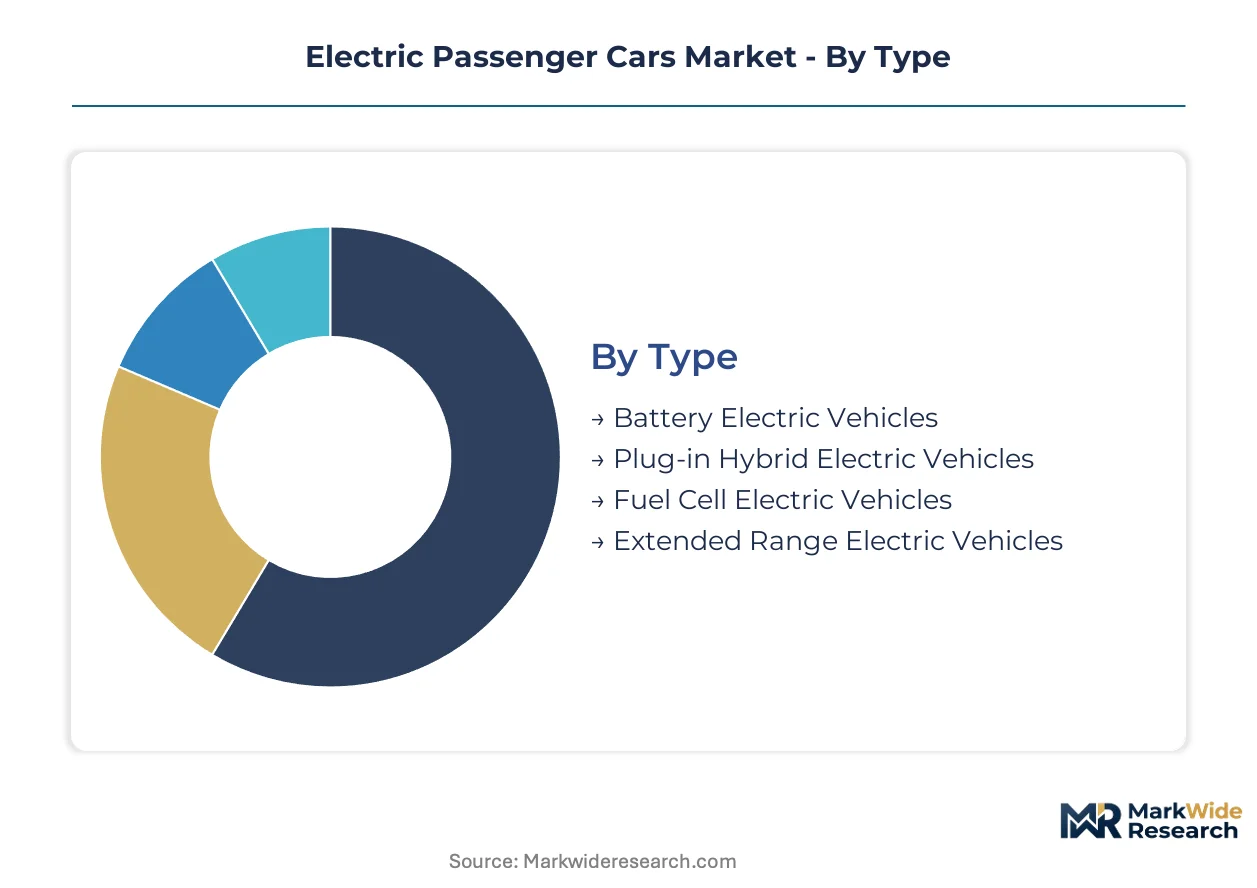
Segmentation in electric passenger cars reveals how capital deployment, infrastructure requirements, and customer economics diverge across propulsion architectures and charging modalities. Manufacturers calibrate platform investments against distinct total cost of ownership profiles and regional regulatory incentives.
Type:
Battery Electric Vehicles demand the highest upfront capital intensity for dedicated skateboard platforms and gigascale battery cell manufacturing, while Plug-in Hybrid Electric Vehicles leverage existing internal combustion engine supply chains with lower retooling requirements.
- Battery Electric Vehicles:Fully electric drivetrains with 40-100+ kWh battery packs eliminate tailpipe emissions entirely. Demand concentrates in China, Germany, and California where charging infrastructure density and purchase subsidies align most favorably, though rural access gaps and apartment-dwelling populations constrain penetration in segments lacking residential charging.
- Plug-in Hybrid Electric Vehicles:Dual powertrain systems combine electric motors with combustion engines for 30-80 km electric-only range. Fleet operators in Germany and the United States favor this architecture where DC fast charging networks remain sparse and route flexibility matters, though tightening EPA and EU CO2 standards compress the compliance window for partial electrification.
- Fuel Cell Electric Vehicles:Hydrogen fuel cell stacks generate electricity onboard with 5-minute refueling times. Japan and South Korea anchor demand through METI and MFDS-supported hydrogen station networks, though capital costs for platinum catalysts and gaseous storage tanks limit mass-market viability.
- Extended Range Electric Vehicles:Series-hybrid configuration uses combustion engines exclusively as generators. China's MIIT credit system classification nuances and domestic range anxiety drive niche positioning, though efficiency penalties versus pure battery electric designs erode cost competitiveness.
Most installed capacity flows through Battery Electric Vehicles. Expansion is steepest in Plug-in Hybrid Electric Vehicles.
Charging Technology:
Charging modality segmentation reflects divergent infrastructure capital requirements and dwell-time economics across residential, commercial, and public deployment contexts.
- AC Charging:Alternating current Level 1 and Level 2 systems deliver 2-19 kW through standard electrical infrastructure. Workplace and residential installations in Germany and the United States dominate volume due to lower capital requirements and adequate overnight dwell times, though power limitations extend charging sessions to 8-12 hours for full replenishment.
- DC Fast Charging:Direct current systems deliver 50-350 kW through dedicated high-voltage infrastructure. Highway corridor deployment in California and Bavaria concentrates investment flows as OEMs and utilities address range anxiety, though distribution grid capacity constraints and demand charges compress station economics in less dense regions.
- Wireless Charging:Inductive pad systems enable automated power transfer without cable handling. Premium fleet applications in urban China pilot dynamic charging integration, though coil alignment precision and efficiency losses limit widespread adoption.
- Solar Charging:Photovoltaic-integrated systems supplement grid electricity with onboard or stationary generation. Experimental deployments in sunbelt regions demonstrate viability for low-utilization vehicles, though surface area constraints and intermittent insolation restrict practical range extension.
AC Charging captures the largest installed base. DC Fast Charging is climbing the fastest as infrastructure buildout accelerates.
Consumer Segment:
Customer-type segmentation exposes divergent procurement behaviors, utilization patterns, and residual value risk allocation between individual and institutional buyers.
- Individual Consumers:Private households purchase through retail channels with financing or lease structures. Range anxiety and charging access limitations in apartment-dwelling populations across Germany and the United States constrain adoption, though total cost of ownership advantages in high-mileage households accelerate conversion.
- Fleets:Corporate and government vehicle pools with centralized procurement and predictable duty cycles. High-utilization commercial operators in North America and Europe leverage battery electric vehicles for total cost of ownership advantages, negotiating direct manufacturer relationships with guaranteed residual values.
- Ride-Sharing Services:Platform-mediated mobility providers with intensive urban utilization patterns. Megacity deployment in China and India prioritizes vehicles with rapid DC fast charging compatibility and durable battery warranties, though driver earnings compression limits acceptable acquisition price points.
- Rental Services:Short-term vehicle providers with dispersed utilization and uncertain customer charging behaviors. Airport and urban locations in the United States and Germany experiment with battery electric vehicle integration, though infrastructure inconsistency and customer education burdens complicate fleet turnover.
Fleets absorb the highest volume of new capacity. Ride-Sharing Services are gaining share fastest as platform economics mature.
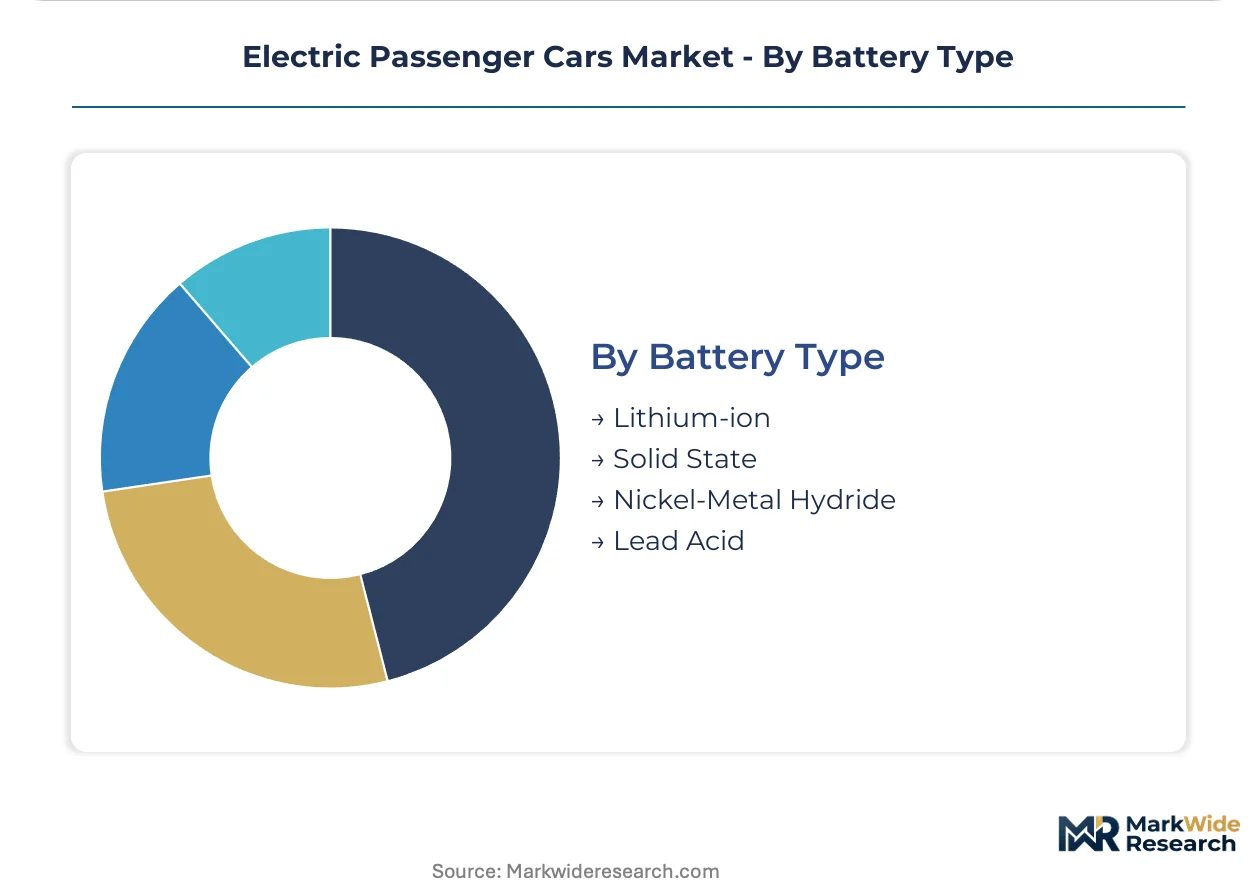
Battery Type:
Cell chemistry segmentation tracks material cost structures, energy density tradeoffs, and supply chain concentration risks across cathode and anode formulations.
- Lithium-ion:Dominant rechargeable chemistry with layered oxide cathodes and graphite anodes in cylindrical, prismatic, or pouch formats. Nickel-cobalt-manganese and lithium iron phosphate variants split the market across premium and mass-market applications, with South American and Australian lithium carbonate supply concentration creating input cost volatility.
- Solid State:Ceramic or polymer electrolytes replace liquid organic solvents for enhanced safety and energy density. Toyota and Samsung SDI pilot production timelines target premium electric passenger cars, though manufacturing scale-up challenges and interface stability problems delay cost parity.
- Nickel-Metal Hydride:Mature chemistry with lower energy density but proven durability in hybrid applications. Toyota Prius legacy demand and secondary use in grid storage sustain niche production, though lithium-ion cost reduction has displaced most automotive applications.
- Lead Acid:Flooded or absorbed glass mat designs for auxiliary power and low-speed electric vehicles. Regulatory phase-out in China and Europe under MEE and REACH restrictions confines remaining demand to aftermarket replacement and industrial applications.
Lithium-ion commands virtually all installed capacity. Solid State is expanding most quickly as validation timelines compress.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta anchors manufacturing capacity for battery electric vehicles, with gigascale cell plants and integrated vehicle assembly concentrating in Shanghai, Suzhou, and Ningbo. Cell chemistry migration and charging infrastructure density are redrawing competitive positioning across national markets.
United States
Fleet operators in California and Texas accelerate procurement of battery electric vehicles as total cost of ownership advantages materialize for high-utilization commercial pools. EPA tailpipe standards through 2032 force accelerated rollout timelines across manufacturer portfolios. Detroit-Warren-Dearborn and Silicon Valley clusters concentrate engineering talent for power electronics and autonomous integration.
Germany
Bavaria and North Rhine-Westphalia host concentrated battery pack assembly and vehicle manufacturing for European export markets. EU Green Deal vehicle CO2 targets and F-Gas Regulation refrigerant constraints tighten compliance pathways and compress product planning cycles. Stuttgart and Wolfsburg engineering centers drive platform standardization across multiple brands.
China
MIIT new energy vehicle credit system enforces domestic production quotas that sustain manufacturing scale and cost reduction curves. Shenzhen and Shanghai metropolitan clusters dominate both cell production and vehicle assembly, with BYD and CATL anchoring supply chains. Dual carbon goals reinforce policy support for electrification through 2035.
Japan
METI-supported hydrogen station networks sustain niche demand for fuel cell electric vehicles despite battery electric vehicle cost compression. Toyota City and Nagoya industrial corridors concentrate hybrid and solid-state battery development programs. JIS standards and PMDA safety frameworks shape validation timelines for next-generation chemistries.
South Korea
MFDS regulatory alignment and METI-equivalent industrial policy support battery cell manufacturing scale-up for export markets. Seoul Capital Area and Busan-Ulsan clusters host Samsung SDI and LG Energy Solution production facilities. Domestic automakers leverage vertical integration advantages in cathode active material supply.
Electric Passenger Cars Market Key Industry Players
Global majors compete with regional champions across platform architecture and cell chemistry integration. The vendor base stratifies into three tiers: integrated cell-and-vehicle manufacturers, platform licensers with multi-brand scale, and regional assemblers with protected domestic share. Dominant competitive moves include capacity expansion in lithium iron phosphate cell production and strategic partnerships for DC fast charging network access.
Within the integrated manufacturing tier, Tesla exemplifies vertical control over cell design and vehicle assembly, while BYD Company Ltd. anchors cost positioning through proprietary battery architectures. Volkswagen AG occupies a platform-licenser position, extending scalable MEB architecture across multiple brands and price tiers. These three represent distinct strategic archetypes: captive supply chain control, domestic market dominance with export expansion, and modular platform economics.
| Leading Market Players |
|---|
| Tesla |
| BYD Company Ltd. |
| Volkswagen AG |
| Ford Motor Company |
| General Motors Company |
| Nissan Motor Company |
| SAIC Motor Corporation Limited |
| Toyota Motor Corporation |
| Daimler AG |
| Others |
Cost & Logistics Intelligence
Fleet operator consolidation in North America and Europe is compressing dealer margins and forcing manufacturers toward direct sales models with transparent pricing. This buyer concentration shifts pricing power toward volume purchasers and accelerates cost transparency across battery pack and charging infrastructure bundles.
Pricing Analysis
Input-cost pass-through from lithium carbonate and nickel sulfate volatility is compressing cathode active material economics and forcing cell manufacturers toward fixed-price offtake contracts. Three-tier pricing structure across premium, standard, and economy levels separates vehicles with 100+ kWh nickel-cobalt-manganese packs from 60-80 kWh lithium iron phosphate configurations and entry-level city cars. Pricing pressure stems from BYD and CATL capacity expansion in China. Fleet buyers exhibit highest price sensitivity due to total cost of ownership modeling, while individual consumers in premium segments show greater tolerance for brand premiums.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Los Angeles, and Shanghai anchor hub-and-spoke patterns for battery cell and module logistics. Manufacturing concentrates in China, South Korea, and Germany for cathode active materials, cell assembly, and pack integration. The supply chain draws from Australian spodumene, Chilean brine, and Indonesian nickel for raw material feedstocks. Single-source vulnerability around Chinese graphite anode production creates structural risk exposure. Distribution runs through captive OEM logistics networks and third-party battery specialists serving multi-brand aftermarket demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electric passenger cars represent a late-cycle quality story as fleet procurement departments prioritize vehicle uptime guarantees and residual value protection over sticker price minimization.
For Market Incumbents: Lock in lithium iron phosphate cell supply through multi-year offtake agreements with CATL and BYD to defend against cathode material cost volatility. Secure DC fast charging network access partnerships in California and Bavaria where grid capacity constraints limit independent station deployment. Reinforce platform standardization across brand portfolios to amortize high-voltage systems engineering costs. For New Entrants and Emerging Players: Solid-state battery pilot production creates a technology-first wedge for premium electric passenger cars targeting Toyota and Samsung SDI validation timelines. Target ride-sharing fleet operators in Indian megacities where PLI scheme subsidies reduce cell import duties and local assembly requirements remain nascent. Pursue battery-as-a-service subscription models to bypass upfront capital barriers among apartment-dwelling urban buyers. For Investors and Strategic Acquirers: Asymmetric upside sits with integrated cell-and-vehicle manufacturers possessing captive cathode active material supply and dominant domestic market share. Long-term viability favors archetypes with demonstrated manufacturing scale and regulatory compliance track records across EPA, EU Green Deal, and MIIT frameworks. Monitor lithium iron phosphate capacity utilization rates as the inflection indicator for cathode chemistry migration speed.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Volkswagen's MEB architecture reduces per-vehicle engineering costs across Audi, Skoda, and Seat brands. |
| Battery Supply Agreement | Tesla's 4680 cell program secures captive supply for Cybertruck and Semi production ramp in Texas. |
| Software-Defined Vehicle Investment | Over-the-air update capabilities create recurring revenue streams and reduce warranty recall costs. |
| Geographic Manufacturing Footprint | BYD's Hungarian assembly plant circumvents EU import tariffs and accelerates European fleet sales. |
| Charging Infrastructure Partnership | Ford's NACS adapter program grants Supercharger network access and reduces range anxiety for F-150 Lightning buyers. |
Research Approach
Bottom-up fleet procurement modeling reconciled against top-down cell production tracking forms the analytical core of this study. Primary interviews with OEM platform engineers, Tier 1 battery procurement leads, fleet operations directors, and charging infrastructure developers informed demand assumptions. Secondary validation drew from EPA certification filings, EU vehicle CO2 compliance databases, MIIT new energy vehicle production statistics, and IHS Markit registration data. Cross-referencing manufacturer production announcements with cathode active material import records enabled supply-side triangulation.
Input-output matrices connect vehicle segment demand to battery cell chemistry requirements, pack capacity configurations, and regional production capacity across the projection horizon. Segmentation dimensions span propulsion architecture, charging modality, consumer type, and battery chemistry tier. CAGRs derive from regression analysis of historical production volumes against regulatory mandate trajectories and infrastructure deployment curves. Forecast inputs incorporate lithium carbonate price elasticity, grid capacity expansion timelines, and fleet turnover cycle assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to battery raw material supply agreements, regional subsidy phase-out schedules, and semiconductor availability for power electronics. Outputs reflect documented assumptions around regulatory compliance timelines and technology cost reduction curves. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
France Solar E-Bike Market
Electric Vehicles
Global Golf Cart and Neighborhood Electric Vehicle (NEV) Market
Electric Vehicles
Middle-East and Africa E-Bike Market
Electric Vehicles
Asia-Pacific Lithium-Ion Battery for Electric Vehicle Market
Electric Vehicles
Middle East Wireless EV Charging Market
Electric Vehicles
Russia Electric Cars Market
Electric Vehicles
Europe Electric Truck Market
Electric Vehicles
Embedded System for Electric Vehicle Market
Electric Vehicles
Luxury Electric Vehicle Market
Electric Vehicles
BEV Electric Drive Unit Market
Electric Vehicles
Electric Vehicle Air Conditioning Market
Electric Vehicles
Off-Highway Electric Machine Battery Pack Systems Market
Electric Vehicles
E-Bike Accessories Market
Electric Vehicles
ASEAN Electric Vehicle Market
Electric Vehicles
Electric Delivery Vans Market
Electric Vehicles
Latin America Automotive High Performance Electric Vehicle Market