
 Japan Automotive Electric Actuators Market | 2026-2036
Japan Automotive Electric Actuators Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Automotive Electric Actuators Market Foresight
Buyer concentration among Japanese OEMs is repositioning procurement leverage toward tier-1 suppliers capable of integrated electromechanical modules. Denso Corporation leverages its captive supply relationships with Toyota to dominate powertrain actuator sourcing. Mitsubishi Electric Corporation sustains R&D intensity in precision motor controls for steering applications. Nidec Corporation anchors volume production through its brushless DC motor expertise serving multiple domestic vehicle platforms.
Automotive electric actuators are electromechanical devices that convert electrical energy into precise mechanical motion, typically operating at voltages from 12V to 48V with position feedback resolution below 0.1 degrees for closed-loop control in vehicle subsystems. These devices manage throttle position, gear selection, braking force distribution, and climate control flap orientation across powertrain and chassis domains. Linear actuators lead volume demand in transmission and brake applications where precise axial displacement governs system response. Rotary actuators command margin concentration in steering systems requiring torque output exceeding 50 Nm with fault-tolerant architectures. Electromechanical technology displaces hydraulic alternatives as OEMs pursue weight reduction and energy recuperation targets.
METI vehicle efficiency standards and JIS quality certifications shape product validation requirements for domestic suppliers seeking OEM qualification. PMDA-aligned functional safety protocols and ISO 26262 automotive safety integrity levels govern actuator software and hardware development cycles for steering and brake applications. Stakeholders must monitor how Japan's revised carbon-neutrality timeline for transport electrification redirects actuator specification priorities across hybrid and fully electric platforms.
Market Dynamics
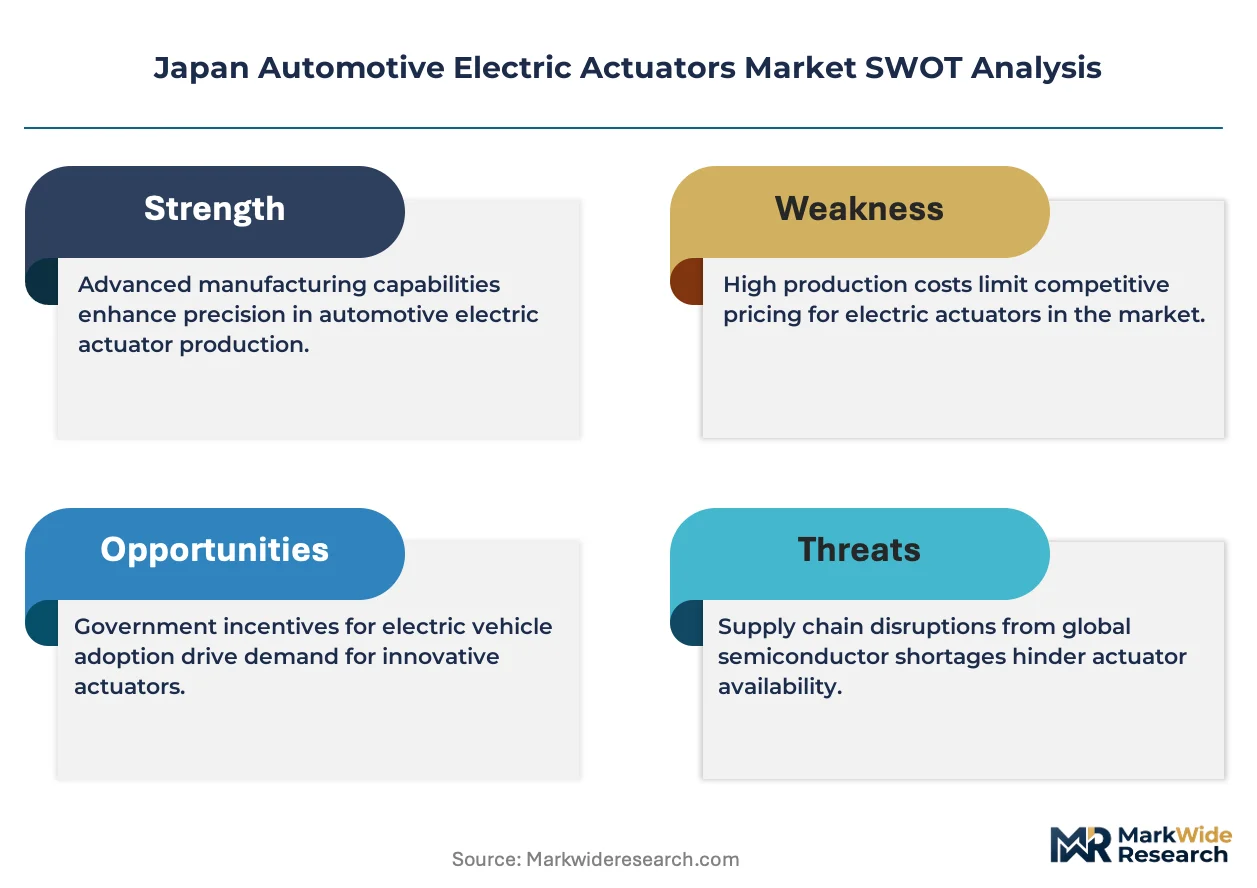
Electrified powertrain proliferation is compressing actuator specification cycles as METI efficiency mandates force simultaneous weight reduction and precision gains across hybrid and battery-electric vehicle programs.
Growth Catalysts
- METI Carbon-Neutrality Roadmaps:Japan's transport decarbonization timeline tightens vehicle efficiency requirements, forcing OEMs to source higher-precision electromechanical actuators for powertrain optimization.
- 48V Mild-Hybrid Architectures:Voltage platform upgrades expand addressable actuator applications across transmission and thermal management systems in domestic vehicle programs.
- Kanto Manufacturing Corridor Concentration:Tier-1 supplier clustering around Tokyo-Yokohama industrial zones reduces logistics friction and accelerates prototype-to-production cycles for electrified platforms.
Market Restraints
- Rare Earth Magnet Cost Volatility:Neodymium and dysprosium price swings embedded in brushless DC motor supply chains compress margin predictability for high-torque rotary actuator production.
- Single-Source Dependency:Precision motor control firmware development concentrates among three domestic electronics houses, creating qualification bottlenecks for new tier-2 entrants.
- Hydraulic System Incumbency:Heavy commercial vehicle braking and steering architectures retain fluid-power actuation due to established service infrastructure and technician familiarity.
Strategic Opportunities
- Kyushu Semiconductor Ecosystem:TSMC's Kumamoto fabrication complex and adjacent packaging facilities enable localized power electronics integration for next-generation smart actuators.
- ISO 26262 ASIL-D Certification Gaps:Fewer than five domestic suppliers currently qualify for highest automotive safety integrity levels in steer-by-wire applications, creating white space for qualified entrants.
- Vehicle-to-Grid Bidirectional Charging:Grid-interactive battery-electric platforms require novel actuator-controlled charge port mechanisms and thermal regulation flaps absent from legacy vehicle designs.
Industry Challenges
- Embedded Software Talent Scarcity:Functional safety firmware development for closed-loop position control requires rare combinations of automotive systems engineering and motor control algorithm expertise.
- JIS Certification Timeline Compression:Revised quality certification protocols for electromechanical components extend validation cycles by eight to fourteen months, delaying platform launch schedules.
- Legacy Powertrain Integration Complexity:Electrified actuator modules must maintain backward compatibility with internal combustion engine architectures during hybrid transition periods, multiplying variant management overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Automotive Electric Actuators Market |
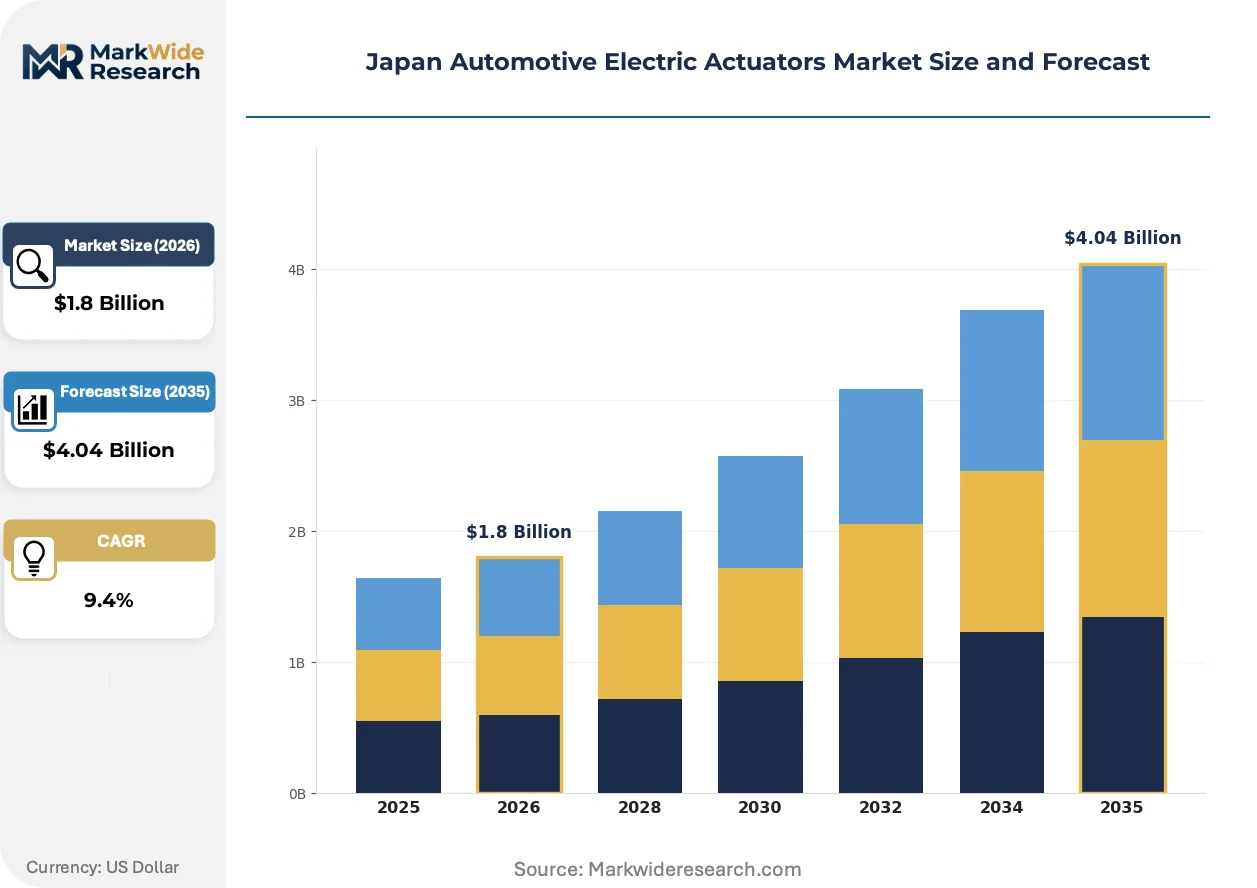
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Linear Actuators, Rotary Actuators, Multi-turn Actuators, Actuator Systems Application: Steering Systems, Transmission Systems, Brake Systems, HVAC Systems End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Technology: Electromechanical, Piezoelectric, Pneumatic, Hydraulic |
| Companies Covered | Denso Corporation, Mitsubishi Electric Corporation, Nidec Corporation, Hitachi Ltd, Continental AG, Robert Bosch GmbH, BorgWarner Inc, Aptiv Plc, Johnson Electric Holdings Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Automotive Electric Actuators Market Shifts & Advancements
Sensor fusion architectures and model-based control algorithms are collapsing the boundary between mechanical actuation and predictive vehicle dynamics, forcing suppliers to reconstitute their engineering competencies around software-defined motion systems.
Integrated torque and position sensing is automating closed-loop calibration procedures that previously required manual technician intervention during vehicle assembly. Toyota and Honda manufacturing plants in Aichi and Saitama prefectures are deploying these self-calibrating actuator modules across transmission and steering subassemblies. This capability is compressing final assembly line cycle times while reducing warranty exposure from misaligned mechanical linkages.
METI's revised vehicle efficiency standards are mandating regenerative braking energy recuperation rates that exceed hydraulic actuator response bandwidth. Domestic OEM procurement teams are rewriting brake-by-wire specifications to require sub-100-millisecond pedal-to-pad latency, disqualifying legacy pneumatic and hydraulic alternatives. Kansai-based tier-1 suppliers are reallocating R&D budgets toward electromechanical brake actuators with redundant motor windings and failsafe mechanical decoupling.
Platform-level sourcing consolidation is concentrating actuator procurement decisions at vehicle program directors rather than subsystem engineers. Tier-1 suppliers in Japan are responding with module-level proposals that bundle motor, controller, gearbox, and position feedback into single part numbers, displacing component-level vendor fragmentation. This pattern is most visible in hybrid powertrain programs where transmission actuator, clutch actuator, and parking lock actuator originate from common supplier engineering teams.
Japan Automotive Electric Actuators Market Segmentation
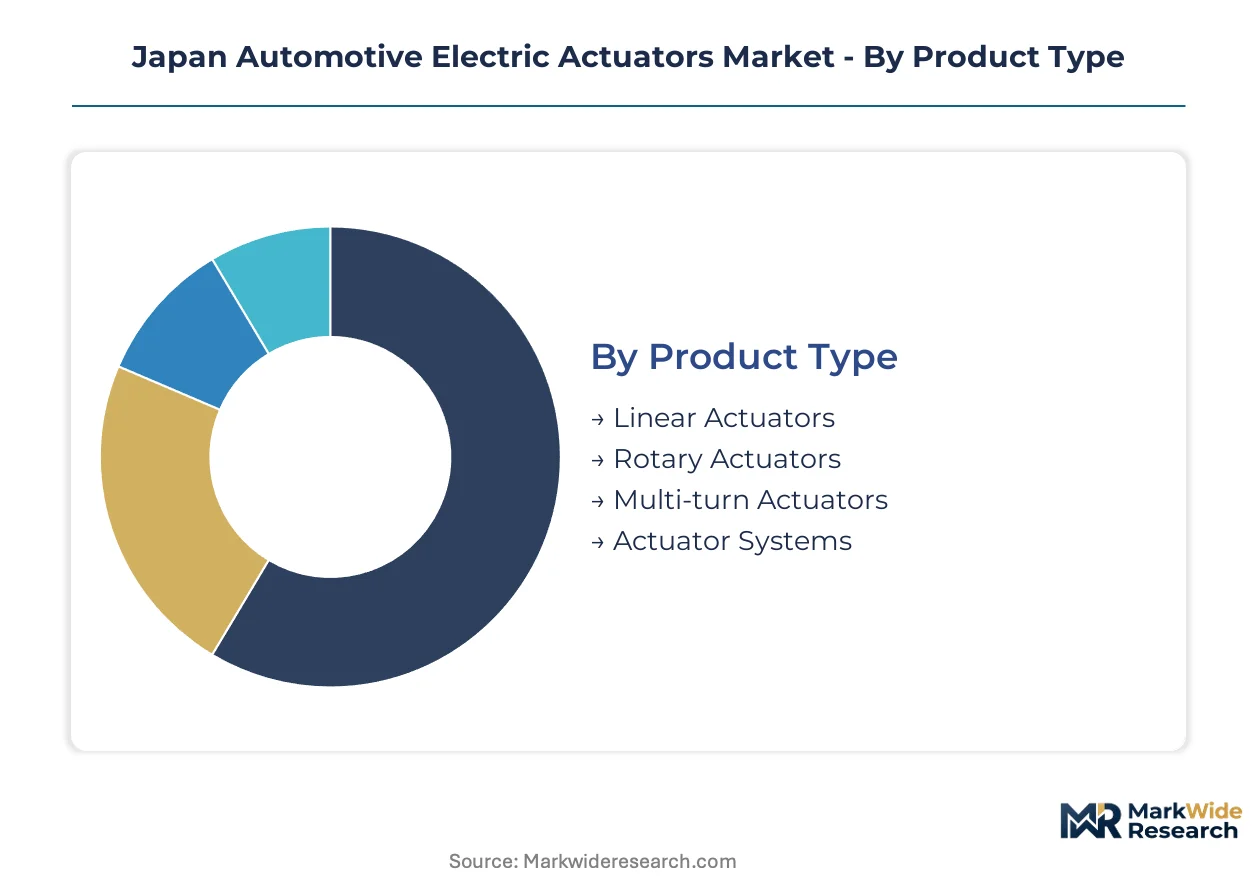
Actuator procurement patterns in Japan diverge sharply between high-volume commodity positions and precision-critical premium applications. Understanding these segment boundaries clarifies where tier-1 suppliers defend margin versus where cost engineering dominates sourcing decisions.
Product Type:
Volume concentration sits with standardized motion platforms, while premium capture flows to integrated electromechanical systems with embedded position intelligence.
- Linear Actuators:These devices generate precise axial displacement through ball-screw or belt-drive mechanisms, typically achieving positioning accuracy below 0.05mm. Demand concentrates in transmission and brake applications across Kanto-based vehicle assembly plants, where METI efficiency mandates force simultaneous weight reduction and shift-speed improvement.
- Rotary Actuators:Torque output exceeding 50 Nm with fault-tolerant dual-winding architectures defines this category. Steering system procurement in Aichi and Saitama prefectures absorbs the majority of domestic volume, driven by steer-by-wire roadmaps that disqualify hydraulic alternatives under revised safety protocols.
- Multi-turn Actuators:Extended rotation range mechanisms serve throttle body and variable valve timing applications with 720-degree+ travel capability.
- Actuator Systems:Integrated modules combining motor, controller, gearbox, and feedback sensors into single part-number sourcing bundles.
Today's leader: Linear Actuators. Tomorrow's challenger: Actuator Systems.
Application:
Powertrain electrification is rewriting which vehicle domains absorb actuator R&D investment and qualification resources.
- Steering Systems:Electromechanical power steering racks and steer-by-wire columns require ASIL-D functional safety certification under ISO 26262 protocols. Kansai-based tier-1 suppliers dominate qualification for these torque-critical positions where pedal-to-response latency targets compress below 100 milliseconds.
- Brake Systems:Brake-by-wire actuators with redundant motor windings and mechanical decoupling mechanisms displace hydraulic architectures. Procurement teams at domestic OEMs specify sub-100-millisecond latency to meet METI regenerative braking energy recuperation mandates that exceed legacy hydraulic response bandwidth.
- Transmission Systems:Clutch, shift, and parking lock actuators manage gear engagement across hybrid and battery-electric powertrain variants.
- HVAC Systems:Climate control flap orientation and thermal management valve actuation operate at lower torque and safety integrity requirements.
Steering Systems currently command premium positioning. Brake Systems are climbing the fastest as electrification timelines accelerate.
End User:
Procurement leverage concentrates differently across the supply chain hierarchy, with platform-level decisions increasingly overriding subsystem engineering preferences.
- OEMs:Toyota, Honda, and Nissan vehicle program directors now consolidate actuator sourcing decisions at platform level rather than delegating to transmission or chassis engineering teams. This shift favors module-level suppliers capable of bundling multiple actuator functions under single part numbers.
- Tier-1 Suppliers:Denso, Mitsubishi Electric, and Nidec anchor domestic supply through captive relationships and R&D intensity in precision motor controls.
- Vehicle Assemblers:Contract manufacturing arrangements for export markets and regional production platforms.
- Aftermarket Providers:Replacement actuator demand for legacy vehicle fleets and collision repair channels.
Today's anchor: OEMs. Tomorrow's pivot point: Tier-1 Suppliers.
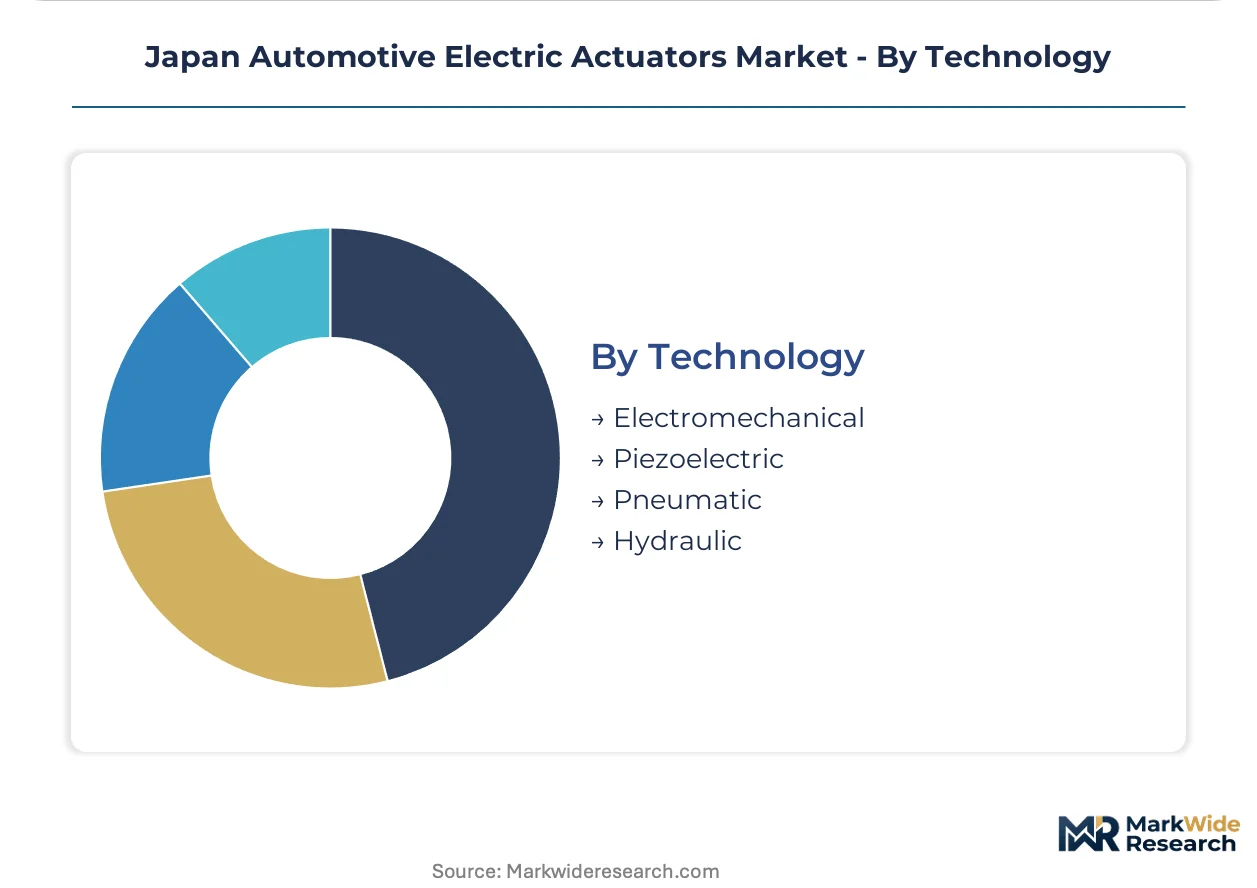
Technology:
Electrification roadmaps are collapsing the viable technology set, with electromechanical platforms displacing fluid-power alternatives across safety-critical domains.
- Electromechanical:Brushless DC motor architectures with integrated position feedback dominate new platform development. Nidec's volume production expertise and Denso's Toyota captive supply relationships anchor domestic manufacturing capacity for these 12V to 48V operating voltage platforms.
- Piezoelectric:Ultra-precise micro-positioning for fuel injection and optical alignment applications leverages ceramic actuator elements with nanometer-scale resolution.
- Pneumatic:Compressed-air actuation retains niche presence in heavy commercial vehicle auxiliary systems.
- Hydraulic:Fluid-power architectures persist in heavy truck braking and steering where service infrastructure and technician familiarity create switching costs.
Electromechanical holds dominant share. Piezoelectric shows steepest expansion trajectory in precision-critical niches.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's precision manufacturing workforce concentrates in three industrial corridors where tier-1 actuator suppliers maintain captive engineering relationships with domestic OEMs.
Kanto
Tokyo-Yokohama manufacturing clusters absorb the majority of linear actuator demand for transmission and brake applications. METI vehicle efficiency mandates force simultaneous weight reduction and shift-speed improvement across hybrid platforms. Denso Corporation anchors powertrain actuator production in this corridor through its Toyota captive supply relationship.
Kansai
Osaka-Kyoto industrial zones concentrate rotary actuator R&D for steer-by-wire and electromechanical braking systems. JIS quality certification protocols and ISO 26262 ASIL-D functional safety requirements govern supplier qualification timelines. Mitsubishi Electric Corporation sustains precision motor control development for steering applications from this region.
Chubu
Aichi and Gifu prefectures host Toyota and Honda vehicle assembly plants deploying self-calibrating actuator modules across transmission and steering subassemblies. Integrated torque and position sensing capabilities compress final assembly line cycle times. Tier-1 suppliers locate module-level engineering teams adjacent to these OEM facilities.
Kyushu
Kumamoto and Fukuoka prefectures leverage TSMC's semiconductor fabrication complex for localized power electronics integration. Smart actuator development benefits from adjacent packaging facilities and reduced logistics friction for next-generation motor controllers. This ecosystem enables faster prototype-to-production cycles for 48V mild-hybrid platforms.
Japan Automotive Electric Actuators Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across three distinct tiers. Captive supply relationships between tier-1 suppliers and domestic OEMs create high barriers to entry for foreign entrants. Three strategic archetypes dominate: integrated electromechanical module suppliers, precision motor control specialists, and volume-scale brushless DC motor producers. Competitive moves concentrate on backward integration into rare earth magnet supply chains and strategic partnerships with semiconductor foundries.
Within the integrated module supplier tier, Denso Corporation and Mitsubishi Electric Corporation exemplify archetypes built on captive OEM relationships and R&D intensity in precision controls. Nidec Corporation anchors the volume-production segment through brushless DC motor expertise. Continental AG and Robert Bosch GmbH represent German-based multinationals competing on global platform standardization. BorgWarner Inc and Aptiv Plc occupy positions as technology-agnostic tier-1 suppliers capable of cross-regional qualification.
| Leading Market Players |
|---|
| Denso Corporation |
| Mitsubishi Electric Corporation |
| Nidec Corporation |
| Hitachi Ltd |
| Continental AG |
| Robert Bosch GmbH |
| BorgWarner Inc |
| Aptiv Plc |
| Johnson Electric Holdings Limited |
| Others |
Supply & Pricing Matrix
Captive supply relationships between tier-1 suppliers and Japanese OEMs anchor both manufacturing position and pricing power across the automotive electric actuator value chain. Denso's Toyota-exclusive arrangements and Nidec's multi-platform volume contracts create divergent margin structures that resist standardization.
Pricing Analysis
Capacity additions in Kyushu's semiconductor corridor are reshaping price floors for smart actuator modules with integrated motor controllers. Pricing stratifies across ASIL-D certified premium tiers, standard JIS-qualified mid-tier, and economy non-safety-critical positions. Cost compression in rotary steering actuators is intensifying because rare earth magnet volatility feeds directly into brushless DC motor bill-of-materials. Fleet procurement teams at commercial vehicle divisions show highest price sensitivity, while steer-by-wire program directors absorb premium positioning for fault-tolerant architectures.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Toyota, Honda, and Nissan platform directors who consolidate multi-actuator sourcing decisions. Manufacturing concentration in Japan, China, and South Korea feeds the regional supply base, with neodymium magnets, silicon steel laminations, and automotive-grade MCUs as critical inputs. Single-source vulnerability around precision motor control firmware creates qualification bottlenecks for new tier-2 entrants. Distribution runs through tier-1 system integrators who bundle motor, gearbox, and controller into module-level part numbers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's automotive electric actuator market represents a late-cycle quality story as METI carbon-neutrality mandates force OEM procurement toward ASIL-D certified precision modules over commodity electromechanical alternatives.
For Market Incumbents: Anticipate margin compression from 48V mild-hybrid platform standardization by deepening backward integration into rare earth magnet supply chains and securing TSMC Kumamoto allocation for next-generation motor controllers. Denso and Mitsubishi Electric should accelerate ISO 26262 ASIL-D certification timelines to defend against German multinational encroachment in steer-by-wire applications. For New Entrants and Emerging Players: Sensor fusion architectures with embedded torque and position sensing offer a technology-first wedge into self-calibrating actuator modules where incumbent firmware development cycles lag. Target Kyushu-based engineering partnerships with semiconductor packaging facilities as the most penetrable geographic entry point, then qualify through tier-1 module suppliers rather than direct OEM engagement. For Investors and Strategic Acquirers: Roll-up economics work for precision motor control specialists because JIS certification timelines and captive OEM relationships create defensible moats that resist pure-play disruption. Focus acquisition screening on tier-2 suppliers with ASIL-D qualification gaps and existing relationships with Aichi or Saitama assembly plant proximity. Watch for inflection when METI revises transport electrification timelines to accelerate brake-by-wire procurement specifications.| Strategic Initiative | Industry Significance |
|---|---|
| ASIL-D Certification Investment | Opens steer-by-wire procurement at Toyota and Honda platform programs. |
| Rare Earth Magnet Backward Integration | Reduces neodymium cost volatility exposure in high-torque rotary actuator production. |
| TSMC Kumamoto Partnership | Enables localized power electronics integration for 48V mild-hybrid smart actuators. |
| Self-Calibrating Module Development | Compresses final assembly cycle times at Aichi and Saitama vehicle plants. |
| Platform-Level Sourcing Consolidation | Bundles transmission, brake, and steering actuators under single tier-1 part numbers. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with tier-1 supplier procurement directors, OEM platform engineers, aftermarket distributors, and JIS certification auditors alongside secondary validation. Sources included METI regulatory filings, JIS standards documentation, vehicle production databases, and tier-1 supplier technical disclosures. Bottom-up actuator shipment modeling and top-down vehicle platform content analysis provided triangulation across the analysis window.
Historical reference periods anchored volume and value projections across the modeling period, with segmentation dimensions spanning product type, application domain, propulsion architecture, and regional production cluster. CAGRs derived from regression analysis against vehicle platform launch schedules and METI efficiency mandate implementation phases. Forecast inputs incorporated hybrid powertrain penetration curves and steer-by-wire technology adoption timelines specific to Japanese OEM roadmaps.
The model holds under stable METI regulatory implementation and consistent rare earth supply availability; deviation in carbon-neutrality timeline acceleration or neodymium export restrictions would shift platform electrification assumptions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Filters Market
Automotive Components
Automotive Tie Rod Market
Automotive Components
Automotive Front-End Module (FEM) Market
Automotive Components
Automotive Active Bonnet Market
Automotive Components
Automotive Hardware Market
Automotive Components
Automotive Exhaust Emission Control Device Market
Automotive Components
India Automotive Glass Fiber Composites Market
Automotive Components
Automotive Transaxle Market
Automotive Components
Automotive Exhaust Silencer Market
Automotive Components
Global Automotive Chrome Accessories Market
Automotive Components
Automotive Bushing Technologies Market
Automotive Components
Automotive Connecting Rod Bearing Market
Automotive Components
Global Automotive HUD Market
Automotive Components
Automotive Seat Frame Market
Automotive Components
Europe Automotive Plastics Market
Automotive Components
Automotive Carbon Thermoplastic Market