
 Automotive Straps Market | 2026-2036
Automotive Straps Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Straps Market Analysis
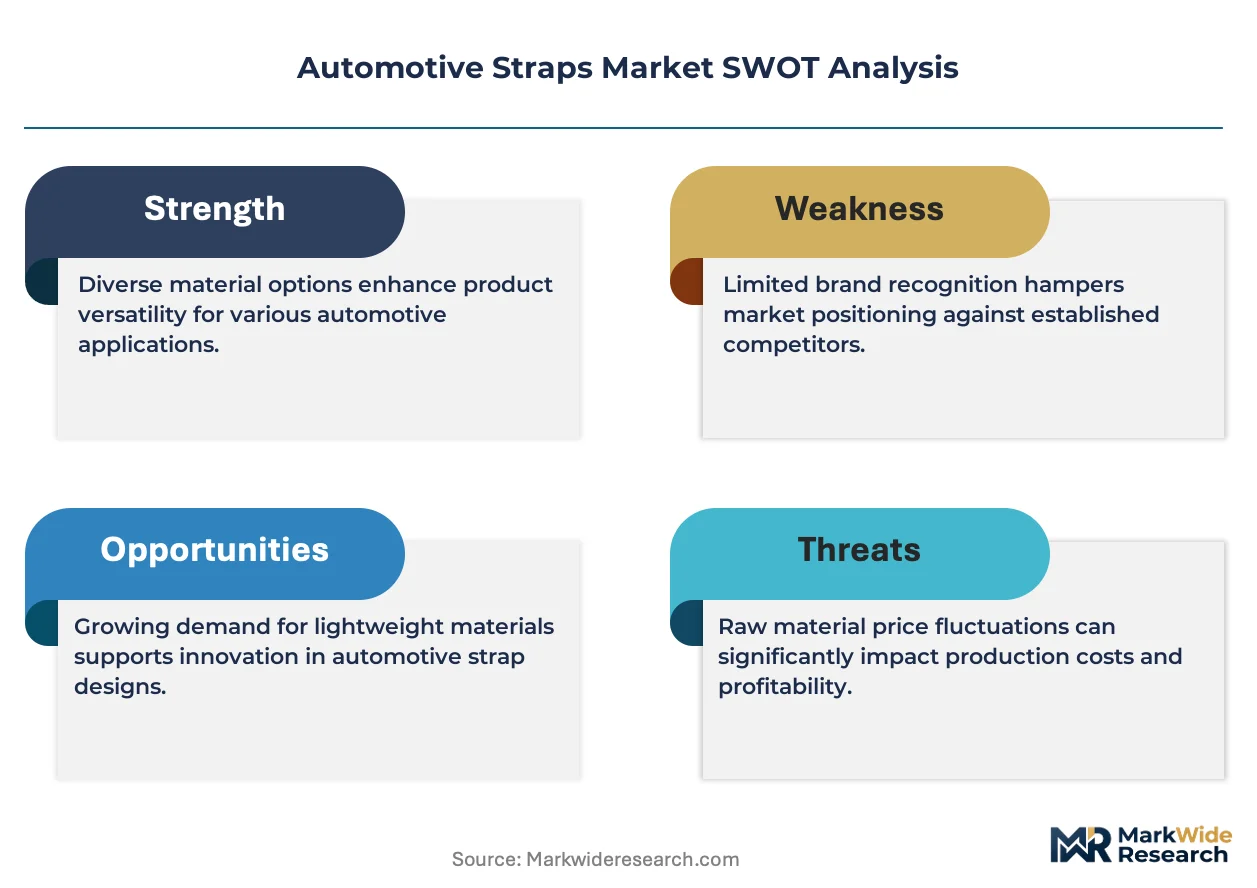
High-tenacity polyester is recalibrating cost-performance tradeoffs across cargo and seat strap categories, displacing conventional nylon in load-critical applications. Erickson Manufacturing Ltd leverages its Canadian manufacturing base to sustain bulk supply contracts with North American fleet operators. Ancra International LLC anchors its position through specialized aerospace-grade webbing technology adapted for heavy-duty automotive cargo restraint. Dolezych GmbH & Co. KG competes on European road-certification depth, controlling access to regulatory-compliant tie-down assemblies for cross-border freight.
Automotive straps are woven textile or synthetic assemblies, typically rated by breaking strength in kilonewtons and elongation percentage, designed to secure occupants, cargo, or equipment against inertial forces during vehicle operation. Seat straps integrate energy-management stitching patterns to control load distribution across the human torso during deceleration events. Cargo straps and tie-down straps represent the largest product type segment, reflecting sustained replacement demand from fleet operators managing DOT inspection cycles. Harness straps exhibit the fastest functionality growth, driven by motorsport safety adoption and premium seating upgrade programs in performance vehicles.
Federal Motor Vehicle Safety Standards in the United States, enforced by NHTSA, dictate webbing flame resistance and dynamic test criteria that filter non-compliant imports from aftermarket channels. The EU's General Safety Regulation and CE marking requirements, administered through type-approval bodies in Germany and France, create divergent compliance pathways that favor regionally certified manufacturers. Stakeholders must monitor material substitution timelines and certification reciprocity agreements to align procurement and production footprints with evolving restraint performance thresholds.
Market Dynamics
The automotive straps market is being fundamentally restructured by the EU's updated General Safety Regulation, which mandates enhanced occupant restraint performance standards and is forcing manufacturers to redesign webbing assemblies for higher dynamic load tolerance.
Growth Catalysts
- EU General Safety Regulation:The mandate for enhanced occupant restraint performance standards across all new vehicle types is accelerating demand for certified high-tenacity polyester webbing in Germany, France, and Italy.
- Electric vehicle lightweighting:EV manufacturers are expanding synthetic restraint adoption to reduce curb weight and extend driving range, creating pull-through demand for advanced cargo and seat strap assemblies.
- German manufacturing corridor concentration:OEM sourcing from tier-one suppliers in Baden-Württemberg and Bavaria is concentrating procurement volumes and stabilizing long-term contract structures.
Market Restraints
- Petrochemical input volatility:High-tenacity polyester and polypropylene feedstock prices fluctuate with crude oil indices, compressing margin predictability for woven textile manufacturers.
- Regional certification fragmentation:Divergent NHTSA FMVSS 302 flame-resistance requirements in the United States versus EU type-approval pathways force dual testing protocols and inventory duplication.
- Nylon displacement limitations:Load-critical applications in heavy-duty cargo restraint retain nylon specifications due to superior abrasion resistance, slowing complete material substitution timelines.
Strategic Opportunities
- India automotive production expansion:Domestic OEM capacity growth and BIS certification alignment with UN ECE regulations create entry pathways for compliant strap suppliers.
- Motorsport harness adoption:Premium performance vehicle seating upgrade programs are absorbing aerospace-derived energy-management stitching technologies at volume scale.
- CE marking reciprocity developments:Emerging mutual recognition agreements between EU type-approval bodies and emerging-market regulators are streamlining cross-border freight equipment certification.
Industry Challenges
- Technical textile engineering talent scarcity:Specialized weaving technicians capable of programming computer-controlled looms for variable-density load distribution patterns command premium wages and limited availability.
- Dynamic testing facility bottlenecks:Sled-test certification backlog at NHTSA-recognized laboratories extends product launch timelines for new webbing formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Straps Market |
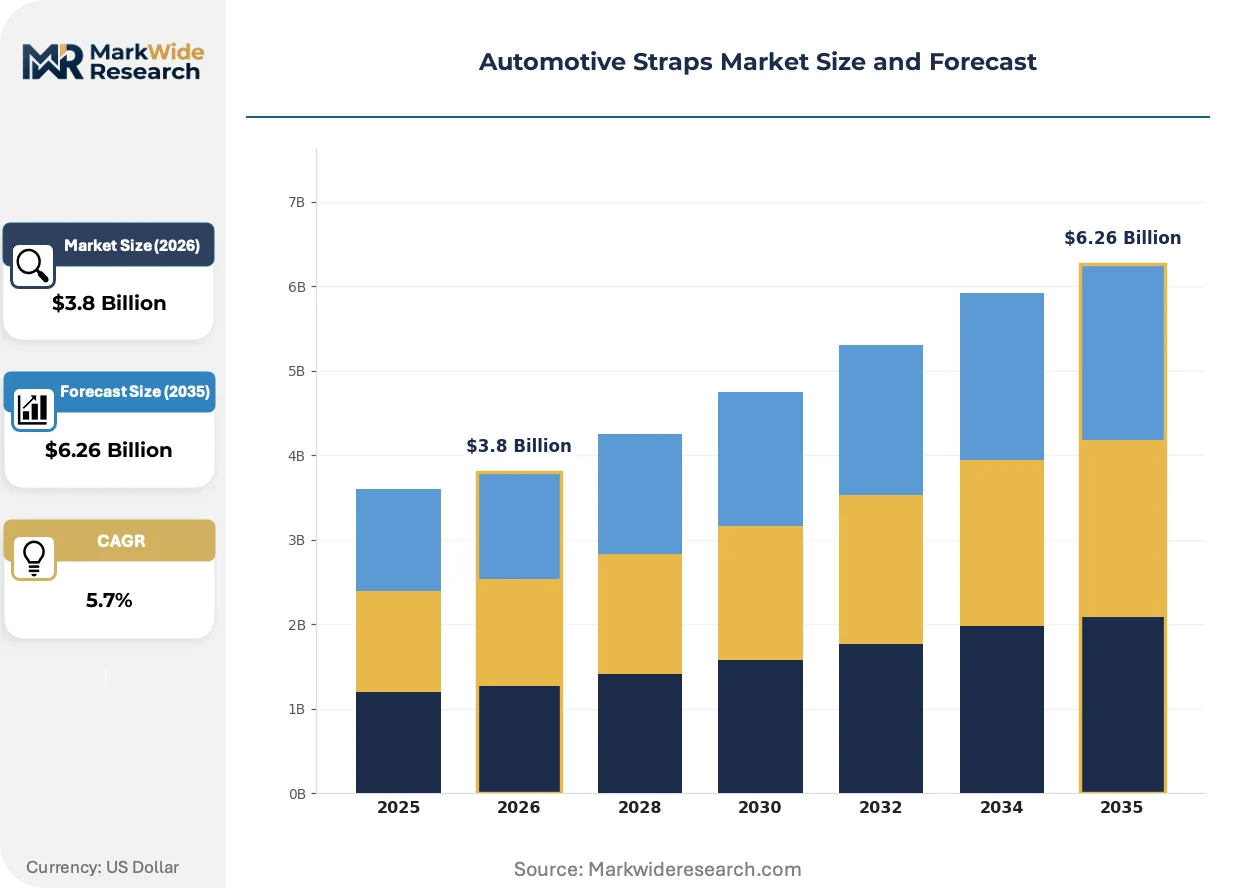
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Seat Straps, Cargo Straps, Harness Straps, Tie-Down Straps Material: Nylon, Polyester, Cotton, Leather End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Fleet Operators Functionality: Securing, Lifting, Towing, Restraining |
| Companies Covered | Erickson Manufacturing Ltd, Hampton Products International Corporation, Ancra International LLC, Dolezych GmbH & Co. KG, Quickloader, Cargo Equipment Corporation, Winston Products LLC, Horizon Global Corporation, Kinedyne LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Straps Market Emerging Trajectories
Active material science breakthroughs and regulatory harmonization pressures are compressing traditional product lifecycles while opening specification windows for next-generation restraint systems.
High-tenacity polyester is electrifying competitive positioning across cargo and seat strap categories by delivering comparable breaking strength to nylon at reduced mass. EV manufacturers in Germany and South Korea are specifying these assemblies for battery-electric platforms where every kilogram of curb weight reduction extends range. The technology is electrifying procurement criteria, forcing incumbent nylon suppliers to defend position through price compression rather than performance differentiation.
REACH chemical compliance requirements are tightening permissible substance thresholds in textile coatings and dyes used for automotive webbing. Manufacturers must reformulate flame-retardant treatments to eliminate restricted halogenated compounds while maintaining NHTSA FMVSS 302 certification. German and French type-approval bodies are enforcing these standards most stringently, filtering non-compliant imports from aftermarket distribution channels.
Fleet operators are consolidating procurement through direct contracts with tier-one strap assemblers rather than aftermarket distributors. Large North American logistics companies now specify breaking strength, elongation percentage, and DOT inspection cycle compatibility in master service agreements. This consolidation is most visible in cross-border freight corridors where uniform equipment standards reduce inspection friction at state and provincial boundaries.
Automotive Straps Market Segmentation
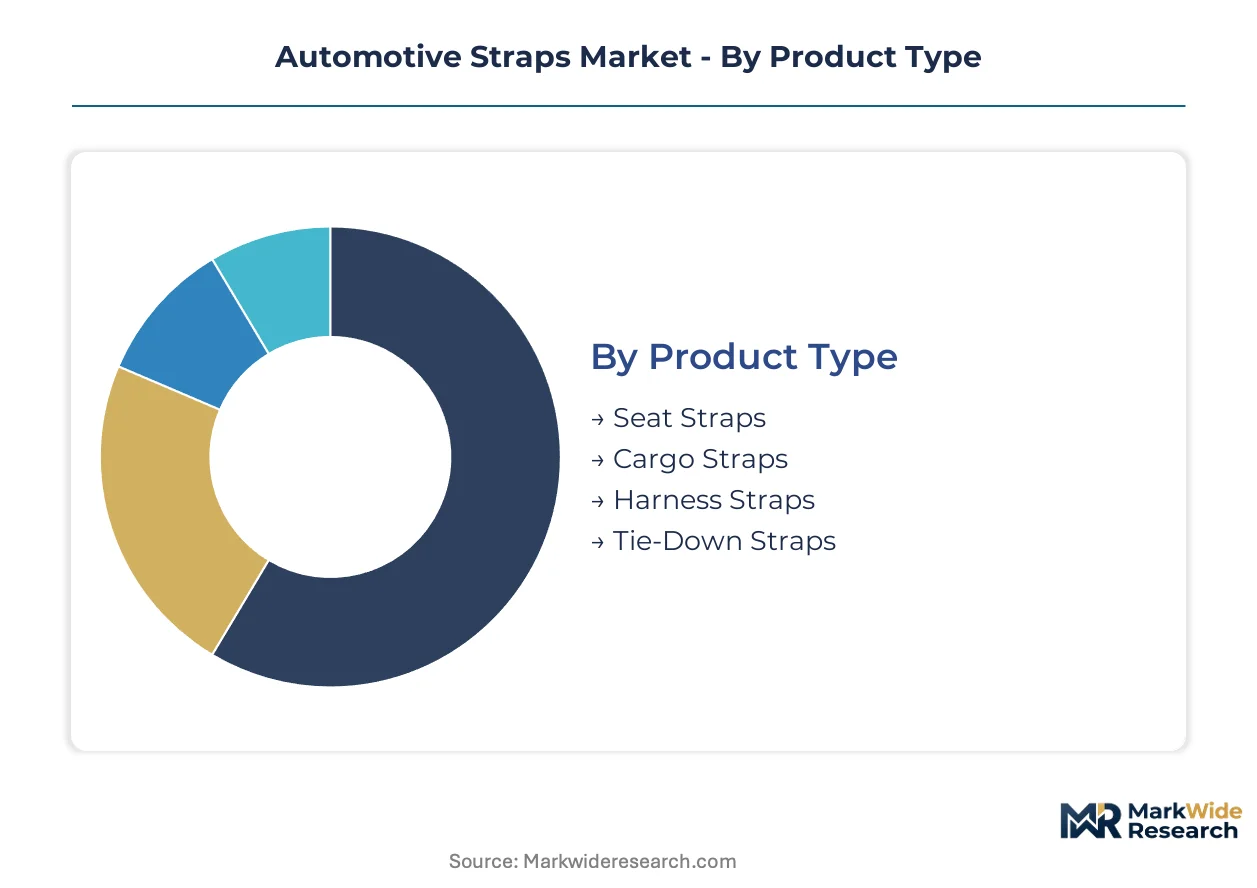
Automotive strap specifications diverge sharply across duty cycles and regulatory exposure. Procurement patterns cluster around load-critical applications where failure carries liability, while commodity segments compete on replacement velocity and inspection compliance.
Product Type:
Capital deployment concentrates in segments requiring dynamic testing infrastructure and certification reciprocity across multiple jurisdictions.
- Cargo Straps:Woven synthetic assemblies rated for breaking strength and elongation percentage, designed to secure freight against inertial forces during transit. Fleet operators in Germany and North America specify these for DOT inspection cycle compatibility, driving sustained replacement demand. Cargo straps absorb the bulk of installed capacity; harness straps are expanding most quickly.
- Seat Straps:Energy-management webbing with controlled stitching patterns that distribute deceleration loads across the human torso. OEMs in Baden-Württemberg source these from tier-one suppliers to meet EU General Safety Regulation performance thresholds.
- Harness Straps:Motorsport-derived restraint systems with aerospace-grade load distribution engineering.
- Tie-Down Straps:Adjustable fastening assemblies for equipment securing and temporary cargo fixation.
Cargo straps absorb the bulk of installed capacity; harness straps are expanding most quickly.
Material:
Feedstock selection determines margin volatility and regulatory compliance pathways simultaneously.
- Polyester:High-tenacity synthetic fiber delivering comparable breaking strength to nylon at reduced mass. EV manufacturers specify polyester assemblies for battery-electric platforms where curb weight reduction extends range.
- Nylon:Superior abrasion resistance retains specification in heavy-duty cargo restraint despite polyester displacement pressure elsewhere.
- Cotton:Natural fiber webbing for vintage vehicle restoration and aesthetic interior applications.
- Leather:Premium hide-based restraints for luxury seating and collector vehicle authenticity requirements.
Nylon retains the largest share of load-critical applications; polyester is climbing the fastest.
End User:
Contract structure and volume predictability separate institutional procurement from fragmented replacement demand.
- Fleet Operators:Large logistics companies consolidate procurement through direct tier-one contracts specifying breaking strength, elongation percentage, and inspection cycle compatibility. North American cross-border freight corridors drive uniform equipment standards.
- OEMs:Vehicle manufacturers source seat and cargo strap assemblies through certified supplier networks in Germany's automotive corridor.
- Aftermarket Providers:Distributors serving replacement demand through retail and installer channels.
- Vehicle Assemblers:Contract manufacturers integrating restraint systems into finished vehicle production.
Fleet operators command the largest contract volumes; OEMs are gaining share fastest.
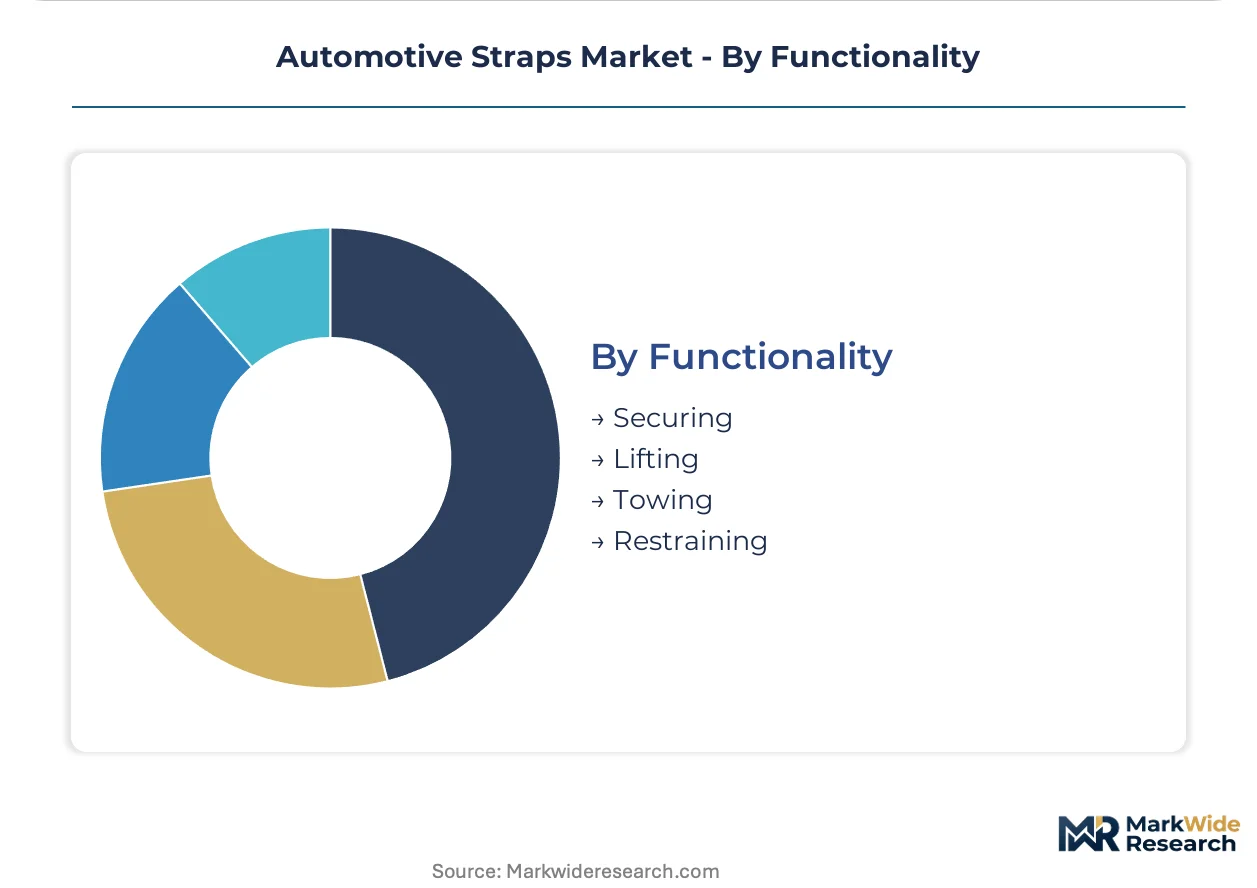
Functionality:
Force application geometry dictates webbing construction and certification testing protocols.
- Restraining:Occupant protection systems managing deceleration energy through controlled webbing elongation. EU type-approval bodies in Germany enforce dynamic performance standards most stringently.
- Securing:Cargo fixation against longitudinal and lateral acceleration forces during vehicle operation.
- Lifting:Vertical load handling applications requiring specialized safety factor engineering.
- Towing:Tensile force transmission for vehicle recovery and trailer connection.
Restraining functionality dominates certification expenditure; securing applications show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Baden-Württemberg's automotive manufacturing corridor concentrates tier-one supplier networks, while Mexico's IMMEX maquiladora zones attract North American strap assembly capacity through tariff-advantaged export structures.
Germany
OEM procurement from tier-one suppliers in Stuttgart and Munich drives certified polyester webbing demand for EU General Safety Regulation compliance. KBA type-approval enforcement filters non-compliant imports from aftermarket channels. Bavarian industrial clusters anchor seat strap assembly contracts for battery-electric platforms.
United States
NHTSA FMVSS 302 flame-resistance standards govern webbing formulations for domestic fleet operators managing DOT inspection cycles. NHTSA sled-test certification backlogs at recognized laboratories extend product launch timelines. Michigan and Ohio automotive corridors concentrate cargo strap sourcing for cross-border freight with Canada.
China
MIIT standards alignment with UN ECE regulations opens export pathways for domestic strap manufacturers serving European OEMs. Dual carbon goals accelerate lightweight synthetic adoption in NEV production. Yangtze River Delta clusters integrate high-tenacity polyester weaving for battery-electric vehicle restraint systems.
Mexico
IMMEX maquiladora programs position Nuevo León and Bajío Region assembly plants for duty-free export to US fleet operators. NHTSA certification reciprocity through USMCA trade structures streamlines cross-border equipment standardization. Querétaro industrial parks host tier-two strap sewing operations for North American OEM supply chains.
India
BIS certification alignment with UN ECE regulations creates entry pathways for compliant suppliers serving Maruti Suzuki and Hyundai domestic production. PLI scheme incentives for automotive component manufacturing attract woven textile investment. Tamil Nadu and Gujarat industrial corridors concentrate seat belt webbing capacity for export-oriented vehicle assembly.
Automotive Straps Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with fleet-direct procurement favoring scale-driven assemblers while OEM channels reward certified tier-one suppliers. The vendor base organizes around three archetypes: integrated textile weavers controlling polymer feedstock to finished webbing, specialized strap assemblers sourcing certified fabric from regional mills, and diversified cargo equipment distributors serving fragmented aftermarket demand. Competitive moves concentrate on backward integration into polymer extrusion capacity and geographic expansion through regulatory reciprocity in emerging production zones.
Among North American fabricators, Erickson Manufacturing Ltd and Winston Products LLC occupy positions within the fleet-direct supply tier, while Dolezych GmbH & Co. KG represents the European regulatory-depth archetype with German type-approval certification control. Ancra International LLC anchors the aerospace-technology adaptation segment, translating specialized webbing engineering from aviation cargo restraint into heavy-duty automotive applications.
| Leading Market Players |
|---|
| Erickson Manufacturing Ltd |
| Hampton Products International Corporation |
| Ancra International LLC |
| Dolezych GmbH & Co. KG |
| Quickloader |
| Cargo Equipment Corporation |
| Winston Products LLC |
| Horizon Global Corporation |
| Kinedyne LLC |
| Others |
Supply Flow & Price Mechanics
Petrochemical feedstock volatility cascades through polyester and polypropylene pricing tiers, with high-tenacity fiber costs compressing margins for woven textile manufacturers serving German OEMs and North American fleet operators. Contract structures bifurcate between long-term offtake agreements anchoring tier-one supplier relationships and spot-market exposure dominating aftermarket channels.
Pricing Analysis
Lead-time premiums reward rapid fulfillment capabilities, with OEMs paying contract premiums for certified polyester webbing delivered within compressed production windows while spot inventory clears at discounted rates through aftermarket distributors. Pricing stratifies across aerospace-grade certification, DOT-compliant fleet specifications, and economy-grade replacement straps. Cost compression in standard-grade cargo straps is intensifying because polyester displacement pressure forces nylon incumbents into price competition. Fleet operators exhibit highest price sensitivity due to bulk procurement scale, while motorsport harness buyers prioritize performance certification over unit cost.
Supply Chain Analysis
Transoceanic freight costs from Asian polymer extrusion centers to European weaving mills and North American assembly plants constitute a material cost layer, with container rate volatility amplifying margin unpredictability for tier-two strap sewers. Supply concentrates in Germany, China, and Mexico, with Baden-Württemberg anchoring high-tenacity polyester weaving, Yangtze River Delta feeding synthetic fiber extrusion, and Nuevo León hosting USMCA-advantaged assembly. Raw material dependencies draw from purified terephthalic acid, monoethylene glycol, and industrial-grade dyes. Single-source vulnerability in aerospace-grade webbing certification creates chokepoint risk. Distribution runs through direct tier-one contracts for OEM volumes and fragmented aftermarket distributors for replacement demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive straps market sits at a material-transition inflection, with high-tenacity polyester displacing nylon across seat and cargo applications as EV manufacturers prioritize curb weight reduction.
For Market Incumbents: Lock in backward integration into polymer extrusion capacity to defend margin position against feedstock volatility, while securing KBA and NHTSA dual-certification infrastructure to filter emerging-market competition from EU and North American procurement channels. For New Entrants and Emerging Players: The mid-tier price gap between aerospace-grade harness straps and economy cargo assemblies offers white-space entry, with BIS-certified suppliers targeting Tamil Nadu and Gujarat automotive corridors for Maruti Suzuki and Hyundai domestic production integration. For Investors and Strategic Acquirers: CE marking reciprocity developments with Indian and Mexican regulators is the leading indicator that certification-arbitrage opportunities are compressing, suggesting five-to-ten-year viability rests on acquiring tier-one suppliers with embedded OEM relationships rather than aftermarket distributors facing consolidation pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Extrusion | Captive PTA and MEG supply insulates German weavers from crude-indexed feedstock swings. |
| Dual-Certification Infrastructure Investment | Parallel KBA and NHTSA testing capacity accelerates product launches across Atlantic corridors. |
| Direct Fleet Procurement Contracts | Master service agreements with North American logistics operators displace aftermarket distributors. |
| Aerospace Technology Adaptation | Aviation-derived energy-management stitching transfers into premium motorsport harness programs. |
| IMMEX Maquiladora Expansion | Nuevo León assembly plants leverage USMCA tariff structures for US fleet operator supply. |
Methodological Framework
Independent corroboration across tier-one supplier procurement officers, OEM platform engineers, aftermarket distributor operations heads, and NHTSA-recognized testing laboratory directors underwrites the qualitative findings. Secondary validation draws from vehicle production databases, IHS Markit registration data, UN ECE type-approval filings, and customs records tracking polyester webbing trade flows. Bottom-up triangulation across component-level bill-of-materials analysis and top-down market sizing through end-use demand aggregation anchors volume estimates.
Historical reference periods spanning pre-pandemic baseline through post-supply-shock recovery establish trajectory anchors across the projection horizon. The analytical framework models segmentation across vehicle class, propulsion architecture, content per vehicle, and regional production cluster. CAGRs derive from regression analysis against automotive production forecasts and material substitution elasticity curves, with EV penetration rates and regulatory compliance timelines as primary forecast inputs.
Underlying measurement precision varies by segment; certified seat strap volumes carry tighter precision than fragmented aftermarket cargo strap replacement cycles. Forecasts reflect assumptions about polymer feedstock cost trajectories and regulatory reciprocity timelines. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive License Plate Light Market
Automotive Components
Automotive Part Cleaners and Degreasers Market
Automotive Components
Global Automotive Condenser Market
Automotive Components
Automotive Sunroof Glass Market
Automotive Components
Automotive Carbon Fiber Composites Parts Market
Automotive Components
Global Automotive Carbon Ceramic Brake Rotors Market
Automotive Components
Global Automotive Sun Visor Market
Automotive Components
Automotive Exhaust Components Aftermarket Market
Automotive Components
Automotive Solenoid Market
Automotive Components
US Automotive Glass Fiber Composites Market
Automotive Components
Global Automotive Composite Market
Automotive Components
Automotive Distributor O Ring Market
Automotive Components
Global Flexible Shaft Couplings Market
Automotive Components
Mexico Automotive Pneumatic Actuators Market
Automotive Components
MEMS Automobile Sensors Market
Automotive Components
Automotive Heater Core Market