
 United States Aftermarket Automotive Parts and Components Market | 2026-2036
United States Aftermarket Automotive Parts and Components Market Size, Share, and Industry Trends Forecast 2026-2036
United States Aftermarket Automotive Parts and Components Market Analytics
Telematics integration into vehicle diagnostics is reconfiguring how fleet managers and independent repair shops source replacement components. AutoZone Inc leverages its extensive store network to sustain same-day parts availability across dense metropolitan corridors. O'Reilly Automotive Inc anchors its competitive stance through professional installer programs that lock in recurring commercial demand. Continental AG differentiates via sensor-rich braking and chassis systems that command premium positioning in the replacement channel.
Aftermarket automotive parts and components encompass replacement and upgrade products manufactured to original equipment specifications or engineered as performance alternatives, typically utilizing stamped steel, aluminum alloys, engineered polymers, and friction materials processed through forging, casting, or injection molding to restore or enhance vehicle function post-original sale. The component dimension reveals electrical parts gaining structural importance as vehicle electronics complexity multiplies repair-event values, while engine parts retain volume leadership due to internal combustion fleet persistence. Sales channel dynamics show online retailers capturing disproportionate growth as digital fitment tools reduce return rates, though wholesalers and distributors still control the bulk flow to professional repair facilities.
NHTSA safety standards govern crash-replacement structural integrity, EPA tailpipe regulations shape catalytic converter and oxygen sensor specifications, and state-level right-to-repair legislation in Massachusetts and expanding jurisdictions mandate diagnostic tool accessibility for independent technicians. These overlapping compliance layers elevate product certification burdens while opening protected market access for certified suppliers. Stakeholders must monitor right-to-repair legislative contagion across additional states and the pace of OEM encrypted systems migration to calibrate channel strategy and inventory investments.
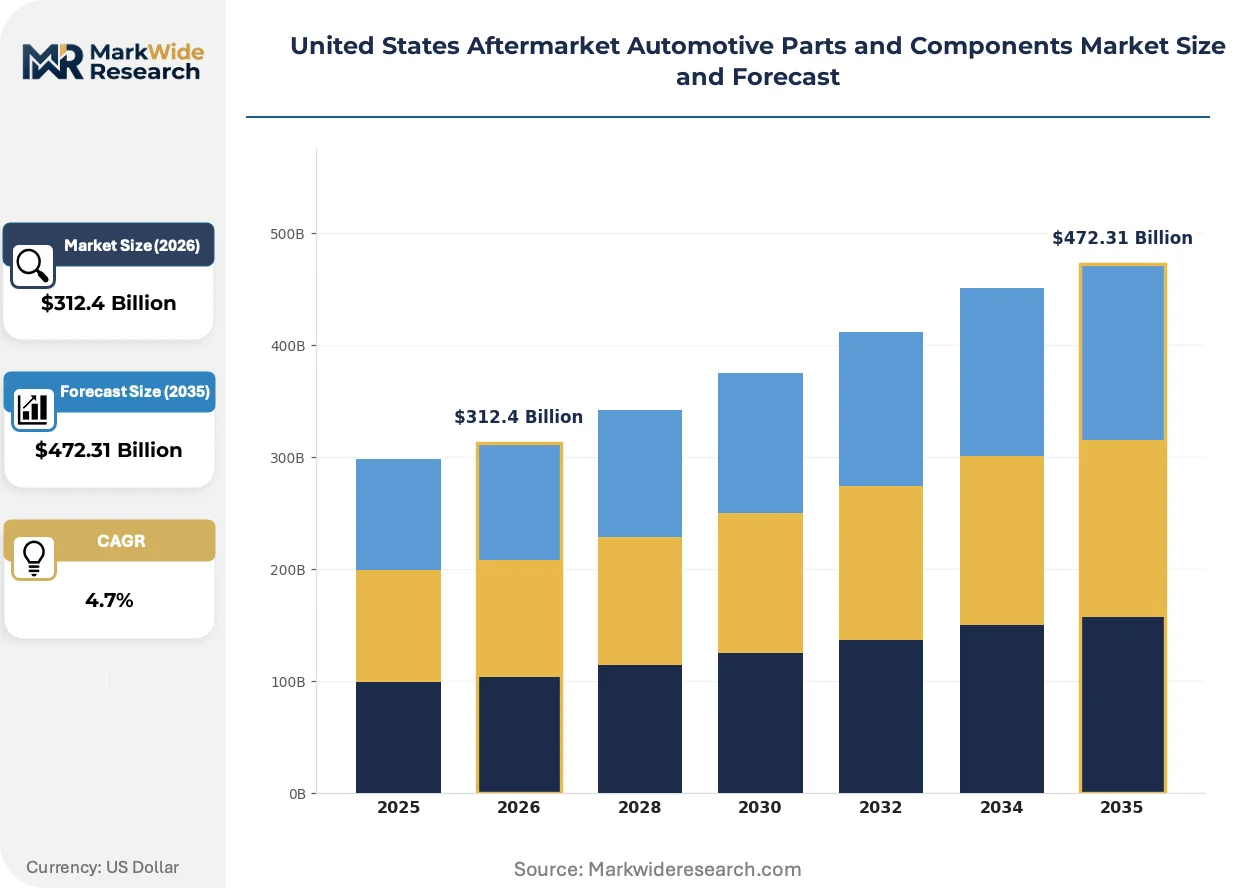
Market Dynamics
Telematics-enabled predictive maintenance is compressing replacement cycles and reordering inventory priorities across the United States aftermarket channel. Fleet operators now anticipate component failures before they occur, shifting procurement from reactive break-fix to scheduled pre-emptive replacement.
Growth Catalysts
- Right-to-repair mandates:Massachusetts legislation and expanding state-level equivalents compel OEMs to release diagnostic protocols, opening encrypted vehicle systems to independent repair shops and expanding addressable demand for replacement parts.
- Sun Belt vehicle aging:Texas, Florida, and Arizona accumulate higher average vehicle mileage than national baselines, concentrating wear-part consumption in corrosion-prone, high-heat operating environments.
- Commercial fleet telematics:Predictive algorithms identify brake, exhaust, and electrical degradation patterns, triggering proactive component orders that smooth demand volatility for distributors serving logistics and delivery operators.
Market Restraints
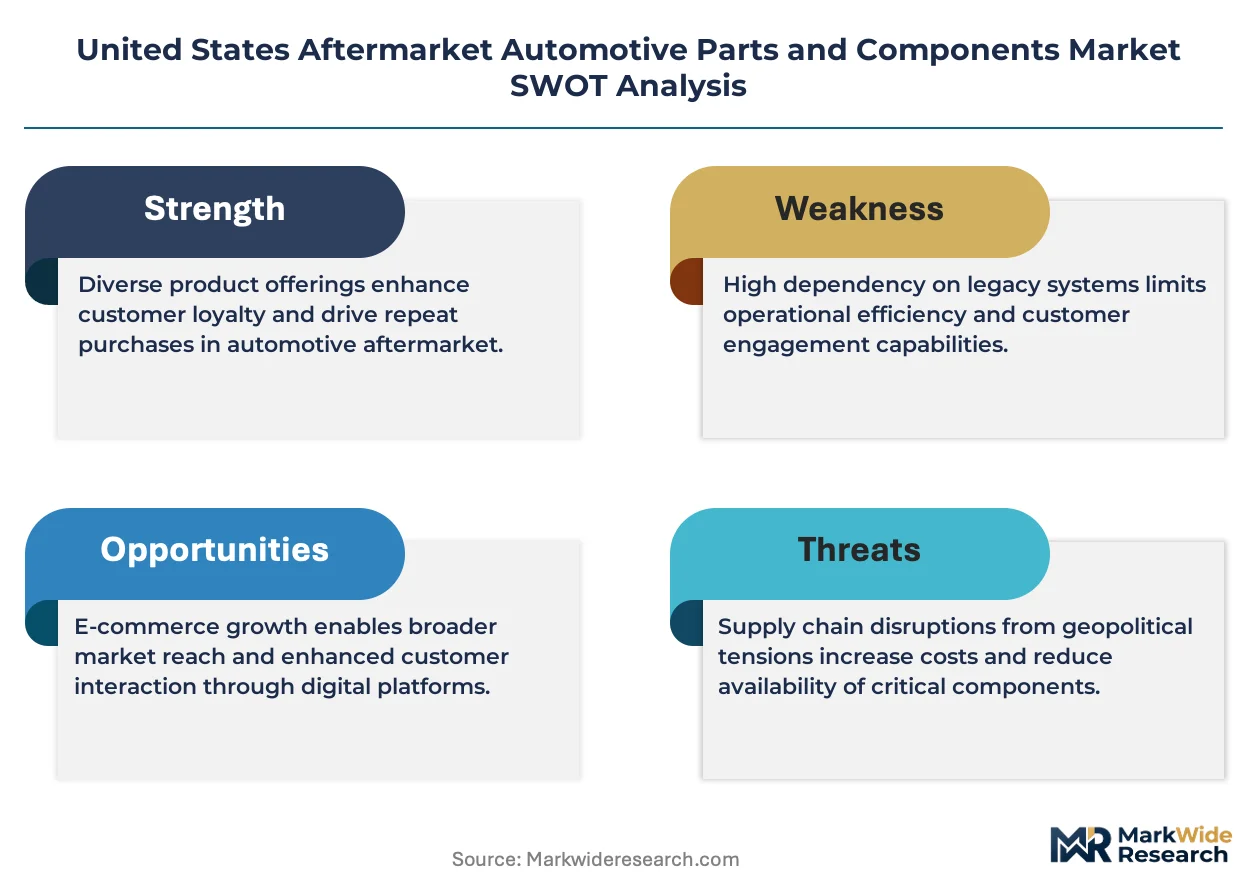
- Aluminum and steel input volatility:Stamped chassis components and forged engine parts face margin pressure from commodity price swings that distributors cannot fully pass through to price-sensitive DIY consumers.
- CARB compliance costs:California Air Resources Board emissions standards for catalytic converters and oxygen sensors impose certification burdens that exclude smaller fabricators from the replacement exhaust channel.
- EV powertrain longevity:Electric vehicle battery and motor systems require fewer wearable replacement parts than internal combustion engines, threatening long-term volume in traditional engine and transmission component categories.
Strategic Opportunities
- Sensor-integrated brake systems:Advanced driver-assistance system proliferation creates replacement demand for wheel-speed sensors, electronic control modules, and actuated calipers that command premium positioning over conventional friction products.
- Direct-to-installer digital platforms:Independent repair shops increasingly bypass traditional two-step distribution, sourcing components through specialized B2B marketplaces that guarantee fitment accuracy and same-day regional fulfillment.
- EPA enforcement tailwinds:Intensified emissions testing and counterfeit parts interdiction protect certified suppliers from gray-market competition, reinforcing legitimate channel volume for verified catalytic converter and sensor manufacturers.
Industry Challenges
- Automotive electronics diagnostics:Repair technicians require continuous training on multiplexed CAN bus architectures and encrypted control module communication, stretching workforce development budgets at independent shops.
- Inventory velocity management:SKU proliferation across hybrid, plug-in, and battery-electric vehicle variants fragments demand signals, forcing distributors to carry broader safety stock without corresponding turnover guarantees.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Aftermarket Automotive Parts and Components Market |
| Market Size in 2026 | $312.4 Billion |
| Market Size in 2035 | $472.31 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Brakes, Filters, Suspensions, Exhaust Systems Component: Body Parts, Electrical Components, Engine Parts, Transmission Parts Sales Channel: Online Retailers, Specialty Stores, Wholesalers, Distributors Vehicle Type: Passenger Cars, Trucks, SUVs, Vans |
| Companies Covered | AutoZone Inc, O'Reilly Automotive Inc, Advance Auto Parts Inc, Magna International Inc, Continental AG, ZF Friedrichshafen AG, DENSO Corporation, Robert Bosch GmbH, Lear Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Aftermarket Automotive Parts and Components Market Evolving Landscape
Connected vehicle data streams are reconfiguring how replacement components are specified, priced, and delivered across the United States aftermarket ecosystem. Three developments dominate the current transformation window.
Artificial intelligence-driven predictive analytics platforms aggregate telematics feeds from commercial fleets to forecast component degradation with mileage-specific precision. Large trucking operators and last-mile delivery services subscribe to these services, receiving automated replacement recommendations that bypass traditional diagnostic delays. This capability is digitizing procurement workflows, compressing the interval between fault detection and parts installation while reducing unscheduled downtime costs.
EPA tailpipe enforcement and California CARB certification requirements are tightening specifications for catalytic converters, diesel particulate filters, and oxygen sensors. Manufacturers must submit extensive emissions durability testing documentation to maintain compliant product listings, elevating barriers to entry for uncertified competitors. The replacement exhaust segment bears the heaviest compliance burden, with distributors increasingly sourcing exclusively from EPA-verified suppliers to avoid liability exposure.
Professional repair shops are consolidating purchasing through specialized digital platforms that integrate VIN-specific fitment databases with real-time inventory visibility. These systems reduce return rates and administrative overhead compared to traditional phone-and-fax ordering with regional warehouses. Shop owners in metropolitan corridors adopt these tools fastest, driven by technician wage pressures that demand maximized billable hour productivity.
United States Aftermarket Automotive Parts and Components Market Segmentation
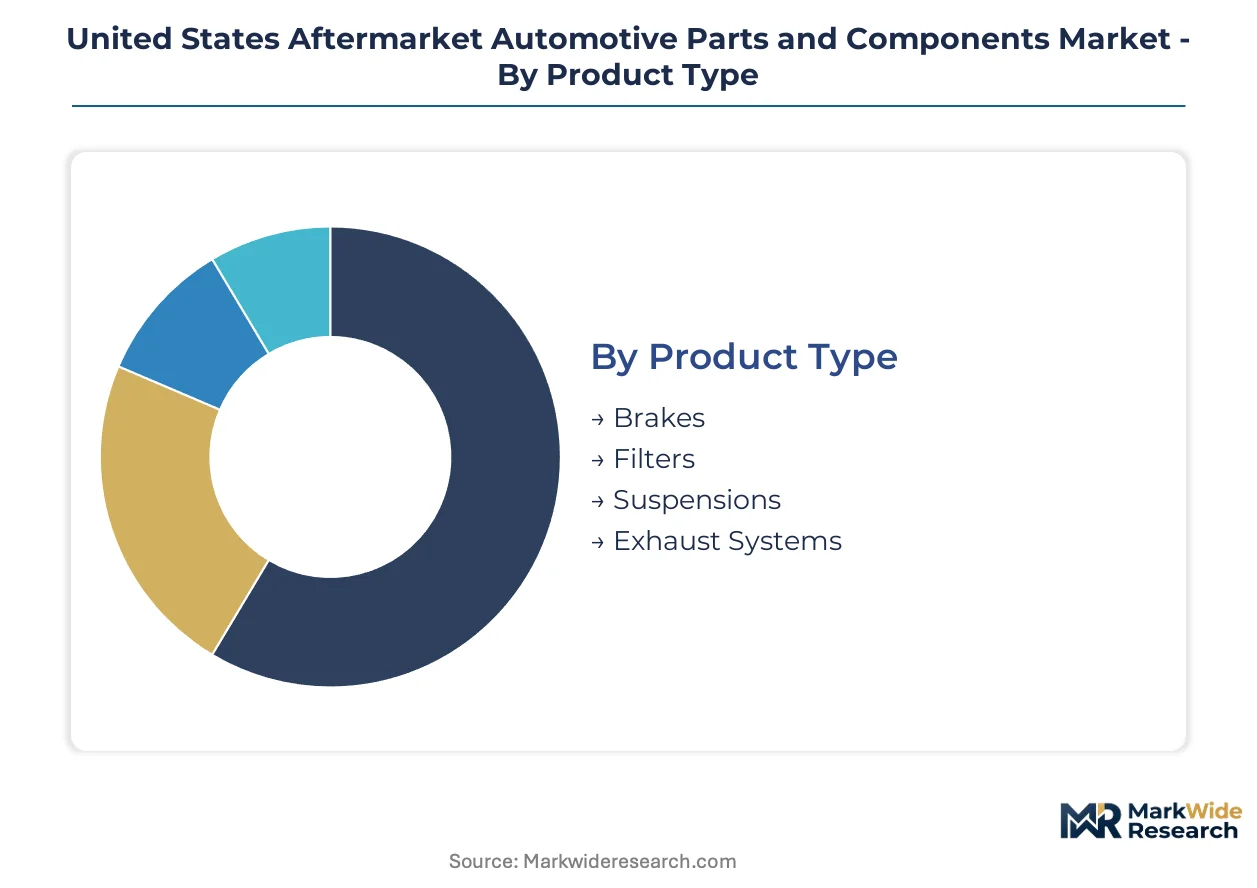
Aftermarket automotive parts and components fragment across multiple intersecting dimensions that dictate inventory velocity, margin structure, and channel access. Understanding these segment boundaries clarifies where procurement cycles compress and where pricing power concentrates.
Product Type:
Brake pads and oil filters turn over fastest due to scheduled maintenance intervals, while exhaust systems and shock absorbers cycle more slowly pending failure events.
- Brakes:Friction materials, rotors, and calipers constitute high-velocity inventory with replacement triggered by mileage-based service schedules. Sun Belt fleet operators in Texas and Arizona drive disproportionate demand as heat and dust accelerate pad degradation.
- Filters:Engine oil, air, and cabin air filters represent predictable recurring revenue with standardized specifications across vehicle platforms. Mass-market retail chains capture the bulk of DIY replacement volume through promotional bundling strategies.
- Suspensions:Shock absorbers, struts, and control arms carry longer replacement cycles tied to road condition exposure.
- Exhaust Systems:Mufflers, catalytic converters, and piping face EPA certification requirements that slow supplier onboarding.
Brakes dominate installed base velocity. Exhaust systems are where EPA enforcement is tightening supplier qualification.
Component:
Margin structure varies sharply across component categories, with electrical modules commanding premium positioning against commodity engine hardware.
- Electrical Components:Sensors, alternators, and starter motors integrate increasingly complex semiconductor content. Massachusetts right-to-repair mandates expand independent shop access to diagnostic protocols, broadening addressable demand for replacement modules.
- Engine Parts:Pistons, gaskets, and timing components retain volume leadership from internal combustion fleet persistence. CARB emissions standards in California shape oxygen sensor and fuel injector specifications.
- Body Parts:Bumpers, fenders, and hoods follow collision repair cycles tied to insurance claim frequency.
- Transmission Parts:Clutch kits, torque converters, and valve bodies serve a shrinking manual transmission installed base.
Engine parts anchor current revenue scale. Electrical components are climbing the fastest as vehicle electronics complexity multiplies per-repair values.
Sales Channel:
Customer type determines channel selection, with professional installers demanding same-day fulfillment that DIY consumers trade for price convenience.
- Wholesalers:Regional distribution warehouses serving independent repair shops with bulk pricing and credit terms. Commercial fleet telematics integration is compressing order-to-delivery windows for brake and exhaust components.
- Online Retailers:Digital platforms with VIN-specific fitment tools reducing return rates below traditional catalog ordering. Metropolitan corridor consumers in Florida and California adopt these channels fastest for price transparency.
- Specialty Stores:Performance-focused retailers catering to enthusiast upgrade demand.
- Distributors:Two-step distribution networks linking manufacturers to installer bays.
Wholesalers control professional installer volume. Online retailers are gaining share fastest as digital fitment accuracy improves.
Vehicle Type:
Operating duty cycles separate light-duty passenger applications from commercial-grade truck and van platforms with accelerated wear patterns.
- Trucks:Heavy-duty brake, suspension, and drivetrain components face accelerated replacement from towing and payload stress. Texas and Arizona commercial operators accumulate annual mileage multiples above national passenger car averages.
- SUVs:All-wheel-drive systems and larger brake packages command premium component pricing. Sun Belt family vehicle concentrations sustain steady filter and tire replacement demand.
- Passenger Cars:Sedan and coupe platforms with standardized component specifications and price-sensitive DIY maintenance behavior.
- Vans:Last-mile delivery and contractor vehicles with severe-duty cycles.
Trucks dominate commercial aftermarket value. SUVs are expanding most quickly as fleet mix shifts toward larger platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mexican manufacturing clusters export brake friction materials and catalytic converter substrates to distributors across the southwestern United States, with cross-border logistics networks enabling 48-hour replenishment cycles for Texas and Arizona service bays.
Texas
Commercial fleet operators in the Dallas-Fort Worth corridor accumulate annual mileage multiples above national passenger car averages, driving accelerated brake pad and suspension component turnover. EPA enforcement of counterfeit catalytic converter interdiction intensifies at Houston port-of-entry inspection facilities. San Antonio anchors a distribution hub network linking Mexican fabrication plants to Sun Belt wholesale warehouses.
California
CARB-certified oxygen sensor and catalytic converter specifications create compliance-filtered supplier pools that exclude uncertified competitors from the replacement exhaust channel. The state's right-to-repair legislation mandates diagnostic protocol accessibility for independent technicians servicing hybrid and plug-in electric fleets. Los Angeles Basin repair shops consolidate purchasing through digital platforms with VIN-specific fitment verification.
Florida
Corrosion-accelerated brake and exhaust system degradation from coastal humidity and salt exposure compresses replacement cycles for aging vehicle populations. NHTSA structural integrity standards govern collision-replacement body panel specifications enforced through Miami-Dade and Tampa Bay distribution channels. Orlando serves as a southeastern logistics node connecting Gulf Coast fabrication capacity to Caribbean export markets.
Arizona
Extreme heat and dust exposure in Phoenix-Tucson metropolitan corridors accelerate friction material degradation and air filter consumption beyond national baselines. Fleet telematics integration among mining and construction operators triggers predictive procurement of heavy-duty brake and suspension components. Flagstaff distribution facilities coordinate mountain-state replenishment for Utah and New Mexico service territories.
Michigan
Detroit-area automotive heritage clusters sustain specialized tooling and technical training infrastructure for internal combustion engine component remanufacturing. NHTSA safety standards for crash-replacement structural parts are administered through Ann Arbor testing facilities with direct supplier certification pathways. Grand Rapids wholesalers maintain legacy inventory depth for domestic truck and SUV platforms with extended service lives.
United States Aftermarket Automotive Parts and Components Market Competitive Landscape
On the supply side, the industry is bifurcated between vertically integrated multinational component manufacturers and specialized domestic distributors with dense metropolitan store networks. Tier-one suppliers with captive semiconductor and sensor fabrication capabilities command premium positioning in electrical and braking system replacement channels. Two strategic archetypes dominate: scale-driven retail chains optimizing same-day availability through inventory density, and technology-anchored manufacturers leveraging embedded software content to lock in recurring module replacement demand. Competitive dynamics center on geographic store expansion to capture professional installer volume and certification investments to maintain EPA and CARB compliant product listings.
Within the retail distribution tier, AutoZone Inc and O'Reilly Automotive Inc exemplify the store-density archetype with extensive metropolitan coverage enabling rapid parts availability for commercial fleet and independent repair shop demand. Among multinational component manufacturers, Continental AG represents the sensor-integrated systems specialist with premium positioning in replacement braking and chassis modules. These three entities anchor distinct competitive vectors—geographic accessibility, professional installer program lock-in, and technology-embedded premium pricing—without overlapping strategic positioning.
| Leading Market Players |
|---|
| AutoZone Inc |
| O'Reilly Automotive Inc |
| Advance Auto Parts Inc |
| Magna International Inc |
| Continental AG |
| ZF Friedrichshafen AG |
| DENSO Corporation |
| Robert Bosch GmbH |
| Lear Corporation |
| Others |
Value Network & Pricing Analysis
Cross-border freight corridors linking Mexican maquiladora clusters to Texas distribution hubs transmit raw material volatility directly into component pricing tiers, concentrating cost pressure on stamped steel chassis parts while enabling premium capture for CARB-certified exhaust modules through supply scarcity.
Pricing Analysis
Technology-generation pricing gaps separate conventional friction brake pads from sensor-integrated electronic caliper systems and emerging solid-state braking architectures. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and semiconductor content density, with EPA-verified catalytic converters commanding substantial premiums over uncertified alternatives. Cost compression in commodity engine hardware intensifies as Mexican fabrication capacity expands, while margins expand for electrical modules serving hybrid fleets. DIY consumers through mass-market retail chains exhibit highest price sensitivity, whereas commercial fleet operators prioritize same-day availability over unit cost.
Supply Chain Analysis
Tariff exposure between Mexico and the United States dominates supply chain risk calculations for stamped metal and forged engine components. Manufacturing concentration in Mexico, China, and Germany feeds the replacement channel with brake friction materials, catalytic converter substrates, and precision sensors. Raw material dependencies on aluminum alloys, rare earth elements for oxygen sensors, and engineered polymers for underhood applications create input cost volatility. Single-source vulnerability concentrates in semiconductor-equipped braking modules from German and Japanese tier-one suppliers. Distribution runs through two-step wholesale networks anchored by regional warehouses in Dallas, Los Angeles, and Detroit.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across propulsion architectures—internal combustion, hybrid, and battery-electric—creates specialized component niches as fleet heterogeneity multiplies SKU requirements and strains inventory planning systems.
For Market Incumbents: Build certification moats around EPA and CARB emissions compliance to exclude gray-market competitors from catalytic converter and oxygen sensor procurement. Deepen backward integration into sensor fabrication to secure semiconductor supply for advanced braking modules. Anchor capacity expansion in Mexican border states to capture cross-border logistics efficiencies while defending against input cost volatility through captive steel and aluminum processing. For New Entrants and Emerging Players: Pursue direct-to-installer digital platforms serving independent repair shops in Florida and Arizona with VIN-specific fitment tools and same-day regional fulfillment. Target sensor-integrated brake system segments where incumbent certification burdens delay product launches. Penetrate through specialized B2B marketplaces that bypass traditional two-step distribution and capture professional installer volume with guaranteed fitment accuracy. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors component suppliers with embedded software content and recurring module replacement revenue streams over commodity hardware fabricators. Long-term viability hinges on exposure to electrification-resistant segments—braking, suspension, and structural collision parts—rather than engine and transmission categories threatened by EV powertrain longevity. Monitor right-to-repair legislative contagion beyond Massachusetts as the signal indicating independent shop addressable demand expansion.| Strategic Initiative | Industry Significance |
|---|---|
| CARB Certification Investment | EPA enforcement protects verified suppliers from counterfeit competition in exhaust channels. |
| Telematics Platform Integration | Predictive maintenance algorithms compress procurement cycles for fleet brake and sensor replacement. |
| Mexican Manufacturing Footprint | Cross-border logistics enable 48-hour replenishment for Sun Belt wholesale warehouses. |
| Direct-to-Installer Marketplace Launch | VIN-specific fitment tools reduce return rates below traditional phone-and-fax ordering systems. |
| Sensor-Integrated Brake System Development | ADAS proliferation creates replacement demand for wheel-speed sensors and electronic control modules. |
Research Methodology
The analysis maps brake friction materials, catalytic converter substrates, electrical sensors, and engine hardware components, each validated through fleet procurement managers, independent repair shop owners, aftermarket distributor operations heads, and OEM platform engineers. Primary interviews with these stakeholders combined trade association datasets, EPA certification registries, state vehicle registration databases, and customs import records. Secondary validation drew from NHTSA safety filings, CARB compliance listings, and commercial telematics provider disclosures. Bottom-up component demand modeling triangulated against top-down market sizing across vehicle age, mileage accumulation, and regional fleet composition.
Assumptions held fixed include prevailing EPA enforcement intensity, Massachusetts right-to-repair diagnostic protocol accessibility, and Mexican manufacturing cost structures, while variables included EV fleet penetration rates, aluminum and steel commodity price trajectories, and telematics adoption curves among commercial operators. The analytical framework segmented by product type, component complexity, sales channel, and vehicle class across the projection horizon. CAGRs derived from regression analysis against historical replacement cycle data, vehicle miles traveled projections, and regulatory compliance cost pass-through modeling. Industry-specific forecast inputs incorporated Sun Belt vehicle aging patterns and commercial fleet telematics integration rates.
Sensitivities concentrate around EPA enforcement escalation, right-to-repair legislative expansion, and EV powertrain longevity impacts on traditional engine component demand. Forecasts embed assumptions about commodity price stabilization and cross-border logistics continuity that operating reality may revise. Continuous validation against fleet procurement behavior and distributor inventory turnover is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Gear Shifter Market
Automotive Components
Automotive Wiper Blades Market
Automotive Components
Automotive Spark Plug Market
Automotive Components
Automotive Catalyst Market
Automotive Components
Europe Automotive Plastics Market
Automotive Components
Automotive Glass Film Market
Automotive Components
Egypt Automotive Lubricants Market
Automotive Components
Beryllium Copper for Automobile Market
Automotive Components
Remote Automotive Exhaust Sensing Market
Automotive Components
Australia Automotive Composites Market
Automotive Components
Automotive Mobile Accessories Market
Automotive Components
Automotive Glass Fiber Composites Market
Automotive Components
Automotive Differential Market
Automotive Components
Automotive Camshaft Phase Variator Market
Automotive Components
United States Automotive Pneumatic Actuators Market
Automotive Components
Brake Cooling Duct and Hose Market