
 Intelligent Motor Control Center Market | 2026-2036
Intelligent Motor Control Center Market Size, Share, and Industry Trends Forecast 2026-2036
Intelligent Motor Control Center Market Foresight
Buyer concentration across industrial manufacturing is recalibrating as large process operators consolidate vendor relationships around full-lifecycle service contracts. ABB leverages its digital twin integration to anchor premium positions in energy-intensive sectors. Siemens AG competes through its embedded control architectures that synchronize motor protection with plant-wide automation networks. Rockwell Automation differentiates via its software-defined motor control platforms that reduce commissioning cycles for multi-site operators.
An intelligent motor control center integrates variable frequency drives, programmable logic controllers, and digital protective relays within a centralized enclosure rated for IEC 61439 or UL 845 compliance, enabling coordinated motor starting, real-time condition monitoring, and predictive maintenance across industrial processes. Variable frequency drives lead product type revenue due to their centrality in energy management retrofits, while wireless integration represents the fastest-expanding technology segment as facilities prioritize cable-reduction strategies. Process automation applications command the largest application share, though motor protection modules are gaining traction in oil and gas environments where unplanned downtime carries severe financial penalties.
The US Department of Energy appliance and equipment standards program, the European Union F-Gas Regulation, and China's GB standards for motor system efficiency are converging to mandate intelligent monitoring capabilities in new and retrofit motor installations. NHTSA and OSHA electrical safety directives in North America further shape enclosure and arc-flash containment specifications. Stakeholders must monitor how evolving interoperability standards between IT and operational technology layers influence procurement criteria and supplier qualification timelines.
Market Dynamics
The shift from hardwired motor control architectures to Ethernet-based industrial networks is restructuring procurement criteria, forcing incumbent suppliers to requalify legacy platforms under IEC 61850 and IEEE 1686 cybersecurity frameworks.
Growth Catalysts
- EU F-Gas Regulation:Phase-down mandates for fluorinated greenhouse gases in cooling systems accelerate VFD retrofits in HVAC-intensive facilities across Germany and France.
- Water treatment utilities:Networked motor control systems enable remote monitoring of pump stations, cutting on-site maintenance visits by enabling predictive diagnostics.
- Edge computing integration:Embedded analytics at the MCC enclosure level compresses response times for fault isolation in continuous-process manufacturing.
Market Restraints
- Copper and silicon carbide price volatility:Power semiconductor substrates face supply concentration from Chinese wafer foundries, squeezing VFD margin structures.
- IEC 61439-2 certification timelines:Type-tested assembly validation for intelligent MCCs extends product launch cycles by 8-14 months in European markets.
- Technical debt in brownfield sites:Legacy magnetic starters lack digital communication interfaces, forcing parallel infrastructure investments during retrofits.
Strategic Opportunities
- India's PLI scheme for industrial automation:Domestic manufacturing incentives create localized assembly opportunities for cost-optimized intelligent MCC platforms.
- Wireless motor monitoring:ISA100.11a and WirelessHART protocols eliminate cable runs in hazardous-area oil and gas installations.
- Service contract unbundling:Predictive maintenance subscriptions separate software revenue from hardware sales, recurring-izing revenue streams.
Industry Challenges
- Cybersecurity skill scarcity:IT/OT convergence demands engineers fluent in both IEC 62443 security zones and motor protection relay configuration.
- Multi-standard compliance burden:Simultaneous UL 845, IEC 61439, and ATEX certifications fragment engineering resources for global product lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intelligent Motor Control Center Market |
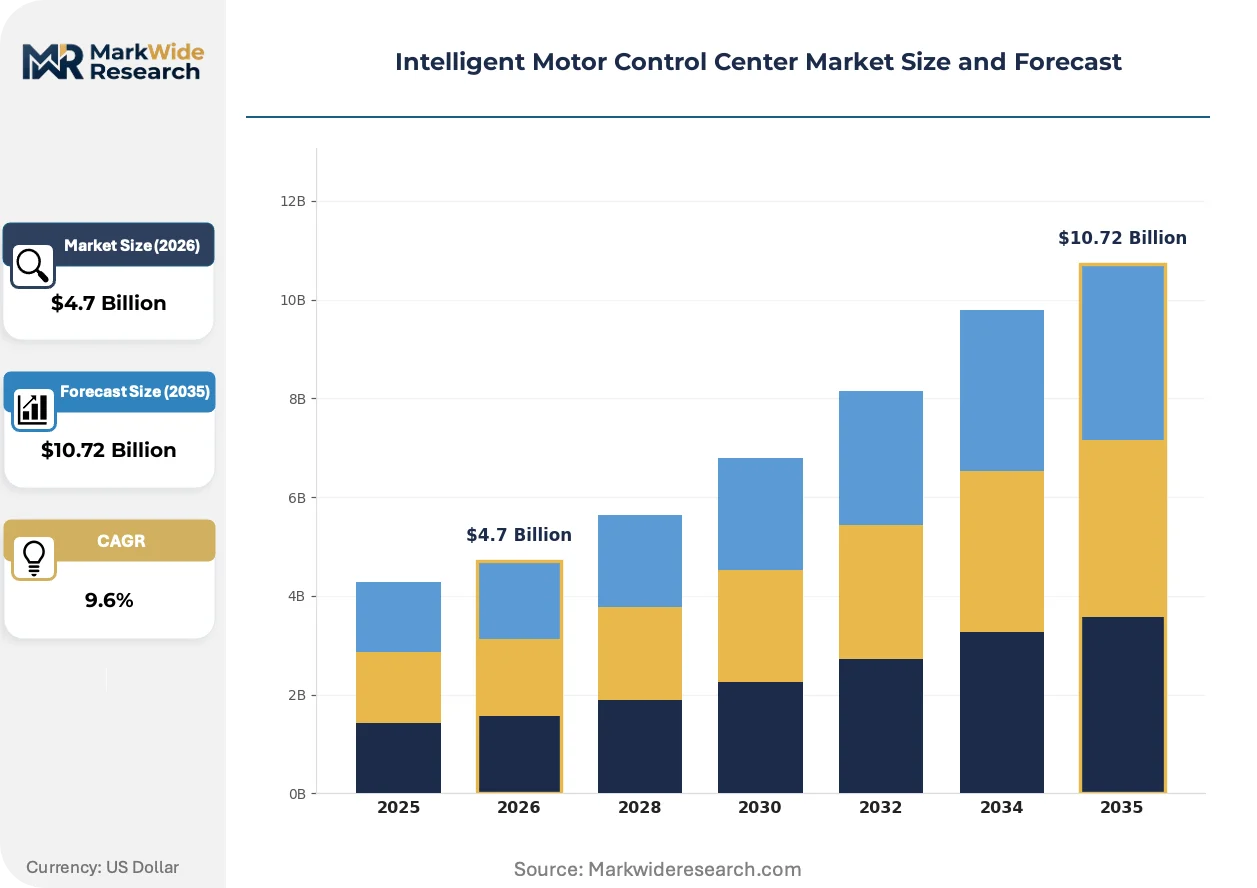
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $10.72 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soft Starters, Variable Frequency Drives, Programmable Logic Controllers, Contactors Technology: Digital Control, Analog Control, Embedded Systems, Wireless Integration End User: Industrial Manufacturing, Oil & Gas, Water Treatment, Energy Generation Application: Process Automation, Motor Protection, Energy Management, HVAC Systems |
| Companies Covered | ABB, Schneider Electric, Siemens AG, Rockwell Automation, Eaton Corporation, Mitsubishi Electric Corporation, Fuji Electric Co., Ltd., WEG, NIDEC CORPORATION, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intelligent Motor Control Center Market Shifts & Advancements
Digital twin technology is migrating from design-phase simulation to operational-phase asset management, embedding physics-based motor models directly into MCC control architectures.
Embedded motor condition monitoring is converging with vibration analysis algorithms to enable bearing-fault prediction without external sensors. Pulp and paper mills in Scandinavia deploy these integrated packages to eliminate unplanned dryer section shutdowns. The technology is converging with cloud-based fleet analytics to compress mean-time-to-repair across multi-site operations.
The US Department of Energy's appliance standards program now mandates intelligent load monitoring for motors above 200 horsepower in federal facilities. This forces OEMs to pre-integrate power metering and communication modules rather than offering them as aftermarket accessories. Defense and wastewater treatment contractors face compressed bid timelines as proof of compliance becomes a gate to contract award.
Buyer preference is hardening around full-lifecycle cost models that internalize energy savings and maintenance avoidance. Equipment financiers in Germany now structure lease payments around verified efficiency gains, displacing traditional capex purchase patterns. Oil and gas operators in the North Sea cluster have adopted this outcome-linked contracting most aggressively, pressuring suppliers to guarantee uptime thresholds.
Intelligent Motor Control Center Market Segmentation
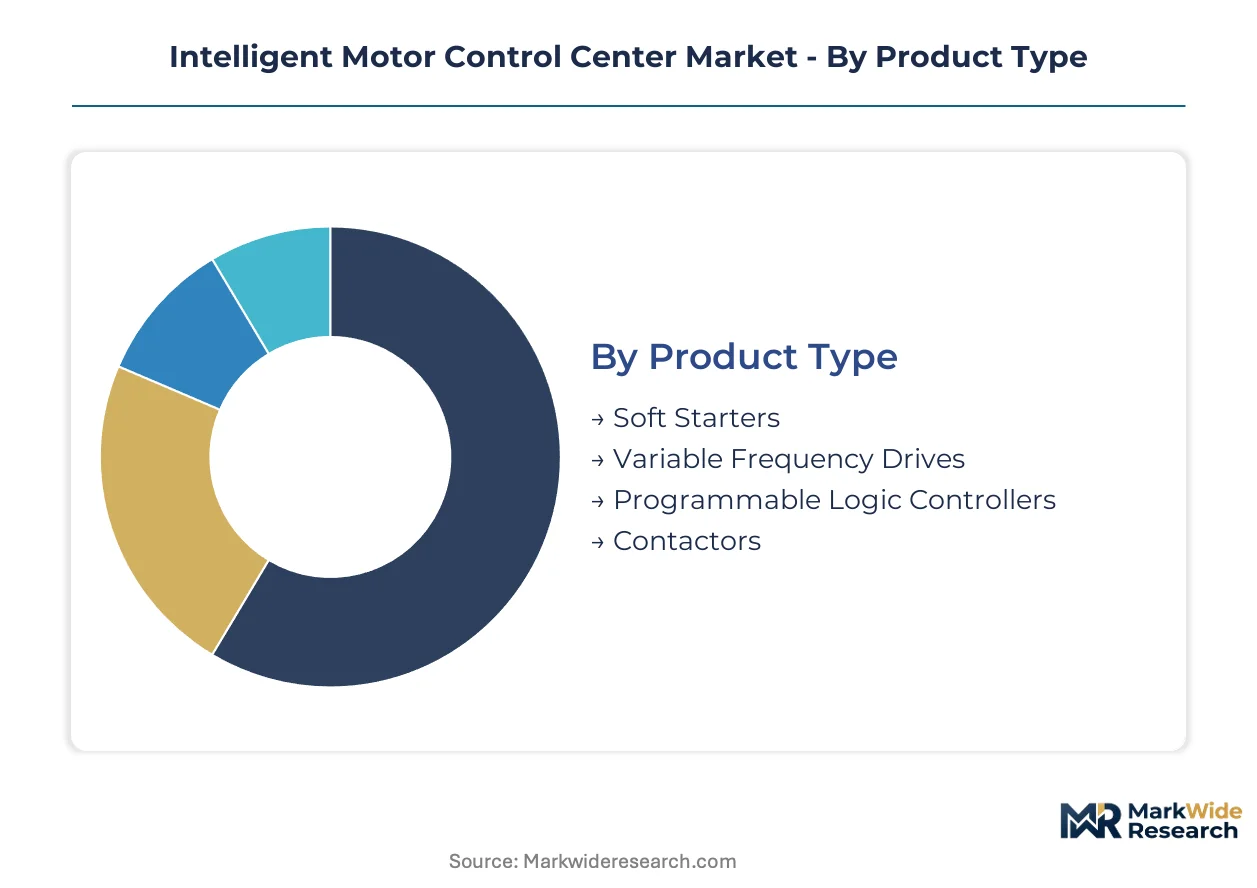
Intelligent motor control center procurement splits sharply between premium architectures for continuous-process industries and cost-optimized platforms for discrete manufacturing. Understanding these fault lines exposes where suppliers can defend margin and where volume commoditization threatens returns.
Product Type:
Variable frequency drives command premium positioning through energy recovery capabilities, while soft starters anchor the volume tier for fixed-speed pump and fan applications.
- Variable Frequency Drives:These units modulate motor speed through pulse-width modulation, cutting energy consumption by 30-50% in centrifugal load applications. Demand concentrates in German automotive paint shops and steel rolling mills where EU ETS carbon costs amplify efficiency payback calculations.
- Soft Starters:Solid-state devices limit inrush current during motor acceleration, extending mechanical equipment life. Water treatment utilities in France specify these for large pump stations where variable speed remains unnecessary but mechanical stress reduction delivers lifecycle value.
- Programmable Logic Controllers:Embedded control processors execute ladder logic for coordinated multi-motor sequences.
- Contactors:Electromechanical switching devices provide basic on/off motor control in cost-sensitive retrofit scenarios.
Today's leader: Variable Frequency Drives. Tomorrow's challenger: Soft Starters.
Technology:
Digital control architectures dominate new installations, yet wireless integration is climbing the fastest as brownfield sites resist cable trenching costs.
- Digital Control:Microprocessor-based systems execute precise motor algorithms with millisecond response times. Oil and gas operators in the North Sea deploy these for compressor anti-surge protection where control fidelity prevents catastrophic equipment damage.
- Wireless Integration:ISA100.11a and WirelessHART protocols eliminate signal cabling in hazardous-area enclosures. Pulp and paper mills in Finland adopt these for remote stock preparation monitoring, cutting installation labor by 60% in multi-story process buildings.
- Embedded Systems:Dedicated computing platforms integrate motor protection, metering, and communication in single-chip designs.
- Analog Control:Legacy voltage and current feedback circuits persist in military-specified equipment requiring deterministic response without software layers.
Digital control captures current procurement budgets. Wireless integration captures specification momentum in retrofit-heavy sectors.
End User:
Industrial manufacturing generates the deepest installed base, while water treatment utilities are expanding procurement most aggressively amid infrastructure modernization mandates.
- Industrial Manufacturing:Discrete and process factories deploy intelligent MCCs for coordinated material handling and machine tool power distribution. German automotive OEMs specify these for body-in-white welding lines where synchronized servo motor control determines production cadence.
- Water Treatment:Municipal and industrial utilities network pump station controls for centralized SCADA visibility. Dutch regional water authorities mandate intelligent motor protection for all new sewage lift stations above 75 kilowatt capacity.
- Oil & Gas:Upstream and downstream facilities prioritize arc-flash containment and explosion-proof enclosures.
- Energy Generation:Combined cycle power plants and renewable substations require synchronized motor starting for auxiliary systems.
Industrial manufacturing owns the installed base. Water treatment owns the replacement cycle.
Application:
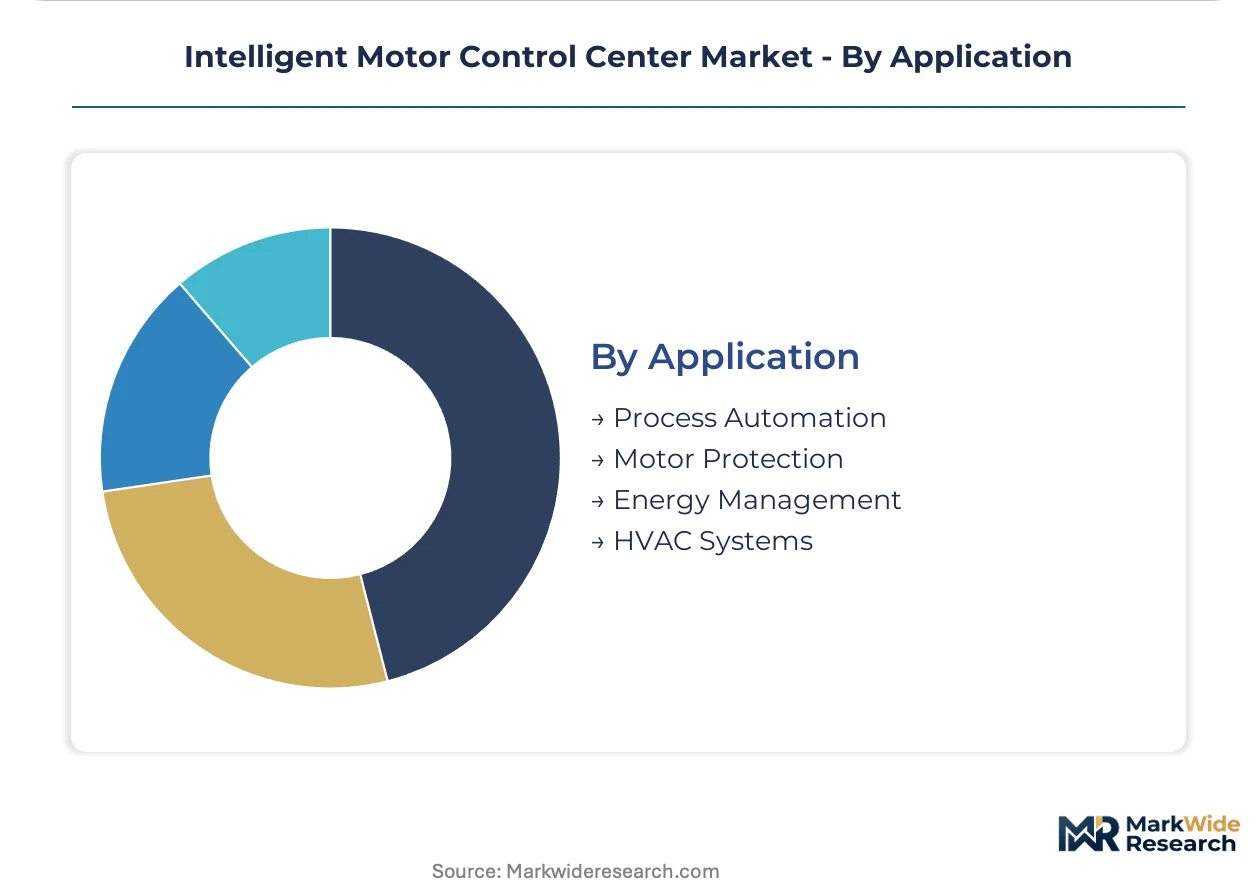
Process automation commands specification authority, though motor protection modules are gaining traction where unplanned downtime carries severe financial penalties.
- Process Automation:Coordinated motor control enables continuous-flow manufacturing with minimal human intervention. Italian ceramic tile producers deploy these for kiln drive synchronization where temperature profile maintenance determines product quality.
- Motor Protection:Intelligent relays monitor thermal, electrical, and mechanical fault signatures to prevent catastrophic failures. Offshore platforms in Norwegian waters specify these for submersible pump protection where replacement costs exceed equipment value by an order of magnitude.
- Energy Management:Integrated metering and demand response capabilities optimize facility power consumption patterns.
- HVAC Systems:Building automation integration enables variable air volume and chilled water optimization.
Process automation defines current procurement. Motor protection is displacing basic overload relays fastest in asset-critical environments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's industrial automation retrofit cycles outpace France's water utility modernization, while China's manufacturing scale and India's automation incentives reshape procurement patterns across Asia.
United States
Federal efficiency mandates and defense contractor demand concentrate procurement in intelligent motor control centers. The Department of Energy appliance standards program mandates intelligent load monitoring for motors above 200 horsepower in federal facilities. Defense and wastewater treatment contractors in Virginia and California face compressed bid timelines as compliance documentation becomes mandatory for contract award.
Germany
EU ETS carbon costs and automotive welding line automation drive replacement of conventional motor control centers. The EU F-Gas Regulation phase-down accelerates variable frequency drive retrofits in HVAC-intensive facilities. Automotive OEMs in Stuttgart and Wolfsburg specify intelligent MCCs for body-in-white welding lines where synchronized servo motor control determines production cadence.
China
GB standards for motor system efficiency and dual carbon goals mandate intelligent monitoring in new industrial installations. The country's national standards body enforces efficiency tiers that disqualify conventional magnetic starters from state-backed projects. Steel rolling mills in Hebei Province and chemical complexes in Jiangsu Province deploy networked motor control systems to meet provincial emissions targets.
India
The PLI scheme for industrial automation creates localized assembly opportunities for cost-optimized intelligent MCC platforms. Central electricity authority guidelines push efficiency upgrades across state electricity board jurisdictions. Automotive suppliers in Pune and chemical processors in Gujarat retrofit pump stations with soft starters to limit inrush current while avoiding full variable speed investments.
France
Water treatment infrastructure modernization and nuclear auxiliary system upgrades expand procurement of networked motor control systems. The EU F-Gas Regulation drives cooling system retrofits in commercial and industrial facilities. Regional water authorities around Paris and Lyon mandate intelligent motor protection for sewage lift stations above 75 kilowatt capacity.
Intelligent Motor Control Center Market Competitive Landscape
European producers anchor the premium tier through embedded control architectures and digital twin integration; Asian specialists hold volume positions through cost-optimized platforms for emerging markets. The vendor base concentrates around full-lifecycle service contracts as large process operators consolidate relationships. Three archetypes dominate: integrated automation conglomerates with software-defined platforms, power electronics specialists with semiconductor supply control, and regional system integrators with localized certification expertise. Strategic moves center on predictive maintenance subscription unbundling and edge computing partnership structures.
Among the integrated automation conglomerates, ABB, Siemens AG, and Rockwell Automation exemplify divergent positioning strategies. ABB occupies a position anchored in digital twin integration for energy-intensive sectors. Siemens AG sits within the embedded control architecture vector, synchronizing motor protection with plant-wide automation networks. Rockwell Automation represents the software-defined platform archetype, reducing commissioning cycles for multi-site operators through unified programming environments.
| Leading Market Players |
|---|
| ABB |
| Schneider Electric |
| Siemens AG |
| Rockwell Automation |
| Eaton Corporation |
| Mitsubishi Electric Corporation |
| Fuji Electric Co., Ltd. |
| WEG |
| NIDEC CORPORATION |
| Others |
Supply & Pricing Matrix
Federal efficiency mandates in the United States and EU F-Gas phase-down requirements in Germany are compressing procurement timelines and forcing suppliers to pre-integrate intelligent monitoring modules rather than offering aftermarket upgrades, reshaping cost structures across certification tiers.
Pricing Analysis
Capacity additions in China and India are reshaping price floors for cost-optimized intelligent MCC platforms while premium-tier suppliers in Germany defend positions through digital twin bundling. Three-tier pricing structure across premium, standard, and economy levels separates IEC 61439-2 certified assemblies with predictive maintenance subscriptions from basic UL 845 compliant units. Price differentiation hinges on embedded edge computing capabilities and wireless protocol support. Cost compression in the economy tier is intensifying because semiconductor substrate supply concentrates in Chinese wafer foundries. Water treatment utilities exhibit highest price sensitivity, while oil and gas operators in the North Sea cluster prioritize uptime guarantees over unit cost.
Supply Chain Analysis
Regional distribution centers in Germany, the United States, and China coordinate hub-and-spoke patterns for intelligent MCC assemblies, with final configuration occurring close to installation sites to accommodate voltage and certification variations. Power semiconductor manufacturing concentrates in China, Taiwan, and South Korea, while copper busbar fabrication and enclosure stamping anchor in Germany and the United States. Raw material dependencies include silicon carbide substrates, electrolytic copper, and engineered thermoplastics for arc-flash containment. Single-source vulnerability in Chinese wafer foundries threatens VFD margin structures. Distribution runs through authorized system integrators and direct OEM channels to large process operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in intelligent motor control centers rests on predictive maintenance subscription unbundling and premium-tier positioning around digital twin integration, with cost-down pressure concentrated in economy-tier commodity assemblies.
For Market Incumbents: Anchor defensive positions through backward integration into power semiconductor sourcing and captive supply of silicon carbide substrates to offset Chinese foundry concentration risk. Deepen certification investment in simultaneous UL 845, IEC 61439, and ATEX compliance to fragment engineering resources of emerging competitors. Prioritize channel control by consolidating authorized system integrator networks in Germany and the United States where retrofit cycles concentrate procurement authority. For New Entrants and Emerging Players: Begin with wireless motor monitoring modules for hazardous-area oil and gas installations in the North Sea cluster, where cable-reduction strategies command specification momentum and incumbent bundling remains incomplete. Target India's PLI scheme for localized intelligent MCC assembly, exploiting domestic manufacturing incentives and state electricity board efficiency mandates. Pursue outcome-linked contracting with water treatment utilities as the go-to-market angle, structuring lease payments around verified energy savings to displace traditional capex purchase patterns. For Investors and Strategic Acquirers: Asymmetric upside sits with regional system integrators possessing localized certification expertise and established relationships with municipal water authorities undergoing infrastructure modernization. Long-term viability favors acquisition targets with predictive maintenance software platforms capable of recurring revenue separation from hardware sales. Watch for inflection where equipment financiers in Germany expand outcome-linked contracting structures beyond automotive and oil and gas into water treatment and discrete manufacturing verticals.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Subscription Launch | Recurring-izes revenue streams for ABB and Siemens AG beyond hardware sales cycles. |
| Edge Computing Partnership Structure | Embeds analytics at MCC enclosure level for Rockwell Automation's multi-site operator clients. |
| Wireless Protocol Certification Investment | Enables ISA100.11a and WirelessHART deployment in Finnish pulp and paper hazardous areas. |
| Backward Integration into SiC Substrates | Reduces exposure to Chinese wafer foundry concentration for VFD margin protection. |
| Localized Assembly under India's PLI Scheme | Captures domestic manufacturing incentives for cost-optimized platforms in Pune and Gujarat. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with maintenance directors, plant engineers, OEM procurement teams, and aftermarket service heads with secondary validation against SEC 10-K filings, customs and trade data, IEC and UL certification registries, and industry association technical reports. Bottom-up sizing of variable frequency drive, soft starter, and motor protection module shipments triangulated against top-down estimates of industrial automation capital expenditure across water treatment, oil and gas, and manufacturing verticals.
Segment-weighting approaches modeled product type, technology architecture, end-user industry, and application intensity across the analysis window, with CAGRs derived from regression analysis of historical replacement cycles and regulatory mandate implementation timelines. Forecast inputs incorporated EU ETS carbon cost trajectories, F-Gas phase-down schedules, and China's dual carbon goal enforcement patterns for motor system efficiency tiers.
Caveats apply where semiconductor substrate supply disruptions, IEC 61439-2 certification timeline extensions, or cybersecurity framework evolutions could materially shift the outlook for intelligent MCC deployment. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Motor
Europe Electric Motors for Electric Vehicle Market
Electric Motor
Brush Motor Control Unit Market
Electric Motor
Brazil Electrically Powered Hydraulic Steering Market
Electric Motor
Global Electric Motors for Electric Vehicle Market
Electric Motor
Automotive ABS Motor Market
Electric Motor
Voice Coil Motor Market
Electric Motor
GCC Electric Motor Market
Electric Motor
Electric Vehicle Motor (EVM) Controller Market
Electric Motor
Global Automotive Onboard Charger Market
Electric Motor
Motors for Robot Body and Robot Wheels Market
Electric Motor
Electric Motors for IC Engine Vehicle Market
Electric Motor
Electronically Commutated Motors Market
Electric Motor
Automotive Wiper Motor Market
Electric Motor
Car Charger Market
Electric Motor
France Alternating Current (AC) Motor Market
Electric Motor
Electric Motor Sales Market