
 Automotive Hubcaps Market | 2026-2036
Automotive Hubcaps Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Hubcaps Market Analytics
The capital-intensity divergence between high-volume stampers and boutique custom producers is collapsing as aluminum forging costs decline. Wheel Pros leverages its North American distribution network to sustain broad SKU coverage across aftermarket channels. Alcoa Corporation anchors its position through captive aluminum smelting and downstream wheel component fabrication. Zanini Auto Grup SA differentiates via integrated painting and finishing lines that serve European OEM assembly plants.
Automotive hubcaps are protective or decorative covers mounted over the central portion of a vehicle wheel, typically manufactured from stamped steel, injection-molded ABS plastic, or cast aluminum alloys with diameters ranging from 13 to 22 inches to match wheel specifications. Their primary purpose spans functional protection of wheel bearings and lug nuts from corrosion and debris intrusion to aesthetic enhancement that supports brand identity and consumer customization preferences. Plastic hubcaps and snap-on installations dominate volume production for economy and mid-range passenger cars where cost minimization outweighs durability demands, while aluminum hubcaps and bolt-on configurations command premium positioning in SUVs and truck segments where load-bearing performance and thermal management justify higher unit economics. Custom hubcaps with sporty and modern design styling represent the fastest-growing margin pool as aftermarket personalization trends accelerate among younger vehicle owners.
The EPA regulates hubcap-related fuel economy contributions through vehicle-level Corporate Average Fuel Economy standards, while NHTSA enforces wheel retention and projection safety requirements that shape hubcap retention mechanism design. China's MIIT implements GB standards for passenger car fuel consumption that indirectly mandate aerodynamic wheel cover adoption, and the EU's REACH framework restricts certain plasticizers and surface coatings used in hubcap manufacturing. Stakeholders must monitor evolving alloy composition standards and cross-border material certification reciprocity to secure supply continuity across divergent regulatory jurisdictions.
Market Dynamics
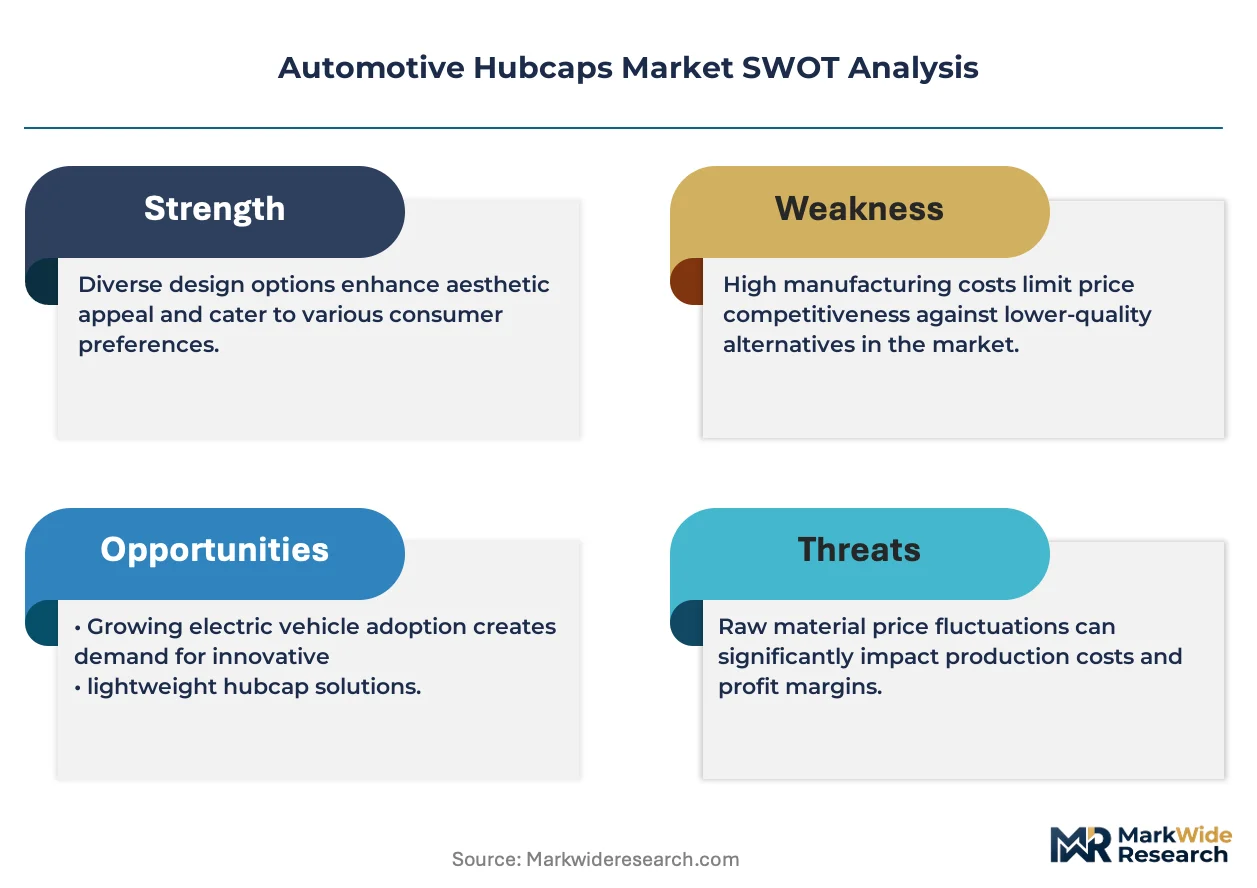
Aluminum forging cost compression is collapsing the capital barrier between high-volume stampers and boutique producers, forcing mid-tier manufacturers to choose between scale investment or specialized finishing capabilities.
Growth Catalysts
- EPA Fuel Economy Mandates:Corporate Average Fuel Economy standards tighten annually, compelling OEMs to specify lightweight aluminum and composite hubcap designs that reduce unsprung mass and improve vehicle efficiency ratings.
- Electric Vehicle Platform Scaling:Chinese automakers are integrating aerodynamic wheel covers into dedicated EV architectures, creating specification pull for seamless hubcap-wheel systems that optimize range performance.
- Aluminum Smelting Integration:Captive primary metal production is securing supply continuity for wheel component fabricators, insulating downstream operations from LME price volatility and alloy certification delays.
Market Restraints
- Steel Price Volatility:Traditional stamped steel hubcap producers face margin compression from scrap metal input cost swings, eroding competitiveness against stable-cost aluminum alternatives.
- REACH Compliance Burden:The EU's chemical registration framework restricts plasticizers and surface coatings used in ABS hubcap manufacturing, forcing reformulation investments or market exit.
- Wheel Cover Substitution:Full aerodynamic wheel covers on premium EVs are displacing conventional hubcaps entirely, threatening volume in the fastest-growing vehicle segment.
Strategic Opportunities
- Aftermarket Personalization Demand:Younger vehicle owners in North America are driving specification of custom hubcap designs through direct-to-consumer channels, bypassing traditional distributor markups.
- MIIT Fuel Consumption Standards:China's GB standards for passenger car efficiency indirectly mandate aerodynamic wheel cover adoption, opening specification windows for advanced hubcap suppliers in the world's largest production market.
- 3D Printing Convergence:Additive manufacturing of prototype tooling is compressing design-to-production timelines for low-volume custom runs, enabling margin capture from short-lead personalization orders.
Industry Challenges
- Alloy Certification Complexity:Cross-border material certification reciprocity gaps between NHTSA, MIIT, and KBA requirements are delaying product launches and forcing redundant testing protocols.
- Paint Line Capital Intensity:Integrated finishing capabilities require continuous oven investments that strain balance sheets, favoring suppliers with captive coating operations over independent stampers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Hubcaps Market |
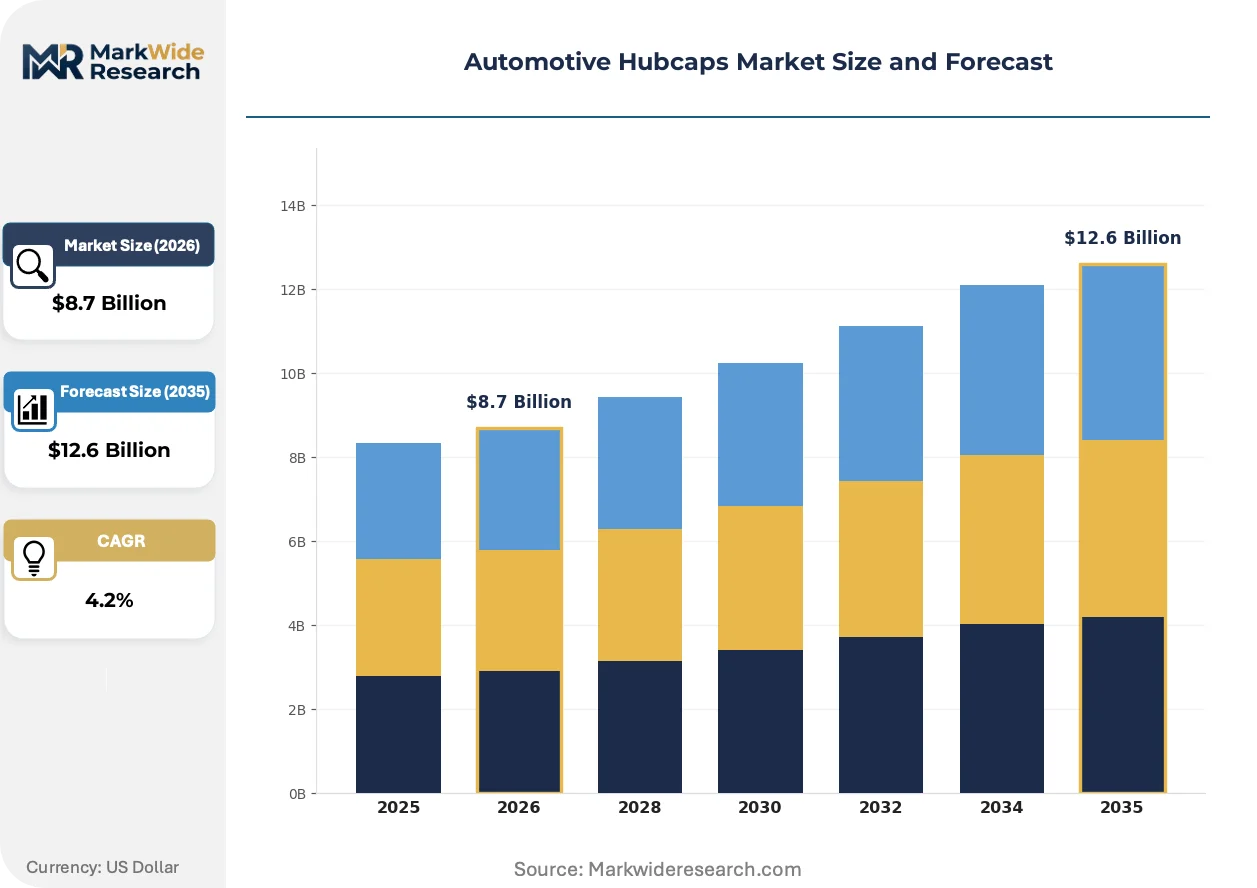
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $12.6 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steel Hubcaps, Plastic Hubcaps, Aluminum Hubcaps, Custom Hubcaps Installation Type: Snap-on Hubcaps, Bolt-on Hubcaps, Full Wheel Covers, Semi-Flush Hubcaps Vehicle Type: Passenger Cars, SUVs, Trucks, Vans Design Style: Sporty, Classic, Modern, Elegant |
| Companies Covered | Wheel Pros, Alcoa Corporation, Zanini Auto Grup SA, CIE Automotive S.A., Swell Marui Automobile Parts Co., LTD, Minth Group, Pacific Industrial Co. Ltd., Dura Automotive Systems, Steel Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Hubcaps Market Evolving Landscape
Material science advances and regulatory pressure on vehicle efficiency are rewiring specification criteria, while digital channels are fragmenting traditional distribution hierarchies in aftermarket supply.
Composite hubcap manufacturing is bifurcating the supplier base into two distinct capability tiers. Long-fiber reinforced thermoplastics deliver weight reduction and corrosion immunity that aluminum cannot match at equivalent cost. European OEM assembly plants are accelerating validation programs for these materials, compressing the timeline for steel design obsolescence in mid-range vehicle segments.
REACH restrictions on chrome plating and specific plasticizers are forcing surface treatment migration toward physical vapor deposition and waterborne coating systems. The industrial consequence is a supply base consolidation around suppliers with integrated environmental compliance infrastructure. Wheel component fabricators serving EU assembly plants are absorbing the highest compliance costs, passing through price adjustments that widen the premium-economy specification gap.
Direct-to-consumer configuration tools are fragmenting traditional aftermarket distribution. Younger vehicle owners are specifying custom hubcap designs through manufacturer websites, displacing distributor-assisted selection. This channel shift is most visible in North America, where Wheel Pros and specialty retailers are building proprietary digital platforms to capture design-margin that previously accrued to independent jobbers.
Automotive Hubcaps Market Segmentation
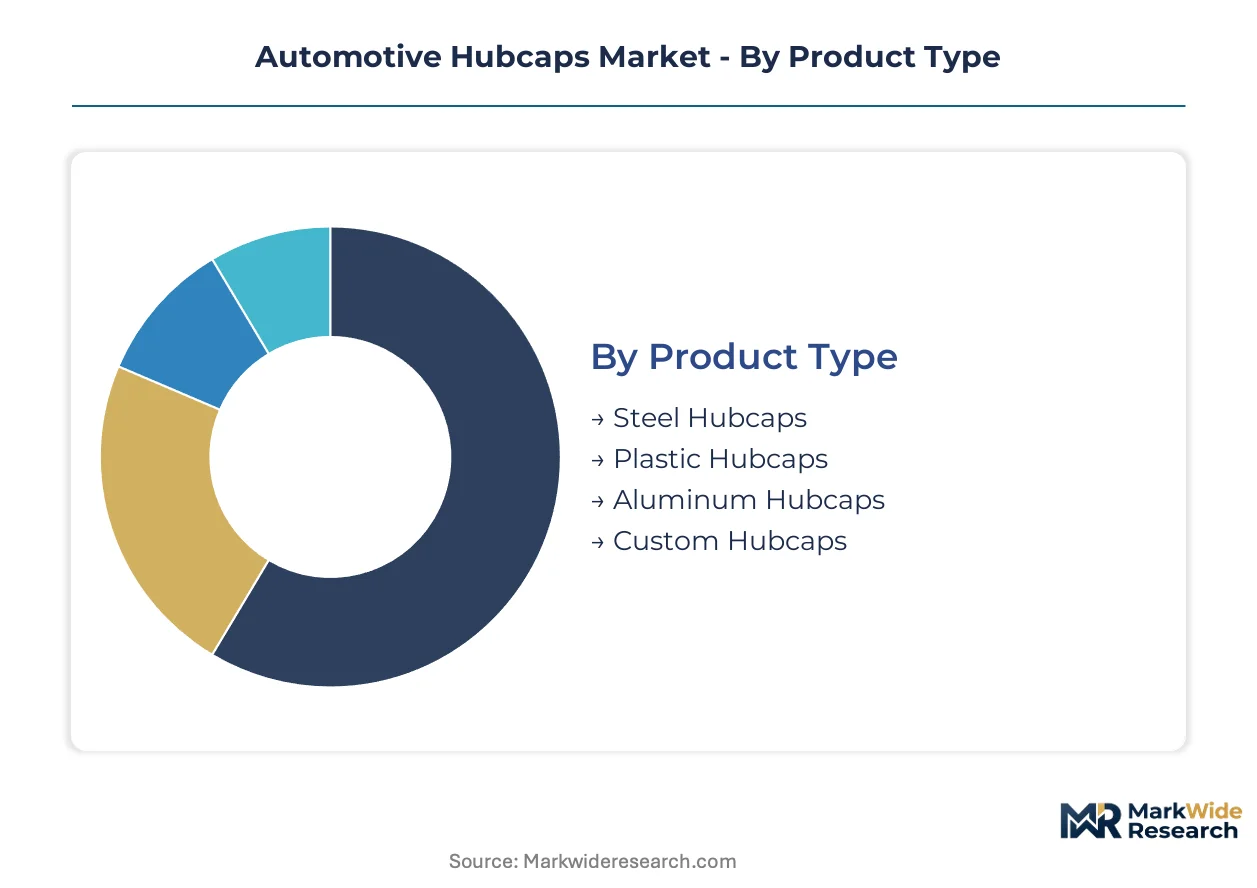
Hubcap specification diverges sharply across OEM and aftermarket channels, with material selection and installation geometry determining regulatory compliance and margin capture. Segmentation reveals how lightweighting mandates and personalization trends are rewiring procurement priorities across vehicle categories.
Product Type:
Domestic production concentrates on stamped steel and injection-molded plastics for high-volume OEM contracts, while aluminum and custom segments rely heavily on export-oriented fabrication and specialty finishing capabilities.
- Steel Hubcaps:Stamped cold-rolled steel construction delivers lowest unit cost for economy passenger car platforms. Demand concentrates with legacy OEMs in Detroit and Stuttgart seeking margin preservation in entry-level trims, though EPA fuel economy pressure is eroding specification share.
- Plastic Hubcaps:Injection-molded ABS and polypropylene compounds enable complex styling geometries at sub-aluminum cost points. Chinese domestic automakers are scaling ABS hubcap procurement for EV platforms where aerodynamic integration matters more than thermal performance.
- Aluminum Hubcaps:Cast and forged aluminum alloys reduce unsprung mass for fuel economy compliance. Captive smelting operations in Russia and Canada secure supply continuity for premium SUV and truck applications.
- Custom Hubcaps:Bespoke designs with proprietary finishes serve aftermarket personalization channels. Direct-to-consumer configuration tools in California and Texas are compressing traditional distributor margins.
Steel hubcaps hold the largest share; momentum sits with aluminum as CAFE standards tighten.
Installation Type:
Cost tier stratification separates snap-on economy solutions from bolt-on premium systems, with full wheel covers commanding the highest engineering investment per unit.
- Snap-on Hubcaps:Plastic retention clips enable tool-free installation for cost-sensitive fleet and rental vehicle operators. Volume concentrates in Mexico and Brazil where labor minimization outweighs durability demands.
- Bolt-on Hubcaps:Threaded lug nut integration secures retention for heavy-duty truck and off-road SUV applications. NHTSA wheel retention requirements are mandating bolt-on specification for vehicles above 6,000 pounds GVWR.
- Full Wheel Covers:Aerodynamic disc designs spanning the entire wheel diameter optimize EV range performance. MIIT fuel consumption standards in China are accelerating validation programs for seamless wheel cover integration.
- Semi-Flush Hubcaps:Partial coverage designs balance styling exposure with brake cooling requirements. European OEM assembly plants in Spain and Czechia are specifying semi-flush geometries for performance hatchback platforms.
Bolt-on systems command premium pricing; full wheel covers are climbing the fastest as EV architectures proliferate.
Vehicle Type:
Application-driven specification splits between mass-market passenger cars and commercial-duty trucks, with SUVs capturing disproportionate aluminum and custom content.
- Passenger Cars:High-volume production favors plastic and steel hubcaps with standardized retention geometry. Japanese kei-car regulations are driving miniaturized hubcap specifications for sub-660cc vehicle platforms.
- SUVs:Elevated ride heights and load ratings demand reinforced aluminum or composite construction. Texas and Alberta oil patch operators are specifying heavy-duty bolt-on systems for full-size SUV fleets.
- Trucks:Commercial duty cycles mandate corrosion-resistant materials and positive retention mechanisms. Brazilian agricultural truck operators are scaling procurement of stainless-steel hubcap alternatives to painted steel.
- Vans:Fleet-dominated procurement prioritizes damage resistance and rapid replacement compatibility. Last-mile delivery operators in Germany and the Netherlands are standardizing universal snap-on designs across mixed vehicle pools.
Passenger cars retain volume leadership; SUVs deliver the steepest margin expansion trajectory.
Design Style:
Customer type fragmentation separates OEM brand-identity programs from aftermarket personalization demand, with age cohort driving stylistic preference divergence.
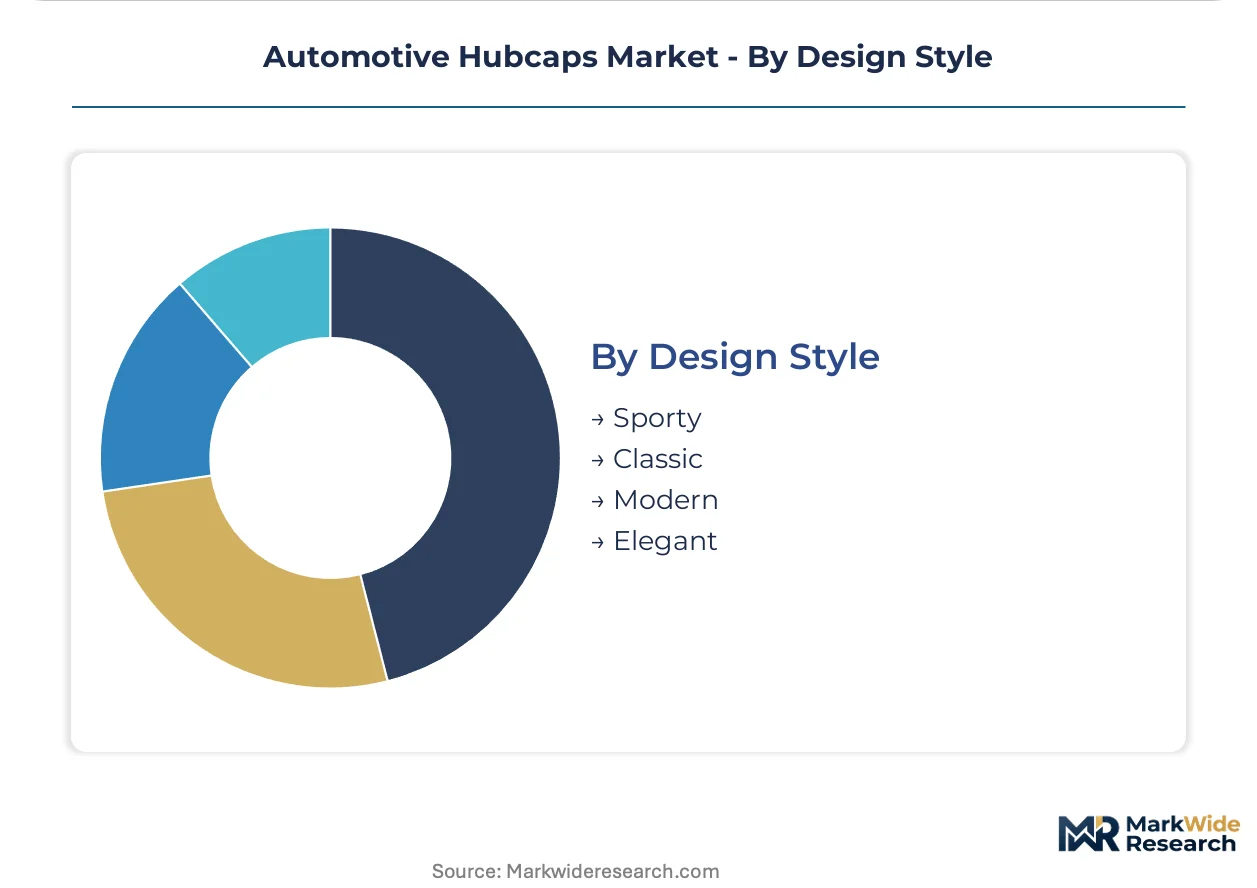
- Sporty:Aggressive spoke patterns and exposed hardware aesthetics target performance vehicle positioning. Younger owners in Florida and Arizona are driving aftermarket sporty hubcap demand through direct-to-consumer channels.
- Classic:Heritage-inspired geometries with chrome and polished finishes serve restoration and premium traditionalist segments. California collector car regulations are preserving specification windows for classic-design hubcaps.
- Modern:Minimalist surfacing and matte finishes align with contemporary EV exterior design language. Scandinavian OEM design studios are influencing modern hubcap specification across European premium brands.
- Elegant:Subdued detailing and premium coating systems support luxury sedan and crossover positioning. Dubai and Riyadh luxury vehicle markets are importing elegant-design hubcaps with physical vapor deposition finishes.
Modern styling captures OEM specification share; sporty designs are expanding most quickly in aftermarket channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across procurement channels, with aftermarket buyers in mature economies resisting premium positioning while fleet operators in emerging markets prioritize unit cost above all else.
United States
EPA Corporate Average Fuel Economy standards tighten annually, compelling Detroit-based OEMs to specify lightweight aluminum hubcap designs. NHTSA wheel retention regulations mandate bolt-on configurations for heavy-duty vehicles above 6,000 pounds GVWR. Manufacturing concentrates in Michigan and Ohio, where stamping operations serve the Detroit Three assembly plants.
China
Domestic EV platform scaling by BYD and NIO generates specification pull for aerodynamic wheel covers that optimize range performance. MIIT GB standards for passenger car fuel consumption indirectly mandate aerodynamic wheel cover adoption across new vehicle platforms. Production clusters in Jiangsu and Zhejiang provinces supply both domestic OEMs and export markets.
Germany
Premium SUV and performance hatchback segments sustain demand for aluminum and semi-flush hubcap geometries. KBA certification requirements for wheel components create regulatory barriers for non-EU suppliers. Supplier engineering centers concentrate in Baden-Württemberg, serving Stuttgart-based luxury OEM assembly operations.
Mexico
Cost-sensitive fleet and rental vehicle procurement drives volume demand for snap-on plastic hubcap designs. Labor minimization priorities in commercial vehicle operations favor tool-free installation systems. Manufacturing facilities in Nuevo León and the Bajío Region export to US aftermarket distributors.
Japan
Kei-car regulations drive miniaturized hubcap specifications for sub-660cc vehicle platforms. METI industrial standards shape material certification requirements for domestic supply chains. Production concentrates in Aichi Prefecture, integrating with Toyota and Honda assembly operations in the Chubu region.
Automotive Hubcaps Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with captive aluminum smelting and integrated finishing capabilities determining competitive position. The upper tier commands specification influence through supply continuity guarantees, while mid-scale stampers face margin compression from material cost volatility. Three archetypes dominate: vertically integrated metal producers, specialist finishers with captive coating lines, and scale-driven distributors with broad SKU coverage. Competitive moves center on backward integration into primary metal production and geographic expansion through distributor acquisition.
Within the integrated producer tier, Alcoa Corporation anchors North American supply through captive smelting operations. Wheel Pros exemplifies the distributor archetype with extensive aftermarket channel coverage. Zanini Auto Grup SA occupies a position among European specialists with integrated painting capabilities serving OEM assembly plants.
| Leading Market Players |
|---|
| Wheel Pros |
| Alcoa Corporation |
| Zanini Auto Grup SA |
| CIE Automotive S.A. |
| Swell Marui Automobile Parts Co., LTD |
| Minth Group |
| Pacific Industrial Co. Ltd. |
| Dura Automotive Systems |
| Steel Technologies |
| Others |
Value Network & Pricing Analysis
Aluminum forging cost compression is simultaneously redrawing supply geography toward captive smelting regions and collapsing price premiums that once separated high-volume stampers from boutique producers. This substitution dynamic concentrates procurement leverage with OEMs while squeezing mid-tier manufacturers into scale-or-specialize decisions.
Pricing Analysis
Aftermarket parts and accessories revenue drives lifetime value capture across the hubcap value chain. Three-tier pricing structure across premium, standard, and economy levels stratifies by material certification grade and volume commitment scale. Cost compression in aluminum forgings is intensifying because Chinese EV platform scaling absorbs excess smelting capacity. Fleet operators in Mexico and Brazil exhibit highest price sensitivity, while German luxury OEMs show least elasticity for KBA-certified bolt-on systems.
Supply Chain Analysis
Strait of Malacca transit underwrites raw material flows for Asian hubcap manufacturing clusters. Primary aluminum supply draws from Russia, Canada, and China, while ABS resin feedstocks rest on petrochemical complexes in South Korea and Singapore. Single-source vulnerability concentrates in captive smelting operations subject to LME price volatility and alloy certification delays. Distribution runs through Tier 1 supplier networks into OEM assembly plants, with aftermarket channels fragmenting toward direct-to-consumer platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive hubcaps trace a cyclical recovery pattern tied to passenger car production volumes rebounding from efficiency-driven platform transitions. EPA CAFE tightening and MIIT GB standard implementation provide the cyclical driver justification.
For Market Incumbents: Secure captive aluminum supply through backward integration into primary smelting or long-term offtake agreements with Russian and Canadian producers. Reinforce specification influence by investing in integrated painting lines that satisfy REACH compliance for EU assembly plants. Full aerodynamic wheel cover substitution on premium EVs threatens conventional hubcap volume, making platform diversification into wheel cover systems essential for volume defense.
For New Entrants and Emerging Players: MIIT certification fast-track for aerodynamic wheel cover integration opens specification windows with BYD and NIO procurement teams. White-space targets concentrate in aftermarket personalization channels serving younger vehicle owners in Texas and California through direct-to-consumer configuration tools. Geographic entry should prioritize Jiangsu and Zhejiang production clusters to leverage existing EV supply chain density.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated specialists with captive finishing capabilities. Long-term viability over the next decade hinges on aluminum smelting integration and REACH-compliant coating infrastructure. Acquisition target archetype: mid-scale stampers with distressed balance sheets but intact OEM relationships. Watch aluminum LME price spreads against scrap steel volatility as the inflection indicator for margin compression severity.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Aluminum Smelting Integration | Insulates Wheel Pros and Alcoa from LME volatility and secures supply continuity for OEM contracts. |
| REACH-Compliant Coating Line Investment | Enables Zanini Auto Grup SA to maintain specification access to Stuttgart-based luxury OEM assembly plants. |
| Aerodynamic Wheel Cover Platform Development | Aligns supplier portfolios with MIIT GB standards and BYD's EV architecture procurement requirements. |
| Direct-to-Consumer Configuration Platform | Captures design-margin from younger owners in North America bypassing traditional distributor markups. |
| Cross-Border Alloy Certification Harmonization | Reduces redundant testing protocols between NHTSA, MIIT, and KBA requirements for faster product launches. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of vehicle production databases, IHS Markit registration data, customs/trade records, and SEC filings from publicly traded suppliers. Interviews with Tier 1 supplier procurement managers, OEM platform engineers, aftermarket distributors, and dealership operations heads informed demand-side validation. Bottom-up triangulation across product-type segments combined with top-down cross-checks against regional production forecasts anchored volume and value estimates.
Segmentation dimensions modeled span vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster. CAGRs were derived from regression analysis of historical shipment data against regulatory mandate implementation timelines. Forecast inputs incorporated EPA CAFE trajectory assumptions and MIIT GB standard phase-in schedules across the projection horizon.
Decision-makers should treat outputs as directional under stable aluminum smelting capacity and unchanged REACH formulation restrictions; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as EV platform scaling rates and cross-border certification reciprocity agreements evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Instrument Cluster Market
Automotive Components
United States Automotive Pneumatic Actuators Market
Automotive Components
Automotive Commutator Market
Automotive Components
Automotive Air Intake Manifold Market
Automotive Components
Automotive Gear Oil Market
Automotive Components
Automotive Exhaust Headers Market
Automotive Components
Morocco Automotive Lubricants Market
Automotive Components
Bulgaria Commercial Vehicles Lubricants Market
Automotive Components
Automotive Connecting Rod Bearing Market
Automotive Components
Africa and Middle East Automotive Pneumatic Actuators Market
Automotive Components
Global Automotive Water Valve Market
Automotive Components
Russia Automotive Pneumatic Actuators Market
Automotive Components
Automotive Lightweighting Market
Automotive Components
Russia Automotive Electric Actuators Market
Automotive Components
Automotive Active Seat Headrests Market
Automotive Components
China Automotive Composites Market