
 Electric Ship Market | 2026-2036
Electric Ship Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Ship Market Intelligence
Zero-emission certification tiers is reorganizing procurement criteria for fleet operators and defense buyers. ABB leverages its integrated powertrain portfolio to dominate port electrification infrastructure. Wärtsilä anchors hybrid system deliveries across Scandinavian ferry routes. Kongsberg Gruppen ASA specializes in autonomous-electric integration for offshore support vessels.
Electric ships integrate battery-electric, hybrid, or fuel-cell propulsion with megawatt-scale power distribution and thermal management systems for commercial and naval marine transport. Passenger vessels lead order books due to predictable routes and shore-charging access, while fuel cell electric systems represent the fastest-growing propulsion technology for long-haul cargo applications. Defense agencies concentrate procurement on silent-running battery systems for submersible and surveillance platforms.
The International Maritime Organization's carbon intensity regulations, the EU Green Deal's Fit for 55 maritime package, and Norway's NOx fund incentives collectively mandate emissions reductions across coastal fleets. These frameworks force shipyards to certify newbuilds against zero-emission standards before port access or charter eligibility. Stakeholders must monitor battery supply chain bottlenecks and hydrogen bunkering infrastructure deployment as decisive variables for fleet conversion timelines.
Market Dynamics
The International Maritime Organization's carbon intensity regulations are forcing coastal fleet operators to abandon conventional diesel propulsion before 2030 certification deadlines. Battery supply chain bottlenecks and hydrogen bunkering gaps now determine conversion feasibility more than technical readiness.
Growth Catalysts
- Norway's NOx fund:Tax rebates covering 40-60% of electric conversion costs for domestic ferry operators have compressed payback periods below five years on high-frequency routes.
- Battery energy density gains:Lithium-nickel-manganese-cobalt cell packs now deliver 300+ Wh/kg, enabling 50 nautical mile all-electric ranges without cargo space sacrifice.
- EU Green Deal maritime package:Mandatory shore-power connectivity at TEN-T core ports by 2030 guarantees charging infrastructure for short-sea vessels.
Market Restraints
- Lithium supply concentration:Australian hard-rock and Chilean brine operations control 70%+ of battery-grade lithium carbonate, exposing shipyards to price volatility and offtake competition from automotive buyers.
- High-voltage certification gaps:Classification societies lack unified standards for megawatt-scale DC distribution above 1,500V, fragmenting approval timelines across Lloyd's Register, DNV, and Bureau Veritas.
- Green methanol substitution threat:Maersk and CMA CGM's dual-fuel newbuild commitments for long-haul container routes divert R&D investment from pure electric architectures.
Strategic Opportunities
- Indonesia archipelago routes:17,000+ islands with sub-100nm inter-island distances present untapped demand for battery-electric passenger and cargo vessels without hydrogen infrastructure dependency.
- Autonomous-electric convergence:Kongsberg's remote-operated vessel systems paired with zero-crew powertrains enable 24-hour continuous operations on repetitive ferry corridors.
- US Inflation Reduction Act harbor craft credits:Section 45W clean commercial vehicle incentives now extend to tugboats and pilot boats, accelerating California and Washington state fleet conversions.
Industry Challenges
- Marine electrical engineering talent scarcity:Shipyards report 18-month recruitment cycles for power electronics specialists capable of integrating silicon carbide inverters with maritime cooling systems.
- Retrofit capex intensity:Converting existing Ro-Pax vessels requires hull cutting for battery compartment flooding and structural reinforcement, consuming 60-70% of newbuild electric premiums without greenfield design optimization.
- Multi-class society approval complexity:Vessels operating across Norwegian, German, and Polish waters face conflicting national interpretations of the IGF Code for low-flashpoint fuels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Ship Market |
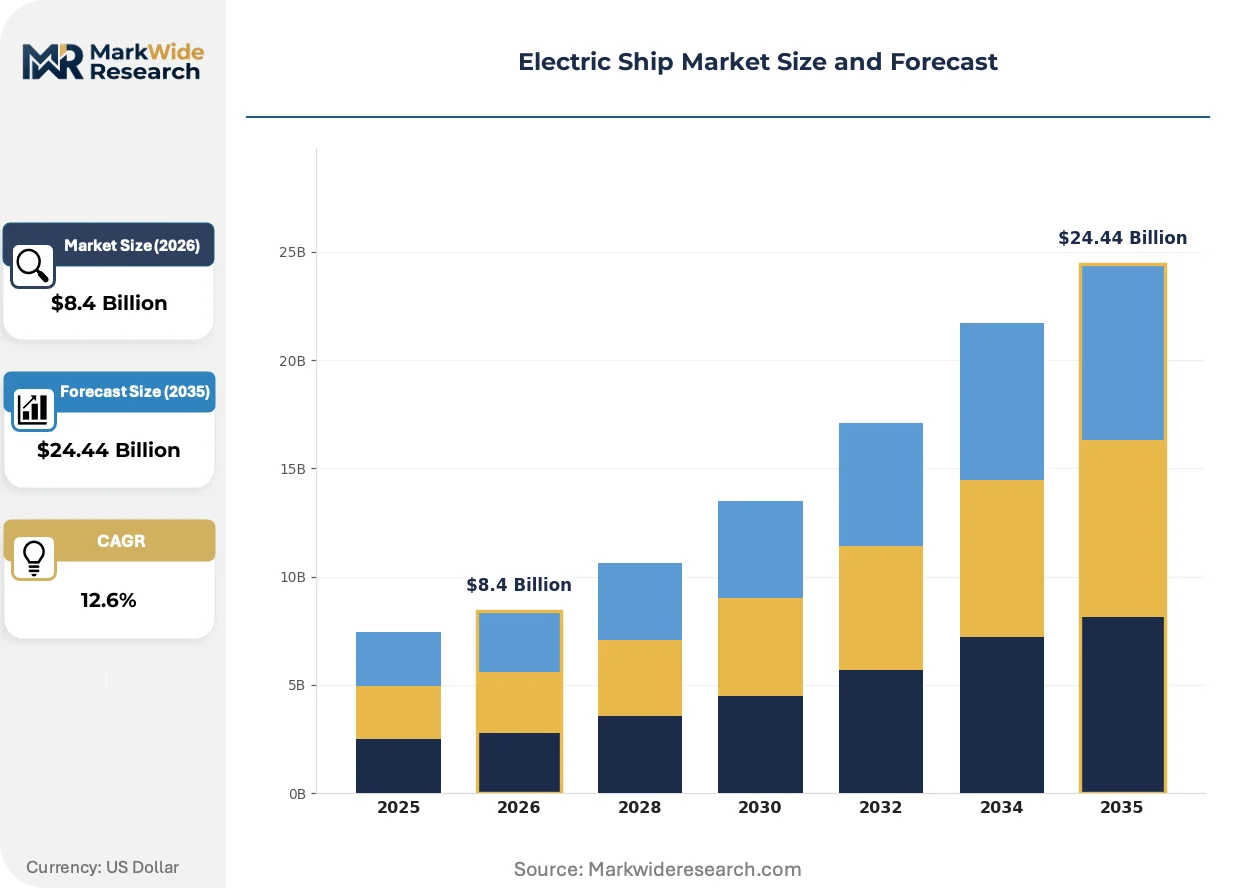
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $24.44 Billion |
| CAGR (2026 – 2036) | 12.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Ship Type: Passenger Vessels, Cargo Ships, Military Vessels, Research Vessels, Fishing Boats Propulsion Technology: Battery Electric, Hybrid Electric, Fuel Cell Electric, Solar Assisted, Supercapacitor Enhanced Application: Coastal Transport, Offshore Support, Naval Operations, Scientific Exploration, Aquaculture Support End User: Shipping Companies, Defense Agencies, Research Institutions, Aquatic Farms, Port Authorities |
| Companies Covered | ABB, Siemens, Wärtsilä, Kongsberg Gruppen ASA, Corvus Energy, Rolls-Royce, General Dynamics Electric Boat, VARD AS, Leclanché, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Ship Market Strategic Shifts & Innovations
Solid-state battery architectures and fuel-cell range extenders are bifurcating propulsion roadmaps for coastal versus deep-sea applications. Shipyards must now certify against dual technology stacks rather than incremental diesel-electric hybrids.
Silicon carbide power electronics are displacing silicon IGBT modules in main propulsion drives above 3MW. Norwegian ferry operators Yxney and Bastø Fosen have specified SiC-based drives for 2024-2026 deliveries, cutting switching losses by 40% and enabling air-cooled transformer rooms that reclaim 8-12% of engine room volume for passenger or cargo use. This displacement is compressing auxiliary system footprints and eliminating seawater cooling loops in battery compartments.
The EU's Fit for 55 maritime package mandates shore-side electricity at all major ports by 2030, with non-compliant vessels facing berth access restrictions. German and Dutch port authorities are accelerating grid reinforcement projects at Hamburg, Rotterdam, and Bremerhaven to handle 20MW+ simultaneous vessel loads. Short-sea container feeders and cruise overnight stays face the steepest compliance costs, driving consolidation onto electrified terminal routes.
Charter contracts now specify carbon intensity per ton-mile rather than fuel consumption alone. Greek and Singapore-based shipowners are rewriting tender documents for offshore support vessels to require EU MRV-verified zero-emission operation during port standby periods. This behavioral shift is visible most acutely in the North Sea oilfield services market, where Equinor and Shell procurement teams have disqualified non-hybrid bids from 2025 onwards.
Electric Ship Market Segmentation
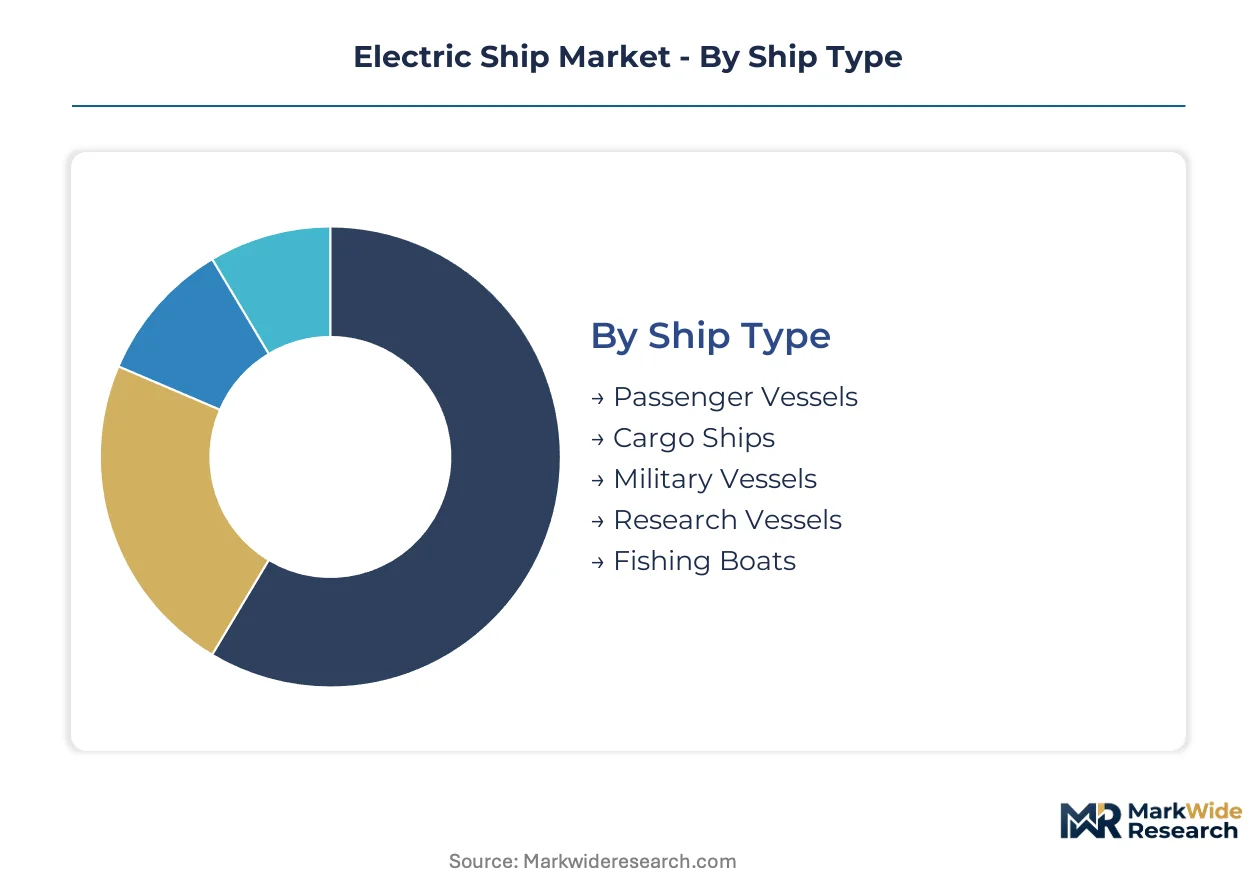
Electric ship procurement patterns diverge sharply across vessel categories, propulsion architectures, and operational missions. Regulatory pressure from the EU Green Deal and IMO carbon intensity rules forces fleet operators to match segment-specific technologies against route profiles and certification requirements.
Ship Type:
Norway's NOx fund and EU port access restrictions create tiered compliance obligations that reshape order book composition across vessel categories.
- Passenger Vessels:Ferries and coastal cruise ships dominate current electrification due to predictable schedules and shore-charging availability. Norwegian operators Bastø Fosen and Fjord1 have specified all-electric designs for fjord routes under strict zero-emission mandates from the country's maritime regulator.
- Cargo Ships:Short-sea container feeders and Ro-Ro vessels face the steepest berth access penalties under EU Fit for 55 rules, accelerating hybrid retrofits at German and Dutch terminals. Long-haul bulk carriers remain diesel-dependent pending hydrogen bunkering infrastructure.
- Military Vessels:Silent-running battery systems for submersible and surveillance platforms concentrate procurement among defense agencies prioritizing acoustic signature reduction over range.
- Research Vessels:Ice-class scientific ships in Arctic waters specify diesel-electric hybrids with battery load-leveling for station-keeping operations.
- Fishing Boats:Small-scale coastal trawlers in Baltic Sea corridors adopt battery-electric propulsion for day-trip durations under 12 hours.
Established volume favors passenger vessels; emerging adoption favors cargo ships.
Propulsion Technology:
Energy density thresholds and infrastructure availability determine which powertrain architectures win specific route assignments.
- Battery Electric:Lithium-nickel-manganese-cobalt packs delivering 300+ Wh/kg now enable 50 nautical mile all-electric ranges without cargo space sacrifice. Norwegian ferry operators specify these systems for high-frequency domestic routes where shore-charging intervals align with turnaround schedules.
- Hybrid Electric:Diesel-electric architectures with battery peak-shaving dominate retrofit economics for existing Ro-Pax fleets. German shipyards report 60-70% cost premiums versus newbuilds due to hull cutting and structural reinforcement requirements.
- Fuel Cell Electric:Expanding most quickly for long-haul cargo applications where hydrogen bunkering infrastructure exists. EU Green Deal funding accelerates pilot deployments at Rotterdam and Hamburg terminals.
- Solar Assisted:Photovoltaic deck arrays supplement auxiliary loads on scientific exploration vessels with extended station-keeping requirements.
- Supercapacitor Enhanced:Rapid-charge buffers enable 10-minute turnaround capabilities for high-frequency Indonesian archipelago ferries with sub-100nm inter-island distances.
Deployment scale currently favors battery electric; infrastructure buildout favors fuel cell electric.
Application:
Route predictability and shore-side power access separate commercially viable electrification from pilot-phase technologies.
- Coastal Transport:Short-sea shipping between EU TEN-T core ports benefits from mandatory shore-power connectivity requirements. Container feeders and cruise overnight stays face immediate compliance deadlines.
- Offshore Support:North Sea oilfield services procurement now disqualifies non-hybrid bids from Equinor and Shell tender processes for platform supply vessels.
- Naval Operations:Submersible surveillance platforms prioritize silent battery propulsion for littoral zone operations.
- Scientific Exploration:Autonomous underwater vehicle support ships integrate Kongsberg remote-operated systems with zero-crew powertrains for 24-hour continuous survey operations.
- Aquaculture Support:Fish farm service vessels in Norwegian coastal waters adopt small-scale electric outboards for net maintenance and feed delivery.
Regulatory certainty favors coastal transport; technology demonstration favors offshore support.
End User:
Procurement authority and capital access determine electrification pace across buyer categories.
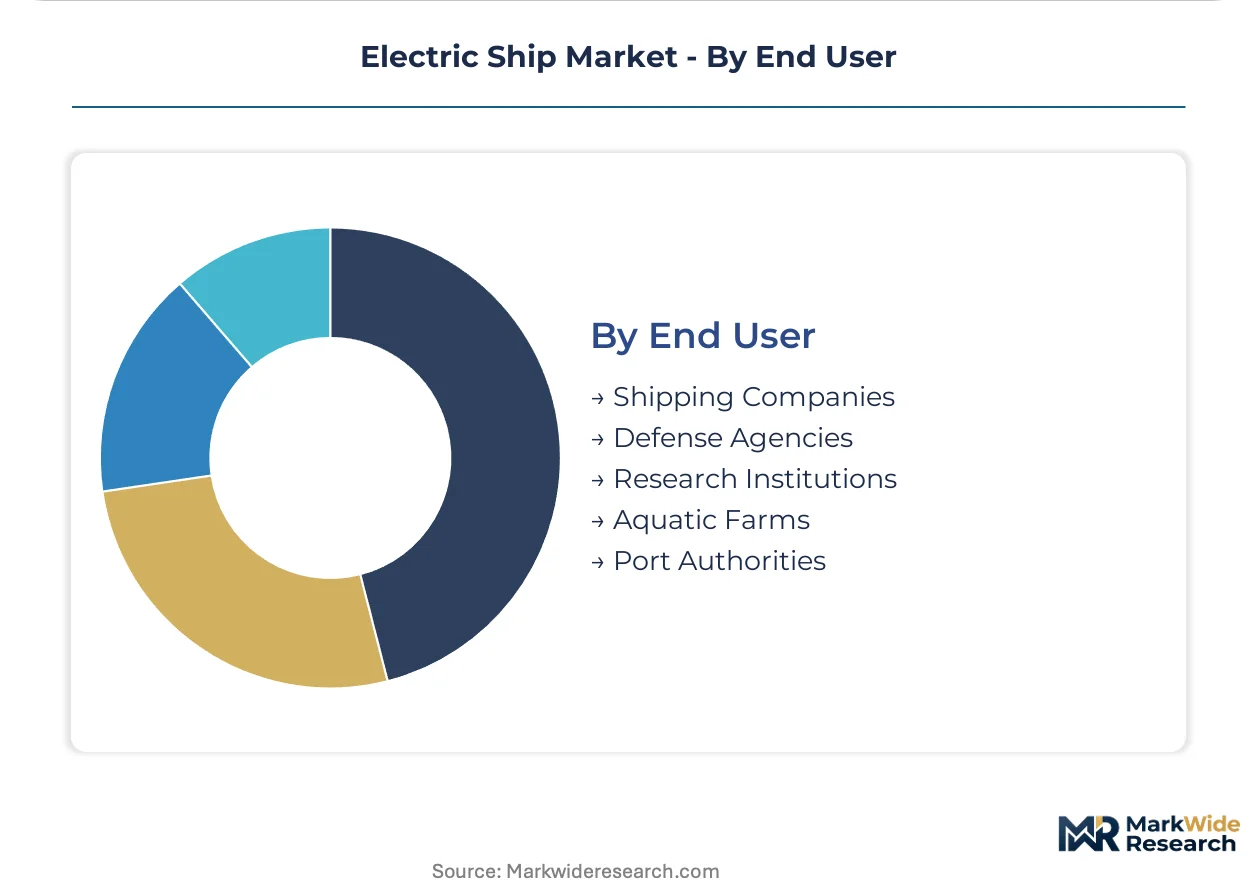
- Shipping Companies:Greek and Singapore-based shipowners rewrite charter contracts to specify carbon intensity per ton-mile, forcing fleet managers to certify EU MRV-verified zero-emission operation during port standby periods.
- Defense Agencies:US Navy and NATO maritime commands concentrate R&D spending on silent-running battery systems for mine countermeasures and special operations craft.
- Research Institutions:Arctic and Antarctic programs specify ice-class diesel-electric hybrids with extended autonomy for remote station resupply.
- Aquatic Farms:Norwegian salmon producers leverage NOx fund rebates for electric workboat conversions at processing facilities.
- Port Authorities:Hamburg, Rotterdam, and Bremerhaven operators accelerate grid reinforcement to handle 20MW+ simultaneous vessel loads under EU Fit for 55 mandates.
Capital availability favors shipping companies; subsidy dependence favors aquatic farms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances in battery cell supply chains and hydrogen bunkering equipment concentrate electric ship development in coastal manufacturing clusters. Norway, Germany, China, the United States, and Indonesia each anchor distinct segments of the value chain through regulatory incentives and port infrastructure commitments.
Norway
Domestic ferry electrification and fjord tourism routes drive vessel demand along western coastal corridors. The NOx fund administered by the country's environmental tax authority covers 40-60% of conversion costs for operators on high-frequency routes. Bergen and Stavanger shipyards specialize in battery-electric newbuilds for Bastø Fosen and Fjord1 fleets serving UNESCO-protected waterways.
Germany
Short-sea container feeders and Ro-Pax retrofits dominate order books at Hamburg and Bremerhaven terminals. The EU Green Deal's Fit for 55 maritime package mandates shore-power connectivity at core ports by 2030, forcing fleet operators to electrify or face berth restrictions. German shipyards report compressed approval timelines for hybrid systems serving North Sea-Baltic Sea corridors.
China
Battery manufacturing scale and port electrification investments position the Yangtze River Delta as a production hub for electric propulsion components. The country's dual carbon goals accelerate coastal vessel conversion timelines along the Pearl River Delta container feeder network. Shanghai and Ningbo port authorities deploy megawatt-scale shore charging for short-sea routes.
United States
Defense procurement for silent-running submersible platforms and harbor craft electrification drive dual-use technology development. The Inflation Reduction Act's Section 45W clean commercial vehicle credits extend to tugboats and pilot boats, accelerating California and Washington state fleet conversions. Pacific Northwest shipyards specialize in autonomous-electric integration for naval applications.
Indonesia
Archipelago geography with sub-100 nautical mile inter-island distances creates natural demand for battery-electric vessels without hydrogen infrastructure dependency. The national port authority prioritizes electrification of Java-Sumatra ferry corridors serving 17,000+ islands. Surabaya and Makassar operators pilot supercapacitor-enhanced systems for 10-minute turnaround capabilities on high-frequency routes.
Electric Ship Market Key Industry Players
Listed leaders compete with private specialists across integrated powertrain and battery system domains. The vendor base organizes around three tiers: diversified industrial conglomerates with maritime divisions, pure-play battery system engineers, and shipyard-integrated propulsion specialists. Strategic moves concentrate on port electrification infrastructure partnerships and silicon carbide power electronics licensing agreements.
Among Nordic integrated system providers, ABB, Wärtsilä, and Kongsberg Gruppen ASA represent distinct archetypes within the competitive structure. ABB exemplifies the diversified conglomerate model with cross-sector power electronics capabilities. Wärtsilä occupies a position as the shipyard-integrated hybrid specialist with Scandinavian ferry route dominance. Kongsberg Gruppen ASA anchors the autonomous-electric convergence tier, pairing remote vessel operation with zero-crew powertrain architectures.
| Leading Market Players |
|---|
| ABB |
| Siemens |
| Wärtsilä |
| Kongsberg Gruppen ASA |
| Corvus Energy |
| Rolls-Royce |
| General Dynamics Electric Boat |
| VARD AS |
| Leclanché |
| Others |
Cost & Logistics Intelligence
The EU Green Deal's Fit for 55 maritime package gates both battery system qualification and price differentiation across European ferry operators and port authorities. Certification against zero-emission standards determines berth access eligibility, compressing procurement timelines and amplifying premiums for pre-qualified suppliers.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake pricing for megawatt-scale battery packs and silicon carbide power electronics. Price differentiation separates IMO-certified zero-emission systems from transitional hybrid architectures, with volume scale and after-sales service bundling as secondary tiering factors. Cost compression in retrofit projects intensifies as shipyards compete for limited NOx fund allocations. Charter operators demonstrate highest price sensitivity due to thin margins on short-sea routes, while defense agencies absorb premiums for silent-running specifications.
Supply Chain Analysis
Port congestion at Rotterdam and Hamburg elevates inbound logistics costs for Korean and Japanese battery cell shipments destined for Scandinavian shipyards. Manufacturing concentrates in China, South Korea, and Norway, with lithium-nickel-manganese-cobalt cathodes, silicon carbide wafers, and maritime-grade power cables as critical inputs. Single-source vulnerability in Australian hard-rock lithium extraction threatens production schedules. Distribution runs through shipyard-integrated propulsion specialists rather than independent component distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The electric ship market sits in early-cycle expansion as battery energy density thresholds cross commercial viability for 50-nautical-mile routes. Norway's fjord electrification mandates and the EU's shore-power deadlines create irreversible demand pull.
For Market Incumbents: Shield integrated powertrain margins by securing captive lithium offtake agreements before automotive buyers lock supply. Accelerate certification investment for megawatt-scale DC distribution above 1,500V to preempt classification society fragmentation. Green methanol dual-fuel commitments from container line operators threaten pure-electric R&D budgets.
For New Entrants and Emerging Players: After-sales software layers for predictive battery health monitoring represent underserved white space where incumbents under-serve. Target Indonesian archipelago ferry operators with supercapacitor-enhanced systems for 10-minute turnaround requirements. Pursue port authority partnerships for grid reinforcement project integration.
For Investors and Strategic Acquirers: The EU's 2030 shore-power mandate reshapes the acquisition landscape toward battery system engineers with proven maritime thermal management. Long-term viability centers on suppliers with backward integration into cell chemistry and cooling system IP. Monitor hydrogen bunkering infrastructure deployment at Rotterdam and Hamburg as the decisive inflection signal for fuel cell electric adoption curves.
| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Power Electronics Licensing | Norwegian ferry operators Yxney and Bastø Fosen specify SiC drives for 40% switching loss reduction. |
| Port Electrification Infrastructure Partnership | German and Dutch authorities at Hamburg and Rotterdam accelerate 20MW+ grid reinforcement projects. |
| Autonomous-Electric System Integration | Kongsberg pairs remote vessel operation with zero-crew powertrains for 24-hour continuous ferry corridors. |
| Battery Supply Agreement with Mining Consortium | Australian hard-rock and Chilean brine lithium concentration creates offtake competition from automotive buyers. |
| Zero-Emission Certification Pre-Qualification | IMO carbon intensity regulations force certification against zero-emission standards before port access eligibility. |
Research Approach
The analysis maps battery-electric, hybrid-electric, and fuel cell electric propulsion architectures, each validated through shipyard procurement directors, ferry fleet operators, classification society surveyors, and port authority infrastructure planners. Primary interviews with stakeholders combine with secondary validation from Lloyd's Register filings, DNV technical reports, EU TEN-T port development databases, and IMO Marine Environment Protection Committee submissions. Bottom-up vessel order book aggregation and top-down regulatory mandate sizing enable triangulation.
Consistency checks against external benchmarks validate volume and value outputs across the projection horizon. Segmentation dimensions modeled include ship type, propulsion technology, application mission, and end-user procurement authority. CAGRs derive from route electrification timeline analysis and battery cost curve trajectories. Forecast inputs incorporate NOx fund allocation schedules and EU Green Deal compliance deadline phasing.
Forecasts assume regulatory continuity in EU Green Deal maritime packages and Norway's NOx fund mechanisms; material policy shifts would require re-modeling. Battery supply chain bottlenecks and hydrogen bunkering infrastructure delays represent specific risk factors that could compress or extend fleet conversion timelines. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine
Marine Chartplotter Market
Marine
Boat Cleat Market
Marine
Marine Propeller Market
Marine
Marine Electronics Market
Marine
Steel Ship Plate Market
Marine
Rescue Boats Market
Marine
Europe Marine Communication Systems Market
Marine
Ship/Boat Keel Market
Marine
Marine Fin Stabilizer Market
Marine
Marine Dynamic Positioning System Market
Marine
Shipbuilding Market
Marine
Marine Gas Oil Market
Marine
LNG Bunkering Vessel Market
Marine
Azimuth Thrusters Market
Marine
Sea Scooter Market
Marine
Jet Boat Market