
 Automotive Defroster Market | 2026-2036
Automotive Defroster Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Defroster Market Analysis
Asset-light manufacturing partnerships is narrowing the capital barrier for aftermarket defroster specialists seeking OEM contracts. Denso Corporation leverages its thermal systems integration expertise to sustain dominance in factory-installed heated windshields. Valeo SA anchors its position through European OEM supply relationships for electric defroster modules. Robert Bosch GmbH competes on sensor-integrated defrost controls that merge climate management with driver assistance systems.
An automotive defroster is a thermal management subsystem that removes ice, frost, and condensation from vehicle glazing through resistive heating elements, forced air convection, or infrared radiation, typically operating at 12V or 48V in conventional architectures and up to 800V in high-voltage EV platforms. Its primary purpose is to maintain optical clarity for operator safety and regulatory compliance under low-temperature operating conditions. PTC Heating technology leads the technology dimension due to its self-regulating thermal output and compatibility with EV electrical architectures, while Infrared defrost systems represent the fastest-growing segment as OEMs seek faster response times and reduced energy draw. The End User dimension concentrates margin pools with OEMs, where long-term supply agreements and platform-specific engineering requirements create high switching costs for vehicle assemblers.
NHTSA Federal Motor Vehicle Safety Standard 103 governs windshield defrosting performance in the United States, while the EU Green Deal and REACH frameworks restrict certain resistive materials and mandate lifecycle assessments for thermal components sold in Europe. These regulations shape demand by forcing material substitutions and energy-efficiency thresholds that favor electric and infrared technologies over conventional convection systems. Stakeholders must monitor how evolving battery-electric platform voltages redefine heating element specifications and supplier qualification requirements.
Market Dynamics
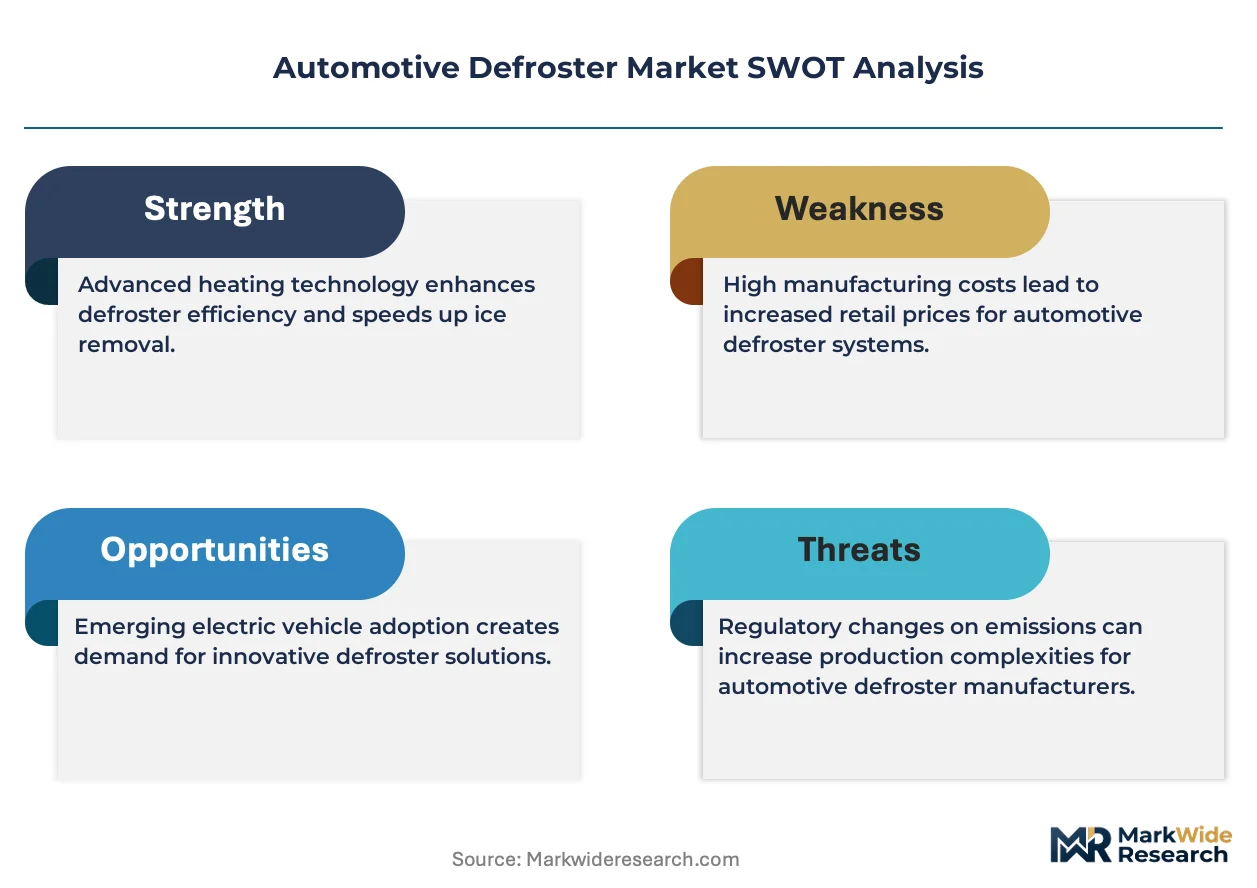
Electrification of vehicle platforms is forcing a wholesale redesign of defroster architectures, as 800V battery systems render legacy 12V resistive heating elements obsolete and demand new thermal management integration strategies.
Growth Catalysts
- NHTSA Federal Motor Vehicle Safety Standard 103:Mandates minimum windshield clearing performance, compelling OEMs to upgrade defroster specifications across all vehicle classes sold in the United States.
- PTC heating elements:Offer self-regulating thermal output that eliminates thermal runaway risk in high-voltage EV architectures, accelerating adoption by electric vehicle platforms.
- German automotive OEMs:Drive supplier investment through platform-specific engineering requirements for integrated heated windshields on premium EV models.
Market Restraints
- Copper and silver price volatility:Resistive heating elements depend on conductive metal films, exposing manufacturers to commodity input cost swings.
- Supply concentration in East Asian substrate suppliers:Transparent conductive oxide coatings for heated windshields rely on a narrow supplier base concentrated in China and South Korea.
- Technical limitation of infrared wavelength penetration:Infrared defrost systems struggle with thick ice accumulation, restricting deployment to mild-climate vehicle specifications.
Strategic Opportunities
- EU Green Deal decarbonization mandates:Create regulatory tailwind for energy-efficient infrared defrost technologies that reduce electrical draw versus conventional convection systems.
- Commercial fleet electrification:Opens white space for heavy-duty defroster modules designed for electric buses and delivery vehicles with continuous-duty thermal requirements.
- Convergence of defrost controls with ADAS sensors:Enables integrated climate-vision systems where thermal management and camera clearing merge into unified modules.
Industry Challenges
- High-voltage electrical safety certification:Engineers with 800V system qualification remain scarce, extending product development timelines for EV defroster programs.
- Legacy HVAC integration complexity:New electric defroster modules must interface with existing cabin climate software architectures, creating validation bottlenecks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Defroster Market |
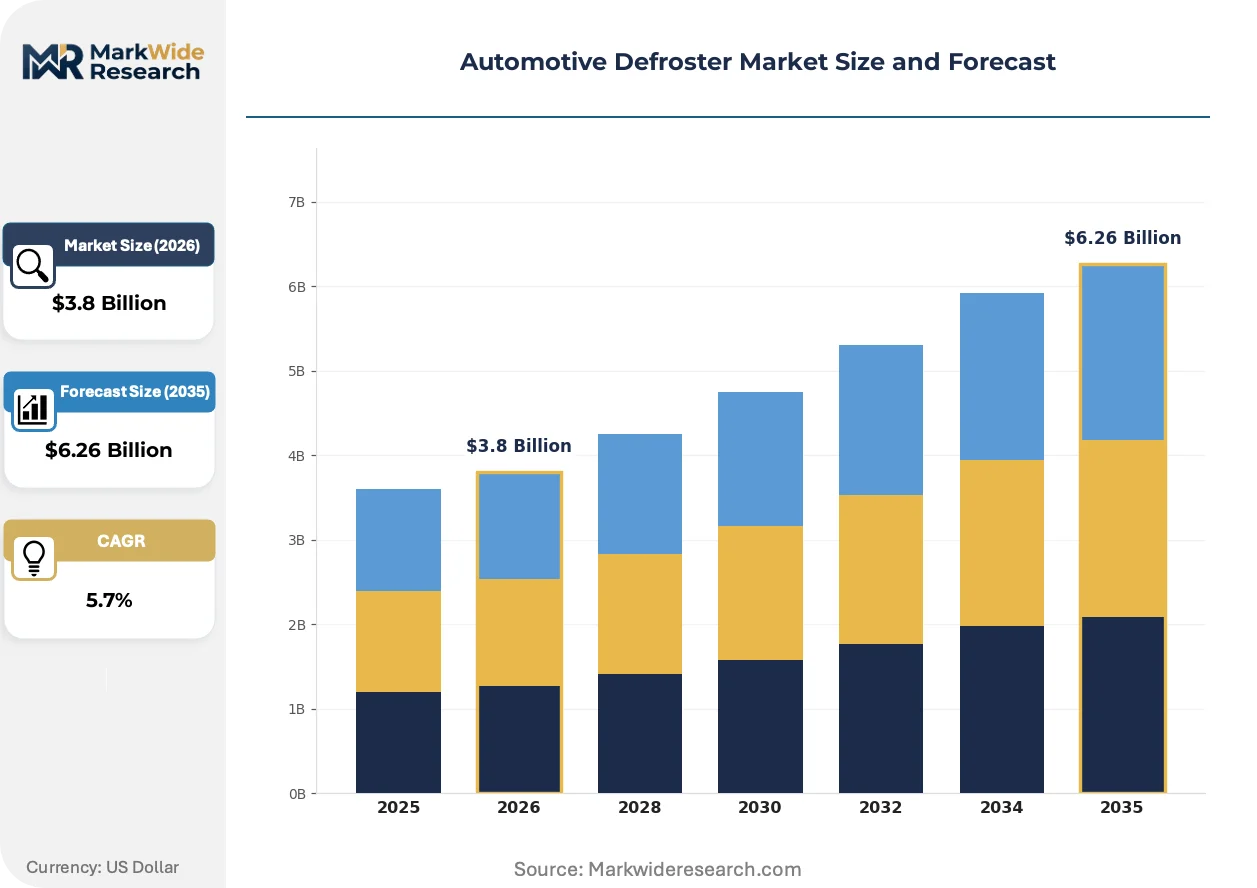
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hot Air Defroster, Electric Defroster, Heated Windshield, Auxiliary Heater Technology: Infrared, Convection, Radiant Heating, PTC Heating End User: OEMs, Aftermarket Providers, Dealerships, Vehicle Assemblers Installation: Factory Installed, Retrofit, Mobile Installations, DIY Kits |
| Companies Covered | Denso Corporation, Valeo SA, Robert Bosch GmbH, Continental AG, Mahle GmbH, Gentherm Incorporated, NXP Semiconductors, Toyoda Gosei, Henkel AG & Co. KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Defroster Market Emerging Trajectories
Defroster technology is bifurcating between incremental efficiency gains in conventional systems and disruptive architectural shifts enabled by high-voltage electrification and smart materials.
Transparent conductive film technology is digitizing windshield heating control through pixel-level thermal zoning. Tier 1 suppliers are embedding microelectrode arrays that enable variable heat distribution based on real-time condensation mapping. This capability is digitizing the transition from binary on-off defrost cycles to precision thermal management that preserves battery range.
REACH framework restrictions on certain resistive metal oxides are forcing material substitutions across European supply chains. ECHA substance evaluations have flagged legacy heating element coatings, compelling reformulation of conductive films. German and French OEMs are responding by qualifying alternative transparent conductor stacks ahead of anticipated substance authorization deadlines.
Fleet procurement of defroster systems is consolidating around total-cost-of-ownership metrics rather than unit price. Large commercial vehicle operators are negotiating lifecycle service agreements that bundle heating element replacement with predictive maintenance analytics. This behavioral shift is most visible in Nordic markets where winter operating conditions drive aftermarket service demand and remote diagnostics adoption.
Automotive Defroster Market Segmentation
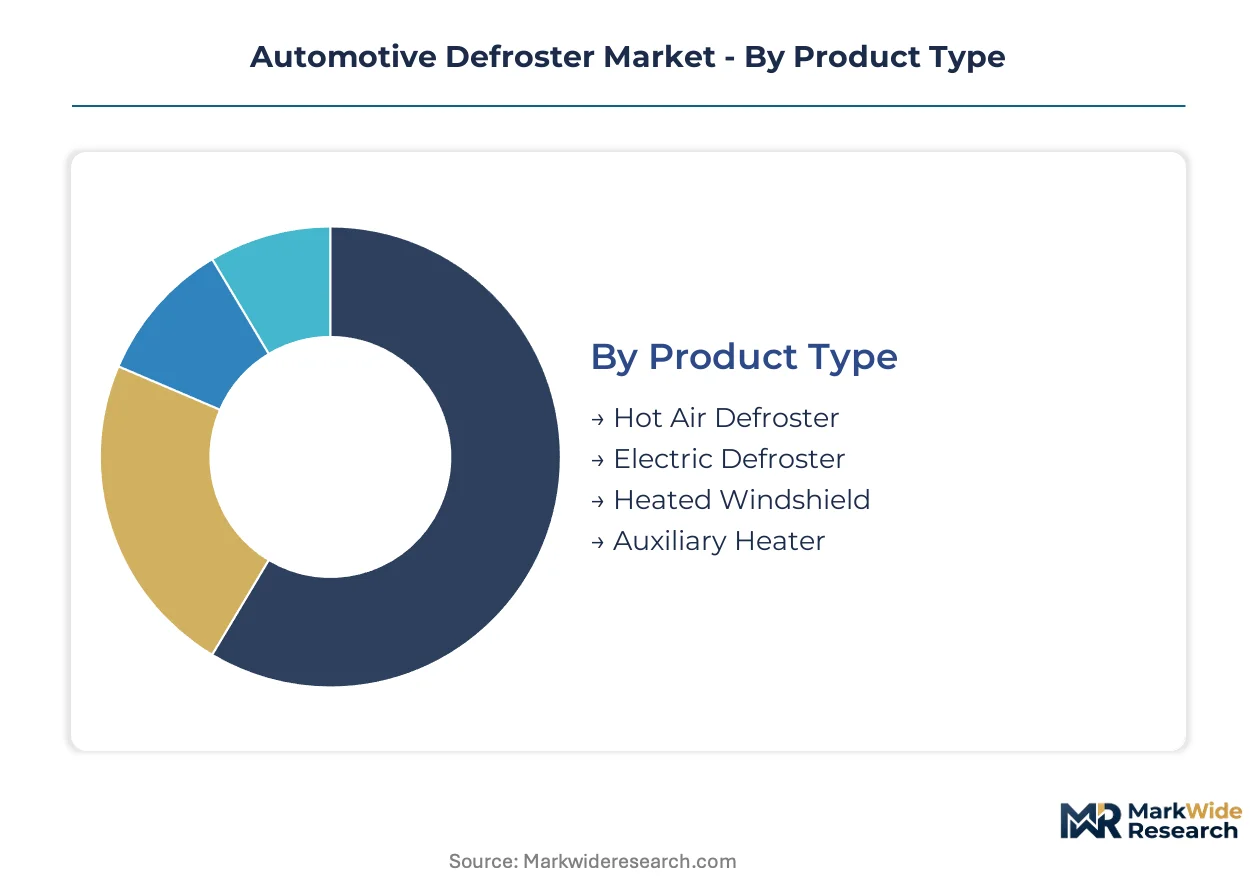
Defroster market segmentation reveals how thermal management requirements diverge across vehicle electrification levels, regulatory environments, and supply chain integration models. Understanding these divisions exposes where margin pools concentrate and which technology transitions command capital allocation.
Product Type:
Vehicle thermal architectures span forced-air legacy systems through integrated glazing solutions, with electrification forcing a fundamental recalibration of which configurations deliver regulatory-compliant performance per watt.
- Hot Air Defroster:Engine-coolant-based forced convection systems channel heated air through dashboard vents. ICE vehicle platforms in Germany and the United States retain this configuration for cost-engineered segments where battery preservation is not a design constraint.
- Electric Defroster:Resistive wire grids embedded in rear windows and mirror housings operate at 12V or 48V. Demand concentrates with Japanese and South Korean OEMs seeking component commonality across hybrid and mild-hybrid lineups.
- Heated Windshield:Transparent conductive oxide films laminated between glass layers enable rapid ice clearance without airflow. Premium EV platforms in Sweden and Norway specify this technology for cabin efficiency.
- Auxiliary Heater:Standalone fuel-fired or electric units supplement primary thermal systems in commercial vehicles. Nordic bus operators deploy these for cold-soak startup scenarios.
Established volume favors hot air defrosters; emerging adoption favors heated windshields.
Technology:
Energy conversion efficiency and voltage compatibility now dominate supplier qualification, with REACH substance restrictions and 800V platform proliferation rewriting material specifications.
- Infrared:Electromagnetic radiation at 3-15 μm wavelengths penetrates ice molecular bonds directly. French and Italian OEMs specify infrared for luxury EVs where defrost speed preserves battery range.
- Convection:Airflow-driven heat transfer from HVAC cores maintains dominance in mass-market ICE vehicles. Cost engineering at Volkswagen and Stellantis sustains this technology's installed base.
- Radiant Heating:Surface-mounted resistive elements on interior glass faces provide zonal control. Aftermarket specialists in Canada supply these for classic vehicle restorations.
- PTC Heating:Positive temperature coefficient ceramics self-limit current draw as temperature rises. Bosch and Valeo qualify these for 400V and 800V battery-electric architectures.
PTC heating captures the steepest expansion trajectory as high-voltage platforms scale.
End User:
Procurement authority and lifecycle responsibility determine contract structures, with platform-specific engineering requirements creating divergent supplier relationship models.
- OEMs:Vehicle manufacturers specify defroster performance thresholds and thermal integration protocols. Long-term supply agreements with Denso and Valeo lock in heated windshield capacity for multi-platform programs.
- Aftermarket Providers:Independent distributors serve collision repair and winterization upgrade demand. Canadian and Finnish distributors stock retrofit kits for pickup truck fleets.
- Dealerships:Authorized service channels handle warranty defroster repairs and technology retrofits. German dealership groups bundle heated windshields with EV lease packages.
- Vehicle Assemblers:Contract manufacturers without full OEM status procure defroster modules to customer specification. Magna Steyr integrates PTC systems for outsourced EV production.
Margin concentration sits with OEMs; growth velocity favors aftermarket providers.
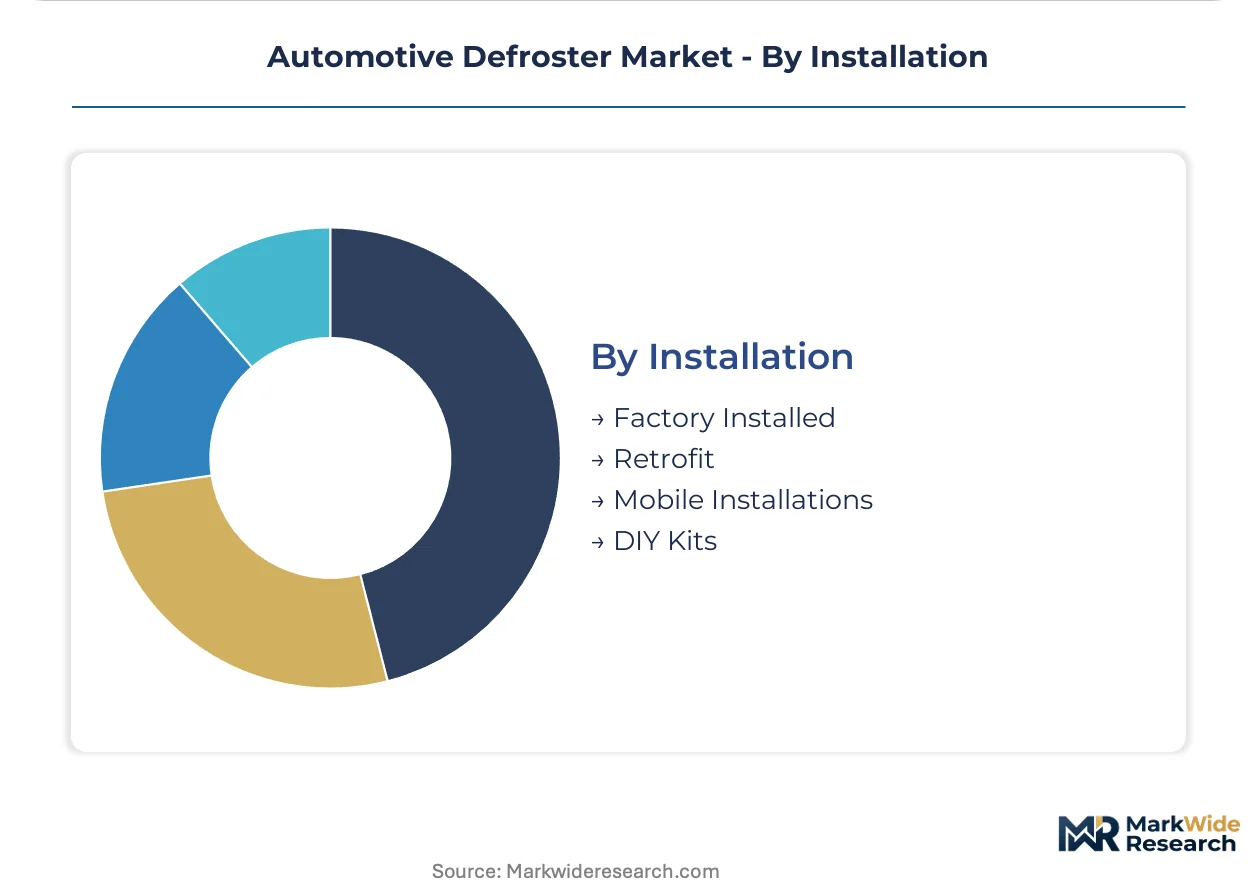
Installation:
Supply chain positioning and liability exposure separate factory-integrated systems from field-deployed alternatives, with certification requirements widening the capability gap.
- Factory Installed:Windshield laminators embed conductive films during glass production. AGC and Saint-Gobain operate dedicated lines for German and US OEM heated windshield programs.
- Retrofit:Post-assembly upgrades replace standard glass with heated equivalents. Swedish specialists serve taxi fleets requiring rapid ice clearance for regulatory compliance.
- Mobile Installations:Service technicians perform defroster repairs at fleet depots. US commercial vehicle operators contract mobile HVAC services for seasonal preparation.
- DIY Kits:Consumer-grade resistive elements attach to existing glass with adhesive backing. E-commerce channels in Poland and Czech Republic move these for aging vehicle populations.
Factory installation commands value capture; retrofit channels address replacement demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in automotive defroster components track the geographic distribution of electric vehicle assembly capacity, with surplus heated windshield production in Germany and Japan supplying deficit markets in North America and emerging Asian economies.
United States
NHTSA Federal Motor Vehicle Safety Standard 103 enforcement drives OEM specification upgrades for windshield clearing performance across passenger and commercial vehicle segments. The Inflation Reduction Act's domestic content incentives accelerate supplier localization for EV thermal management subsystems. Michigan and Ohio industrial corridors concentrate heated windshield laminator investments serving Detroit-based OEM electrification programs.
Germany
KBA type-approval requirements for 800V electrical safety certification shape supplier qualification protocols for high-voltage defroster architectures. EU Green Deal decarbonization mandates prioritize energy-efficient PTC and infrared technologies over conventional convection systems in platform engineering decisions. Stuttgart and Munich automotive clusters anchor heated windshield R&D capacity for premium EV models targeting Nordic and Alpine operating conditions.
China
MIIT new energy vehicle production quotas expand addressable demand for 400V and 800V compatible defroster modules across domestic OEM lineups. GB standards for electrical safety in high-voltage passenger vehicles establish conformance baselines for resistive heating element designs. Yangtze River Delta transparent conductive oxide suppliers scale capacity to serve both domestic EV assemblers and export markets for heated windshield substrates.
Japan
METI carbon neutrality roadmaps for automotive manufacturing prioritize thermal efficiency in cabin climate system specifications for next-generation platforms. JIS standards for vehicle electrical components govern defroster element durability testing protocols under extreme temperature cycling. Toyota City and Hiroshima production basins integrate PTC heating expertise from hybrid program heritage into dedicated battery-electric defroster architectures.
South Korea
MFDS-equivalent vehicle safety administration aligns defroster performance certification with UN ECE regulations for export market access. Government EV subsidy programs with domestic component sourcing requirements channel procurement toward local heated windshield and PTC module suppliers. Seoul Capital Area and Busan-Ulsan industrial zones concentrate thermal management subsystem production for Hyundai-Kia global EV platform rollouts.
Automotive Defroster Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in the supply chain. The market exhibits tiered concentration, with a handful of thermal management conglomerates controlling factory-installed heated windshield capacity while fragmented substrate and control module suppliers populate lower-margin segments. Two strategic archetypes dominate: vertically integrated automotive suppliers with climate system heritage, and glass laminators with conductive film deposition expertise. Competitive dynamics center on long-term OEM supply agreement renewals and high-voltage electrical safety certification races for 800V platform qualification.
Among Japanese-origin conglomerates, Denso Corporation and Toyoda Gosei occupy positions reflecting thermal systems integration heritage. German industrial groups Continental AG and Robert Bosch GmbH exemplify the vertically integrated archetype spanning control electronics through heating element assembly. French-listed Valeo SA represents European OEM supply relationship depth in electric defroster modules. Gentherm Incorporated anchors North American specialist positioning in climate comfort subsystems. NXP Semiconductors sits within the semiconductor tier supplying defrost control ICs, while Mahle GmbH and Henkel AG & Co. KGaA represent German engineering and materials science competencies respectively.
| Leading Market Players |
|---|
| Denso Corporation |
| Valeo SA |
| Robert Bosch GmbH |
| Continental AG |
| Mahle GmbH |
| Gentherm Incorporated |
| NXP Semiconductors |
| Toyoda Gosei |
| Henkel AG & Co. KGaA |
| Others |
Supply Flow & Price Mechanics
Single-source dependency on Yangtze River Delta transparent conductive oxide suppliers determines both the three-tier pricing structure across premium, standard, and economy levels and the geographic concentration of heated windshield laminator capacity. Copper and silver price volatility in resistive heating element manufacturing feeds directly into contract renegotiation cycles for OEM supply agreements.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake pricing for heated windshield modules, with premium tiers commanding ISO 26262 functional safety certification and 800V electrical safety validation. Price differentiation separates PTC heating architectures from legacy convection systems through energy efficiency metrics and platform integration complexity. Cost compression in standard-tier hot air defrosters is intensifying because Stellantis and Volkswagen procurement teams are consolidating supplier bases across ICE vehicle programs. Aftermarket retrofit providers exhibit the highest price sensitivity due to thin margin structures and spot-market substrate purchasing.
Supply Chain Analysis
Tariff exposure between China and the United States dominates strategic planning for transparent conductive oxide sourcing, forcing German and Japanese OEMs to qualify alternative substrate suppliers in South Korea and Taiwan. Heated windshield production draws from indium tin oxide films, silver nanowire coatings, and microelectrode arrays as critical component inputs. Single-source vulnerability concentrates in East Asian glass laminators with conductive film deposition expertise. Distribution runs through Tier 1 thermal system integrators holding long-term OEM supply agreements rather than direct component sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Infrared defrost technology threatens to displace PTC heating in premium EV segments, forcing incumbents to defend installed base through certification races and platform lock-in strategies.
For Market Incumbents: Insulate heated windshield capacity through backward integration into transparent conductive oxide substrate production, particularly in South Korea and Taiwan. Secure 800V electrical safety certification ahead of competitor qualification timelines to create switching costs for German and Swedish OEM platform programs. Prioritize R&D investment in pixel-level thermal zoning to differentiate against infrared substitution threats in luxury vehicle segments. For New Entrants and Emerging Players: Establish a beachhead in commercial fleet electrification for electric bus and delivery vehicle defroster modules, where continuous-duty thermal requirements and lifecycle service agreements favor specialized suppliers. Target Nordic aftermarket distributors serving taxi and ride-hail fleets with regulatory-mandated rapid ice clearance specifications. Pursue mobile installation service partnerships with fleet operators seeking seasonal preparation outsourcing. For Investors and Strategic Acquirers: The market sits at a technology substitution phase that favors vertically integrated thermal management conglomerates with high-voltage platform heritage over pure-play substrate suppliers. Long-term viability hinges on defroster control integration with ADAS sensor clearing modules. Monitor EU Green Deal substance authorization deadlines as an inflection indicator for material substitution-driven M&A activity.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Reduces engineering validation costs for Denso and Valeo across multi-OEM EV programs. |
| Battery Supply Agreement | Locks in 800V system qualification capacity for PTC heating module production scaling. |
| Software-Defined Vehicle Investment | Enables real-time condensation mapping and predictive thermal management for range preservation. |
| Geographic Manufacturing Footprint | Mitigates tariff exposure through localized laminator investments in Michigan and Ohio corridors. |
| Charging Infrastructure Partnership | Creates bundled service offerings for commercial fleet operators with thermal preconditioning needs. |
Methodological Framework
A standing panel of OEM platform engineers, Tier 1 supplier procurement directors, aftermarket distributors, and dealership service operations provided ongoing calibration across the analysis window. Primary interviews combined with secondary validation from vehicle production databases, IHS Markit registration data, NHTSA compliance filings, and EU type-approval records. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators for demand estimation.
Scenario-bracketing framed volume and value outputs across vehicle class, propulsion architecture, content per vehicle, and regional production cluster dimensions. CAGRs derived from fitted growth curves applied to technology adoption S-cycles for PTC heating and infrared defrost systems. Forecast inputs incorporated MIIT new energy vehicle production quotas, KBA 800V certification timelines, and REACH substance evaluation schedules.
Sensitivities concentrate around copper and silver commodity price swings, East Asian substrate supply disruptions, and 800V platform rollout delays by major OEMs. Forecasts reflect documented assumptions on electrification penetration rates and regulatory enforcement timelines. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Asia-Pacific Automotive Composites Market
Automotive Components
Automotive Mobile Accessories Market
Automotive Components
India Automotive Airfilters Market
Automotive Components
Automotive Camshaft Phase Variator Market
Automotive Components
Automotive Engine Bearings Market
Automotive Components
Alloys for Automotive Market
Automotive Components
North America Automotive Heat Shield Market
Automotive Components
Automotive Wiper Blades Market
Automotive Components
Europe Automotive AHSS Market
Automotive Components
Global Automotive Thermal Management Market
Automotive Components
Automotive Dynamic Spotlight Market
Automotive Components
North America Automotive Glass Market
Automotive Components
Automotive Exhaust Manifolds Market
Automotive Components
Global Automotive Pneumatic Valve Market
Automotive Components
Platinum Automotive Catalyst Market
Automotive Components
India Automotive Stamping Market