
 Automotive Silicone Market | 2026-2036
Automotive Silicone Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Silicone Market Intelligence
China is reconfiguring regional supply dynamics through expanded domestic silicone monomer and downstream compounding capacity. Dow Inc. leverages integrated silicone feedstock operations to secure cost advantages across automotive sealant lines. Wacker Chemie AG anchors European supply through its Burghausen manufacturing complex, while Shin-Etsu Chemical Co., Ltd. dominates high-purity silicone polymer output for electronic module applications.
Automotive silicone encompasses elastomeric, adhesive, and coating formulations based on polydimethylsiloxane chemistry, valued for thermal stability from minus sixty to plus two hundred degrees Celsius and dielectric properties essential for under-hood and electrified powertrain sealing. Liquid silicone rubber (LSR) leads technology segmentation due to injection molding compatibility with complex geometric parts, while room-temperature vulcanizing (RTV) silicone competes in aftermarket repair and gasket replacement channels where cure speed and field applicability determine selection. Engine components and electronic modules concentrate value capture, as electrification raises thermal management and insulation requirements beyond conventional rubber capabilities.
EPA emission regulations and NHTSA fuel economy mandates compel lighter, more durable sealing materials that withstand aggressive thermal cycling, while EU REACH restrictions on volatile organic content reshape adhesive and coating formulation requirements across export-bound production. China's MIIT new energy vehicle standards and GB automotive material specifications add compliance layers for suppliers serving domestic OEMs. Stakeholders must monitor regulatory divergence between major automotive production jurisdictions to align product certification investments with actual market access requirements.
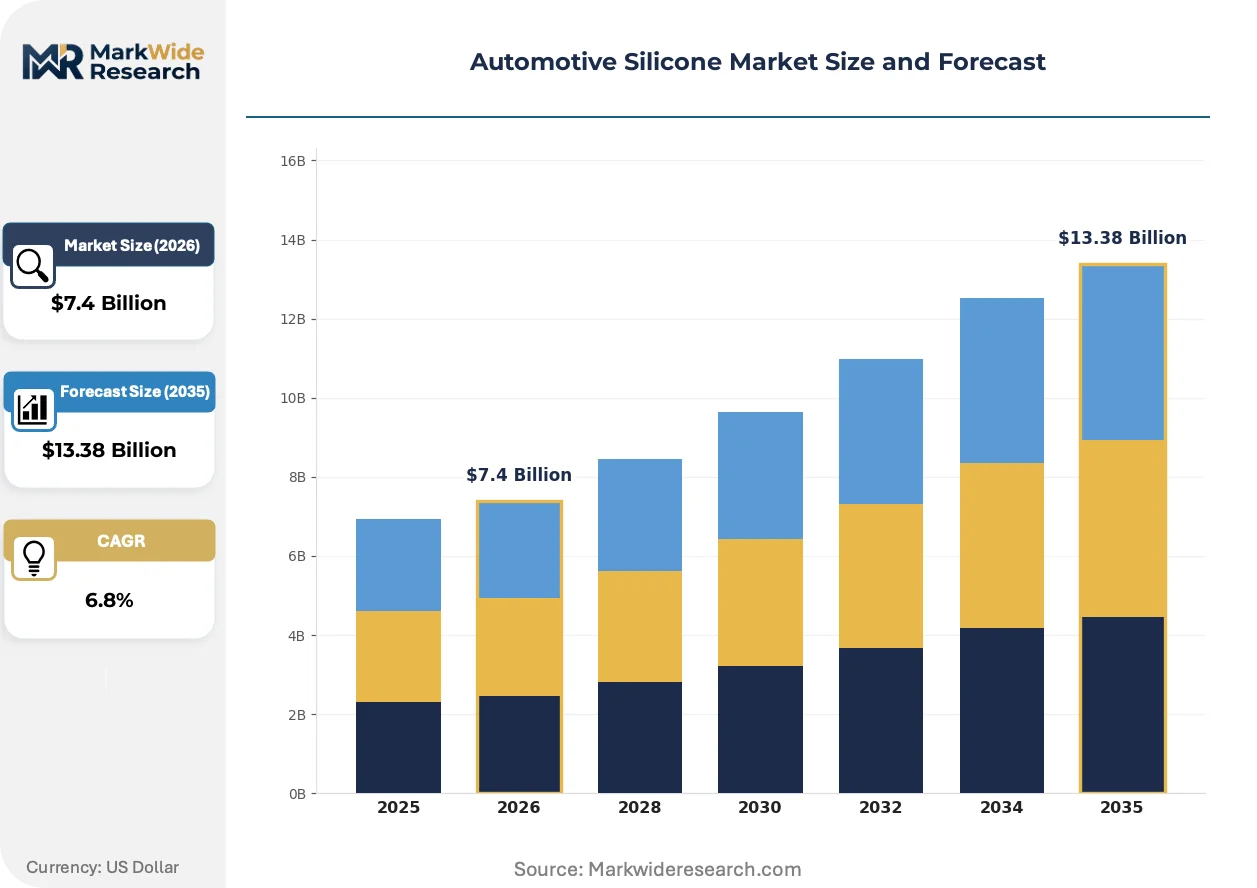
Market Dynamics
Electrification is compressing silicone specification windows as battery thermal management demands materials that survive aggressive thermal cycling between minus forty and plus one hundred fifty degrees Celsius while maintaining dielectric integrity across high-voltage architectures.
Growth Catalysts
- EPA Tier 3 emission standards:Tighter particulate limits force OEMs toward silicone gaskets and seals that outlast fluoroelastomers in exhaust after-treatment systems, expanding specification lists at Detroit Three powertrain divisions.
- Electric vehicle battery pack sealing:Liquid silicone rubber injection molding enables complex geometric seals around cylindrical and prismatic cell arrays, with Tesla, BYD, and Volkswagen Group collectively driving volume commitments.
- China's MIIT new energy vehicle mandates:Domestic production quotas for battery electric and plug-in hybrid platforms accelerate silicone consumption at CATL, BYD, and Gotion High-Tech cell manufacturing facilities.
Market Restraints
- Siloxane D4/D5/D6 regulatory friction:ECHA REACH restrictions on cyclic siloxanes in wash-off cosmetics create spillover scrutiny on automotive sealant formulations, forcing reformulation investments without equivalent performance guarantees.
- Methyl chloride and silicon metal volatility:Ferrosilicon alloy production cuts in Yunnan and Xinjiang provinces transmit upstream cost spikes to silicone monomer pricing, compressing compounder margins unpredictably.
- Fluoroelastomer substitution in cost-sensitive segments:FKM materials retain foothold in high-temperature turbocharger hoses where silicone thermal stability advantages do not justify price premiums for mass-market internal combustion platforms.
Strategic Opportunities
- India's PLI scheme for automotive components:Domestic value-add requirements for advanced chemistry materials create localized compounding opportunities as Maruti Suzuki, Tata Motors, and Mahindra expand electric portfolios.
- Solid-state battery interface materials:Next-generation cell architectures demand compressible silicone foams and thermally conductive gap fillers that accommodate solid electrolyte swelling cycles absent in liquid-electrolyte designs.
- Autonomous sensor module encapsulation:Lidar and radar housings require optically clear silicone potting compounds with low outgassing properties, opening specification channels outside traditional under-hood applications.
Industry Challenges
- Multi-jurisdiction certification timelines:Simultaneous EPA, ECHA REACH, and China GB standard compliance requires parallel testing protocols that extend product qualification cycles by twelve to eighteen months.
- High-purity silicone polymer processing expertise:Semiconductor-grade contamination control for electronic module applications demands cleanroom infrastructure and analytical chemistry capabilities scarce among traditional automotive rubber compounders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Silicone Market |
| Market Size in 2026 | $7.4 Billion |
| Market Size in 2035 | $13.38 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sealants, Adhesives, Coatings, Elastomers Application: Engine Components, Interior Accessories, Exterior Parts, Electronic Modules End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Technology: RTV Silicone, LSR, HTV, Silicone Blend |
| Companies Covered | Dow Inc., Wacker Chemie AG, Elkem ASA, Shin-Etsu Chemical Co., Ltd., KCC Corporation, Henkel AG & Co. KGaA, Momentive Performance Materials Inc., 3M Company, Evonik Industries AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Silicone Market Strategic Shifts & Innovations
Material science convergence with electrification architectures is collapsing the historical separation between thermal management, electrical insulation, and structural sealing functions into unified silicone formulation platforms.
Self-healing silicone elastomers incorporating dynamic covalent bond chemistry enable autonomous crack repair in battery pack seals subjected to vibration and thermal expansion stresses. BMW and Rivian have advanced these materials to pilot production for module-to-pack sealing interfaces. The technology is migrating from aerospace satellite applications into automotive volume manufacturing as qualification protocols adapt.
EU F-Gas Regulation phase-down schedules for hydrofluorocarbon blowing agents force reformulation of silicone foam products used in NVH and thermal insulation applications. Compounders are pivoting toward water-blown and physical blowing agent alternatives, with German KBA type-approval timelines determining competitive positioning in European OEM supply bases.
Cell manufacturer procurement teams are consolidating silicone specifications around fewer qualified suppliers capable of delivering thermal interface materials, adhesives, and sealants from unified chemistry platforms. Tier 1 integrators including Bosch, Denso, and CATL's packaging divisions now require compounders to demonstrate vertical control from monomer through finished good. This concentration is most visible in China's Yangtze River Delta battery manufacturing cluster.
Automotive Silicone Market Segmentation
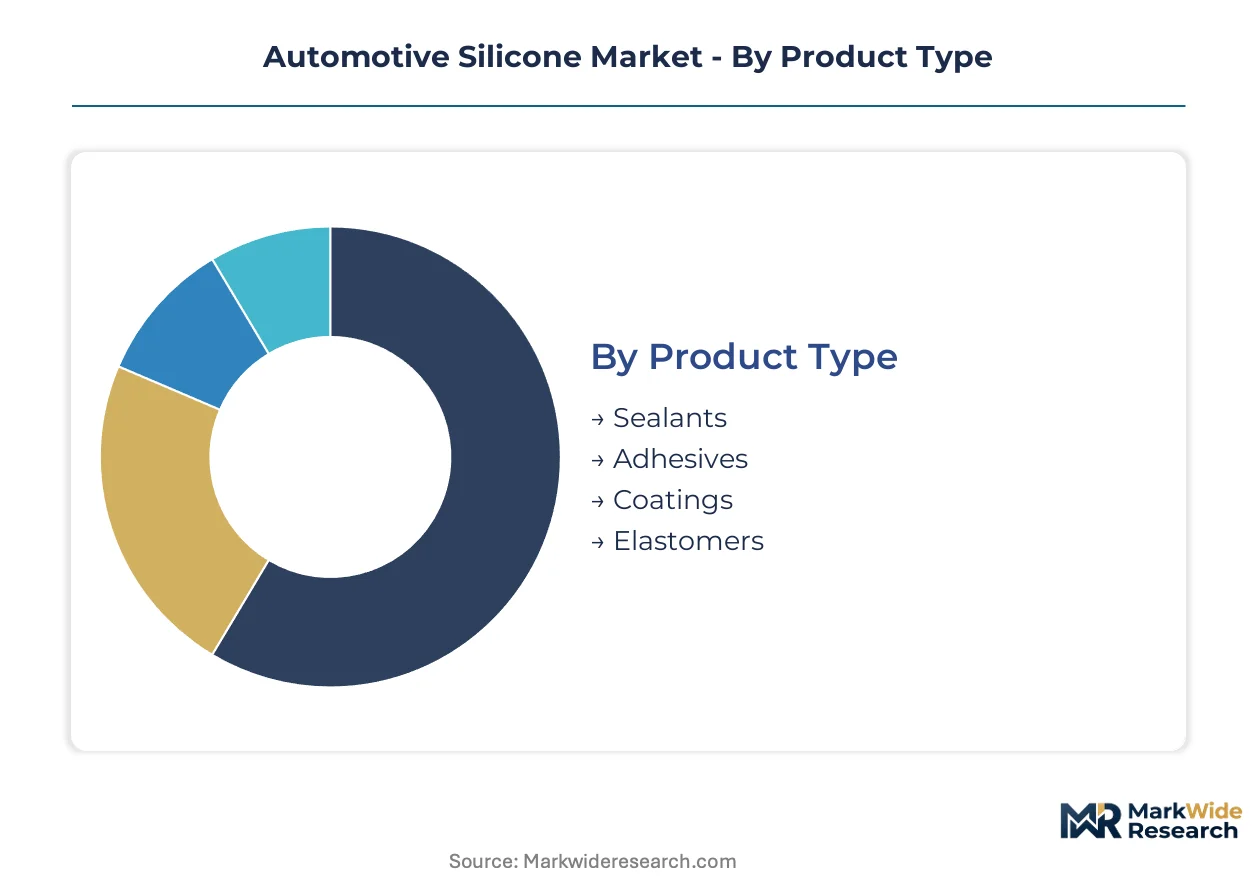
Automotive silicone purchasing patterns diverge sharply between specification-driven OEM procurement and price-sensitive aftermarket channels. Material selection criteria vary by thermal exposure severity, electrical insulation requirements, and assembly process compatibility across vehicle subsystems.
Product Type:
Aftermarket service intensity concentrates in sealant and adhesive categories where field repair applications demand rapid cure formulations and shelf-stable packaging.
- Elastomers:High-consistency rubber and liquid silicone rubber compounds deliver compression set resistance and dielectric stability for gaskets, O-rings, and vibration dampeners. Demand clusters in electric vehicle battery module sealing at CATL and BYD manufacturing facilities, where thermal cycling endurance between minus forty and plus one hundred fifty degrees Celsius determines specification approval.
- Sealants:One-part moisture-cure and two-part addition-cure formulations provide environmental sealing for powertrain assemblies and lighting enclosures. EPA Tier 3 emission standards compel Detroit Three powertrain divisions to specify silicone over fluoroelastomers in exhaust after-treatment systems due to superior thermal aging resistance.
- Adhesives:Structural bonding grades bond dissimilar substrates in lightweight vehicle architectures.
- Coatings:Thermal spray and dip-coat formulations protect electronic components from moisture and corrosion.
Elastomers hold the largest share; momentum sits with sealants as electrification raises thermal management requirements.
Application:
Cost tier differentiation separates premium specification grades for under-hood thermal exposure from economy formulations serving interior comfort applications.
- Electronic Modules:Potting compounds, conformal coatings, and thermal interface materials insulate high-voltage inverters, onboard chargers, and battery management systems. EU REACH restrictions on volatile organic content reshape adhesive formulation requirements for export-bound German OEM production, while China's GB automotive material specifications add compliance layers for domestic supply.
- Engine Components:Gaskets, hoses, and seals withstand aggressive thermal cycling in turbocharged and hybrid powertrains. NHTSA fuel economy mandates compel lighter, more durable sealing materials that outlast conventional rubber in aggressive thermal environments.
- Exterior Parts:Weatherstrip seals and lighting gaskets resist UV degradation and moisture intrusion.
- Interior Accessories:Soft-touch surfaces and HVAC seals prioritize occupant comfort over extreme temperature performance.
Engine components command established volume; electronic modules are climbing the fastest as vehicle electrification accelerates.
End User:
Volume concentration favors Tier-1 integrators consolidating specifications across multiple OEM platforms.
- Tier-1 Suppliers:Bosch, Denso, and CATL packaging divisions procure silicone thermal interface materials, adhesives, and sealants from unified chemistry platforms. Procurement teams now require compounders to demonstrate backward integration from monomer through finished good, concentrating supply around fewer qualified vendors in China's Yangtze River Delta cluster.
- OEMs:Ford, Volkswagen Group, and Tesla specify materials directly for proprietary battery pack and powertrain designs. India's PLI scheme for automotive components creates localized compounding opportunities as Maruti Suzuki, Tata Motors, and Mahindra expand electric portfolios.
- Vehicle Assemblers:Contract manufacturers apply silicone materials in final assembly operations.
- Aftermarket Providers:Distributors and jobbers serve repair channels with RTV silicone for gasket replacement and leak repair.
Tier-1 suppliers dominate procurement volume; aftermarket providers offer margin expansion through brand differentiation.
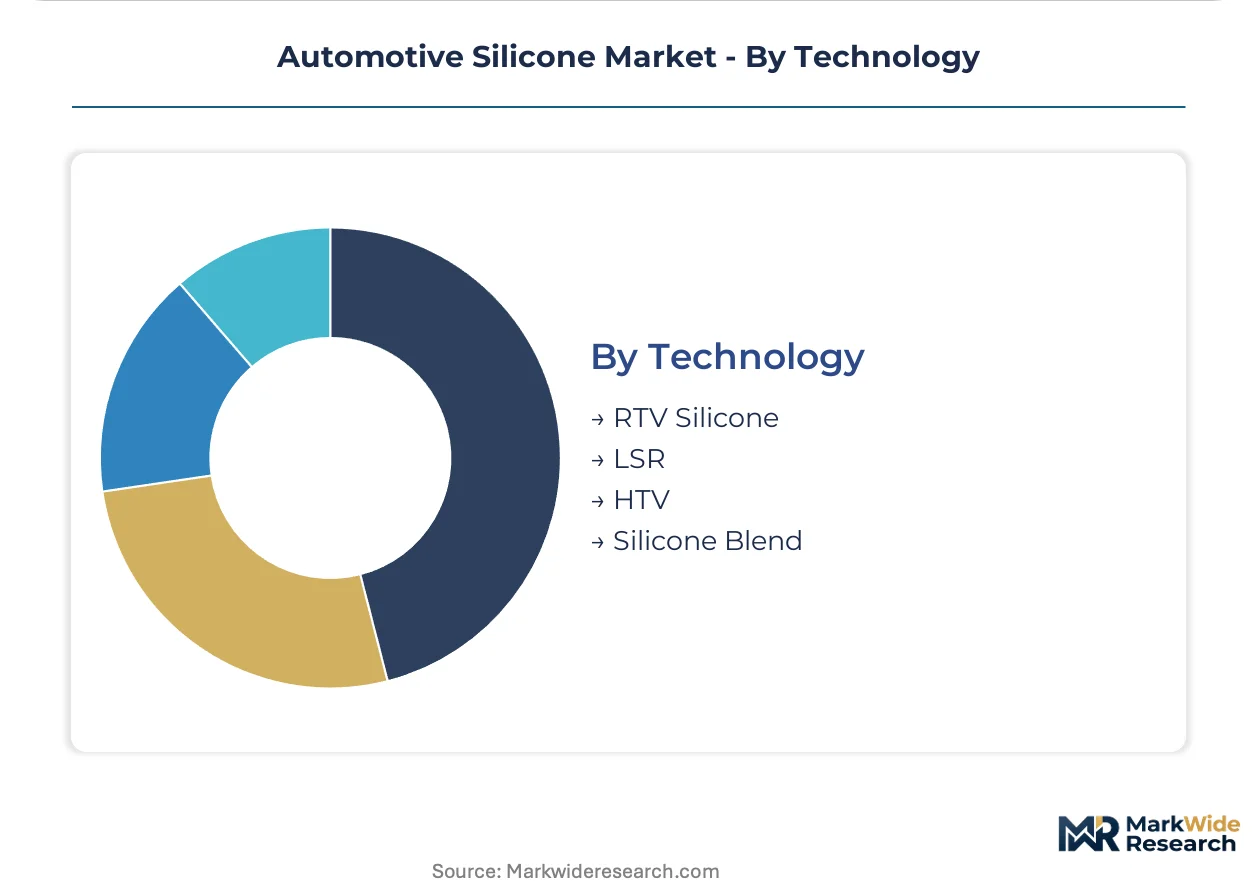
Technology:
Supply concentration in high-purity polymer processing creates capability scarcity for electronic-grade formulations.
- LSR:Liquid silicone rubber enables injection molding of complex geometric seals with tight dimensional tolerances. Tesla, BYD, and Volkswagen Group collectively drive volume commitments for battery pack sealing around cylindrical and prismatic cell arrays.
- RTV Silicone:Room-temperature vulcanizing formulations compete in aftermarket repair where cure speed and field applicability determine selection. ECHA REACH restrictions on cyclic siloxanes in wash-off cosmetics create spillover scrutiny on automotive sealant formulations, forcing reformulation investments.
- HTV:High-temperature vulcanizing grades serve compression molding applications for thick-section parts.
- Silicone Blend:Modified formulations combine silicone with organic polymers for cost-performance optimization.
LSR captures the premium specification tier; RTV silicone maintains aftermarket penetration through distribution density.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Shanghai-Ningbo port complex underwrites China's dominance in automotive silicone logistics, handling the majority of Asia-Pacific silicone monomer imports and finished compound exports. This maritime infrastructure connects Yangtze River Delta manufacturing clusters to global OEM supply chains.
China
CATL and BYD battery manufacturing facilities in Fujian and Guangdong provinces drive silicone consumption for thermal interface materials and module sealing. MIIT new energy vehicle mandates enforce domestic content requirements that favor local compounders. The Yangtze River Delta cluster around Shanghai anchors high-purity silicone polymer production for electronic-grade applications.
Germany
Volkswagen Group and BMW powertrain divisions specify silicone formulations for turbocharger hoses and exhaust after-treatment systems. EU REACH restrictions on cyclic siloxanes compel reformulation investments at compounders serving export-bound production. The Burghausen chemical complex in Bavaria maintains integrated silicone feedstock operations for European automotive supply.
United States
Detroit Three OEMs expand silicone specification lists under EPA Tier 3 emission standards for particulate control. NHTSA fuel economy mandates accelerate lightweight sealing material adoption in powertrain assemblies. Michigan and Ohio manufacturing corridors concentrate Tier-1 procurement activity for thermal management compounds.
Japan
Toyota and Nissan electrification programs raise demand for high-voltage insulation materials in hybrid and battery electric platforms. METI carbon neutrality roadmaps pressure suppliers toward lower-emission silicone production processes. The Nagoya industrial zone hosts specialized compounders serving precision electronic module applications.
India
Maruti Suzuki and Tata Motors electric portfolio expansion creates localized compounding opportunities under the PLI scheme for automotive components. BIS automotive material specifications add certification requirements for silicone sealants and adhesives. The Chennai-Bangalore industrial corridor attracts investment in battery pack assembly and associated thermal management material supply.
Automotive Silicone Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in feedstock and intermediate production. The market exhibits tiered consolidation with integrated chemical conglomerates controlling monomer supply and regional compounders competing on formulation flexibility. Three archetypes dominate: integrated petrochemical-silicone majors, specialized elastomer compounders, and automotive-focused adhesive-coating suppliers. Competitive moves concentrate on backward integration into silicon metal and methyl chloride sourcing, plus strategic partnerships with cell manufacturers for qualified supplier status.
Among integrated chemical conglomerates, Dow Inc., Wacker Chemie AG, and Shin-Etsu Chemical Co., Ltd. exemplify the feedstock-integrated archetype. Dow represents North American captive supply capabilities through its Midland operations. Wacker occupies a position as a European anchor with integrated siloxane production. Shin-Etsu sits within the high-purity polymer tier serving electronic module specifications. These three entities demonstrate how control over silicon metal through finished compound production shapes competitive positioning in electrification-driven demand segments.
| Leading Market Players |
|---|
| Dow Inc. |
| Wacker Chemie AG |
| Elkem ASA |
| Shin-Etsu Chemical Co., Ltd. |
| KCC Corporation |
| Henkel AG & Co. KGaA |
| Momentive Performance Materials Inc. |
| 3M Company |
| Evonik Industries AG |
| Others |
Cost & Logistics Intelligence
The Shanghai-Ningbo port complex channels silicone monomer flows from Yunnan and Xinjiang production zones to Yangtze River Delta compounders, with freight rate volatility transmitting directly to liquid silicone rubber pricing tiers and compressing margins for non-integrated formulators serving price-sensitive aftermarket channels.
Pricing Analysis
Volume-discount tiering structures stratify across automotive-grade certification levels, with OEM-direct contracts commanding premiums for EPA Tier 3 and EU REACH-compliant formulations while aftermarket RTV silicone competes on distributor density and rapid-cure convenience. Price differentiation hinges on silicon metal sourcing security and cleanroom-grade polymer purity for electronic module specifications. Cost compression in standard-grade elastomers is intensifying because ferrosilicon alloy production cuts in southwestern China transmit unpredictable upstream spikes. Tier-1 integrators exhibit lowest price sensitivity due to qualification lock-in, whereas independent repair shops and regional distributors face acute margin pressure from commodity-grade alternatives.
Supply Chain Analysis
Export-control regimes on semiconductor-grade silicone precursors limit technology transfer for high-purity polymer processing, constraining capacity expansion outside established manufacturing corridors. Geographic supply concentration centers on China, Germany, and the United States, with methyl chloride and silicon metal dependencies drawing from ferrosilicon smelters in Yunnan, Xinjiang, and Appalachian coal regions. Single-source vulnerability sits with cyclic siloxane purification capabilities for electronic-grade formulations. Distribution runs through Tier-1 integrator consolidation around CATL, BYD, and Bosch procurement platforms, with qualified supplier status determining market access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive silicone markets are reconfiguring around service-attach revenue streams, with thermal interface material requalification cycles and battery pack seal replacement protocols expanding recurring revenue faster than virgin compound sales.
For Market Incumbents: Entrench qualified supplier status at CATL and BYD by deepening backward integration into silicon metal and methyl chloride sourcing, while accelerating cleanroom infrastructure investments to defend against fluoroelastomer substitution in cost-sensitive turbocharger hose segments. Certification investments for solid-state battery interface materials represent the critical defensive lever.
For New Entrants and Emerging Players: India's Chennai-Bangalore industrial corridor offers white-space penetration as Maruti Suzuki and Tata Motors localize electric portfolio supply chains under PLI scheme incentives. Target aftermarket RTV silicone distribution density in Southeast Asian repair networks where cure-speed convenience determines selection. Pursue partnership routes with regional battery pack assemblers seeking second-source thermal management qualifications.
For Investors and Strategic Acquirers: Specialized compounders with captive siloxane production and electronic-grade contamination control capabilities present acquisition targets with durable positioning through electrification-driven specification consolidation. Long-term viability frames around 5-10 year windows of battery thermal management material demand. Monitor ECHA REACH enforcement intensity on cyclic siloxane restrictions as the inflection signal for reformulation investment cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicon Metal | Dow Inc. and Wacker Chemie AG secure cost advantages against ferrosilicon volatility in Yunnan and Xinjiang. |
| Cleanroom Capacity Expansion | High-purity polymer processing for CATL and BYD electronic module specifications demands contamination control infrastructure. |
| Solid-State Battery Interface Qualification | BMW and Rivian pilot programs validate compressible silicone foams for next-generation cell architectures. |
| India PLI Scheme Localization | Maruti Suzuki and Tata Motors electric expansion creates compounding opportunities under domestic value-add requirements. |
| Autonomous Sensor Encapsulation Development | Lidar and radar housing specifications open optically clear potting compound channels beyond traditional under-hood applications. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted across primary interview programs, with Tier-1 supplier procurement managers, OEM platform engineers, aftermarket distribution heads, and silicone compounding technical directors providing operational validation. Secondary sources incorporated customs and trade flow data from the Shanghai-Ningbo port complex, SEC 10-K filings from integrated chemical conglomerates, MIIT new energy vehicle production statistics, and ECHA REACH regulatory disclosure databases. Bottom-up volume modeling triangulated against top-down value estimates from silicon metal through finished compound production chains.
Calibration approaches anchored segment-level projections against observed qualification timelines at CATL, BYD, and Tesla battery manufacturing facilities, with vehicle electrification penetration rates and content-per-vehicle assumptions for thermal interface materials, adhesives, and sealants modeled throughout the forecast period. CAGRs derived from polynomial trend fitting across historical silicone monomer consumption patterns and forward-looking OEM platform commitments. Regulatory divergence between EPA Tier 3, EU REACH, and China GB standards shaped geographic adoption curve assumptions.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by mid-cap compounders or sudden ECHA REACH enforcement escalations on cyclic siloxanes would shift outcomes. Material shifts in solid-state battery commercialization timelines or autonomous vehicle sensor deployment rates would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Global Aerosol Market
Specialty Chemicals
Cellulose Derivatives Market
Specialty Chemicals
Methyl Salicylate Market
Specialty Chemicals
Naphthol AS-IRG Market
Specialty Chemicals
Africa Lactic Acid Market
Specialty Chemicals
Antifouling Agent Market
Specialty Chemicals
Undecylenic Acid Market
Specialty Chemicals
Fluorinated Plasma Surface Treatment Market
Specialty Chemicals
Precipitated Barium Sulfate Market
Specialty Chemicals
Europe Malic Acid Market
Specialty Chemicals
Silver Sulfate Market
Specialty Chemicals
Europe Aerosol Cans Market
Specialty Chemicals
Zinc Eugenol Market
Specialty Chemicals
Methyltrimethoxysilane Market
Specialty Chemicals
Monoaluminum Phosphate Market
Specialty Chemicals
UV Light Stabilizers Market