
 Precipitated Barium Sulfate Market | 2026-2036
Precipitated Barium Sulfate Market Size, Share, and Industry Trends Forecast 2026-2036
Precipitated Barium Sulfate Market Analytics
Chinese specialty chemical producers is shifting capacity toward higher-purity precipitated grades for coatings and electronics applications. Solvay leverages its European manufacturing footprint to supply pharmaceutical-grade material with certified heavy-metal thresholds. Cimbar Performance Minerals anchors North American supply through integrated barite mining and chemical processing operations. SAKAI CHEMICAL INDUSTRY CO.,LTD. dominates Asian technical-grade markets with consistent particle-size distribution for plastics compounding.
Precipitated barium sulfate is a synthetic inorganic compound produced through controlled precipitation of barium salts with sodium sulfate, yielding particles with defined morphology and 98.0-99.5% purity depending on end-use requirements. The material functions primarily as a functional filler, providing opacity, chemical inertness, and density to coatings, plastics, and rubber formulations while maintaining low oil absorption. Industrial and paint grades command the largest volume pools, though pharmaceutical-grade material captures disproportionate margin due to stringent USP and EP certification requirements. Coatings applications lead consumption globally, while plastics compounding represents the fastest-expanding segment as polymer processors substitute precipitated barium sulfate for higher-cost white pigments.
REACH registration and the EU F-Gas Regulation shape European product standards for chemical purity and environmental release, while FDA and EPA oversight in the United States governs food-contact and industrial applications respectively. China's SAMR enforces GB standards for barium compound specifications, creating a fragmented compliance landscape that favors producers with multi-jurisdiction certification capabilities. Stakeholders must monitor evolving heavy-metal thresholds and carbon-intensity disclosures, as these criteria increasingly determine supplier qualification across automotive and electronics value chains.
Market Dynamics
Automotive powder coating specifications are tightening purity thresholds for heavy-metal content, forcing precipitated barium sulfate suppliers to reconfigure precipitation chemistry and certification workflows across manufacturing footprints.
Growth Catalysts
- REACH heavy-metal thresholds:European coatings formulators now require sub-10 ppm lead specifications, pulling technical-grade producers toward pharmaceutical-capable process lines.
- Plastics compounding substitution:Polymer processors in automotive interiors are displacing titanium dioxide with precipitated barium sulfate to reduce formulation costs while maintaining opacity.
- China's export-grade scaling:Domestic chemical producers in Shandong and Jiangsu provinces are expanding precipitated capacity certified to USP and EP standards for coatings and electronics markets.
Market Restraints
- Barite ore concentration:Mining operations in Guizhou province control over half of China's feedstock supply, creating single-source vulnerability for non-integrated precipitated sulfate producers.
- Energy cost volatility:Precipitation and calcination stages require sustained thermal input; natural gas price swings in European manufacturing footprints compress margin predictability.
- Precipitated calcium carbonate substitution:Lower-density fillers are capturing volume in non-critical plastics applications where density specifications allow formulation flexibility.
Strategic Opportunities
- India's automotive coatings expansion:Domestic OEM paint shops are qualifying precipitated grades for metallic and pearlescent finishes as vehicle production scales in Tamil Nadu and Gujarat.
- EU F-Gas Regulation compliance:Refrigeration coatings requiring chemical inertness and thermal stability are opening specification windows for high-purity precipitated sulfate in heat-exchanger applications.
- Electronics-grade particle engineering:Dielectric filler applications in printed circuit boards are converging with semiconductor packaging demand for sub-micron particle distribution control.
Industry Challenges
- Multi-jurisdiction certification timelines:Simultaneous USP, EP, and GB standard qualification requires 18-24 month validation cycles that delay market entry for new production lines.
- Precipitation reactor scaling:Maintaining consistent particle morphology when expanding from pilot to commercial batch volumes demands process engineering expertise concentrated among legacy equipment suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Precipitated Barium Sulfate Market |
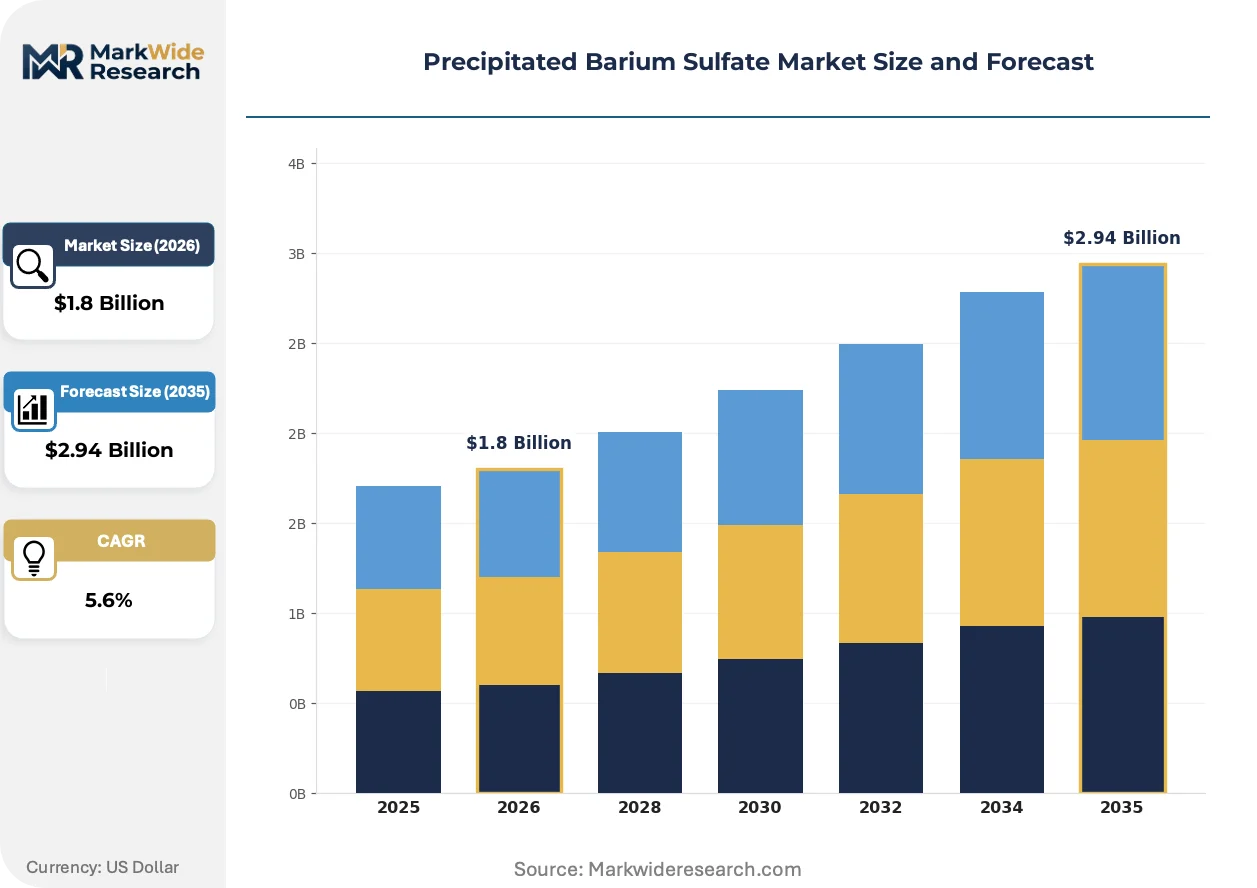
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.94 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grades, Paint Grade, Rubber Grade, Pharmaceutical Grade Application: Coatings, Plastics, Paper, Inks End User: Construction, Automotive, Electronics, Consumer Goods Distribution Channel: Direct Sales, Distributors, Online Retail, Others |
| Companies Covered | Solvay, Cimbar Performance Minerals, Huntsman International LLC, SAKAI CHEMICAL INDUSTRY CO.,LTD., Venator Materials PLC, SHENZHOU JIAXIN CHEMICAL CO.,LTD., Shaanxi Fuhua Chemical Co., Ltd., Barium & Chemicals, Inc., Fengchen Group Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Precipitated Barium Sulfate Market Evolving Landscape
Particle engineering capabilities are separating commodity precipitated sulfate from premium grades, with morphology control becoming the primary axis of supplier differentiation in coatings and electronics applications.
Nano-scale precipitation technology is electrifying competitive positioning in dielectric filler markets. Semiconductor packaging manufacturers in South Korea and Taiwan are adopting sub-100 nanometer precipitated grades for low-loss substrate applications. This particle-size compression is enabling displacement of legacy fused silica in high-frequency circuit boards.
EPA toxics rules are tightening reporting thresholds for barium compound releases, forcing coatings manufacturers to document supply-chain provenance and heavy-metal testing protocols. Industrial paint formulators in Michigan and Ohio are now requiring batch-level certificates of analysis from precipitated sulfate suppliers, shifting qualification from annual audits to per-shipment verification.
Buyer concentration among automotive OEMs is compressing supplier negotiation leverage. Tier-1 coatings manufacturers in Germany and Japan are consolidating qualified vendor lists to three or fewer precipitated sulfate sources per manufacturing region, replacing the previous six-to-eight supplier fragmentation. This consolidation is most visible in Stuttgart and Nagoya automotive clusters where paint-shop integration demands synchronized logistics and quality systems.
Precipitated Barium Sulfate Market Segmentation
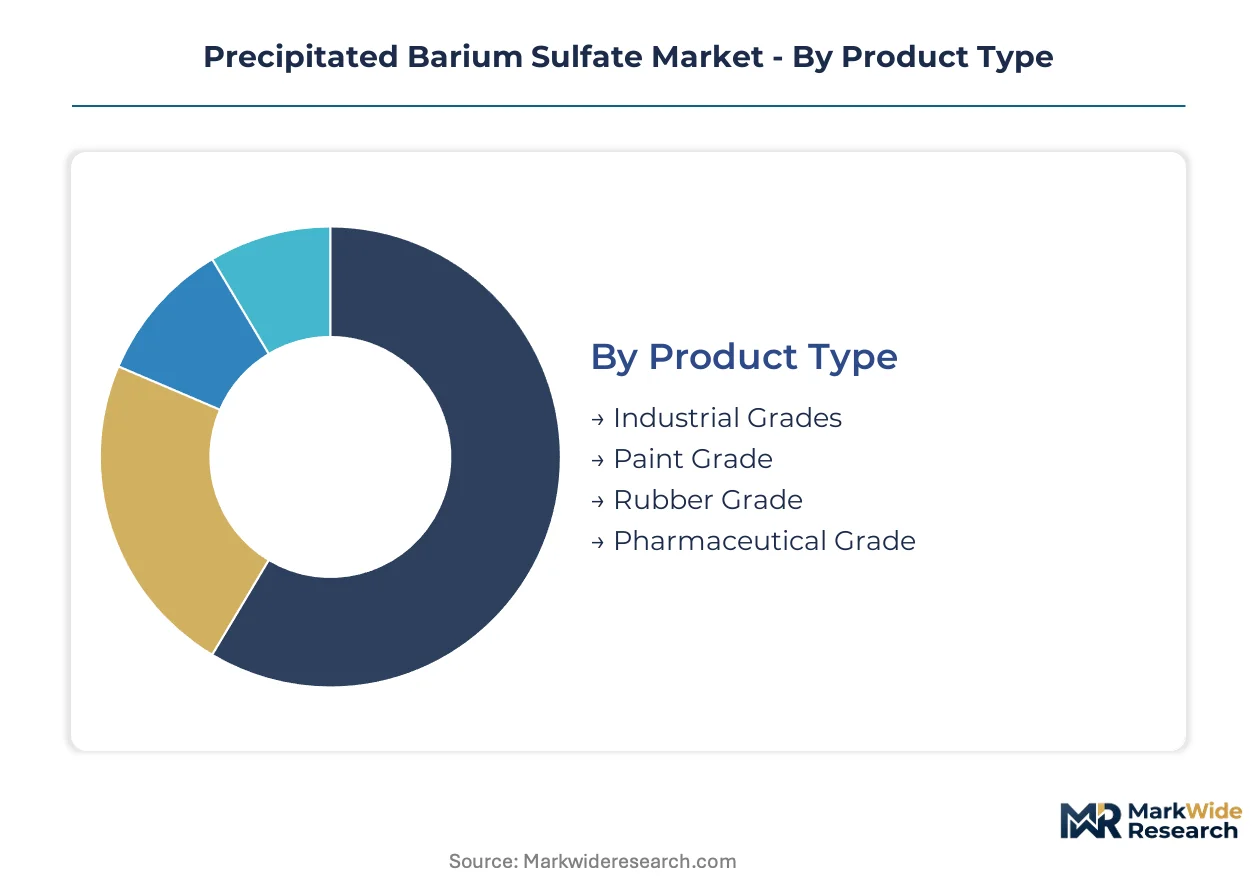
Precipitated barium sulfate markets segment across purity thresholds, particle morphology, and certification requirements that determine pricing power and customer lock-in. Each dimension creates distinct competitive arenas with different margin structures and supplier qualification barriers.
Product Type:
Upgrade cycles in coatings and electronics are pulling technical-grade producers toward pharmaceutical-capable precipitation lines and heavy-metal certification workflows.
- Industrial Grades:Standard precipitation yields 98.0-99.0% purity with controlled particle size for general filler applications. Demand concentrates in construction coatings and commodity plastics across China's Shandong manufacturing belt, where SAMR's GB standards enforce baseline heavy-metal thresholds that now exceed legacy industrial specifications.
- Paint Grade:Optimized for low oil absorption and high gloss retention in automotive and architectural coatings. Procurement is shifting toward REACH-certified material as European formulators enforce sub-10 ppm lead specifications across metallic and pearlescent finish lines.
- Rubber Grade:Coarser particle distribution enhances dispersion in tire and industrial rubber compounding. Compounders in Germany's KBA-regulated automotive supply chain specify consistent morphology for dynamic load applications.
- Pharmaceutical Grade:USP and EP certification demands 99.5%+ purity with documented heavy-metal testing for contrast media and excipient applications. Solvay's European footprint dominates this tier due to multi-jurisdiction validation capabilities.
Industrial grades sit at the top of the volume ranking, with pharmaceutical grade climbing the fastest as certification requirements tighten across automotive and electronics value chains.
Application:
Cost-tier differentiation separates commodity fillers from performance-critical applications where particle engineering commands price premiums.
- Coatings:Powder and liquid formulations consume the largest volume pool, with automotive OEM specifications driving purity upgrades. Stuttgart and Nagoya paint-shop clusters now require batch-level certificates of analysis, replacing annual supplier audits with per-shipment verification protocols.
- Plastics:Polymer processors substitute precipitated barium sulfate for titanium dioxide in automotive interiors to reduce formulation costs while maintaining opacity. This segment is gaining share fastest as compounding specifications expand across Tamil Nadu and Gujarat manufacturing zones.
- Paper:Brightness and opacity enhancement in coated paper grades. Mills in North American and European markets face pressure from precipitated calcium carbonate substitution where density specifications allow formulation flexibility.
- Inks:Fine particle grades enable high-definition printing with controlled rheology. Specialty ink formulators in Japan's JIS-regulated packaging sector specify narrow particle distribution for UV-curable systems.
Coatings commands the largest revenue pool, while plastics demonstrates the steepest expansion trajectory as substitution economics improve.
End User:
Customer-type concentration among automotive OEMs compresses supplier negotiation leverage and consolidates qualified vendor lists.
- Construction:Architectural coatings and waterproofing membranes drive steady industrial-grade consumption. China's property sector volatility creates demand uncertainty for non-certified material.
- Automotive:Tier-1 coatings manufacturers in Germany and Japan have consolidated to three or fewer qualified precipitated sulfate sources per region, replacing previous six-to-eight supplier fragmentation. REACH and EPA toxics rules now govern heavy-metal documentation across integrated paint-shop operations.
- Electronics:Dielectric filler applications in printed circuit boards and semiconductor packaging require sub-micron particle distribution control. South Korean and Taiwanese substrate manufacturers adopt nano-scale grades for low-loss high-frequency applications.
- Consumer Goods:Food-contact and cosmetic applications demand pharmaceutical-grade certification. FDA oversight governs US market entry with extended validation timelines.
Automotive anchors current demand concentration, with electronics expanding most quickly as semiconductor packaging specifications tighten.
Distribution Channel:
Supply chain configuration favors direct relationships for certified grades while distributors handle commodity volume.
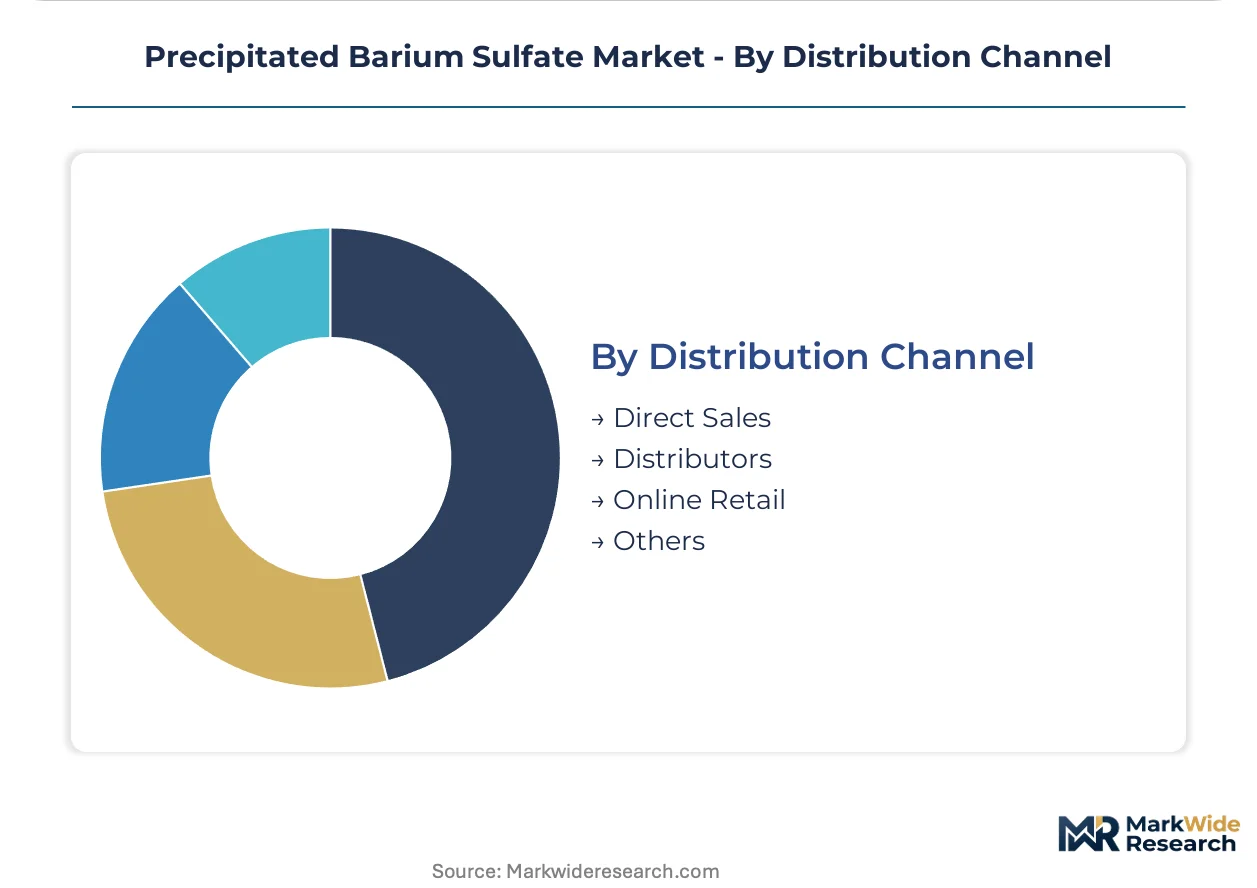
- Direct Sales:Pharmaceutical and coatings-grade material moves through technical service relationships with precipitation chemistry support. Solvay and SAKAI CHEMICAL INDUSTRY CO.,LTD. maintain field engineering presence at major automotive paint-shop clusters.
- Distributors:Industrial and rubber grades flow through regional chemical distributors with inventory positioning in China's Jiangsu province and the US Midwest. Cimbar Performance Minerals leverages integrated mining and processing for North American distributor supply.
- Online Retail:Limited to small-volume technical-grade purchases for research and specialty compounding. SAMR's e-commerce regulations enforce product registration for chemical sales.
- Others:Agent networks and trading houses facilitate cross-border procurement for non-integrated precipitated sulfate producers dependent on Guizhou barite ore supply.
Direct sales captures the premium tier by certification requirement, with distributor channels handling the largest physical volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's precipitated barium sulfate producers outpace German rivals in export-grade capacity expansion, while Japanese technical-grade specialists maintain tighter particle-size control for electronics applications.
China
Domestic chemical producers in Shandong and Jiangsu provinces scale precipitated capacity for coatings and electronics export markets. SAMR enforces GB standards for barium compound specifications that now exceed legacy industrial thresholds. Mining concentration in Guizhou province controls over half of national feedstock supply, creating single-source vulnerability for non-integrated producers.
Germany
Automotive OEM paint shops in Stuttgart drive REACH-certified material demand for metallic and pearlescent finishes. ECHA's heavy-metal thresholds now require sub-10 ppm lead specifications across coatings formulations. KBA-regulated tire compounders specify consistent morphology from precipitated sulfate suppliers for dynamic load applications.
United States
EPA toxics rules tighten reporting thresholds for barium compound releases in Michigan and Ohio industrial paint operations. FDA oversight governs pharmaceutical-grade certification timelines for contrast media applications. Cimbar Performance Minerals anchors North American supply through integrated barite mining and chemical processing operations.
Japan
SAKAI CHEMICAL INDUSTRY CO.,LTD. dominates technical-grade markets with consistent particle-size distribution for plastics compounding. METI-aligned JIS standards regulate specialty ink formulations for UV-curable packaging systems. Nagoya automotive clusters consolidate qualified vendor lists to three or fewer precipitated sulfate sources per manufacturing region.
South Korea
Semiconductor packaging manufacturers adopt nano-scale precipitated grades for low-loss high-frequency substrate applications. MFDS pharmaceutical regulations create parallel certification requirements for medical-grade material. Busan-Ulsan chemical processing zones attract precipitated sulfate suppliers targeting dielectric filler specifications.
Precipitated Barium Sulfate Market Competitive Landscape
European producers anchor the pharmaceutical-grade tier; Asian specialists hold technical-grade volume leadership. The vendor base splits between integrated mining-chemical operators and precipitation-focused compounders. Three archetypes dominate: purity-certification leaders, particle-engineering specialists, and backward-integrated feedstock owners. Capacity expansion and multi-jurisdiction certification represent the dominant competitive moves.
Within the certification-intensive tier, Solvay exemplifies European pharmaceutical-grade positioning through multi-jurisdiction validation capabilities. SAKAI CHEMICAL INDUSTRY CO.,LTD. and Cimbar Performance Minerals occupy complementary geographic anchors across Asian technical-grade and North American integrated supply respectively. These three represent distinct strategic postures—European purity leadership, Asian particle consistency, and North American vertical feedstock control—rather than direct product competition.
| Leading Market Players |
|---|
| Solvay |
| Cimbar Performance Minerals |
| Huntsman International LLC |
| SAKAI CHEMICAL INDUSTRY CO.,LTD. |
| Venator Materials PLC |
| SHENZHOU JIAXIN CHEMICAL CO.,LTD. |
| Shaanxi Fuhua Chemical Co., Ltd. |
| Barium & Chemicals, Inc. |
| Fengchen Group Co., Ltd. |
| Others |
Value Network & Pricing Analysis
Automotive OEM consolidation to three qualified suppliers per region in Stuttgart and Nagoya clusters forces precipitated barium sulfate producers to absorb certification costs or surrender margin, compressing pricing power across REACH-certified grades while elevating spot-market volatility for uncertified industrial material.
Pricing Analysis
Distributor margins of 12-18% on industrial-grade material separate commodity pricing from direct-to-OEM pharmaceutical-grade contracts. Three-tier pricing structure across pharmaceutical, paint, and industrial levels tracks certification burden and batch-testing intensity. Cost compression in technical grades intensifies because Chinese producers scale USP-capable capacity for export markets. Construction coatings buyers exhibit highest price sensitivity, while semiconductor packaging manufacturers accept premium positioning for sub-micron particle control.
Supply Chain Analysis
Workforce availability constraints in Shandong and Jiangsu chemical processing zones limit expansion velocity for precipitation reactor operations. Supply concentrates in China, Germany, and Japan, with Guizhou barite ore feeding half of Chinese capacity. Feedstock draws from mined barite, sodium sulfate reagents, and thermal energy inputs. Single-source vulnerability runs through Guizhou mining concentration. Distribution runs through direct technical service relationships for certified grades and regional distributors for commodity volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precipitated barium sulfate markets read as a late-cycle quality story. REACH sub-10 ppm lead specifications and EPA toxics documentation rules pull procurement toward pharmaceutical-capable producers with multi-jurisdiction validation.
For Market Incumbents: Hedge against titanium dioxide substitution reversals by deepening backward integration into Guizhou barite mining or securing long-term ore offtake agreements. Solvay's European certification infrastructure offers a defensive template. Prioritize reactor scaling expertise to maintain particle morphology consistency across volume expansion. For New Entrants and Emerging Players: Begin with India's Tamil Nadu and Gujarat automotive coatings expansion, where domestic OEM paint shops are qualifying new precipitated grades for metallic finishes. Target electronics-grade nano-precipitation for South Korean semiconductor packaging demand. Pursue technical service partnerships with established distributor networks rather than direct OEM qualification. For Investors and Strategic Acquirers: Asymmetric upside sits with integrated mining-chemical operators possessing Guizhou ore access and multi-jurisdiction certification capabilities. Five-to-ten-year viability favors producers with simultaneous USP, EP, and GB standard qualification. Monitor EPA heavy-metal reporting threshold revisions as inflection signal for North American supply chain restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Barite Mining | Captive Guizhou ore supply eliminates single-source vulnerability for non-integrated producers. |
| Multi-Jurisdiction Certification Investment | Simultaneous USP, EP, and GB qualification opens automotive and electronics procurement channels. |
| Nano-Scale Precipitation Capacity Expansion | Sub-100 nanometer grades penetrate South Korean semiconductor packaging substrate applications. |
| Long-Term Supply Agreement with Automotive OEMs | Tier-1 coatings manufacturers in Stuttgart and Nagoya consolidate vendor lists to three sources. |
| Green Manufacturing Transition | Carbon-intensity disclosures increasingly determine supplier qualification across automotive value chains. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary engagement covered plant managers at precipitation facilities, procurement leads at automotive Tier-1 coatings manufacturers, distribution channel partners in China's Jiangsu province, and technical R&D directors at specialty chemical compounders. Secondary validation drew from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings from listed chemical producers, and SAMR GB standard documentation. Bottom-up capacity modeling and top-down demand triangulation anchored volume estimates.
Historical reference periods anchored the forecast window to observed capacity utilization and certification timeline patterns across the projection horizon. Segmentation dimensions modeled include purity grade tier, end-use industry application, particle morphology specification, and regional production hub cluster. CAGRs derived from weighted average of demand-side substitution elasticity and supply-side capacity expansion schedules. Forecast inputs incorporated REACH heavy-metal threshold evolution and EPA toxics rule reporting burden.
Several conditions sit outside the modeled scope, including abrupt barite ore export restrictions, natural gas price shock impacts on European calcination economics, and breakthrough calcium carbonate substitution in non-critical plastics. Forecasts reflect documented assumptions about certification timeline stability and automotive production trajectory. Material deviation in regulatory enforcement intensity or mining policy warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Rosin Press Market
Specialty Chemicals
Acetyl Isovaleryl Market
Specialty Chemicals
Dipentene (Limonene) Market
Specialty Chemicals
Hydroxypropionic Acid Market
Specialty Chemicals
Polyquaternium 6 Market
Specialty Chemicals
Organic Sulfur Market
Specialty Chemicals
Security Ink Market
Specialty Chemicals
Structure Directing Agents Market
Specialty Chemicals
Global Curing Agents Market
Specialty Chemicals
Acrylic Powder Market
Specialty Chemicals
Global Prepacked Chromatography Columns Market
Specialty Chemicals
Bio-Based Phenol Market
Specialty Chemicals
LAMEA Metal Biocides Market
Specialty Chemicals
Ascorbic Acid Market
Specialty Chemicals
Medical Propellants Market
Specialty Chemicals
Glucosinolates Market