
 Naphthol AS-IRG Market | 2026-2036
Naphthol AS-IRG Market Size, Share, and Industry Trends Forecast 2026-2036
Naphthol AS-IRG Market Outlook
The capital-intensity divergence between integrated pigment houses and merchant naphthol suppliers is bifurcating competitive dynamics across the value chain. BASF SE leverages captive naphthol production to secure feedstock for its pigment divisions, while Laxmi Organic Industries Limited anchors its position through backward integration into dye intermediate manufacturing. PRAVIN DYECHEM PVT. LTD competes as a specialized Indian supplier with deep ties to domestic textile chemical channels.
Naphthol AS-IRG functions as a diazo coupling component in the synthesis of azo pigments, requiring controlled crystallization to achieve the specific particle size distribution demanded by high-performance printing ink and plastics coloration applications. Application Grade material dominates volume flows, serving pigment houses that demand batch-to-batch consistency for automotive and packaging coatings. Pharmaceutical Grade represents a concentrated margin pool, where Merck KGaA and Osaka Organic Chemical Industry Ltd. operate under stringent pharmacopeial standards that limit qualified supply sources.
REACH registration requirements in Europe and China's GB standards under SAMR oversight are elevating analytical documentation burdens for importers of naphthol intermediates. India's CDSCO and BIS frameworks are converging toward harmonized impurity profiles for dye intermediates destined for food-contact and pharmaceutical applications. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate reformulation costs and qualification timelines.
Market Dynamics
REACH registration requirements and China's GB standards under SAMR oversight are bifurcating supplier qualification tiers, forcing merchant naphthol producers to absorb analytical documentation costs or exit European and Chinese pigment channels entirely.
Growth Catalysts
- Automotive coatings specification tightening:OEMs in Germany and Japan now mandate batch-to-batch crystallinity consistency for exterior azo pigments, pulling Application Grade naphthol AS-IRG through qualified supply chains.
- REACH Article 33 disclosure obligations:Importers of naphthol intermediates into the European Economic Area must demonstrate SVHC-free certification, advantaging pre-registered suppliers with existing dossiers.
- Textile cluster expansion in India:Dye intermediate producers in Gujarat and Maharashtra are scaling coupling component capacity to serve domestic pigment houses reducing import dependence.
Market Restraints
- Aniline feedstock volatility:Naphthol AS-IRG synthesis depends on aniline derivatives whose pricing fluctuates with crude oil and benzene spreads, compressing merchant producer margins during upstream spikes.
- Supply concentration in China:A limited number of Jiangsu and Zhejiang-based intermediate manufacturers control crystallization technology for high-purity grades, creating single-source risk for European pigment formulators.
- Phthalocyanine pigment substitution:Blue and green shade requirements in packaging inks increasingly default to copper phthalocyanine chemistry, displacing azo pigment demand in specific color index ranges.
Strategic Opportunities
- Pharmaceutical Grade qualification:USP and EP monograph compliance for naphthol intermediates opens formulation access to parenteral dye applications where pharmacopeial traceability commands premium positioning.
- India PLI scheme for specialty chemicals:Production-linked incentives for dye intermediate manufacturing reduce capital recovery periods for domestic naphthol AS-IRG capacity additions serving export markets.
- Digital color matching platforms:Cloud-based spectrophotometry tools are compressing pigment qualification cycles, enabling remote batch approval that reduces geographic friction between Indian suppliers and European buyers.
Industry Challenges
- Crystallization process engineering scarcity:Controlled particle size distribution for high-fastness pigments requires specialized chemical engineers familiar with diazo coupling kinetics, a talent pool concentrated in legacy German and Swiss pigment houses.
- Multi-jurisdiction dossier maintenance:Simultaneous REACH, GB standard, and BIS compliance demands dedicated regulatory affairs functions that strain mid-scale merchant producers without captive legal resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Naphthol AS-IRG Market |
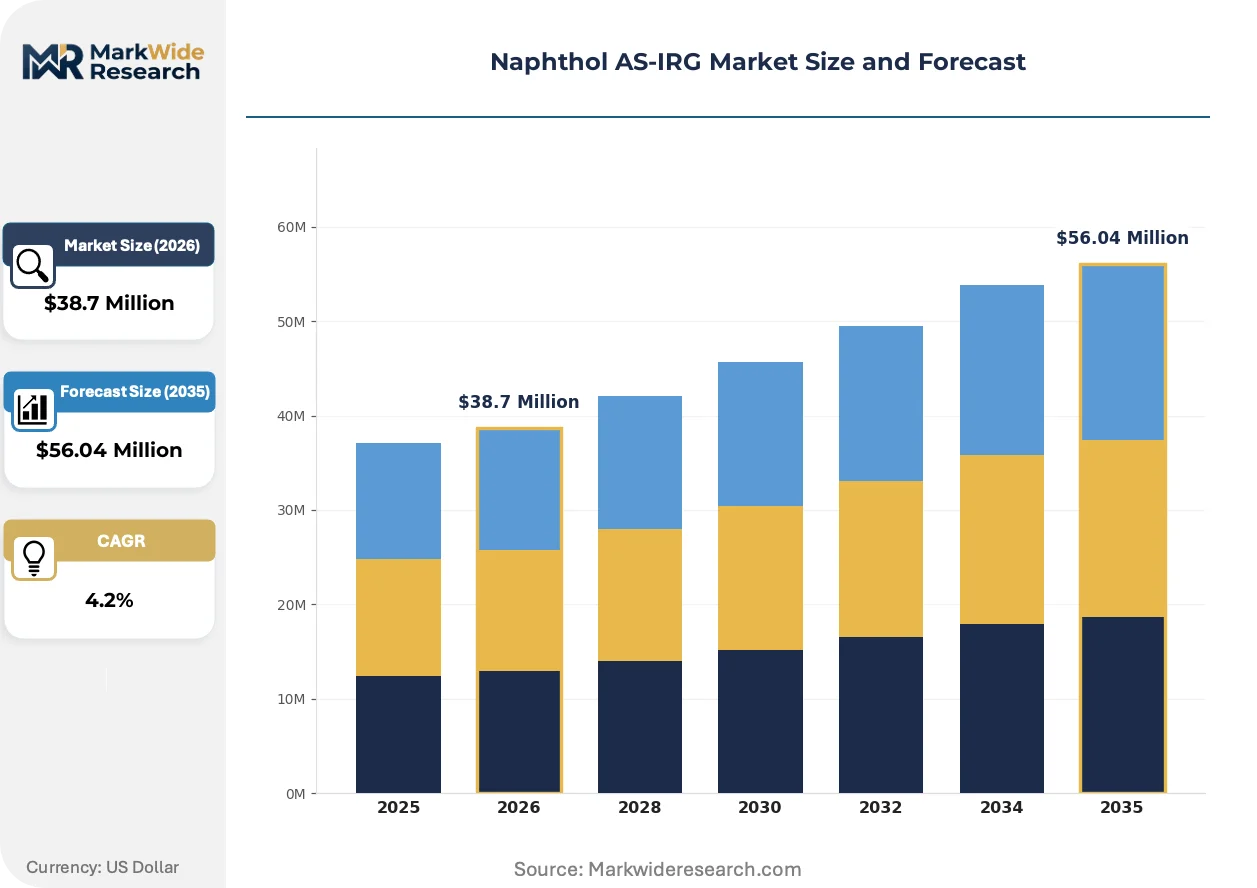
| Market Size in 2026 | $38.7 Million |
| Market Size in 2035 | $56.04 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Application Grade, Industrial Grade, Pharmaceutical Grade, Food Grade End User: Chemical Manufacturers, Pharmaceuticals, Food Producers, Agriculture Form: Liquid, Powder, Granular, Crystalline Distribution Channel: Direct Sales, Distributors, Online Retail, Wholesalers |
| Companies Covered | BASF SE, PRAVIN DYECHEM PVT. LTD, Laxmi Organic Industries Limited, Merck KGaA, Qingdao Longyuntong Corporation, Jiangsu Tianbo Chemical Co.Ltd., Vipul Organics, Osaka Organic Chemical Industry Ltd., Kiri Industries Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Naphthol AS-IRG Market Strategic Shifts
Continuous crystallization technology and regulatory data digitization are compressing batch-to-batch variation windows while fragmenting traditional supplier-customer relationships around real-time quality verification.
Continuous flow reactors for diazo coupling are fragmenting conventional batch manufacturing economics in naphthol intermediate production. Pigment houses in Italy and Japan are piloting these systems to reduce solvent waste and crystallization cycle times. The technology is fragmenting capital allocation patterns, with integrated producers investing in modular skid-mounted units while merchant suppliers delay conversion due to retrofit costs.
REACH Annex XVII restrictions on PAH impurities in consumer-facing articles are tightening allowable thresholds for naphthol-derived colorants. The European Chemicals Agency's 2024 guidance on extractable aromatic amines has forced reformulation of legacy azo pigment recipes. Automotive interior applications face the steepest requalification burdens, driving pigment manufacturers toward pre-certified intermediate suppliers with established analytical traceability.
Direct procurement relationships between textile chemical distributors and Indian naphthol producers are disintermediating traditional European trading houses. Buying consortia in Turkey and Bangladesh now negotiate annual volume contracts through digital platforms that bypass layered distributor markups. This channel compression is most visible in commodity-grade applications where pharmacopeial documentation is not required and price transparency dominates supplier selection criteria.
Naphthol AS-IRG Market Segmentation
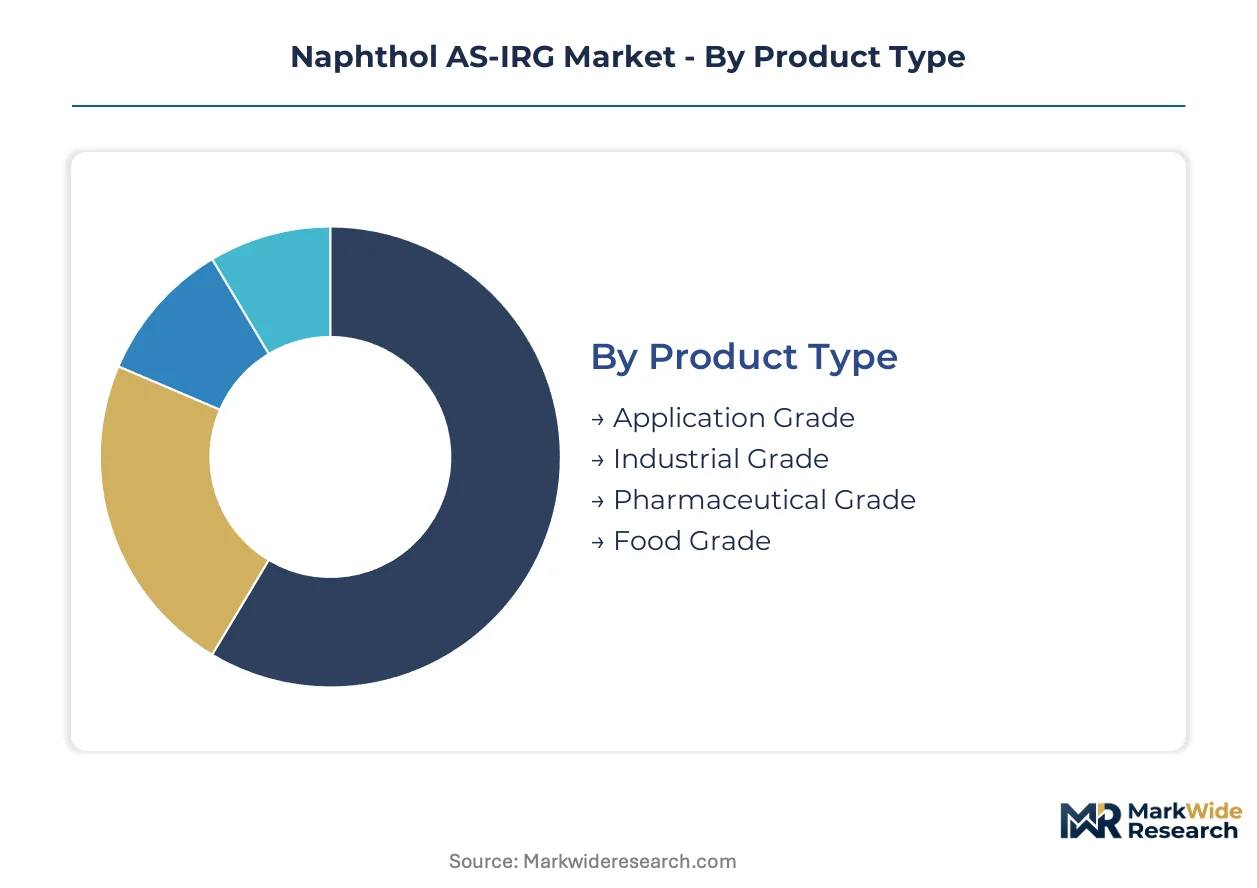
Segmentation in the Naphthol AS-IRG market reveals divergent qualification barriers and margin structures across purity tiers and end-use applications. Understanding these divides enables suppliers to align crystallization investments with the regulatory intensity of target customer segments.
Product Type:
Application Grade and Industrial Grade segments serve predominantly domestic pigment houses in India and China, while Pharmaceutical Grade and Food Grade volumes flow disproportionately toward export markets bound for REACH-regulated European channels and FDA-scrutinized North American applications.
- Application Grade:This segment supplies diazo coupling components for high-fastness azo pigments used in automotive and packaging coatings. Demand concentrates in Gujarat and Maharashtra textile clusters where domestic pigment formulators are scaling capacity to reduce import dependence from Jiangsu-based suppliers.
- Pharmaceutical Grade:USP and EP monograph compliance defines this tier, limiting qualified sources to manufacturers with pharmacopeial traceability systems. European parenteral dye applications command premium positioning, though CDSCO and BIS frameworks in India are tightening impurity profiles for export-bound material.
- Industrial Grade:Serves commodity pigment production with less stringent crystallinity specifications.
- Food Grade:FSSAI and FDA compliance requirements restrict supply to specialized intermediate houses with dedicated food-contact manufacturing lines.
Application Grade commands the established base. The steepest expansion runs through Pharmaceutical Grade.
End User:
Cost tier stratification separates capital-intensive integrated pigment houses from price-sensitive merchant chemical manufacturers, with regulatory compliance costs widening the gap between qualified and unqualified supplier tiers.
- Chemical Manufacturers:Pigment houses in Germany and Japan mandate batch-to-batch crystallinity consistency for exterior automotive coatings. These buyers absorb premium pricing for pre-certified intermediates with established REACH dossiers and SVHC-free certification.
- Pharmaceuticals:Parenteral dye formulation requires pharmacopeial-grade naphthol with documented impurity profiles. EMA and FDA inspections of active pharmaceutical ingredient suppliers cascade backward to intermediate qualification requirements.
- Food Producers:Food-contact colorant regulations under EFSA and FSSAI limit acceptable aromatic amine residues.
- Agriculture:Seed treatment and agrochemical coloring applications prioritize volume scale over purity premiums.
Chemical Manufacturers anchor volume flows. Pharmaceuticals generate the highest margin capture per kilogram.
Form:
Supply concentration in crystallization technology favors powder and crystalline formats, while liquid formulations remain niche due to solvent handling complexities and stability constraints during long-haul shipping.
- Powder:Standard format for pigment synthesis with established handling protocols across Indian and Chinese manufacturing plants. Particle size distribution requirements for high-fastness applications favor spray-dried powders with controlled agglomeration characteristics.
- Crystalline:High-purity grades for pharmaceutical and food applications require controlled cooling crystallization to achieve specific polymorphs. Jiangsu and Zhejiang-based manufacturers dominate this technology, creating single-source risk for European formulators.
- Liquid:Solvent-based slurries for continuous flow reactor feeding.
- Granular:Reduced dust generation for automated handling systems.
Powder maintains the volume base. Crystalline formats are climbing the fastest on pharmaceutical demand.
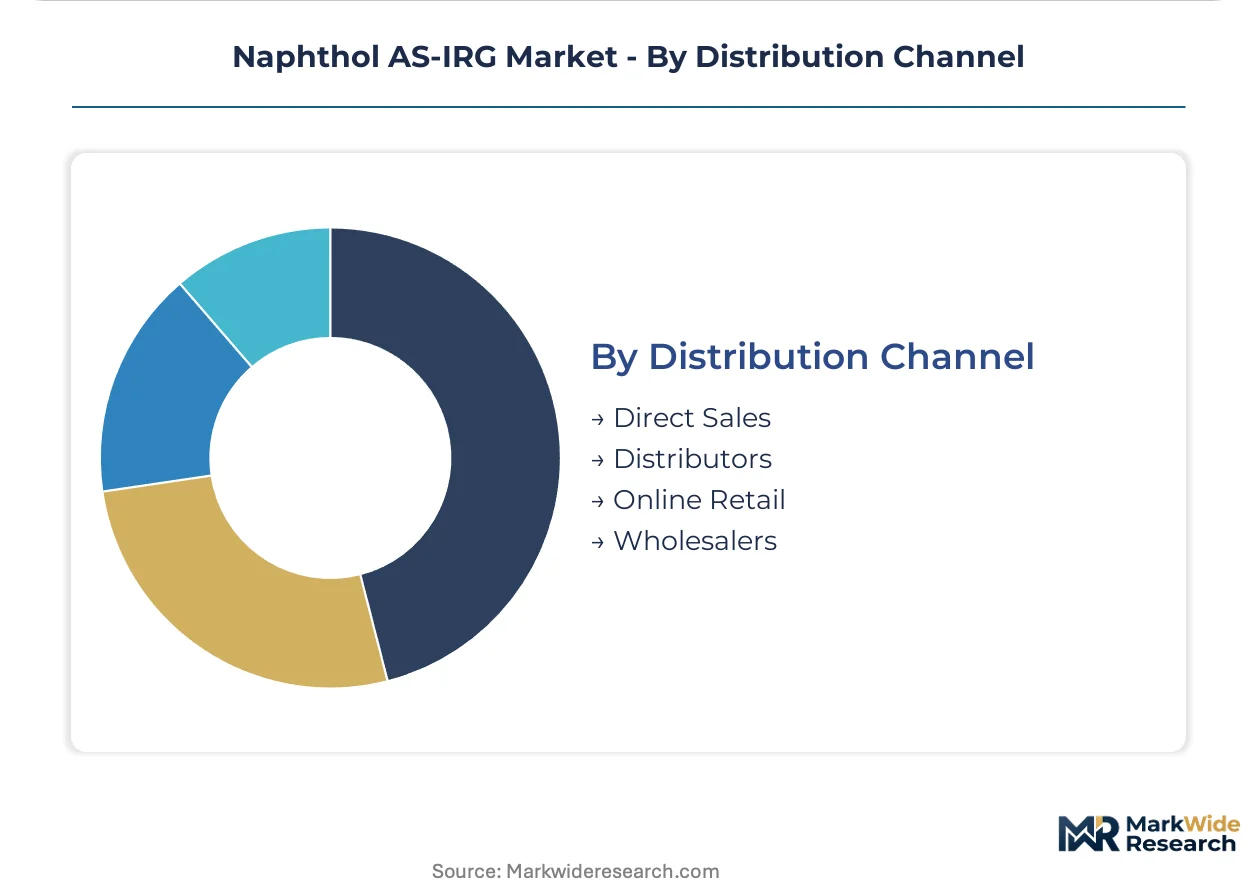
Distribution Channel:
Customer type fragmentation separates qualified buyers requiring technical documentation from commodity purchasers prioritizing price transparency, with digital platforms compressing traditional trading house markups.
- Direct Sales:Annual volume contracts between Indian naphthol producers and European pigment houses bypass layered distributor structures. Cloud-based spectrophotometry tools enable remote batch approval, reducing geographic friction in these direct relationships.
- Distributors:Traditional European trading houses retain relevance in Pharmaceutical Grade channels where regulatory documentation and local technical support justify margin premiums.
- Wholesalers:Serve fragmented textile chemical distributors in Turkey and Bangladesh.
- Online Retail:Emerging for small-volume laboratory and R&D procurement.
Direct Sales capture the expanding share. Distributors defend position in documentation-intensive grades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. European buyers prioritize REACH-registered intermediates for automotive coatings, while Indian procurement concentrates on textile cluster supply. Chinese demand splits between domestic pigment production and export-grade pharmaceutical qualification.
Germany
Automotive OEMs in Stuttgart and Munich mandate batch-to-batch crystallinity consistency for exterior azo pigments. ECHA's 2024 guidance on extractable aromatic amines drives reformulation of legacy pigment recipes. Pigment houses in Ludwigshafen and Leverkusen anchor qualified supply chains for high-fastness applications.
China
Domestic pigment manufacturers in Jiangsu and Zhejiang scale coupling component capacity for packaging ink applications. SAMR's GB standards under evolving oversight tighten purity thresholds for consumer-facing colorants. Crystallization technology for high-purity grades concentrates in Changzhou and Hangzhou chemical parks.
India
Textile chemical distributors in Gujarat and Maharashtra expand procurement of naphthol intermediates to serve domestic pigment formulators. CDSCO and BIS frameworks converge toward harmonized impurity profiles for export-bound dye intermediates. Dye intermediate producers in Ankleshwar and Tarapur scale backward integration into naphthol AS-IRG manufacturing.
Japan
Pigment houses in Osaka and Tokyo pilot continuous flow reactors for diazo coupling to reduce solvent waste. METI oversight of chemical manufacturing standards elevates documentation burdens for imported intermediates. Technical partnerships between Japanese pigment formulators and Indian suppliers compress qualification cycles through digital color matching platforms.
United States
Packaging ink formulators in the Midwest and Northeast prioritize SVHC-free certification for food-contact applications. FDA scrutiny of color additive petitions cascades backward to intermediate qualification requirements. Direct procurement relationships between US distributors and Indian producers disintermediate traditional European trading channels for commodity-grade volumes.
Naphthol AS-IRG Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with backward integration into dye intermediate manufacturing separating qualified suppliers from merchant producers. The upper tier captures premium positioning through captive feedstock security and established regulatory dossiers. Three archetypes dominate: integrated pigment houses with in-house naphthol production, specialized Indian dye intermediate manufacturers, and pharmaceutical-grade specialists with pharmacopeial traceability. Competitive moves center on capacity expansion in Indian textile clusters and technology licensing for continuous crystallization systems.
Within the integrated tier, BASF SE anchors European supply security through captive production serving pigment divisions. Laxmi Organic Industries Limited exemplifies the Indian specialist archetype with deep ties to domestic textile chemical channels. PRAVIN DYECHEM PVT. LTD occupies a position among specialized suppliers leveraging geographic proximity to Gujarat and Maharashtra industrial clusters. These three represent the competitive spectrum from global integrated players to regional merchant specialists.
| Leading Market Players |
|---|
| BASF SE |
| PRAVIN DYECHEM PVT. LTD |
| Laxmi Organic Industries Limited |
| Merck KGaA |
| Qingdao Longyuntong Corporation |
| Jiangsu Tianbo Chemical Co.Ltd. |
| Vipul Organics |
| Osaka Organic Chemical Industry Ltd. |
| Kiri Industries Ltd. |
| Others |
Value Chain & Pricing Dynamics
Phthalocyanine pigment substitution in blue and green shade applications simultaneously compresses azo pigment demand and shifts procurement geography toward Indian suppliers with cost-advantaged naphthol AS-IRG production. This displacement dynamic concentrates pricing power with Jiangsu and Zhejiang crystallization specialists while forcing European pigment houses to absorb REACH compliance premiums or exit qualified supply tiers entirely.
Pricing Analysis
Long-term offtake contracts dominate procurement between European pigment formulators and pre-registered naphthol suppliers with established REACH dossiers. Three-tier pricing structure across Pharmaceutical Grade, Application Grade, and Industrial Grade levels separates pharmacopeial-traceable material commanding premium positioning from commodity textile intermediates. Cost compression in Application Grade is intensifying because Indian domestic producers are scaling backward integration into dye intermediate manufacturing. Chemical Manufacturers in Germany and Japan show least price sensitivity due to OEM-mandated crystallinity specifications, while Turkish and Bangladeshi buying consortia prioritize price transparency over documentation.
Supply Chain Analysis
Strategic stockpiling of aniline derivatives buffers merchant naphthol producers against benzene spread volatility, while just-in-time delivery governs high-purity crystalline grades for pharmaceutical applications. Supply concentrates in China, India, and Germany, with Jiangsu-based manufacturers controlling crystallization technology for high-purity grades. Feedstock draws from aniline derivatives, naphthalene intermediates, and diazonium salt precursors. Single-source vulnerability runs through Changzhou and Hangzhou chemical parks for crystalline formats. Distribution runs through direct annual volume contracts and digital platforms disintermediating traditional European trading houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among Indian textile chemical distributors and European pigment houses with REACH-registered supply chains, fragmenting traditional trading house margins and compressing qualification timelines for merchant producers.
For Market Incumbents: Consolidate captive naphthol production through modular continuous flow reactor investments in Gujarat and Maharashtra clusters to secure feedstock against aniline volatility. Deepen pharmacopeial traceability systems to defend Pharmaceutical Grade positioning against emerging Indian specialists with CDSCO-compliant export capacity. Channel control through cloud-based spectrophotometry partnerships with Japanese pigment formulators reduces geographic friction in batch approval cycles.
For New Entrants and Emerging Players: CDSCO fast-track qualification for export-bound dye intermediates opens formulation access to European parenteral dye applications where pharmacopeial documentation limits qualified sources. Target commodity-grade textile channels in Turkey and Bangladesh where digital platform procurement prioritizes price transparency over REACH dossiers. Joint venture crystallization technology licensing from legacy German pigment houses accelerates particle size distribution capability acquisition.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors backward-integrated specialists with regulatory dossier depth over merchant producers exposed to multi-jurisdiction compliance burdens. Acquisition targets with established SAMR GB standard pre-certification and BIS harmonized impurity profiles offer 5-10 year viability through qualification barrier protection. Watch for ECHA guidance revisions on extractable aromatic amines as inflection indicators for reformulation-driven intermediate demand shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Naphthol Manufacturing | Ankleshwar and Tarapur producers reduce import dependence from Jiangsu suppliers through captive coupling component capacity. |
| Continuous Crystallization Technology Licensing | Modular skid-mounted units from Italian and Japanese pilot programs fragment conventional batch manufacturing economics. |
| REACH Dossier Pre-Registration Investment | SVHC-free certification secures European Economic Area pigment channel access against Article 33 disclosure obligations. |
| Digital Color Matching Platform Partnership | Cloud-based spectrophotometry compresses qualification cycles between Indian suppliers and European automotive coatings formulators. |
| Pharmaceutical Grade USP/EP Compliance Buildout | Merck KGaA and Osaka Organic Chemical Industry standards limit qualified supply sources for parenteral dye applications. |
Study Parameters
A spread of perspectives from pigment house procurement directors, dye intermediate plant managers, regulatory affairs specialists at REACH consultancy firms, and textile chemical distributors converged on the working assumptions underlying volume and value estimates. Primary interviews with these stakeholders combined with secondary validation from customs and trade data, SEC 10-K filings of listed pigment manufacturers, ACC and Cefic chemical industry reports, and BIS standard documentation. Bottom-up crystallization capacity assessments triangulated against top-down azo pigment consumption patterns across automotive coatings and packaging ink applications.
Segmentation dimensions modeled include grade tier (Pharmaceutical, Application, Industrial, Food), end-use industry (Chemical Manufacturers, Pharmaceuticals, Food Producers, Agriculture), form factor (Powder, Crystalline, Liquid, Granular), and regional production hub (Gujarat, Maharashtra, Jiangsu, Zhejiang, Ludwigshafen). CAGRs were derived through regression analysis of historical naphthol intermediate trade flows and forward projection of OEM specification tightening trajectories. Key inputs encompassed aniline derivative pricing spreads, REACH registration status distributions, and textile cluster capacity expansion announcements.
Underlying assumptions cover sustained automotive coatings specification tightening, stable aniline feedstock availability, and gradual BIS-CDSCO harmonization, with deviation risk concentrated in ECHA guidance revisions and SAMR GB standard enforcement intensity. Revision becomes warranted when phthalocyanine substitution rates in packaging inks exceed modeled thresholds or when Indian PLI scheme disbursements accelerate domestic capacity additions beyond projected trajectories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Global Flash Chromatography Market
Specialty Chemicals
Organo-Modified Siloxanes Market
Specialty Chemicals
Petroleum Jelly Market
Specialty Chemicals
VCI Aerosol Market
Specialty Chemicals
Avobenzone Market
Specialty Chemicals
Xanthene Derivatives Market
Specialty Chemicals
Glucosinolates Market
Specialty Chemicals
Technical Aerosol Market
Specialty Chemicals
Brominated Flame Retardants Market
Specialty Chemicals
Australia and New Zealand Aerosol Market
Specialty Chemicals
Ethylhexane Diol Market
Specialty Chemicals
Middle East and Africa Amino Acids Market
Specialty Chemicals
Global Silicone Defoamer Market
Specialty Chemicals
Phosphatidylcholine Market
Specialty Chemicals
Synthetic and Bio-Based Adipic Acid Market
Specialty Chemicals
Textile Flame Retardants Market