
 Silicone Rubber Market | 2026-2036
Silicone Rubber Market Size, Share, and Industry Trends Forecast 2026-2036
Silicone Rubber Market Outlook
Modular kit configurations for liquid silicone rubber dispensing systems is hardening as the default procurement format for mid-volume medical molders. Dow leverages its upstream siloxane capacity to sustain pricing leverage across formulation tiers. Wacker Chemie AG anchors European supply through its Burghausen integrated site, while Shin-Etsu Chemical dominates Asian electronics-grade output with captive monomer production.
Silicone rubber denotes a synthetic elastomer composed of polysiloxane chains with silicon-oxygen backbones and organic side groups, typically vulcanized via platinum-catalyzed addition or peroxide curing to achieve temperature stability from minus sixty to plus two hundred thirty degrees Celsius. Its primary industrial purpose centers on sealing, insulating, and cushioning applications where thermal cycling, chemical exposure, or biocompatibility preclude organic elastomers. Elastomers command the largest product-type position due to entrenched automotive and industrial demand, while liquid silicone rubber formulations represent the fastest-expanding formulation category driven by thin-wall medical molding and overmolding complexity. Medical end-use applications concentrate the highest margin pools, though automotive gaskets and electronics insulation still absorb the greatest absolute volume.
FDA biocompatibility standards under ISO 10993 and EPA silicone emissions guidelines shape formulation chemistry and facility permitting for US-based producers. REACH substance restrictions and the EU MDR device regulations in Europe compel full material traceability and restricted-substance documentation across supply chains. China's GB standards and NMPA medical device rules add parallel compliance layers for market access. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and qualification gaps.
Market Dynamics
Medical device manufacturers are consolidating procurement around certified liquid silicone rubber grades as EU MDR traceability mandates and FDA biocompatibility standards harden compliance thresholds, compressing qualification timelines and favoring converters with integrated formulation-to-molding capabilities.
Growth Catalysts
- EU MDR traceability mandates:Full material genealogy requirements are forcing medical molders toward pre-certified silicone suppliers, locking in multi-year supply agreements with qualified converters.
- Thin-wall medical molding:Liquid silicone rubber formulations enable complex overmolding of diagnostic wearables and implantable sensors, expanding addressable component geometries.
- Germany's automotive supplier corridor:Thermal management gasket demand from EV battery pack manufacturers sustains high-volume elastomer consumption despite powertrain electrification headwinds.
Market Restraints
- Siloxane monomer concentration:Captive production at Dow, Wacker, and Shin-Etsu limits third-party formulation flexibility and sustains input cost pass-through power.
- Platinum catalyst volatility:Precious metal price swings directly compress margins for addition-cure liquid silicone rubber grades used in medical applications.
- Thermoplastic elastomer substitution:TPE overmolding advances threaten silicone in non-implantable consumer electronics sealing where biocompatibility is non-critical.
Strategic Opportunities
- India's medical device PLI scheme:Domestic manufacturing incentives attract silicone converters to establish localized compounding and molding capacity for export-oriented OEMs.
- Self-healing silicone formulations:Autonomous repair chemistry extends sealant lifecycle in infrastructure and renewable energy applications, opening premium pricing tiers.
- Digital dispensing integration:Closed-loop dosing systems combining liquid silicone rubber with real-time viscosity monitoring reduce scrap rates and accelerate mold qualification.
Industry Challenges
- ISO 10993-18 chemist scarcity:Qualified toxicologists capable of executing extractables and leachables protocols command premium compensation, extending medical grade certification timelines.
- Legacy injection molding asset retrofit:Converting thermoplastic lines to liquid silicone rubber processing requires specialized cold runner systems and vacuum venting, straining mid-volume converter capex.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Silicone Rubber Market |
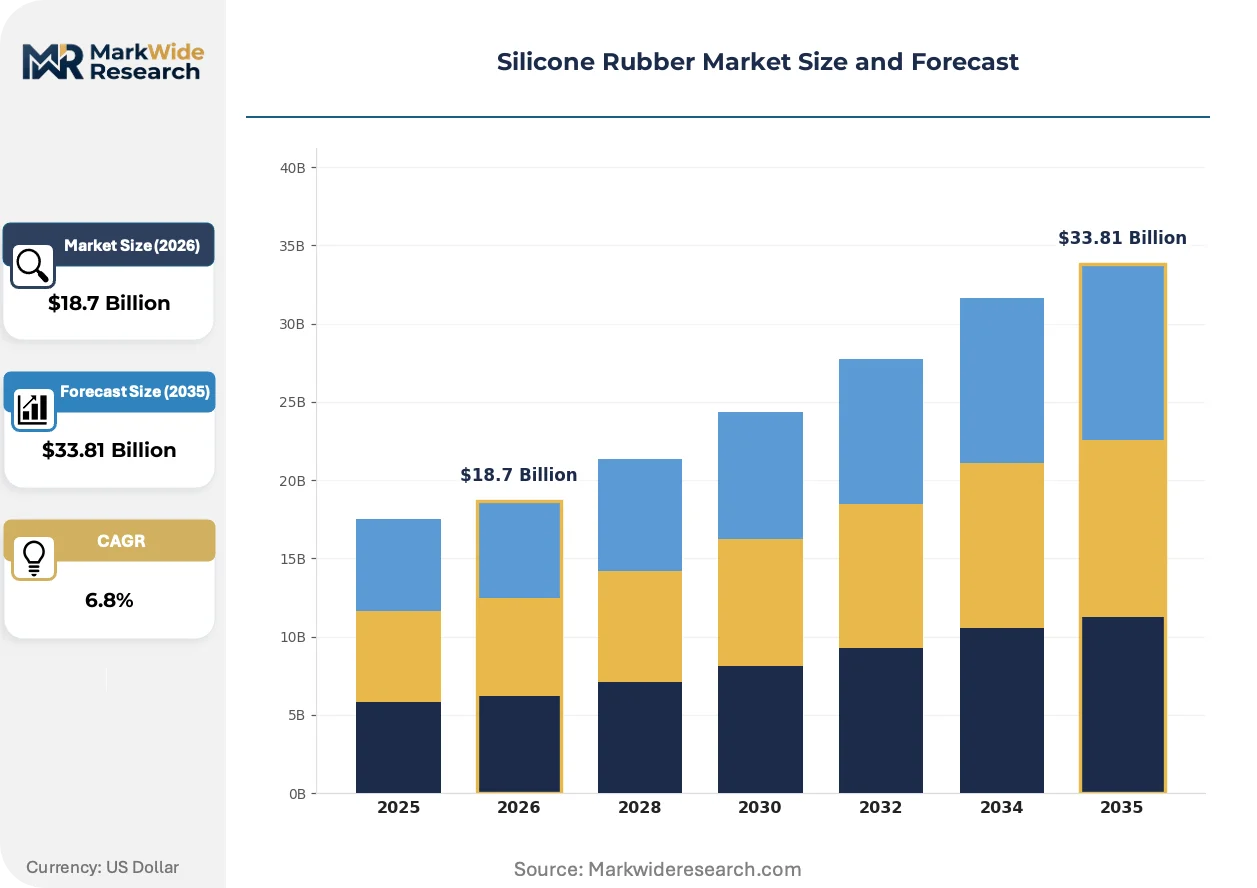
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermoplastics, Elastomers, Adhesives, Sealants End Use Industry: Automotive, Electronics, Medical, Aerospace Formulation: Liquid Silicone Rubber, Room Temperature Vulcanizing, High-Temperature Vulcanizing, Coatings Application: Gaskets, Molded Parts, Insulation, Soft-touch Products |
| Companies Covered | Momentive Performance Materials, Stockwell Elastomerics, Dow, Rui-He New Material, Suconvey Rubber, Wacker Chemie AG, Shin-Etsu Chemical, Pierce-Roberts Rubber Company, Elkem Silicones, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Silicone Rubber Market Strategic Shifts
Formulation chemistry and regulatory data architecture are converging to reshape how silicone rubber converters demonstrate compliance, with digital traceability systems now as critical as material performance specifications.
Platinum-catalyzed liquid silicone rubber with integrated in-mold sensing capabilities is integrating conductive fillers and microfluidic channels directly into medical device housings. Diagnostic wearable manufacturers in China's Shenzhen electronics cluster are adopting these grades at accelerated qualification paces. The technology is integrating functional electronics into previously passive sealing components, compressing assembly steps and shifting value capture toward compounders with device physics expertise.
REACH substance restriction updates under ECHA's SVHC candidate list are compelling silicone formulators to substitute legacy plasticizers and residual catalyst packages. Industrial consequence includes reformulation costs and supply chain requalification for medical device exporters. European converters serving implantable neuromodulation device OEMs are responding by accelerating partnerships with siloxane producers offering pre-audited raw material portfolios.
Modular kit configurations for liquid silicone rubber dispensing equipment are displacing integrated system procurement among mid-volume medical molders. Equipment distributors in Germany's Baden-Württemberg manufacturing belt are unbundling dosing units, mixing stations, and mold temperature controllers into separately configurable modules. This pattern is most visible among German automotive suppliers pivoting capacity toward medical device contracts requiring rapid process reconfiguration.
Silicone Rubber Market Segmentation
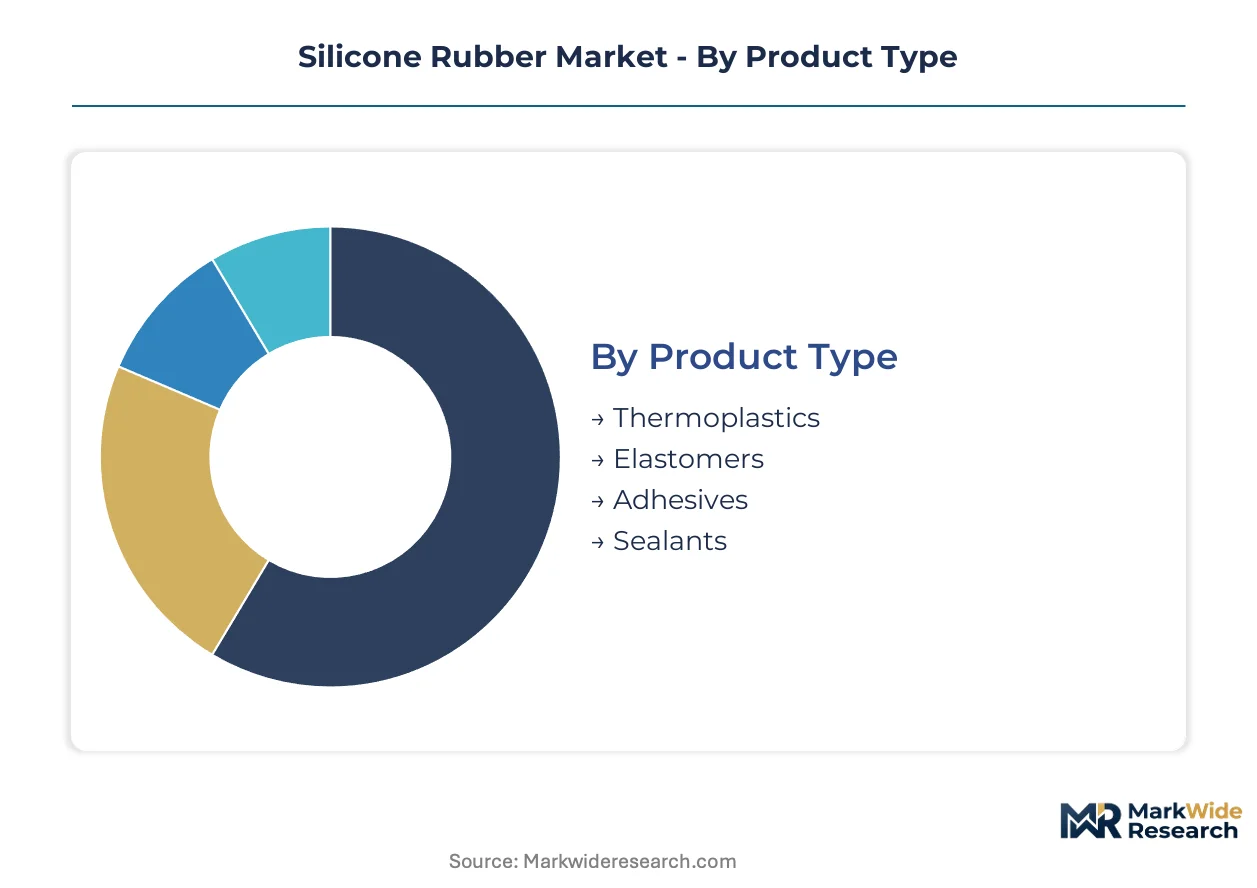
Silicone rubber procurement decisions hinge on whether components operate as standalone seals or integrate into complex assemblies. Formulation chemistry and curing protocols determine which segments capture medical certification premiums versus commodity automotive volume.
Product Type:
Integration depth varies sharply across this category, with some grades functioning as finished goods and others requiring secondary processing into composite structures.
- Elastomers:Cross-linked polysiloxane networks deliver the temperature stability and compression set resistance that automotive gasket manufacturers in Germany's supplier corridor demand. EV battery pack sealing consumes the greatest absolute tonnage despite powertrain electrification reducing engine bay applications.
- Thermoplastics:Silicone-modified thermoplastic compounds enable overmolding onto rigid substrates for electronics housings, compressing assembly steps in China's Shenzhen manufacturing cluster. Medical device OEMs favor these grades for diagnostic wearables requiring soft-touch grips combined with structural rigidity.
- Adhesives:One-part and two-part silicone bonding systems serve infrastructure and renewable energy sealing where substrate mismatch precludes mechanical fastening.
- Sealants:Neutral-cure and acetoxy-cure formulations dominate construction and industrial maintenance applications requiring weathering resistance.
Volume placements concentrate in Elastomers; the faster expansion belongs to Thermoplastics.
End Use Industry:
Margin structures diverge dramatically across end-use sectors, with regulatory burden and qualification timelines determining pricing power.
- Medical:Implantable neuromodulation devices and diagnostic wearables command the steepest certification premiums under FDA biocompatibility standards and EU MDR traceability mandates. Liquid silicone rubber grades for thin-wall molding absorb extended ISO 10993-18 extractables testing timelines.
- Automotive:Thermal management gaskets for EV battery packs sustain high-volume consumption from Germany's Baden-Württemberg supplier belt. Powertrain electrification shifts demand toward coolant system sealing away from traditional engine applications.
- Electronics:High-purity insulation grades serve semiconductor fabrication equipment and consumer device waterproofing in Asian manufacturing clusters.
- Aerospace:Fuel-resistant fluorosilicone formulations meet FAA fire-smoke-toxicity specifications for cabin and engine sealing.
Medical captures the highest margin pools; automotive maintains the greatest absolute throughput.
Formulation:
Curing chemistry dictates processing equipment requirements and cycle economics, separating continuous production from batch fabrication.
- Liquid Silicone Rubber:Platinum-catalyzed addition-cure systems enable automated injection molding of complex geometries with flash-free precision. Medical device manufacturers in China's electronics clusters adopt these grades for diagnostic wearable housings integrating microfluidic channels.
- High-Temperature Vulcanizing:Peroxide-cured solid silicone compounds serve compression-molded automotive gaskets and industrial rolls requiring thick-section curing.
- Room Temperature Vulcanizing:Condensation-cure systems support field-applied sealants and prototyping where oven curing is impractical.
- Coatings:Solvent-borne and solventless silicone finishes provide thermal protection and release properties for cookware and industrial tooling.
High-Temperature Vulcanizing retains the largest installed base; Liquid Silicone Rubber is climbing the fastest.
Application:
Component geometry and performance specifications determine whether silicone serves a passive sealing function or an active functional role.
- Gaskets:Static and dynamic sealing profiles absorb the greatest formulation volume across automotive powertrain and industrial flange applications. Compression set resistance specifications tighten for EV thermal management systems.
- Molded Parts:Custom geometries from liquid silicone rubber enable overmolded medical device components combining sealing with biocompatible surface contact. Complex part designs favor converters with integrated formulation-to-molding capabilities.
- Insulation:Wire and cable jacketing serves high-temperature electrical applications where organic elastomers degrade.
- Soft-touch Products:Overmolded grips and consumer goods surfaces compete with thermoplastic elastomer alternatives where biocompatibility is non-critical.
Gaskets dominate current placements; molded parts show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicone rubber production clusters in Germany, China, and the United States while consumption spreads across medical device manufacturing hubs and automotive supplier corridors. Raw material integration determines regional cost structures.
United States
FDA biocompatibility standards under ISO 10993 drive medical-grade silicone procurement from domestic compounders. The EPA regulates silicone emissions from manufacturing facilities. Medical device OEMs in Minnesota's Twin Cities cluster source certified liquid silicone rubber for implantable components.
Germany
EV battery thermal management gaskets sustain elastomer demand from Baden-Württemberg automotive suppliers. REACH substance restrictions and EU MDR traceability mandates compel full material genealogy documentation. Wacker Chemie's Burghausen integrated site anchors European siloxane supply.
China
Electronics-grade silicone consumption concentrates in Shenzhen's manufacturing cluster for diagnostic wearables. NMPA medical device rules and GB standards impose parallel compliance requirements. Domestic converters serve both export-oriented OEMs and local healthcare procurement.
Japan
Semiconductor fabrication equipment insulation drives high-purity silicone demand from Japanese electronics manufacturers. METI industrial standards govern material specifications for advanced applications. Shin-Etsu's captive monomer production dominates Asian electronics-grade output.
India
Medical device PLI scheme incentives attract silicone converters to establish localized compounding capacity. CDSCO regulations align with international standards for export-oriented manufacturing. Gujarat and Maharashtra industrial corridors host emerging molding operations serving global OEMs.
Silicone Rubber Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across formulation tiers, creating a tiered structure where upstream siloxane integration determines pricing power. Dow, Wacker, and Shin-Etsu maintain captive monomer production, while mid-volume converters rely on third-party raw material supply. Two strategic archetypes dominate: integrated siloxane-to-compound producers and specialized medical-grade formulators. Competitive moves center on multi-year supply agreements with qualified medical molders and modular dispensing equipment partnerships.
Within the integrated producer tier, Dow and Wacker Chemie AG exemplify upstream-backward structures with siloxane manufacturing anchored in North American and European production complexes. Shin-Etsu Chemical occupies a comparable position in Asian supply architecture. Among specialized fabricators, Momentive Performance Materials and Elkem Silicones represent formulators serving medical and industrial end-use segments without captive raw material integration. Stockwell Elastomerics and Pierce-Roberts Rubber Company sit within the regional converter tier, emphasizing customized compounding and molded component supply.
| Leading Market Players |
|---|
| Momentive Performance Materials |
| Stockwell Elastomerics |
| Dow |
| Rui-He New Material |
| Suconvey Rubber |
| Wacker Chemie AG |
| Shin-Etsu Chemical |
| Pierce-Roberts Rubber Company |
| Elkem Silicones |
| Others |
Value Chain & Pricing Dynamics
Qualified toxicologists capable of executing ISO 10993-18 extractables and leachables protocols command premium compensation in Minnesota's Twin Cities medical device cluster, widening labor-cost differentials between medical-grade certified converters and commodity automotive suppliers. This workforce scarcity stratifies pricing tiers across the silicone rubber value chain.
Pricing Analysis
Margin tightening in medical-grade liquid silicone rubber reflects platinum catalyst volatility and extended certification timelines under FDA biocompatibility standards. Three-tier pricing structure across implantable-certified, diagnostic-grade, and industrial-standard levels separates converters by qualification depth. Cost-down pressure on automotive elastomer grades accelerates because EV battery pack manufacturers negotiate volume offtake agreements with Germany's Baden-Württemberg supplier belt. Automotive OEMs exhibit highest price sensitivity; implantable neuromodulation device manufacturers absorb premiums for traceability-assured supply.
Supply Chain Analysis
Siloxane monomer supply rests on captive production at integrated producers in the United States, Germany, and Japan. Raw material flows draw from chlorosilane cracking operations, platinum group metal catalysts, and specialty filler packages. Single-source vulnerability concentrates around Shin-Etsu's Asian electronics-grade output and Wacker's Burghausen European anchor. Distribution runs through qualified converter networks serving medical molders with full material genealogy documentation under EU MDR traceability mandates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The silicone rubber market sits in a formulation-transition phase as liquid silicone rubber grades displace high-temperature vulcanizing compounds in thin-wall medical molding applications.
For Market Incumbents: Anchor multi-year supply agreements with qualified medical molders facing compressed EU MDR qualification timelines. Deepen backward integration into siloxane monomer production to defend margin position against platinum catalyst volatility. Prioritize certification investment in ISO 10993-18 testing capabilities to capture implantable device premiums. For New Entrants and Emerging Players: Enter via India's medical device PLI scheme corridors in Gujarat and Maharashtra, where domestic manufacturing incentives attract localized compounding capacity for export-oriented OEMs. Target diagnostic wearable segments in China's Shenzhen electronics cluster requiring rapid mold qualification. Pursue modular dispensing equipment partnerships as the go-to-market angle. For Investors and Strategic Acquirers: Re-rating potential sits with specialized medical-grade formulators possessing integrated formulation-to-molding capabilities given EU MDR traceability mandates and FDA biocompatibility standards hardening compliance thresholds. Long-term viability favors converters with captive siloxane supply or exclusive raw material partnerships. Watch platinum group metal price trajectories as margin compression inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Siloxane Monomer | Dow and Wacker sustain pricing leverage across formulation tiers through captive chlorosilane cracking. |
| Medical Grade Certification Investment | ISO 10993-18 testing capabilities command premium positioning with implantable neuromodulation OEMs. |
| Modular Dispensing Equipment Partnership | Germany's Baden-Württemberg belt unbundles dosing units for rapid medical process reconfiguration. |
| India PLI Scheme Localization | Gujarat and Maharashtra corridors attract compounding capacity for export-oriented medical device manufacturing. |
| Self-Healing Formulation Development | Autonomous repair chemistry opens premium tiers in renewable energy infrastructure sealing applications. |
Study Parameters
Document review covered SEC 10-K filings from Dow and Wacker Chemie, complemented by interviews with medical device procurement managers, silicone compounding plant managers, and regulatory affairs leads at implantable neuromodulation OEMs. Secondary validation drew from FDA 510(k) databases, EMA MDR guidance documents, and customs trade data on siloxane monomer flows. Bottom-up volume estimates triangulated against top-down industry association data from Cefic and ACC.
Historical shipment patterns cross-referenced against panel input from automotive supplier procurement teams and diagnostic wearable manufacturers. The analytical framework modeled formulation chemistry, end-use industry, and regional regulatory cluster dimensions across the projection horizon. CAGRs derived from elasticity-adjusted demand curves incorporating EV battery pack sealing content and thin-wall medical molding penetration rates. Platinum group metal price trajectories and EU MDR implementation timelines served as key forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under platinum catalyst price spikes or REACH substance restriction expansions. Assumptions reflect current regulatory trajectories and technology substitution patterns. A small set of named triggers—platinum volatility, MDR enforcement intensity, thermoplastic elastomer substitution rates—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rubber
Rubber Plated Hose Market
Rubber
Global Rubber Vulcanization Market
Rubber
Rubber Bulb Seals Market
Rubber
Europe Rubber Hose Market
Rubber
Polybutadiene Rubber (PBR) Market
Rubber
Global Automotive Elastomers Market
Rubber
Rubber Reinforcing Chemicals Market
Rubber
Performance Elastomers Market
Rubber
Rubber Splicing Tape Market
Rubber
Global Rubber Coated Fabrics Market
Rubber
Isoprene Rubber Market
Rubber
Rubber Sand Market
Rubber
EMEA and Asia Pacific Electrical Insulating Rubber Gloves Market
Rubber
Rubber Flooring Market
Rubber
Rubber Accelerators Market
Rubber
Hospital Rubber Sheet Market