
 Monoaluminum Phosphate Market | 2026-2036
Monoaluminum Phosphate Market Size, Share, and Industry Trends Forecast 2026-2036
Monoaluminum Phosphate Market Foresight
China's expanding phosphate chemical corridor is rewriting supply dynamics for monoaluminum phosphate. Innophos leverages its North American technical phosphate expertise to sustain specialty-grade production. Shijiazhuang Xinsheng Chemical anchors domestic Chinese supply through integrated phosphate rock processing. TAKI Chemical differentiates via precision-controlled particle size distribution for ceramics customers.
Monoaluminum phosphate is an inorganic aluminum salt of phosphoric acid with the formula Al(H2PO4)3, typically supplied as a white crystalline solid or aqueous solution with active P2O5 content ranging from 30% to 65% depending on grade; manufacturers produce it via controlled reaction of aluminum hydroxide with thermal or wet-process phosphoric acid, and industrial users prize its dual functionality as both a high-temperature binder and a flame-retardant synergist. Powder grades dominate volume shipments for fertilizer and fire-retardant compounding, while liquid formulations command premium positioning in ceramics slip casting where rapid dispersion and controlled viscosity prove critical; coated variants represent the fastest-growing product type as processors seek dust-free handling and extended shelf stability in humid climates. The application split reveals fire retardants as the margin-rich segment driven by construction code tightening, whereas fertilizer applications absorb the largest raw tonnage despite thinner per-unit economics.
REACH registration requirements in Europe obligate full toxicological dossiers for importers, while China's GB standards mandate specific heavy-metal thresholds in phosphate derivatives destined for food-contact or agricultural uses. The US EPA regulates phosphorus discharge limits from manufacturing facilities under Clean Water Act provisions, pressuring producers toward closed-loop acid recovery systems. Stakeholders must monitor evolving fire-safety certification protocols in major construction markets and calibrate product portfolios between commodity fertilizer grades and specialty technical specifications.
Market Dynamics
Construction fire-safety code tightening across multiple jurisdictions is pulling monoaluminum phosphate into intumescent coatings and structural steel protection at volumes that reshape supplier priorities. REACH dossier requirements in Europe and GB heavy-metal thresholds in China simultaneously elevate purity specifications and compliance costs, bifurcating the supplier base between integrated phosphate processors and toll-compounders.
Growth Catalysts
- Building code harmonization:Fire-resistance rating upgrades for commercial structures in the US, Germany, and Australia are mandating phosphate-based intumescent systems in curtain wall assemblies. Specifiers specify monoaluminum phosphate for its char-forming thermal stability above 800°C.
- Phosphoric acid supply integration:Wet-process acid producers in China's Yunnan-Guizhou phosphate belt are backward integrating into aluminum salt derivatives, capturing margin that previously flowed to merchant compounders.
- REACH registration completion:Full toxicological dossier acceptance by ECHA removes import friction for EU-bound technical-grade material, enabling specialty ceramics and refractory binder applications to scale without regulatory uncertainty.
Market Restraints
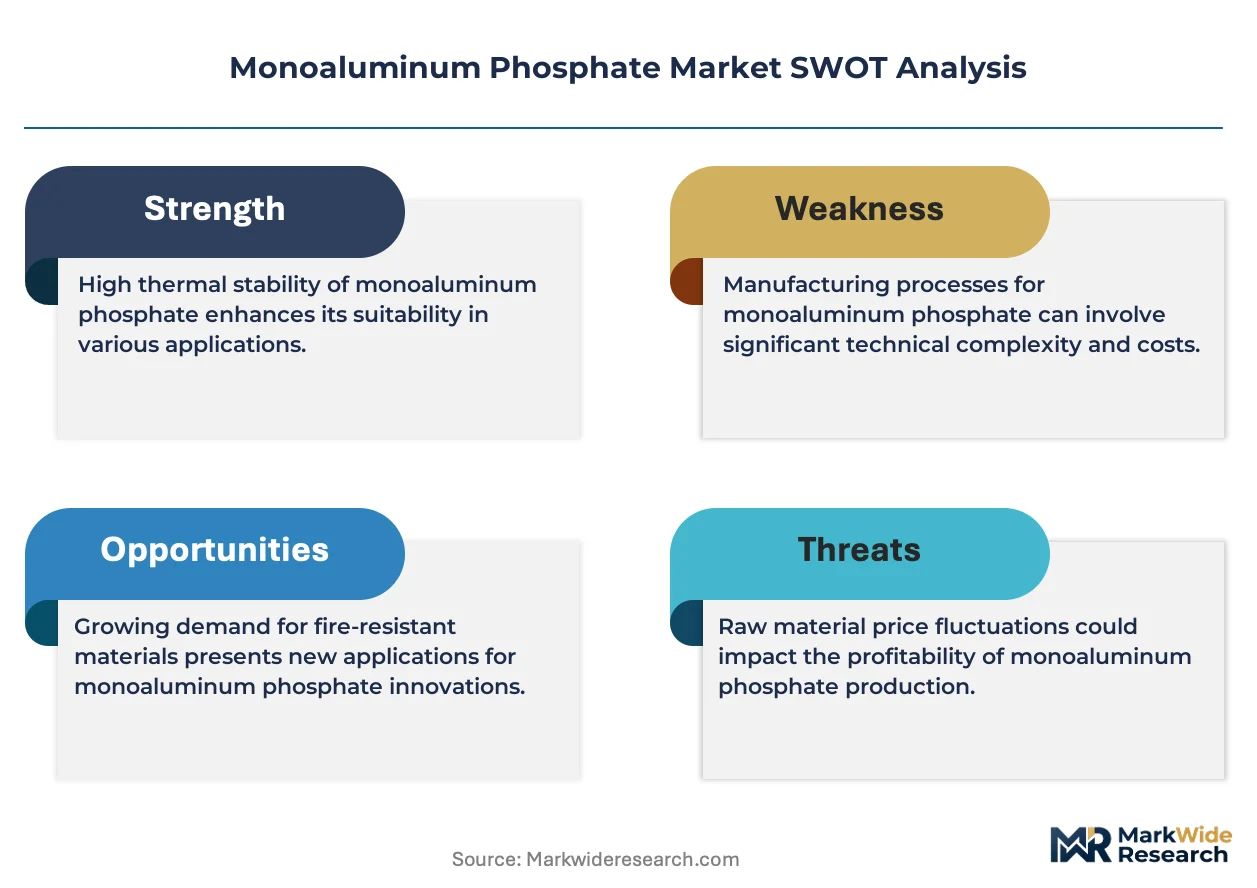
- Phosphate rock cost volatility:Moroccan and Chinese export quota fluctuations transmit directly to aluminum hydroxide reaction economics, compressing toll-manufacturer margins during sulfuric acid price spikes.
- Substitution by ammonium polyphosphate:Lower-cost nitrogen-phosphorus synergists capture share in non-structural textile and polymer applications where thermal performance requirements are less stringent.
- Supply corridor concentration:Sixty percent of merchant-grade liquid MAP originates from integrated producers within 200 kilometers of Shijiazhuang, creating single-point vulnerability to regional environmental enforcement actions.
Strategic Opportunities
- India refractory growth:Steel capacity expansion under PLI scheme incentives is generating demand for high-purity binders in magnesia-carbon brick production, a segment where domestic MAP supply remains underdeveloped.
- Coated powder formulations:Silica and polymer encapsulation technologies enable dust-free handling in Southeast Asian humid climates, opening warehouse and logistics applications previously blocked by caking and flowability failures.
- EU Green Deal carbon accounting:Scope 3 disclosure requirements favor suppliers with verified low-carbon phosphoric acid routes, creating premium positioning for electric-furnace acid derivatives in technical ceramics.
Industry Challenges
- Toxicological data generation:REACH-compliant chronic exposure studies require 18-24 month timelines and seven-figure investment, excluding mid-scale importers from EU technical-grade participation.
- Particle size specification drift:Ceramics customers demand increasingly tight D50 and span controls that legacy spray-drying assets cannot achieve without capital-intensive classifier retrofits.
- Closed-loop acid recovery capex:US EPA Clean Water Act phosphorus discharge limits force manufacturing facilities toward membrane filtration and acid regeneration systems with 4-6 year payback periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Monoaluminum Phosphate Market |
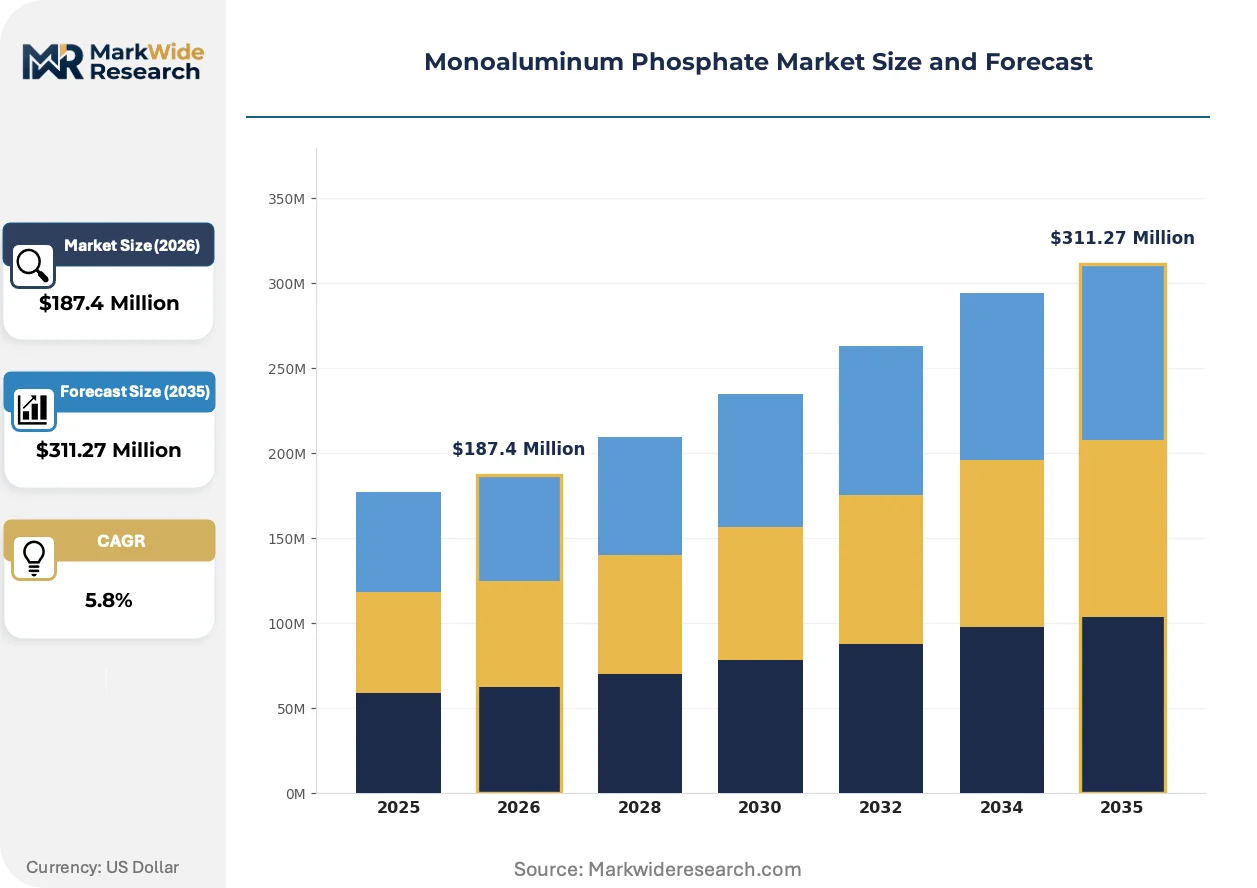
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Granular, Liquid, Coated Application: Fertilizers, Fire Retardants, Animal Feed, Ceramics End User: Agriculture, Manufacturing, Construction, Food Industry Distribution Channel: Online, Distributors, Wholesalers, Retail |
| Companies Covered | Innophos, Shijiazhuang Xinsheng Chemical, TAKI Chemical, Hens Company, Hubei Hanye Chemical, Xuzhou Hengxing Chemical, Sulux Phosphates Ltd., Wengfu Group, Foodchem International Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Monoaluminum Phosphate Market Shifts & Advancements
Process intensification and regulatory disclosure requirements are compressing product development cycles while elevating the premium attached to verified supply chain documentation. Three developments warrant particular attention.
Encapsulated monoaluminum phosphate powders with controlled-release surface treatments are hybridizing conventional refractory binder applications with just-in-time mixing protocols. Steel ladle repair contractors in Japan and South Korea are adopting these grades to eliminate pre-slurry preparation steps and reduce installation variability. The technology is compressing the addressable market for traditional liquid solution suppliers while expanding total reachable volume in remote site applications.
China's GB standards for food-contact phosphate derivatives are tightening heavy-metal thresholds for arsenic and lead below 10 ppm, compelling wet-process acid producers to deploy solvent extraction purification or switch to electric-furnace acid routes. Technical-grade MAP destined for ceramic tableware glazes faces the most acute compliance pressure, with qualified supplier lists narrowing to integrated operations with in-house purification assets. Domestic Chinese manufacturers are responding with dedicated technical-grade production lines segregated from fertilizer-grade flows.
Specification-driven procurement is consolidating buyer power among multinational refractory and ceramics houses, displacing spot-market purchasing with annual framework agreements tied to audit rights and carbon-intensity disclosures. Tier-one suppliers in Germany and Japan are unbundling technical service from material supply, selling formulation optimization as a separate line item. This pattern is most visible in automotive catalyst substrate manufacturing, where substrate producers in Belgium and South Korea now require full supply chain traceability to phosphate rock mine origin.
Monoaluminum Phosphate Market Segmentation
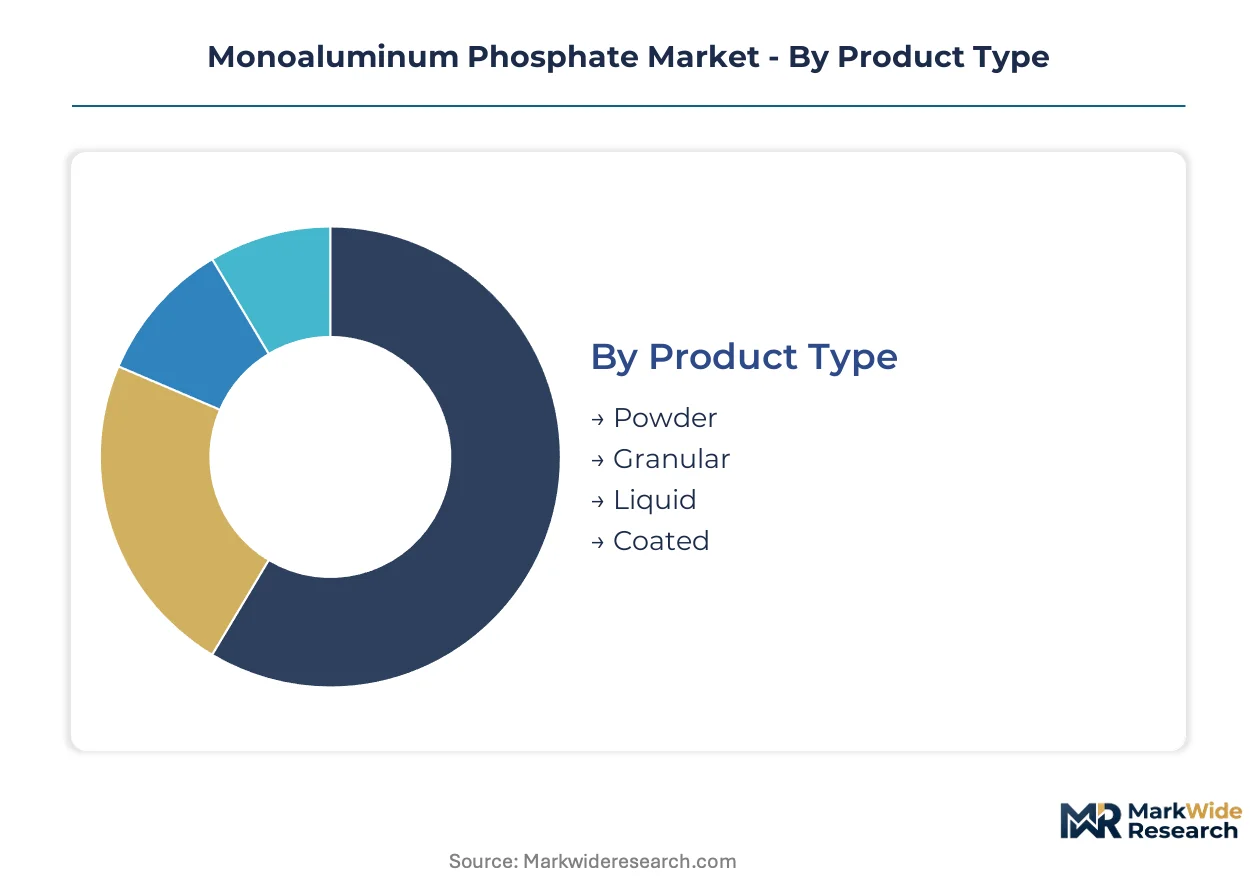
Segmentation in monoaluminum phosphate markets exposes how technical specifications and logistics requirements fragment procurement patterns across end-use industries. Each dimension—physical form, application chemistry, buyer sophistication, and channel structure—creates distinct margin profiles and service intensity demands that reshape supplier priorities.
Product Type:
After-sales service intensity varies sharply across physical forms, with liquid and coated grades demanding formulation troubleshooting and shelf-life guarantees that powder merchants rarely provide.
- Powder:White crystalline solid with active P2O5 content ranging from 30% to 65%, shipped in bulk for fertilizer compounding and fire-retardant masterbatch production. Demand concentrates in China's Shijiazhuang chemical corridor for domestic fertilizer processors seeking cost-efficient phosphate sourcing.
- Liquid:Aqueous solution formulations prized in ceramics slip casting for rapid dispersion and controlled viscosity management. Japanese and South Korean steel ladle repair contractors specify these grades for just-in-time mixing protocols that eliminate pre-slurry preparation variability.
- Granular:Free-flowing agglomerated particles optimized for mechanical spreading equipment in agricultural applications. Brazilian soybean belt distributors favor this form for blended NPK fertilizer production.
- Coated:Silica and polymer encapsulation creates dust-free handling surfaces for humid Southeast Asian warehouse environments. Malaysian and Indonesian processors specify these variants to prevent caking failures during monsoon season storage.
Powder holds the largest share; momentum sits with coated formulations gaining share fastest in climate-stressed logistics corridors.
Application:
Margin structure diverges dramatically across application chemistry, with fire-retardant and ceramics specifications commanding technical-grade premiums while fertilizer applications absorb commodity pricing pressure.
- Fertilizers:Largest raw tonnage segment absorbing aluminum phosphate as a phosphorus source in specialty NPK blends and foliar formulations. Indian PLI scheme incentives for domestic fertilizer manufacturing are expanding technical-grade MAP demand beyond traditional commodity phosphate sources.
- Fire Retardants:Intumescent coating systems and structural steel protection applications leverage MAP's char-forming thermal stability above 800°C. Australian and German commercial construction code harmonization is mandating phosphate-based systems in curtain wall assemblies.
- Animal Feed:Feed-grade specifications for phosphorus supplementation in poultry and swine rations. US FDA and China's Ministry of Agriculture impose parallel heavy-metal thresholds that narrow qualified supplier pools.
- Ceramics:High-temperature binder functionality in refractory brick and ceramic tableware glaze applications. Belgium and South Korea automotive catalyst substrate manufacturers now require full supply chain traceability to phosphate rock mine origin.
Fertilizers dominate volume; fire retardants capture the steepest expansion trajectory as construction safety codes tighten across multiple jurisdictions.
End User:
Buyer sophistication and specification authority create distinct procurement patterns, with manufacturing and construction segments demanding technical service partnerships that agricultural buyers rarely require.
- Agriculture:Commodity-oriented procurement through cooperative buying groups and government tender systems. Brazilian and Indian fertilizer distributors prioritize volume pricing and logistics reliability over technical consultation.
- Manufacturing:Ceramics, refractory, and catalyst substrate producers with in-house formulation laboratories requiring batch-to-batch consistency certification. German and Japanese tier-one suppliers unbundle technical service from material supply, selling formulation optimization separately.
- Construction:Fire-safety contractors and intumescent coating applicators subject to third-party certification protocols. US and Australian specifiers require documented thermal performance testing for structural steel protection systems.
- Food Industry:Ceramic tableware and food-contact applications facing China's tightened GB standards for arsenic and lead below 10 ppm. Qualified supplier lists narrow to integrated operations with solvent extraction purification assets.
Manufacturing commands premium positioning; construction is expanding most quickly as fire-safety mandates proliferate.
Distribution Channel:
Channel economics reflect buyer scale and urgency, with distributor networks capturing technical-grade volume while direct procurement concentrates among integrated phosphate processors.
- Distributors:Technical-grade specialists with warehousing and formulation support capabilities serving mid-scale ceramics and refractory customers. European REACH-registered distributors capture EU-bound specialty volume.
- Wholesalers:Bulk fertilizer-grade handlers in China's Yunnan-Guizhou phosphate belt and Moroccan export corridors. Price volatility in phosphate rock transmits directly through this channel.
- Online:Emerging platform procurement for standardized powder grades and small-batch liquid formulations. Indian and Southeast Asian processors experiment with digital sourcing for spot requirements.
- Retail:Limited presence in agricultural co-op stores for garden and specialty crop applications. North American lawn and garden channels represent marginal volume.
Distributors hold the largest share; online channels are gaining share fastest as procurement digitization penetrates mid-scale manufacturing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies: China deploys monoaluminum phosphate predominantly for fertilizer and industrial chemical intermediates, while Germany and the United States concentrate demand in fire-retardant construction systems and technical ceramics requiring REACH and EPA-certified purity grades.
China
Shijiazhuang anchors domestic supply through integrated phosphate rock processing corridors serving fertilizer and refractory binder demand. GB standards mandate heavy-metal thresholds below 10 ppm for food-contact derivatives, compelling wet-process acid producers toward solvent extraction purification. The Yunnan-Guizhou phosphate belt is backward integrating into aluminum salt derivatives, capturing margin previously flowing to merchant compounders.
United States
Construction fire-safety code tightening pulls monoaluminum phosphate into intumescent coatings and structural steel protection across commercial developments. EPA Clean Water Act phosphorus discharge limits pressure manufacturing facilities toward closed-loop acid recovery systems with extended payback periods. Gulf Coast chemical processors specialize in liquid formulations for ceramics customers requiring rapid dispersion protocols.
Germany
REACH registration completion by ECHA removes import friction for EU-bound technical-grade material, enabling specialty ceramics applications to scale. Tier-one refractory houses unbundle technical service from material supply, selling formulation optimization as a separate revenue line. The Ruhr industrial corridor concentrates precision ceramics manufacturing demanding tight particle size distribution controls.
Japan
Steel ladle repair contractors specify encapsulated monoaluminum phosphate powders for just-in-time mixing protocols that eliminate pre-slurry preparation variability. METI industrial standards shape procurement specifications for high-temperature binder applications in automotive catalyst substrate manufacturing. Nagoya-based ceramics producers require full supply chain traceability to phosphate rock mine origin.
India
Steel capacity expansion under PLI scheme incentives generates demand for high-purity binders in magnesia-carbon brick production, a segment where domestic MAP supply remains underdeveloped. FSSAI and CDSCO impose parallel heavy-metal thresholds that narrow qualified supplier pools for feed-grade specifications. Gujarat and Maharashtra industrial corridors attract technical-grade imports to fill refractory formulation gaps.
Monoaluminum Phosphate Market Competitive Landscape
Capability concentration sits with integrated phosphate processors possessing in-house acid purification and particle size control assets; scale advantage sits with wet-process acid producers in China's Yunnan-Guizhou belt leveraging captive phosphate rock supply. The supplier base bifurcates between REACH-registered technical-grade specialists and toll-compounders serving commodity fertilizer applications. Three archetypes dominate: integrated phosphate rock processors, precision ceramics-grade specialists, and regional fertilizer-grade compounders. Competitive moves center on backward integration into phosphoric acid production and silica encapsulation technology licensing for humid-climate storage applications.
Among North American technical phosphate specialists, Innophos occupies a position exemplifying premium-grade production capabilities. Chinese integrated processors Shijiazhuang Xinsheng Chemical and Wengfu Group represent the scale-driven archetype anchored in phosphate belt concentration. Japanese precision ceramics-grade suppliers include TAKI Chemical, which sits within the specialization tier serving steel ladle repair and automotive catalyst substrate manufacturers.
| Leading Market Players |
|---|
| Innophos |
| Shijiazhuang Xinsheng Chemical |
| TAKI Chemical |
| Hens Company |
| Hubei Hanye Chemical |
| Xuzhou Hengxing Chemical |
| Sulux Phosphates Ltd. |
| Wengfu Group |
| Foodchem International Corporation |
| Others |
Supply & Pricing Matrix
Shijiazhuang's integrated phosphate chemical corridor concentrates wet-process acid capacity that directly shapes downstream pricing power for monoaluminum phosphate derivatives. Capacity additions in China's Yunnan-Guizhou belt are compressing merchant compounder margins while REACH-registered European suppliers sustain technical-grade premiums.
Pricing Analysis
Long-term offtake agreements dominate technical-grade procurement by multinational refractory houses, while spot-market transactions persist for fertilizer-grade powder in China's domestic corridor. Three-tier pricing structure across premium, standard, and economy levels separates REACH-certified ceramics grades from commodity fertilizer specifications and unregistered technical material. Pricing pressure stems from ammonium polyphosphate substitution in non-structural fire-retardant applications where thermal performance requirements are less stringent. Agricultural buyers in Brazil and India exhibit the highest price sensitivity through cooperative tender systems, whereas Japanese steel ladle repair contractors accept premium positioning for encapsulated just-in-time formulations.
Supply Chain Analysis
Tariff exposure between China and key export destinations dominates supply chain risk calculus for merchant-grade liquid MAP. Sixty percent of global merchant supply originates from integrated producers within 200 kilometers of Shijiazhuang, with secondary concentration in Morocco's phosphate export corridor and Germany's Ruhr industrial cluster. Wet-process phosphoric acid, aluminum hydroxide, and thermal acid purification capacity constitute critical input dependencies. Single-source vulnerability concentrates in Shijiazhuang's environmental enforcement exposure. Distribution runs through technical-grade specialists with warehousing and formulation support capabilities serving mid-scale ceramics customers, supplemented by bulk fertilizer handlers in China's Yunnan-Guizhou belt.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Monoaluminum phosphate markets are approaching a platform-economics inflection as specification-driven procurement consolidates buyer power and unbundles technical service from material supply. The interoperability shift toward full supply chain traceability to phosphate rock mine origin is reshaping supplier qualification protocols across automotive catalyst substrate manufacturing.
For Market Incumbents: Insulate technical-grade positioning by completing REACH dossier investments and deploying silica encapsulation technology for humid-climate storage applications. Backward integration into electric-furnace acid production secures low-carbon positioning under EU Green Deal carbon accounting requirements. Capacity addition in India's Gujarat and Maharashtra corridors addresses refractory binder demand gaps created by PLI scheme steel expansion. For New Entrants and Emerging Players: Pursue coated powder formulations for Southeast Asian warehouse and logistics applications previously blocked by caking failures during monsoon season storage. India's magnesia-carbon brick production for steel capacity expansion represents the most penetrable geography given underdeveloped domestic MAP supply. Digital platform procurement for standardized powder grades and small-batch liquid formulations offers a direct go-to-market angle bypassing established distributor relationships. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated phosphate processors with in-house acid purification and particle size control assets over toll-compounders exposed to phosphate rock cost volatility. Long-term viability over a five-to-ten-year window rests on verified low-carbon phosphoric acid routes and REACH registration completion. The signal to watch is consolidation among multinational refractory houses displacing spot-market purchasing with annual framework agreements tied to audit rights and carbon-intensity disclosures.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acid Production | Captures margin previously flowing to merchant compounders in China's Yunnan-Guizhou belt. |
| Silica Encapsulation Technology Licensing | Opens warehouse applications in Malaysian and Indonesian monsoon climate conditions. |
| REACH Registration Completion | Removes import friction for EU-bound technical-grade ceramics and refractory material. |
| Capacity Expansion in India | Addresses refractory binder gaps from PLI scheme steel capacity expansion incentives. |
| Supply Chain Traceability Certification | Meets Belgian and South Korean automotive catalyst substrate manufacturer requirements. |
Research Methodology
Operator-level perspectives from phosphate plant managers, procurement leads at refractory OEMs, ceramics technical R&D directors, and distribution channel partners anchored the qualitative base. Primary interview insights combined with customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and GB standards documentation for bottom-up and top-down triangulation.
Scenario-bracketing framed analytical approaches across the analysis window, modeling physical form, application chemistry, end-user sophistication, and regional production hub segmentation. CAGRs derived from production capacity expansion pipelines, regulatory compliance cost trajectories, and substitution elasticity estimates for ammonium polyphosphate in non-structural applications.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by wet-process acid producers or rapid environmental enforcement actions in Shijiazhuang would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
PPG-20 Methyl Glucose Ether Market
Specialty Chemicals
Eitelite Market
Specialty Chemicals
Alkoxide Market
Specialty Chemicals
Vulcanization Accelerators Market
Specialty Chemicals
Catharanthine Market
Specialty Chemicals
UK Insect Repellent Market
Specialty Chemicals
Non-Commercial Acrylic Paints Market
Specialty Chemicals
Allantoin Market
Specialty Chemicals
Sugarcane Wax Market
Specialty Chemicals
Pyrrolidone Market
Specialty Chemicals
Global Tattoo Inks Market
Specialty Chemicals
Perfluoropolyether (PFPE) Market
Specialty Chemicals
Medical Propellants Market
Specialty Chemicals
Organosilicon Electrolyte Market
Specialty Chemicals
Natural Ingredient Insect Repellent Market
Specialty Chemicals
Hyaluronic Acid Products Market