
 UV Light Stabilizers Market | 2026-2036
UV Light Stabilizers Market Size, Share, and Industry Trends Forecast 2026-2036
UV Light Stabilizers Market Intelligence
A shift toward performance-driven procurement by original equipment manufacturers in the automotive and construction sectors is reorganizing the competitive landscape. This contrasts with traditional purchasing based on volume and price by compounders. BASF SE leverages its extensive R&D capabilities to meet these specific performance criteria. Clariant AG specializes in stabilizer solutions for demanding coating applications, while Songwon Industrial Co., Ltd. competes on manufacturing scale and supply chain efficiency.
UV light stabilizers are chemical additives integrated into polymers and coatings to prevent degradation from ultraviolet radiation. These compounds function by absorbing harmful UV rays or scavenging free radicals, thereby preserving the material's mechanical properties and appearance. Hindered Amine Light Stabilizers (HALS) command the largest share due to their high efficiency and long-term stability in plastics applications. Benzotriazole-based stabilizers are prominent in the coatings segment, where clarity and color retention are critical performance metrics.
Regulatory frameworks significantly influence product formulation and market access for UV stabilizers. The EU's REACH regulation, substance controls under the US EPA, and China's GB standards for materials all mandate rigorous testing and registration. These compliance hurdles shape R&D investment toward developing safer and more effective stabilizer chemistries. Consequently, formulators must decide between investing in novel, compliant molecules or optimizing existing, approved substance portfolios.
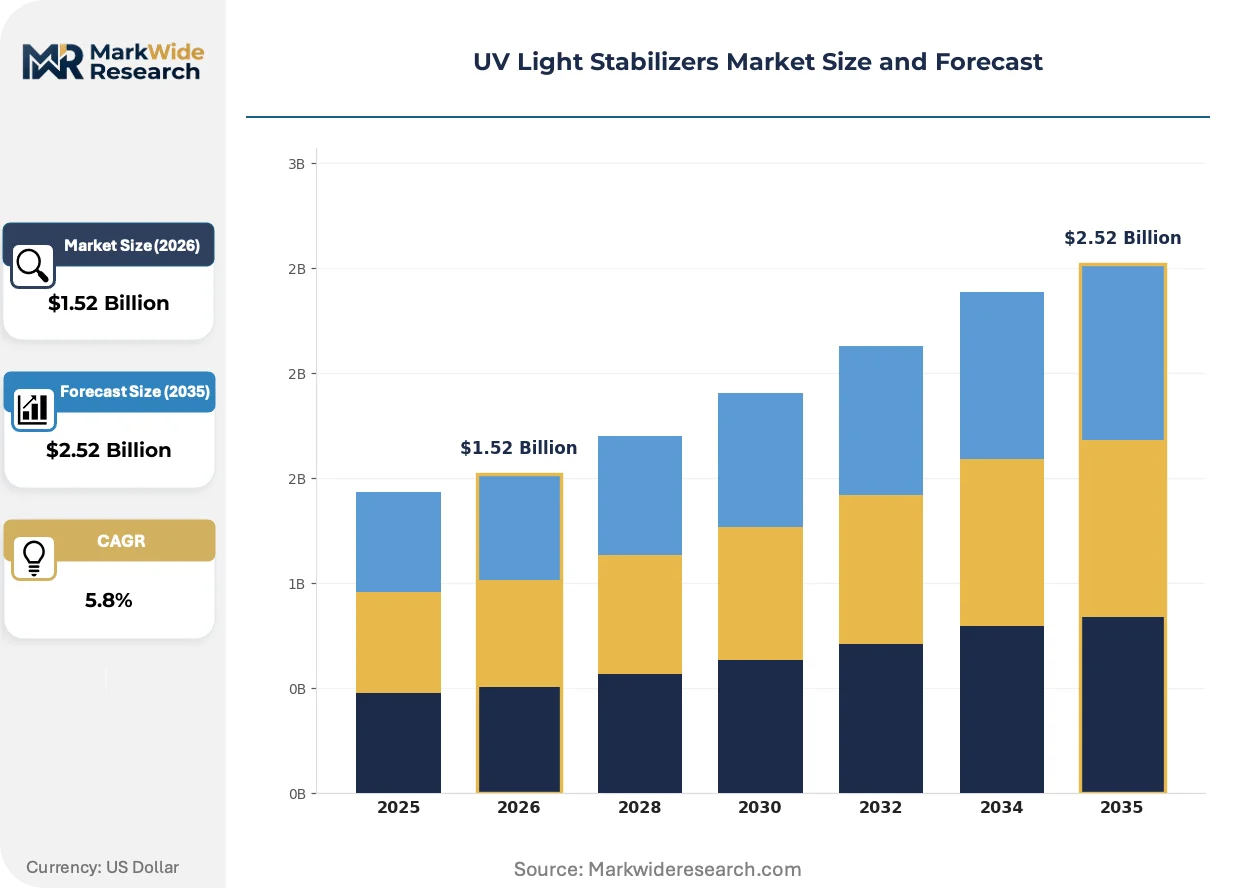
Market Dynamics
The convergence of stringent substance regulations and performance-driven procurement is the central force shaping the UV stabilizer market. Mandates like the EU's REACH and China's GB standards compel formulators to develop novel chemistries for demanding end-use sectors, moving the basis of competition from volume to specialized performance.
Growth Catalysts
- Automotive Lightweighting:The transition to polymer composites in vehicles to reduce weight and improve fuel efficiency necessitates advanced UV stabilizers to ensure long-term component integrity and appearance.
- Building and Construction Codes:Stricter building codes in regions like the EU and North America mandate longer service lives for exterior materials like siding and window profiles, boosting demand for high-performance stabilizers.
- Renewable Energy Infrastructure:The expansion of solar energy installations requires highly durable polymeric backsheets and encapsulants, creating a significant demand vector for specialized, long-lasting UV protection additives.
Market Restraints
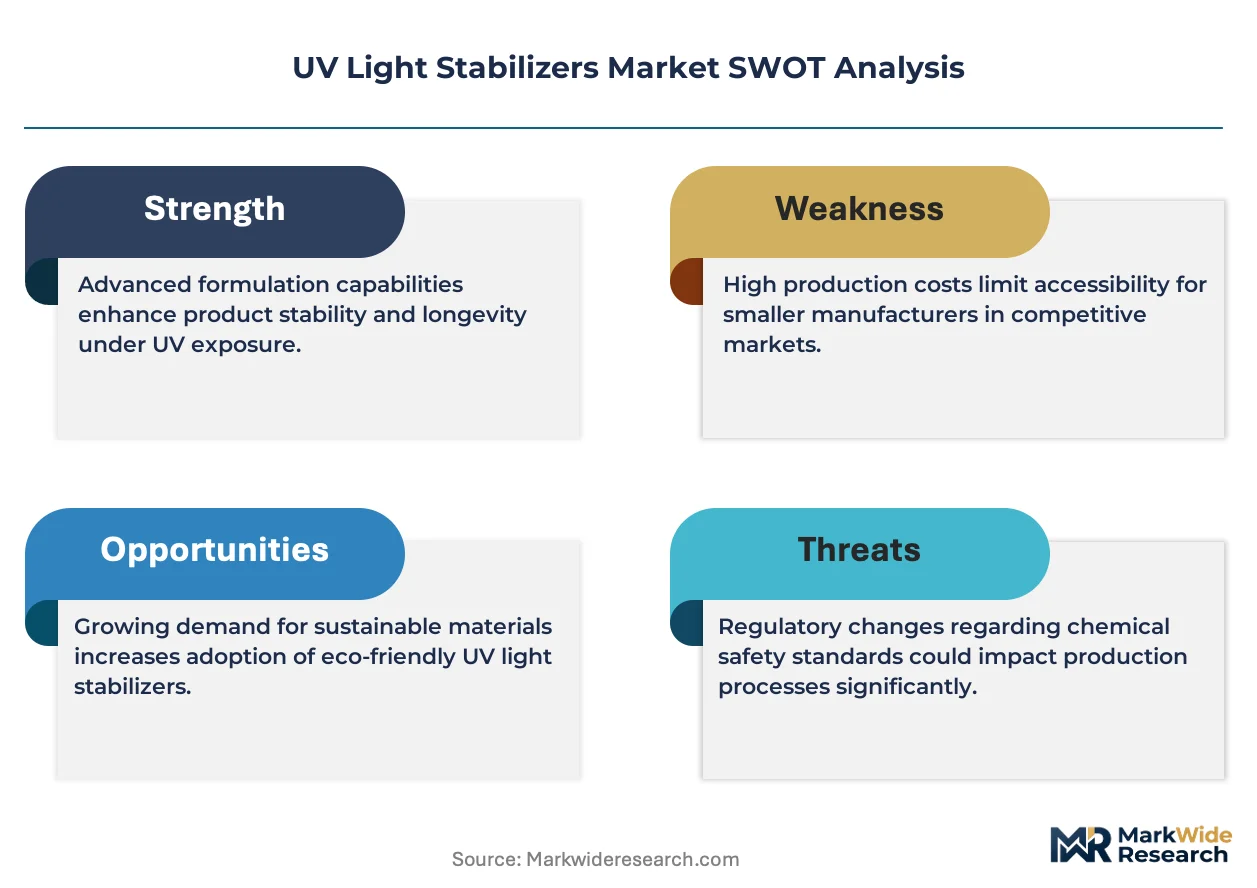
- Raw Material Volatility:Price fluctuations of key precursors, particularly those for Hindered Amine Light Stabilizers (HALS), create margin pressure and supply chain uncertainty for manufacturers.
- Regulatory Compliance Costs:The high cost and long timelines associated with substance registration under the EU's REACH and the US EPA's TSCA act as a barrier to entry for novel chemistries.
- Substitution by Intrinsic Polymers:Development of inherently UV-stable base polymers, such as certain fluoropolymers or acrylics, can reduce or eliminate the need for traditional additive packages in niche applications.
Strategic Opportunities
- Agricultural Films:Expanding use of greenhouse and mulch films in India and Southeast Asia presents an opportunity for stabilizers that balance UV protection with light transmission for optimal crop growth.
- Additive Manufacturing Materials:The need for weatherable and UV-resistant filaments and resins for 3D printing creates a new application frontier for customized stabilizer packages.
- Circular Economy Solutions:Formulating stabilizers that enhance the durability of recycled plastics allows for their use in higher-value applications, aligning with sustainability mandates from brand owners.
Industry Challenges
- Extended Validation Cycles:Proving the long-term efficacy of new stabilizer formulations requires multi-year weathering tests, delaying commercialization and return on R&D investment.
- Formulation Complexity:Ensuring compatibility and avoiding negative interactions with other additives, such as flame retardants and colorants, within a polymer matrix presents a persistent technical challenge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UV Light Stabilizers Market |
| Market Size in 2026 | $1.52 Billion |
| Market Size in 2035 | $2.52 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hindered Amine Light Stabilizers, Benzotriazole, Organophosphate, Others Application: Plastics, Coatings, Inks, Adhesives End User: Automotive, Consumer Goods, Construction, Electronics Form: Granules, Powders, Liquid, Concentrates |
| Companies Covered | Altana AG, ADEKA Corporation, Clariant AG, Rianlon Corporation, Songwon Industrial Co., Ltd., BASF SE, Everlight Chemical Industrial Corporation, Valtris Specialty Chemicals, LANXESS AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UV Light Stabilizers Market Strategic Shifts & Innovations
The market's innovation trajectory is defined by a push toward multifunctional additives offering more than just UV protection. Formulators are embedding sustainability and enhanced processing characteristics into the stabilizer chemistry to meet new regulatory and OEM demands.
Polymeric Hindered Amine Light Stabilizers (HALS) provide superior resistance to migration and extraction from the polymer matrix. Automotive and packaging manufacturers are adopting these high-molecular-weight additives to ensure long-term performance and compliance with food contact regulations. This enhanced permanence is miniaturizing the risk of performance degradation over a product's service life.
Substance restrictions under China's Ministry of Ecology and Environment (MEE) and updated GB standards are tightening controls on chemical additives in finished goods. This regulatory pressure is forcing a re-evaluation of stabilizer portfolios for products sold into the Chinese market, particularly for electronics and automotive parts. Consequently, producers are accelerating compliance testing and prioritizing globally harmonized formulations.
Specification-based procurement by original equipment manufacturers is altering purchasing dynamics. Instead of compounders choosing additives based on cost, OEMs in the automotive sector now mandate specific high-performance stabilizers to meet warranty and durability targets. This shift is most prominent in North America and Europe, where long-term material performance is a critical differentiator.
UV Light Stabilizers Market Segmentation
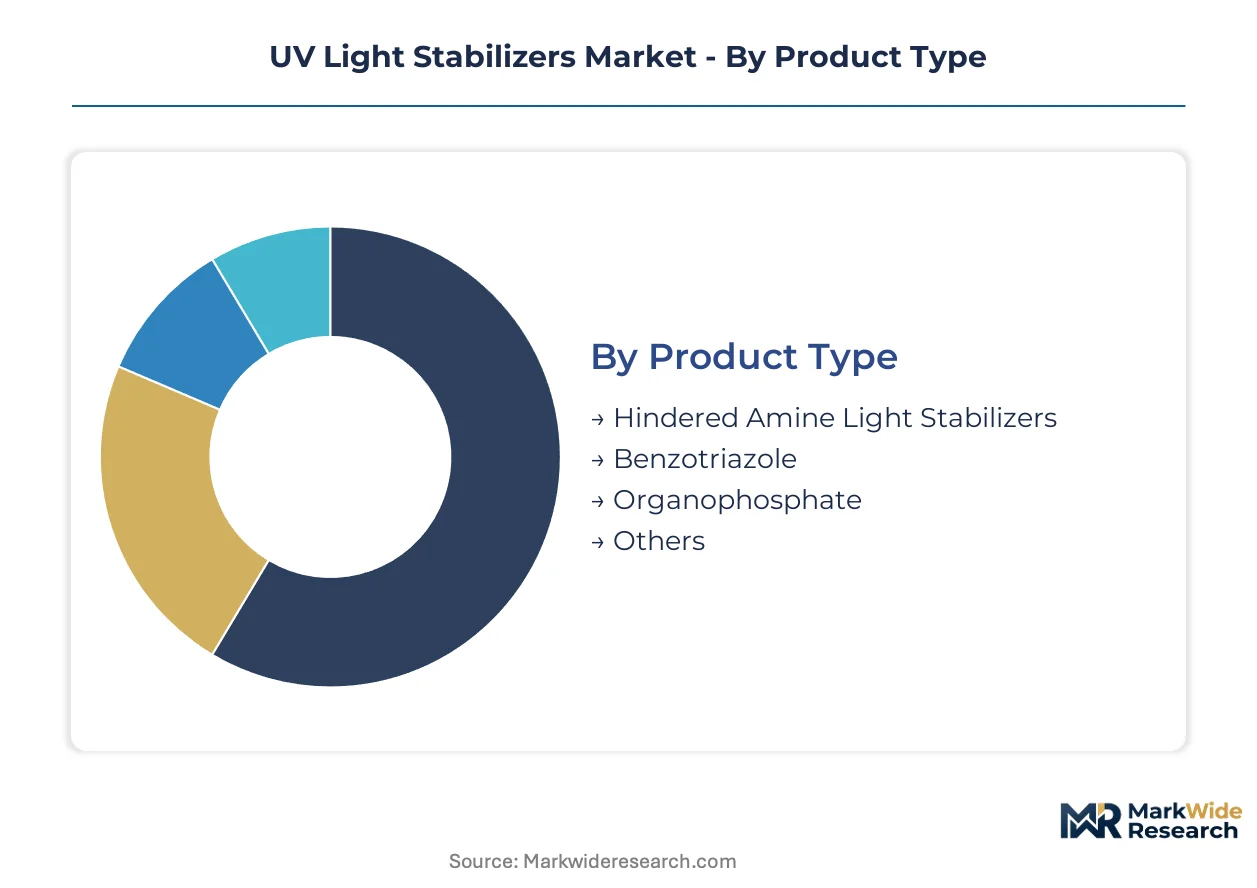
The UV light stabilizers market is segmented by product type, application, end user, and form, reflecting the diverse requirements across industries. Each segment faces unique material challenges and regulatory pressures, influencing product development and market penetration strategies for manufacturers.
Product Type:
Product type segmentation often highlights the varying adoption rates between established and emerging chemistries across different geographic markets, influencing regional production and export dynamics.
- Hindered Amine Light Stabilizers (HALS):These polymer-bound molecules scavenge free radicals, offering exceptional long-term UV protection without significant light absorption. Demand for HALS is concentrated in automotive and construction applications across Europe and North America, where extended material warranties are critical.
- Benzotriazole:Benzotriazoles are UV absorbers that convert UV radiation into harmless thermal energy, protecting the polymer surface. These stabilizers are widely utilized in high-performance coatings and clear plastics, particularly in Asian markets, where clarity and color stability are paramount for consumer electronics.
- Organophosphate:Organophosphate stabilizers function primarily as processing stabilizers, protecting polymers from degradation during high-temperature manufacturing. They find niche applications in materials requiring enhanced thermal stability during extrusion or molding processes in industrial manufacturing.
- Others:This category encompasses a range of specialized UV stabilizer chemistries, including benzophenones and nickel quenchers, used for specific performance requirements or in niche polymer systems.
Hindered Amine Light Stabilizers (HALS) holds the largest share; momentum sits with Benzotriazole due to its expanding use in demanding coating applications.
Application:
Application complexity dictates the formulation requirements for UV stabilizers, with certain sectors demanding highly specialized and durable additive packages for long-term performance.
- Plastics:UV stabilizers are essential in plastics to prevent photo-oxidation, discoloration, and embrittlement, preserving mechanical properties and aesthetic appeal. The extensive use of plastics in outdoor applications, such as automotive exteriors and building materials, drives significant volume.
- Coatings:In coatings, UV stabilizers maintain color, gloss, and film integrity, protecting underlying substrates from UV-induced degradation. High-performance coatings for architectural and industrial uses require robust stabilizer systems to ensure extended service life.
- Inks:UV stabilizers in printing inks prevent fading, yellowing, and degradation of pigments, especially in outdoor signage and packaging applications. Digital printing technologies for outdoor media require stable ink formulations.
- Adhesives:Adhesives exposed to sunlight benefit from UV stabilizers to prevent bond weakening, discoloration, and material breakdown. Construction and automotive assembly increasingly rely on durable adhesive solutions.
Plastics applications are foundational for UV stabilizer demand, while coatings demonstrate significant expansion driven by aesthetic and durability requirements.
End User:
The end-user segment reflects the diverse industries that integrate UV light stabilizers into their products, each with distinct performance expectations and regulatory compliance needs.
- Automotive:The automotive sector uses UV stabilizers in exterior and interior polymer components to resist weathering, cracking, and color fade. Stringent manufacturer warranties and vehicle longevity mandates advanced stabilizer solutions.
- Construction:UV stabilizers are critical for building materials like PVC profiles, roofing membranes, and outdoor decking to ensure long-term durability and appearance. Stricter building codes in Europe and North America necessitate high-performance additives.
- Consumer Goods:UV stabilizers protect a wide array of consumer products, including outdoor furniture, electronics casings, and toys, from sun damage. These stabilizers maintain product aesthetics and functional integrity over time.
- Electronics:Electronic devices, particularly those with outdoor exposure or clear polymer components, utilize UV stabilizers to prevent material degradation and maintain optical clarity. The expansion of outdoor displays and smart devices creates new demand.
The automotive industry drives substantial volume for UV stabilizers, with the construction sector showing rapid adoption due to evolving material standards.
Form:
The form of UV stabilizers influences their processing, dispersion, and compatibility within various polymer matrices and application methods.
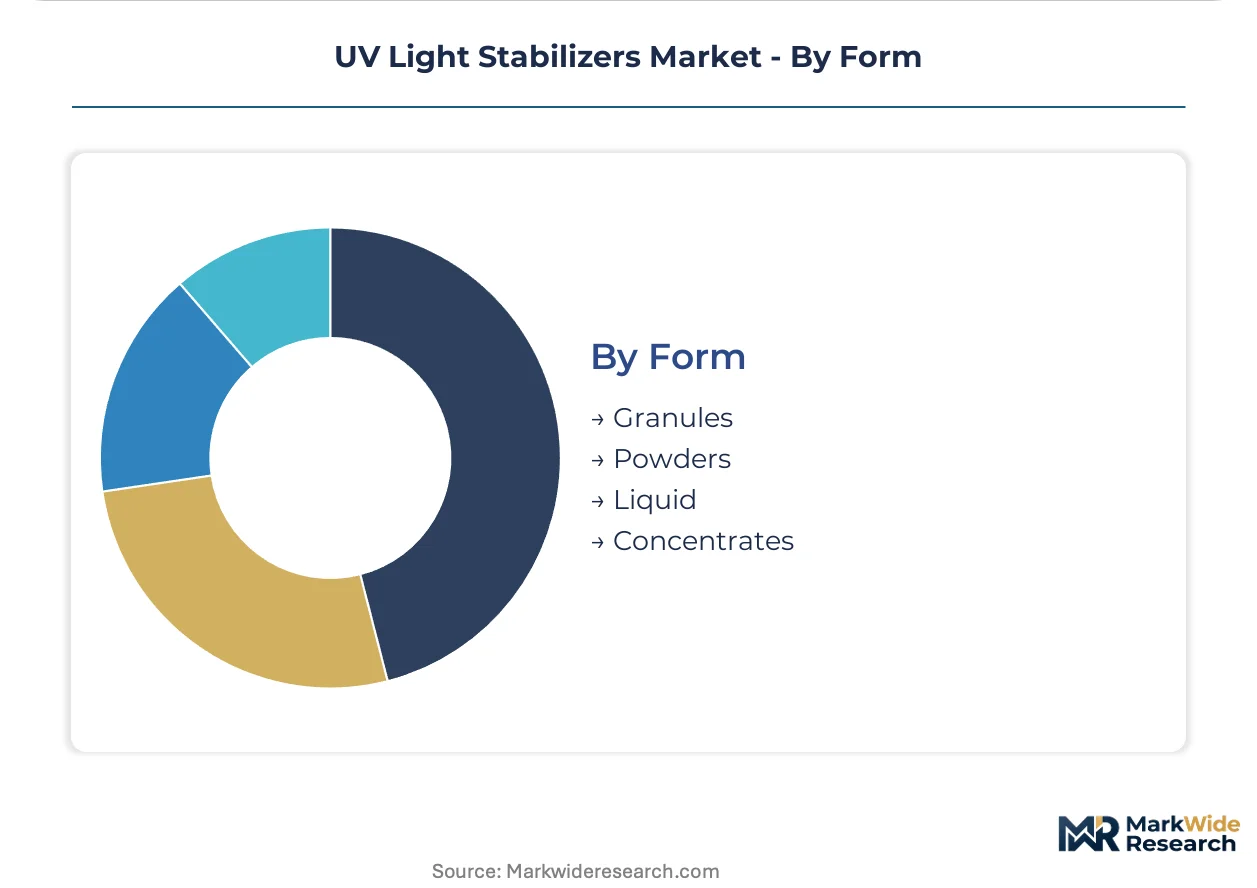
- Granules:Granular UV stabilizers offer ease of handling, reduced dust, and good flow properties, making them suitable for bulk compounding and extrusion processes. Their widespread use in large-scale plastics manufacturing underscores their market presence.
- Powders:Powdered UV stabilizers provide high surface area for efficient dispersion in certain polymer systems and coatings formulations. They are often preferred for specific blending processes where fine particle size is advantageous.
- Liquid:Liquid UV stabilizers offer excellent dispersion and compatibility in solvent-based systems and liquid resins, particularly in coating and ink applications. Their ease of incorporation simplifies formulation processes for manufacturers.
- Concentrates:Stabilizer concentrates, or masterbatches, are highly loaded formulations that allow for precise dosing and improved dispersion of additives into base polymers. They streamline manufacturing processes and ensure consistent performance.
Granules represent the traditional form for UV stabilizers, while liquid forms offer enhanced processing benefits for specific applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's industrial provinces are increasingly the supply hub for UV light stabilizers, feeding demand from automotive and construction sectors in North America and Europe. This dynamic trade corridor reflects distinct regional manufacturing strengths and end-use requirements. Regulatory differences between these regions shape product formulation and market access.
China
Demand for UV light stabilizers in China stems from its expansive automotive production and consumer electronics manufacturing. Stringent GB standards and Ministry of Ecology and Environment (MEE) substance controls compel formulators to develop compliant chemistries. The Yangtze River Delta region represents a significant hub for both stabilizer production and application in finished goods.
United States
The United States market for UV stabilizers is driven by automotive lightweighting initiatives and durable building material requirements. Compliance with US EPA regulations and TSCA mandates rigorous testing for new chemical substances. Chemical manufacturing along the Gulf Coast supports domestic production for automotive and construction applications.
Germany
Germany exhibits strong demand for UV stabilizers in its premium automotive sector and advanced construction projects. The EU's REACH regulation heavily influences chemical formulations, alongside stringent national building codes for material longevity. The Rhine-Main region, a center for specialty chemical production, develops innovative stabilizer solutions.
India
India's expanding agricultural sector, particularly greenhouse and mulch films, creates a significant demand for UV stabilizers. The country's Bureau of Indian Standards (BIS) guides material quality, influencing additive specifications for various applications. Gujarat's chemical industry contributes to domestic supply, supporting manufacturing centers for diverse end-use products.
Japan
Japanese demand for UV stabilizers is concentrated in high-performance electronics casings and automotive exterior components. METI guidelines and Japan Industrial Standards (JIS) ensure material durability and aesthetic integrity. The Tokyo-Yokohama industrial region integrates specialized stabilizers into precision polymer applications.
UV Light Stabilizers Market Key Industry Players
Player mix skews toward large, diversified chemical conglomerates and specialized additive manufacturers. The market exhibits a tiered structure, with a few global giants alongside numerous regional and niche players. Strategic archetypes include R&D-intensive innovators, application-specific solution providers, and cost-efficient volume producers. Key competitive moves involve continuous R&D investment and strategic partnerships to meet evolving regulatory and performance demands.
On the premium-tier vector, BASF SE, a German multinational chemical company, represents a strong emphasis on extensive research and development capabilities to address complex material challenges. Clariant AG, a Swiss specialty chemical company, exemplifies a focus on specialized stabilizer solutions tailored for demanding coating applications, where clarity and color retention are critical. Songwon Industrial Co., Ltd., a South Korean chemical manufacturer, occupies a position emphasizing manufacturing scale and supply chain efficiency, catering to broader industrial needs. These entities anchor distinct competitive strategies within the market, from high-performance innovation to volume-driven supply.
| Leading Market Players |
|---|
| Altana AG |
| ADEKA Corporation |
| Clariant AG |
| Rianlon Corporation |
| Songwon Industrial Co., Ltd. |
| BASF SE |
| Everlight Chemical Industrial Corporation |
| Valtris Specialty Chemicals |
| LANXESS AG |
Cost & Logistics Intelligence
Long-term supply agreements for high-performance UV stabilizers lock in both supply access and price visibility for automotive original equipment manufacturers. This contract structure mitigates raw material volatility for buyers and ensures consistent supply for critical applications.
Pricing Analysis
The technology-generation pricing gap is evident between established Hindered Amine Light Stabilizers and emerging high-performance polymeric HALS. Value-based pricing dominates for specialized, compliant formulations, while transactional pricing applies to more commoditized offerings. Price differentiation stems from performance grade, regulatory compliance, and customization for specific polymer matrices. Pricing pressure intensifies due to raw material volatility and increased competition from Asian producers. Compounders often exhibit the most price sensitivity, whereas automotive and construction OEMs prioritize performance and long-term warranties over marginal cost savings.
Supply Chain Analysis
Inbound logistics costs, especially container availability and freight rates from Asian manufacturing hubs, directly influence the final cost of UV stabilizers. Geographic supply concentration primarily centers in China, Germany, and the United States. The market relies on key precursors for Hindered Amine Light Stabilizers and benzotriazole intermediates. Raw material price volatility represents a significant structural supply chain risk for manufacturers. Downstream distribution occurs through direct sales to large industrial end-users and through specialized distributors serving smaller compounders and formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
A shift towards performance-driven procurement by original equipment manufacturers is reorganizing the competitive landscape, consolidating buying power. This dynamic necessitates strategic adjustments across the value chain.
For Market Incumbents: Compound existing R&D capabilities to develop next-generation, compliant UV stabilizer chemistries meeting stringent global regulations like REACH and China's GB standards. Invest in certification processes to demonstrate long-term efficacy and safety, leveraging these as a competitive advantage against emerging threats from non-compliant alternatives. Form strategic partnerships with key automotive and construction OEMs to co-develop tailored solutions, locking in future demand and mitigating margin pressure.
For New Entrants and Emerging Players: Certification fast-track programs for novel, sustainable UV stabilizer formulations offer a clear entry point into niche, high-value applications. Target underpenetrated segments such as additive manufacturing materials and circular economy solutions for recycled plastics. The agricultural films market in India and Southeast Asia presents a penetrable segment for specialized stabilizers balancing UV protection with light transmission. Go-to-market strategies should emphasize a performance-based value proposition and compliance with evolving sustainability mandates.
For Investors and Strategic Acquirers: Specialty chemical formulators with deep regulatory expertise and a strong intellectual property portfolio represent attractive acquisition targets over the next 5-10 years. Companies demonstrating vertical integration into key precursors or possessing a diversified portfolio of compliant chemistries also offer long-term value. A signal to watch is the acceleration of regulatory approvals for new, environmentally benign stabilizer technologies, indicating a shift in market favor.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Compliant Chemistries | Ensures supply security for high-demand, regulated applications like automotive and construction components. |
| Joint Ventures for Sustainable Formulations | Accelerates development of eco-friendly stabilizers, aligning with brand owner sustainability mandates and circular economy goals. |
| Investment in Advanced Weathering Testing | Validates long-term performance claims, critical for meeting OEM warranties and stricter building codes. |
| Acquisition of Niche Additive Manufacturers | Expands product portfolio into specialized applications such as additive manufacturing or high-performance coatings. |
| Strategic Partnerships with Polymer Compounders | Secures downstream integration, ensuring optimal stabilizer dispersion and performance in final polymer products. |
Research Approach
Desk research of academic journals, chemical industry reports, and regulatory filings preceded structured interviews with R&D directors, procurement leads, and regulatory compliance specialists. This approach combined primary insights from industry stakeholders with secondary validation from published data. Market sizing and segmentation leveraged both bottom-up and top-down triangulation methods, ensuring comprehensive coverage.
Variance decomposition across product type, application, end-user, and regional regulatory impact informed the quantitative modeling framework over the projection horizon. This approach allowed for detailed analysis of growth drivers and restraints within each segment. Compound annual growth rates were derived through regression analysis, considering historical trends and anticipated market share shifts. Polymer consumption growth and automotive production forecasts served as key industry-specific forecast inputs.
Underlying assumptions cover raw material stability and consistent regulatory enforcement, with deviation risk concentrated in unforeseen geopolitical shifts or rapid technological breakthroughs. Forecasts reflect these assumptions. Recalibration cycles align with material shifts in named drivers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
1 - 4 - Cyclohexanedimethanol Dibenzoate Market
Specialty Chemicals
Fluorinated Plasma Surface Treatment Market
Specialty Chemicals
Magnesium Gluconate Market
Specialty Chemicals
Global Specialty Resins Market
Specialty Chemicals
North America Non-Phthalate Plasticizers Market
Specialty Chemicals
Perfluoropolyether (PFPE) Market
Specialty Chemicals
Zinc Ricinoleate Market
Specialty Chemicals
Micronized PTFE Market
Specialty Chemicals
Abierixin Market
Specialty Chemicals
UK Insect Repellent Market
Specialty Chemicals
Acetyl Isovaleryl Market
Specialty Chemicals
PEG and PPG Esters Market
Specialty Chemicals
Preparative and Process Chromatography Market
Specialty Chemicals
Security Ink Market
Specialty Chemicals
North America Sulfonylureas Market
Specialty Chemicals
Fabric Antibacterial Spray Market