
 Cellulose Derivatives Market | 2026-2036
Cellulose Derivatives Market Size, Share, and Industry Trends Forecast 2026-2036
Cellulose Derivatives Market Analysis
The EU Green Deal is restructuring demand trajectories for cellulose derivatives across European pharmaceutical and coatings supply chains. Dow leverages backward integration into wood pulp sourcing to secure cost-stable feedstock for ethyl cellulose production. Ashland sustains technology leadership in hydroxypropyl cellulose for controlled-release drug matrices. Daicel Corporation anchors Asian supply through captive acetylation capacity at its Aboshi complex.
Cellulose derivatives are chemically modified polysaccharides produced through etherification or esterification of cellulose hydroxyl groups, yielding materials with tunable solubility, viscosity, and film-forming properties for controlled industrial deployment. Carboxymethyl cellulose dominates volume as a workhorse thickener in food systems and oilfield fluids where margin pools remain commoditized. Ethyl cellulose commands premium positioning in pharmaceutical coatings and electronics membranes where barrier precision justifies higher formulation value. Methyl cellulose competes in construction-grade cement retarders and plant-based meat binders, a segment where thermal gelation functionality drives specification stickiness.
REACH registration requirements in Europe, FDA excipient guidelines in the United States, and China's GB standards for food additives collectively shape product purity thresholds and market access conditions for cellulose derivative manufacturers. EMA's evolving quality-by-design mandates for drug formulations are pushing pharmaceutical buyers toward certified excipient grades with documented batch-to-batch consistency. Stakeholders must monitor how biorefinery co-product streams and enzymatic modification technologies alter the cost position of conventional etherification routes.
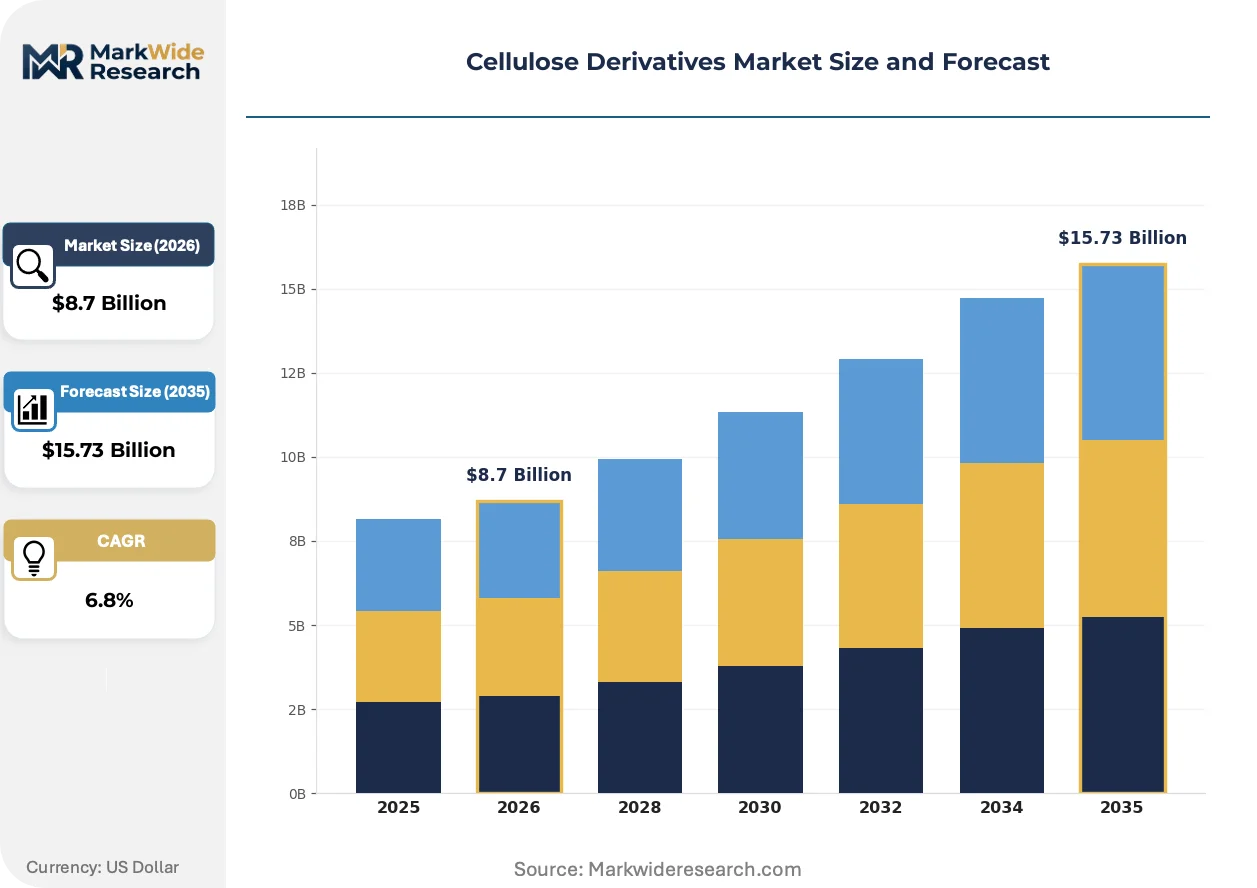
Market Dynamics
REACH registration deadlines are compressing supplier qualification timelines across European pharmaceutical supply chains, forcing buyers to consolidate approved vendor lists and favor certified excipient grades with documented batch-to-batch consistency.
Growth Catalysts
- EMA Quality-by-Design Mandates:Drug manufacturers now specify certified cellulose ether grades for controlled-release matrices, creating pull-through demand for hydroxypropyl methylcellulose with documented dissolution profiles.
- China's Dual Carbon Goals:Domestic biorefinery expansion is accelerating enzymatic cellulose modification capacity, lowering feedstock costs for local carboxymethyl cellulose producers serving food and construction sectors.
- Plant-Based Meat Formulation:Thermal gelation properties of methyl cellulose are capturing specification stickiness in alternative protein binders as food technologists replace methylcellulose with purpose-modified grades.
Market Restraints
- Wood Pulp Price Volatility:Dissolving-grade pulp costs fluctuate with paper industry demand cycles, compressing margins for ethyl cellulose producers lacking backward integration into forestry assets.
- Acetylation Capacity Concentration:Captive acetate esterification infrastructure clusters in Japan and China, creating supply vulnerability for pharmaceutical coating houses dependent on cellulose acetate phthalate imports.
- Petrochemical Substitute Pressure:Polyvinylpyrrolidone and synthetic thickeners compete in lower-specification coating applications where barrier precision requirements relax.
Strategic Opportunities
- Indian Pharmaceutical Expansion:CDSCO excipient guidelines are tightening parallel to US FDA alignment, creating first-mover advantage for suppliers establishing certified manufacturing in Gujarat and Telangana.
- Biorefinery Co-Product Streams:Lignocellulosic ethanol residues offer alternative cellulose feedstocks for etherification, potentially undercutting conventional pulp-based cost structures in Nordic and Brazilian operations.
- EU Green Deal Procurement Rules:Public tender specifications now weight bio-based content scores, advantaging cellulose derivatives over synthetic alternatives in construction and packaging applications.
Industry Challenges
- Excipient Master File Navigation:FDA Type II drug master file preparation requires 18-24 month timelines and specialized regulatory affairs expertise that mid-tier suppliers struggle to resource.
- Legacy Equipment Retrofit Costs:Continuous etherification reactor upgrades demand capital outlays exceeding $15 million per production line, straining family-owned European manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cellulose Derivatives Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carboxymethyl Cellulose, Hydroxypropyl Cellulose, Methyl Cellulose, Ethyl Cellulose End Use Industry: Food & Beverage, Pharmaceuticals, Personal Care, Paints & Coatings Functionality: Thickening Agent, Stabilizer, Binder, Film Former Form: Powder, Granules, Liquid, Gel |
| Companies Covered | Dow, SE Tylose GmbH & Co. KG, Ashland, Daicel Corporation, CP Kelco, Eastman Chemical Company, Lenzing AG, Borregaard, Shin-Etsu Chemical Co., Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cellulose Derivatives Market Emerging Trajectories
Enzymatic modification routes and precision etherification control systems are converging to reshape cost structures and performance specifications across cellulose derivative categories.
Continuous flow reactor technology is integrating real-time viscosity monitoring with automated alkali dosing to tighten molecular weight distribution in hydroxypropyl cellulose production. Pharmaceutical formulators adopting these grades report reduced tablet-to-tablet dissolution variability. The technology is integrating quality-by-design principles directly into excipient manufacturing, compressing downstream validation burdens for drug sponsors.
EU F-Gas Regulation phase-down schedules are pressuring coating houses to eliminate solvent-based ethyl cellulose application systems. Waterborne dispersion grades now dominate new equipment specifications in German and Italian pharmaceutical packaging operations. Electronics membrane manufacturers in the Netherlands and Belgium are accelerating solvent recovery investments to extend legacy coating line viability through 2027 compliance deadlines.
Direct-to-manufacturer excipient sourcing is consolidating purchasing decisions previously fragmented through distributor networks. Large pharmaceutical sponsors in the United States and Germany now mandate supplier audits and quality agreements that bypass regional chemical distributors entirely. This channel compression is most visible in controlled-release formulation procurement, where three buyers now account for majority volume in North American hydroxypropyl methylcellulose contracts.
Cellulose Derivatives Market Segmentation
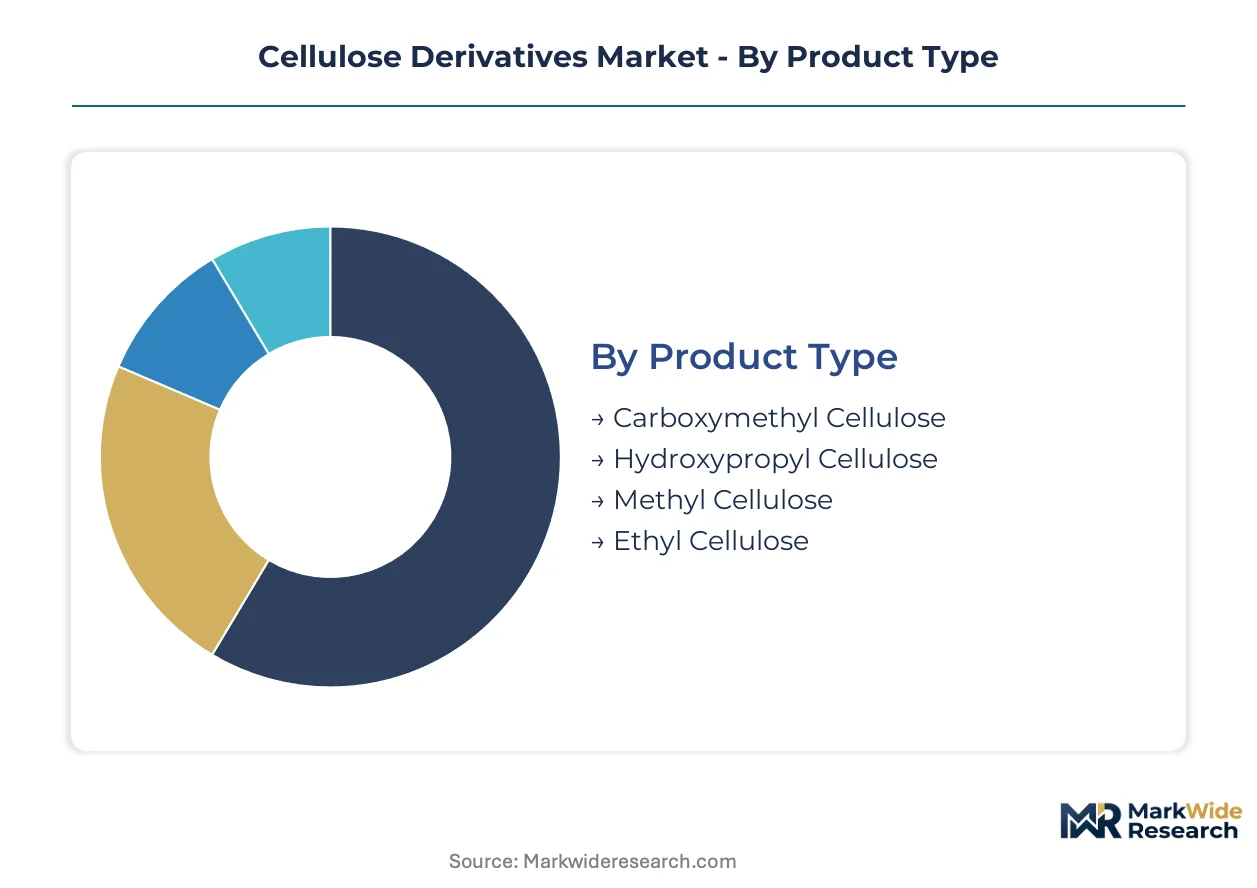
Cellulose derivative specifications vary dramatically across end-use contexts, with pharmaceutical grades commanding tenfold premiums over industrial thickeners. Procurement teams segment purchases by purity certification, dissolution profile, and regulatory documentation rather than chemical identity alone.
Product Type:
Volume leaders dominate commoditized applications while premium grades capture formulation value in regulated industries.
- Carboxymethyl Cellulose:Anionic ether with degree of substitution typically 0.7-1.2, manufactured through alkali-catalyzed reaction with chloroacetic acid. Food technologists in China specify food-grade CMC for dairy stabilizers as domestic biorefinery expansion compresses feedstock costs. Industrial procurement for oilfield drilling fluids remains price-sensitive, with buyers switching between regional suppliers based on spot pulp quotations.
- Ethyl Cellulose:Thermoplastic cellulose ether with ethoxy substitution 44-50%, insoluble in water but soluble in organic solvents. Pharmaceutical coating houses in Germany and Italy specify ethyl cellulose for moisture-barrier tablet coatings as EU F-Gas Regulation deadlines accelerate solvent recovery investments. Electronics membrane manufacturers in Belgium demand narrow molecular weight distribution grades for precision barrier applications.
- Hydroxypropyl Cellulose:Nonionic ether with hydroxypropyl groups substituting hydroxyl positions, exhibiting inverse temperature solubility. Controlled-release matrix formulations.
- Methyl Cellulose:Nonionic ether with methoxy substitution 27-32%, characterized by thermal gelation upon heating. Construction-grade cement retarders and plant-based meat binders.
Today's leader: Carboxymethyl Cellulose. Tomorrow's challenger: Ethyl Cellulose.
End Use Industry:
Regulatory stringency separates pharmaceutical procurement from industrial buyers, with certification costs creating tiered market access.
- Pharmaceuticals:Excipient grades require documented batch-to-batch consistency, dissolution profile certification, and FDA Type II drug master file support. EMA quality-by-design mandates are compressing supplier qualification timelines, forcing drug manufacturers to consolidate approved vendor lists. Hydroxypropyl methylcellulose for controlled-release matrices commands premium positioning.
- Food & Beverage:Thickening and stabilizing applications in dairy, bakery, and beverage systems. FSSAI in India and China's SAMR enforce additive purity standards parallel to Codex Alimentarius.
- Personal Care:Rheology modifiers for creams, lotions, and hair care formulations. Thermal gelation properties drive specification in rinse-off products.
- Paints & Coatings:Water retention and workability modifiers for construction coatings. EU Green Deal procurement rules weight bio-based content scores, advantaging cellulose derivatives over synthetic thickeners in public tenders.
Pharmaceuticals anchor premium value capture. Food & Beverage drives volume throughput.
Functionality:
Performance requirements determine molecular weight specifications and substitution patterns, with film-forming grades demanding tightest process control.
- Thickening Agent:Viscosity-building function dependent on polymer chain length and concentration. CMC dominates food and industrial applications where cost efficiency outweighs precision requirements.
- Film Former:Continuous polymer matrices for pharmaceutical coatings and electronics membranes. Ethyl cellulose and hydroxypropyl cellulose grades require narrow polydispersity indices to ensure uniform barrier properties.
- Stabilizer:Colloidal protection and suspension maintenance in emulsion systems. Dairy and beverage applications.
- Binder:Adhesion and cohesive strength in tablet matrices and construction materials. Direct compression tableting favors specific particle size distributions.
Film forming commands the steepest specification premiums. Thickening faces synthetic substitute pressure.
Form:
Physical presentation affects dissolution kinetics, dust exposure, and handling logistics across manufacturing environments.
- Powder:Standard presentation for most etherification products, requiring dust control systems in pharmaceutical facilities. Bulk density and flow properties determine handling equipment specifications.
- Liquid:Pre-dispersed or dissolved formats for automated dosing systems. Electronics membrane coating lines in the Netherlands specify liquid ethyl cellulose to eliminate solvent recovery burdens.
- Granules:Agglomerated forms for reduced dusting and improved flow. Direct compression tableting operations.
- Gel:Concentrated aqueous systems for personal care and food applications. Thermal gelation of methyl cellulose exploited in plant-based meat texture development.
Powder retains volume dominance. Liquid formats gain share in solvent-regulated environments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cellulose derivative manufacturing traces its industrial lineage to early 20th century Germany, where etherification chemistry first scaled for commercial coatings. Production networks now span pulp-rich Nordic zones, acetylation clusters in East Asia, and pharmaceutical-grade facilities concentrated near regulatory agencies.
Germany
Pharmaceutical coating houses in Frankfurt-Rhine-Main and Cologne-Bonn corridors drive specification-grade ethyl cellulose procurement. EMA quality-by-design mandates compress supplier qualification timelines, forcing drug manufacturers to consolidate approved vendor lists. Industrial biotechnology research in Hamburg and Berlin advances enzymatic modification routes for next-generation cellulose ethers.
China
Domestic biorefinery expansion accelerates enzymatic cellulose modification capacity, lowering feedstock costs for carboxymethyl cellulose producers. GB standards for food additives enforce additive purity thresholds parallel to Codex Alimentarius. Yangtze River Delta coating houses now export pharmaceutical-grade cellulose ethers to European and Southeast Asian markets.
United States
Controlled-release formulation procurement concentrates among three buyers accounting for majority North American hydroxypropyl methylcellulose contracts. FDA Type II drug master file preparation requires specialized regulatory affairs expertise. New Jersey and Massachusetts pharmaceutical clusters mandate supplier audits that bypass regional chemical distributors entirely.
Japan
Captive acetylation infrastructure at the Aboshi complex anchors Asian supply for pharmaceutical coating applications. METI industrial policy supports precision etherification control systems integration. Osaka-Kobe electronics membrane manufacturers demand narrow molecular weight distribution grades for barrier precision applications.
India
CDSCO excipient guidelines tighten parallel to US FDA alignment, creating first-mover advantage for suppliers establishing certified manufacturing. Gujarat and Telangana pharmaceutical expansion drives demand for documented batch-to-batch consistency. Mumbai-Pune industrial corridors attract cellulose ether distributors serving domestic drug manufacturers and export coating houses.
Cellulose Derivatives Market Vendor Landscape
Capital-heavy producers compete with asset-light specialty compounders across tiered supply positions. Consolidation characterizes pharmaceutical-grade segments where regulatory certification costs exclude mid-tier entrants. Three archetypes dominate: backward-integrated forestry operators, precision etherification specialists, and regional toll manufacturers serving industrial thickeners. Capacity expansion and strategic partnerships constitute the dominant competitive moves as players secure pulp supply agreements and pharmaceutical excipient certifications.
Among North American chemical conglomerates, Dow and Ashland exemplify divergent strategic positions within pharmaceutical-grade cellulose ethers. Dow leverages upstream control over wood pulp sourcing to secure cost-stable feedstock for ethyl cellulose production. Ashland occupies a technology leadership position in hydroxypropyl cellulose for controlled-release drug matrices. Daicel Corporation represents the captive acetylation model dominant in East Asian supply architecture.
| Leading Market Players |
|---|
| Dow |
| SE Tylose GmbH & Co. KG |
| Ashland |
| Daicel Corporation |
| CP Kelco |
| Eastman Chemical Company |
| Lenzing AG |
| Borregaard |
| Shin-Etsu Chemical Co., Ltd |
| Others |
Supply Flow & Price Mechanics
Pharmaceutical coating houses in Germany and Italy concentrate procurement decisions among three buyers, locking in contract-based long-term offtake structures that favor certified excipient grades with documented batch-to-batch consistency. This buyer concentration feeds premium-mid-economy pricing differentiation across hydroxypropyl methylcellulose, ethyl cellulose, and industrial carboxymethyl cellulose tiers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates FDA Type II drug master file grades from food-grade and industrial thickeners. Price differentiation hinges on certification level and volume scale, with pharmaceutical buyers absorbing tenfold premiums for dissolution profile documentation. Cost compression in industrial CMC intensifies as Chinese biorefinery expansion floods commoditized segments. Food and beverage procurement teams exhibit highest price sensitivity, while controlled-release formulators prioritize specification consistency over unit economics.
Supply Chain Analysis
Skilled chemical process engineers in Germany, Japan, and China anchor etherification reactor operations, with workforce availability constraining capacity expansion timelines for continuous flow upgrades. Raw material dependencies center on dissolving-grade wood pulp, chloroacetic acid for carboxymethylation, and propylene oxide for hydroxypropyl modification. Single-source vulnerability clusters around captive acetylation infrastructure in East Asia. Distribution runs through direct-to-manufacturer channels for pharmaceutical grades, bypassing regional chemical distributors entirely.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story, with EMA quality-by-design mandates and FDA Type II drug master file requirements shifting procurement toward premium certified grades with documented dissolution profiles.
For Market Incumbents: Lock in backward integration into forestry assets or long-term pulp supply agreements to defend margin position against wood price volatility. Prioritize continuous etherification reactor upgrades in Germany and Japan to tighten molecular weight distribution for pharmaceutical coating houses facing EU F-Gas Regulation deadlines. Synthetic substitute pressure from polyvinylpyrrolidone demands specification stickiness through quality-by-design certification. For New Entrants and Emerging Players: Begin with enzymatic modification routes leveraging lignocellulosic ethanol residues in Nordic or Brazilian biorefinery corridors, where alternative cellulose feedstocks undercut conventional pulp-based cost structures. Target India's Gujarat and Telangana pharmaceutical clusters, where CDSCO guideline tightening creates first-mover advantage for certified manufacturing. Pursue toll manufacturing partnerships with established distributors in Mumbai-Pune corridors to bypass legacy equipment retrofit capital requirements. For Investors and Strategic Acquirers: Specialty chemical conglomerates with pharmaceutical excipient portfolios are the most active acquirer in this space, seeking precision etherification capabilities and captive acetylation infrastructure. Five-to-ten year viability favors backward-integrated forestry operators and technology leaders in controlled-release matrix grades. Monitor enzymatic modification yield improvements as inflection indicator for cost structure disruption.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Forestry Assets | Dow's wood pulp sourcing secures cost-stable feedstock for ethyl cellulose production. |
| Continuous Etherification Reactor Upgrade | Ashland's real-time viscosity monitoring tightens molecular weight distribution for pharmaceutical formulators. |
| Enzymatic Modification Route Development | Chinese biorefinery expansion accelerates cellulose ether capacity serving food and construction sectors. |
| FDA Type II Drug Master File Investment | CDSCO alignment in India creates certification barrier excluding mid-tier European family manufacturers. |
| Direct-to-Manufacturer Channel Compression | Large US and German pharmaceutical sponsors now mandate supplier audits bypassing distributors entirely. |
Methodological Framework
Direct dialogue with pharmaceutical formulation scientists, regulatory affairs directors at excipient suppliers, procurement leads at German coating houses, and chemical process engineers at etherification facilities grounded this analysis. Secondary validation drew from EMA quality-by-design guidance documents, FDA Type II drug master file databases, SEC 10-K filings of North American chemical conglomerates, and trade flow data from Nordic and East Asian pulp markets. Bottom-up capacity assessments and top-down demand modeling triangulated volume estimates.
Bottom-up unit economics analysis of etherification reactor operations across Germany, China, and Japan anchored the forecast framework. Segmentation dimensions modeled include product type, end-use industry, functionality, and form across the analysis window. CAGRs derived from elasticity-adjusted demand projections for controlled-release pharmaceuticals, plant-based meat binders, and construction-grade cement retarders. Feedstock cost trajectories for dissolving-grade pulp and enzymatic modification yield curves informed supply-side assumptions.
Several conditions sit outside the modeled scope, including sudden REACH registration deadline extensions, breakthrough synthetic substitute technologies displacing cellulose ethers in barrier applications, and pulp market disruptions from paper industry demand spikes. Forecasts reflect assumptions about regulatory stringency continuity and enzymatic route commercialization timelines. Material deviation in wood pulp price volatility or EMA quality-by-design enforcement intensity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Europe Sugarcane Wax Market
Specialty Chemicals
Octocrylene Market
Specialty Chemicals
Bemotrizinol Market
Specialty Chemicals
Methyltrimethoxysilane Market
Specialty Chemicals
Global Benzoyl Peroxide Market
Specialty Chemicals
Shikimic Acid Market
Specialty Chemicals
US Post Laser Recovery Products Market
Specialty Chemicals
North America Non-Phthalate Plasticizers Market
Specialty Chemicals
Global Silicone Defoamer Market
Specialty Chemicals
Toner Spray Market
Specialty Chemicals
Biodegradable Chelating Agents Market
Specialty Chemicals
4-Propyl-1,3,2-Dioxathiolane 2,2-Dioxid Market
Specialty Chemicals
Hyaluronic Acid Market
Specialty Chemicals
Australia and New Zealand Aerosol Market
Specialty Chemicals
Chevron Seals Market
Specialty Chemicals
Polyglycolic Acid (PGA) Market