
 Africa Lactic Acid Market | 2026-2036
Africa Lactic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Lactic Acid Market Outlook
Food and beverage processors is rotating toward pharmaceutical and cosmetic formulators as the fastest-expanding buyer archetype in the Africa lactic acid landscape. Corbion leverages its fermentation technology leadership to supply high-purity grades across North and West African distribution networks. Galactic anchors its position through backward integration into carbohydrate feedstock sourcing, securing cost advantages for industrial-grade output. Henan Jindan Lactic Acid Technology competes aggressively on volume scale, shipping containerized acid to African port hubs from Asian manufacturing bases.
Lactic acid is a chiral organic acid produced primarily through carbohydrate fermentation or chemical synthesis, existing as L-lactic acid, D-lactic acid, or racemic mixtures with purity thresholds defining grade classification. The compound functions as an antimicrobial preservative, pH modulator, and chemical precursor for polylactic acid bioplastics across food, pharmaceutical, and industrial applications. Food grade lactic acid dominates current volume flows, sustained by dairy processing and beverage acidification throughout Sub-Saharan Africa, while pharmaceutical grade commands premium positioning due to stringent purity requirements for intravenous and parenteral formulations. Biodegradable plastics represents the fastest-growing end user segment, as polylactic acid feedstock demand accelerates among packaging converters seeking alternatives to petroleum-derived polymers.
South Africa's Department of Health foodstuffs regulations, Nigeria's National Agency for Food and Drug Administration and Control standards, and evolving East African Community harmonized technical regulations collectively shape product certification requirements and import compliance pathways for lactic acid suppliers. These frameworks mandate documented purity specifications, allergen labeling, and Good Manufacturing Practice alignment, effectively filtering market access to certified producers and distributors. Stakeholders must monitor regulatory convergence between national food safety authorities and the African Continental Free Trade Area's emerging technical barriers-to-trade protocols, as harmonized standards will determine which grade specifications achieve cross-border recognition.
Market Dynamics
Fermentation technology advancement and regulatory tightening on food additive purity are compressing supplier margins while elevating certified-grade premiums across African procurement channels.
Growth Catalysts
- Foodstuffs Regulations:South Africa's Department of Health updated labeling mandates push manufacturers toward certified food-grade acid suppliers, filtering out uncertified imports.
- Polylactic Acid Feedstock Demand:Packaging converters seeking petroleum alternatives are accelerating biodegradable plastics consumption as the fastest-expanding end-use vertical.
- Lagos-Kano Corridor:Nigeria's beverage and snack production clusters concentrate bulk chemical procurement, creating density economies for lactic acid distributors.
Market Restraints
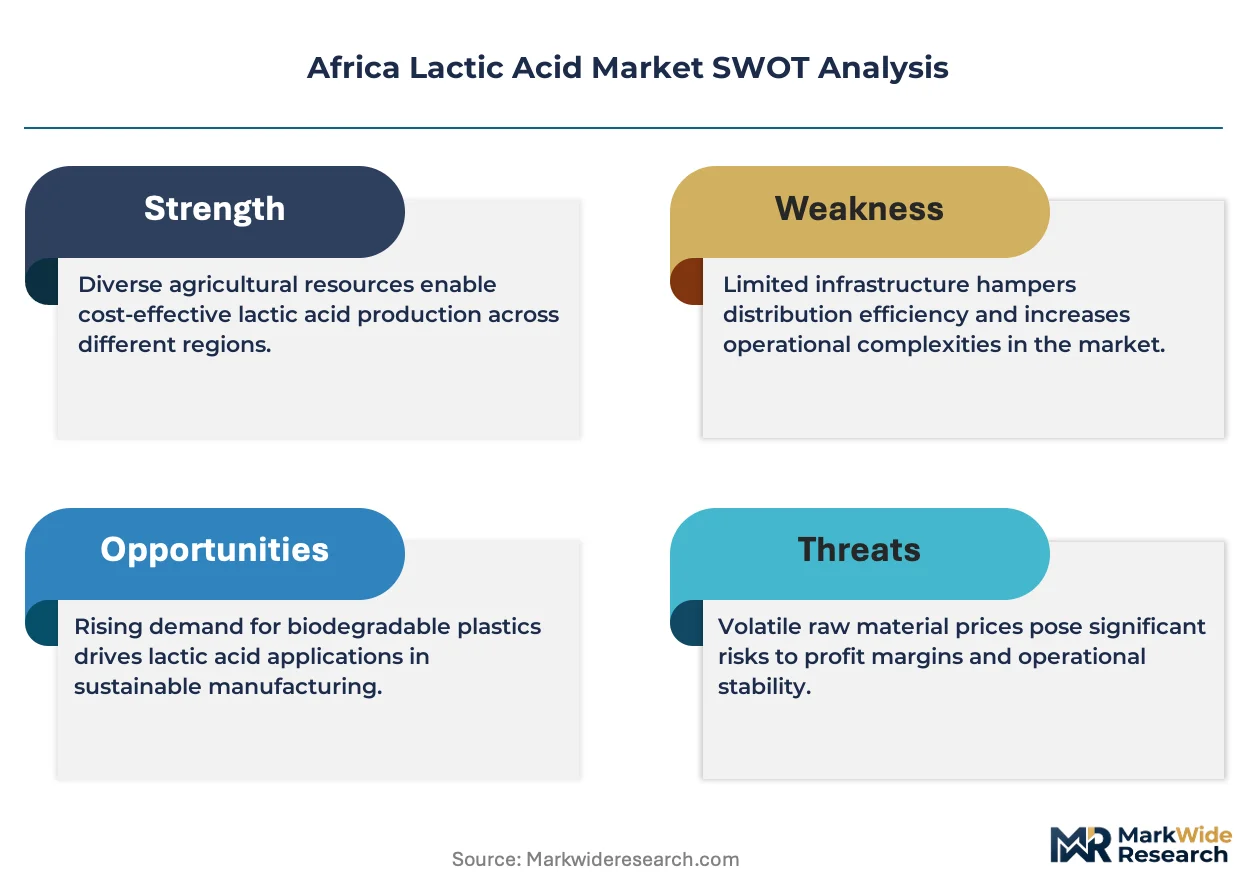
- Carbohydrate Feedstock Volatility:Maize and cassava price swings directly compress fermentation economics for regional producers lacking backward integration.
- Import Dependence:Containerized shipments from Asian manufacturing bases concentrate supply risk at Durban, Lagos, and Mombasa port bottlenecks.
- Pharmaceutical Grade Purity Thresholds:Stringent intravenous formulation standards limit local production participation to a narrow certified tier.
Strategic Opportunities
- East African Community Harmonization:Emerging technical regulations convergence creates cross-border grade recognition pathways for first-mover certification alignment.
- Cosmetic Formulator Expansion:Pharmaceutical-grade suppliers are pivoting toward pH adjuster demand in skincare manufacturing across Nairobi and Addis Ababa.
- Fermentation-Chemical Synthesis Hybridization:Technology convergence enables racemic mixture optimization for industrial-grade output cost reduction.
Industry Challenges
- Good Manufacturing Practice Certification Timelines:NAFDAC and SAHPRA documentation requirements extend supplier qualification cycles by 12-18 months.
- Cold Chain Integrity:Temperature-sensitive high-purity grades face degradation risk across last-mile distribution networks in landlocked markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Lactic Acid Market |
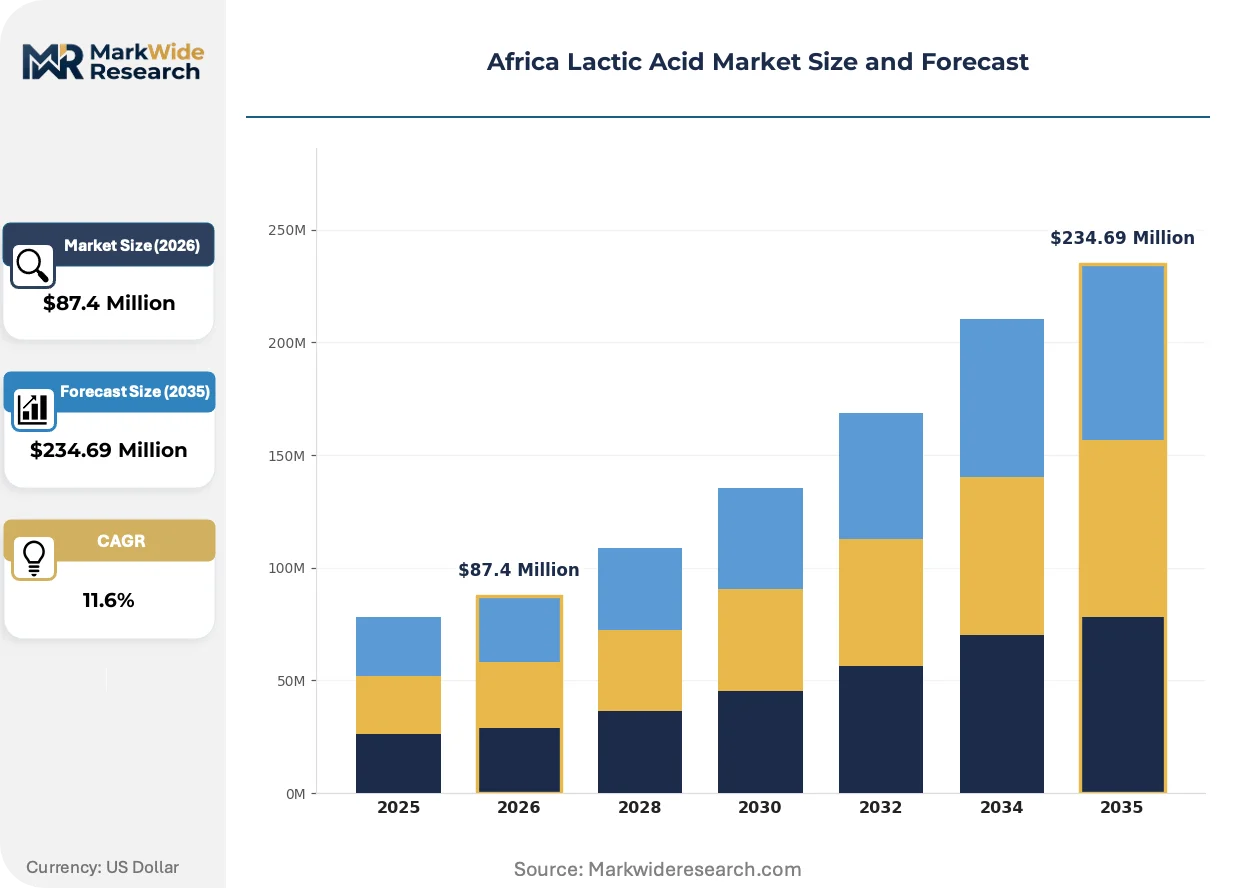
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $234.69 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Grade, Pharmaceutical Grade, Industrial Grade, Cosmetic Grade End User: Food & Beverage, Pharmaceuticals, Cosmetics, Biodegradable Plastics Form: Liquid, Powder, Granules, Crystal Application: Preservatives, Emulsifiers, pH Regulators, Flavor Enhancers |
| Companies Covered | Corbion, Galactic, Henan Jindan Lactic Acid Technology, Brenntag, Foodchem International Corporation, BASF SE, NatureWorks, Cargill, Jungbunzlauer Suisse, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Lactic Acid Market Strategic Shifts
Bioprocess intensification and regulatory harmonization are compressing traditional supply hierarchies while opening tier-jumping pathways for technology-advantaged producers.
Continuous fermentation systems with cell retention technology are replacing batch processing in new African installations. Dairy processors and industrial bioplastics manufacturers are adopting these systems at pilot scale in South Africa and Egypt. Equipment footprint reduction is miniaturizing capital requirements for mid-scale entrants previously excluded by batch reactor economics.
South Africa's Department of Health foodstuffs regulations, Nigeria's NAFDAC standards, and East African Community technical regulations are converging toward mutual recognition frameworks. This regulatory alignment reduces duplicate certification burdens for suppliers operating across multiple jurisdictions. Food-grade lactic acid traders are consolidating compliance documentation to exploit emerging cross-border passporting provisions.
Direct procurement from fermentation specialists is displacing distributor-mediated purchasing among large beverage and dairy processors. Long-term offtake agreements with volume commitments are replacing spot market transactions in Lagos and Johannesburg. This channel compression is most visible among multinational fast-moving consumer goods manufacturers consolidating supplier panels to three certified sources maximum.
Africa Lactic Acid Market Segmentation
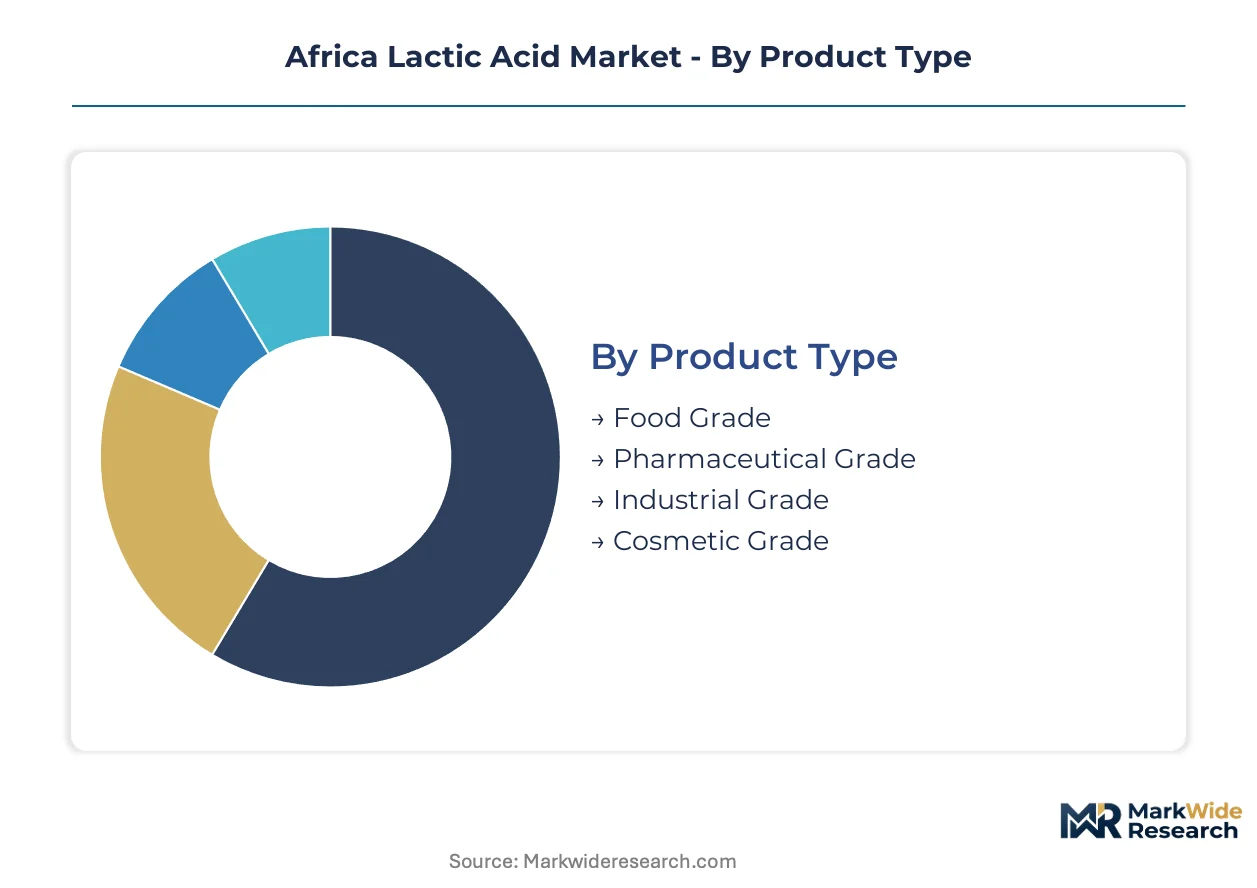
Grade purity thresholds and application-specific certification requirements fragment procurement patterns across African lactic acid channels. Substitution dynamics vary sharply by segment, with food-grade acid facing citric acid displacement while pharmaceutical grades command irreplaceable positions in parenteral formulations.
Product Type:
Substitution pressure intensifies downward from pharmaceutical toward industrial grades, where mineral acids compete aggressively on cost.
- Food Grade:Lactic acid meeting CODEX Alimentarius and national food safety authority specifications for antimicrobial preservation and pH modulation. Dairy processors in South Africa and Nigeria's Lagos-Kano corridor anchor procurement volumes under tightened Department of Health and NAFDAC labeling mandates.
- Pharmaceutical Grade:Ultra-high purity acid conforming to intravenous and parenteral formulation standards with documented endotoxin limits. Local production participation remains restricted to certified tiers due to SAHPRA and NAFDAC Good Manufacturing Practice documentation extending qualification cycles.
- Industrial Grade:Racemic mixtures and technical specifications serving chemical synthesis and metal treatment applications. Price competition from sulfuric and hydrochloric acids compresses margins for fermentation-based suppliers lacking feedstock backward integration.
- Cosmetic Grade:Buffered and neutralized formulations for pH adjustment in skincare manufacturing. Nairobi and Addis Ababa formulators are pivoting demand toward pharmaceutical-grade suppliers seeking cosmetic channel expansion.
Food Grade retains volume leadership; Biodegradable Plastics feedstock demand holds the steepest expansion curve among grade-adjacent applications.
End User:
Customer concentration patterns split between multinational fast-moving consumer goods manufacturers consolidating supplier panels and fragmented local processors.
- Food & Beverage:Acidification and preservation across processed dairy, fermented products, and beverages. Bulk procurement clusters in Nigeria's FMCG corridor and South African beverage production facilities.
- Pharmaceuticals:Excipient and active pharmaceutical ingredient applications requiring documented purity certificates. Stringent intravenous formulation standards limit accessible supply tiers.
- Cosmetics:pH adjustment and moisturizing agent functions in skincare and personal care manufacturing. East African Community regulatory harmonization is opening cross-border grade recognition pathways.
- Biodegradable Plastics:Polylactic acid feedstock for packaging converters seeking petroleum-derived polymer alternatives. This vertical is climbing the fastest as environmental regulations tighten across African markets.
Food & Beverage commands current procurement tonnage; Biodegradable Plastics is gaining share fastest on converter substitution mandates.
Form:
Logistics economics and end-use handling requirements determine form selection, with liquid dominating bulk shipments and solids capturing value-added niches.
- Liquid:Standard aqueous solutions at varying concentrations for direct processing integration. Containerized ocean freight from Asian manufacturing bases concentrates supply risk at Durban, Lagos, and Mombasa port bottlenecks.
- Powder:Spray-dried acid for extended shelf-life and reduced transport weight. Dairy and pharmaceutical processors in landlocked markets face cold chain integrity challenges with temperature-sensitive high-purity grades.
- Granules:Free-flowing particulate form for controlled dissolution in industrial applications. Chemical synthesis users favor this form for reactor feeding precision.
- Crystal:High-purity solid for specialized pharmaceutical and laboratory specifications. Premium positioning reflects additional purification steps and packaging requirements.
Liquid form retains volume leadership; Powder holds the steepest expansion curve on hinterland distribution cost optimization.
Application:
Functional substitution varies by application, with preservatives facing multiple alternative chemistries while pH regulators maintain more defensible positions.
- Preservatives:Antimicrobial function through pH reduction and lactate ion activity. Competition from benzoates and sorbates intensifies in cost-sensitive processed food segments.
- Emulsifiers:Lactic acid esters and derivatives stabilizing oil-water interfaces in dairy and bakery applications. Specific functionality limits direct substitution.
- pH Regulators:Buffering and acidification across food, pharmaceutical, and cosmetic matrices. Irreplaceable in fermentation processes and certain pharmaceutical formulations.
- Flavor Enhancers:Taste modification and sourness contribution in beverages and confectionery. Citric acid and malic acid compete on cost and regional taste preference alignment.
pH Regulators retain volume leadership; Biodegradable Plastics precursor applications hold the steepest expansion curve among functional categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Durban Container Terminal anchors Southern African lactic acid distribution, handling bulk chemical shipments that feed inland processing corridors through the Johannesburg-Durban freight spine.
South Africa
Beverage acidification and dairy preservation dominate Gauteng and Western Cape demand. The Department of Health's updated foodstuffs regulations mandate certified food-grade supplier documentation, filtering procurement toward SAHPRA-aligned distributors. Cape Town's pharmaceutical manufacturing cluster is expanding pH adjuster consumption for intravenous formulation production.
Nigeria
Lagos-Kano corridor snack and beverage producers concentrate bulk chemical procurement volumes. NAFDAC's tightened Good Manufacturing Practice certification extends supplier qualification timelines by 12-18 months. Kano's dairy processing facilities are integrating fermentation-grade acid for traditional product preservation.
Egypt
Pharmaceutical excipient demand from Cairo-Alexandria drug manufacturers anchors pharmaceutical-grade consumption. The country's national pharmaceutical regulator aligns purity specifications with emerging African Continental Free Trade Area technical standards. Port Said's chemical import infrastructure serves Red Sea distribution to East African markets.
Kenya
Nairobi skincare formulators are pivoting toward pharmaceutical-grade suppliers for pH adjustment in cosmetic manufacturing. East African Community harmonized technical regulations are creating cross-border grade recognition pathways. Mombasa port cold chain limitations constrain temperature-sensitive high-purity grade distribution to landlocked hinterlands.
Ethiopia
Addis Ababa's emerging personal care manufacturing base is absorbing cosmetic-grade lactic acid for moisturizer and pH buffer applications. The country's national food and drug authority is developing alignment protocols with EAC mutual recognition frameworks. Industrial parks around the capital are attracting fermentation technology pilot installations for import substitution.
Africa Lactic Acid Market Competitive Environment
Listed leaders compete with private specialists across certification tiers and feedstock integration depth. Market structure concentrates around three to five dominant suppliers holding pharmaceutical-grade certifications, with fragmented industrial-grade competition from mineral acid substitutes. Strategic archetypes separate fermentation technology leaders, carbohydrate feedstock integrators, and Asian volume shippers. Capacity expansion and backward integration into maize and cassava sourcing represent the dominant competitive moves.
Among fermentation technology specialists, Corbion and Galactic exemplify the premium-grade archetype through documented purity capabilities and African distribution network presence. Henan Jindan Lactic Acid Technology occupies the volume-driven position, shipping containerized acid to Durban, Lagos, and Mombasa port hubs from Asian manufacturing bases. These three anchors illustrate the competitive tension between technology-certified premiums and scale-driven cost positioning across African procurement channels.
| Leading Market Players |
|---|
| Corbion |
| Galactic |
| Henan Jindan Lactic Acid Technology |
| Brenntag |
| Foodchem International Corporation |
| BASF SE |
| NatureWorks |
| Cargill |
| Jungbunzlauer Suisse |
| Others |
Value Chain & Pricing Dynamics
Sixty-to-ninety-day inventory cycles at Lagos and Durban port hubs concentrate pricing power among containerized shippers while compressing margins for landlocked distributors lacking cold-chain redundancy. Pharmaceutical-grade premiums widen against industrial-grade baselines as NAFDAC and SAHPRA certification timelines filter supplier tiers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical-grade certified suppliers from food-grade volume players and industrial-grade commodity sellers. Price differentiation rests on SAHPRA alignment and fermentation feedstock backward integration. Cost compression in industrial-grade tiers intensifies because sulfuric and hydrochloric acid substitutes compete aggressively. Beverage processors in Nigeria's FMCG corridor exhibit highest price sensitivity; intravenous formulation manufacturers in Cape Town demonstrate lowest.
Supply Chain Analysis
Container availability constraints on Asia-Africa trade lanes elevate inbound logistics costs for fermentation-grade acid shipments through Mombasa and Lagos. Supply concentrates in China, Belgium, and Thailand as primary manufacturing origins. Raw material dependencies draw from maize starch, cassava chips, and molasses feedstocks. Single-source vulnerability at Durban Container Terminal creates concentration risk. Distribution runs through certified distributor networks with SAHPRA and NAFDAC documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Polylactic acid feedstock adoption among packaging converters signals early-cycle expansion with biodegradable plastics penetration accelerating across African markets.
For Market Incumbents: Consolidate certification documentation across SAHPRA, NAFDAC, and EAC harmonized standards to defend against Asian volume shippers undercutting on price. Deepen backward integration into Nigerian maize and cassava sourcing to secure fermentation economics against carbohydrate price volatility. Channel control through direct procurement relationships with Lagos-Kano beverage clusters reinforces position. For New Entrants and Emerging Players: Last-mile cold chain gaps in landlocked East African markets present service-layer white space where incumbents under-serve pharmaceutical-grade powder distribution. Target Nairobi and Addis Ababa cosmetic formulators seeking pH adjuster supply with EAC-aligned certification. Go-to-market leverage through industrial park pilot fermentation installations enables technology demonstration before scale commitment. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with lactic acid divisions lacking African distribution presence. Five-to-ten-year viability frames around regulatory harmonization completion and bioplastics substitution mandates. Target acquisition archetype: fermentation technology specialists with EAC certification progress and captive carbohydrate supply. Signal to watch: East African Community mutual recognition framework ratification accelerating cross-border grade passporting.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock | Captive maize and cassava supply secures fermentation cost advantages against Asian importers. |
| Pharmaceutical-Grade Certification Investment | SAHPRA and NAFDAC alignment opens intravenous formulation channels with premium pricing. |
| East African Community Regulatory Harmonization | Cross-border grade recognition reduces duplicate compliance burdens for multi-territory suppliers. |
| Continuous Fermentation Technology Deployment | Cell retention systems miniaturize capital requirements for mid-scale African entrants. |
| Long-term Offtake Agreements with FMCG Manufacturers | Volume commitments from Lagos-Johannesburg beverage clusters displace spot market transactions. |
Study Parameters
Two parallel data streams informed the analysis: primary engagement with fermentation technology directors, procurement leads at Nigerian dairy processors, pharmaceutical quality assurance managers, and East African cosmetic formulators; and secondary validation through customs trade records, SAHPRA registration databases, EAC technical regulation filings, and SEC disclosures from listed suppliers. Bottom-up volume builds across grade tiers and end-use segments triangulated against top-down market sizing from production capacity assessments and import flow analysis.
Across the analysis window, the forecasting framework modeled grade purity thresholds, application-specific certification requirements, regional regulatory cluster adoption curves, and feedstock cost dynamics. CAGRs derived from segment-level volume trajectories weighted by pharmaceutical-grade premium realization and industrial-grade substitution elasticity. Key inputs included polylactic acid capacity buildout timelines among packaging converters and EAC harmonization implementation schedules.
Forecasts assume regulatory continuity in South African Department of Health foodstuffs regimes, NAFDAC GMP certification pathways, and EAC technical barrier-to-trade protocols; material policy shifts would require re-modeling. Commodity price volatility in maize and cassava markets, port congestion at Durban and Lagos, and cold chain infrastructure gaps in hinterland distribution represent specific revision risks. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Isostearyl Alcohol Market
Specialty Chemicals
Global Spray Polyurethanes Foam Market
Specialty Chemicals
Cellulose Ether and Derivatives Market
Specialty Chemicals
Global Anti-Static Agents Market
Specialty Chemicals
Alkylene Carbonates Market
Specialty Chemicals
4-Benzoylbutyric Acid Market
Specialty Chemicals
Titanium Fluoride Phosphate Market
Specialty Chemicals
India Prussian Blue Market
Specialty Chemicals
Global Vinyl Sulfone Market
Specialty Chemicals
Germany Starch Derivatives Market
Specialty Chemicals
Tubatoxin Market
Specialty Chemicals
Global Ceramide Market
Specialty Chemicals
CMIT/MIT Market
Specialty Chemicals
Cubeb Oil Market
Specialty Chemicals
Diindolylmethane Market
Specialty Chemicals
Global Molecular Weight Marker Market