
 Methyl Salicylate Market | 2026-2036
Methyl Salicylate Market Size, Share, and Industry Trends Forecast 2026-2036
Methyl Salicylate Market Outlook
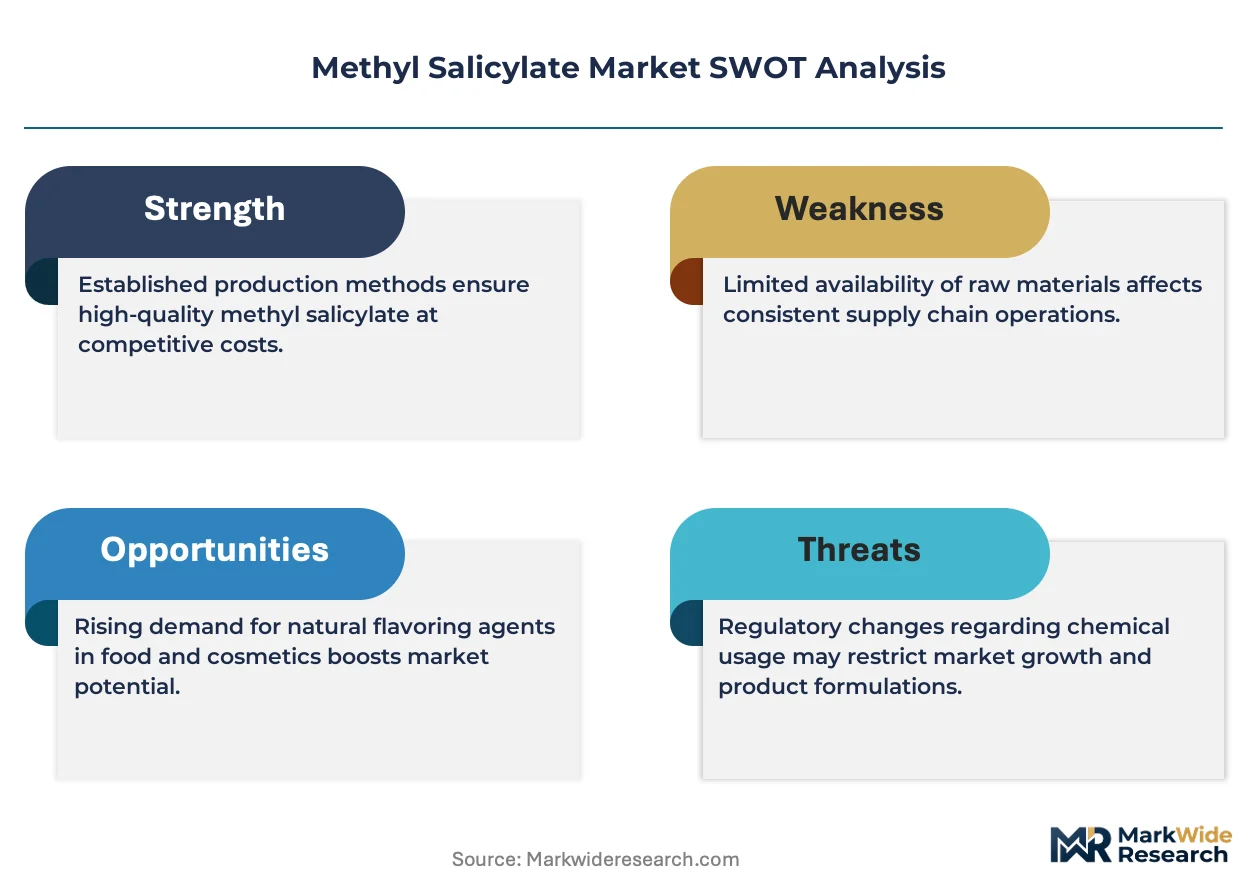
Technical service contracts for custom synthesis and regulatory documentation are shifting how methyl salicylate suppliers monetize relationships beyond bulk chemical sales. Eastman Chemical Company leverages its integrated aromatic chemicals platform to sustain cost-competitive supply across North American pharmaceutical accounts. Novacyl dominates European specialty salicylate derivatives through backward integration into salicylic acid feedstock. Zhenjiang Gaopeng Pharmaceutical occupies a strong position in Asian API-grade production, competing on pharmacopeia compliance and batch consistency.
Methyl salicylate is an organic ester synthesized from salicylic acid and methanol, characterized by a boiling point near 222°C and a characteristic wintergreen odor that underpins its functional identity. It serves primarily as a counterirritant in topical analgesic formulations and as a fragrance and flavoring agent across consumer products. The pharmaceutical product type anchors current revenue pools given its entrenched use in over-the-counter muscle pain therapies, while the cosmetic segment differentiates through premium fragrance applications where natural-origin positioning commands margin premiums. The pain relief application leads volume consumption, though flavor enhancement in confectionery and oral care sustains steady demand from food producers seeking GRAS-certified additives.
EPA oversight of chemical manufacturing emissions and FDA enforcement of drug substance Current Good Manufacturing Practice standards shape production economics and facility investment requirements for domestic suppliers. REACH registration obligations in Europe and China's NMPA pharmacopeia alignment for imported API grades create layered compliance barriers that filter market access. Stakeholders must monitor evolving monograph revisions and green chemistry mandates to anticipate which purity grades and documentation packages will become table stakes for contract renewals.
Market Dynamics
Pharmaceutical formulators are tightening purity specifications for API-grade methyl salicylate, forcing suppliers to revalidate batch documentation and upgrade analytical capabilities to meet evolving FDA monograph and REACH registration thresholds.
Growth Catalysts
- Topical analgesic expansion:Pain relief formulations in over-the-counter segments are absorbing higher volumes of pharmacopeia-grade material as retail shelf space for muscle rubs and patches widens across North American and European pharmacy chains.
- REACH compliance premiums:European ECHA registration requirements for salicylate derivatives are filtering out non-compliant traders, consolidating procurement relationships with registered manufacturers who can deliver full dossier documentation.
- India API manufacturing scale-up:Domestic Indian producers are backward-integrating into salicylic acid feedstock to capture contract manufacturing opportunities for export-oriented pain relief brands.
Market Restraints
- Methanol price volatility:Esterification feedstock costs fluctuate with natural gas and coal pricing in key production zones, compressing margin stability for non-integrated compounders.
- Salicylic acid supply concentration:Three Asian producers control the majority of technical-grade feedstock, creating bottleneck risk for European and North American formulators lacking long-term offtake agreements.
- Natural wintergreen substitution:Botanically derived methyl salicylate from Gaultheria procumbens extraction is capturing premium fragrance applications, displacing synthetic material in cosmetic positioning.
Strategic Opportunities
- Brazilian pharmaceutical market penetration:ANVISA regulatory alignment with USP-NF standards is opening pathways for API-grade suppliers to serve Latin American generic topical drug manufacturers.
- Green chemistry process incentives:EPA Safer Choice and EU Green Deal bio-based manufacturing mandates are rewarding producers who demonstrate carbon-intensity reductions in esterification pathways.
- Direct-to-formulator digital platforms:Specialty chemical marketplaces are disintermediating traditional distributor networks, enabling qualified suppliers to capture documentation-heavy pharmaceutical accounts with faster technical response.
Industry Challenges
- Analytical chemist scarcity:Validated HPLC method development and ICH Q3D elemental impurity testing expertise is concentrating at contract research organizations, inflating quality assurance payrolls for mid-size producers.
- Multipurpose equipment validation:Shared reactor trains across salicylate derivative families require extensive cleaning validation protocols, extending campaign changeover timelines and reducing effective capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Methyl Salicylate Market |
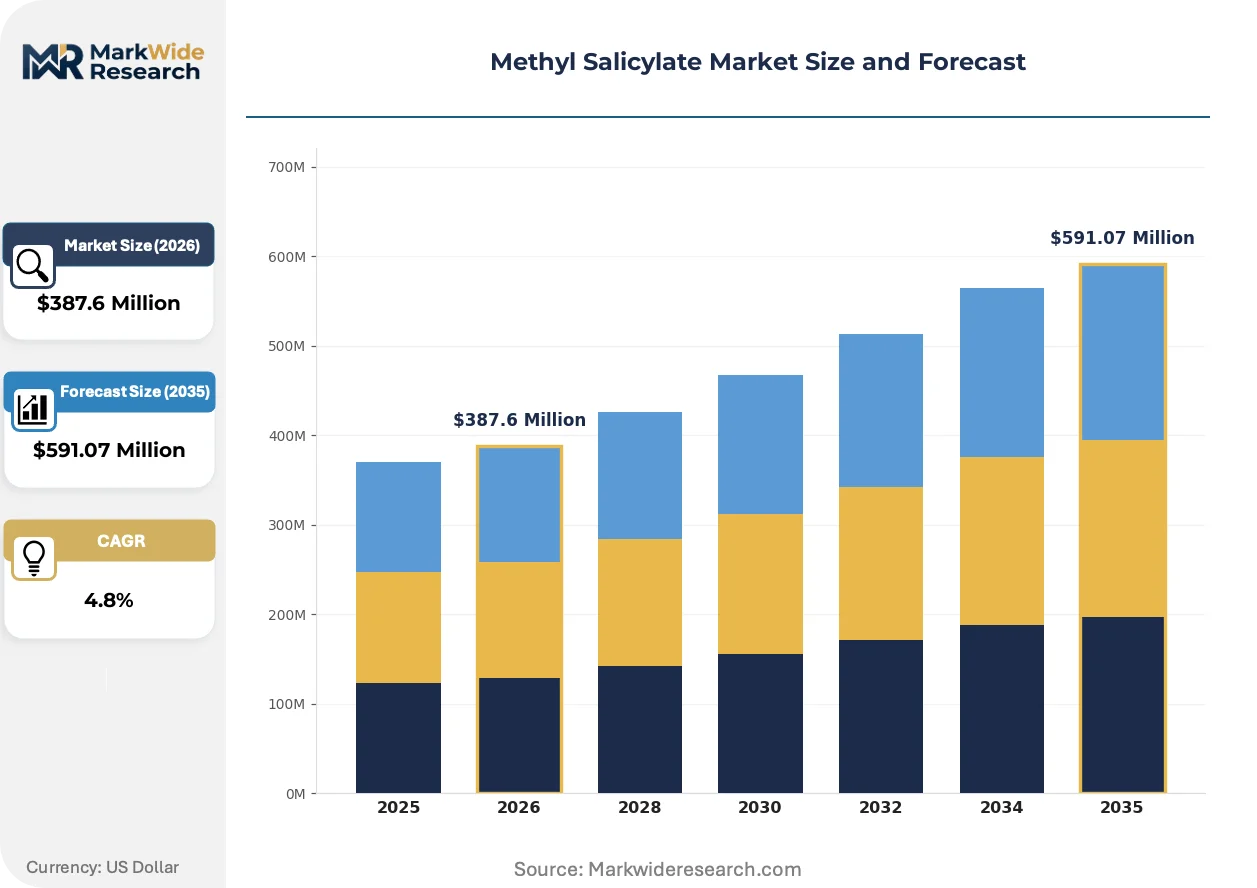
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $591.07 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pharmaceutical, Cosmetic, Food Flavoring, Aroma Compound Application: Pain Relief, Fragrance, Flavor Enhancement, Industrial Solvent End User: Healthcare Providers, Cosmetic Manufacturers, Food Producers, Chemical Companies Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesale |
| Companies Covered | Tokyo Chemical Industry Co., Ltd., Thermo Fisher Scientific India Pvt. Ltd., Novacyl, Eastman Chemical Company, BASF SE, Zhenjiang Gaopeng Pharmaceutical Co., Ltd., Siddharth Carbochem Products Ltd., Shandong Longxin Chemical, Alta Laboratories Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Methyl Salicylate Market Strategic Shifts
Continuous processing technologies and regulatory data integrity mandates are converging to reshape how methyl salicylate manufacturers demonstrate batch consistency and secure pharmaceutical qualification.
Continuous flow reactor systems for salicylic acid methylation are electrifying process economics by shrinking reactor footprint, intensifying heat transfer, and enabling real-time PAT monitoring that satisfies FDA process analytical technology expectations. European and North American pharmaceutical chemical specialists are piloting these installations to reduce solvent inventory and accelerate batch release timelines. The technology is electrifying competitive positioning for suppliers seeking to displace batch-reactor competitors in high-value API-grade tenders.
EU REACH Annex XVII restrictions on skin sensitizers are tightening labeling and concentration thresholds for cosmetic-grade methyl salicylate, compelling fragrance houses to reformulate wintergreen-accord products and document safety assessments under ECHA guidance. German and French cosmetic formulators are accelerating substitution testing for alternative cooling agents. The regulatory pressure is compressing demand elasticity for synthetic material in premium personal care while expanding documentation burdens for suppliers serving European beauty brands.
Pharmaceutical procurement teams are consolidating qualified supplier lists from twelve-vendor panels to three-vendor strategic partnerships, demanding dedicated technical service liaisons and customized regulatory packages. This concentration is displacing spot-market traders and forcing residual suppliers to invest in pharmacovigilance support capabilities. The shift is most visible among North American generic topical drug manufacturers who now prioritize supply assurance and audit transparency over unit price in methyl salicylate tenders.
Methyl Salicylate Market Segmentation
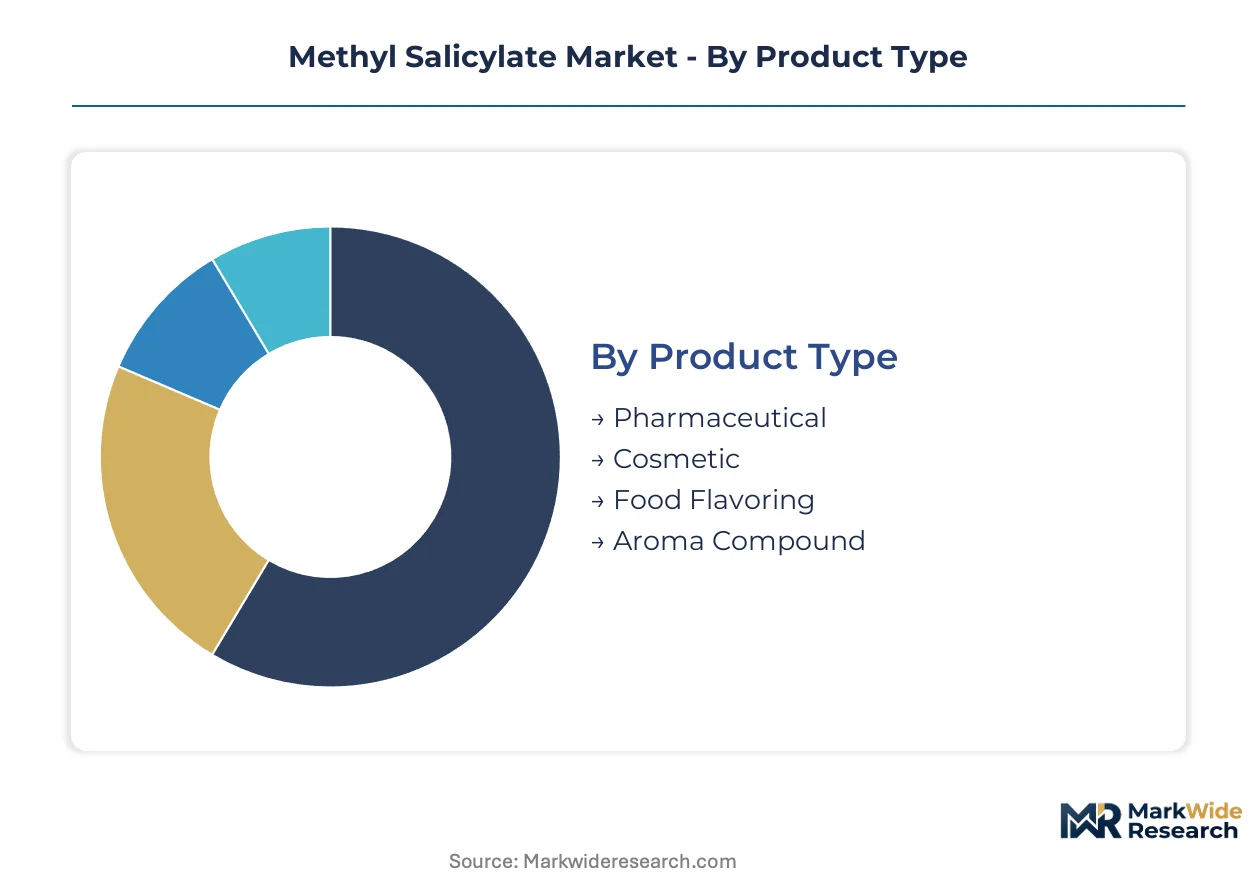
Methyl salicylate procurement patterns diverge sharply across purity grades and documentation requirements. Pharmaceutical formulators demand USP-NF compliance and complete regulatory dossiers, while fragrance houses prioritize odor profile consistency over analytical certificates.
Product Type:
Certification burdens stratify sharply across this dimension, with pharmaceutical grades requiring FDA drug substance Current Good Manufacturing Practice validation and REACH registration, while food-grade material demands GRAS affirmation and FSSAI clearance for Indian export markets.
- Pharmaceutical:USP-NF monograph compliance anchors specification sheets, with elemental impurity testing under ICH Q3D guidelines now mandatory for API-grade tenders. Demand concentrates in North American generic topical drug manufacturers expanding patch and gel formulations for retail pharmacy chains.
- Cosmetic:Odor profile standardization and skin sensitization documentation under EU REACH Annex XVII shape supplier qualification. European fragrance houses in Germany and France drive specification evolution as natural wintergreen substitution pressures synthetic positioning.
- Food Flavoring:GRAS certification and batch-specific COA documentation satisfy FEMA and FDA food additive requirements.
- Aroma Compound:Technical-grade material serves industrial fragrance compounding with less stringent purity thresholds.
Pharmaceutical sits at the top of the volume ranking, with Cosmetic climbing the fastest as premium personal care brands reformulate around natural-origin positioning.
Application:
Cost tier differentiation separates high-value pharmaceutical applications from commodity industrial uses, with pain relief formulations commanding three-to-five-fold price premiums over solvent-grade material.
- Pain Relief:Counterirritant mechanisms in topical analgesics demand pharmacopeia-grade purity with validated HPLC assay methods. North American and European pharmacy chains absorb expanding volumes as over-the-counter muscle rub shelf space widens.
- Fragrance:Wintergreen odor profiles in premium personal care require organoleptic batch consistency and EU-compliant safety assessments. German and French cosmetic formulators are accelerating substitution testing for alternative cooling agents under tightening skin sensitizer regulations.
- Flavor Enhancement:Confectionery and oral care applications sustain steady demand through GRAS-certified additive procurement.
- Industrial Solvent:Technical-grade material serves specialty coating and adhesive formulations with minimal documentation overhead.
Pain Relief dominates absolute volume consumption, with Fragrance expanding most quickly as clean-label positioning reshapes premium cosmetic procurement.
End User:
Customer type determines technical service intensity, with healthcare providers and cosmetic manufacturers demanding dedicated regulatory liaisons while chemical companies prioritize spot-market pricing flexibility.
- Healthcare Providers:Hospital systems and clinic chains require validated supply chain documentation and pharmacovigilance support for topical analgesic procurement.
- Cosmetic Manufacturers:Fragrance houses and personal care formulators in France and Germany drive ECHA-compliant safety assessment requirements.
- Food Producers:Confectionery and oral care manufacturers prioritize GRAS certification and batch traceability systems.
- Chemical Companies:Industrial solvent buyers emphasize bulk pricing and flexible delivery scheduling over analytical package depth.
Healthcare Providers anchor current procurement volume, with Cosmetic Manufacturers gaining share fastest as premium fragrance applications multiply.
Distribution Channel:
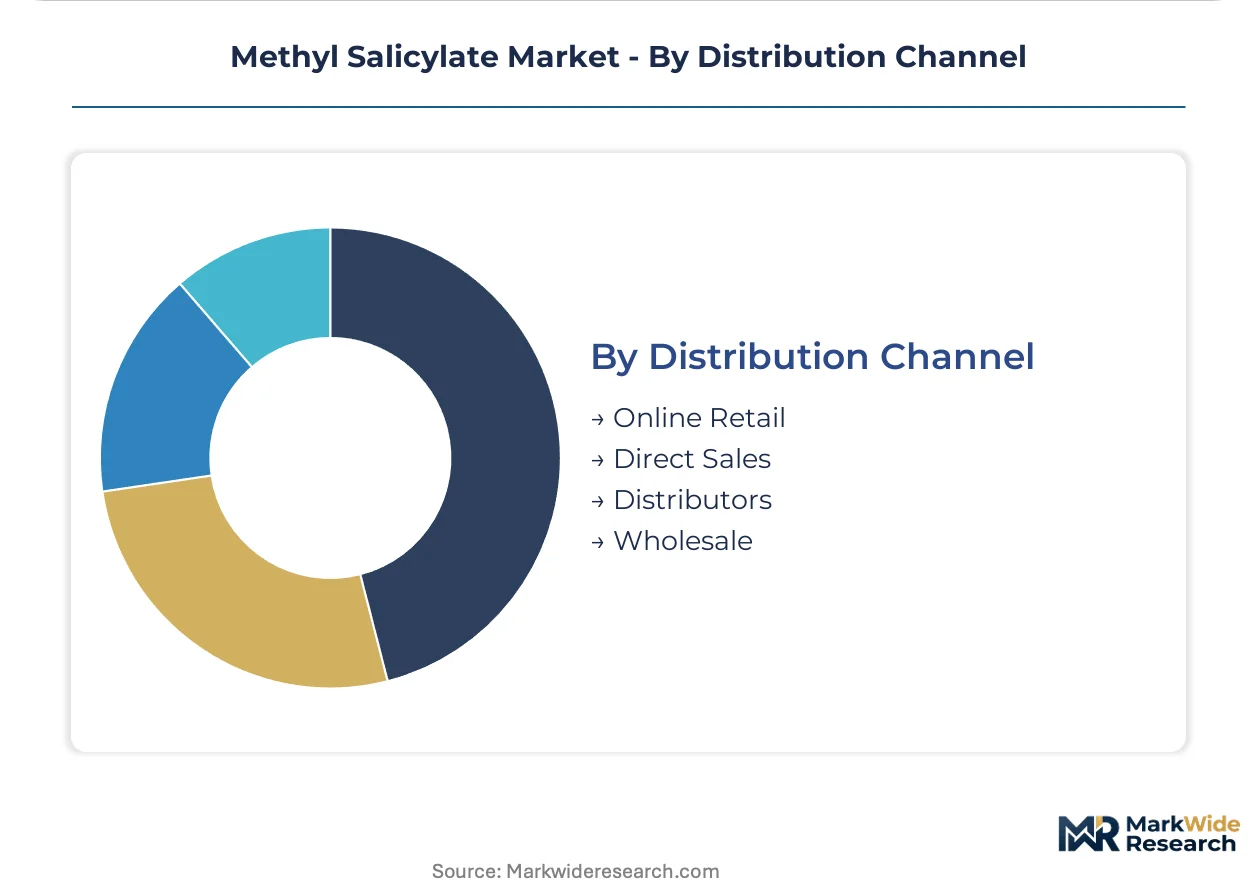
Supply concentration in direct sales relationships is displacing traditional distributor networks as pharmaceutical procurement teams consolidate qualified supplier lists and demand faster technical response.
- Online Retail:Specialty chemical marketplaces are disintermediating traditional channels for mid-tier purity grades, enabling qualified suppliers to capture documentation-heavy accounts with accelerated response timelines.
- Direct Sales:Strategic partnerships with dedicated technical service liaisons dominate API-grade pharmaceutical procurement as vendor panels shrink from twelve suppliers to three.
- Distributors:Regional chemical distributors retain relevance for industrial solvent and technical-grade material with lower documentation burdens.
- Wholesale:Bulk commodity transactions serve food flavoring and aroma compound segments with standardized specifications.
Direct Sales commands the largest revenue share, with Online Retail climbing fastest as digital platforms penetrate specialty chemical procurement workflows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's API manufacturing scale-up contrasts with Germany's tightening REACH compliance burdens, while the United States and China pursue divergent regulatory pathways for pharmaceutical-grade material.
United States
FDA monograph revisions for topical analgesics are elevating purity documentation requirements. EPA Safer Choice program incentives reward carbon-intensity reductions in esterification processes. New Jersey and Pennsylvania chemical corridors host contract manufacturers expanding pharmacopeia-grade production for generic drug formulators.
Germany
ECHA REACH Annex XVII restrictions on skin sensitizers are compressing cosmetic-grade demand elasticity. EU Green Deal bio-based manufacturing mandates favor producers demonstrating sustainable process chemistry. Frankfurt and Hamburg fragrance houses accelerate substitution testing for alternative cooling agents under tightening safety assessments.
India
Domestic API manufacturers are backward-integrating into salicylic acid feedstock to capture export-oriented pain relief contracts. CDSCO pharmacopeia alignment with USP-NF standards streamlines regulatory pathways for pharmaceutical exports. Gujarat and Maharashtra chemical clusters concentrate methyl salicylate procurement scaling for contract research organizations serving North American generic brands.
China
NMPA pharmacopeia alignment requirements for imported API grades create layered compliance barriers filtering market access. Dual carbon goals intensify scrutiny of coal-derived methanol feedstock in esterification pathways. Shandong and Jiangsu provinces dominate technical-grade production, with Zhejiang facilities upgrading analytical capabilities for pharmaceutical qualification.
Brazil
ANVISA regulatory alignment with USP-NF standards opens pathways for API-grade suppliers serving Latin American generic topical drug manufacturers. Hospital system procurement consolidation demands validated supply chain documentation. São Paulo pharmaceutical clusters absorb expanding volumes of pharmacopeia-grade material for retail pharmacy chain distribution.
Methyl Salicylate Market Competitive Environment
Top-tier vendors anchor integrated aromatic chemicals platforms, while mid-scale compounders compete on batch consistency and regional pharmacopeia compliance. The supplier base stratifies between backward-integrated feedstock controllers and specialized esterification houses. Three archetypes dominate: multinational chemical conglomerates with diversified salicylate portfolios, Asian API-grade specialists competing on documentation packages, and regional fragrance compounders prioritizing odor profile standardization. Capacity expansion and strategic technical service partnerships represent the dominant competitive moves as procurement panels consolidate.
Among the named participants, Tokyo Chemical Industry Co., Ltd. and Thermo Fisher Scientific India Pvt. Ltd. exemplify laboratory and reagent-grade supply archetypes with distribution reach across multiple geographies. Novacyl occupies a position within European specialty salicylate derivatives through captive salicylic acid supply. Eastman Chemical Company represents North American integrated aromatic chemicals production. Zhenjiang Gaopeng Pharmaceutical Co., Ltd. and Siddharth Carbochem Products Ltd. anchor Asian API-grade manufacturing competing on pharmacopeia compliance. BASF SE exemplifies multinational diversified chemical production with cross-segment salicylate capabilities.
| Leading Market Players |
|---|
| Tokyo Chemical Industry Co., Ltd. |
| Thermo Fisher Scientific India Pvt. Ltd. |
| Novacyl |
| Eastman Chemical Company |
| BASF SE |
| Zhenjiang Gaopeng Pharmaceutical Co., Ltd. |
| Siddharth Carbochem Products Ltd. |
| Shandong Longxin Chemical |
| Alta Laboratories Ltd. |
| Others |
Value Chain & Pricing Dynamics
Pharmaceutical procurement consolidation from twelve-vendor panels to three-vendor strategic partnerships is forcing suppliers to absorb documentation costs and technical service investments, compressing margin structures for non-integrated compounders while rewarding backward-integrated manufacturers with pricing power anchored in captive salicylic acid supply.
Pricing Analysis
Capacity additions in China's Shandong and Jiangsu provinces are reshaping price floors for technical-grade material, while API-grade premiums widen. Three-tier pricing structure across pharmaceutical, cosmetic, and industrial grades separates USP-NF compliant batches from REACH-registered cosmetic material and technical solvent grades. Pricing pressure stems from methanol feedstock volatility tied to natural gas and coal pricing. Chemical companies buying industrial solvent grades exhibit highest price sensitivity; healthcare providers purchasing API-grade material prioritize supply assurance over unit cost.
Supply Chain Analysis
REACH registration and FDA drug substance CGMP certification are gating market access, filtering out non-compliant traders. Supply concentrates in China, India, and Germany, with Shandong and Jiangsu provinces dominating technical-grade output and Gujarat and Maharashtra clusters scaling API-grade production. Feedstock dependencies center on salicylic acid from Asian producers, methanol from coal and natural gas streams, and specialized catalysts for esterification. Single-source vulnerability runs through concentrated salicylic acid supply. Distribution runs through direct sales relationships for pharmaceutical grades and regional distributors for industrial material.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where pharmaceutical formulators are prioritizing pharmacopeia compliance and batch consistency over spot-market pricing, compressing viable supplier pools to integrated manufacturers with validated analytical capabilities.
For Market Incumbents: Deploy dedicated technical service liaisons to defend qualified supplier status as procurement panels consolidate. Deepen backward integration into salicylic acid feedstock to insulate margin structures from Asian feedstock concentration risk. Expand analytical capabilities for ICH Q3D elemental impurity testing to meet evolving FDA monograph thresholds.
For New Entrants and Emerging Players: Contract research organizations serving North American generic drug manufacturers represent the most penetrable channel partner type for documentation-heavy API-grade supply. Target Brazilian pharmaceutical clusters where ANVISA alignment with USP-NF standards is opening procurement pathways. Pursue green chemistry process certifications to capture EPA Safer Choice and EU Green Deal incentive flows.
For Investors and Strategic Acquirers: Asymmetric upside sits with Asian API-grade specialists possessing pharmacopeia compliance infrastructure and established regulatory dossiers. Five-to-ten year viability favors producers with demonstrated carbon-intensity reductions in esterification pathways. Watch for FDA monograph revision announcements as inflection indicators for quality-grade demand shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Salicylic Acid | Captive feedstock supply insulates margin structures from Asian concentration risk. |
| Continuous Flow Reactor Installation | Real-time PAT monitoring satisfies FDA process analytical technology expectations for API-grade tenders. |
| REACH Registration Completion | Full dossier documentation filters out non-compliant traders in European procurement. |
| Green Chemistry Certification | EPA Safer Choice and EU Green Deal mandates reward carbon-intensity reductions. |
| Direct-to-Formulator Digital Platform | Specialty chemical marketplaces disintermediate distributor networks for faster technical response. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with pharmaceutical procurement managers, API manufacturing plant directors, fragrance house technical directors, and regulatory affairs specialists with secondary validation against FDA monograph filings, ECHA REACH registrations, CDSCO export approvals, customs trade data, and chemical industry association reports. Bottom-up volume modeling and top-down value triangulation anchored segment-level outputs.
Historical reference periods anchored the forecast window against documented production capacity, trade flows, and regulatory milestone timelines across the projection horizon. Segmentation dimensions modeled include product grade tier, end-use application, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to volume and value baselines. Forecast inputs incorporated methanol feedstock pricing trajectories and evolving pharmacopeia compliance thresholds.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA monograph revision timing, ECHA Annex XVII restriction expansion, and natural wintergreen substitution rates in premium fragrance applications. A model refresh is warranted upon material change in salicylic acid feedstock supply concentration or green chemistry mandate enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Distarch Phosphate Market
Specialty Chemicals
Fatliquoring Agents Market
Specialty Chemicals
Ethyl Ascorbic Acid Market
Specialty Chemicals
Salicylate Market
Specialty Chemicals
Squalene Market
Specialty Chemicals
Isostearyl Alcohol Market
Specialty Chemicals
Bio-Based Aromatics Market
Specialty Chemicals
Bromocyclopentane Market
Specialty Chemicals
Silicone Acrylate Market
Specialty Chemicals
4-Benzoylbutyric Acid Market
Specialty Chemicals
Global Baking Soda Substitute Market
Specialty Chemicals
Monomethyl Acetoacetamide Market
Specialty Chemicals
Glutathione Market
Specialty Chemicals
Petroleum Jelly Market
Specialty Chemicals
Phenyl Trimethicone Market
Specialty Chemicals
Multichannel Reagent Reservoir Market