
 Methyltrimethoxysilane Market | 2026-2036
Methyltrimethoxysilane Market Size, Share, and Industry Trends Forecast 2026-2036
Methyltrimethoxysilane Market Analytics
Chinese silane producers is repositioning capacity toward higher-purity methyltrimethoxysilane grades for electronics-grade applications. Shin-Etsu Chemical Co. Ltd. anchors its position through captive chlorosilane feedstock integration across Japanese manufacturing sites. Dow competes on formulation science breadth, extending its silane portfolio into hybrid adhesive systems for automotive OEMs. Wacker Chemie AG specializes in construction-sector delivery, leveraging regional compounding facilities to control specification-grade supply chains.
Methyltrimethoxysilane (MTMS) functions as an organosilicon coupling agent with the molecular formula CH₃Si(OCH₃)₃, typically manufactured via methanolysis of methyltrichlorosilane to yield a liquid with specific gravity near 0.95 g/cm³ and flash point around 11°C. The compound serves primarily as a crosslinking precursor in moisture-cure silicone systems and as a surface modifier for inorganic substrates requiring hydrophobic functionalization. Liquid formulations dominate commercial volumes due to ease of metered dosing in continuous adhesive and sealant production lines. Construction end-use applications sustain the largest current consumption base, though electronics-grade specifications in semiconductor encapsulation represent the fastest-expanding margin pool. Concentrated product types occupy the premium tier where moisture sensitivity demands controlled packaging and shorter logistics cycles.
REACH registration requirements in Europe and EPA TSCA Section 5 scrutiny in the United States constrain market entry for unregistered silane variants, elevating compliance costs for specialty grades. China's MEE enforces GB 30982 VOC limits in construction adhesives, directly favoring MTMS-based low-solvent formulations over conventional solvent-borne alternatives. Japan's METI chemical substance classification under CSCL mandates prior notification for new silane derivatives used in electronics manufacturing. Stakeholders must track evolving substance restriction lists across these jurisdictions to anticipate reformulation mandates and secure advance positioning in specification-driven segments.
Market Dynamics
China's MEE enforcement of GB 30982 VOC limits is compressing solvent-borne adhesive formulations and redirecting formulation demand toward MTMS-based low-solvent systems across construction and electronics manufacturing clusters.
Growth Catalysts
- MEE VOC Regulations:China's GB 30982 standards mandate reduced solvent content in construction adhesives, directly favoring MTMS-based formulations over conventional alternatives in sealant production.
- Electronics Encapsulation Demand:Semiconductor packaging requirements for moisture-resistant encapsulation materials are pulling higher-purity MTMS grades into advanced manufacturing processes.
- Silicone Downstream Clustering:Eastern coastal provinces in China concentrate silicone compounding capacity, creating localized demand density that reduces logistics friction for MTMS suppliers.
Market Restraints
- Chlorosilane Feedstock Volatility:Methyltrichlorosilane price swings transmit directly into MTMS production economics, squeezing margin stability for non-integrated producers.
- Moisture Sensitivity Handling:MTMS hydrolytic instability demands nitrogen-blanketed storage and shortened distribution cycles, elevating working capital requirements across the value chain.
- Flammability Classification:The 11°C flash point triggers hazardous material shipping protocols under DOT and ADR regulations, constraining last-mile delivery flexibility.
Strategic Opportunities
- India Construction Chemicals:BIS certification requirements for structural sealants in commercial building projects create specification-grade entry points for compliant MTMS suppliers.
- Hybrid Adhesive Formulations:Convergence of silicone-urethane hybrid systems in automotive OEM assembly lines opens formulation partnerships beyond traditional silicone houses.
- South Korea Display Manufacturing:MFDS-regulated electronics materials sourcing for OLED encapsulation favors regional MTMS purification investments serving Samsung and LG supply chains.
Industry Challenges
- High-Purity Certification Timelines:Electronics-grade qualification cycles spanning 18-24 months for semiconductor customers delay revenue recognition from new capacity investments.
- Specialized Handling Infrastructure:Moisture-exclusion protocols require stainless steel reactor fleets and inert gas distribution networks that demand capital deployment ahead of contracted demand.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Methyltrimethoxysilane Market |
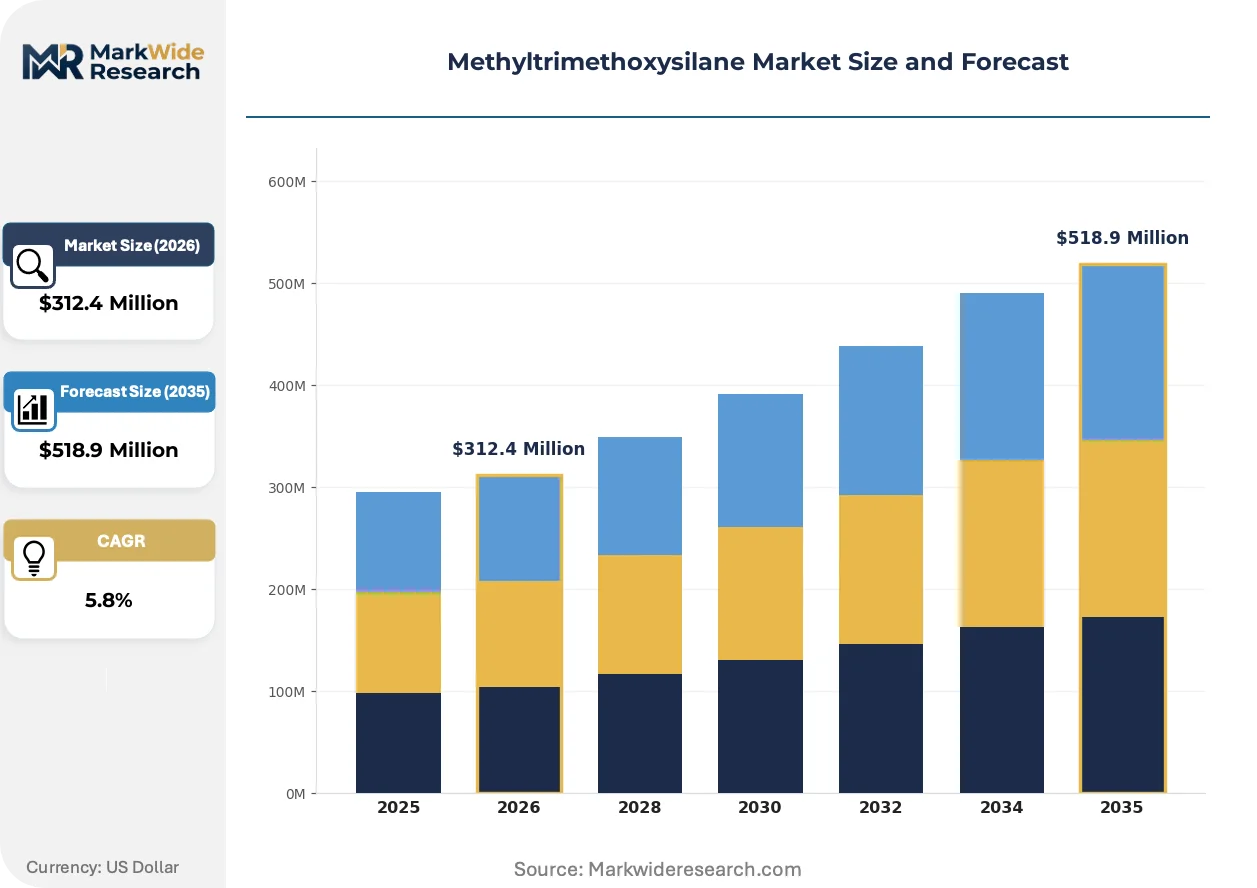
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $518.9 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Concentrated, Diluted, Liquid, Powder Application: Adhesives, Sealants, Coatings, Surface Modifiers End Use Industry: Construction, Automotive, Electronics, Textile Delivery Mode: Bulk, Drum, Tote, Container |
| Companies Covered | Evonik Industries AG, Shin-Etsu Chemical Co. Ltd., Dow, Gelest Inc., Huangshan KBR New Material Technology Co. Ltd., Zhejiang Sucon Silicone Co. Ltd., Hubei Liding Chemical Co. Ltd., United Chemical Technologies, Wacker Chemie AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Methyltrimethoxysilane Market Evolving Landscape
Formulation science is converging with regulatory chemistry to reshape how silane coupling agents enter end-use specifications, with moisture-cure system architectures undergoing systematic redesign across adhesive and coating applications.
Continuous flow reactor technology for methanolysis of methyltrichlorosilane is integrating into Chinese and Japanese manufacturing footprints, replacing batch kettle operations. Electronics-grade producers in Jiangsu and Shizuoka prefectures are adopting these systems to reduce residual chloride contamination below 50 ppm thresholds. This process architecture is integrating quality consistency with throughput scalability, compressing the cost gap between industrial-grade and high-purity MTMS specifications.
REACH authorization requirements under ECHA Annex XIV are tightening downstream notification obligations for silanes used in consumer-facing construction products. Formulators exporting into EU member states must now document substance volume tracking and safe-use scenarios across the supply chain. Sealant manufacturers serving German and French building renovation markets are responding by consolidating supplier bases toward pre-registered MTMS sources with complete exposure dossiers.
Specification-driven procurement is consolidating buyer power among tier-one construction chemical houses and automotive OEMs, displacing spot-market purchasing for standard-grade material. Long-term offtake agreements with volume commitments and technical service attachments are replacing transactional spot contracts in silicone sealant supply chains. This pattern is most visible in China's Yangtze River Delta, where Wacker and Dow maintain dedicated technical service presence at major compounding facilities.
Methyltrimethoxysilane Market Segmentation
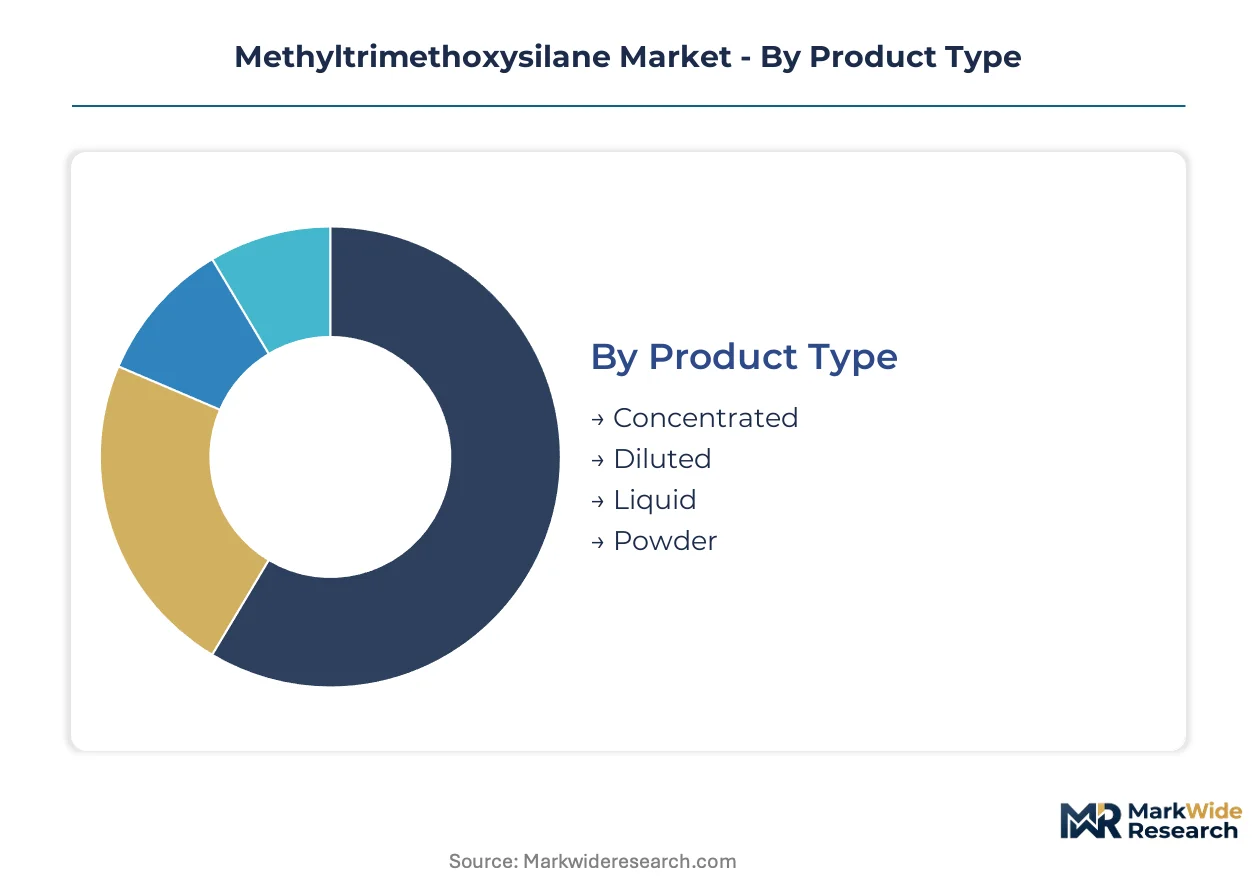
MTMS specifications diverge sharply across end-use requirements, with construction-grade volumes commanding scale economics while electronics-grade purity thresholds capture margin premiums. Formulators select product types and delivery modes based on moisture sensitivity protocols and continuous dosing infrastructure at compounding facilities.
Product Type:
Upgrade cycles in silicone formulation are pushing specification thresholds upward, with moisture-cure system architects demanding tighter chloride specifications and hydrolytic stability windows.
- Liquid:Standard commercial form with specific gravity near 0.95 g/cm³ enables precise metered dosing in continuous adhesive production lines across China's Yangtze River Delta silicone clusters. Construction sealant manufacturers favor this format for compatibility with existing blending infrastructure and minimal handling conversion costs.
- Concentrated:Higher active-content formulations reduce freight expenditure per functional unit and suit moisture-exclusion packaging for electronics-grade applications. Jiangsu province purification facilities are expanding capacity to serve semiconductor encapsulation demand with residual chloride below 50 ppm.
- Diluted:Pre-adjusted concentration for direct-use scenarios in small-batch textile finishing operations eliminates on-site solvent handling.
- Powder:Solid carrier systems for specialized coating applications requiring extended shelf stability and reduced flammability classification in transport.
Volume placements concentrate in Liquid; the faster expansion belongs to Concentrated.
Application:
Cost tier stratification separates specification-grade from commodity positioning, with semiconductor-facing applications commanding 3-5x formulation premiums over construction alternatives.
- Sealants:Primary consumption channel where MTMS serves as crosslinking precursor in moisture-cure silicone systems for structural glazing and expansion joint applications. China's GB 30982 VOC limits are compressing solvent-borne alternatives and redirecting specification demand toward MTMS-based low-solvent formulations.
- Adhesives:Hybrid silicone-urethane systems in automotive OEM assembly lines leverage MTMS for controlled cure kinetics and substrate adhesion promotion. Dow and Wacker maintain technical service presence at major compounding facilities to secure formulation lock-in.
- Coatings:Hydrophobic surface functionalization for inorganic substrates in industrial maintenance and architectural protection.
- Surface Modifiers:Precision treatments for filler dispersion and pigment compatibility in advanced polymer composites.
Sealants retain the largest volume footprint; Adhesives in automotive hybrids are climbing the fastest.
End Use Industry:
Customer type segmentation reveals divergent procurement patterns, with construction chemical houses negotiating long-term offtake agreements while electronics buyers impose 18-24 month qualification timelines.
- Construction:Dominant current consumption base encompassing structural glazing, waterproofing membranes, and concrete protection systems. Eastern coastal provinces in China concentrate demand density where silicone downstream clusters reduce logistics friction for MTMS suppliers.
- Electronics:Fastest-expanding margin pool driven by semiconductor encapsulation requirements for moisture-resistant die-attach and underfill materials. South Korea's MFDS-regulated materials sourcing for OLED manufacturing favors regional purification investments.
- Automotive:OEM assembly line specifications for lightweight bonding and NVH reduction in electric vehicle platforms.
- Textile:Niche applications in fiber surface treatment and water-repellent finishing for technical fabrics.
Construction maintains volume leadership; Electronics shows the steepest expansion trajectory.
Delivery Mode:
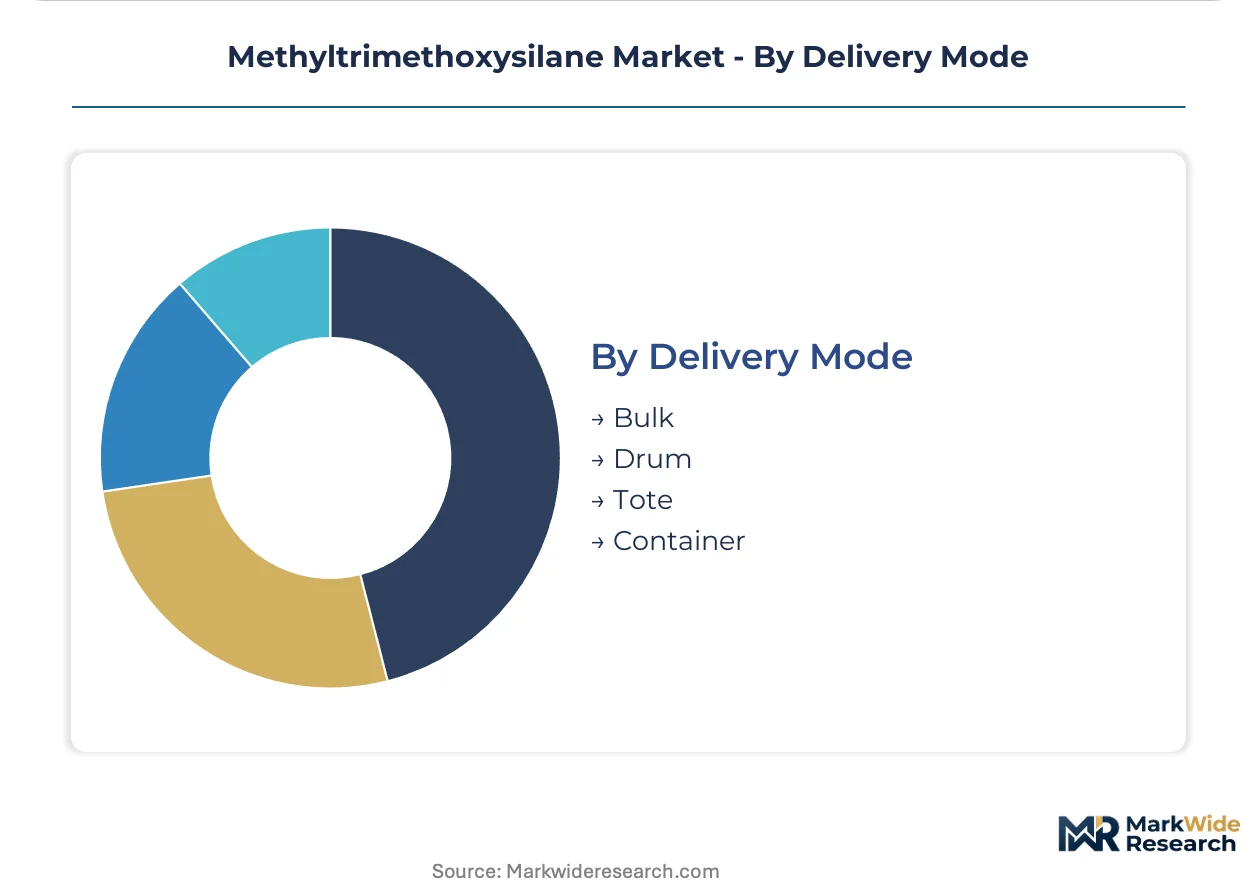
Supply concentration patterns favor bulk infrastructure at integrated producers, while regional distributors capture drum and tote volumes for mid-scale formulators lacking nitrogen-blanketed storage.
- Bulk:Tanker delivery to large-scale silicone compounding facilities minimizes packaging cost and handling steps. Requires dedicated nitrogen-blanketed storage vessels and inert gas distribution networks at recipient sites.
- Drum:Standard 200-liter format for medium-volume formulators with controlled atmosphere warehousing capabilities.
- Tote:Intermediate bulk containers suit regional blending operations with moderate throughput and limited fixed storage investment.
- Container:Small-package formats for R&D sampling, specialty coating operations, and export logistics to distant markets.
Bulk captures the largest tonnage positions; Tote formats are gaining share fastest among regional compounders.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Methyltrichlorosilane availability from chlorosilane manufacturing clusters anchors regional MTMS production economics. China, Germany, Japan, South Korea, and the United States concentrate the bulk of integrated capacity and downstream formulation demand.
China
Construction sealant manufacturers in Jiangsu and Shandong provinces drive industrial-grade consumption volumes. MEE enforcement of GB 30982 VOC limits compels formulators toward low-solvent MTMS systems. The Yangtze River Delta silicone downstream cluster dominates regional procurement, with Wacker and Dow maintaining technical service presence at major compounding facilities.
Germany
Automotive OEM assembly lines for hybrid adhesive systems sustain specification-grade demand from suppliers serving BMW and Volkswagen supply chains. ECHA REACH authorization requirements under Annex XIV tighten downstream notification obligations for construction product formulators. The North Rhine-Westphalia chemical corridor hosts integrated silane production serving both domestic compounding and export markets.
Japan
Semiconductor packaging manufacturers pull higher-purity MTMS grades for moisture-resistant encapsulation materials. METI chemical substance classification under CSCL mandates prior notification for new silane derivatives used in electronics manufacturing. Shizuoka prefecture purification facilities adopt continuous flow reactor technology to meet sub-50 ppm chloride thresholds.
South Korea
OLED display manufacturing for Samsung and LG Electronics generates electronics-grade material demand with stringent purity requirements. MFDS-regulated materials sourcing protocols favor regional MTMS purification investments over import-dependent supply chains. The Seoul Capital Area concentration of display fabs creates localized demand density for certified suppliers.
United States
Construction chemical houses and automotive adhesive formulators sustain steady consumption across moisture-cure silicone applications. EPA TSCA Section 5 scrutiny constrains market entry for unregistered silane variants, elevating compliance costs for specialty grades. The Gulf Coast chlorosilane production corridor feeds downstream MTMS manufacturing serving North American formulation markets.
Methyltrimethoxysilane Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue electronics-grade purification and regional compounding partnerships. The market structure consolidates around integrated chlorosilane-to-silane manufacturers with captive feedstock supply, while specialty distributors capture mid-scale formulator volumes lacking nitrogen-blanketed storage infrastructure. Three archetypes dominate: integrated chemical conglomerates with backward control over methyltrichlorosilane, regional purification specialists serving semiconductor customers, and formulation-technology houses extending technical service reach. Capacity expansion in high-purity grades and strategic partnerships with automotive OEM adhesive suppliers constitute the dominant competitive moves.
Among integrated chemical producers, Shin-Etsu Chemical Co. Ltd. and Wacker Chemie AG exemplify the archetype of captive feedstock integration, while Dow occupies a position bridging formulation science breadth with silane portfolio extension. Evonik Industries AG represents the specialty chemicals vector with purification capabilities targeting electronics-grade specifications. Zhejiang Sucon Silicone Co. Ltd. and Hubei Liding Chemical Co. Ltd. sit within the China-based regional supplier tier serving construction-sector demand clusters.
| Leading Market Players |
|---|
| Evonik Industries AG |
| Shin-Etsu Chemical Co. Ltd. |
| Dow |
| Gelest Inc. |
| Huangshan KBR New Material Technology Co. Ltd. |
| Zhejiang Sucon Silicone Co. Ltd. |
| Hubei Liding Chemical Co. Ltd. |
| United Chemical Technologies |
| Wacker Chemie AG |
| Others |
Value Network & Pricing Analysis
Chlorosilane process engineers concentrated in China's Jiangsu and Shandong provinces create labor-cost differentials that widen pricing spreads between industrial-grade and electronics-grade methyltrimethoxysilane tiers, with purification expertise commanding premium wage multiples that feed directly into margin structures.
Pricing Analysis
Technical service bundling separates contract structures in this market, with long-term offtake agreements incorporating on-site formulation support commanding premiums over unbundled spot transactions. Three-tier pricing structure across electronics-grade, construction-specification, and industrial-commodity levels reflects chloride contamination thresholds and certification documentation depth. Price differentiation hinges on residual purity specifications and REACH dossier completeness for EU-bound shipments. Cost compression in industrial-grade tiers is intensifying because Chinese methyltrichlorosilane spot volatility transmits rapidly into non-integrated producer margins. Construction chemical houses exhibit highest price sensitivity due to volume procurement leverage, while semiconductor encapsulation buyers prioritize qualification stability over unit cost.
Supply Chain Analysis
Hazardous material freight classifications elevate logistics expenditure for drum and tote formats relative to bulk tanker economics, with DOT and ADR protocols constraining last-mile flexibility for smaller formulators. Manufacturing concentrates in China, Germany, and Japan where integrated chlorosilane facilities anchor cost positions. Methyltrichlorosilane feedstock, methanol reagent, and nitrogen blanketing infrastructure constitute critical input dependencies. Single-source vulnerability runs through Jiangsu province purification capacity serving South Korean display manufacturers. Distribution runs through regional compounding facilities with captive nitrogen-blanketed storage, while specialty distributors capture mid-scale formulator volumes lacking infrastructure investment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as producers pursue captive chlorosilane supply to insulate margin stability against feedstock volatility and secure qualification timelines for electronics-grade specifications.
For Market Incumbents: Deploy continuous flow reactor technology to compress the cost gap between industrial and high-purity grades while reducing residual chloride below semiconductor thresholds. Consolidate supplier relationships with Yangtze River Delta silicone compounding clusters to lock in volume commitments against emerging Chinese purification specialists. Secure backward integration into methyltrichlorosilane production or long-term feedstock offtakes to defend margin stability against spot price swings. For New Entrants and Emerging Players: Begin with India construction chemicals where BIS certification requirements for structural sealants create specification-grade entry barriers for established suppliers. Target electronics-grade purification investments serving South Korean OLED manufacturers under MFDS-regulated sourcing protocols, as display fab concentration in the Seoul Capital Area generates localized demand density. Pursue technical service partnerships with automotive OEM adhesive formulators seeking hybrid silicone-urethane system development. For Investors and Strategic Acquirers: Re-rating potential sits with regional purification specialists possessing semiconductor customer qualifications given electronics-grade margin premiums and 18-24 month qualification moats. Long-term viability favors integrated producers with captive chlorosilane supply and established REACH dossiers for EU market access. Monitor methyltrichlorosilane price volatility indices as inflection indicators for margin compression among non-integrated competitors.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chlorosilane Feedstock | Captive methyltrichlorosilane supply insulates margin stability against spot volatility in Chinese manufacturing hubs. |
| Continuous Flow Reactor Deployment | Sub-50 ppm chloride consistency from Jiangsu and Shizuoka facilities meets semiconductor encapsulation qualification thresholds. |
| Long-term Supply Agreement with Construction Chemical Houses | Volume commitments with Wacker and Dow technical service attachments displace spot purchasing in Yangtze River Delta clusters. |
| Electronics-Grade Purification Investment | South Korean MFDS-regulated sourcing for Samsung and LG OLED manufacturing favors regional certification over import dependence. |
| REACH Dossier Completion for EU Access | Pre-registered MTMS sources with full exposure documentation secure German and French building renovation market positions. |
Research Methodology
Multi-period observation of methyltrichlorosilane spot pricing, GB 30982 enforcement patterns, and semiconductor customer qualification timelines anchored the trend analysis, supplemented by interviews with plant managers at integrated silane facilities, procurement leads at downstream silicone sealant manufacturers, distribution channel partners handling nitrogen-blanketed logistics, and technical R&D directors developing hybrid adhesive formulations. Secondary validation drew from customs and trade data, ACC and Cefic chemical industry reports, SEC 10-K filings of listed materials companies, and ECHA REACH registration databases. Bottom-up volume builds across product grades, applications, and delivery modes triangulated against top-down chlorosilane production capacity assessments.
Segment-weighting approaches distributed value and volume projections across liquid, concentrated, diluted, and powder product types; sealant, adhesive, coating, and surface modifier applications; construction, electronics, automotive, and textile end-use industries; and bulk, drum, tote, and container delivery formats. CAGRs were derived from elasticity-adjusted demand modeling incorporating MEE regulatory enforcement trajectories, semiconductor packaging technology roadmaps, and automotive lightweighting content assumptions. Electronics-grade purity thresholds and VOC compliance specifications served as critical forecast inputs shaping grade-mix projections.
Underlying measurement precision varies by segment; electronics-grade volumes carry tighter precision than construction-commodity tiers due to concentrated customer visibility and qualification documentation. Forecasts reflect assumptions regarding MEE enforcement consistency, chlorosilane capacity expansion timing, and semiconductor capital expenditure cycles that could revise projections if regulatory delays or technology substitution accelerates. Stakeholders should weight assumptions against their own operating context and feedstock exposure profiles.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
North America Non-Phthalate Plasticizers Market
Specialty Chemicals
Organometallics Market
Specialty Chemicals
Antifouling Agent Market
Specialty Chemicals
Global Molecular Weight Marker Market
Specialty Chemicals
Preparative Chromatography Market
Specialty Chemicals
Specialty Plasticizer Market
Specialty Chemicals
Explosives and Pyrotechnics Market
Specialty Chemicals
Titanium Fluoride Phosphate Market
Specialty Chemicals
Colloidal Silver Market
Specialty Chemicals
Ethylhexane Diol Market
Specialty Chemicals
Africa Lactic Acid Market
Specialty Chemicals
Global Immersion Oil Market
Specialty Chemicals
Tubatoxin Market
Specialty Chemicals
Free-From Titanium Dioxide Market
Specialty Chemicals
Sodium Hyaluronate Market
Specialty Chemicals
Spiroglycol Market