
 Water Soluble Elastomers Market | 2026-2036
Water Soluble Elastomers Market Size, Share, and Industry Trends Forecast 2026-2036
Water Soluble Elastomers Market Analytics
Buyer concentration among pharmaceutical contract manufacturers is hardening as tier-one drug formulators consolidate supplier lists to secure compliant material streams. BASF SE leverages its integrated polyvinyl alcohol supply chain to serve European pharma customers with certified medical-grade elastomers. Dow anchors North American demand through polyurethane elastomer production tailored to adhesive and coating specifications. LANXESS AG competes on specialty rubber customization for food-contact and cosmetic applications requiring rapid dissolution profiles.
Water soluble elastomers are polymeric materials engineered to degrade or dissolve upon contact with aqueous environments, typically formulated with hydrophilic backbone structures such as polyvinyl alcohol segments or polyurethane blocks containing ether and ester linkages that enable controlled breakdown rates measured in minutes to hours depending on molecular weight and crosslink density. These materials serve industrial and commercial purposes spanning temporary adhesives, edible films, biomedical coatings, and textile sizing agents where complete removal without residue is operationally critical. Polyvinyl alcohol dominates product type volumes due to established film-forming performance and broad regulatory acceptance across pharmaceutical and food packaging applications. Polyurethane captures expanding share in foam production and specialty coatings where tunable elasticity and dissolution kinetics command premium positioning. Gelatin maintains entrenched demand in pharmaceuticals and cosmetics, though animal-origin sourcing constraints are redirecting some formulation work toward synthetic alternatives.
REACH registration requirements in Europe, FDA 21 CFR food-contact substance notifications in the United States, and BIS certification protocols for polymer imports into India collectively elevate compliance costs while filtering out uncertified suppliers from regulated end-use channels. EU MDR medical device regulations further tighten biocompatibility documentation for elastomers deployed in drug-delivery systems and wound-care applications. Stakeholders must monitor evolving purity thresholds and substitution timelines as regulatory bodies in multiple geographies advance restrictions on residual monomer content and additive migration limits.
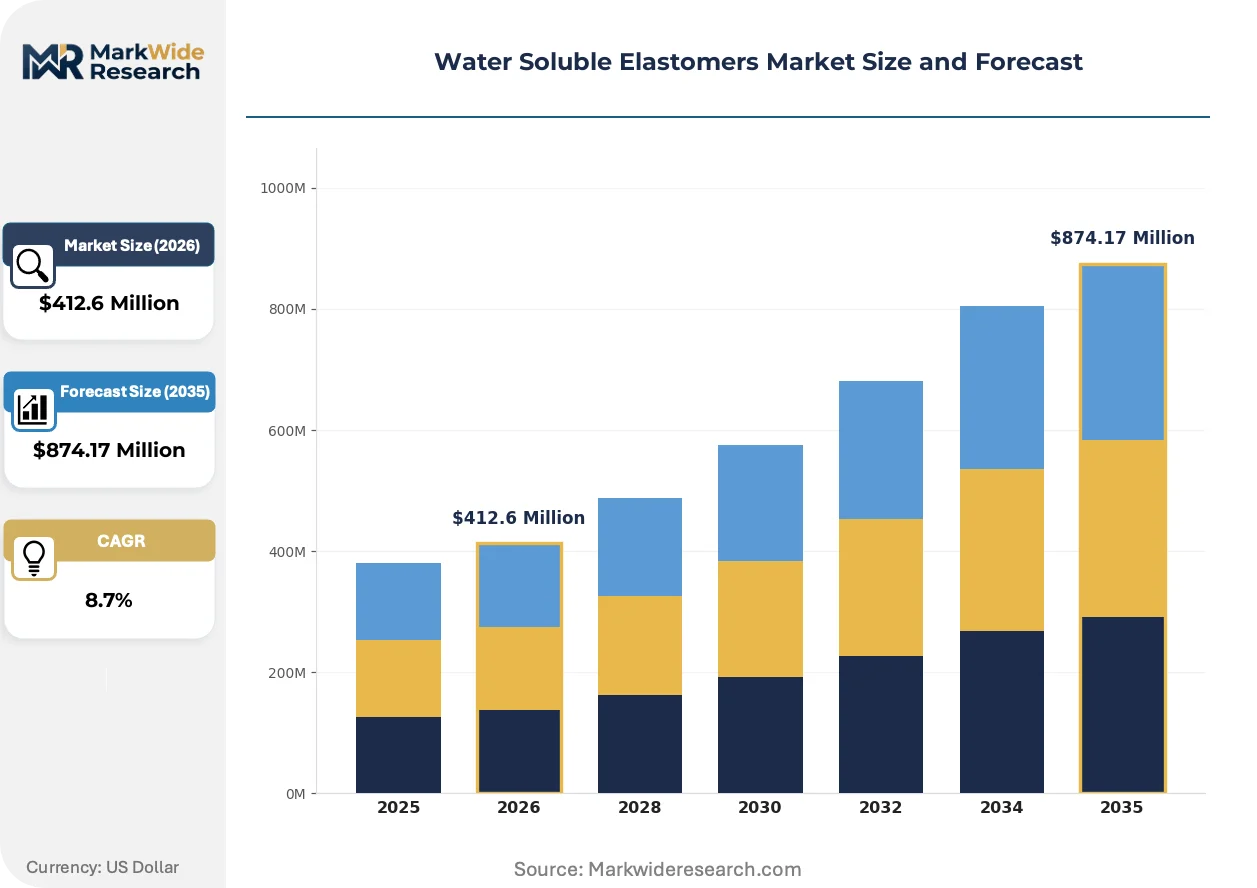
Market Dynamics
Pharmaceutical contract manufacturers are consolidating supplier lists to secure REACH and EU MDR compliant material streams, hardening buyer concentration and filtering uncertified producers from regulated channels. This structural force is reshaping competitive access across controlled-release drug coating applications.
Growth Catalysts
- EU MDR biocompatibility mandates:Medical device regulations tighten documentation requirements for elastomers in drug-delivery systems, pulling certified medical-grade formulations into wound-care and implantable applications.
- Polyurethane block chemistry advances:Tunable ether-ester linkages enable dissolution kinetics measured in minutes to hours, commanding premium positioning in specialty foam production and biomedical coatings.
- Germany's chemical corridor concentration:Manufacturing clusters around Ludwigshafen and Leverkusen concentrate formulation expertise and polymer compounding infrastructure for pharmaceutical-grade supply.
Market Restraints
- Vinyl acetate monomer price volatility:Feedstock cost swings for polyvinyl alcohol production compress margin stability for film-forming grade manufacturers.
- REACH registration burden:European Chemicals Agency documentation requirements elevate compliance costs for residual monomer content thresholds, excluding smaller compounders from regulated end-use channels.
- Animal-origin gelatin substitution pressure:Sourcing constraints on pharmaceutical-grade gelatin redirect formulation work toward synthetic alternatives, disrupting established supply relationships in edible films and capsules.
Strategic Opportunities
- India BIS certification pathway:Polymer import protocols create first-mover advantage for certified suppliers targeting pharmaceutical and food packaging applications in underpenetrated subcontinent markets.
- Cosmetic rapid-dissolution formats:Water-soluble mask substrates and single-use serum pods open formulation partnerships with beauty brands seeking residue-free removal experiences.
- EU Green Deal circularity incentives:Biodegradability mandates in single-use packaging accelerate R&D investment in hydrophilic backbone structures that degrade completely in aqueous environments.
Industry Challenges
- Cross-functional polymer chemist scarcity:Formulation expertise spanning hydrophilic backbone design, crosslink density control, and regulatory documentation remains concentrated among legacy compounders.
- FDA 21 CFR notification timelines:Food-contact substance review cycles extend 18-24 months, delaying market entry for novel polyurethane block compositions in edible film applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Water Soluble Elastomers Market |
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $874.17 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyvinyl Alcohol, Polyurethane, Gelatin, Natural Rubber Application: Adhesives, Coatings, Foam Production, Packaging End User: Pharmaceuticals, Cosmetics, Food Industry, Textile Distribution Channel: Online Retail, Direct Sales, Specialty Stores, Distributors |
| Companies Covered | BASF SE, Dow, DuPont de Nemours, Inc., LANXESS AG, Arkema, Wacker Chemie AG, Huntsman Corporation, Avient Corporation, Covestro AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Water Soluble Elastomers Market Evolving Landscape
Active pharmaceutical ingredient manufacturers are demanding dissolution-profile customization that unifies controlled-release performance with clean-label biodegradability claims. This dual requirement is compressing development cycles and reshaping R&D investment priorities across elastomer compounders.
Block copolymer architecture is unifying elasticity and dissolution control in a single molecular design. Pharmaceutical coaters are adopting these structures at accelerating pace for tablet film coatings requiring precise breakdown in gastric environments. The technology is unifying previously separate formulation steps, reducing processing complexity for contract manufacturers.
REACH authorization timelines for residual vinyl acetate monomer are tightening purity thresholds for polyvinyl alcohol grades entering medical applications. European compounders are responding with upstream distillation investments to meet descending migration limits. Food-contact and pharmaceutical segments face the steepest compliance ramps, with certification-driven supplier selection hardening through 2024-2025 renewal cycles.
Certification-driven procurement now dominates pharmaceutical and medical device channels, with FDA 21 CFR and EU MDR documentation replacing price-primary sourcing criteria. Distributors serving these segments are restructuring technical service teams to support regulatory filing assistance. This behavioral shift is most visible in Germany and Switzerland, where contract manufacturers maintain dual-certified supplier lists to ensure continuity through regulatory transition periods.
Water Soluble Elastomers Market Segmentation
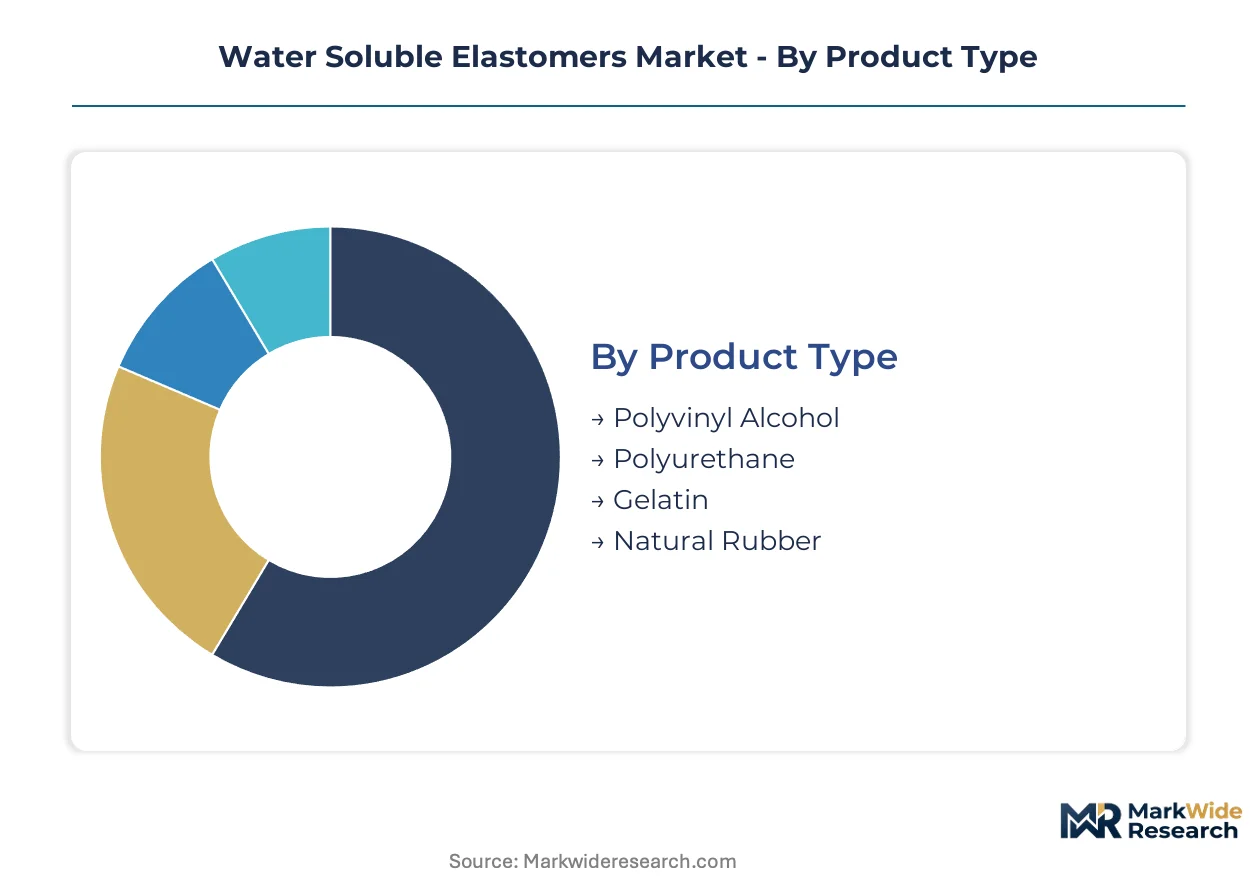
Water soluble elastomers serve divergent performance requirements across pharmaceutical coatings, food-contact films, and temporary industrial adhesives. Segmentation reveals how molecular architecture and dissolution kinetics determine pricing tiers and regulatory certification pathways.
Product Type:
Buyers prioritize hydrophilic backbone structures that balance film-forming performance against regulatory acceptance timelines.
- Polyvinyl Alcohol:Hydrophilic polymer chains with ether linkages enable controlled breakdown rates from minutes to hours. Pharmaceutical coaters in Germany's Ludwigshafen corridor specify medical-grade PVA for tablet film coatings requiring precise gastric dissolution. REACH registration requirements for residual vinyl acetate monomer compress supplier lists to compounders with upstream distillation capabilities.
- Polyurethane:Block copolymer architectures unify tunable elasticity with dissolution kinetics measured across variable timeframes. Biomedical foam producers command premium positioning where ether-ester linkages enable minute-scale breakdown in wound-care applications. FDA 21 CFR notification timelines extend market entry for novel compositions.
- Gelatin:Animal-origin protein structures maintain entrenched demand in edible films and capsule formulations despite sourcing constraints redirecting formulation work toward synthetic alternatives.
- Natural Rubber:Plant-derived latex derivatives serve niche textile sizing applications where complete aqueous removal without residue remains operationally critical.
Polyvinyl Alcohol leads on scale; Polyurethane leads on momentum.
Application:
End-use specifications fragment around dissolution speed requirements and residue tolerance thresholds.
- Adhesives:Temporary bonding formulations for electronics assembly and paper lamination demand clean removal without solvent exposure. German automotive suppliers specify rapid-dissolution grades for fixture positioning during component installation.
- Coatings:Controlled-release pharmaceutical films and biomedical surface treatments require biocompatibility documentation under EU MDR mandates. BASF SE leverages integrated PVA supply chains to serve European pharma customers with certified medical-grade streams.
- Foam Production:Specialty biomedical foams with tunable porosity and breakdown profiles command premium positioning in wound-care and drug-delivery matrices.
- Packaging:Edible and water-dispersible films for single-use food and cosmetic applications face EU Green Deal circularity incentives accelerating biodegradability R&D investment.
Coatings dominate value concentration; Packaging climbs fastest on regulatory tailwinds.
End User:
Procurement patterns diverge between regulated channels demanding certification documentation and industrial buyers prioritizing cost-performance ratios.
- Pharmaceuticals:Contract manufacturers consolidate supplier lists to secure REACH and EU MDR compliant material streams for controlled-release drug coatings. FDA 21 CFR and EMA documentation requirements harden buyer concentration around dual-certified compounders.
- Cosmetics:Water-soluble mask substrates and single-use serum pods open formulation partnerships with beauty brands seeking residue-free removal experiences. Rapid-dissolution formats gain share in premium skincare positioning.
- Food Industry:Edible films and packaging applications face BIS certification protocols in India creating first-mover advantage for certified suppliers targeting underpenetrated subcontinent markets.
- Textile:Sizing agents requiring complete aqueous removal without fabric residue maintain steady industrial demand across yarn processing operations.
Pharmaceuticals anchor revenue concentration; Cosmetics expands most quickly on format innovation.
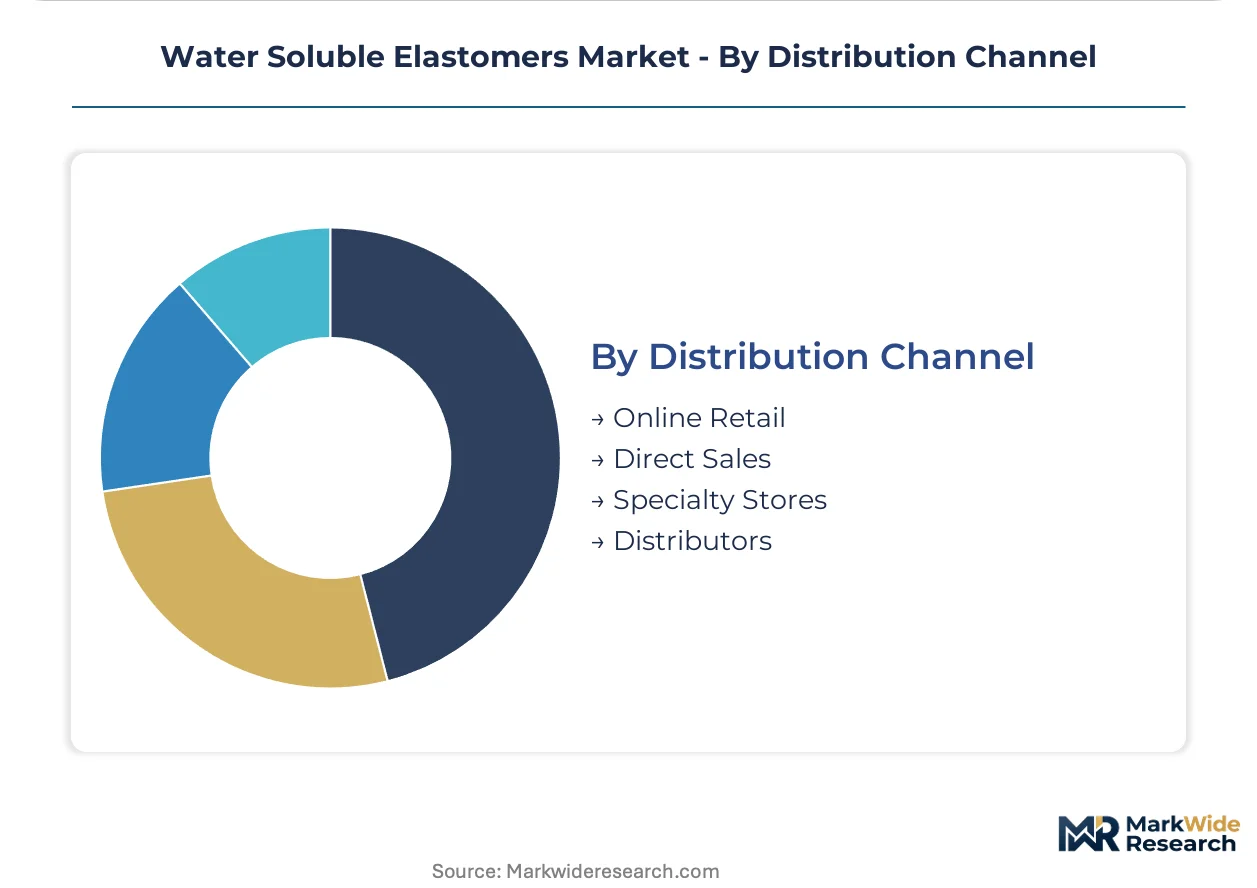
Distribution Channel:
Channel selection tracks buyer scale and technical service requirements for regulatory filing assistance.
- Direct Sales:Pharmaceutical and medical device manufacturers source certified medical-grade elastomers through technical service teams supporting EU MDR and FDA documentation. Distributors restructure capabilities to assist with regulatory filing assistance.
- Distributors:Regional compounders serving food-contact and cosmetic applications rely on distributor networks for formulation sampling and smaller volume fulfillment.
- Online Retail:Research-grade and pilot-scale quantities reach academic and startup formulators through specialized polymer e-commerce platforms.
- Specialty Stores:Niche textile and adhesive applications access technical grades through regional chemical supply houses with formulation expertise.
Direct Sales commands the largest transaction values; Distributors retain broadest segment coverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands pharmaceutical-grade formulation density that the United States matches only in absolute volume, while India builds certification infrastructure to capture redirected sourcing from animal-origin constraints.
Germany
Pharmaceutical contract manufacturers around Ludwigshafen and Leverkusen consolidate supplier lists for REACH-compliant polyvinyl alcohol streams. ECHA registration requirements for residual vinyl acetate monomer filter uncertified compounders from medical-grade channels. BASF SE anchors supply through integrated distillation and polymerization assets serving EU MDR documentation needs.
United States
FDA 21 CFR food-contact substance notifications drive eighteen-to-twenty-four-month review cycles for novel polyurethane block compositions. Dow anchors North American polyurethane elastomer production for adhesive and coating specifications. Greater Houston and Gulf Coast petrochemical corridors concentrate feedstock integration for vinyl acetate monomer supply stability.
India
Bureau of Indian Standards certification protocols for polymer imports create first-mover positioning for suppliers targeting pharmaceutical and food packaging applications. CDSCO documentation requirements for medical-grade materials harden procurement criteria among Mumbai and Ahmedabad formulators. Maharashtra and Gujarat chemical corridors concentrate compounding infrastructure for rapid-dissolution film production.
Switzerland
Swissmedic biocompatibility mandates for drug-delivery systems pull certified medical-grade elastomers into wound-care applications. Dual-certified supplier lists maintained by Basel contract manufacturers ensure continuity through EU MDR transition periods. Rhine corridor formulation expertise concentrates around Novartis and Roche supplier ecosystems.
China
NMPA medical device registration requirements tighten documentation for elastomers in implantable applications. Yangtze River Delta chemical clusters around Shanghai and Ningbo expand polyvinyl alcohol capacity for export-grade pharmaceutical coatings. GB standards for food-contact polymers redirect domestic formulation work toward synthetic gelatin alternatives.
Water Soluble Elastomers Market Competitive Landscape
German producers anchor the premium-tier certification segment; North American specialists hold scale positions in polyurethane block chemistry. Market structure tilts toward consolidated supply among integrated chemical conglomerates with upstream monomer control, while mid-cap compounders compete on specialty rubber customization. Three archetypes dominate: integrated petrochemical majors with captive vinyl acetate supply, specialty polymer houses with regulatory filing capabilities, and regional compounders serving food-contact niche applications. Capacity expansion and backward integration into distillation assets represent the dominant competitive moves as purity thresholds tighten.
Within the integrated major tier, BASF SE and Dow exemplify archetypes built on petrochemical backbone integration and regional market anchoring respectively. LANXESS AG occupies a position representing specialty customization capabilities for rapid-dissolution formats. Covestro AG and Wacker Chemie AG sit within the European-based polymer technology cluster, with Huntsman Corporation and Arkema representing transatlantic diversification patterns. DuPont de Nemours, Inc. and Avient Corporation anchor North American formulation expertise, while the collective positioning of these entities illustrates how certification infrastructure and geographic feedstock access determine competitive access to pharmaceutical and medical device channels.
| Leading Market Players |
|---|
| BASF SE |
| Dow |
| DuPont de Nemours, Inc. |
| LANXESS AG |
| Arkema |
| Wacker Chemie AG |
| Huntsman Corporation |
| Avient Corporation |
| Covestro AG |
| Others |
Value Network & Pricing Analysis
Polymer chemist concentration in Germany's Ludwigshafen-Leverkusen corridor drives labor-cost premiums that widen spreads between medical-grade and industrial-grade pricing tiers. REACH documentation expertise commands salary premiums that compound into certified elastomer pricing, while Asian compounding clusters operate on leaner technical staffing models that compress standard-grade price floors.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for export-grade polyvinyl alcohol, forcing European producers to defend medical-grade premiums through certification differentiation. Three-tier pricing structure across pharmaceutical, food-contact, and industrial grades anchors the market, with EU MDR documentation and FDA 21 CFR notification status as the primary price differentiation drivers. Cost compression in standard-grade film applications is intensifying because of vinyl acetate monomer feedstock volatility. Pharmaceutical contract manufacturers show least price sensitivity due to regulatory compliance requirements, while textile sizing buyers operate on tight cost-performance ratios.
Supply Chain Analysis
Certification gating through REACH registration and FDA 21 CFR notifications filters supplier access to regulated end-use channels, concentrating compliant material flows through audited compounders. Supply concentrates in Germany, the United States, and China, with vinyl acetate monomer, polyurethane prepolymers, and pharmaceutical-grade gelatin as critical input dependencies. Single-source vulnerability runs through European distillation assets for residual monomer control. Distribution runs through direct technical sales for pharmaceutical and medical device channels, with regional distributors serving food-contact and cosmetic sampling needs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where pharmaceutical coaters are consolidating supplier lists around dual-certified compounders capable of supporting EU MDR and FDA documentation simultaneously.
For Market Incumbents: Anchor backward integration into vinyl acetate distillation assets to meet descending REACH purity thresholds for residual monomer content. Deepen regulatory filing assistance capabilities as pharmaceutical buyers replace price-primary sourcing with certification-driven procurement. Defend against synthetic gelatin substitutes by accelerating medical-grade polyvinyl alcohol capacity in Germany's chemical corridor.
For New Entrants and Emerging Players: Specialized polymer e-commerce platforms offer low-friction entry for research-grade and pilot-scale quantities targeting academic formulators and startup compounders. India's BIS certification pathway for pharmaceutical and food packaging applications represents the most penetrable geography, with Mumbai and Ahmedabad formulators seeking alternative suppliers to animal-origin gelatin. Pursue formulation partnerships with cosmetic brands developing rapid-dissolution mask substrates and single-use serum pods.
For Investors and Strategic Acquirers: Specialty chemical conglomerates with pharmaceutical regulatory infrastructure are the most active acquirer in this space, seeking to bolt-on elastomer compounding capabilities that complement existing polymer portfolios. Over the medium-term horizon, vertically integrated compounders with captive vinyl acetate supply and EU MDR certification track records represent the preferred acquisition archetype. Watch for inflection in FDA 21 CFR notification timelines for novel polyurethane block compositions as a signal of competitive access expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Vinyl Acetate Distillation | Captive supply of purified monomer secures REACH-compliant medical-grade PVA production against purity threshold tightening. |
| EU MDR Certification Investment | Biocompatibility documentation capabilities unlock wound-care and implantable drug-delivery applications for polyurethane elastomers. |
| India BIS Certification Pathway | First-mover positioning in underpenetrated pharmaceutical and food packaging markets redirects sourcing from animal-origin constraints. |
| Cosmetic Rapid-Dissolution Format Partnerships | Water-soluble mask substrates and serum pods open premium positioning with beauty brands seeking residue-free removal experiences. |
| Green Manufacturing Transition | EU Green Deal circularity incentives accelerate R&D in hydrophilic backbone structures with complete aqueous biodegradability. |
Research Methodology
Bottom-up pharmaceutical coating demand modeling reconciled against top-down polyurethane and polyvinyl alcohol supply tracking forms the analytical core of this study. Primary interviews with polymer compounding plant managers, pharmaceutical procurement leads, regulatory affairs directors at medical device manufacturers, and cosmetic formulation chemists were validated against secondary sources including ECHA REACH registration databases, FDA 21 CFR food-contact substance notifications, BIS certification records, and customs trade data for vinyl acetate monomer flows.
Input-output matrices mapping elastomer grade tiers to end-use industries, dissolution kinetic specifications, and regional regulatory clusters drive volume and value projections across the modeling period. CAGRs were derived from segment-level growth rate reconciliation against macroeconomic drivers and regulatory timeline assumptions. Forecast inputs include pharmaceutical contract manufacturing expansion rates, EU MDR transition compliance deadlines, and vinyl acetate monomer price volatility indices.
The model assumes a particular technology adoption path for block copolymer architectures in tablet film coatings; alternative pathways for synthetic gelatin substitutes would alter the outlook for animal-origin protein displacement. Forecasts reflect assumptions around REACH authorization timelines and FDA review cycle durations. A model refresh is warranted upon material change in residual vinyl acetate monomer purity thresholds or EU MDR biocompatibility documentation requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Elastomeric Membrane
UV Stabilized Thermoplastic Elastomer Market
Elastomeric Membrane
Perfluoroelastomer (FFKM) Market
Elastomeric Membrane
Specialty Elastomer Market
Elastomeric Membrane
Global Acrylic Elastomers Market
Elastomeric Membrane
Vinyl Terminated Polydimethylsiloxane Market
Elastomeric Membrane
Hot Cast Elastomers Market
Elastomeric Membrane
Global Elastomeric Foam Market
Elastomeric Membrane
Polyisoprene Elastomers Market
Elastomeric Membrane
Thermo Elastic Acrylic Market
Elastomeric Membrane
Middle-East and Africa Fluoroelastomers Market
Elastomeric Membrane
EPDM Waterproofing Membrane Market
Elastomeric Membrane
Stretchable Conductive Material Market
Elastomeric Membrane
Global Flexible Elastomeric Foam Market
Elastomeric Membrane
Styrene Ethylene Butylene Styrene (SEBS) Market
Elastomeric Membrane
Polysulfide Elastomers Market
Elastomeric Membrane
South America Thermoplastic Elastomer (TPE) Market