
 Antifouling Agent Market | 2026-2036
Antifouling Agent Market Size, Share, and Industry Trends Forecast 2026-2036
Antifouling Agent Market Intelligence
Expanded production capacity in China for advanced marine coatings is reshaping competitive positioning in the antifouling agent sector. AkzoNobel leverages its global distribution network to supply shipyards in key hubs like Singapore and Rotterdam. Hempel A/S specializes in high-performance coatings for the shipping industry, while PPG Industries competes through its broad portfolio covering multiple end-user segments. This concentration of manufacturing influences supply chain logistics for vessel operators.
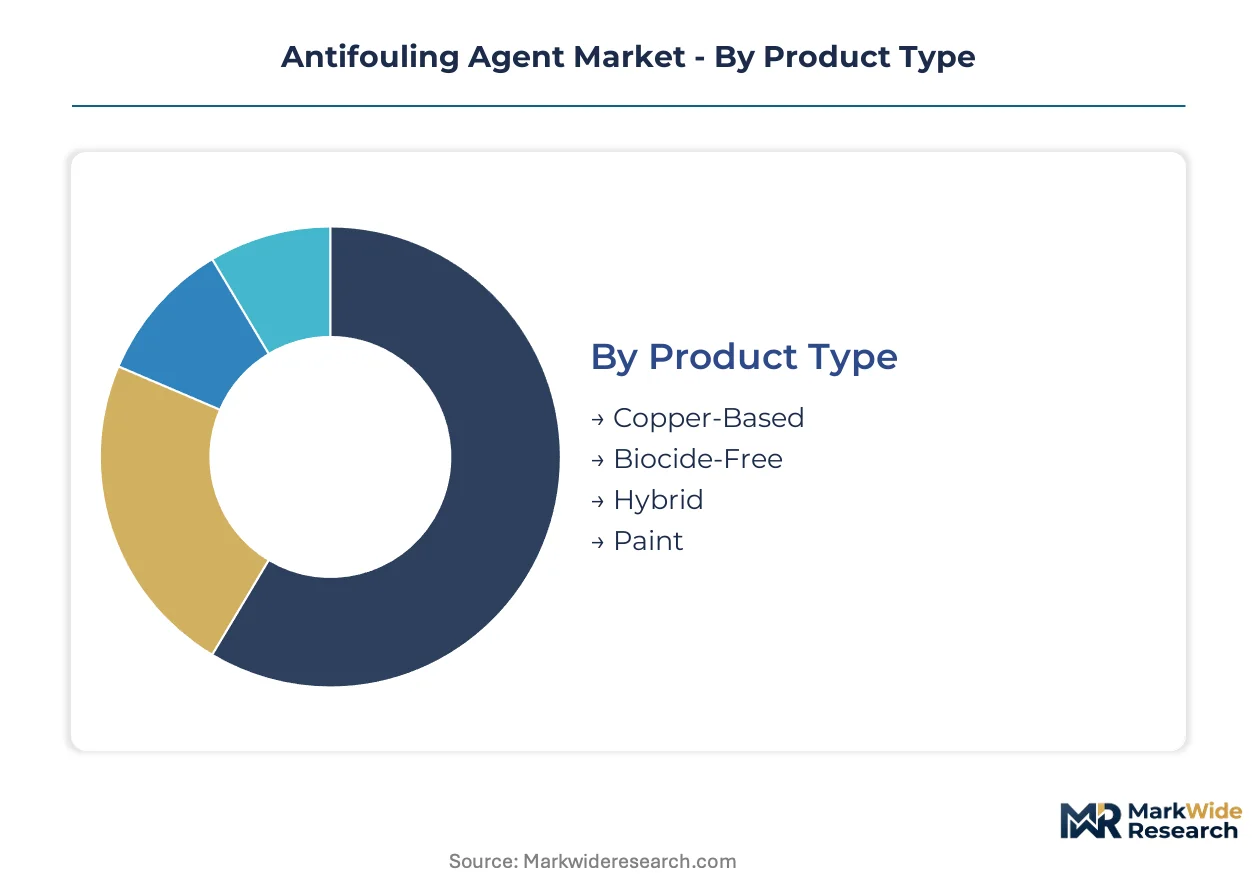
Antifouling agents are specialized coatings applied to submerged surfaces to inhibit the growth of biofouling organisms. These formulations typically incorporate biocides, such as copper compounds, to deter the attachment of barnacles and algae, thereby maintaining hydrodynamic efficiency. Within product types, copper-based formulations continue to lead in volume, but biocide-free alternatives represent the fastest-growing segment due to environmental pressures. The shipping industry remains the dominant end user, with applications focused on boat hulls.
The regulatory landscape is a primary market determinant, governed by bodies like the International Maritime Organization (IMO) and national authorities. The EU's Biocidal Products Regulation (BPR) and the US EPA's registration requirements for pesticides strictly control the types of biocides permitted in formulations. These rules compel manufacturers to invest in R&D for compliant, low-leaching technologies. The industry's path forward depends on balancing biocide efficacy with long-term marine ecosystem health.
Market Dynamics
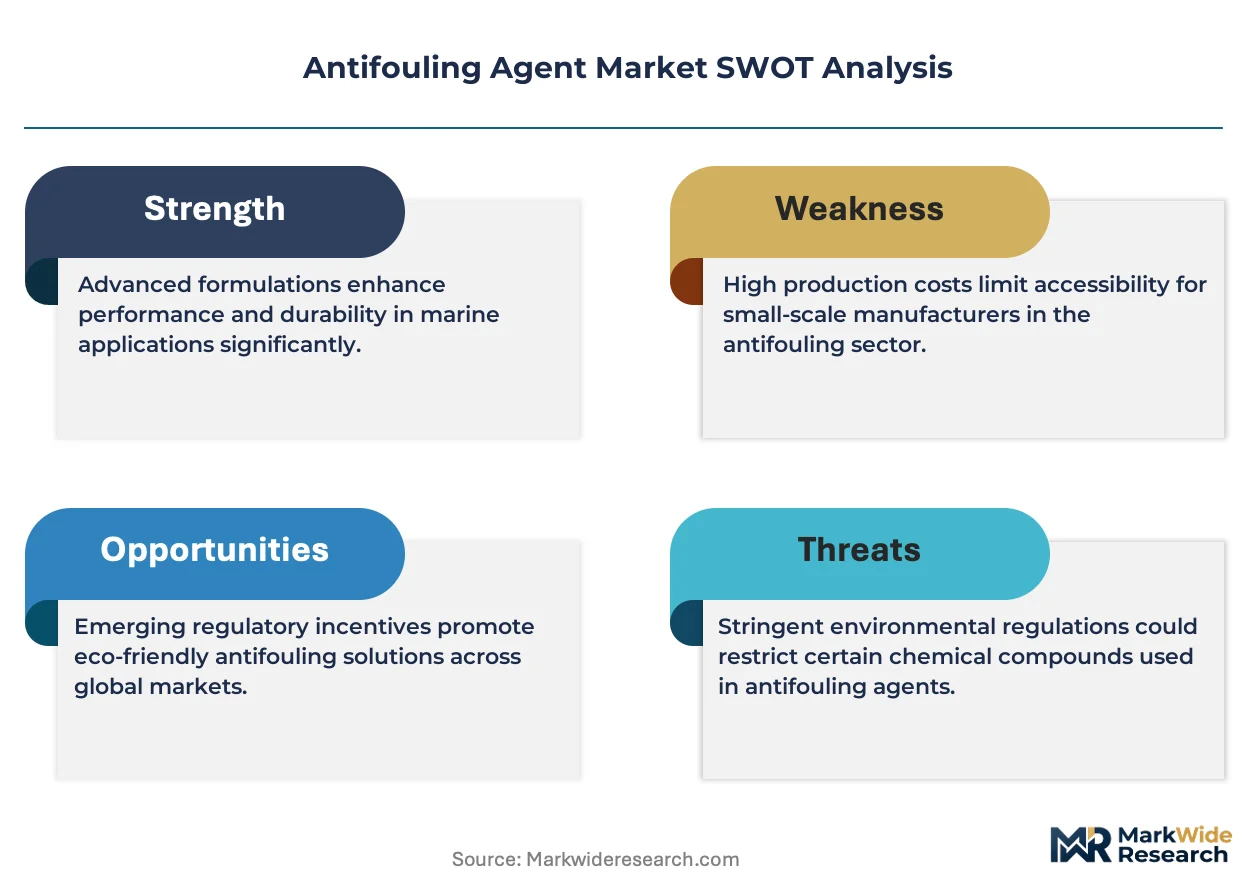
The central dynamic shaping the antifouling agent market is the regulatory mandate to reduce marine ecosystem impact. This pressure forces a technological pivot away from traditional biocides toward compliant, low-leaching, and biocide-free formulations that maintain vessel performance.
Growth Catalysts
- Fuel Efficiency Needs:The shipping industry requires advanced coatings to maintain hydrodynamic efficiency and reduce fuel consumption, a primary operational cost.
- Shipbuilding Concentration:New vessel construction and maintenance demand is geographically focused in countries like China and South Korea, anchoring sales volumes.
- IMO Mandates:International Maritime Organization rules against harmful systems necessitate fleet-wide adoption of compliant coatings, driving retrofits and new applications.
Market Restraints
- Biocide Approval Costs:The EU's Biocidal Products Regulation (BPR) imposes expensive, lengthy approval processes, hindering the launch of new active ingredients.
- Input Cost Volatility:Price fluctuations for raw materials like copper directly impact manufacturer margins and create pricing uncertainty for vessel operators.
- Alternative Performance Gaps:Biocide-free formulations can struggle to match the efficacy of traditional coatings in harsh marine conditions, slowing their adoption.
Strategic Opportunities
- Aquaculture Applications:The expansion of offshore fish farming creates a new market for specialized coatings designed for nets and equipment.
- Foul-Release Technologies:Silicone-based coatings that prevent bio-adhesion, instead of using biocides, represent a high-growth path aligned with environmental regulations.
- Smart Coatings:Integrating sensors into coating layers to monitor fouling enables new data-driven services for optimizing vessel cleaning schedules.
Industry Challenges
- Skilled Applicator Shortage:Proper application of advanced coatings requires specialized training, and a lack of skilled labor in shipyards can lead to premature coating failures.
- Long-Term Performance Validation:Proving the multi-year effectiveness of new biocide-free formulations is a lengthy and expensive process, creating a barrier to market adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Antifouling Agent Market |
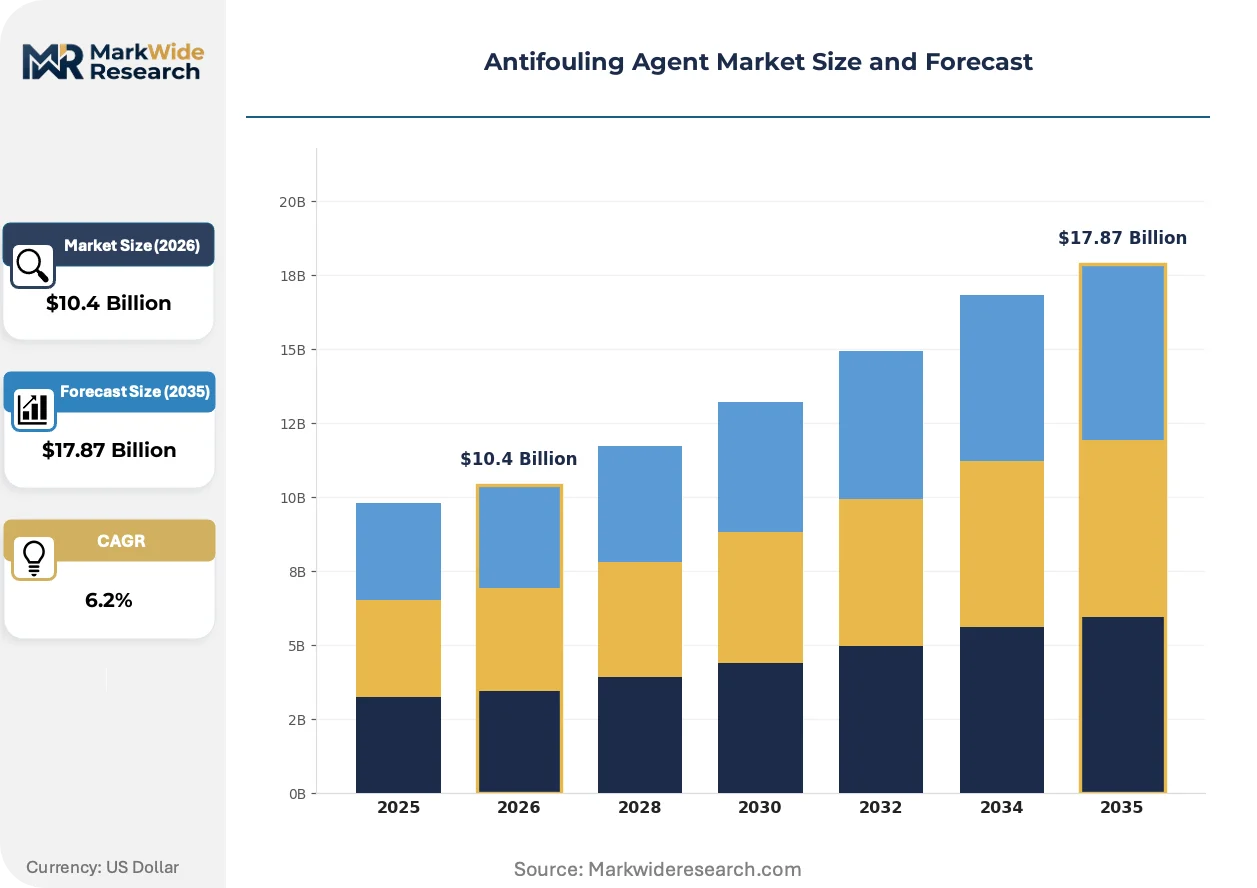
| Market Size in 2026 | $10.4 Billion |
| Market Size in 2035 | $17.87 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Copper-Based, Biocide-Free, Hybrid, Paint End User: Shipping Industry, Aquaculture, Oil & Gas, Marine Equipment Application: Boat Hulls, Offshore Structures, Fish Farms, Subsea Equipment Formulation Type: Water-Based, Solvent-Based, Eco-Friendly, Concentrate |
| Companies Covered | PPG Industries, Nippon Paint Marine Coatings, AkzoNobel, BASF, The Sherwin-Williams Company, Hempel A/S, Chugoku Marine Paints, Kansai Paint, Jotun, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Antifouling Agent Market Strategic Shifts & Innovations
The market's evolution is defined by a fundamental pivot toward sustainable performance. Innovations now focus on balancing ecological compliance, driven by regulators like the IMO, with the shipping industry's unceasing demand for operational efficiency and fuel savings.
Self-polishing copolymers (SPCs) provide a controlled release of biocides through surface erosion. Commercial shipping fleets are adopting advanced SPCs to extend dry-docking intervals and ensure predictable performance. This core technology is hybridizing with biocide-free agents, creating sophisticated systems that combine chemical deterrence with low-friction surfaces for enhanced fuel economy.
Regulation from the US EPA, specifically its Vessel General Permit (VGP) program, strictly governs discharges from commercial vessels. This rule forces ship operators to use coatings with documented low-leaching rates for biocides like copper. Consequently, vessels operating in U.S. waters are a key market for compliant low-leach and advanced biocide-free antifouling systems.
A notable behavioral change is the shift from upfront cost purchasing to a total cost of ownership (TCO) evaluation. This new model challenges the position of basic, shorter-lifespan coatings by factoring in fuel savings and extended service intervals. This trend is most visible among large container lines and LNG carriers where fuel is a dominant operational expense.
Antifouling Agent Market Segmentation
The antifouling agent market segments across various dimensions, reflecting distinct technological approaches, end-user requirements, and application environments. Understanding these divisions helps clarify the diverse performance demands and regulatory pressures shaping product development and adoption across the marine industry.
Product Type:
The use-case spectrum for antifouling agents ranges from traditional biocide-releasing systems to advanced environmentally compliant solutions.
- Copper-Based:These formulations incorporate copper compounds as the primary biocide, effectively deterring a broad range of marine organisms. The shipping industry widely adopts copper-based coatings for their proven efficacy and cost-effectiveness in diverse marine conditions.
- Biocide-Free:These advanced coatings rely on physical properties, such as foul-release technologies, rather than chemical biocides to prevent biofouling. Demand for biocide-free solutions is expanding rapidly due to stringent environmental regulations from bodies like the IMO and the EU's BPR.
- Hybrid:Hybrid products combine elements of biocide-releasing and biocide-free technologies, often featuring a reduced biocide content alongside foul-release properties. These formulations seek to balance performance with environmental compliance.
- Paint:This category broadly refers to conventional paint systems that may or may not include specific antifouling agents, typically used for smaller vessels or less demanding applications.
The dominant share belongs to Copper-Based formulations, while Biocide-Free solutions are closing the gap fastest.
End User:
The operational scale and specific environmental challenges faced by different marine industries dictate their antifouling agent needs.
- Shipping Industry:This segment encompasses commercial vessels, including cargo ships, tankers, and cruise liners, which require coatings to maintain hydrodynamic efficiency and reduce fuel consumption. Large shipping companies prioritize long-term performance and extended dry-docking intervals.
- Aquaculture:This sector involves offshore fish farming and requires specialized coatings for nets, cages, and submerged structures to prevent biofouling interference with water flow and fish health. Growth in offshore aquaculture creates new demand for non-toxic solutions.
- Oil & Gas:Offshore platforms, rigs, and subsea infrastructure in the oil and gas industry need robust antifouling protection for structural integrity and operational efficiency. Prolonged immersion in harsh conditions demands highly durable coatings.
- Marine Equipment:This category includes various submerged equipment, buoys, and sensors that require protection from biofouling to ensure accurate functioning and extended service life.
Demand is primarily driven by the Shipping Industry, with Aquaculture showing significant expansion.
Application:
The specific surface exposure and functional requirements of marine assets determine the optimal antifouling application strategy.
- Boat Hulls:This is the primary application area for antifouling agents, critical for maintaining vessel speed, fuel efficiency, and reducing maintenance costs. Hull coatings are designed for dynamic water flow conditions.
- Offshore Structures:Fixed and floating platforms, wind turbine foundations, and other large marine structures require long-lasting antifouling protection to prevent structural degradation and biofouling accumulation. These applications demand high durability.
- Fish Farms:Coatings for aquaculture nets and cages prevent the growth of marine organisms that can restrict water flow, reduce oxygen levels, and impact fish health. Non-toxic formulations are essential here.
- Subsea Equipment:Various underwater sensors, remotely operated vehicles (ROVs), and other specialized subsea machinery rely on antifouling coatings for uninterrupted operation.
Major volume concentrates in Boat Hulls applications, as Offshore Structures presents specialized requirements.
Formulation Type:
Environmental compliance and application characteristics heavily influence the selection of antifouling formulation types.
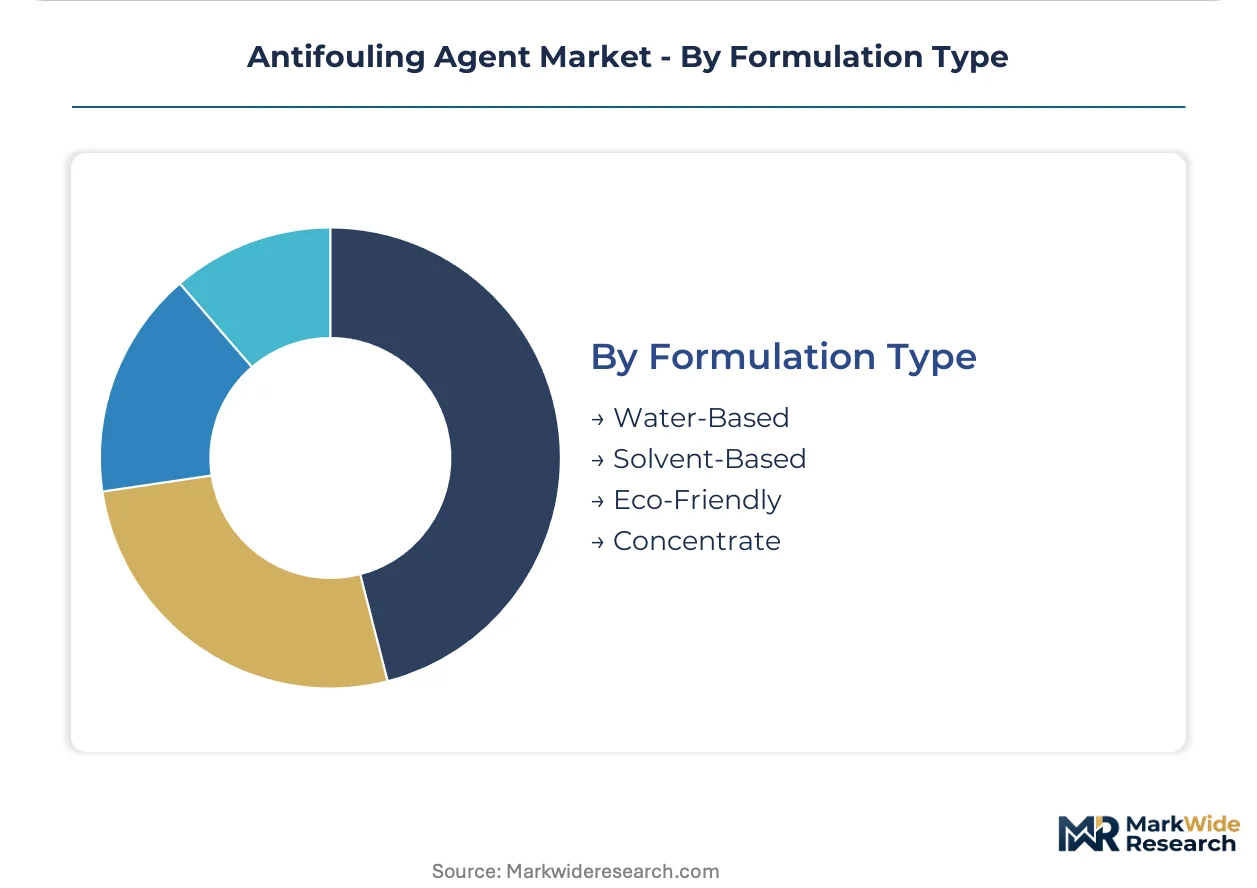
- Water-Based:These formulations use water as the primary solvent, reducing volatile organic compound (VOC) emissions and aligning with stricter environmental regulations. Shipyards increasingly adopt water-based systems for improved worker safety and reduced environmental impact.
- Solvent-Based:Traditional solvent-based formulations offer robust performance and drying characteristics, though they typically have higher VOC content. These products maintain a presence in regions with less stringent emission controls.
- Eco-Friendly:This segment includes biocide-free and low-VOC formulations designed to minimize environmental impact while providing effective biofouling prevention. Regulatory bodies like the US EPA encourage the adoption of eco-friendly options.
- Concentrate:Concentrated antifouling agents require dilution before application, offering potential benefits in terms of storage and transportation efficiency.
The shift toward Eco-Friendly formulations reflects evolving environmental standards, while Solvent-Based options maintain a traditional presence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supply-side concentration for antifouling agents is evident in key shipbuilding nations, influencing global distribution and market dynamics. Major manufacturing capabilities in Asia drive product availability worldwide. This geographic focus impacts supply chain logistics for vessel operators.
China
China's shipbuilding dominance fuels substantial demand for antifouling agents, particularly for new vessel construction. The country's dual carbon goals encourage adoption of more environmentally compliant coatings. Manufacturing hubs in the Yangtze River Delta actively produce advanced marine coatings.
South Korea
South Korea's robust shipbuilding industry requires high-performance antifouling systems for its diverse fleet. The national maritime authorities emphasize fuel efficiency standards for commercial vessels. Shipyards in Busan and Ulsan integrate advanced coatings into new builds.
United States
The United States maritime sector demands compliant antifouling solutions for its extensive commercial and recreational fleets. The US EPA's Vessel General Permit program strictly regulates biocide discharges. Ports along the Gulf Coast and East Coast are key service points for coating applications.
Netherlands
The Netherlands, with its major port infrastructure, serves as a critical distribution hub for antifouling products in Europe. The EU's Biocidal Products Regulation (BPR) drives demand for low-leaching and biocide-free formulations. Rotterdam's extensive port facilities support significant coating maintenance activities.
Singapore
Singapore's strategic position as a global shipping hub generates consistent demand for antifouling agents for vessel maintenance. The Maritime and Port Authority of Singapore promotes sustainable maritime practices. Ship repair yards in Tuas and Jurong provide extensive coating application services.
Antifouling Agent Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in the antifouling agent market. The market exhibits a tiered structure, with global coating manufacturers alongside niche technology providers. Strategic archetypes include diversified chemical giants and specialized marine coating companies. Portfolio diversification and technology licensing are dominant competitive moves.
AkzoNobel, a Netherlands-based chemical company, occupies a position as a major global supplier, leveraging its extensive distribution network for marine coatings. Hempel A/S, a Denmark-based specialist, exemplifies high-performance marine coatings tailored for the demanding shipping industry. PPG Industries, a US-based diversified manufacturer, represents a broad portfolio spanning multiple end-user segments, including marine applications. These companies anchor significant market share through established brand recognition and continuous product innovation. Their operations often involve substantial R&D investment to meet evolving regulatory requirements and performance expectations. Such players frequently engage in strategic partnerships to expand their technological capabilities or geographic reach, influencing the overall market trajectory.
| Leading Market Players |
|---|
| PPG Industries |
| Nippon Paint Marine Coatings |
| AkzoNobel |
| BASF |
| The Sherwin-Williams Company |
| Hempel A/S |
| Chugoku Marine Paints |
| Kansai Paint |
| Jotun |
| Others |
Cost & Logistics Intelligence
The Yangtze River Delta's expanded production capacity for advanced marine coatings influences downstream pricing power for antifouling agents. This concentration of manufacturing capabilities allows key players to dictate terms for large-volume contracts, particularly for new vessel construction.
Pricing Analysis
The EU's Biocidal Products Regulation (BPR) dictates the pricing tier structure for antifouling agents. Pricing stratifies across premium, standard, and economy tiers, reflecting performance efficacy and environmental compliance. Price differentiation stems from the biocide content and foul-release properties, alongside brand premium for established manufacturers. Pricing pressure stems from input cost volatility for raw materials like copper, impacting manufacturer margins. Commercial shipping lines evaluating total cost of ownership are less price-sensitive than recreational vessel owners.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities are common in the antifouling agent market, reflecting the long project cycles in shipbuilding. Geographic supply concentrates in China, South Korea, and the Netherlands, which serve as manufacturing and distribution hubs. The supply chain draws from critical raw materials such as copper compounds and specialized polymers for foul-release coatings. Commodity price volatility for key inputs represents a structural supply chain risk. Distribution runs through established global networks and direct sales channels to major shipyards, alongside specialized distributors for smaller vessel operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits as a cyclical recovery play, driven by renewed shipbuilding activity and the shipping industry's need to modernize fleets for fuel efficiency.
For Market Incumbents:
Harden core market positions by accelerating investment in biocide-free and low-leaching formulations to comply with evolving regulations like the US EPA's VGP program. Secure long-term supply agreements for critical raw materials to mitigate input cost volatility. Develop specialized application training programs for shipyard personnel to counter the skilled applicator shortage, ensuring product performance and customer satisfaction. Expand digital service offerings for smart coatings to provide data-driven maintenance insights, differentiating against traditional offerings.
For New Entrants and Emerging Players:
The aquaculture sector presents a geographic underpenetration opportunity for specialized, non-toxic antifouling solutions. Target niche applications such as offshore fish farming equipment and subsea sensors with high-performance, environmentally benign coatings. A strong go-to-market angle involves collaborating directly with aquaculture operators to validate long-term efficacy and build trust in novel biocide-free technologies. Focus on certifications that demonstrate ecological safety and compliance with local environmental standards for these specialized markets.
For Investors and Strategic Acquirers:
Long-term, this sits as a sustainability-driven innovation play because environmental compliance mandates continuous R&D and product evolution. Seek acquisition targets that possess proprietary foul-release technologies or advanced biocide-free formulations with proven performance records. Companies with strong intellectual property in smart coating integration or specialized application services represent attractive archetypes. The accelerated adoption rates of biocide-free formulations in commercial shipping is a key signal to watch for inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Asia | This strengthens supply chain resilience and meets demand from major shipbuilding nations. |
| Invest in Biocide-Free R&D | This ensures compliance with stricter environmental regulations and captures high-growth segments. |
| Secure Raw Material Supply Agreements | This mitigates price volatility for critical inputs like copper and specialized polymers. |
| Develop Skilled Applicator Training | This improves application quality, extends coating lifespan, and reduces premature failures. |
| Strategic Partnerships for Smart Coatings | This integrates sensor technology for data-driven maintenance and optimized vessel operations. |
Research Approach
Initial hypotheses were tested against primary input from marine coating R&D directors, shipyard procurement managers, vessel fleet operators, and regulatory compliance officers, and refined through iterative analysis. This involved combining in-depth interviews with industry stakeholders with extensive secondary validation from IMO reports, EU BPR guidelines, US EPA VGP documents, and maritime industry publications. The analysis employed both bottom-up and top-down triangulation to ensure comprehensive market sizing and forecasting.
Demand-supply balance modeling formed the core analytical framework for projecting market trajectories across the analysis window. The model integrated historical trends and future projections, segmenting the market by product type, end-user, application, formulation type, and regional regulatory adherence. Compound annual growth rates were derived through regression analysis and expert consensus, incorporating industry-specific forecast inputs such as new shipbuilding orders and global shipping fleet size.
The forecast holds incumbent behavior within observed patterns; aggressive moves by disruptive technology startups or large chemical conglomerates entering the market would shift outcomes. Forecasts reflect assumptions regarding technological advancements and regulatory enforcement. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Fe EDDHA Market
Specialty Chemicals
Synthetic and Bio-Based Adipic Acid Market
Specialty Chemicals
Europe Non-Phthalate Plasticizers Market
Specialty Chemicals
Protein Purification Resin Market
Specialty Chemicals
L-Ergothioneine Market
Specialty Chemicals
Alkylene Carbonates Market
Specialty Chemicals
Textile Flame Retardants Market
Specialty Chemicals
Global Anti-Static Agents Market
Specialty Chemicals
Barium Derivatives Market
Specialty Chemicals
Releasing Agents Market
Specialty Chemicals
Preparative and Process Chromatography Market
Specialty Chemicals
Sulfonated Melamine Formaldehyde Market
Specialty Chemicals
Sol-Gel Processing Market
Specialty Chemicals
Polyether Modified Silicone Market
Specialty Chemicals
Fluorinated Plasma Surface Treatment Market
Specialty Chemicals
Bromocyclopentane Market