
 Europe Aerosol Cans Market | 2026-2036
Europe Aerosol Cans Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Aerosol Cans Market Foresight
Personal care demand is decoupling from traditional single-use formats as brands pursue refillable and concentrated delivery systems. Ball Corporation leverages its European aluminum rolling network to supply lightweight can bodies across cosmetics and pharmaceutical aerosols. Crown Holdings anchors production through integrated metal decorating facilities in Spain and Italy. Trivium Packaging differentiates via steel-to-aluminum conversion programs targeting household product lines.
Aerosol cans are sealed, pressurized metal or glass containers that store and dispense products as fine sprays, foams, or mists through a valve-and-actuator system; aluminum variants typically employ 3104-H19 alloy with wall thicknesses of 0.28–0.32 mm to withstand internal pressures of 8–15 bar while enabling thin-walled, lightweight construction. These containers serve primary functions in controlled product dispensing, shelf-life extension, and user convenience across consumer and industrial applications. Aluminum dominates type-based segmentation due to its infinite recyclability and established European collection infrastructure, while steel retains cost advantages in industrial lubricant and paint applications where corrosion resistance and puncture tolerance outweigh weight considerations. Personal care leads application segmentation through deodorant, hair care, and sun care volumes, though food and beverage aerosols for whipped cream and cooking sprays represent a faster-growing niche with specialized interior coating requirements.
REACH regulates chemical composition of propellants and interior coatings, while the EU Green Deal mandates recycled content thresholds that reshape raw material sourcing decisions for can makers. CE marking and F-Gas Regulation constrain hydrofluorocarbon propellant use, pushing formulation shifts toward compressed air and nitrogen alternatives. Stakeholders must monitor evolving Extended Producer Responsibility schemes and packaging waste directives that will determine compliance costs and material specifications across European manufacturing footprints.
Market Dynamics
REACH compliance and the EU Green Deal are compressing formulation timelines while mandating recycled aluminum thresholds, forcing can makers to requalify supply chains and propellant chemistries simultaneously.
Growth Catalysts
- Refillable format adoption:Personal care brands across Germany and France are piloting reusable aerosol systems that cut per-use aluminum intensity. This shift aligns with Extended Producer Responsibility schemes tightening across the EU.
- Compressed air propellants:The F-Gas Regulation is accelerating nitrogen and compressed air alternatives to hydrofluorocarbons. Household cleaning manufacturers are reformulating product lines to meet 2025 phase-down milestones.
- Recycled aluminum infrastructure:European collection and sorting systems for 3104-H19 alloy scrap now achieve closed-loop recovery rates above 70 percent in key member states.
Market Restraints
- Aluminum ingot price volatility:Primary aluminum smelting energy costs in Europe fluctuate with natural gas benchmarks, compressing can body margins unpredictably.
- Interior coating qualification delays:New epoxy-phenolic formulations required for food-contact aerosols face 18-24 month EFSA approval timelines.
- Steel cost advantages in industrial segments:Lubricant and paint applications retain tinplate preference where puncture resistance outweighs lightweighting benefits.
Strategic Opportunities
- Food and beverage aerosol expansion:Whipped cream and cooking spray applications in Southern Europe present faster growth than saturated personal care channels.
- Steel-to-aluminum conversion programs:Household product lines currently on tinplate can migrate to recycled aluminum as EPR fees widen the cost gap.
- CSRD-aligned sustainability reporting:Corporate sustainability reporting mandates create procurement preference for can suppliers with verified Scope 3 emissions data.
Industry Challenges
- Propellant chemist talent scarcity:Formulation expertise in low-GAS and compressed gas systems concentrates among retiring specialists in Germany and the Netherlands.
- Legacy decorating line retrofit costs:Metal printing equipment for high-definition graphics on thin-walled aluminum requires capital outlays that mid-tier converters struggle to justify.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Aerosol Cans Market |
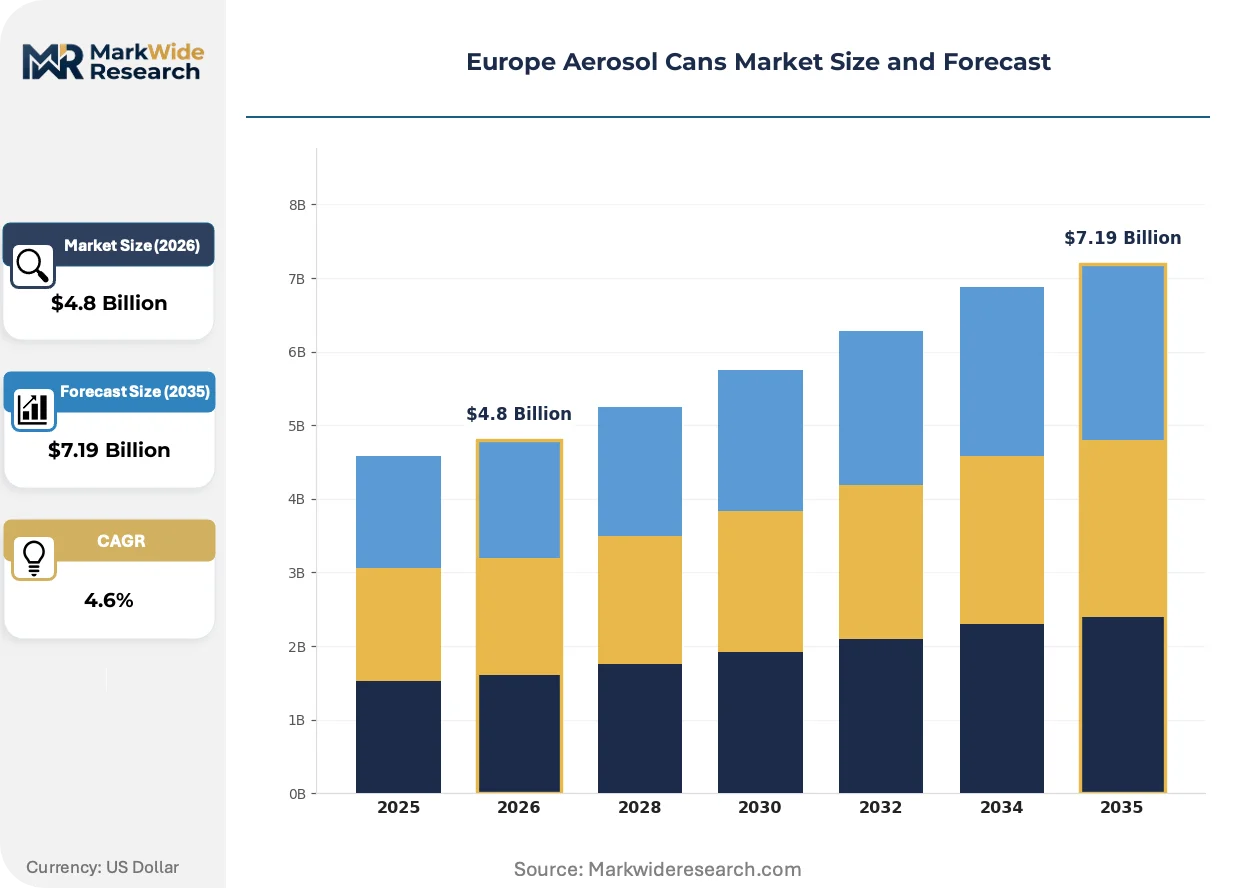
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
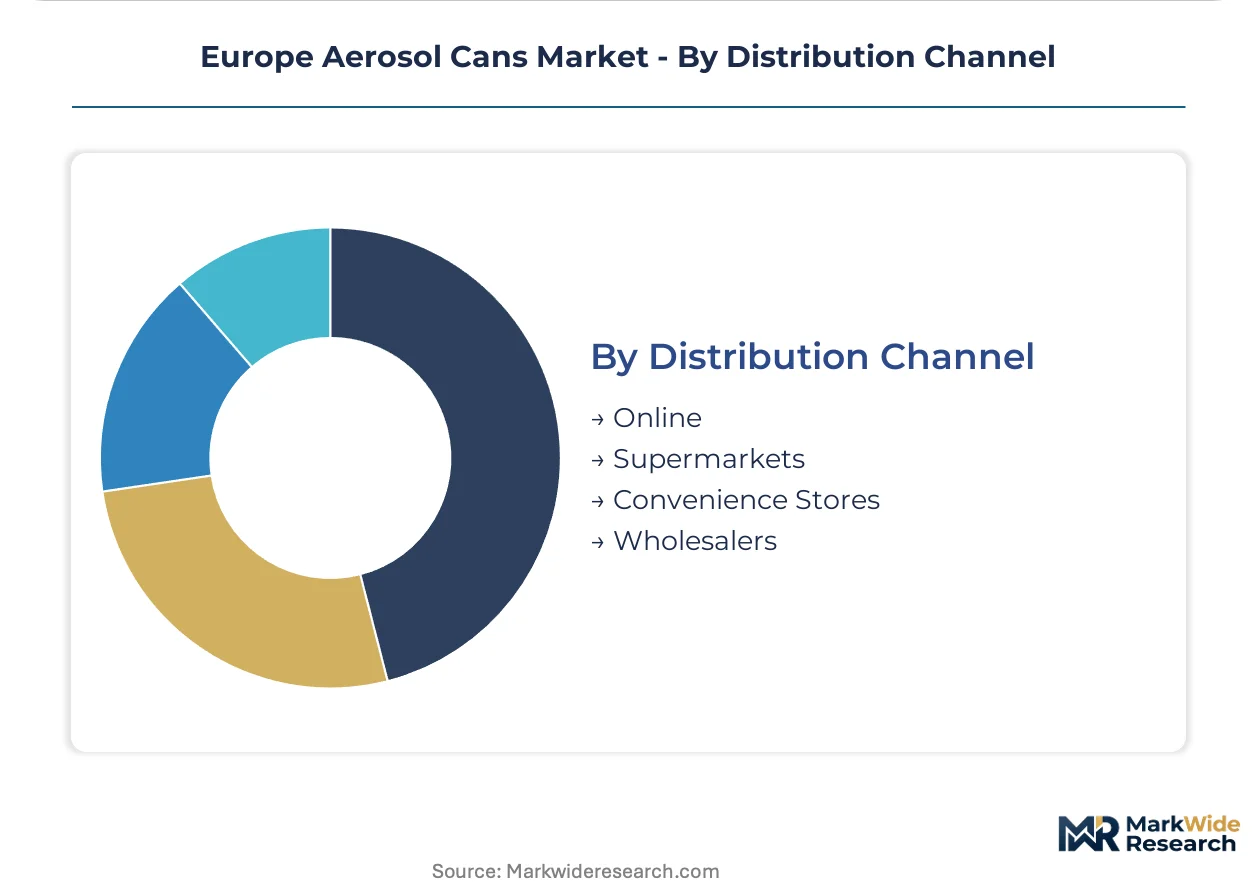
| Segmentation | Type: Aluminum, Steel, Glass, Plastic Application: Personal Care, Household, Food & Beverage, Industrial End User: Manufacturers, Retailers, Distributors, Consumers Distribution Channel: Online, Supermarkets, Convenience Stores, Wholesalers |
| Companies Covered | Ball Corporation, Crown Holdings, Trivium Packaging, Ardagh Group, CCL Industries, Can-Pack SA, Nampak Ltd, Toyo Seikan Group Holdings, COLEP Packaging, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Aerosol Cans Market Shifts & Advancements
Reformulation chemistry and lightweight alloy processing are converging to redefine acceptable performance thresholds across European aerosol manufacturing.
Necked-in aluminum can designs with reduced wall thickness are rewriting material efficiency benchmarks. Personal care brands in France and Germany are qualifying 0.28 mm gauge bodies for deodorant volumes up to 150 ml. This specification compression is enabling 12-15 percent aluminum weight reduction without sacrificing 15 bar pressure tolerance.
REACH Annex XVII restrictions on volatile organic compounds are tightening propellant portfolios. Aerosol manufacturers must substitute hydrocarbon blends with dimethyl ether or compressed gas systems in household cleaning segments. German formulators are advancing nitrogen-based systems for glass cleaner applications ahead of 2026 enforcement windows.
Retailers are consolidating supplier bases to simplify Scope 3 emissions tracking. Discounters in Spain and Italy now require batch-level carbon footprint documentation from can providers. This documentation burden favors converters with integrated aluminum rolling and in-house life cycle assessment capabilities.
Europe Aerosol Cans Market Segmentation
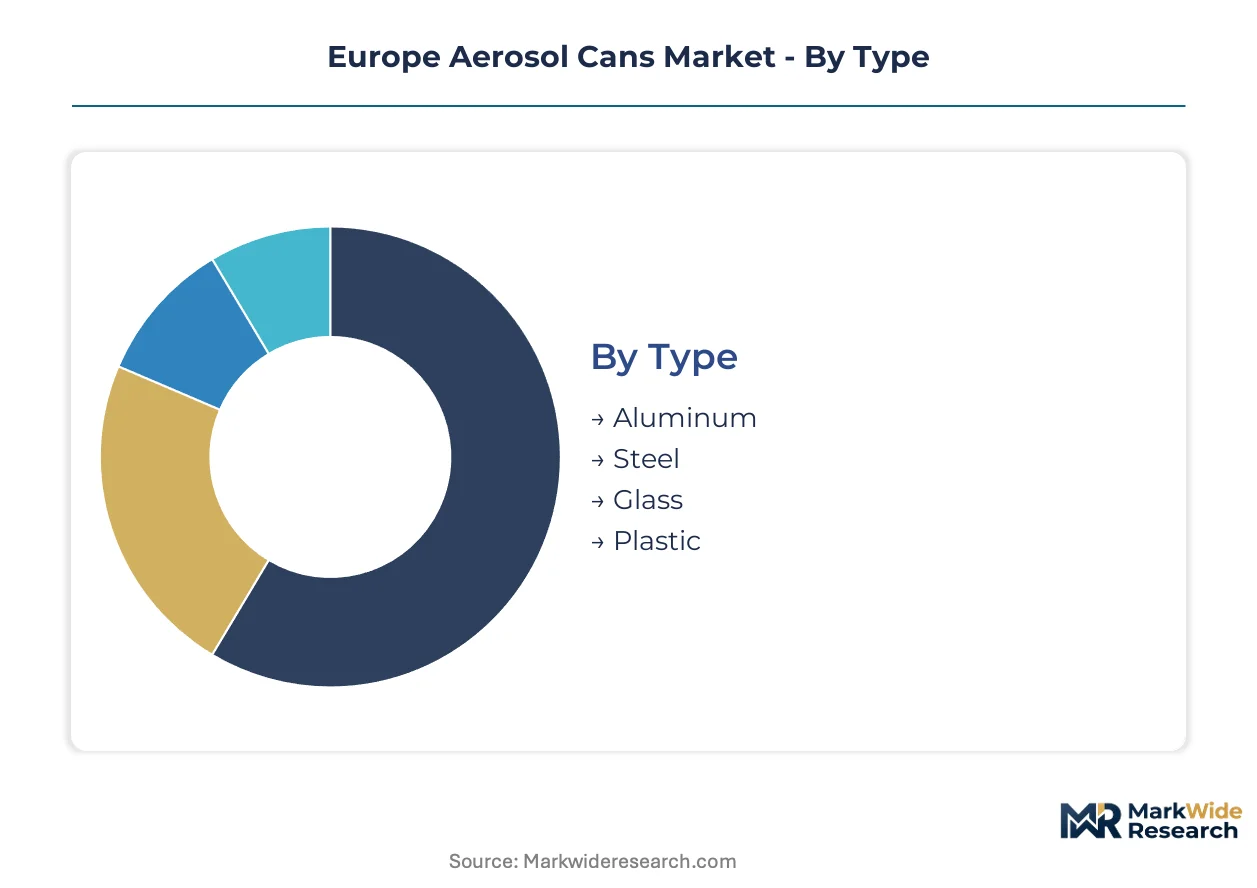
Segmentation in the Europe Aerosol Cans Market reveals how material specifications, regulatory compliance, and channel economics fragment procurement decisions across the value chain. Manufacturers must align production configurations with distinct performance thresholds and sustainability mandates governing each category.
Type:
Customization versus standardization tensions run deepest in material selection, where infinite recyclability competes with puncture tolerance and corrosion resistance for specification dominance.
- Aluminum:3104-H19 alloy construction with wall thicknesses of 0.28–0.32 mm withstands internal pressures of 8–15 bar while enabling thin-walled lightweight design. Demand concentrates in German and French personal care markets where REACH compliance and EU Green Deal recycled content thresholds favor closed-loop recovery infrastructure achieving above 70 percent scrap reprocessing rates in key member states.
- Steel:Tinplate variants retain cost advantages in industrial lubricant and paint applications where puncture resistance and corrosion tolerance outweigh lightweighting benefits. Italian and Spanish manufacturers anchor production through integrated metal decorating facilities serving household cleaning segments with lower pressure tolerance requirements.
- Glass:Specialized interior coating compatibility for pharmaceutical and cosmetic aerosols where chemical inertness takes priority over weight efficiency.
- Plastic:Emerging formats for non-pressurized or low-pressure dispensing systems in niche personal care applications.
Leading the category by volume: Aluminum. Growing fastest: Steel-to-aluminum conversion programs in household product lines.
Application:
Volume concentration tracks end-use maturity, with saturated channels funding innovation investments in faster-expanding niches requiring specialized barrier technologies.
- Personal Care:Deodorant, hair care, and sun care volumes dominate current throughput across European filling lines. German and French brands are piloting refillable aerosol systems that cut per-use aluminum intensity while navigating Extended Producer Responsibility scheme tightening.
- Food & Beverage:Whipped cream and cooking spray applications in Southern Europe present specialized interior coating requirements and faster expansion than saturated personal care channels. EFSA approval timelines of 18-24 months for new epoxy-phenolic formulations constrain rapid scaling.
- Household:Cleaning product manufacturers are reformulating to nitrogen and compressed air propellants ahead of F-Gas Regulation phase-down milestones.
- Industrial:Lubricant and paint applications retain preference for steel construction where puncture resistance governs specification decisions.
Personal Care commands the largest share by unit volume. Food & Beverage demonstrates the steepest expansion trajectory driven by Southern European consumption patterns.
End User:
Procurement authority concentrates differently across the value chain, with formulation ownership separating from packaging specification control.
- Manufacturers:Brand owners and contract fillers who specify can geometry, alloy grade, and interior coating chemistry. Discounters in Spain and Italy now require batch-level carbon footprint documentation, favoring converters with integrated aluminum rolling and in-house life cycle assessment capabilities.
- Retailers:Consolidating supplier bases to simplify Scope 3 emissions tracking and reduce compliance documentation burden.
- Distributors:Intermediate stockholding points serving fragmented regional demand with limited specification influence.
- Consumers:End purchasers whose sustainability preferences transmit through retailer procurement criteria rather than direct channel relationships.
Manufacturers retain the greatest specification authority. Retailers are gaining procurement leverage fastest through consolidated supplier base requirements.
Distribution Channel:
Channel economics determine packaging format flexibility, with velocity and shelf-space constraints shaping minimum order quantities and decoration complexity.
- Supermarkets:High-velocity personal care and household segments requiring standardized SKUs and high-definition graphics capability. Legacy decorating line retrofit costs for thin-walled aluminum printing equipment challenge mid-tier converters.
- Online:Direct-to-consumer channels enabling subscription refillable formats and concentrated delivery systems with reduced per-use aluminum intensity.
- Convenience Stores:Impulse-driven smaller format purchases with limited shelf space favoring compact can geometries.
- Wholesalers:Industrial and foodservice volume aggregation with lower decoration requirements and bulk packaging tolerance.
Supermarkets dominate current volume throughput. Online channels are climbing the fastest through refillable format adoption and subscription model expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European aerosol can production concentrates in Germany, Italy, and Spain, while consumption spreads more evenly across Western European personal care and household markets. This geographic split shapes logistics costs and recycled aluminum sourcing strategies for converters operating across the region.
Germany
Deodorant and hair care brands in Cologne and Hamburg are piloting refillable aerosol systems that reduce per-use aluminum intensity. REACH compliance deadlines from ECHA are accelerating transitions to low-GAS propellants in household cleaning formulations. The Rhine-Ruhr industrial corridor hosts integrated aluminum rolling and can body manufacturing facilities serving cosmetics and pharmaceutical aerosol demand.
France
Sun care and cosmetic aerosol volumes in Paris and Lyon are driving qualification of 0.28 mm gauge aluminum bodies for premium personal care applications. The EU Green Deal's recycled content thresholds are reshaping procurement decisions for can makers sourcing 3104-H19 alloy scrap. The Auvergne-Rhône-Alpes region anchors metal decorating and interior coating capabilities for food-contact aerosol specifications.
Italy
Household cleaning manufacturers in Milan and Turin are reformulating product lines to compressed air and nitrogen propellants ahead of F-Gas Regulation phase-down milestones. CE marking requirements for pressurized containers are tightening quality assurance protocols across filling operations. Emilia-Romagna hosts integrated tinplate decorating facilities serving industrial lubricant and paint applications where steel retains cost advantages.
Spain
Whipped cream and cooking spray applications in Madrid and Barcelona present faster growth trajectories than saturated personal care channels with specialized epoxy-phenolic coating requirements. Extended Producer Responsibility schemes are widening cost gaps between recycled aluminum and virgin material alternatives. Catalonia concentrates metal printing capacity for high-velocity supermarket SKUs requiring high-definition graphics on thin-walled substrates.
United Kingdom
Online direct-to-consumer channels in London and Manchester are enabling subscription refillable formats with reduced per-use aluminum intensity. CSRD-aligned sustainability reporting mandates are creating procurement preference for can suppliers with verified Scope 3 emissions data. The Midlands region retains legacy steel can fabrication for industrial aerosol segments where puncture resistance governs specification decisions.
Europe Aerosol Cans Market Competitive Landscape
Top-tier vendors anchor integrated aluminum rolling and metal decorating capabilities, while mid-tier converters struggle to justify capital outlays for thin-walled printing equipment. The vendor base stratifies across three archetypes: integrated metal packaging conglomerates with captive aluminum supply, regional converters focused on steel-to-aluminum migration programs, and specialized decorators serving niche pharmaceutical and cosmetic specifications. Dominant competitive moves include capacity expansion in recycled aluminum processing and strategic partnerships with personal care brands for refillable format co-development.
Within the integrated conglomerate tier, Ball Corporation and Crown Holdings exemplify archetypes combining European aluminum rolling networks with high-volume can body supply. Trivium Packaging occupies a position representing steel-to-aluminum conversion specialists targeting household product lines with sustainability-driven procurement mandates. These three entities anchor competitive dynamics through differentiated approaches to recycled content qualification and propellant system compatibility testing.
| Leading Market Players |
|---|
| Ball Corporation |
| Crown Holdings |
| Trivium Packaging |
| Ardagh Group |
| CCL Industries |
| Can-Pack SA |
| Nampak Ltd |
| Toyo Seikan Group Holdings |
| COLEP Packaging |
| Others |
Supply & Pricing Matrix
Aluminum gauge differentiation between 0.28 mm premium thin-wall and 0.32 mm standard specifications creates parallel supply chain configurations across European can manufacturing. REACH-compliant coating chemistries and recycled content thresholds widen procurement cost spreads between certified and uncertified converter tiers.
Pricing Analysis
Short lead-time premiums of 15-20 percent apply to spot orders from German and French personal care brands facing compressed formulation timelines. Three-tier pricing structure across premium thin-wall, standard gauge, and industrial steel specifications reflects alloy grade and interior coating certification levels. Pricing pressure stems from primary aluminum smelting energy cost volatility tied to natural gas benchmarks. Discounters in Spain and Italy exhibit highest price sensitivity, while pharmaceutical aerosol buyers prioritize coating qualification over unit cost.
Supply Chain Analysis
3104-H19 alloy supply rests on German rolling mills, Spanish recycling infrastructure, and Italian metal decorating facilities. Raw material dependencies include primary aluminum ingot, tinplate coil, and epoxy-phenolic interior coating resins. Single-source vulnerability concentrates in specialized propellant chemist talent pools across Germany and the Netherlands. Distribution runs through integrated converter-direct channels for high-volume personal care, with wholesaler intermediaries serving fragmented industrial demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European aerosol can manufacturing is becoming a vertical-integration race as converters pursue captive aluminum rolling capacity to secure recycled content qualification and propellant system compatibility testing.
For Market Incumbents: Extend backward integration into European scrap collection and sorting infrastructure to lock in 3104-H19 alloy supply ahead of EU Green Deal recycled content thresholds. Defend market position by retrofitting metal decorating lines for high-definition graphics on thin-walled substrates, countering mid-tier converter capacity constraints. Prioritize co-development partnerships with German and French personal care brands on refillable format qualification.
For New Entrants and Emerging Players: Begin with steel-to-aluminum conversion programs targeting Spanish and Italian household cleaning segments where EPR fees widen the cost gap. Food and beverage aerosol applications in Southern Europe present the most penetrable white space, with specialized interior coating requirements creating barrier-to-entry protection. Pursue direct-to-consumer online channels enabling subscription refillable formats with reduced per-use aluminum intensity.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by integrated metal packaging conglomerates seeking recycled aluminum processing capacity. Long-term viability favors converters with verified Scope 3 emissions data and in-house life cycle assessment capabilities aligned with CSRD mandates. Watch for F-Gas Regulation enforcement windows as inflection indicators for compressed air propellant system adoption rates.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Scrap Recycling | Secures 3104-H19 alloy supply for EU Green Deal compliance in German and French operations. |
| Thin-Wall Gauge Qualification | Enables 12-15 percent aluminum weight reduction for deodorant volumes up to 150 ml. |
| Compressed Air Propellant Reformulation | Aligns household cleaning products with F-Gas Regulation phase-down milestones ahead of enforcement. |
| Steel-to-Aluminum Conversion Programs | Migrates tinplate household product lines to recycled aluminum as EPR fees widen cost gaps. |
| CSRD-Aligned Sustainability Reporting | Creates procurement preference among discounters requiring batch-level carbon footprint documentation. |
Research Methodology
Independent corroboration across converter production data, filling line throughput records, and regulatory filing databases underwrites the qualitative findings in this study. Primary interviews with plant managers at European rolling mills, procurement leads at personal care brand owners, and technical R&D directors at coating suppliers combined with secondary validation from ECHA REACH registrations, EU packaging waste directive filings, and aluminum trade association statistics. Bottom-up volume modeling triangulated against top-down market sizing from national packaging production surveys.
Historical reference periods spanning pre-pandemic baseline, supply disruption interval, and normalization phase anchored the forecast window. Segmentation dimensions modeled include material type, application category, end-user procurement authority, and distribution channel velocity. CAGRs were derived from regression analysis of alloy price trajectories, propellant formulation adoption curves, and EPR scheme implementation timelines. Industry-specific inputs incorporated recycled aluminum collection rate trajectories and interior coating approval pipeline status.
Underlying measurement precision varies by segment; aluminum volume and personal care application data carry tighter precision than emerging plastic format estimates. Forecasts reflect documented assumptions regarding regulatory enforcement timing, scrap recovery infrastructure buildout, and brand owner sustainability commitment durability. A small set of triggers—including natural gas price spikes, EFSA coating approval delays, and propellant chemist retirement waves—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Explosives and Pyrotechnics Market
Specialty Chemicals
Natural Phytosphingosine Market
Specialty Chemicals
Betanin Market
Specialty Chemicals
United States Aerosol Cans Market
Specialty Chemicals
4-ADPA Market
Specialty Chemicals
Europe Non-Phthalate Plasticizers Market
Specialty Chemicals
Washable Marker Market
Specialty Chemicals
Global Ceramide Market
Specialty Chemicals
Inorganic Flame Retardants Market
Specialty Chemicals
Organo-Modified Bentonite Market
Specialty Chemicals
Lanolin Market
Specialty Chemicals
Dipentene (Limonene) Market
Specialty Chemicals
Chromium Polynicotinate Market
Specialty Chemicals
Naphthol AS-IRG Market
Specialty Chemicals
Releasing Agents Market
Specialty Chemicals
Medical Propellants Market