
 Fluorinated Plasma Surface Treatment Market | 2026-2036
Fluorinated Plasma Surface Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Fluorinated Plasma Surface Treatment Market Analysis
Multi-source procurement for fluorinated plasma equipment is consolidating as OEMs reduce vendor lists to capture technical consistency and service integration. Nordson Corporation leverages its atmospheric plasma portfolio to dominate high-throughput automotive lines. Plasmatreat sustains technology leadership through radiofrequency plasma systems tailored for medical polymer substrates. AcXys Technologies anchors European demand with low-pressure installations across French and German aerospace suppliers.
Fluorinated plasma surface treatment deposits fluorocarbon functional groups onto substrates via glow discharge, typically operating at 13.56 MHz radiofrequency or 2.45 GHz microwave excitation with CF4, C2F6, or SF6 process gases to achieve water contact angles exceeding 110 degrees for hydrophobic barrier performance. The gas phase segment leads volume due to its compatibility with continuous inline manufacturing, while atmospheric pressure technology captures the fastest expansion as manufacturers eliminate vacuum chamber bottlenecks. Liquid phase treatment retains margin concentration in semiconductor wafer processing where angstrom-level thickness control commands premium positioning.
EPA oversight of fluorinated greenhouse gas emissions under the American Innovation and Manufacturing Act constrains process chemistry selection for US-based installations, while REACH Annex XVII restrictions on per- and polyfluoroalkyl substances in Europe accelerate plasma fluorination as a precision alternative to bulk PFAS application. FDA device regulations for permanent implant surface properties further shape medical validation protocols. Stakeholders must monitor evolving fluorinated gas phase-out schedules and align capital planning with emerging low-global-warming-potential precursor availability.
Market Dynamics
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are redirecting European industrial investment toward plasma fluorination as a precision alternative to bulk PFAS application, compressing substitution timelines across medical device and automotive supply chains.
Growth Catalysts
- EPA Greenhouse Gas Oversight:The American Innovation and Manufacturing Act constrains process chemistry selection for US-based installations, accelerating adoption of low-global-warming-potential plasma precursors in domestic manufacturing corridors.
- Medical Device Surface Modification:FDA validation protocols for permanent implant properties are standardizing fluorinated plasma protocols across catheter and cardiovascular device production lines.
- German Precision Manufacturing Cluster:Automotive and medical OEM concentration in Baden-Württemberg and Bavaria generates concentrated demand for atmospheric plasma throughput systems.
Market Restraints
- Fluorinated Gas Supply Concentration:CF4, C2F6, and SF6 precursor production concentrates among limited specialty gas suppliers, exposing equipment operators to input cost volatility and allocation risk.
- Technical Thickness Limitations:Angstrom-level control requirements in semiconductor wafer processing restrict liquid phase treatment scalability outside captive fabrication facilities.
- REACH F-Gas Phase-Down Schedules:The EU F-Gas Regulation creates regulatory friction for process gas selection, forcing capital planning alignment with emerging precursor availability windows.
Strategic Opportunities
- Indian Medical Device Manufacturing:CDSCO regulatory harmonization with ISO 13485 standards creates entry pathways for plasma surface treatment providers serving domestic implant production scaling.
- Atmospheric Pressure Technology Convergence:Integration of microwave excitation with inline continuous manufacturing eliminates vacuum chamber bottlenecks, opening automotive exterior component treatment volumes.
- EU Green Deal Industrial Funding:CSRD-aligned capital allocation mechanisms subsidize plasma fluorination retrofits as PFAS reduction compliance pathways for precision manufacturers.
Industry Challenges
- Radiofrequency Engineering Talent Scarcity:13.56 MHz system design and plasma diagnostics expertise concentrates among aging specialist cohorts, constraining equipment manufacturer expansion capacity.
- Multi-Site Validation Complexity:FDA device master file amendments require coordinated protocol replication across geographically dispersed medical OEM production facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fluorinated Plasma Surface Treatment Market |
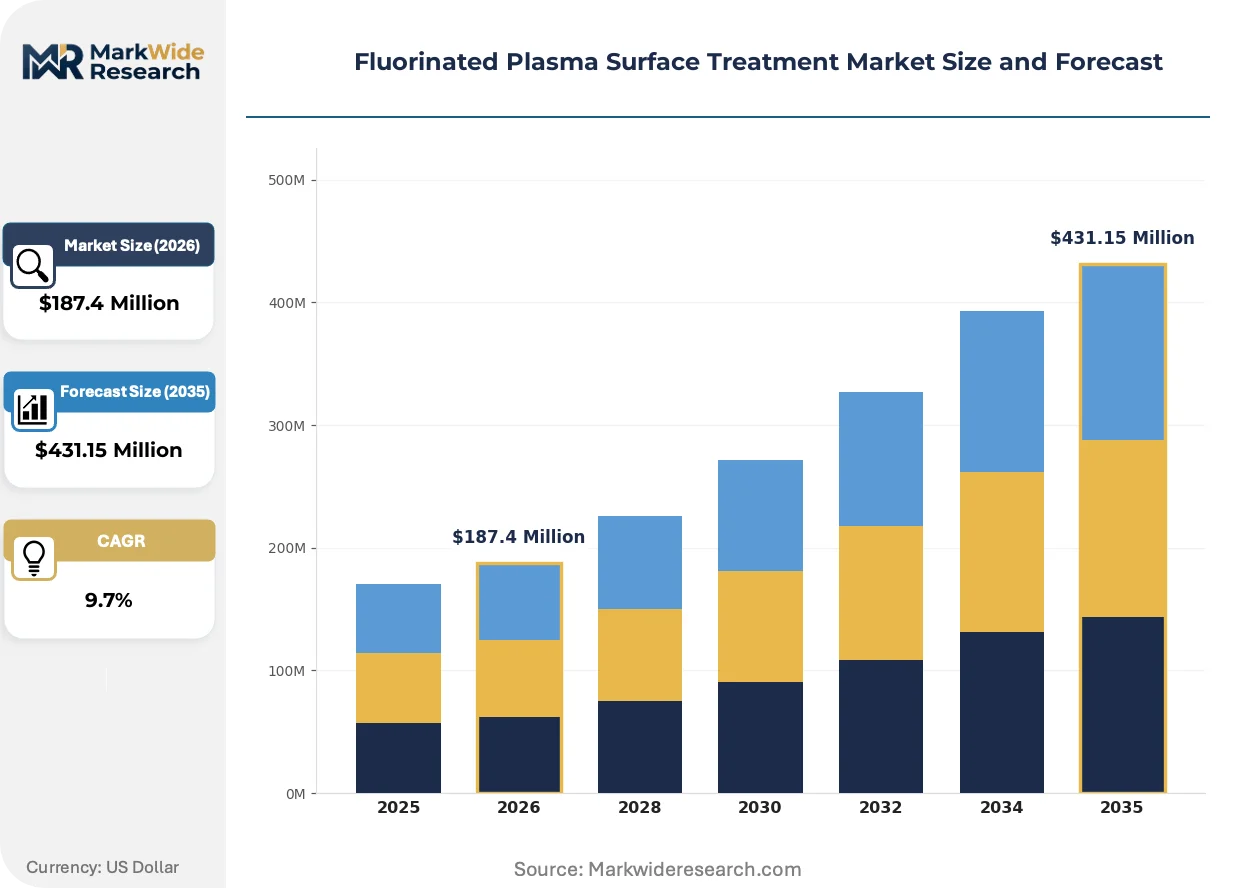
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $431.15 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gas Phase, Liquid Phase, Powder Phase, Solution Phase Application: Aerospace, Medical Devices, Electronics, Automotive End User: Manufacturers, Research Institutions, Semiconductor Industries, Coating Providers Technology: Atmospheric Pressure, Low Pressure, Microwave Plasma, Radiofrequency Plasma |
| Companies Covered | Nordson Corporation, Plasmatreat, AcXys Technologies, Enercon Industries Corporation, 3DT LLC, Henniker Plasma, Plasmalex, AST Products, Relyon Plasma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fluorinated Plasma Surface Treatment Market Emerging Trajectories
Plasma fluorination technology is compressing traditional wet chemistry timelines as manufacturers seek angstrom-precision surface control without bulk chemical inventory exposure.
Atmospheric pressure plasma treatment is electrifying automotive exterior manufacturing by enabling inline fluorocarbon deposition at production line speeds. Tier-1 suppliers in Stuttgart and Wolfsburg are retrofitting paint shop sequences with open-air plasma stations. This electrifying deployment is displacing vacuum batch processing for bumper and trim component hydrophobic barrier application.
The EU F-Gas Regulation phase-down schedule is forcing process gas substitution across European installation bases. Industrial users are qualifying CF4 alternatives with reduced global warming potential for existing radiofrequency equipment. Medical device manufacturers in Ireland and the Netherlands face compressed validation timelines to maintain CE marking compliance under evolving Annex XVII restrictions.
Buyer concentration among catheter OEMs is consolidating vendor qualification lists to capture technical consistency. Procurement teams now require integrated service contracts spanning equipment, consumables, and process validation support. This pattern is most visible in Minnesota and Massachusetts medical device corridors, where three manufacturers account for dominant fluorinated plasma equipment procurement volumes.
Fluorinated Plasma Surface Treatment Market Segmentation
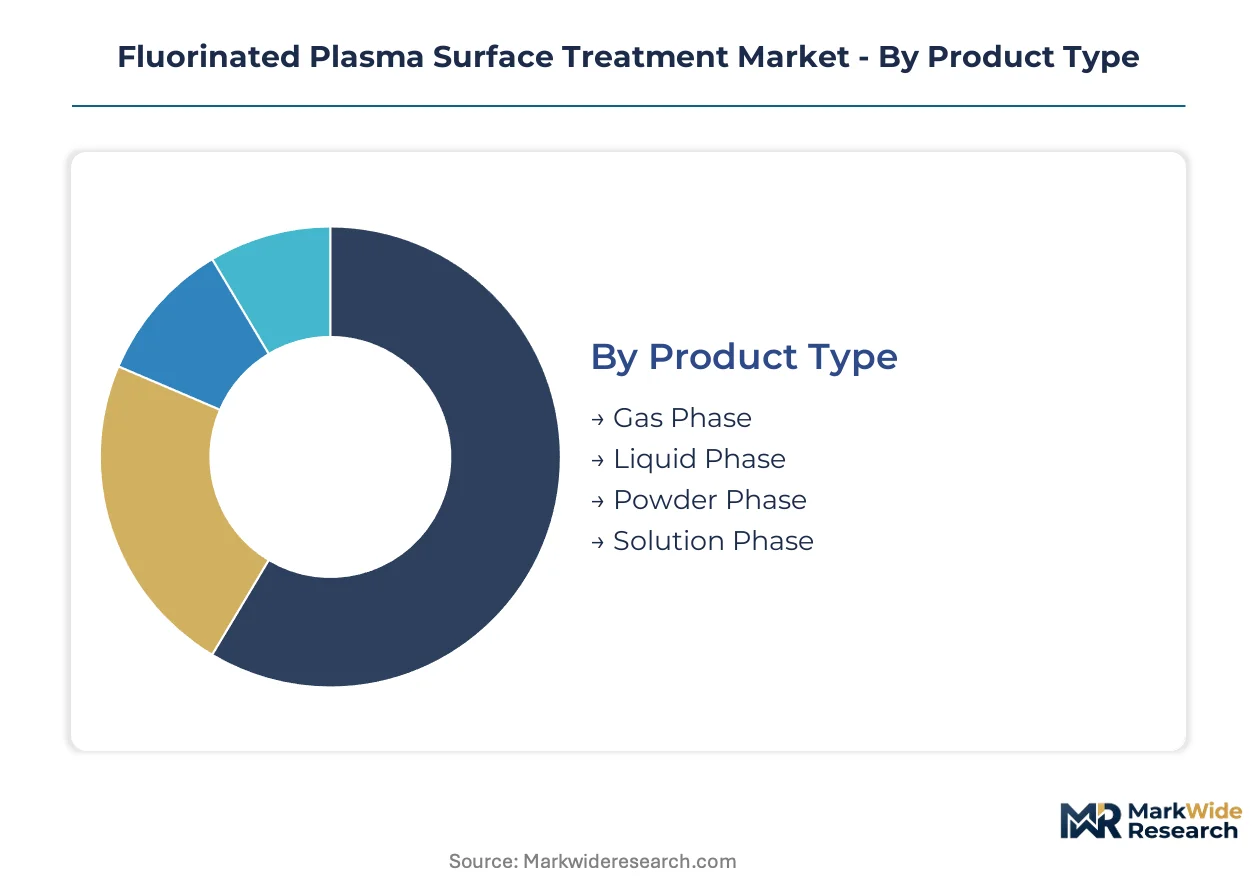
Fluorinated plasma surface treatment segments diverge sharply by integration depth. Standalone atmospheric systems serve high-throughput automotive lines, while embedded low-pressure modules integrate into captive semiconductor fabrication workflows.
Product Type:
Gas phase systems operate as standalone inline installations, while liquid and solution phases embed into captive wafer processing workflows with precision thickness control requirements.
- Gas Phase:Continuous inline deposition using CF4, C2F6, or SF6 precursors achieves water contact angles exceeding 110 degrees. Demand concentrates in German automotive corridors where paint shop retrofits require high-throughput hydrophobic barrier application without vacuum bottlenecks.
- Liquid Phase:Angstrom-level thickness control through submerged plasma discharge suits semiconductor wafer processing. Captive fabrication facilities in Ireland and the Netherlands command premium positioning for permanent implant surface validation under FDA protocols.
- Powder Phase:Fluidized bed plasma fluorination for particulate substrates serves specialty coating providers with batch processing requirements.
- Solution Phase:Electrochemical plasma dissolution in fluorinated electrolytes targets research institutions exploring novel surface chemistries.
Volume placements concentrate in Gas Phase; the faster expansion belongs to Liquid Phase as semiconductor wafer processing scales.
Application:
Medical device and automotive applications generate margin concentration through regulatory-validated specifications, while aerospace and electronics segments prioritize performance tier differentiation.
- Medical Devices:Catheter and cardiovascular implant surface modification requires FDA device master file compliance. Procurement consolidates among Minnesota and Massachusetts OEMs demanding integrated service contracts spanning equipment, consumables, and validation support.
- Automotive:Exterior component hydrophobic treatment at atmospheric pressure eliminates vacuum chamber bottlenecks. Stuttgart and Wolfsburg tier-1 suppliers retrofit paint shop sequences with open-air plasma stations for bumper and trim barrier application.
- Aerospace:French and German aerospace suppliers deploy low-pressure installations for fuel system component sealing under EASA certification requirements.
- Electronics:Printed circuit board moisture barrier treatment operates at lower specification tiers with price-sensitive procurement patterns.
Revenue concentration sits with Medical Devices; Electronics represents the most price-compressed application tier.
End User:
Manufacturer procurement dominates capital deployment, while research institutions and semiconductor industries operate distinct acquisition models with extended validation timelines.
- Manufacturers:High-volume automotive and medical OEMs consolidate vendor lists to capture technical consistency. Multi-site FDA validation requirements force coordinated protocol replication across geographically dispersed production facilities.
- Semiconductor Industries:Captive fabrication facilities in Ireland and the Netherlands maintain dedicated process engineering teams for angstrom-level thickness control. REACH Annex XVII restrictions compress substitution timelines for PFAS reduction compliance.
- Research Institutions:Academic and government laboratories pilot novel precursor chemistries with reduced global warming potential under EPA oversight constraints.
- Coating Providers:Job shop operators serve fragmented demand across industrial maintenance and specialty component refurbishment.
Capital deployment concentrates among Manufacturers; Research Institutions show the steepest expansion trajectory as novel precursor development accelerates.
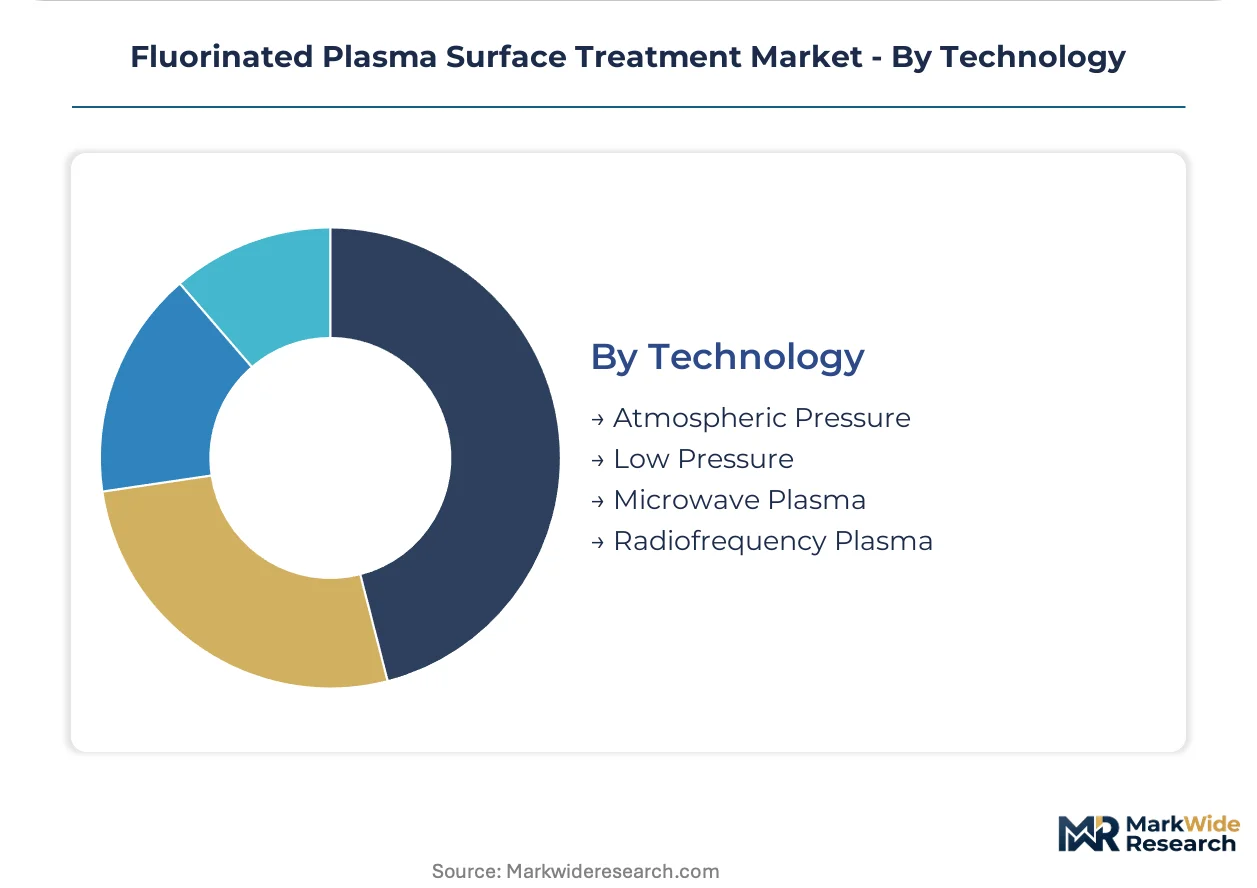
Technology:
Radiofrequency and microwave excitation systems compete on throughput versus precision, while pressure regime selection determines integration architecture.
- Atmospheric Pressure:Microwave excitation enables inline continuous manufacturing without vacuum chamber bottlenecks. German automotive OEMs in Baden-Württemberg and Bavaria generate concentrated demand for throughput systems displacing batch vacuum processing.
- Radiofrequency Plasma:13.56 MHz systems tailored for medical polymer substrates sustain technology leadership through precise discharge control. Engineering talent scarcity among aging specialist cohorts constrains equipment manufacturer expansion capacity.
- Low Pressure:Vacuum chamber installations anchor European aerospace supply chains with French and German precision manufacturing clusters.
- Microwave Plasma:2.45 GHz excitation serves specialized semiconductor wafer processing with rapid deposition rate requirements.
Installed base concentrates in Radiofrequency Plasma; Atmospheric Pressure systems gain share fastest through automotive exterior manufacturing electrification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German specialty gas production anchors European fluorinated plasma supply chains, while US and Asian manufacturing corridors drive equipment demand through diverging regulatory pathways.
United States
Automotive exterior manufacturing and medical device clusters in Minnesota and Massachusetts propel equipment procurement. EPA oversight under the American Innovation and Manufacturing Act constrains process chemistry selection, accelerating low-global-warming-potential precursor adoption. Domestic manufacturers navigate input cost volatility as CF4 and C2F6 supply concentrates among limited specialty gas distributors.
Germany
Baden-Württemberg and Bavaria precision manufacturing corridors generate concentrated demand for atmospheric plasma throughput systems. REACH Annex XVII restrictions on per- and polyfluoroalkyl substances redirect investment toward plasma fluorination as a controlled PFAS alternative. Stuttgart and Wolfsburg tier-1 suppliers retrofit paint shop sequences with open-air plasma stations for bumper hydrophobic barrier application.
France
Aerospace fuel system component sealing requirements under EASA certification sustain low-pressure installation demand. AcXys Technologies anchors European supply through regional equipment presence. Toulouse and Paris aerospace clusters deploy vacuum chamber systems for precision sealing applications, compressing validation timelines under evolving EU F-Gas Regulation phase-down schedules.
Ireland
Semiconductor fabrication facilities command premium positioning for angstrom-level thickness control in captive wafer processing workflows. REACH restrictions compress substitution timelines for PFAS reduction compliance. Dublin and Cork manufacturing sites maintain dedicated process engineering teams for medical implant surface validation under FDA device master file protocols.
India
Domestic implant production scaling creates entry pathways for plasma surface treatment providers. CDSCO regulatory harmonization with ISO 13485 standards accelerates medical device manufacturing investment. Maharashtra and Karnataka medical technology clusters pilot fluorinated plasma adoption for catheter surface modification as procurement consolidates among emerging domestic OEMs.
Fluorinated Plasma Surface Treatment Market Vendor Landscape
Global majors compete with regional champions across technology specialization and service integration depth. The vendor base stratifies into atmospheric pressure specialists, low-pressure system fabricators, and integrated service providers. Three archetypes dominate: throughput-optimized automotive suppliers, precision-focused medical device enablers, and captive semiconductor integration specialists. Competitive moves center on multi-site service contract consolidation and low-global-warming-potential precursor qualification partnerships.
Among US-based equipment manufacturers, Nordson Corporation and Enercon Industries Corporation exemplify scale-driven atmospheric pressure portfolio breadth. European specialists occupy differentiated positions: Plasmatreat represents radiofrequency precision for medical polymer substrates, while AcXys Technologies anchors French and German aerospace demand through low-pressure system integration. These three companies illustrate the geographic technology clustering that shapes competitive positioning across Atlantic supply chains.
| Leading Market Players |
|---|
| Nordson Corporation |
| Plasmatreat |
| AcXys Technologies |
| Enercon Industries Corporation |
| 3DT LLC |
| Henniker Plasma |
| Plasmalex |
| AST Products |
| Relyon Plasma |
| Others |
Supply Flow & Price Mechanics
EPA greenhouse gas oversight under the American Innovation and Manufacturing Act gates qualified supply access and premium-tier pricing for equipment operators seeking low-global-warming-potential precursor compatibility. Buyers without validated process chemistry portfolios face exclusion from medical device OEM procurement lists where FDA master file compliance commands price premiums.
Pricing Analysis
Extended warranty and validation service bundling separates premium-tier equipment suppliers from unbundled hardware vendors in competitive tenders. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and geographic service coverage density. Cost compression in economy-tier atmospheric systems intensifies as Chinese equipment manufacturers expand export capacity. Electronics segment buyers exhibit highest price sensitivity, while semiconductor captive fabrication facilities show least elasticity due to angstrom-precision requirements.
Supply Chain Analysis
Regional distribution centers in Germany, the United States, and Japan maintain hub-and-spoke patterns for CF4, C2F6, and SF6 precursor delivery to equipment installation bases. Specialty gas production concentrates in Germany and Japan, with microwave generator components sourcing from South Korean and Taiwanese electronics suppliers. Single-source vulnerability runs through limited qualified suppliers of low-global-warming-potential alternatives under EPA phase-down schedules. Distribution runs through direct OEM channel partnerships rather than independent distributors for medical device validation-intensive deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Atmospheric pressure plasma technology is displacing legacy vacuum batch processing across automotive exterior manufacturing, compressing substitution timelines for tier-1 supplier capital planning.
For Market Incumbents: Lock in multi-site service contract consolidation with catheter OEMs in Minnesota and Massachusetts to defend against emerging Asian equipment manufacturers. Prioritize backward integration into low-global-warming-potential precursor qualification partnerships under EPA oversight timelines. Expand atmospheric pressure throughput capacity in Baden-Württemberg to capture paint shop retrofit volumes from Stuttgart automotive suppliers. For New Entrants and Emerging Players: Begin with CDSCO regulatory harmonization pathways in Maharashtra and Karnataka medical technology clusters where domestic implant production scaling creates white-space demand. Target atmospheric pressure system deployment for Indian catheter manufacturers seeking ISO 13485 compliance without legacy vendor switching costs. Pursue equipment-leasing models with integrated validation support to lower capital barriers for emerging OEMs. For Investors and Strategic Acquirers: EU F-Gas Regulation phase-down acceleration is the leading indicator that plasma fluorination equipment demand will outpace legacy wet chemistry substitution rates across European medical device supply chains. Target acquisition candidates with established CE marking technical files and radiofrequency engineering specialist teams. Monitor EPA precursor approval announcements as inflection signals for domestic manufacturing corridor equipment placement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Low-GWP Precursor Qualification Partnership | EPA approval under AIM Act secures access to US medical device OEM procurement lists. |
| Multi-Site FDA Master File Replication | Coordinated validation across Minnesota and Massachusetts facilities accelerates catheter OEM vendor consolidation. |
| Atmospheric Pressure Throughput Expansion | Baden-Württemberg capacity addition captures Stuttgart tier-1 paint shop retrofit demand. |
| CDSCO Harmonization Pathway Investment | ISO 13485 alignment in Maharashtra opens domestic Indian implant manufacturing equipment placement. |
| Radiofrequency Engineering Talent Acquisition | 13.56 MHz system design expertise concentration constrains equipment manufacturer expansion capacity. |
Methodological Framework
Independent corroboration across equipment manufacturer sales directors, specialty gas procurement leads at medical device OEMs, and automotive tier-1 supplier process engineering heads underwrites the qualitative findings. Primary field engagement with plasma diagnostics specialists, FDA regulatory affairs consultants, and REACH compliance officers at Irish semiconductor fabrication facilities combined with secondary validation from EPA AIM Act docket records, ECHA Annex XVII restriction updates, and SEC equipment manufacturer 10-K disclosures. Bottom-up installation base enumeration and top-down end-use demand estimation triangulate volume outputs.
Rate-of-change decomposition across the analysis window segments expansion by gas phase versus liquid phase technology, medical device versus automotive application, and atmospheric pressure versus radiofrequency excitation architecture. CAGRs derive from equipment placement velocity modeling, precursor consumption intensity ratios, and validated replacement cycle assumptions. Forecast inputs incorporate EU F-Gas Regulation phase-down schedule compliance timelines and CDSCO regulatory harmonization progression indicators.
Underlying measurement precision varies by segment; semiconductor wafer processing and medical device surface modification carry tighter precision than electronics moisture barrier applications due to captive fabrication facility data availability. Forecasts reflect assumptions about EPA precursor approval timelines and REACH restriction enforcement consistency. Periodic stress-testing of base assumptions against regulatory announcement velocity and specialty gas supply allocation patterns is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Propyl Isovalerate Market
Specialty Chemicals
Silanes and Silicones Market
Specialty Chemicals
Inorganic Flame Retardants Market
Specialty Chemicals
Caryophyllene Market
Specialty Chemicals
Squalene Market
Specialty Chemicals
Methyltrimethoxysilane Market
Specialty Chemicals
United States Aerosol Cans Market
Specialty Chemicals
Optical Whitening Agents Market
Specialty Chemicals
Middle East and Africa Polyvinylpyrrolidone (PVP) Market
Specialty Chemicals
Precast Gels Market
Specialty Chemicals
Global Hydroxy Ethyl Cellulose (HEC) Market
Specialty Chemicals
Bio-Based Phenol Market
Specialty Chemicals
Flame-Retardant Synergist Systems with Low Smoke Toxicity Market
Specialty Chemicals
Ricinoleic Acid Market
Specialty Chemicals
Phosphatidylcholine Market
Specialty Chemicals
Germany Starch Derivatives Market