
 Liquid Silicone Rubber Market | 2026-2036
Liquid Silicone Rubber Market Size, Share, and Industry Trends Forecast 2026-2036
Liquid Silicone Rubber Market Intelligence
The EU Green Deal's F-Gas Regulation is realigning fluorosilicone substitution patterns across European supply chains. Dow leverages captive siloxane feedstock to sustain cost advantages in medical-grade formulations. Wacker Chemie AG anchors high-purity LSR output from its Burghausen complex, while Shin-Etsu Chemical dominates Asian electronics-grade supply through integrated monomer-to-polymer operations.
Liquid silicone rubber denotes a two-part platinum-cured elastomer system comprising vinyl-functional polydimethylsiloxane and hydride crosslinker, vulcanizing at 120-200°C without peroxide byproducts to yield optical clarity and thermal stability from -60°C to 230°C. Medical Devices applications lead value capture due to ISO 10993 certification burdens and multi-year supplier qualification cycles. Molding processes command the dominant application share as liquid injection molding tolerances tighten for automotive LED lens housings and respiratory device seals. Adhesives segments compete on faster cure chemistry for wearable electronics assembly.
FDA 21 CFR Part 177.2600 compliance shapes US medical LSR formulation requirements, while REACH Annex XVII restrictions on volatile siloxanes constrain European consumer goods grades. China's GB 4806.11-2016 food-contact standards and NMPA medical device registration rules govern import access. Stakeholders must monitor platinum group metal price volatility and regional peroxide-cure phaseout timelines to calibrate raw material sourcing and capital allocation across curing technology platforms.
Market Dynamics
Platinum-catalyzed curing systems are displacing peroxide-cured alternatives across medical and automotive supply chains as FDA biocompatibility standards tighten and optical clarity requirements intensify for LED lens applications.
Growth Catalysts
- FDA 21 CFR Part 177.2600 compliance:Medical device manufacturers are accelerating qualification of implant-grade formulations as regulatory pathways for peroxide-cured alternatives narrow.
- Freiburg-Munich precision molding cluster:Co-located tooling expertise among German automotive suppliers and medical OEMs compresses development cycles for multi-cavity LSR tooling.
- Fluorosilicone substitution:The EU Green Deal's F-Gas Regulation is redirecting demand toward high-performance LSR grades in sealing applications previously served by fluorinated elastomers.
Market Restraints
- Platinum group metal volatility:Price swings in platinum catalysts directly compress margins for medical-grade formulations where alternative curing chemistries remain non-viable.
- Burghausen supply concentration:European high-purity LSR output remains anchored to a single integrated chemical complex, creating geographic risk exposure for qualified medical supply chains.
- REACH Annex XVII siloxane restrictions:Volatile organic compound limits on low-molecular-weight siloxanes constrain formulation flexibility for European consumer goods grades.
Strategic Opportunities
- India CDSCO medical device registration:Underpenetrated implantable device manufacturing is opening procurement channels for ISO 10993-certified LSR as domestic production incentives expand.
- Wearable electronics adhesives:Faster-cure LSR chemistries are capturing assembly steps previously served by thermal epoxies in fitness tracker and hearing aid manufacturing.
- China dual carbon goals:NMPA efficiency mandates for respiratory device seals are favoring platinum-cured LSR over thermoplastic alternatives in high-volume manufacturing.
Industry Challenges
- Multi-year supplier qualification cycles:ISO 10993 certification burdens lock medical OEMs into existing supply relationships, extending payback periods for new market entrants.
- Liquid injection molding tolerance compression:Automotive LED lens housings now demand sub-10-micron repeatability, requiring simultaneous upgrades in tooling design, process control, and material lot consistency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Liquid Silicone Rubber Market |
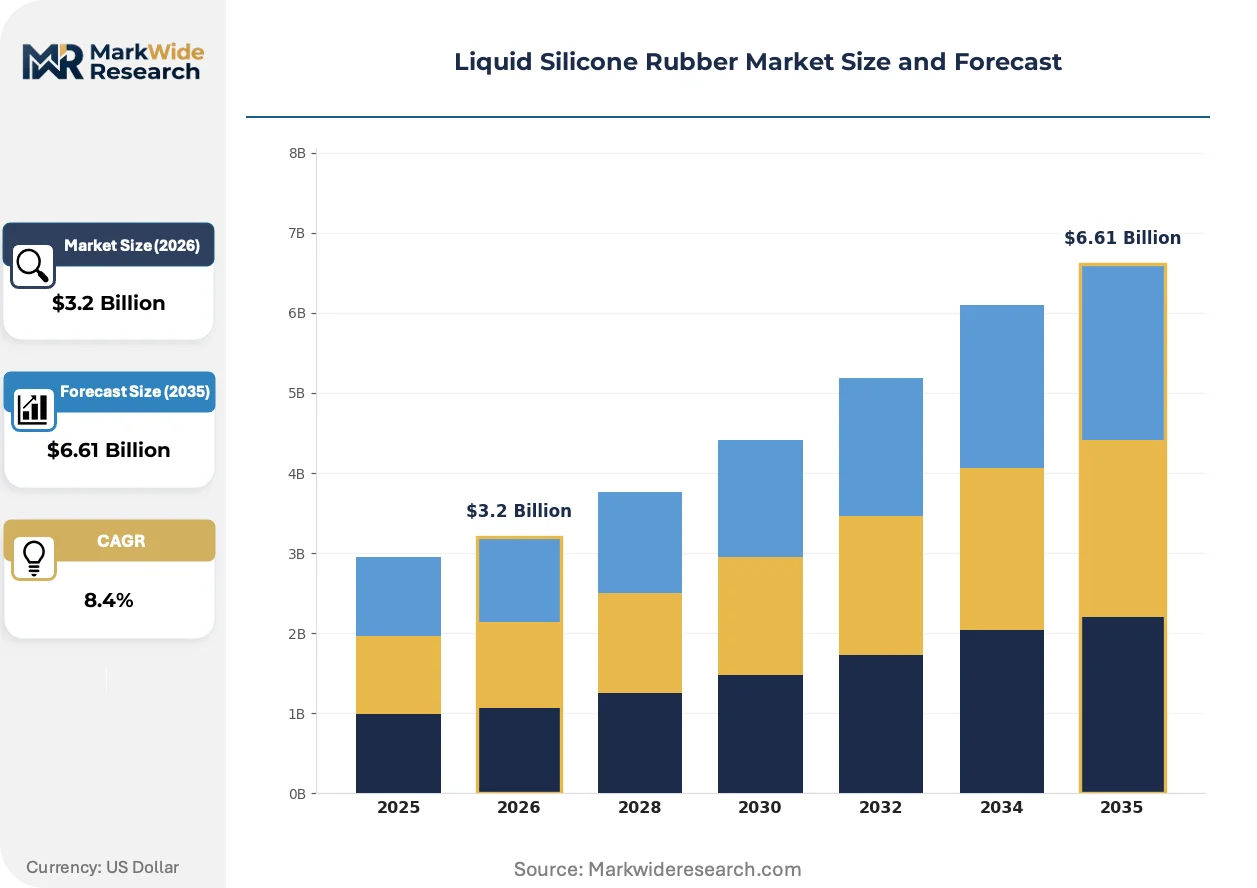
| Market Size in 2026 | $3.2 Billion |
| Market Size in 2035 | $6.61 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medical Devices, Automotive Parts, Consumer Goods, Electronics Application: Molding, Coating, Adhesives, Sealants End User: Manufacturers, Distributors, OEMs, Engineering Firms Form: Liquid, Semi-Finished, Blocks, Compounds |
| Companies Covered | Elkem Silicones, CHT Germany GmbH, Dow, Avantor Inc., KCC Silicone Corporation, Wacker Chemie AG, Shin-Etsu Chemical, Rui-He New Material, Momentive Performance Materials, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Liquid Silicone Rubber Market Strategic Shifts & Innovations
Formulation chemistry and curing control systems are converging to enable thinner-wall molding and faster cycle times, reshaping competitive positioning across medical implant and automotive lighting supply chains.
Additive manufacturing of LSR tooling inserts is expanding into rapid prototyping workflows for medical device seals. German precision molders are adopting printed conformal cooling channels to reduce cycle times in multi-cavity respiratory mask production. This capability is compressing time-to-market for FDA-submission batches and enabling design iteration frequencies previously unattainable with machined steel tooling.
REACH F-Gas Regulation amendments are accelerating fluorosilicone phaseout timelines across European automotive sealing applications. Tier-1 suppliers are requalifying engine compartment gaskets and transmission seals using high-temperature LSR grades to maintain thermal performance without fluorinated content. German and French OEMs are driving the fastest specification updates, with qualification completion deadlines compressing supplier development windows.
Buyer consolidation among contract medical device manufacturers is consolidating procurement leverage around qualified LSR compounders. Large-scale CDMOs are unbundling material supply from molding services, forcing compounders to certify directly against OEM specifications rather than through intermediary toll processors. This pattern is most visible in Minnesota and Massachusetts medical device corridors, where three CDMOs now control a majority of implantable silicone component sourcing decisions.
Liquid Silicone Rubber Market Segmentation
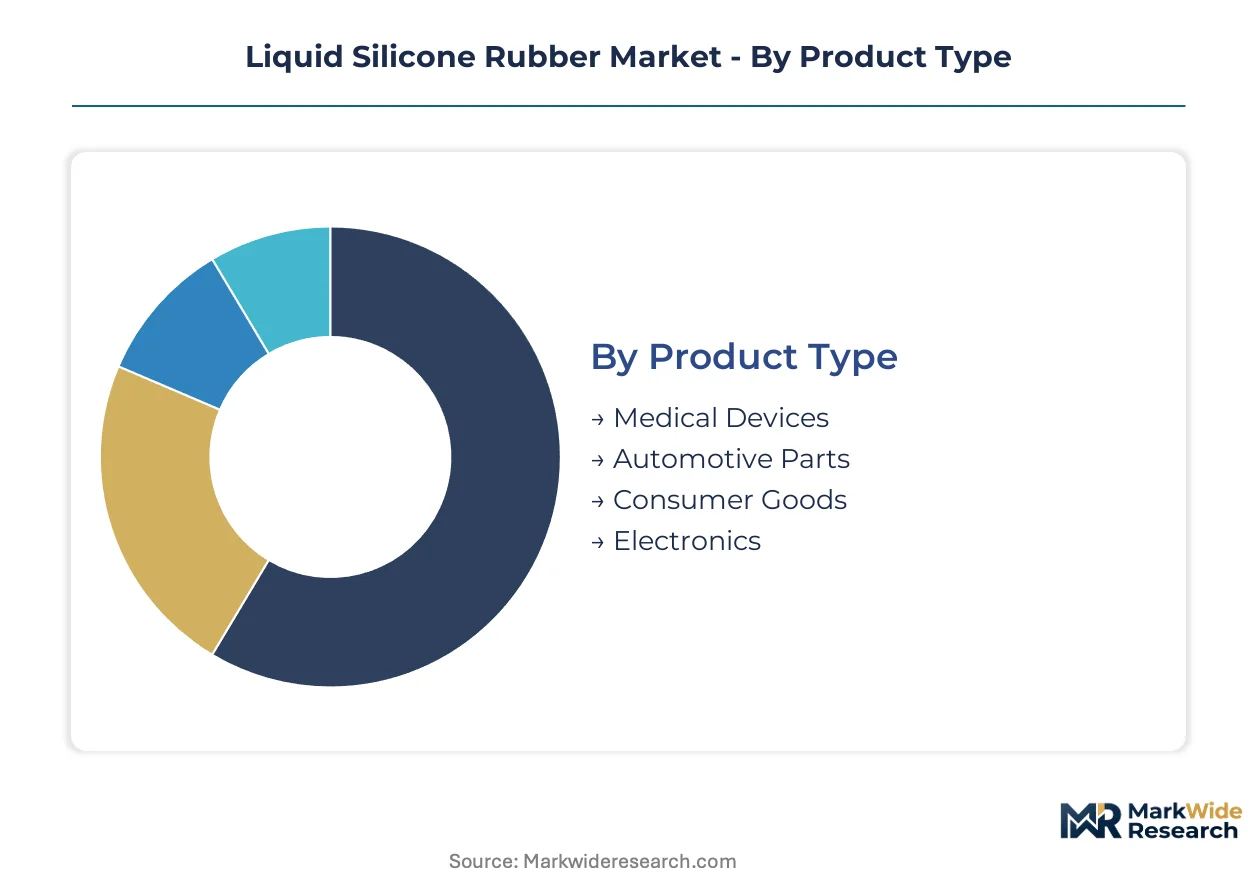
LSR procurement patterns diverge sharply across curing chemistry, purity grades, and processing formats, with medical and automotive buyers imposing incompatible specification regimes that fragment supplier portfolios. Segmentation clarity enables compounders to align R&D spending against qualification timelines and margin structures that vary by end-use.
Product Type:
Replacement cycles and specification upgrades are compressing as FDA biocompatibility pathways narrow for legacy formulations and automotive LED optical clarity tolerances tighten.
- Medical Devices:Implant-grade formulations meeting ISO 10993 certification dominate procurement value, with demand concentrating in Minnesota and Massachusetts corridors where CDMOs control component sourcing decisions. Multi-year supplier qualification cycles lock OEMs into existing relationships.
- Automotive Parts:LED lens housings and respiratory device seals drive precision molding investments, with Freiburg-Munich tooling clusters compressing development cycles for sub-10-micron repeatability requirements. EU F-Gas Regulation amendments accelerate fluorosilicone substitution timelines.
- Consumer Goods:REACH Annex XVII volatile siloxane limits constrain formulation flexibility for European consumer applications.
- Electronics:Wearable device assembly favors faster-cure chemistries displacing thermal epoxies in fitness tracker manufacturing.
Volume placements concentrate in Medical Devices; the faster expansion belongs to Automotive Parts.
Application:
Cost tier differentiation separates capital-intensive liquid injection molding from lower-barrier coating and adhesive segments.
- Molding:Liquid injection molding commands dominant value share as multi-cavity tooling tolerances tighten for automotive LED lens housings. German precision molders adopt additive-manufactured conformal cooling channels to reduce cycle times in respiratory mask production.
- Adhesives:Faster-cure LSR chemistries capture assembly steps in hearing aid and fitness tracker manufacturing, climbing the fastest as wearable electronics procurement scales.
- Coating:Thin-film applications compete on cure speed for consumer electronics protection.
- Sealants:Engine compartment and transmission applications requalify under EU F-Gas Regulation phaseout deadlines.
Capital deployment concentrates in Molding; the steepest expansion trajectory belongs to Adhesives.
End User:
Customer type determines specification authority, with OEMs and CDMOs increasingly unbundling material supply from molding services.
- OEMs:Direct qualification against OEM specifications now dominates medical device procurement, bypassing intermediary toll processors in Minnesota and Massachusetts corridors.
- Manufacturers:Integrated compounder-molders face margin pressure as procurement leverage consolidates among large-scale CDMOs.
- Distributors:Standard-grade LSR flows through distribution for consumer goods and industrial applications.
- Engineering Firms:Design-phase specification influence concentrates in automotive lighting and medical implant development.
Procurement authority concentrates in OEMs; the fastest share gain belongs to Manufacturers pursuing direct certification.
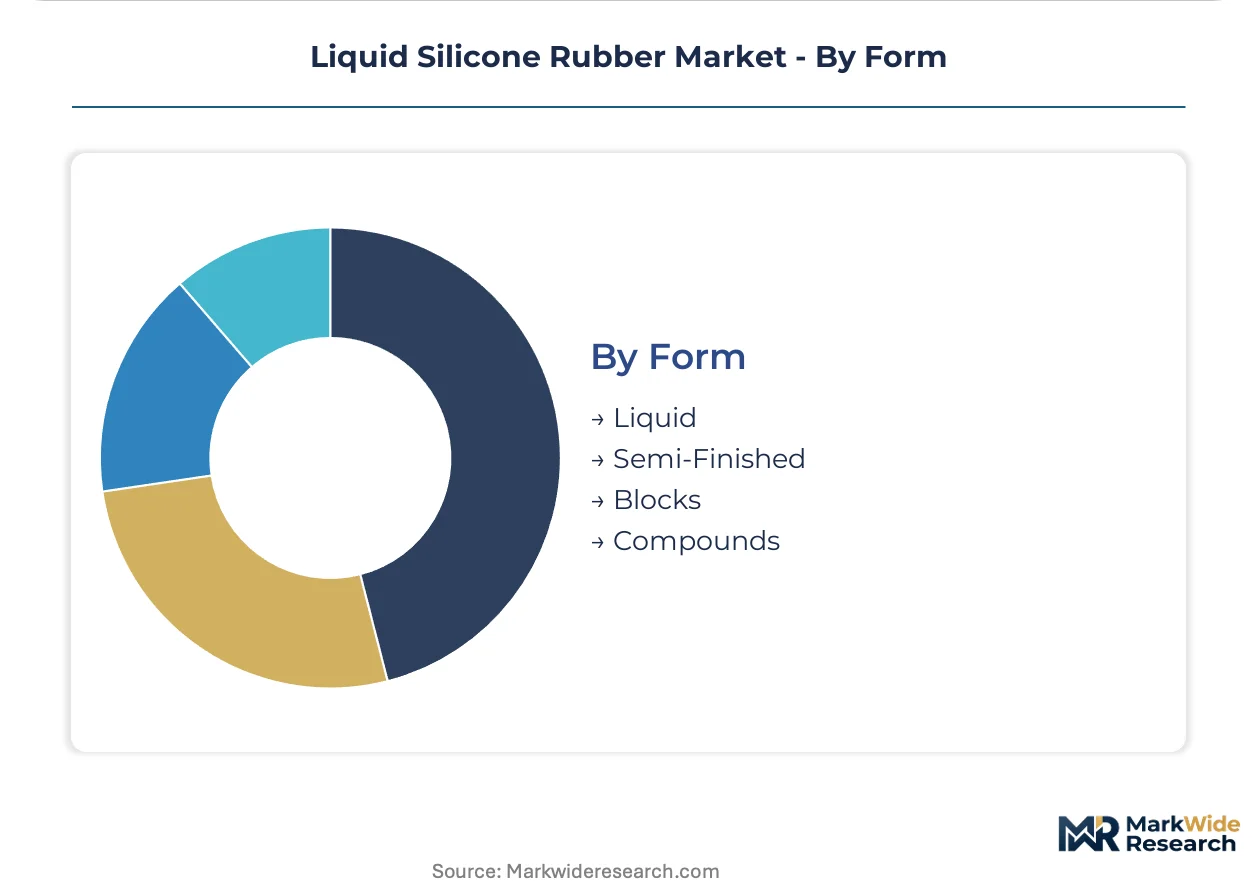
Form:
Supply concentration around high-purity liquid formats creates geographic risk exposure for qualified medical supply chains.
- Liquid:Two-part platinum-cured systems comprising vinyl-functional polydimethylsiloxane and hydride crosslinker dominate medical and automotive precision applications. Burghausen complex anchors European high-purity output.
- Compounds:Pre-formulated grades with pigment and additive packages streamline molding operations for automotive suppliers.
- Semi-Finished:Intermediate forms serve toll processors and regional compounders lacking integrated monomer-to-polymer capabilities.
- Blocks:Solid forms support compression molding operations in industrial and consumer goods segments.
Value capture concentrates in Liquid; the expanding application base belongs to Compounds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Freiburg-Munich precision molding clusters anchor European LSR tooling expertise, while Asian electronics corridors and US medical device corridors concentrate demand across incompatible specification regimes.
United States
Minnesota and Massachusetts medical device corridors dominate implant-grade procurement as CDMOs consolidate sourcing leverage. FDA 21 CFR Part 177.2600 compliance pathways narrow for peroxide-cured alternatives, accelerating platinum-catalyzed formulation qualifications. Boston-area precision molders compress development cycles for respiratory device seals through additive-manufactured conformal cooling channels.
Germany
Automotive LED lens housings and medical OEMs co-locate around Freiburg and Munich tooling clusters. EU Green Deal F-Gas Regulation amendments redirect engine compartment sealing demand toward high-temperature LSR grades. Burghausen complex anchors European high-purity output, creating geographic concentration risk for qualified medical supply chains.
China
NMPA medical device registration rules and GB 4806.11-2016 food-contact standards govern import access for respiratory device seals. Dual carbon goals favor platinum-cured LSR over thermoplastic alternatives in high-volume manufacturing. Yangtze River Delta electronics assemblers adopt faster-cure chemistries for wearable device production.
Japan
METI efficiency mandates and PMDA medical device pathways shape formulation requirements for implantable components. Electronics-grade supply concentrates through integrated monomer-to-polymer operations serving precision molding applications. Osaka-area molders specialize in sub-10-micron repeatability tooling for automotive lighting components.
India
CDSCO medical device registration opens procurement channels for ISO 10993-certified LSR as domestic production incentives expand. Underpenetrated implantable device manufacturing creates qualification opportunities for compounders bypassing intermediary toll processors. Gujarat and Maharashtra industrial corridors attract molding capacity investments targeting export markets.
Liquid Silicone Rubber Market Key Industry Players
Premium-margin players sit above commodity-margin players across medical certification tiers, with ISO 10993-qualified compounders commanding pricing power over standard-grade suppliers. The vendor base stratifies into three archetypes: integrated siloxane-to-polymer operators with captive feedstock, regional compounders serving automotive tooling clusters, and specialty formulators targeting faster-cure electronics applications. Dominant competitive moves include backward integration into siloxane monomer production and direct OEM qualification bypassing toll processors.
Among integrated chemical conglomerates, Dow, Wacker Chemie AG, and Shin-Etsu Chemical occupy positions spanning medical-grade formulation and electronics-grade supply. Dow leverages captive siloxane feedstock to sustain cost advantages in platinum-catalyzed systems. Wacker Chemie AG anchors high-purity output from its Burghausen complex, representing the European integrated archetype. Shin-Etsu Chemical exemplifies Asian electronics-grade concentration through vertically structured monomer-to-polymer operations.
| Leading Market Players |
|---|
| Elkem Silicones |
| CHT Germany GmbH |
| Dow |
| Avantor Inc. |
| KCC Silicone Corporation |
| Wacker Chemie AG |
| Shin-Etsu Chemical |
| Rui-He New Material |
| Momentive Performance Materials |
| Others |
Cost & Logistics Intelligence
CDMO procurement consolidation across Minnesota and Massachusetts corridors forces compounders to absorb multi-year ISO 10993 certification costs upfront, compressing margins for non-qualified suppliers while anchoring premium pricing to direct OEM qualification status.
Pricing Analysis
Value-based pricing anchors to FDA 21 CFR Part 177.2600 compliance outcomes and implant-grade biocompatibility certification. Three-tier pricing structure across platinum-catalyzed medical grades, automotive precision formulations, and standard industrial compounds separates qualified from unqualified supply. Cost compression in automotive LED lens segments intensifies because sub-10-micron repeatability requirements demand simultaneous tooling and material lot consistency investments. Medical device OEMs show least price sensitivity due to locked supplier relationships, while consumer goods buyers face maximum pressure from REACH Annex XVII compliance burdens.
Supply Chain Analysis
Direct-to-OEM channels handle qualified medical-grade demand, bypassing intermediary toll processors as CDMOs unbundle material supply from molding services. Geographic concentration centers on Germany's Burghausen complex for European high-purity output, China's Yangtze River Delta for electronics-grade supply, and US Minnesota-Massachusetts corridors for implantable device procurement. Raw material flows draw from siloxane monomer production, platinum group metal catalysts, and hydride crosslinker intermediates. Single-source vulnerability at the Burghausen complex creates geographic risk exposure for qualified medical supply chains. Distribution runs through certified compounder-direct relationships for medical grades and regional distributors for standard industrial formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platinum-catalyzed capacity expansion timelines lag demand acceleration from FDA peroxide-cure phaseouts, propping pricing power for qualified compounders with existing ISO 10993 certifications.
For Market Incumbents: Cement supplier lock-in through captive siloxane feedstock investments and direct OEM qualification pipelines that bypass toll processors. Accelerate conformal cooling channel additive manufacturing adoption in Freiburg-Munich tooling clusters to defend cycle time advantages against emerging Asian molders. Threat of faster-cure adhesive chemistries displacing thermal epoxies in wearable electronics demands R&D prioritization in electronics-grade formulation portfolios. For New Entrants and Emerging Players: Faster-cure LSR adhesive technologies for wearable electronics assembly offer the most penetrable white-space entry point. Target India's CDSCO medical device registration pathway as domestic production incentives expand implantable manufacturing capacity. Pursue toll processor bypass strategies by certifying directly against OEM specifications rather than through established CDMO intermediaries. For Investors and Strategic Acquirers: The window for entry favors integrated siloxane-to-polymer operators with captive feedstock and existing medical-grade certification infrastructure. Long-term viability hinges on backward integration into monomer production and regional diversification beyond single-complex supply concentration. Watch NMPA respiratory device seal efficiency mandates as the inflection signal for platinum-cured LSR share capture against thermoplastic alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Siloxane Monomer | Captive feedstock secures cost advantage for Dow and Wacker in platinum-catalyzed formulations. |
| Direct OEM Qualification Bypass | CDMO unbundling forces compounders to certify against FDA 21 CFR Part 177.2600 specifications directly. |
| Additive Manufacturing of Conformal Cooling | German precision molders compress respiratory mask cycle times through printed tooling inserts. |
| Fluorosilicone Substitution Acceleration | EU F-Gas Regulation amendments redirect engine compartment sealing toward high-temperature LSR grades. |
| India CDSCO Registration Pathway | Domestic production incentives open procurement channels for ISO 10993-certified implantable device supply. |
Research Approach
Trade statistics from customs databases, SEC 10-K filings from integrated chemical conglomerates, and ECHA REACH registration records formed the secondary backbone. Primary fieldwork encompassed interviews with plant managers at European siloxane complexes, procurement leads at Minnesota and Massachusetts medical device CDMOs, technical R&D directors at German precision molding clusters, and distribution channel partners serving Asian electronics assemblers. Bottom-up and top-down triangulation validated volume estimates against capacity disclosures and end-use consumption patterns.
Bottom-up modeling of vinyl-functional polydimethylsiloxane consumption by grade tier, end-use industry, and regional production hub anchored value projections across the analysis window. Top-down cross-checks applied macroeconomic sensitivity filters to automotive LED lens housing demand and medical implant procurement cycles. CAGRs were derived from segmented growth rate blending across curing chemistry platforms, with particular weighting to platinum-catalyzed displacement timelines and F-Gas Regulation substitution deadlines.
Several conditions sit outside the modeled scope, including force majeure disruptions at the Burghausen complex, abrupt platinum group metal price spikes, and unscheduled FDA peroxide-cure restriction accelerations. Forecasts reflect base-case assumptions about qualification timeline durations and CDMO consolidation trajectories. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rubber
Global Crumb Rubber Market
Rubber
Rubber Reinforcing Chemicals Market
Rubber
Recycled Elastomers Market
Rubber
Rubber Accelerators Market
Rubber
Global Styrene Butadiene Styrene Market
Rubber
Sterile Rubber Stopper Market
Rubber
Tire and Rubber Lubricants Market
Rubber
Global Medical Rubber Stopper Market
Rubber
Global Liquid Synthetic Rubber Market
Rubber
Polybutadiene Rubber (PBR) Market
Rubber
Flexible Rubber Sheets Market
Rubber
Global Rubber Additives Market
Rubber
Rubber Color Masterbatch Market
Rubber
Global Latex Allergy Market
Rubber
Snap on Rubber Stopper Market
Rubber
Global Automotive Elastomers Market